
 Ammunition Belt Market | 2026-2036
Ammunition Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Ammunition Belt Market Outlook
Maintenance and refurbishment service contracts for legacy belt link systems is hardening into a distinct revenue layer alongside original equipment sales. FN Herstal leverages its NATO-standard M13 link production lines to sustain long-term aftermarket commitments across European defense ministries. General Dynamics anchors its position through backward integration into brass and steel feed strip manufacturing for US military programs. Rheinmetall AG competes on dual-use technology transfer, supplying both disintegrating link systems and barrel assemblies to allied forces.
An ammunition belt is a continuous or segmented feed device that holds cartridges in linked configuration for automatic weapon cycling, typically constructed from stamped steel, extruded aluminum, or injection-molded polymer with precise pitch tolerances measured in millimeters to ensure reliable extraction and chambering. The assembly's primary purpose is to enable sustained automatic fire without manual reloading, critical for machine gun operations in military and security contexts. Disintegrating belt links dominate military procurement due to their single-use design eliminating recovery logistics, while polymer belt links represent the fastest-expanding material category as weight reduction becomes a decisive performance parameter for infantry-portable systems. Steel belt links retain the largest installed base but face margin compression from raw material volatility and longer replacement cycles.
US military specifications governed by the Department of Defense and NATO standardization agreements shape product interoperability requirements across allied procurement, while the EU Green Deal and REACH regulations from ECHA increasingly constrain polymer additive chemistries and surface coating processes used in European-manufactured belt links. Stakeholders must monitor how divergent transatlantic sustainability mandates affect material qualification timelines and cross-border supply eligibility for defense contractors serving multiple jurisdictions.
Market Dynamics
Lightweight polymer belt links are compressing replacement cycles across NATO small-caliber automatic weapons programs, forcing suppliers to retool stamping and injection-molding lines for disintegrating link geometries that reduce infantry load burdens.
Growth Catalysts
- REACH polymer additive compliance:European defense contractors qualifying halogen-free flame retardants for belt link resins gain preferential access to EU Green Deal-aligned procurement tenders.
- Marine Corps squad automatic weapons modernization:Sustained orders for M27 IAR-compatible linked ammunition systems drive volume commitments through 2030.
- Disintegrating link technology:Single-use designs eliminating battlefield link recovery logistics now dominate infantry-portable machine gun specifications.
Market Restraints
- Brass and steel feed stock volatility:Raw material price swings compress margins on legacy metal belt link production lines.
- Dual-use technology transfer controls:Export licensing friction constrains European manufacturers from supplying barrel-and-link assemblies to non-NATO allied forces.
- Polymer degradation in extreme climates:Thermal cycling limits on injection-molded links restrict deployment latitude for high-temperature desert operations.
Strategic Opportunities
- US Army Next Generation Squad Weapon program:6.8mm ammunition belt specifications create entry points for qualified polymer link suppliers.
- Maintenance and refurbishment service contracts:Aftermarket revenue layers for legacy M13 link systems harden alongside original equipment sales.
- Backward integration into captive brass supply:In-house feed stock production insulates margin pressure from commodity metal markets.
Industry Challenges
- NATO standardization agreement compliance timelines:STANAG qualification protocols for new belt link geometries extend product launch schedules by 18-24 months.
- Legacy metal-to-polymer production line conversion:Retooling capital requirements strain mid-tier suppliers without defense prime contracting relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammunition Belt Market |
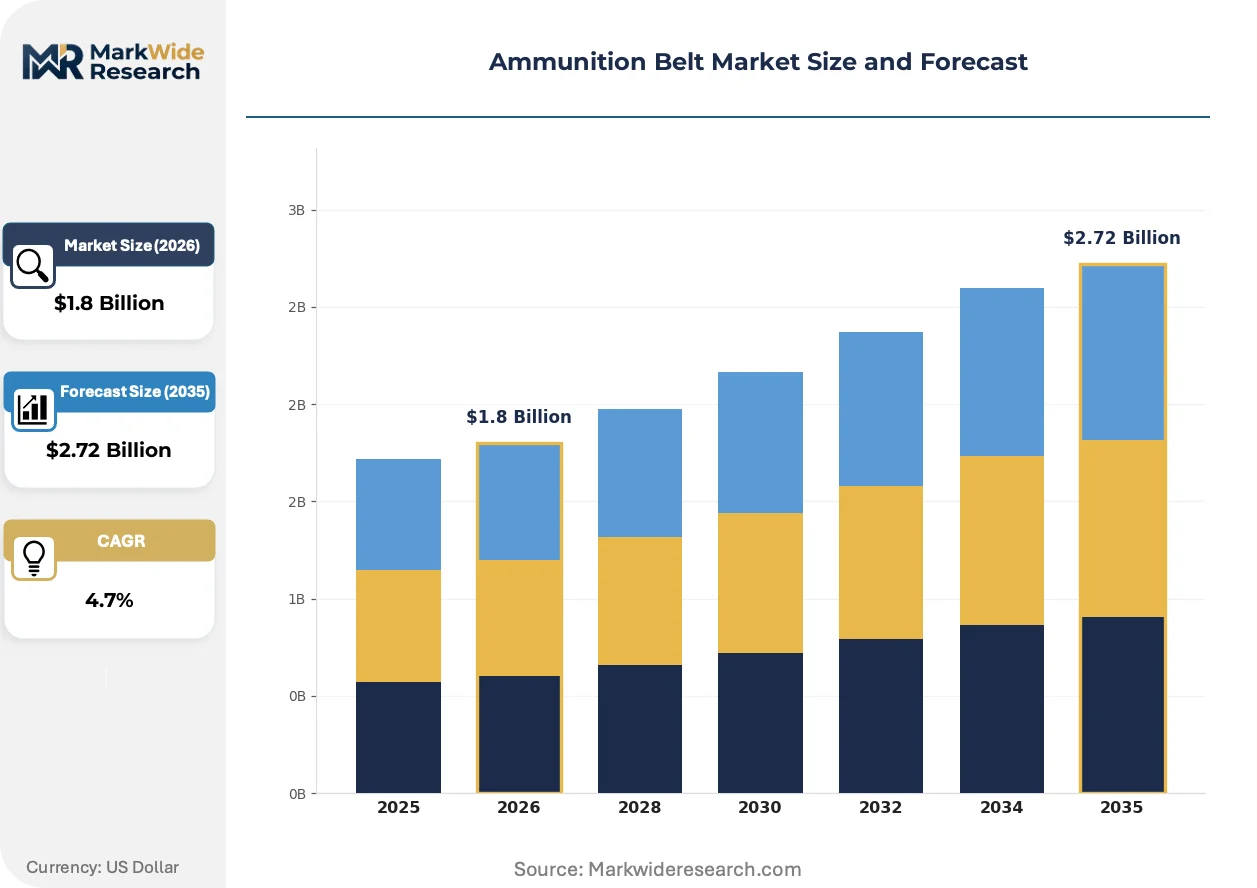
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Links, Disintegrating Belt, Fabricated Belt, Chain Belt Material: Plastic, Steel, Aluminum, Nylon End User: Military, Law Enforcement, Commercial, Civilian Application: Military Use, Sporting, Training, Hunting |
| Companies Covered | FN Herstal, General Dynamics, BAE Systems, Rheinmetall AG, Meggitt PLC, Oerlikon Contraves, Curtiss-Wright Corporation, Eurolinks-SIPR Defence, Triple K Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammunition Belt Market Strategic Shifts
Material science advances and regulatory chemistry constraints are rewriting qualification protocols for ammunition belt manufacturing, while procurement consolidation among allied defense ministries compresses supplier qualification windows.
Hybrid metal-polymer belt link construction is unifying the structural rigidity of stamped steel feed lips with the weight savings of glass-reinforced nylon bodies. US Army and Marine Corps program offices are fast-tracking adoption for next-generation squad automatic weapons. This convergence is unifying previously separate supplier ecosystems into integrated design-build contracts that compress tier-2 component sourcing.
EU Green Deal and ECHA REACH regulations are constraining halogenated flame retardants and heavy-metal surface coatings in European-manufactured belt links. Defense contractors serving NATO and EU member states must now dual-qualify additive packages to maintain cross-border supply eligibility. German and Belgian suppliers face the steepest reformulation timelines as their national defense ministries align procurement with 2030 sustainability targets.
Allied defense ministries are consolidating ammunition belt procurement under multi-year framework agreements with embedded service provisions. Traditional spot-buying through national arsenals is yielding to vendor-managed inventory models with performance-based logistics clauses. This restructuring is most advanced in US and UK military supply chains, where prime contractors now assume lifecycle responsibility for link refurbishment and field-level replacement forecasting.
Ammunition Belt Market Segmentation
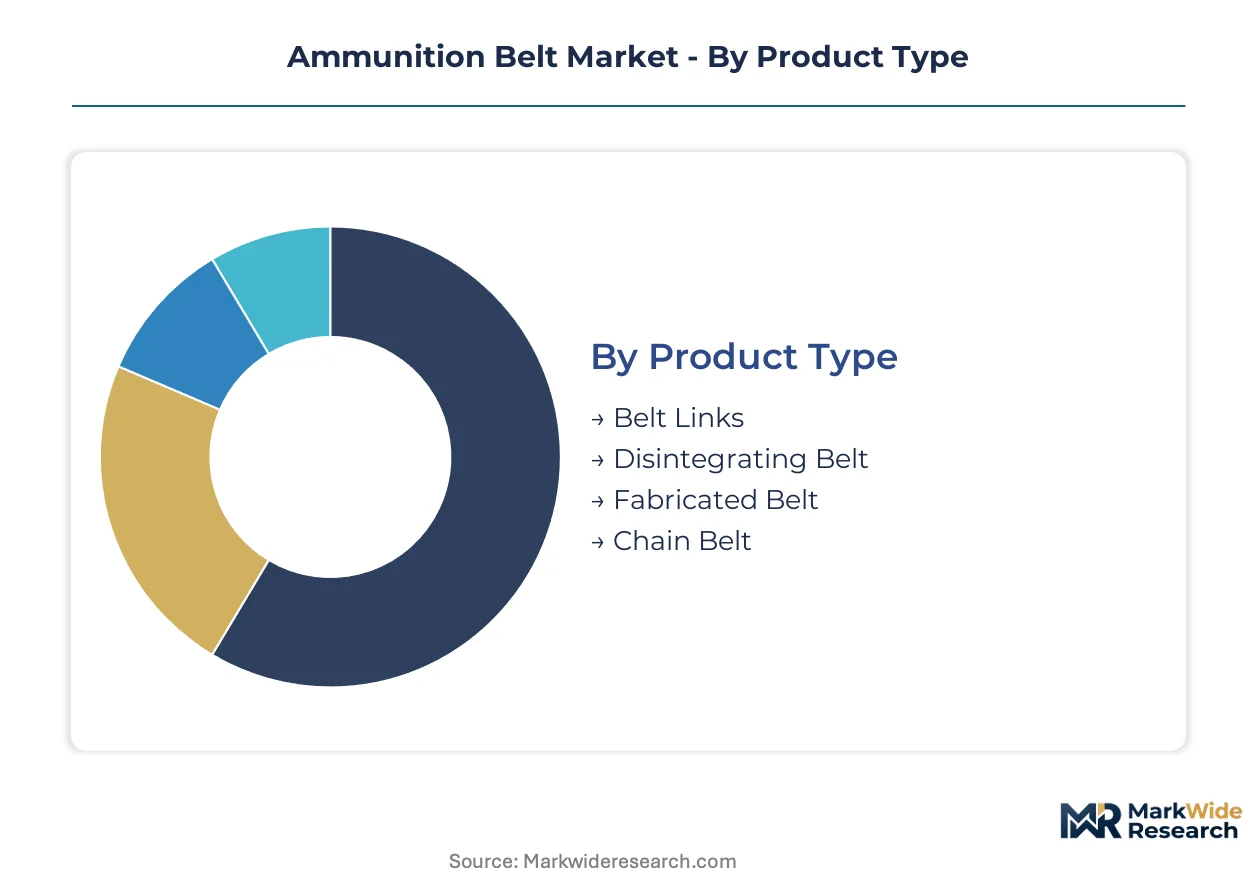
Ammunition belt procurement divides sharply between legacy system sustainment and next-generation platform integration. Material science advances and NATO standardization protocols drive upgrade decisions across each segment category.
Product Type:
Replacement cycles accelerate as disintegrating link designs displace reusable belt systems in infantry-portable automatic weapons.
- Disintegrating Belt:Single-use links eject during firing, eliminating battlefield recovery logistics. US Marine Corps M27 IAR programs and Army Next Generation Squad Weapon specifications concentrate procurement volume here.
- Belt Links:Individual stamped or molded connectors assembled into continuous feeds. NATO STANAG M13 standardization sustains long-term demand across European defense ministries with embedded refurbishment service contracts.
- Fabricated Belt:Woven textile carriers for specialized vehicle-mounted applications requiring flexible feed paths.
- Chain Belt:Reusable metal chains for heavy machine gun systems with established recovery protocols.
Disintegrating belt configurations sit at the top of the volume ranking, with belt links climbing the fastest through aftermarket modernization programs.
Material:
Cost tiers separate premium polymer formulations from commodity metal feed stocks, with qualification timelines widening the gap.
- Plastic:Glass-reinforced polymer compounds deliver 40-60% weight reduction versus steel. EU Green Deal REACH compliance requirements for halogen-free flame retardants constrain supplier qualification to Belgian and German manufacturers with reformulation capabilities.
- Steel:Stamped carbon steel retains the largest installed base in legacy NATO machine gun systems. Raw material volatility from brass and steel commodity markets compresses production margins.
- Aluminum:Extruded alloys balance weight savings with structural rigidity for aircraft and vehicle-mounted weapons.
- Nylon:Injection-molded variants serve training and simulation markets with reduced thermal tolerance requirements.
Plastic formulations are expanding share fastest in infantry applications, while steel maintains dominance in vehicle-mounted heavy weapons.
End User:
Customer type determines specification stringency, with defense procurement driving interoperability standards that cascade to adjacent segments.
- Military:Department of Defense and NATO standardization agreements mandate precise pitch tolerances and disintegrating link geometries. Multi-year framework agreements with vendor-managed inventory clauses consolidate supplier relationships.
- Law Enforcement:Specialized tactical units procure linked ammunition systems for sustained suppression capabilities. Specifications typically mirror military standards with reduced volume commitments.
- Commercial:Security contractors and range operators purchase refurbished M13 link systems through secondary markets.
- Civilian:Collectors and enthusiasts acquire linked ammunition for historical reenactment and display purposes under strict regulatory constraints.
Military end users command the specification-setting role, with law enforcement representing the fastest-expanding customer category outside defense primes.
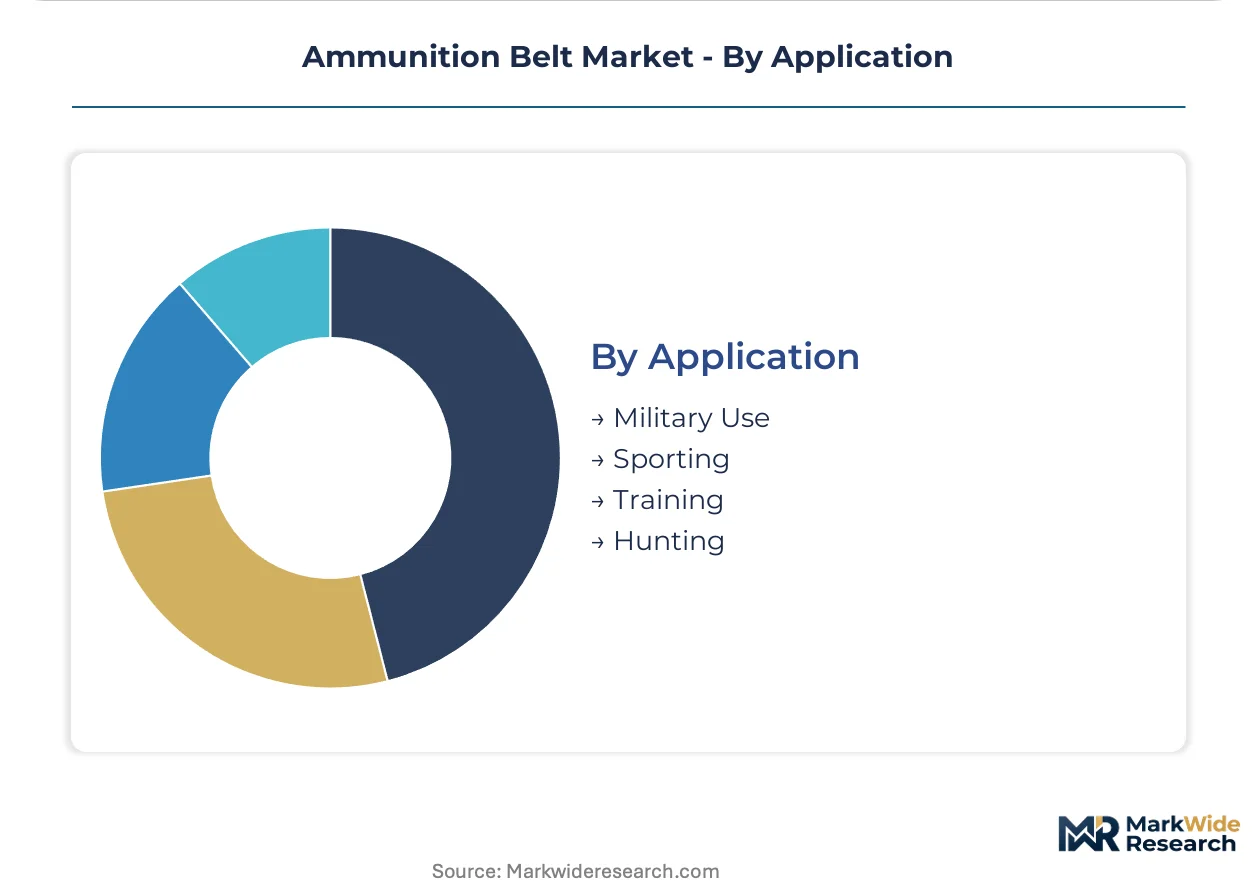
Application:
Volume concentration follows platform deployment patterns, with operational tempo dictating replacement frequency across use cases.
- Military Use:Combat and deterrence operations drive continuous feed system consumption across small-caliber automatic weapons. Squad automatic weapon modernization programs in the United States anchor procurement scale.
- Training:High-volume expenditure in live-fire exercises sustains demand for cost-optimized linked ammunition configurations. Military training centers and allied partnership programs concentrate orders.
- Sporting:Competitive shooting disciplines with belt-fed weapon categories generate specialized demand for precision-manufactured links.
- Hunting:Restricted legal frameworks limit linked ammunition deployment for civilian hunting applications.
Military use absorbs the dominant procurement volume, with training applications gaining share through allied capacity-building initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between transatlantic regulatory regimes are redirecting polymer belt link production toward jurisdictions with streamlined REACH-equivalent protocols. Defense contractors now site manufacturing to exploit these arbitrage opportunities while maintaining NATO STANAG interoperability.
United States
Army and Marine Corps modernization programs drive sustained procurement volume for 5.56mm and emerging 6.8mm linked ammunition systems. Department of Defense vendor-managed inventory clauses consolidate supplier relationships under multi-year framework agreements. Manufacturing concentrates in the Midwest industrial corridor, where brass and steel feed stock processors cluster near legacy defense arsenals.
Germany
Rheinmetall AG anchors European production of disintegrating link systems and barrel assemblies for allied forces. ECHA REACH regulations on halogen-free flame retardants constrain polymer additive packages, forcing reformulation investments. Defense manufacturing clusters in North Rhine-Westphalia and Bavaria, where dual-use technology transfer controls create licensing friction for non-NATO exports.
Belgium
FN Herstal sustains NATO-standard M13 link production lines with embedded long-term aftermarket commitments. EU Green Deal alignment requirements shape procurement eligibility for European defense ministries. Liège-based manufacturing facilities serve as a hub for STANAG-qualified belt link supply across continental NATO members.
United Kingdom
BAE Systems participates in consolidated ammunition belt procurement under multi-year framework agreements with performance-based logistics clauses. National defense procurement increasingly mirrors US vendor-managed inventory models. Manufacturing activity concentrates in the Midlands and Northwest England, where legacy metalworking capabilities support hybrid metal-polymer link development.
Switzerland
Oerlikon Contraves supplies linked ammunition feed systems for vehicle-mounted and aircraft applications requiring precision pitch tolerances. Swiss neutrality status creates specialized export licensing pathways distinct from NATO standardization agreements. Industrial activity centers in the Zurich-Oerlikon region, where precision engineering traditions align with ammunition component manufacturing.
Ammunition Belt Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with defense primes commanding specification-setting authority and tier-2 suppliers filling capacity gaps. The market structure consolidates around NATO-standardized product lines where STANAG qualification creates durable competitive moats. Three archetypes dominate: vertically integrated defense primes with captive metallurgy operations, polymer injection specialists with REACH-compliant formulation capabilities, and regional metal stampers serving legacy refurbishment contracts. Competitive dynamics center on backward integration into brass supply and strategic partnerships for polymer additive qualification.
Among European defense primes, Rheinmetall AG and FN Herstal exemplify the integrated-systems archetype, combining barrel and link assembly production under unified design-build contracts. General Dynamics occupies a position within the US-centric prime tier, leveraging domestic brass and steel feed stock manufacturing to insulate margin pressure from commodity volatility. These three anchors demonstrate how geographic alignment with major procurement programs determines competitive positioning more than pure manufacturing scale.
| Leading Market Players |
|---|
| FN Herstal |
| General Dynamics |
| BAE Systems |
| Rheinmetall AG |
| Meggitt PLC |
| Oerlikon Contraves |
| Curtiss-Wright Corporation |
| Eurolinks-SIPR Defence |
| Triple K Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Brass and steel feed stock volatility cascades through three distinct pricing tiers for ammunition belt procurement, with NATO-standard M13 links commanding premium contract rates while refurbished legacy systems trade at compressed margins in secondary markets.
Pricing Analysis
Distributor margins on polymer belt links widen where REACH-compliant additive packages qualify suppliers for EU Green Deal-aligned defense tenders. Three-tier pricing structure across premium polymer, standard steel, and economy refurbished links separates procurement channels. Cost compression in commodity metal tiers intensifies because raw material swings erode stamping line profitability. Law enforcement buyers exhibit highest price sensitivity, while Department of Defense vendor-managed inventory contracts anchor volume at negotiated rates.
Supply Chain Analysis
Single-source vulnerability sits with German and Belgian polymer formulation capabilities under ECHA REACH regulatory timelines. Manufacturing concentrates in the United States, Germany, and Belgium, with feed stock processing anchored in the American Midwest. Raw material dependencies span brass rod, carbon steel strip, and glass-reinforced nylon resin. Tariff exposure on non-NATO barrel-and-link assemblies constrains Rheinmetall's export licensing pathways. Distribution runs through defense prime contractors holding multi-year framework agreements with allied ministries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ammunition belt procurement functions as a stable compounder where NATO standardization agreements lock in replacement cycle visibility across allied defense budgets.
For Market Incumbents: Anticipate margin compression from polymer conversion capital requirements by securing captive brass supply contracts and accelerating STANAG qualification for hybrid metal-polymer geometries. Backward integration into feed stock production insulates against commodity volatility. Channel control through embedded refurbishment service clauses hardens customer retention. For New Entrants and Emerging Players: Enter via law enforcement tactical unit procurement, where specification mirroring of military standards occurs without prime contracting relationships. Training application aftermarket for refurbished M13 links offers penetrable white space. Go-to-market leverage rests on REACH-compliant polymer formulation partnerships with Belgian or German compounders. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier metal stampers face retooling capital strain without defense prime relationships. Five-to-ten year viability favors integrated-systems archetypes combining barrel and link production. Signal to watch involves US Army Next Generation Squad Weapon program award announcements shifting volume toward 6.8mm polymer link specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Brass Supply | In-house feed stock production insulates General Dynamics from commodity metal market swings. |
| REACH-Compliant Polymer Reformulation | Halogen-free flame retardant qualification opens EU Green Deal-aligned procurement tenders for Belgian suppliers. |
| STANAG M13 Link Refurbishment Service Contracts | FN Herstal embeds long-term aftermarket commitments across European defense ministries. |
| Hybrid Metal-Polymer Link Development | US Army and Marine Corps program offices fast-track adoption for next-generation squad automatic weapons. |
| Vendor-Managed Inventory Partnerships | Prime contractors assume lifecycle responsibility for link forecasting under UK and US military supply chains. |
Study Parameters
Bottom-up defense procurement modeling reconciled against top-down ammunition component production tracking forms the analytical core. Primary interviews with program officers at NATO standardization offices, procurement leads at defense ministries, plant managers at brass processing facilities, and aftermarket service heads at legacy system sustainment operations combined with secondary validation. Trade data from EUROSTAT and US Census Bureau defense export classifications, NATO STANAG documentation, ECHA REACH substance registration databases, and Department of Defense contract award announcements anchored supply-side calibration. Triangulation across these sources verified volume estimates.
Input-output matrices mapped polymer resin consumption to finished belt link output across injection-molding and metal stamping facilities. Segmentation dimensions modeled encompass product type, material formulation, end-user category, and application use case, with regional regulatory cluster as an additional defense-specific dimension. CAGRs derived from replacement cycle analysis tied to squad automatic weapon modernization timelines and allied training expenditure patterns. Forecast inputs incorporated NATO member state defense budget trajectories and polymer additive qualification pipeline status.
Inputs from primary defense procurement contacts were available through the study window; gaps in classified program milestone schedules introduce uncertainty bands around Next Generation Squad Weapon volume timing. Forecasts reflect documented assumptions regarding REACH compliance deadline adherence and STANAG qualification protocol durations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
Global Small Arms and Light Weapons (SALW) Market
Weapons and Ammunition
Ballistic Composite Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
Airsoft Guns Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Smoke Grenade Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Medium Caliber Ammunition Market
Weapons and Ammunition
France Nuclear Bombs and Missiles Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market