
 Africa Airport Operations Market | 2026-2036
Africa Airport Operations Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Airport Operations Market Analytics
The capability gap between capital-heavy international operators and domestically funded African airport authorities is rotating competitive dynamics across the continent. Fraport AG Frankfurt Airport Services Worldwide leverages its global hub management expertise to sustain concession contracts in major African gateways. Ethiopian Airlines Group anchors its position through integrated airline-airport operations in Addis Ababa. Airports Company South Africa competes on infrastructure scale but navigates capital constraints that limit expansion velocity.
Africa airport operations encompass the coordinated management of aircraft turnaround, passenger processing, baggage flow, and airside safety systems requiring compliance with ICAO Annex 14 aerodrome standards and local civil aviation regulations. Ground handling services dominate operational expenditure across African terminals, while automation systems represent the fastest-growing technology segment as airports modernize aging infrastructure. Non-aeronautical revenue streams including retail concessions and advertising now capture margin pools that offset regulated aeronautical fee limitations. Passenger services remain structurally mature in North African hubs but expand capacity in East and West African markets where terminal infrastructure lags traffic growth.
South Africa's Civil Aviation Authority enforces aerodrome certification standards that shape infrastructure investment timelines, while Kenya's Kenya Airports Authority operates under East African Community harmonized safety protocols that facilitate cross-border service standardization. Nigeria's Federal Airports Authority must reconcile NCAA operational directives with fiscal constraints that delay runway rehabilitation schedules. Stakeholders should monitor which regulatory bodies accelerate private sector participation frameworks versus those maintaining state-controlled capital allocation.
Market Dynamics
Low-cost carrier fleet expansion across the continent is compressing turnaround windows and forcing ground handlers to reconfigure apron workflows for higher-density narrowbody operations. This operational squeeze demands simultaneous infrastructure modernization while regulatory certification timelines remain fixed.
Growth Catalysts
- ICAO Annex 14 aerodrome certification:Harmonized safety standards across African Civil Aviation Commission member states reduce cross-border operational friction for multinational ground handlers.
- Ethiopian Airlines Group hub strategy:Integrated airline-airport operations in Addis Ababa generate spillover demand for third-party ground handling capacity and cargo terminal services.
- Biometric passenger processing:Automated border control systems reduce terminal congestion and enable higher passenger throughput without proportional infrastructure expansion.
Market Restraints
- Jet fuel price volatility:Ground handling contracts indexed to fuel surcharges create margin instability for fixed-fee service providers during price spikes.
- Foreign exchange concentration:Revenue denominated in local currencies against dollar-denominated equipment leases strains balance sheets of domestically funded airport authorities.
- Runway rehabilitation backlogs:Nigeria's Federal Airports Authority faces operational hour restrictions that compress available slot capacity at Lagos Murtala Muhammed International.
Strategic Opportunities
- Kenya Jomo Kenyatta International expansion:Underpenetrated cargo cold chain infrastructure presents white space for temperature-controlled pharmaceutical handling services.
- South Africa private sector participation frameworks:Airports Company South Africa concession restructuring opens operational contracts to specialized international operators.
- Mobile check-in convergence with baggage tracking:Integration of passenger-facing applications with RFID baggage systems enables unbundled premium handling tiers.
Industry Challenges
- Aircraft maintenance engineer scarcity:Technical crew certification bottlenecks at South African Civil Aviation Authority-approved training organizations limit line maintenance capacity expansion.
- Legacy terminal system integration:1990s-era baggage handling infrastructure at Abuja Nnamdi Azikiwe International requires phased retrofit without operational shutdown.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Airport Operations Market |
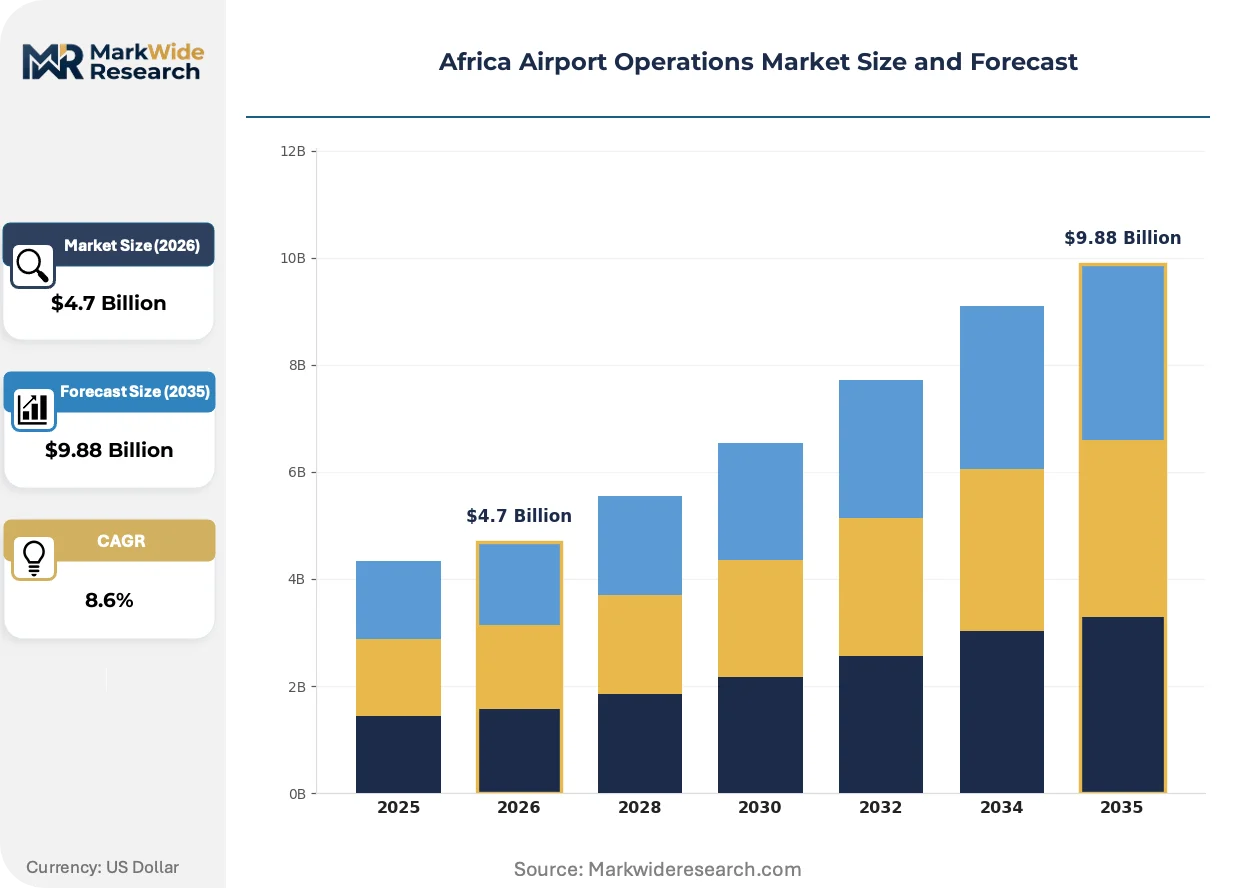
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ground Handling, Air Traffic Control, Passenger Services, Baggage Services End User: Airport Authorities, Airlines, Ground Service Providers, Third-Party Logistics Technology: Automation Systems, Communication Tools, Security Equipment, Maintenance Solutions Revenue Stream: Aeronautical Revenue, Non-Aeronautical Revenue, Concessions, Advertising |
| Companies Covered | Office National des Aéroports, Fraport AG Frankfurt Airport Services Worldwide, Ethiopian Airlines Group, Angola Airports Company, Corporation for Cape Town International Airport, Egyptian Holding Company for Airports and Air Navigation, Kenya Airports Authority, RwandAir, Airports Company South Africa, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Airport Operations Market Evolving Landscape
Automation is penetrating African airport operations through modular retrofit rather than greenfield replacement, with technology vendors adapting solutions for constrained capital environments and intermittent power supply. This adaptation pattern favors scalable systems over integrated platforms.
Artificial intelligence-powered predictive maintenance for ground support equipment is fragmenting traditional fixed-interval servicing contracts. Low-cost carriers operating high-cycle narrowbody fleets adopt sensor-based monitoring to minimize AOG incidents. Equipment lessors respond with usage-based maintenance clauses that transfer operational risk to technology-enabled operators.
Kenya Airports Authority implementation of East African Community harmonized safety protocols accelerates cross-border training reciprocity. Maintenance technicians certified in Nairobi gain operational recognition at Entebbe and Kigali without redundant assessment. Regional carriers exploit this standardization to deploy floating technical crews across hub networks.
Airlines are unbundling ground handling procurement from parent network contracts. Ethiopian Airlines Group's cargo division now sources specialized cold chain services independently from passenger handling. This disintermediation creates direct commercial relationships between pharmaceutical shippers and certified handlers at Addis Ababa, bypassing traditional airline intermediaries.
Africa Airport Operations Market Segmentation
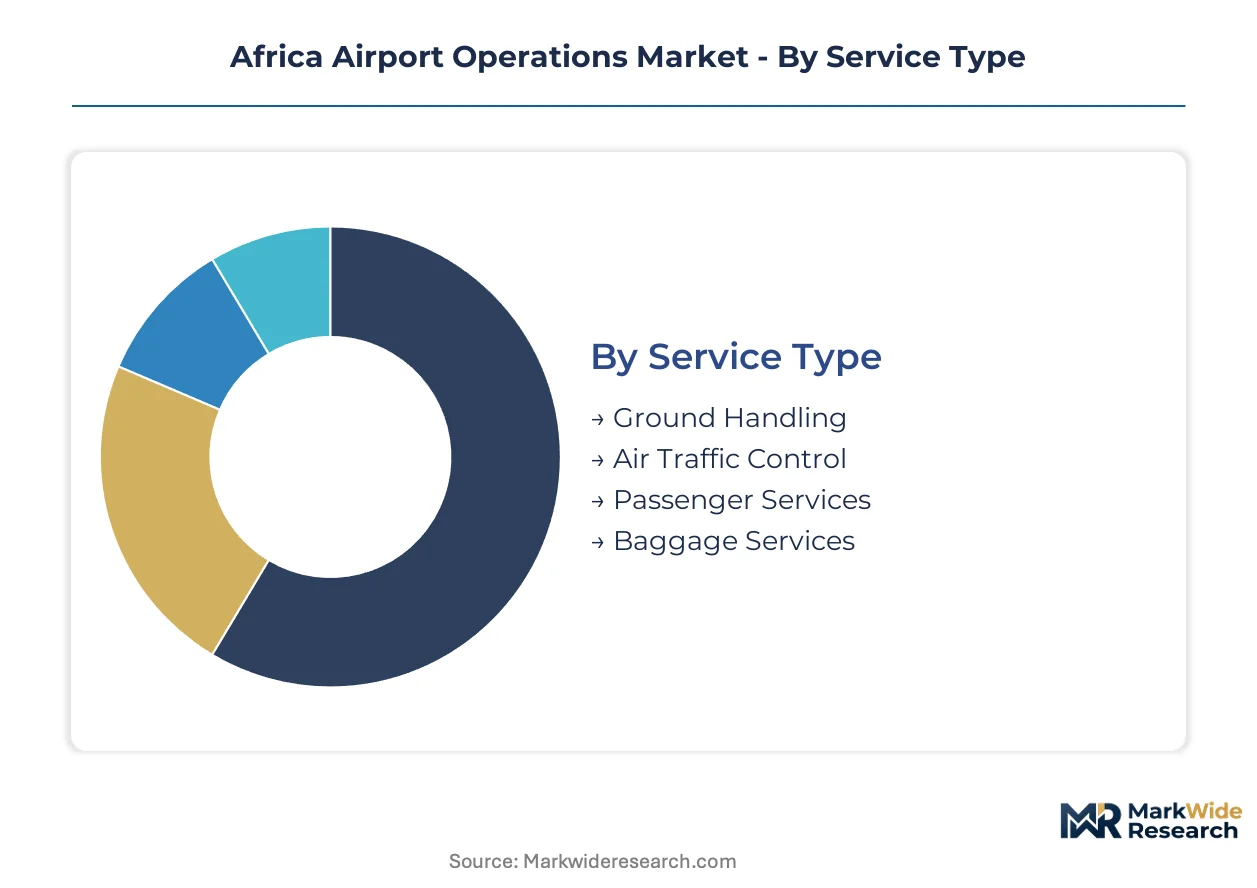
Service type segmentation reveals how operational expenditure concentrates across African terminals, with ground handling absorbing disproportionate capital allocation. Technology and revenue stream splits expose where automation investments and margin recovery opportunities diverge across airport authorities and private operators.
Service Type:
Ground handling flows through direct airport authority procurement in Nigeria and Kenya, while passenger services channel through airline-negotiated contracts at Ethiopian Airlines Group's integrated hub.
- Ground Handling:Aircraft turnaround coordination, cargo terminal operations, and apron safety management requiring ICAO Annex 14 aerodrome certification compliance. Demand concentrates at Lagos Murtala Muhammed International and Addis Ababa Bole International where low-cost carrier fleet expansion compresses turnaround windows.
- Air Traffic Control:Airspace management, approach sequencing, and ground movement coordination under national civil aviation regulator oversight. South Africa's Airports Company South Africa channels this through centralized procurement with the country's national aviation regulator enforcing certification standards.
- Passenger Services:Check-in processing, boarding gate management, and lounge operations.
- Baggage Services:RFID-tracked baggage flow and reclaim systems.
Ground handling dominates installed base. Air traffic control is where expansion concentrates.
End User:
Cost tier segmentation separates capital-heavy international operators from domestically funded authorities facing foreign exchange constraints.
- Airport Authorities:State-owned entities managing terminal infrastructure, runway systems, and regulatory compliance under national civil aviation oversight. Nigeria's Federal Airports Authority reconciles NCAA operational directives with fiscal constraints that delay rehabilitation schedules.
- Airlines:Integrated carriers like Ethiopian Airlines Group that self-perform ground handling to capture margin and control service quality at hub operations.
- Ground Service Providers:Specialized handlers competing for concession contracts at major gateways.
- Third-Party Logistics:Cold chain specialists and freight forwarders accessing cargo terminals independently.
Airport authorities anchor volume procurement. Third-party logistics is gaining share fastest.
Technology:
Application angle distinguishes retrofit installations for legacy terminals from modular systems designed for intermittent power supply.
- Automation Systems:Biometric passenger processing, automated baggage handling, and sensor-based ground support equipment monitoring. Kenya Jomo Kenyatta International deploys these to reduce terminal congestion without proportional infrastructure expansion.
- Communication Tools:Air-ground data link and collaborative decision-making platforms.
- Security Equipment:Screening technologies and access control systems.
- Maintenance Solutions:Predictive analytics for runway and terminal infrastructure.
Security equipment dominates current procurement. Automation systems are climbing the fastest.
Revenue Stream:
Margin structure differentiates regulated aeronautical fees from concession-driven recovery pools.
- Aeronautical Revenue:Landing charges, aircraft parking fees, and passenger service charges subject to regulatory rate-setting. South Africa's Civil Aviation Authority shapes investment timelines through aerodrome certification requirements.
- Non-Aeronautical Revenue:Retail concessions, duty-free operations, and property leasing that offset regulated fee limitations at major hubs.
- Concessions:Food and beverage, retail, and service contracts.
- Advertising:Terminal media and digital display networks.
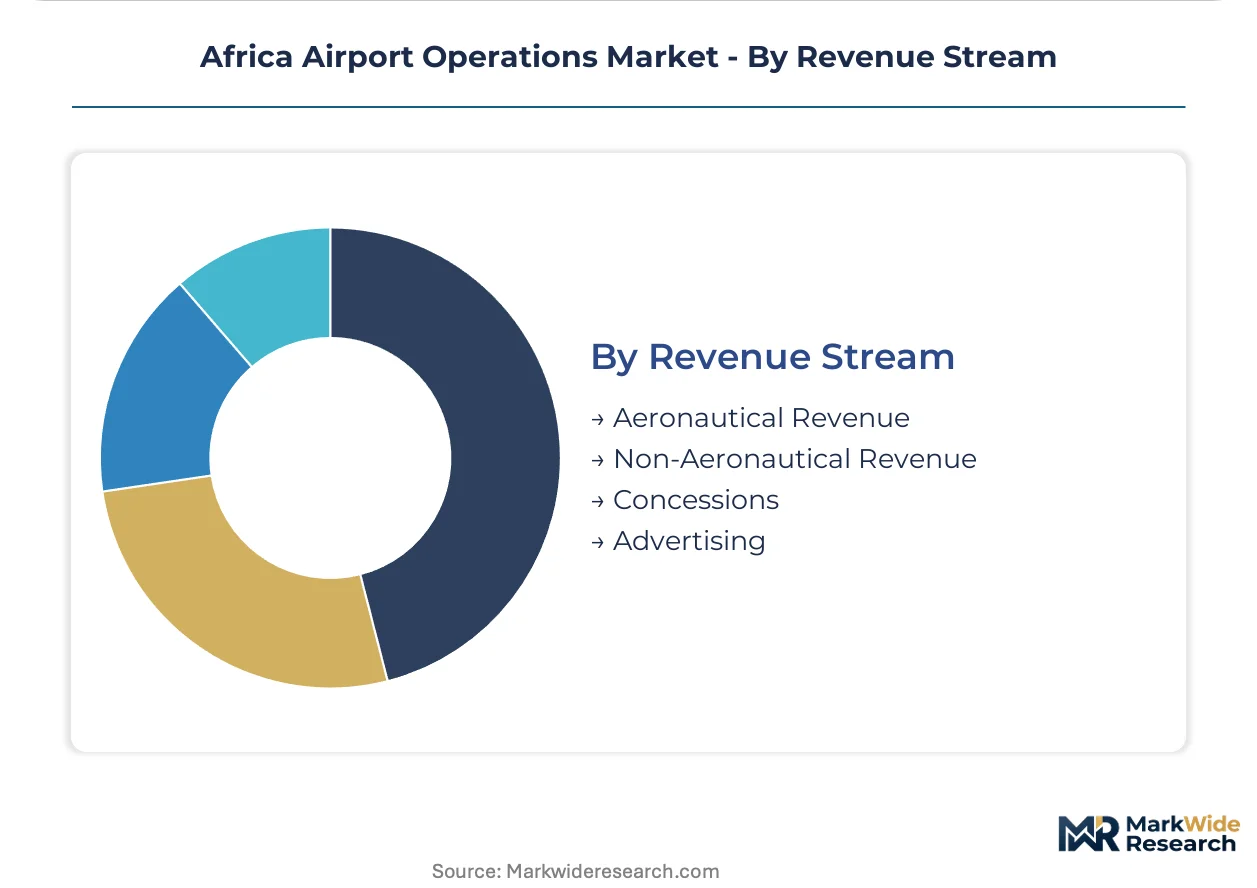
Aeronautical revenue anchors regulatory compliance funding. Non-aeronautical revenue is where margin recovery concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across African aviation markets. East African hubs absorb premium service costs through cargo-driven margins, while West African authorities face acute budget constraints that compress procurement timelines and limit technology adoption.
South Africa
Airports Company South Africa manages O.R. Tambo International and Cape Town International under Civil Aviation Authority certification standards that mandate continuous infrastructure upgrades. The country's national aviation regulator enforces aerodrome compliance timelines that shape capital allocation across Durban King Shaka and other secondary gateways. Johannesburg anchors the region's ground handling demand, with low-cost carrier expansion at Lanseria Airport driving apron workflow reconfiguration.
Nigeria
Federal Airports Authority operates Lagos Murtala Muhammed International and Abuja Nnamdi Azikiwe International under NCAA operational directives that conflict with fiscal limitations delaying runway rehabilitation. The country's national civil aviation regulator maintains strict certification requirements despite constrained government budgets. Lagos concentrates West Africa's ground handling volume, where slot restrictions at the aging international terminal compress carrier scheduling flexibility.
Ethiopia
Ethiopian Airlines Group integrates airline and airport operations at Addis Ababa Bole International, generating spillover demand for third-party cargo terminal services and cold chain infrastructure. The country's civil aviation administration aligns with ICAO Annex 14 standards that facilitate cross-border operational recognition. Addis Ababa anchors East African hub connectivity, with cargo-driven margins supporting premium ground handling procurement that exceeds regional norms.
Kenya
Kenya Airports Authority implements East African Community harmonized safety protocols that enable maintenance technician reciprocity across Entebbe and Kigali. The authority operates Jomo Kenyatta International under regional standards that accelerate cross-border training recognition. Nairobi drives underpenetrated pharmaceutical cold chain demand, with temperature-controlled cargo infrastructure representing expansion white space for specialized handlers.
Egypt
Egyptian Holding Company for Airports and Air Navigation manages Cairo International and coastal resort terminals under civil aviation ministry oversight that balances tourism revenue dependence with infrastructure modernization needs. The country's national aviation regulator maintains ICAO compliance while navigating foreign exchange constraints on equipment procurement. Cairo anchors North African connectivity, with Red Sea resort airports generating seasonal ground handling volatility that strains year-round capacity planning.
Africa Airport Operations Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in African airport operations. Fraport AG Frankfurt Airport Services Worldwide and Ethiopian Airlines Group occupy positions that blend concession management with operational control, while state-owned authorities compete on infrastructure scale against capital constraints. Three archetypes dominate: global concession operators leveraging hub management expertise, integrated airline-airport hybrids capturing margin through vertical coordination, and domestically funded authorities competing on regulatory relationships. Competitive moves concentrate on concession restructuring to admit private sector participation and automation retrofit partnerships that transfer technology risk.
Among the integrated operator tier, Ethiopian Airlines Group and Airports Company South Africa exemplify contrasting strategic positions. Fraport AG Frankfurt Airport Services Worldwide represents the global concession archetype, sustaining operational contracts through transferred hub management expertise. Kenya Airports Authority and Federal Airports Authority of Nigeria occupy the state-authority tier, navigating capital constraints that limit expansion velocity against regulatory compliance mandates. Office National des Aéroports and Egyptian Holding Company for Airports and Air Navigation demonstrate how North African authorities balance tourism-dependent revenue streams with infrastructure modernization requirements.
| Leading Market Players |
|---|
| Office National des Aéroports |
| Fraport AG Frankfurt Airport Services Worldwide |
| Ethiopian Airlines Group |
| Angola Airports Company |
| Corporation for Cape Town International Airport |
| Egyptian Holding Company for Airports and Air Navigation |
| Kenya Airports Authority |
| RwandAir |
| Airports Company South Africa |
| Others |
Value Network & Pricing Analysis
Long-term ground handling concession contracts with take-or-pay minimums lock in both apron access for low-cost carriers and revenue visibility for airport authorities across Lagos and Addis Ababa. These fixed-commitment structures transfer demand volatility risk to airline operators while insulating service providers from short-term traffic fluctuations.
Pricing Analysis
After-sales maintenance revenue from ground support equipment drives lifetime value capture for handlers serving Ethiopian Airlines Group's high-cycle narrowbody fleet. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification tier and service bundling intensity. Cost compression in standard-tier apron services is intensifying because low-cost carriers unbundle handling procurement from parent network contracts. Domestic airport authorities in Nigeria and Kenya exhibit highest price sensitivity due to foreign exchange constraints, while integrated airline-airport hybrids in Ethiopia absorb premium pricing.
Supply Chain Analysis
Port congestion at Mombasa and Dar es Salaam elevates inbound logistics costs for baggage handling equipment and biometric processing systems sourced from European and Asian manufacturing hubs. Supply concentration rests on Germany, China, and South Korea for automated sorting infrastructure, while jet fuel hedging instruments and RFID tracking hardware draw from Singapore and UAE trading centers. Single-source vulnerability concentrates in specialized cold chain refrigeration units for pharmaceutical cargo at Nairobi Jomo Kenyatta International. Distribution runs through authorized equipment lessors with regional maintenance depots in Johannesburg and Cairo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in African airport operations gains momentum from biometric passenger processing adoption that compresses terminal congestion without proportional infrastructure investment. Low-cost carrier fleet commitments across the continent sustain demand visibility for ground handling capacity.
For Market Incumbents: Fortify concession renewal positions at Lagos Murtala Muhammed International and Addis Ababa Bole International through accelerated automation retrofit partnerships that transfer technology risk to equipment vendors. Deepen backward integration into predictive maintenance analytics for ground support equipment to capture usage-based service revenue from sensor-enabled operators. Priority lever: ICAO Annex 14 certification investment to preempt regulatory compliance-driven contract reassignments.
For New Entrants and Emerging Players: Cold chain infrastructure gaps at Kenya Jomo Kenyatta International present immediate white-space opportunity for temperature-controlled pharmaceutical handlers. Underpenetrated cargo terminal automation in West African secondary gateways offers expansion terrain with lower competitive density than saturated North African hubs. Go-to-market angle: direct commercial relationships with pharmaceutical shippers bypassing traditional airline intermediaries, replicating Ethiopian Airlines Group cargo division's disintermediation model.
For Investors and Strategic Acquirers: Specialist ground handlers with ICAO-certified operations in East African Community member states represent acquisition targets with cross-border operational recognition leverage. Long-term viability hinges on concession restructuring momentum at Airports Company South Africa and Federal Airports Authority of Nigeria that admits private sector participation. Signal to watch: harmonized safety protocol adoption accelerating maintenance technician reciprocity across Entebbe, Kigali, and Nairobi.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Passenger Processing Deployment | Automated border control at Kenya Jomo Kenyatta International reduces terminal congestion without infrastructure expansion. |
| Concession Restructuring for Private Participation | Airports Company South Africa framework opens operational contracts to specialized international ground handlers. |
| Cold Chain Infrastructure Expansion | Temperature-controlled pharmaceutical handling at Addis Ababa Bole International captures cargo-driven margin premiums. |
| Predictive Maintenance Analytics Integration | Sensor-based ground support equipment monitoring minimizes AOG incidents for high-cycle narrowbody fleets. |
| East African Community Safety Protocol Harmonization | Cross-border training reciprocity enables floating technical crew deployment across Entebbe and Kigali. |
Research Methodology
A spread of perspectives from airport operations directors, ground handling procurement managers, civil aviation regulator certification officers, and low-cost carrier fleet planning executives converged on the working assumptions shaping demand projections. Primary interview insights combined with secondary validation from ICAO aerodrome certification databases, national civil aviation authority directives, airline fleet commitment disclosures, and East African Community harmonized safety protocol documentation. Bottom-up service-type segmentation triangulated against top-down regional traffic growth patterns.
Segmentation dimensions modeled span service type, end user archetype, technology application, and revenue stream structure across the projection horizon. Ground handling, air traffic control, passenger services, and baggage services formed the operational segmentation backbone. Analytical framework incorporated automation system penetration curves, concession contract renewal timelines, and low-cost carrier fleet expansion trajectories. CAGRs derived from installed base growth rates adjusted for regulatory certification lag effects and foreign exchange volatility impacts on equipment procurement.
Underlying assumptions cover sustained low-cost carrier fleet expansion, stable ICAO Annex 14 certification timelines, and gradual private sector participation framework adoption, with deviation risk concentrated in runway rehabilitation backlogs and jet fuel price volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market
Airport Operations
Canada Airport Operations Market
Airport Operations
Global Air Charter Services Market
Airport Operations
Airport Ground Handling Market
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
Business Jet Ground Handling Services Market
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
Middle East Airport Operations Market
Airport Operations
Global Airside Services Market
Airport Operations
France Airport Operations Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
Airport Terminal Operations Market
Airport Operations
South Korea Airport Operations Market
Airport Operations
UK Airport Operations Market
Airport Operations
Airport Operations Market
Airport Operations
Europe Airport Operations Market