
 Middle East Commercial Aircraft Cabin Seating Market | 2026-2036
Middle East Commercial Aircraft Cabin Seating Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Commercial Aircraft Cabin Seating Market Foresight
Maintenance and retrofit service contracts are rebalancing how seating value gets captured across the aircraft lifecycle. Safran SA leverages its MRO network to extend aftermarket revenue streams beyond original equipment sales. Collins Aerospace anchors its regional presence through integrated cabin systems that bundle seating with lighting and connectivity. RECARO Aircraft Seating GmbH & Co. KG specializes in lightweight structures that help carriers manage fuel burn on long-haul routes serving the Gulf.
Middle East commercial aircraft cabin seating comprises engineered passenger stations with load-rated frames, fire-blocking upholstery, and pitch-adjustable configurations designed for certified aircraft interiors. Primary construction employs aluminum or composite structures with foam cushioning and leather or fabric dress covers, manufactured through thermoforming, CNC machining, and automated sewing processes to meet flammability standards. Business class and premium economy segments command disproportionate margin pools as Gulf carriers compete through cabin experience differentiation. Smart seats with integrated power and connectivity are gaining traction fastest, though economy class volumes still dominate unit shipments across the regional fleet.
GCAA mandates align with EASA CS-25 airworthiness requirements for seat crashworthiness and flammability, while FAA TSO-C127b certifications govern supplier market access for US-origin platforms operating in the region. The UAE's General Civil Aviation Authority and Saudi Arabia's GACA are both tightening sustainability reporting requirements that will cascade into seating material selection and end-of-life recycling obligations. Stakeholders must monitor how Gulf carrier fleet plans and evolving certification harmonization between European and Middle Eastern regulators reshape procurement timelines and supplier qualification pathways.
Market Dynamics
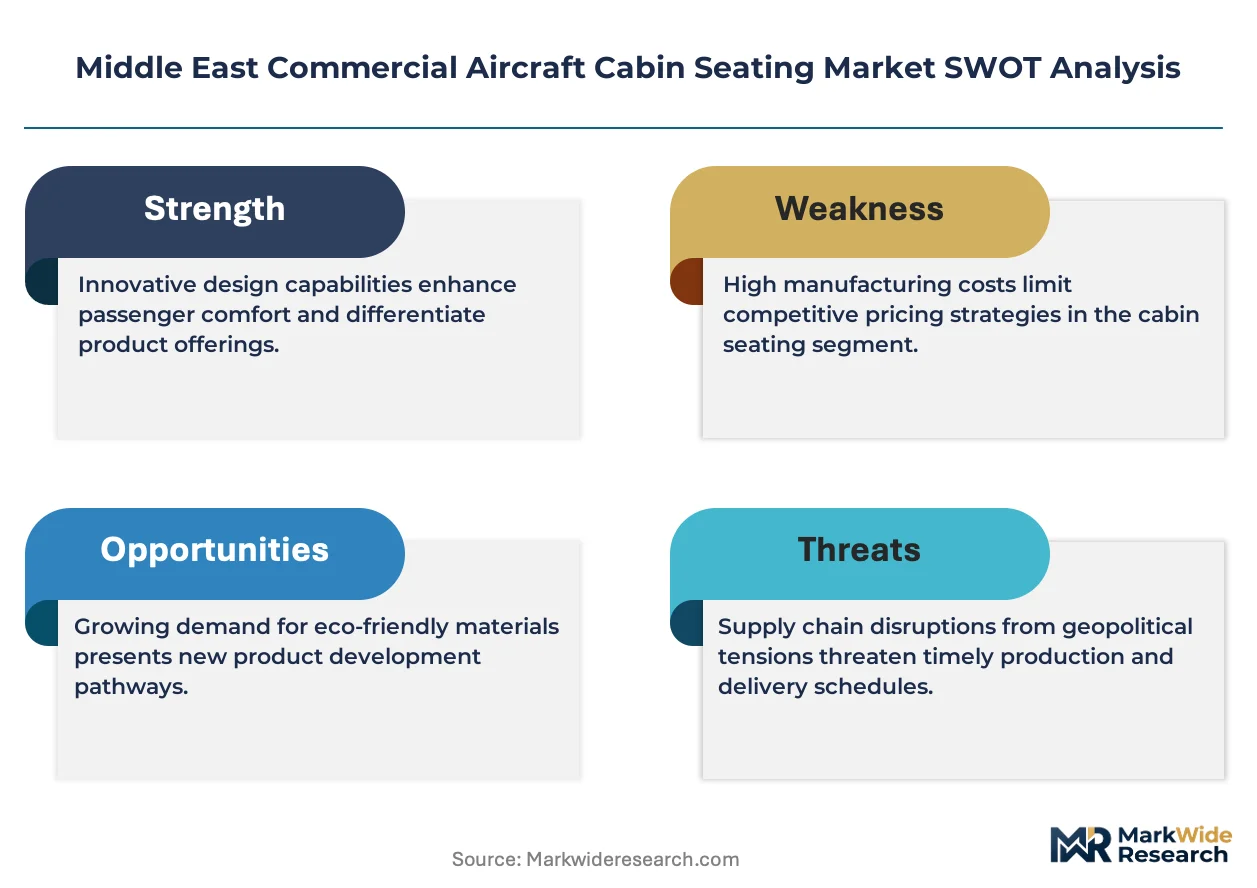
Gulf carrier fleet renewal cycles and GCAA-EASA certification harmonization are compressing supplier qualification timelines while expanding premium cabin retrofit pipelines.
Growth Catalysts
- GCAA-EASA alignment:Harmonized airworthiness standards under CS-25 reduce dual-certification burdens for seating manufacturers supplying UAE and Saudi operators.
- Fleet densification:Full-service carriers in Qatar and the UAE are expanding widebody orders with premium-heavy configurations that multiply per-aircraft seating values.
- Fire-blocking textile innovation:Advanced aramid and PBI blends meeting TSO-C127b flammability thresholds enable lighter seat designs without sacrificing crashworthiness ratings.
Market Restraints
- Aluminum price volatility:Primary seat frame material costs swing with LME pricing, squeezing margin visibility on long-delivery contracts.
- Supply concentration in Western Europe:Certification-capable upholstery and foam suppliers cluster in Germany and France, creating single-source vulnerability for Gulf-based MROs.
- Legacy platform compatibility:Retrofit demand for older Boeing 777 and Airbus A330 fleets requires costly frame redesigns to accommodate modern IFE integration.
Strategic Opportunities
- Saudi Arabia's GACA localization mandates:Vision 2030 industrial content rules create openings for joint-venture seat assembly facilities in Riyadh and Jeddah.
- Smart seat convergence:Integration of USB-C power, Bluetooth connectivity, and biometric sensors opens premium pricing tiers for business class installations.
- End-of-life recycling obligations:UAE sustainability reporting requirements for aircraft interiors drive demand for disassembly and material recovery services.
Industry Challenges
- Certification timeline compression:GCAA's accelerated approval pathways for modified seat designs strain engineering validation resources.
- Composite repair technician scarcity:Carbon fiber frame damage assessment requires specialized NDT skills that regional MRO networks lack at scale.
- Legacy IFE integration:Power and data cabling from 1990s-era seat architectures conflicts with modern slimline retrofit footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Commercial Aircraft Cabin Seating Market |
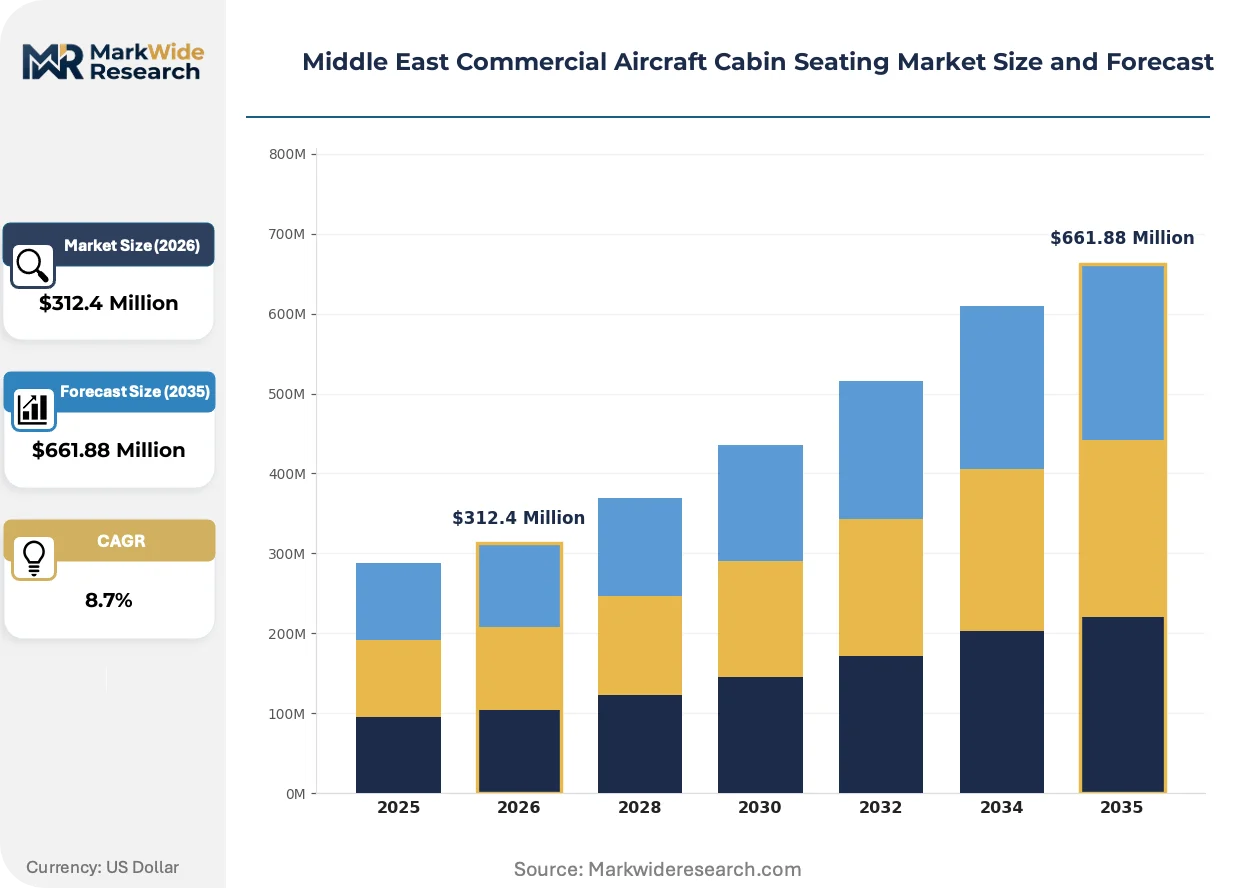
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seating Class: First Class, Business Class, Economy Class, Premium Economy Material Type: Leather, Fabric, Foam, Plastic Seat Configuration: 2-2, 3-3, 2-4-2, 1-2-1 Innovation Level: Standard, Ergonomic, Convertible, Smart Seats |
| Companies Covered | Safran SA, Collins Aerospace, RECARO Aircraft Seating GmbH & Co. KG, Diehl Stiftung & Co. KG, Jamco Corporation, STELIA Aerospace, Thompson Aero Seating, Adient Aerospace, Acro Aircraft Seating, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Commercial Aircraft Cabin Seating Market Shifts & Advancements
Seating architectures are pivoting from passive passenger accommodation to active cabin experience platforms, with weight reduction and connectivity integration as twin design imperatives.
Modular seat platforms are converging with standardized rail and track systems that permit rapid cabin reconfiguration between premium and economy densities. Emirates and Etihad are specifying these architectures for new A350 deliveries to preserve operational flexibility. This convergence is compressing the traditional trade-off between passenger comfort metrics and airline revenue optimization.
EASA's updated CS-25.853 flammability standards and GCAA's parallel adoption are tightening smoke and toxicity thresholds for cabin materials. Manufacturers must reformulate foam cushioning and dress cover substrates to meet amended heat release rates. Business class seating faces the steepest compliance costs due to multi-layer construction complexity and lower production volumes.
Carrier procurement teams are unbundling seat purchase from long-term MRO agreements, reversing the bundled lifecycle contracts that dominated the 2010s. Etihad and Qatar Airways now separately negotiate hardware supply and retrofit service tiers. This behavioral shift is most pronounced in the UAE, where Dubai's position as a regional MRO hub creates competitive aftermarket alternatives to OEM-captive service networks.
Middle East Commercial Aircraft Cabin Seating Market Segmentation
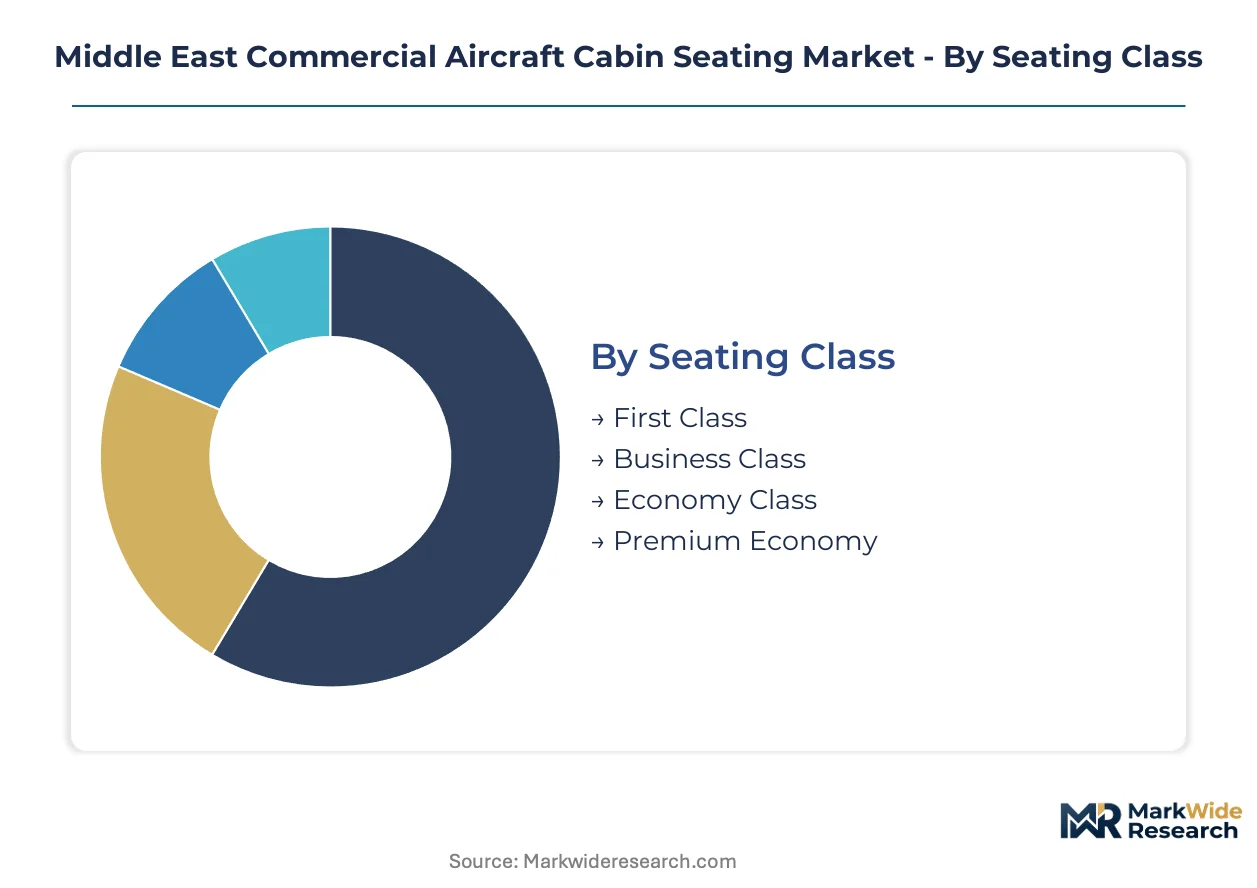
Seating procurement in the Middle East diverges sharply by cabin tier, with Gulf carriers optimizing fleet configurations around premium yield per square meter. Certification requirements from GCAA and EASA create asymmetric compliance burdens across segments, reshaping supplier qualification strategies.
Seating Class:
First class and business class installations demand TSO-C127b flammability certification plus CS-25.561 crashworthiness validation, while economy configurations face streamlined approval pathways under GCAA's accelerated certification framework.
- First Class:Enclosed suite architectures with lie-flat beds, personal storage, and privacy doors require multi-layer fire-blocking assemblies and complex electrical integration for IFE and climate control. Emirates' A380 fleet and Etihad's Residence product anchor regional demand in the UAE, though production volumes remain constrained by narrowbody fleet retirements.
- Business Class:Reverse herringbone and staggered seating configurations dominate Qatar Airways' Qsuite and Emirates' 777 retrofit programs, commanding premium pricing through direct aisle access and convertible dining surfaces. Saudi Arabia's GACA localization mandates are pressuring suppliers to establish regional assembly capacity for this high-margin segment.
- Economy Class:Slimline designs with 31-32 inch pitch specifications ship in highest volumes across LCC fleets serving Dubai and Sharjah.
- Premium Economy:Hybrid recline mechanisms and increased legroom variants are gaining traction on Emirates' A350 and Etihad's 787 routes to European destinations.
Leading the category by volume: Economy Class. Growing fastest: Premium Economy.
Material Type:
Material selection tracks directly against flammability performance tiers, with EASA CS-25.853 amendments driving reformulation across upholstery and cushioning supply chains.
- Leather:Full-grain and corrected-grain hides treated with fire-retardant topcoats dominate first and business class dress covers, with Italian and German tanneries supplying Gulf carriers through certified Tier-2 converters. UAE-based MROs are developing in-house leather refurbishment capabilities to capture lifecycle value.
- Fabric:Wool-nylon blends and technical textiles meeting heat release rate thresholds are displacing leather in premium economy cabins on Saudi Arabian Airlines' domestic fleet renewal.
- Foam:Viscoelastic and polyurethane cushioning layers with integrated fire-blocking barriers face reformulation costs under amended GCAA smoke toxicity standards.
- Plastic:Injection-molded ABS and polycarbonate components for tray tables, armrests, and decorative trim panels concentrate manufacturing in Western European supplier clusters.
Highest certification burden: Leather. Steepest cost escalation: Foam.
Seat Configuration:
Configuration choices reflect route-specific yield optimization, with widebody densification trends compressing traditional pitch standards while preserving aisle access premiums.
- 1-2-1:Direct aisle access layouts in business class maximize privacy and sleeping surface dimensions, specified by Qatar Airways for 777X and A350-1000 deliveries. These configurations multiply per-aircraft seat counts while elevating unit values through integrated storage and power systems.
- 2-4-2:Widebody economy layouts on Emirates' A380 upper deck and Etihad's 787-9 fleet balance passenger throughput with galley and lavatory adjacency requirements.
- 2-2:Narrowbody business class configurations on A321LR and 737 MAX fleets serving regional Gulf routes.
- 3-3:Single-aisle economy standards dominate Flydubai and Air Arabia short-haul networks from Dubai and Sharjah hubs.
Widest deployment: 3-3. Expanding most quickly: 1-2-1.
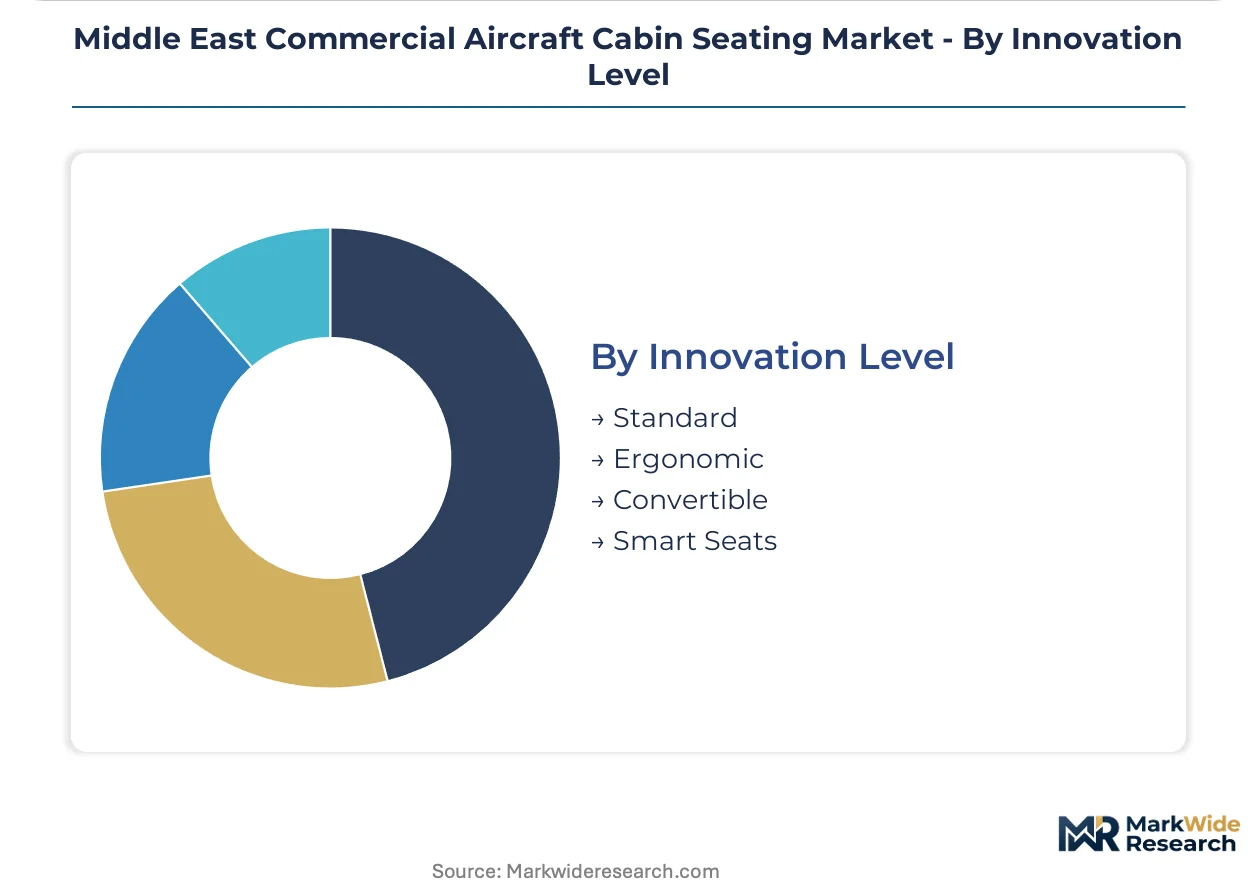
Innovation Level:
Technology integration intensity separates procurement tiers, with smart seat architectures requiring supplemental type certificates for electrical and connectivity systems.
- Smart Seats:Sensor-embedded cushions tracking occupancy and biometric stress indicators, combined with USB-C power delivery and Bluetooth audio pairing, are specified for Emirates' next-generation A350 business class. These systems demand FCC and CE marking for passenger device interoperability plus GCAA validation for aircraft installation.
- Convertible:Mechanisms permitting rapid cabin reconfiguration between business and economy densities are being trialed by Etihad for seasonal route adjustments.
- Ergonomic:Lumbar support actuation and adjustable headrests feature in Saudi Arabian Airlines' premium economy rollout.
- Standard:Fixed-recline designs with passive cushioning retain dominance across LCC and charter operator fleets.
Climbing the fastest: Smart Seats. Deepest installed base: Standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seating production concentrates in Western European manufacturing clusters while consumption centers on Gulf carrier fleet bases. The UAE and Saudi Arabia absorb the majority of regional procurement volume through Dubai, Abu Dhabi, and Riyadh hub operations.
United Arab Emirates
Dubai International and Zayed International airports drive premium cabin retrofit demand as Emirates and Etihad expand A350 and 777X fleets. GCAA mandates EASA CS-25 alignment for all new seat certifications, compressing supplier qualification timelines. Jebel Ali's aviation logistics zone hosts regional MRO facilities that capture aftermarket seating refurbishment contracts.
Saudi Arabia
Saudia and Riyadh Air fleet expansion under Vision 2030 accelerates widebody seating procurement with local content requirements. GACA localization rules pressure suppliers to establish Jeddah and Riyadh assembly partnerships. King Abdulaziz International Airport's terminal expansion creates concentrated demand for business class installations.
Qatar
Qatar Airways' Qsuite retrofit programs and 777X deliveries sustain Doha's position as a premium seating demand center. The Qatar Civil Aviation Authority maintains EASA-equivalent certification standards for seat crashworthiness validation. Hamad International Airport's capacity expansion drives concurrent galley-lavatory-seating integration projects.
Kuwait
Kuwait Airways' narrowbody renewal generates economy and business class seating volumes below Gulf tier-one carrier scale. The Directorate General of Civil Aviation applies GCAA-harmonized flammability standards for interior materials. Kuwait International Airport's terminal modernization concentrates limited procurement activity.
Oman
Oman Air's fleet right-sizing produces selective premium cabin upgrade cycles rather than fleet-wide replacements. The Public Authority for Civil Aviation enforces EASA-aligned certification for modified seat designs. Muscat International Airport serves as a secondary hub with lower per-aircraft seating values than UAE or Saudi operations.
Middle East Commercial Aircraft Cabin Seating Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct manufacturing and engineering tiers. The market structures around three player categories: integrated cabin systems providers, specialized seat manufacturers, and regional assembly joint ventures. Consolidation pressures favor multi-product portfolios that bundle seating with lighting, connectivity, and galley systems. Strategic moves center on MRO network expansion and Saudi localization partnerships to satisfy GACA industrial content mandates.
Among European-based manufacturers, Safran SA, RECARO Aircraft Seating GmbH & Co. KG, and Diehl Stiftung & Co. KG occupy positions across the premium and economy seating spectrum. These firms exemplify the certification-capable tier that dominates Gulf carrier procurement through EASA-aligned validation capabilities. Their geographic concentration in Germany and France creates supply chain vulnerability that Saudi localization initiatives aim to dilute.
| Leading Market Players |
|---|
| Safran SA |
| Collins Aerospace |
| RECARO Aircraft Seating GmbH & Co. KG |
| Diehl Stiftung & Co. KG |
| Jamco Corporation |
| STELIA Aerospace |
| Thompson Aero Seating |
| Adient Aerospace |
| Acro Aircraft Seating |
| Others |
Supply & Pricing Matrix
Captive upholstery and foam supply from German and French Tier-2 converters anchors both procurement security and margin structures for Gulf carrier seating programs. This backward integration into certified material streams lets manufacturers defend premium pricing for TSO-C127b compliant assemblies while exposing economy tier producers to aluminum frame cost volatility.
Pricing Analysis
Margin tightening in economy class reflects LME aluminum swings and Flydubai's volume-driven procurement leverage. Three-tier pricing structure across premium, standard, and economy levels separates crashworthiness-certified business class suites from streamlined GCAA accelerated-approval economy seats. Price differentiation rests on EASA CS-25.561 validation tier and after-sales MRO bundling. Cost-down pressure on slimline configurations accelerates because Sharjah-based LCCs negotiate unbundled hardware-only contracts.
Supply Chain Analysis
Direct-to-OEM channels handle Emirates and Etihad fleet renewal demand while regional MRO distributors serve retrofit aftermarket. Manufacturing gravity centers on Germany, France, and Italy for certification-capable seat frames and fire-blocking textiles. Raw material flows draw from aerospace-grade aluminum suppliers, Italian tanneries, and specialty aramid fiber producers. Single-source vulnerability concentrates in Western European foam and upholstery converters. Distribution runs through Jebel Ali aviation logistics zones for UAE-based carrier programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart seat architectures with integrated power and biometric systems are displacing passive cushioning platforms across Gulf carrier procurement specifications. This technology transition compresses supplier qualification timelines while elevating compliance burdens for electrical system validation.
For Market Incumbents: Anchor regional MRO network density to defend aftermarket revenue against Etihad's unbundled procurement shift. Expand Jeddah assembly partnerships ahead of GACA localization enforcement. Prioritize GCAA-EASA dual certification investment to compress rival qualification windows for A350 and 777X programs. For New Entrants and Emerging Players: Lightweight composite frame expertise offers entry into Saudi Arabian Airlines' premium economy rollout where incumbent capacity constraints create qualification gaps. Target Kuwait Airways narrowbody renewal volumes below tier-one carrier procurement scale. Lead with accelerated GCAA certification timelines as the primary go-to-market angle against established European suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in regional assembly joint ventures satisfying Vision 2030 industrial content rules. Long-term viability hinges on MRO service network control rather than hardware manufacturing scale. Monitor GACA enforcement intensity on localization mandates as the primary inflection signal for Saudi market access value.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Assembly Joint Venture | Jeddah and Riyadh facilities satisfy GACA localization mandates while preserving EASA certification alignment. |
| Smart Seat Platform Launch | USB-C power and biometric integration command premium positioning in Emirates A350 business class specifications. |
| MRO Network Expansion | Jebel Ali refurbishment capabilities capture lifecycle value from unbundled procurement contracts at Dubai-based carriers. |
| Fire-Blocking Material Reformulation | Aramid-PBI blend development meets amended GCAA smoke toxicity thresholds for CS-25.853 compliance. |
| Composite Repair Technician Training | Regional NDT skill development addresses carbon fiber damage assessment gaps in Gulf MRO networks. |
Research Methodology
GCAA certification databases, EASA CS-25 amendment records, and fleet delivery schedules from Emirates and Etihad formed the secondary backbone for market sizing. Primary interviews with aircraft interior procurement directors, MRO facility managers, and seating manufacturer program managers validated demand assumptions. Bottom-up triangulation against top-down carrier fleet plans anchored volume projections.
Bottom-up modeling aggregated individual aircraft seating configurations by cabin class and airline program, while top-down analysis cross-checked against regional fleet renewal capex disclosures. Segmentation dimensions included seating class, material type, seat configuration, and innovation level across the projection horizon. CAGRs derived from fitted trend lines on historical delivery data and announced order backlogs. Forecast inputs incorporated aluminum price sensitivity and certification timeline compression scenarios.
Several conditions sit outside the modeled scope, including unannounced fleet retirements, geopolitical disruptions to Western European supply flows, and abrupt shifts in GCAA-EASA harmonization pace. Forecasts reflect assumptions on carrier delivery schedule adherence and certification pathway stability. Practitioners should monitor GACA localization enforcement announcements and Emirates A350 entry-into-service timing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Global Aircraft Enclosures Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Global Aircraft Cabin Upgrades Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market