
 Europe Ammunition Market | 2026-2036
Europe Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ammunition Market Foresight
Market Context with Strategic Players
Modular propellant systems and programmable fuze technology is tilting production lines toward precision effects rather than mass-volume output. Rheinmetall AG leverages its Rh-120 tank gun platform dominance to anchor artillery shell contracts across Bundeswehr and export programs. BAE Systems plc sustains naval ammunition lines through its Glasgow manufacturing base, competing for Royal Navy and NATO fleet replenishment orders. Nammo AS specializes in shoulder-launched munitions and small-caliber specialty rounds, positioning its Nordic plants as alternative supply nodes amid continental capacity constraints.
Technical Definition and Structural Segments
Europe ammunition encompasses complete rounds, projectiles, propellant charges, and fuzes engineered to specific pressure curves, chamber dimensions, and ballistic coefficients for defined weapon systems. Brass-cased cartridges with Boxer or Berdan priming remain standard for NATO small arms interoperability, while steel and polymer alternatives reduce material cost and weight in training and certain operational loads. Cartridges and shells together occupy the largest value share, with shell production drawing premium margins from guided and extended-range variants. Military usage dominates absolute volume, though sports shooting and hunting sustain steady commercial demand through specialized distribution networks. Small caliber rounds face margin compression from scale competition, while medium and large calibers retain pricing power through limited qualified suppliers and complex forging requirements.
Regulatory Frame and Forward Outlook
REACH regulates chemical constituents in primers and propellants across EU manufacturing, while the EU Green Deal accelerates substitution timelines for lead styphnate and other toxic initiators. ECHA authorization processes and national explosives regulators in Germany, France, and Italy shape product approval cycles and cross-border transfer protocols. National procurement offices must weigh supply security against environmental compliance timelines as reformulation investments stretch qualification periods.
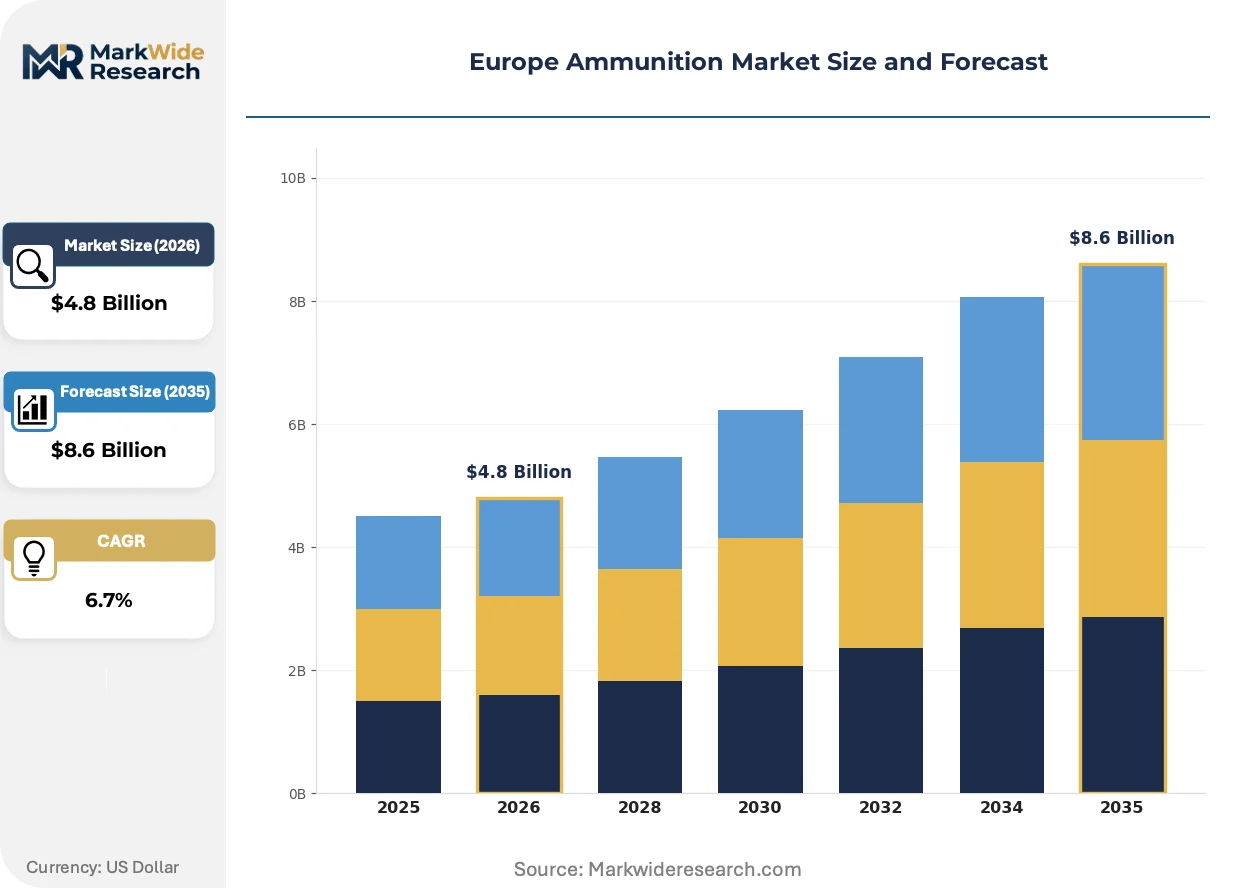
Market Dynamics
REACH authorization timelines and the EU Green Deal are compressing product development cycles while forcing simultaneous investment in lead-free primer chemistry and legacy line maintenance across European manufacturing plants.
Growth Catalysts
- Artillery modernization programs:NATO member states are expanding 155mm precision-guided shell inventories to replenish depleted stockpiles and extend range requirements.
- REACH substitution mandates:Regulatory pressure to eliminate lead styphnate and toxic heavy metals is accelerating R&D funding for green initiator chemistry.
- Poland's defense acceleration:Warsaw's procurement office is issuing multi-year framework agreements for small-caliber ammunition to build sovereign manufacturing capacity.
Market Restraints
- Nitrocellulose supply concentration:European propellant manufacturers depend on a narrow supplier base for refined cotton linters, creating input volatility.
- ECHA authorization friction:New chemical entity approvals for primer reformulations extend qualification periods by 18-36 months beyond traditional timelines.
- Qualified forging capacity scarcity:Large-caliber shell body production requires specialized press equipment concentrated in Germany and France.
Strategic Opportunities
- Romania and Bulgaria expansion:Underdeveloped ammunition industrial bases in southeastern Europe offer greenfield facility locations with lower labor costs and EU funding access.
- Polymer cartridge convergence:Combining polymer case technology with telescoped ammunition designs opens weight reduction contracts for next-generation infantry weapons.
- EU Defense Fund alignment:Collaborative procurement mechanisms are creating pooled R&D budgets for cross-border ammunition standardization projects.
Industry Challenges
- Explosives chemist talent scarcity:Retirement waves among formulation specialists are outpacing university pipeline output across Germany, France, and Sweden.
- Dual-use export licensing complexity:National authorities apply inconsistent interpretation of EU Common Military List categories, fragmenting cross-border transfer protocols.
- Legacy press equipment integration:Modern programmable fuze assembly lines must interface with 1970s-era forging and finishing machinery without production interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ammunition Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Balls, Shells, Cartridges, Rockets Usage: Military, Law Enforcement, Hunting, Sports Shooting Material: Brass, Steel, Aluminum, Polymer Caliber: Small, Medium, Large, Specialty |
| Companies Covered | Rheinmetall AG, BAE Systems plc, General Dynamics Corporation, Leonardo S.p.A., KNDS N.V., FN Herstal, Nammo AS, Thales Group, Northrop Grumman Corp, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ammunition Market Shifts & Advancements
Digital manufacturing controls and chemistry substitution pressures are converging to transform how European ammunition is formulated, qualified, and delivered to military buyers.
Programmable air-burst fuzes with embedded micro-electromechanical systems are rendering obsolete traditional point-detonating designs for infantry and artillery applications. Bundeswehr and French Army procurement offices are embedding these requirements into new vehicle and weapon platform specifications. The shift is compressing margins for fuze suppliers unable to demonstrate software-defined effects programming.
EU Green Deal implementation timelines are forcing simultaneous reformulation of primer mixes and propellant stabilizers ahead of full REACH authorization cycles. Manufacturers face parallel investment in toxicology testing and production line revalidation. Small-caliber cartridge producers in Germany and Italy are most exposed given their higher volume throughput and thinner margin structures.
Framework contracting is consolidating formerly fragmented national procurement into multi-year, multi-nation agreements with performance-based logistics clauses. Traditional spot-ordering through national arsenals is giving way to vendor-managed inventory systems. The transformation is most advanced in Nordic and Baltic procurement offices seeking interoperability guarantees through pooled stockpiling arrangements.
Europe Ammunition Market Segmentation
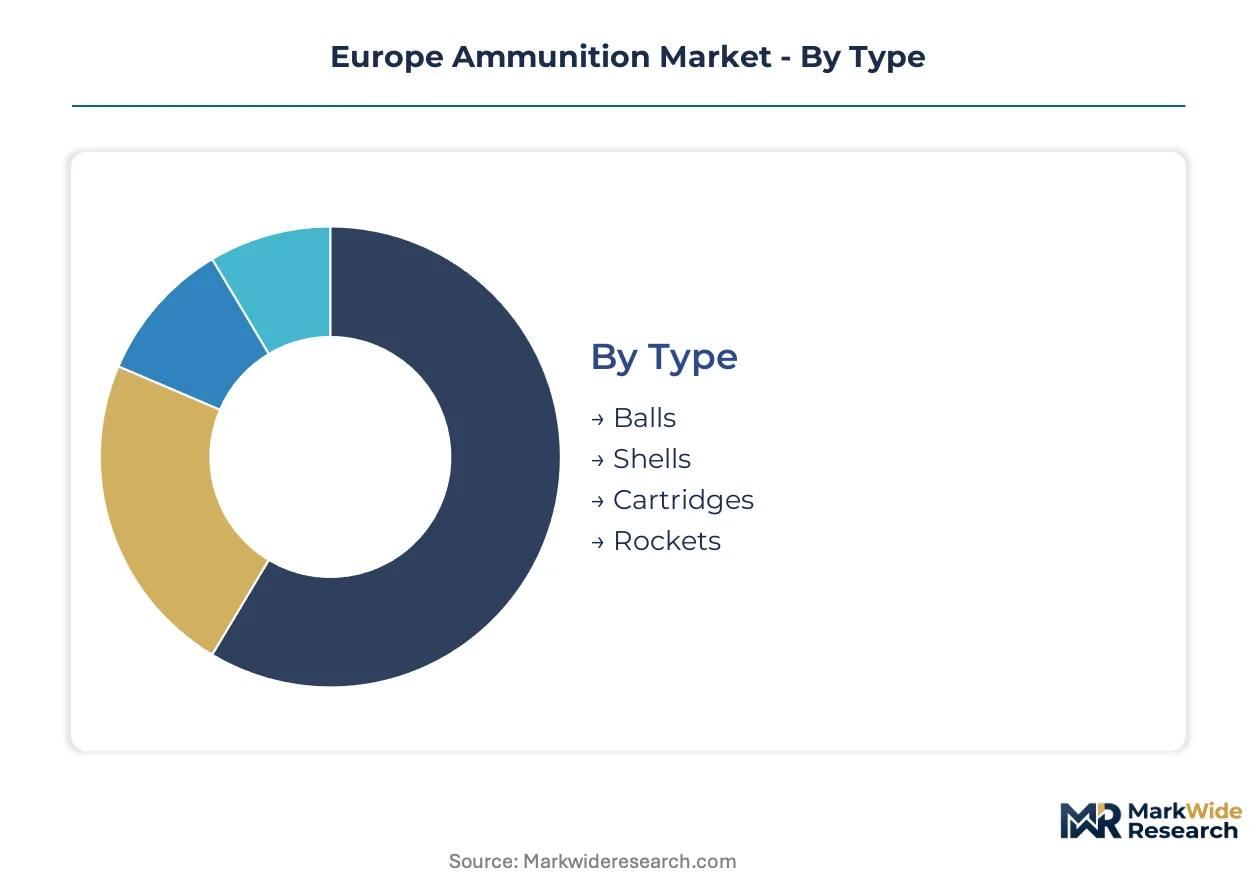
Segmentation reveals how procurement patterns and regulatory pressures fragment the European ammunition landscape. Different end-users impose divergent technical specifications, certification requirements, and volume rhythms that reshape supplier priorities across the value chain.
Type:
After-sales service intensity varies dramatically by ammunition type, with precision-guided shells demanding embedded diagnostics support while ball ammunition requires minimal technical follow-through.
- Shells:Steel or forged alloy projectiles paired with variable propellant charges and programmable fuzes for artillery systems. Bundeswehr and French Army procurement offices are embedding air-burst fuze requirements into 155mm platform specifications, stretching supplier qualification timelines.
- Cartridges:Complete small arms rounds integrating case, primer, propellant, and projectile in standardized NATO chamberings. Polish defense acceleration programs are driving multi-year framework agreements for 5.56mm and 7.62mm inventories to build sovereign manufacturing capacity.
- Balls:Solid projectiles without explosive payload, primarily for training and small arms applications. German and Italian producers face REACH-driven reformulation costs for lead-free projectile cores.
- Rockets:Self-propelled munitions with integral motor systems for shoulder-launched and vehicle-mounted applications. Nordic procurement offices prioritize interoperability through pooled stockpiling arrangements for anti-armor variants.
Shells hold the largest share; momentum sits with Cartridges as Poland and Baltic states expand small-caliber inventories.
Usage:
Cost tier stratification separates military-grade certified production from commercial segments where price sensitivity dominates procurement decisions.
- Military:NATO-standardized rounds subject to STANAG qualification, lot acceptance testing, and traceability protocols. German, French, and Polish defense budgets are expanding fastest, concentrating demand for precision-guided artillery and small-caliber resupply.
- Law Enforcement:Reduced-penetration and frangible rounds optimized for urban engagement scenarios. Italian and Spanish national police procurement offices are consolidating formerly fragmented spot-ordering into multi-year supply agreements.
- Hunting:Specialized projectiles with controlled expansion characteristics for game compliance regulations. Scandinavian markets sustain steady demand through specialized distribution networks despite seasonal volume fluctuations.
- Sports Shooting:Match-grade ammunition with tight velocity and dimensional tolerances for competitive disciplines. German and Czech shooting federations maintain certification standards that limit qualified supplier pools.
Military usage commands absolute volume; Law Enforcement is expanding most quickly as national police forces consolidate procurement.
Material:
Volume concentration in brass-cased NATO standard rounds creates procurement rigidity, while alternative materials open weight reduction and cost optimization pathways.
- Brass:Copper-zinc alloy cases with established NATO interoperability and reloading compatibility. Bundeswehr and Royal Navy specifications mandate brass for operational loads despite higher material costs.
- Polymer:Injection-molded composite cases enabling 20-30% weight reduction for dismounted infantry loads. Telescoped ammunition designs are converging with polymer technology in next-generation weapon development programs.
- Steel:Lacquer-coated or polymer-jacketed cases for cost-sensitive training applications. Eastern European arsenals maintain legacy production lines with steel-case dominance.
- Aluminum:Lightweight alternative with limited reloading viability, positioned between brass performance and steel economy. Italian commercial producers have scaled aluminum lines for hunting and sports segments.
Brass retains the largest installed base; Polymer is gaining share fastest as weight reduction contracts multiply across NATO modernization programs.
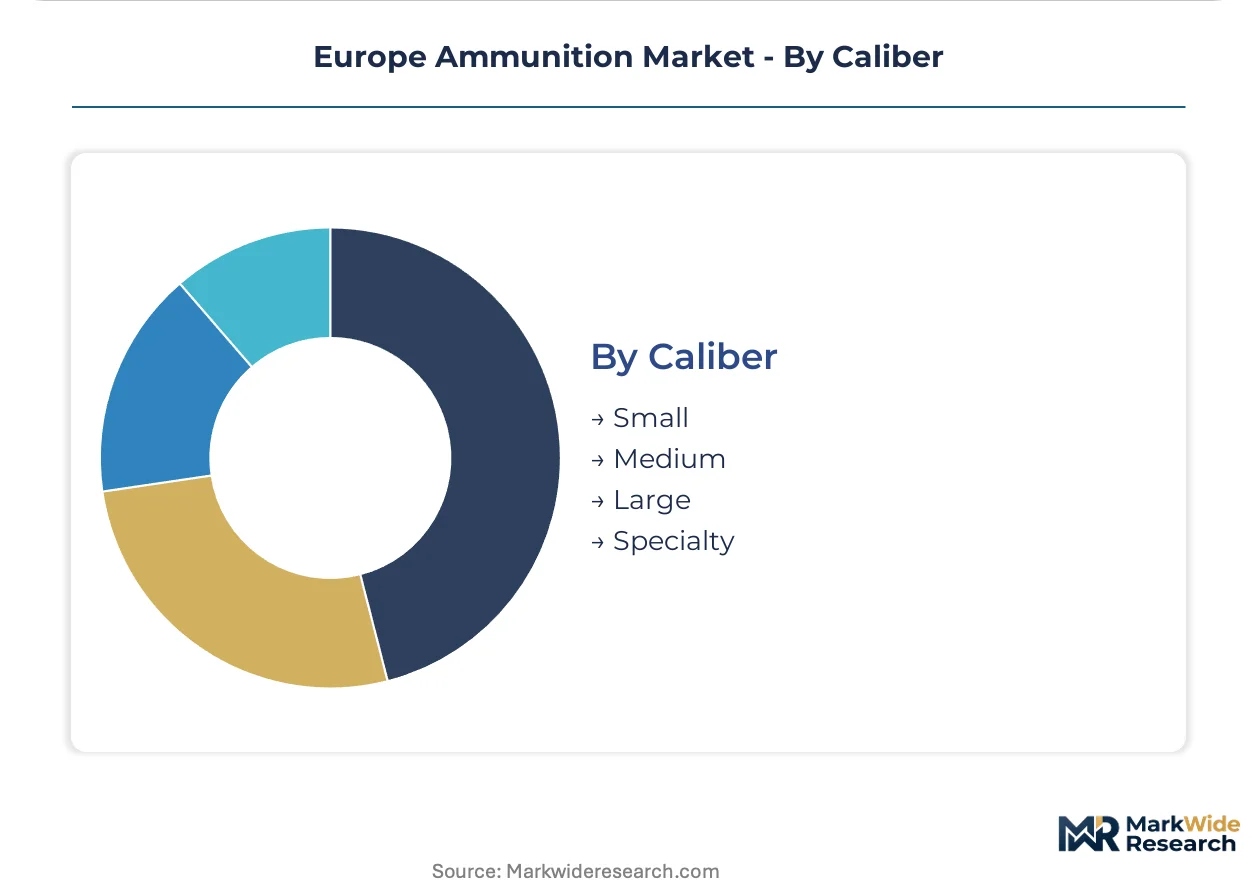
Caliber:
Supply concentration in large-caliber forging capacity creates margin differentiation, while small-caliber segments face scale-driven price compression.
- Large:120mm tank gun and 155mm artillery rounds requiring specialized press equipment concentrated in Germany and France. Extended-range and guided variants draw premium margins from limited qualified suppliers.
- Small:Pistol and rifle cartridges from 9mm through 7.62mm NATO, produced at highest volume across European plants. Margin compression from scale competition is most acute in this segment.
- Medium:Crew-served weapon rounds including 12.7mm and 40mm grenade systems. Romanian and Bulgarian expansion opportunities target this caliber band for greenfield capacity.
- Specialty:Subsonic, armor-piercing, and reduced-ricochet rounds for specific tactical requirements. Nammo AS and niche European producers dominate through formulation expertise rather than scale.
Small caliber holds the largest share; Large caliber shows the steepest expansion trajectory as artillery modernization programs accelerate across NATO member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Polish defense procurement offices concentrate the region's largest ammunition contracts, with Bundeswehr framework agreements and Warsaw's sovereign manufacturing push anchoring buyer-side leverage across NATO supply chains.
Germany
Bundeswehr artillery modernization programs are driving 155mm precision-guided shell demand through multi-year procurement frameworks. REACH authorization timelines from ECHA are compressing lead-free primer qualification cycles for domestic manufacturers. The Rhineland industrial corridor hosts concentrated forging capacity for large-caliber shell bodies, with press equipment investments accelerating near Oberndorf and Unterlüß.
Poland
Warsaw's procurement office is issuing sovereign manufacturing mandates for 5.56mm and 7.62mm cartridge production to reduce import dependency. National defense acceleration programs align with EU Defense Fund collaborative mechanisms for cross-border standardization. The Radom and Skarżysko-Kamienna industrial zones are attracting greenfield ammunition facility investments with EU structural funding support.
France
French Army requirements for programmable air-burst fuzes are embedding software-defined effects into 155mm platform specifications. ANSM explosives licensing protocols shape product approval cycles for primer reformulations ahead of full REACH compliance. The Bourges and Saint-Étienne manufacturing clusters maintain specialized forging and fuze assembly lines for NATO export programs.
Italy
Carabinieri and national police procurement consolidation is shifting law enforcement ammunition from spot-ordering to multi-year supply agreements. ECHA-driven toxicology testing requirements are stretching qualification periods for small-caliber lead-free projectile cores. The Lombardy and Piedmont regions retain commercial cartridge production capacity for hunting and sports shooting distribution networks.
Sweden
Nordic defense procurement offices are pooling stockpiling arrangements for anti-armor rocket interoperability across Baltic Sea coordination frameworks. National explosives regulators enforce stringent formulation standards that limit qualified supplier pools for specialty munitions. The Karlskoga manufacturing base anchors regional capacity for shoulder-launched munitions and reduced-ricochet tactical rounds.
Europe Ammunition Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply structures, with consolidated forging capacity in Germany and France anchoring premium large-caliber positions while fragmented small-caliber segments face scale-driven margin compression. Three archetypes dominate: integrated defense conglomerates with platform-ammunition bundling power, specialized explosives chemists with formulation IP, and state-linked arsenals with captive domestic demand. Competitive moves concentrate on capacity expansion in southeastern European greenfield sites and strategic partnerships for polymer cartridge technology licensing.
Among German-based integrated suppliers, Rheinmetall AG exemplifies the platform-anchored archetype through tank gun system bundling, while KNDS N.V. represents the Franco-German cross-border consolidation model. Nammo AS occupies the Nordic specialist position with shoulder-launched munitions expertise. These three entities illustrate how geographic clustering, state procurement relationships, and technical specialization stratify competitive positioning across NATO supply chains.
| Leading Market Players |
|---|
| Rheinmetall AG |
| BAE Systems plc |
| General Dynamics Corporation |
| Leonardo S.p.A. |
| KNDS N.V. |
| FN Herstal |
| Nammo AS |
| Thales Group |
| Northrop Grumman Corp |
| Others |
Supply & Pricing Matrix
Nitrocellulose supply concentration in Eastern European cotton linter refineries channels margin capture toward German and French propellant blenders, while forging press scarcity in the Rhineland and Bourges clusters locks premium pricing into large-caliber shell contracts. Cost-plus frameworks with NATO procurement offices index raw material escalators to commodity benchmarks, compressing margin buffers for small-caliber cartridge producers facing REACH-driven reformulation overhead.
Pricing Analysis
Cost-plus contracts with NATO framework agreements index nitrocellulose and brass ingot prices to London Metal Exchange benchmarks, insulating prime contractors from input volatility while transferring risk to downstream component suppliers. Price differentiation rests on STANAG certification tier and lot-traceability depth, with Bundeswehr operational loads commanding premiums over training-grade allocations. Cost compression in small-caliber segments is intensifying because Polish sovereign manufacturing mandates are introducing volume competition into previously protected national supply chains. Eastern European training ammunition buyers exhibit highest price sensitivity; French and German military procurement offices show lowest elasticity given platform-interoperability requirements.
Supply Chain Analysis
Supply-chain finance facilities from Rheinmetall and KNDS extend 90-120 day payment terms to qualified forging subcontractors, stabilizing working capital for press operators amid volatile input costs. Geographic supply concentration centers on Germany, France, and Poland for finished ammunition, with nitrocellulose precursor sourcing drawn from Czech and Hungarian chemical processors. Raw material dependencies include cotton linters for propellant bases, brass rod for cartridge cases, and tungsten alloys for penetrator cores. Single-source vulnerability runs through the narrow qualified supplier base for 155mm shell forging presses concentrated in Oberndorf and Bourges. Distribution runs through national arsenals and vendor-managed inventory systems for military end-users, with commercial channels feeding hunting and sports segments through specialized retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
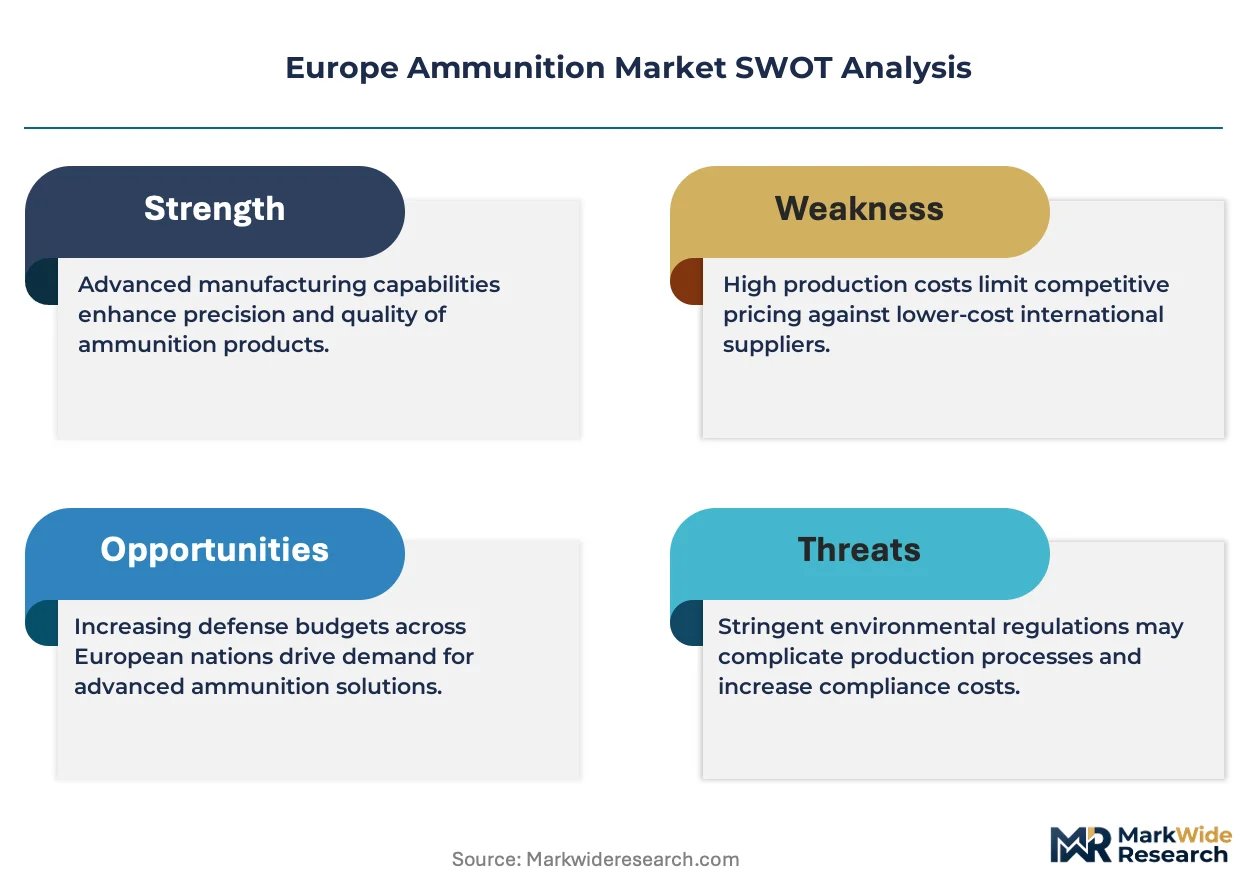
Fragmentation across caliber bands and national procurement silos creates niche entry points, as Poland's sovereign manufacturing push and REACH reformulation timelines disrupt established supplier relationships. Modular primer chemistry and polymer cartridge platforms enable specialist positioning without full-scale forging investments.
For Market Incumbents: Harden platform-ammunition bundling power by embedding programmable fuze requirements into next-generation artillery specifications, locking out competitors lacking software-defined effects capabilities. Acquire or partner with lead-free primer formulation specialists in Italy and Spain to compress ECHA qualification timelines before REACH deadlines tighten. Capacity addition in Romanian greenfield sites captures EU structural funding while hedging against German labor cost escalation. For New Entrants and Emerging Players: Build out polymer cartridge assembly capacity in Bulgaria or Romania to serve NATO weight-reduction contracts without competing for scarce forging press access. The most penetrable segment sits with medium-caliber crew-served weapon rounds, where Romanian industrial zones offer greenfield locations with lower qualification barriers than established German or French facilities. Go-to-market leverage rests on EU Defense Fund collaborative procurement mechanisms, positioning entrants as cross-border standardization partners rather than national spot suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty chemicals firms holding explosives formulation IP but lacking ammunition integration. Long-term viability favors platforms with embedded software content and recurring qualification revenue streams over pure manufacturing scale. Acquisition targets should show demonstrated ECHA pre-registration for lead-free primer candidates. The signal to watch is Bundeswehr and French Army embedding air-burst fuze requirements into platform specifications, accelerating consolidation among programmable effects suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Primer Reformulation | ECHA authorization timelines compress competitive windows for REACH-compliant chemistry. |
| Polymer Cartridge Scale-Up | Telescoped ammunition designs from Nexter and Rheinmetall drive polymer case adoption. |
| Romanian Greenfield Capacity | EU structural funding lowers capital barriers for medium-caliber forging investments. |
| Programmable Fuze Integration | French Army software-defined effects requirements reshape artillery supplier tiers. |
| EU Defense Fund Alignment | Collaborative procurement pools R&D budgets for cross-border ammunition standardization. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with Bundeswehr procurement officers, French Army artillery program managers, ECHA regulatory specialists, and explosives chemists at Nordic and German manufacturers providing operational perspective. Secondary validation drew from NATO STANAG documentation, ECHA authorization registers, EU Defense Fund award disclosures, and national defense budget appropriations. Bottom-up triangulation across caliber-specific production volumes and top-down reconciliation against national procurement frameworks anchored value estimates.
Calibration against historical NATO replenishment cycles and Polish sovereign manufacturing announcements refined demand assumptions across the projection horizon. Segmentation dimensions modeled include ammunition type, military versus commercial usage, case material, and caliber band, with additional cross-cutting analysis of REACH compliance status and programmable fuze integration depth. CAGRs were derived from slope-log regression across disclosed national framework values and implied production ramp schedules, with nitrocellulose supply elasticity and forging press utilization rates as industry-specific sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Romanian greenfield entrants or accelerated REACH enforcement by ECHA would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Guns and Accessories Market
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
Smart Bombs Market
Weapons and Ammunition
Recoilless Rifle Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Asia-Pacific Ammunition Market
Weapons and Ammunition
Cruise Missile Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Asia-Pacific Nuclear Bombs and Missiles Market
Weapons and Ammunition
Turret System Market
Weapons and Ammunition
Smart Weapons Market