
 Americas Ballistic Missile Market | 2026-2036
Americas Ballistic Missile Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Ballistic Missile Market Outlook
Premium solid-fuel propulsion systems is decoupling from commodity liquid-engine alternatives across the Americas Ballistic Missile landscape. Lockheed Martin Corporation leverages its vertically integrated solid-rocket motor supply chain to dominate land-based strategic programs. Northrop Grumman Corporation sustains its position through captive production of composite aeroshells and guidance electronics. Aerojet Rocketdyne anchors the propulsion tier with specialized thrust-vectoring technologies for submarine-launched platforms.
Ballistic missiles are self-propelled strategic weapons systems delivering payloads along ballistic trajectories, typically incorporating multi-stage solid or liquid propulsion with inertial or satellite-augmented guidance achieving circular error probable measurements below ten meters. Sea-based platforms lead procurement volume across the Americas due to nuclear deterrent patrol requirements and Ohio-class replacement programs. Hypersonic technology represents the fastest-expanding segment as defense agencies prioritize maneuverable reentry vehicles capable of evading existing interceptor networks. Conventional warhead configurations remain the mature margin pool, sustaining upgrade cycles rather than generational replacement.
The U.S. Department of Defense and Brazil's national aerospace regulator shape demand through defense acquisition regulations and technology transfer protocols governing cross-border component flows. The FAA and U.S. State Department ITAR framework restrict propulsion and guidance exports, concentrating supplier relationships within cleared domestic and allied channels. Stakeholders must monitor evolving congressional appropriations for next-generation interceptor architectures and corresponding test infrastructure investments.
Market Dynamics
Hypersonic glide vehicle countermeasures are forcing a fundamental reconfiguration of interceptor architectures across the Americas, redirecting R&D investment toward maneuverable reentry vehicle tracking and non-ballistic trajectory prediction systems.
Growth Catalysts
- Ohio-class Replacement Program:The U.S. Navy's submarine modernization is accelerating sea-based platform procurement, sustaining solid-fuel propulsion demand through 2035.
- ITAR Framework Consolidation:U.S. State Department export controls are concentrating supplier relationships within cleared domestic channels, reinforcing captive production networks.
- Southwestern Test Infrastructure:Arizona and New Mexico missile defense ranges are anchoring contractor activity, creating localized production clusters for next-generation interceptors.
Market Restraints
- Specialized Material Concentration:Composite aeroshell and advanced ceramic production remains concentrated among cleared domestic suppliers, creating single-source vulnerability.
- ITAR Licensing Friction:U.S. State Department technology transfer protocols impose multi-year approval timelines for cross-border component flows, delaying allied procurement.
- Liquid-Engine Substitution Collapse:Commodity liquid propulsion systems face structural displacement by solid-fuel alternatives, stranding legacy production capacity.
Strategic Opportunities
- Brazilian Naval Modernization:Brazil's submarine development program offers entry points for propulsion technology partnerships under technology transfer agreements.
- Hypersonic-Missile Convergence:Integration of scramjet propulsion with traditional ballistic architectures is opening new performance tiers for maneuverable strike systems.
- Argentine Platform Renewal:Argentina's surface fleet upgrade cycle is creating demand for vertical launch system integration and sea-based deterrent infrastructure.
Industry Challenges
- Thrust-Vectoring Engineering Scarcity:Specialized expertise in submarine-launched platform propulsion remains concentrated among legacy workforce cohorts nearing retirement.
- Multi-Year Certification Timelines:FAA and Department of Defense flight test protocols impose extended validation cycles for new guidance electronics.
- Legacy System Integration Complexity:New interceptor architectures must interface with existing command-and-control networks, constraining design flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Ballistic Missile Market |
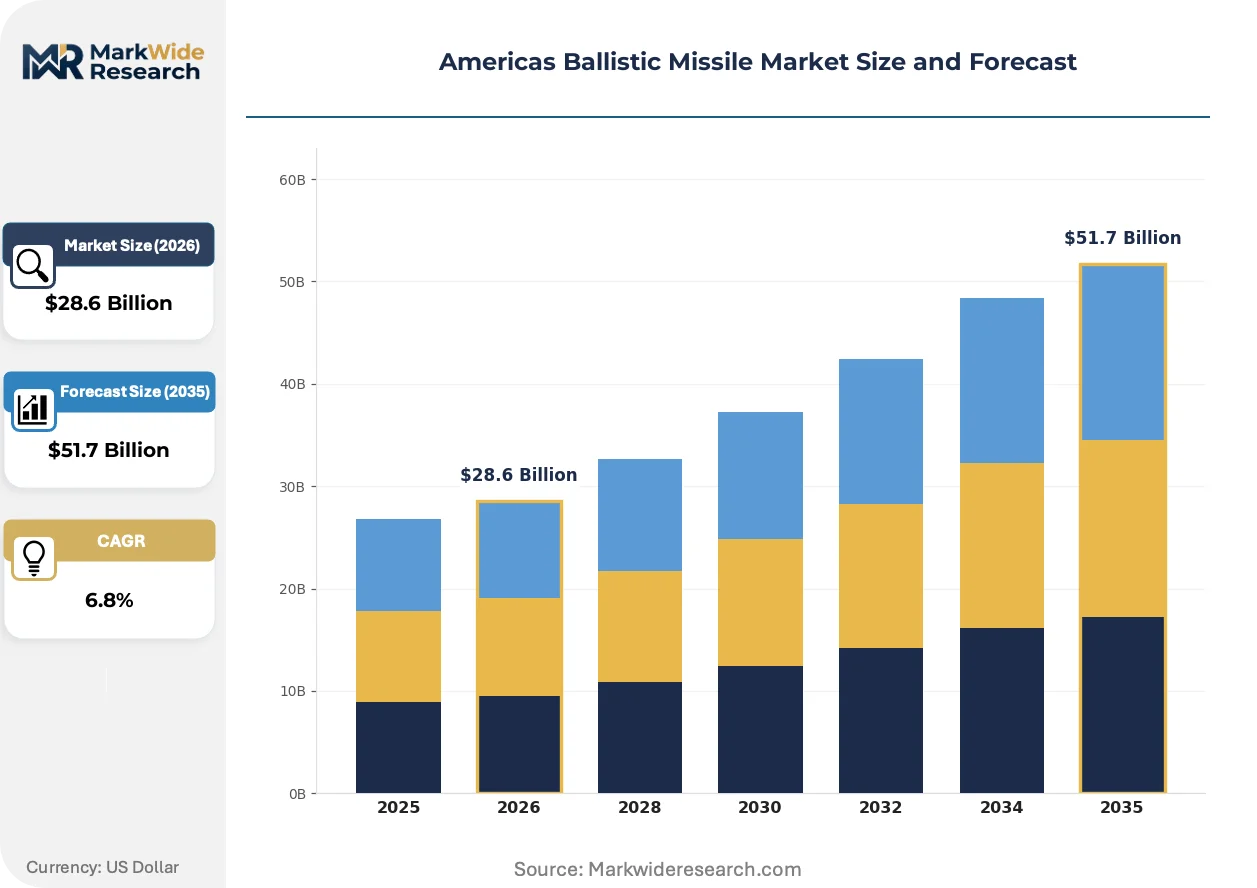
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Land-Based, Sea-Based, Air-Launched, Submarine-Launched Application: Strategic Defense, Tactical Warfare, Space Launch, Research End User: Government, Military, Defense Contractors, Research Institutions Technology: Conventional, Nuclear, Hypersonic, Ballistic |
| Companies Covered | Lockheed Martin Corporation, General Dynamics Corporation, Northrop Grumman Corporation, The Boeing Company, BAE Systems plc, RTX Corporation, Aerojet Rocketdyne, MBDA, Raytheon Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Ballistic Missile Market Strategic Shifts
Active electronically scanned array radar networks are reshaping detection capabilities against maneuvering reentry vehicles. Three convergent developments are redefining technical requirements across the Americas.
Solid-rocket motor manufacturing is automating precision grain casting and automated filament winding for composite motor cases. The U.S. Department of Defense and prime contractors are accelerating adoption of these production methods. This automation is compressing lead times for strategic propulsion systems while reducing lot-to-lot performance variance.
Brazil's national aerospace regulator is tightening technology transfer protocols for submarine-launched platform components, requiring local assembly of guidance electronics. This policy is fragmenting supply chain relationships and mandating joint venture structures for foreign suppliers. Argentine and Chilean procurement offices are observing these precedents for their own naval modernization frameworks.
Defense agencies are consolidating prime contractor relationships around fixed-price development contracts with milestone-based payments. Traditional cost-plus arrangements are retreating to early-stage research programs. This shift is most visible in southwestern U.S. production clusters, where Arizona and New Mexico test facilities anchor competitive bidding for interceptor prototypes.
Americas Ballistic Missile Market Segmentation
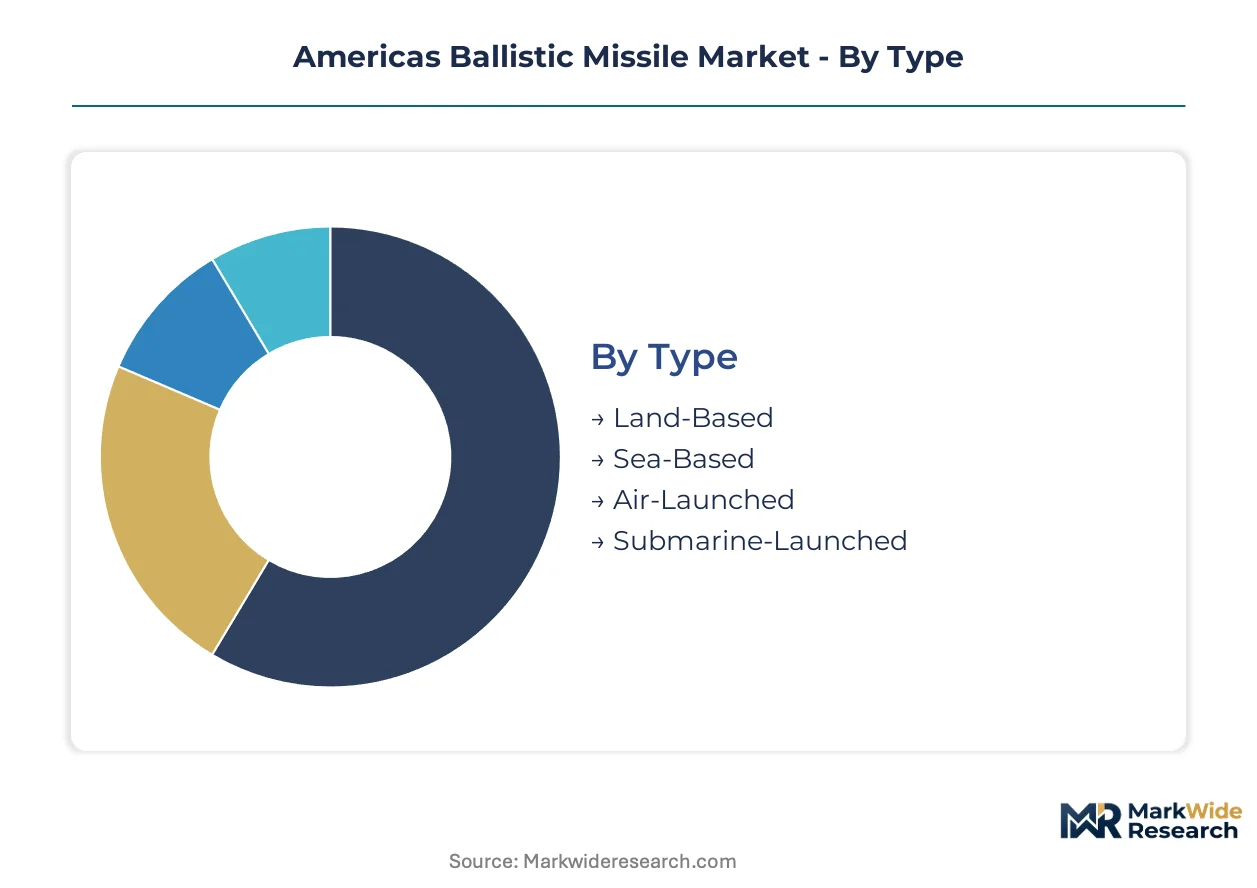
Segmentation in the Americas Ballistic Missile Market reveals distinct procurement patterns across platform types and operational roles. Defense agencies allocate budgets differently for strategic deterrent systems versus tactical applications, with technology choices driving supplier selection and production location decisions.
Type:
Integration depth varies sharply across platform categories, with submarine-launched systems demanding the most embedded subsystem complexity while land-based platforms accommodate more modular architectures.
- Sea-Based:These platforms incorporate vertical launch systems on surface combatants, integrating solid-fuel boosters with shipboard command interfaces. The U.S. Navy's Ohio-class replacement program concentrates procurement in southwestern U.S. production clusters, constrained by ITAR licensing timelines for cross-border component flows.
- Submarine-Launched:Specialized thrust-vectoring propulsion systems deploy from submerged tubes, requiring pressure-hardened guidance electronics and composite aeroshells. Brazil's naval modernization program is accelerating demand through technology transfer agreements mandating local assembly of guidance systems.
- Land-Based:Fixed and mobile ground platforms dominate strategic deterrent deployments with silo-based or road-mobile configurations.
- Air-Launched:These systems deploy from strategic bomber platforms, requiring compact propulsion and rapid target acquisition capabilities.
Sea-Based platforms lead volumes today; Submarine-Launched systems are gaining share fastest.
Application:
Cost tier differentiation separates mature upgrade cycles from generational replacement programs, with research applications commanding premium pricing for experimental payloads.
- Strategic Defense:Long-range deterrent systems with intercontinental reach incorporate multiple independently targetable reentry vehicles. The U.S. Department of Defense's hypersonic glide vehicle countermeasures are redirecting R&D investment toward maneuverable reentry vehicle tracking systems in Arizona and New Mexico test ranges.
- Hypersonic:Maneuverable reentry vehicles capable of evading existing interceptor networks are expanding most quickly as defense agencies prioritize non-ballistic trajectory prediction capabilities.
- Tactical Warfare:Theater-range systems support regional conflict scenarios with conventional warhead configurations and precision targeting.
- Space Launch:Derivative ballistic technologies support satellite deployment and suborbital research missions.
- Research:Experimental platforms validate new propulsion concepts and guidance architectures under FAA and Department of Defense flight test protocols.
Strategic Defense commands the largest budget allocation; Hypersonic applications are climbing the fastest.
End User:
Customer type determines procurement flexibility, with direct government acquisition enabling streamlined vendor selection compared to contractor-mediated purchases.
- Military:Service branches operate the primary inventory of deployed systems, with the U.S. Navy sustaining solid-fuel propulsion demand through submarine modernization. Multi-year certification timelines for new guidance electronics constrain platform refresh rates.
- Government:National defense agencies set requirements and fund development programs, with congressional appropriations shaping next-generation interceptor architectures.
- Defense Contractors:Prime contractors manage subsystem integration and production, consolidating around fixed-price development contracts with milestone-based payments.
- Research Institutions:Universities and national laboratories conduct foundational propulsion and materials research under early-stage cost-plus arrangements.
Military end users dominate procurement volumes today; Defense Contractors are expanding their share fastest through production consolidation.
Technology:
Supply concentration for advanced materials creates single-source vulnerability in the highest-performance tiers, while conventional technologies support competitive sourcing.
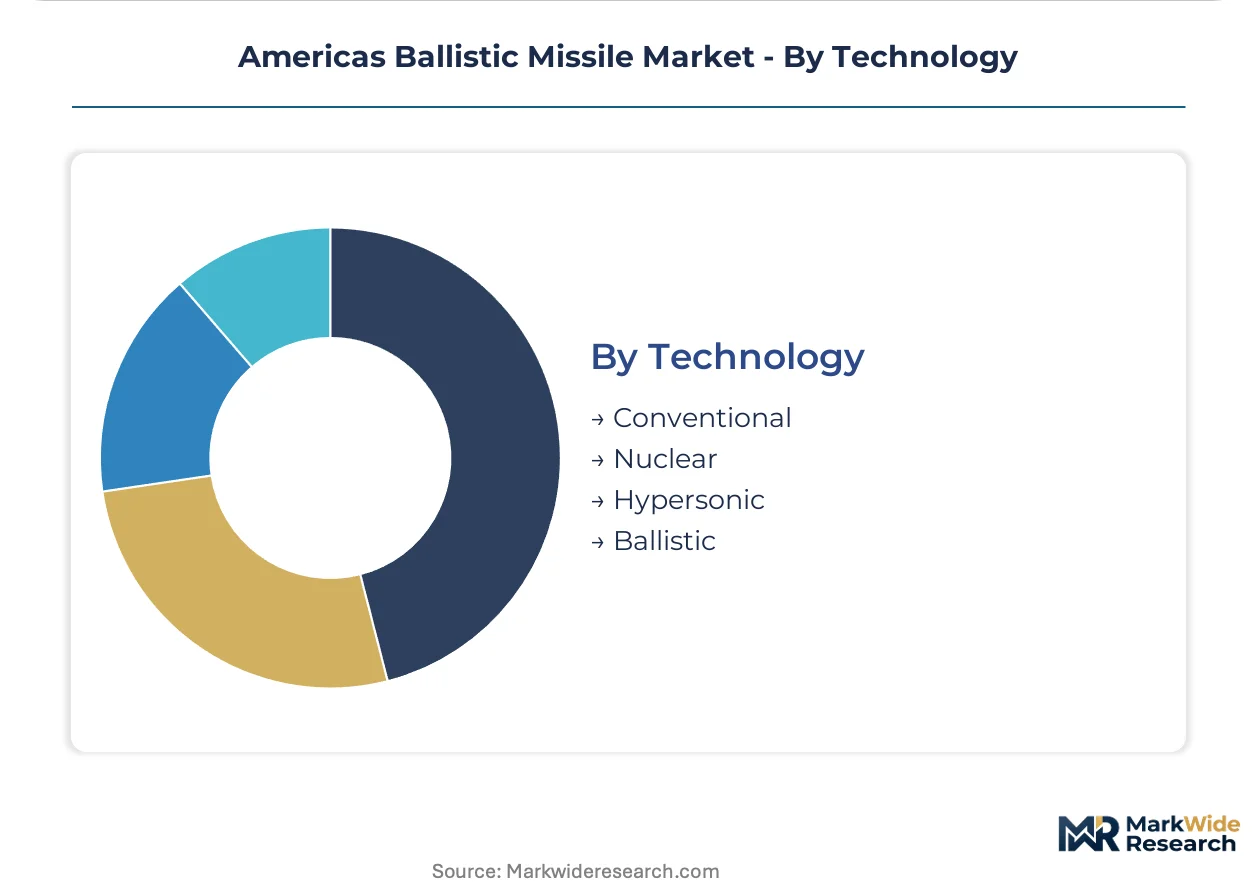
- Hypersonic:Scramjet propulsion integrated with traditional ballistic architectures opens new performance tiers for maneuverable strike systems. Brazil's national aerospace regulator is tightening technology transfer protocols, fragmenting supply chain relationships for foreign suppliers.
- Nuclear:Warhead-delivery platforms require specialized command-and-control integration with existing deterrent infrastructure, constraining design flexibility for new interceptor architectures.
- Conventional:Non-nuclear payloads sustain mature margin pools through upgrade cycles rather than generational replacement, with automated filament winding reducing lot-to-lot performance variance in solid-rocket motor manufacturing.
- Ballistic:Traditional trajectory systems face structural displacement by maneuverable alternatives, stranding legacy liquid-engine production capacity.
Conventional technology leads volumes today; Hypersonic systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized thrust-vectoring engineers and solid-rocket motor technicians concentrate in southwestern U.S. production clusters, anchoring contractor activity near Arizona and New Mexico test ranges. Brazil's submarine development program is cultivating parallel propulsion expertise through technology transfer mandates.
United States
The U.S. Department of Defense's hypersonic glide vehicle countermeasures are redirecting R&D investment toward maneuverable reentry vehicle tracking systems. FAA and State Department ITAR frameworks restrict propulsion and guidance exports, concentrating supplier relationships within cleared domestic channels. Arizona and New Mexico missile defense ranges anchor localized production clusters for next-generation interceptors.
Brazil
Brazil's national aerospace regulator is tightening technology transfer protocols for submarine-launched platform components, requiring local assembly of guidance electronics. ANVISA and defense acquisition regulations shape demand through technology transfer agreements governing cross-border component flows. The submarine development program in Rio de Janeiro state is accelerating sea-based platform procurement through joint venture structures.
Canada
Defense procurement offices in Ottawa are observing U.S. hypersonic countermeasure developments for NORAD modernization implications. Health Canada and national defense agencies coordinate on dual-use technology assessments affecting cross-border component flows. Ontario-based research institutions conduct foundational propulsion studies under early-stage cost-plus arrangements with allied programs.
Argentina
Argentina's surface fleet upgrade cycle is creating demand for vertical launch system integration and sea-based deterrent infrastructure. The national defense ministry shapes procurement through acquisition regulations prioritizing regional technology partnerships. Buenos Aires and Cordoba industrial zones host emerging subsystem integration capacity for naval modernization programs.
Mexico
Mexican aerospace manufacturing clusters near Querétaro and Baja California are positioning for component supply roles under ITAR-cleared channels. The Secretariat of National Defense regulates technology access for foreign defense contractors seeking nearshore production advantages. Monterrey's industrial corridor is developing precision machining capacity for solid-rocket motor casings.
Americas Ballistic Missile Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Americas Ballistic Missile landscape. The supplier base concentrates around cleared domestic channels reinforced by ITAR licensing requirements. Three archetypes dominate: vertically integrated prime contractors controlling captive solid-rocket motor supply chains; specialized propulsion houses focusing on thrust-vectoring technologies; and composite aeroshell manufacturers with advanced ceramic capabilities. Competitive moves center on fixed-price development contract consolidation and automated production method adoption.
Within the vertically integrated prime tier, Lockheed Martin Corporation and Northrop Grumman Corporation occupy positions exemplifying captive supply chain control over strategic propulsion systems. Aerojet Rocketdyne anchors the specialized propulsion archetype, representing concentrated expertise in submarine-launched platform engineering. These three entities sit within the core supplier network sustaining U.S. Navy Ohio-class replacement demand through 2035.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| Northrop Grumman Corporation |
| The Boeing Company |
| BAE Systems plc |
| RTX Corporation |
| Aerojet Rocketdyne |
| MBDA |
| Raytheon Technologies |
| Others |
Value Chain & Pricing Dynamics
Automated filament winding and precision grain casting in solid-rocket motor manufacturing compress production timelines while concentrating supplier power among ITAR-cleared domestic channels in Arizona and New Mexico. This automation wave simultaneously reduces lot-to-lot variance and raises capital barriers, filtering the supplier base toward vertically integrated primes with captive composite aeroshell production.
Pricing Analysis
Bundled subsystem integration commands premium positioning against unbundled component supply in this market. Fixed-price development contracts with milestone-based payments dominate prime-tier procurement, while cost-plus arrangements retreat to early-stage research programs. Price differentiation rests on ITAR certification tier and volume scale, with cleared domestic channels capturing margin premiums. Pricing pressure intensifies in commodity liquid-engine segments facing displacement by solid-fuel alternatives. Defense contractors exhibit highest price sensitivity due to congressional appropriation constraints, while military end users prioritize performance reliability over unit cost.
Supply Chain Analysis
ITAR qualification gates fragment supplier relationships into cleared domestic and allied channels, excluding non-compliant foreign competitors. Geographic supply concentration centers on the United States, Brazil, and Canada, with southwestern U.S. production clusters anchoring prime contractor activity. Raw material dependencies include advanced ceramics, carbon fiber composites, and specialty solid propellant precursors. Single-source vulnerability in composite aeroshell production creates structural supply risk. Distribution runs through prime contractor integration networks with direct military and government end-user relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value through Brazil's technology transfer mandates, where local assembly requirements create joint-venture entry points at lower regulatory friction than U.S. ITAR-cleared channels.
For Market Incumbents: Anticipate thrust-vectoring engineering scarcity as legacy workforce cohorts approach retirement, accelerating knowledge-capture investments and automated production method adoption. Lockheed Martin Corporation and Northrop Grumman Corporation should deepen backward integration into solid-rocket motor supply chains to defend margin position against fixed-price contract compression. Priority lever sits in southwestern U.S. production cluster expansion near Arizona and New Mexico test infrastructure.
For New Entrants and Emerging Players: Argentine surface fleet upgrade programs represent an underserved buyer archetype with vertical launch system integration demand and limited incumbent saturation. Brazil's submarine development program offers technology transfer partnership structures under ANVISA-mandated local assembly protocols. Go-to-market angle should emphasize joint venture formations with Rio de Janeiro state industrial zones to satisfy national aerospace regulator requirements.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized propulsion houses with thrust-vectoring expertise and composite aeroshell manufacturers holding advanced ceramic capabilities. Long-term viability favors acquisition targets with ITAR-cleared status and southwestern U.S. facility presence. Signal to monitor: congressional appropriation shifts toward hypersonic glide vehicle countermeasures and corresponding test infrastructure investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Price Development Contract Consolidation | Redirects prime contractor risk allocation toward milestone-based payment structures under Department of Defense procurement reform. |
| Automated Solid-Rocket Motor Manufacturing | Compresses lead times for strategic propulsion systems while reducing performance variance in southwestern U.S. production clusters. |
| ITAR-Cleared Channel Reinforcement | Concentrates supplier relationships within domestic and allied frameworks under State Department technology transfer protocols. |
| Brazilian Joint Venture Formation | Satisfies ANVISA local assembly mandates for submarine-launched platform guidance electronics through Rio de Janeiro partnerships. |
| Hypersonic-Missile Convergence R&D | Integrates scramjet propulsion with ballistic architectures for maneuverable strike systems evading existing interceptor networks. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with submarine program officers, solid-rocket motor plant managers, defense procurement executives, and thrust-vectoring engineering specialists with secondary validation against Department of Defense budget submissions, FAA flight test protocols, congressional appropriation records, and ITAR licensing disclosure databases. Bottom-up platform deployment forecasts and top-down defense budget allocation analysis provided triangulation checks across the analytical framework.
Segment-weighting approaches distributed value and volume projections across platform type, application, end user, and technology dimensions, with additional modeling of propulsion architecture and geographic production cluster variables. CAGRs were derived through regression analysis of historical procurement cycles and projected modernization program timelines. Forecast inputs incorporated Ohio-class replacement program schedules, Brazilian submarine development milestones, and hypersonic glide vehicle countermeasure funding trajectories.
Underlying measurement precision varies by segment; submarine-launched and hypersonic applications carry tighter precision than mature conventional warhead configurations given defined program timelines. Forecasts reflect documented assumptions regarding congressional appropriation continuity and ITAR framework stability. Model refresh is warranted upon material change in Department of Defense hypersonic countermeasure prioritization or Brazilian technology transfer protocol revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Airsoft Guns Market
Weapons and Ammunition
Global Artillery Systems Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Torpedo Market
Weapons and Ammunition
Anti-Tank Missile System Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Nuclear Bombs and Missiles Market
Weapons and Ammunition
Airborne Weapon System Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Ammunition Handling Systems Market