
 Non Lethal Projectiles Market | 2026-2036
Non Lethal Projectiles Market Size, Share, and Industry Trends Forecast 2026-2036
Non Lethal Projectiles Market Analytics
Leasing and operational rental models for less-lethal launcher systems is reshaping competitive dynamics in the non lethal projectiles space. Axon Enterprise leverages its body-worn camera ecosystem to anchor bundled service contracts that include projectile deployment. Safariland sustains manufacturing scale across duty gear and less-lethal ammunition categories. Rheinmetall AG competes through defense-grade engineering standards applied to police and military training projectile lines.
Non lethal projectiles encompass kinetic impact munitions designed to incapacitate or deter targets without causing fatal trauma, typically featuring rubber, foam, or chemical irritant payloads with muzzle energies calibrated below lethal thresholds for human engagement. These systems serve law enforcement, military training, and security applications where lethal force exceeds operational requirements. Bean bag rounds and foam rounds dominate procurement volumes among police departments due to established protocols and lower liability exposure. Pepper balls represent the fastest-growing product category as agencies seek chemical incapacitation with reduced kinetic injury risk. Civilian self-defense applications through handheld delivery devices create emerging margin pools outside institutional channels.
FDA oversight of chemical irritant formulations intersects with NHTSA transport regulations for hazardous munitions shipping, while OSHA workplace safety standards govern manufacturing facility compliance for projectile producers. The EU AI Act and forthcoming automated targeting restrictions in Europe will shape demand for human-in-the-loop launcher systems. Stakeholders must monitor evolving use-of-force litigation patterns and corresponding insurance cost structures that will determine procurement prioritization across agency budgets.
Market Dynamics
Leasing models for less-lethal launcher systems are compressing capital expenditure cycles across municipal police departments, forcing manufacturers to restructure revenue recognition around recurring service streams rather than unit sales.
Growth Catalysts
- DOJ Use-of-Force Policy Revisions:Federal oversight mandates are institutionalizing kinetic impact munitions in standard riot response protocols across US urban police departments.
- Pepper Ball Chemistry Advances:Reformulated capsaicin payloads with extended incapacitation duration are displacing traditional tear gas in crowd control scenarios.
- Military Training Simulation Demand:Defense-grade non-lethal projectiles for force-on-force exercises are expanding procurement volumes at US Army and Marine Corps installations.
Market Restraints
- Natural Rubber Price Volatility:Bean bag and foam projectile manufacturers face margin compression from fluctuating Southeast Asian latex supply contracts.
- NHTSA Hazmat Shipping Compliance:Chemical irritant formulations trigger costly specialized freight classifications that inflate landed costs for remote agency deliveries.
- Reusable Launcher Economics:Durable launcher platforms with 15-20 year service lives suppress replacement demand compared to consumable ammunition sales.
Strategic Opportunities
- Civilian Self-Defense Channel Expansion:Handheld pepper ball delivery devices for home security applications are opening margin pools outside institutional procurement.
- EU AI Act Human-in-the-Loop Mandates:Automated targeting restrictions will favor launcher systems with manual override architectures in European law enforcement tenders.
- OSHA Manufacturing Compliance Services:Third-party workplace safety auditing for projectile production facilities represents adjacent revenue streams for specialized consultancies.
Industry Challenges
- Ballistics Expertise Scarcity:Engineering talent capable of calibrating sub-lethal muzzle energies commands premium compensation in a shallow labor pool.
- Multi-Agency Certification Timelines:Individual state POST commissions require separate product approvals that extend sales cycles by 18-24 months.
- Legacy Launcher Integration:New ammunition formats must maintain backward compatibility with installed 37mm and 40mm launcher inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non Lethal Projectiles Market |
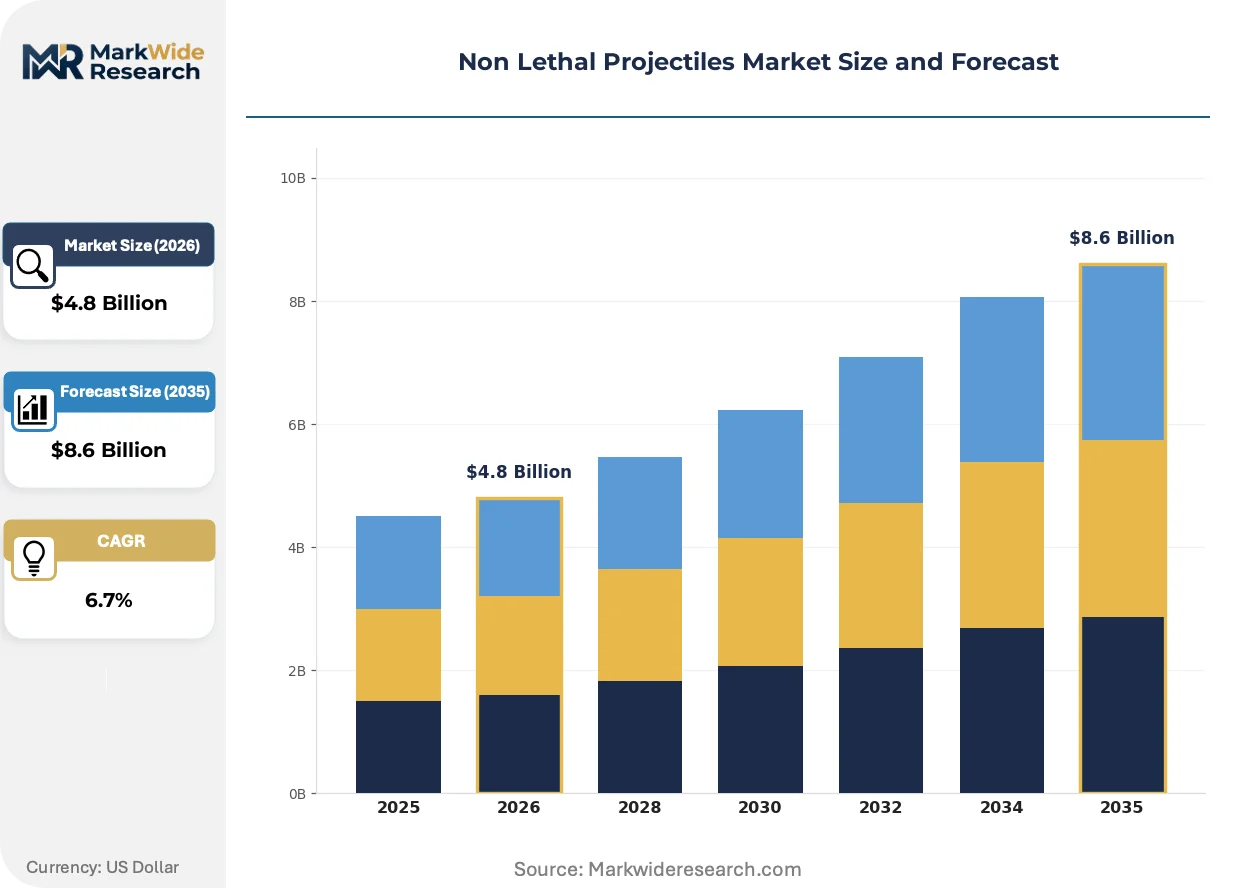
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Bullets, Bean Bag Rounds, Pepper Balls, Foam Rounds Application: Crowd Control, Self-Defense, Law Enforcement, Military Training Delivery Mode: Launchers, Handheld Devices, Grenades, Airsoft Guns End User: Police, Military, Security Firms, Civilian Users |
| Companies Covered | Axon Enterprise, Safariland, Rheinmetall AG, Combined Systems Inc., FN Herstal, Byrna Technologies, Genasys Inc., Nonlethal Technologies, PepperBall Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non Lethal Projectiles Market Evolving Landscape
Smart projectile architectures with embedded sensors are redefining accountability standards in less-lethal engagements, creating audit trails that reshape liability frameworks for deploying agencies.
Precision-guided kinetic impact munitions with micro-thruster stabilization are rendering obsolete conventional fin-stabilized rounds that suffer accuracy degradation beyond 30 meters. SWAT teams and specialized response units in California and Texas are field-testing these systems for hostage rescue scenarios. The technology is compressing acceptable engagement ranges and tightening rules-of-fire protocols.
REACH chemical substance restrictions in Europe are forcing reformulation of legacy CS and OC irritant payloads to exclude newly classified hazardous compounds. Manufacturers serving German and French police markets must resubmit toxicity documentation for modified formulations. Pepper ball producers with pre-registered chemical dossiers are securing first-mover advantage in retendering cycles.
Agency purchasing cooperatives are consolidating procurement authority for less-lethal systems under state-level contracts that displace individual municipal negotiations. The Los Angeles Sheriff's Department and Chicago Police Department now source through California and Illinois statewide agreements. This concentration is squeezing regional distributors and favoring manufacturers with direct government sales infrastructure.
Non Lethal Projectiles Market Segmentation
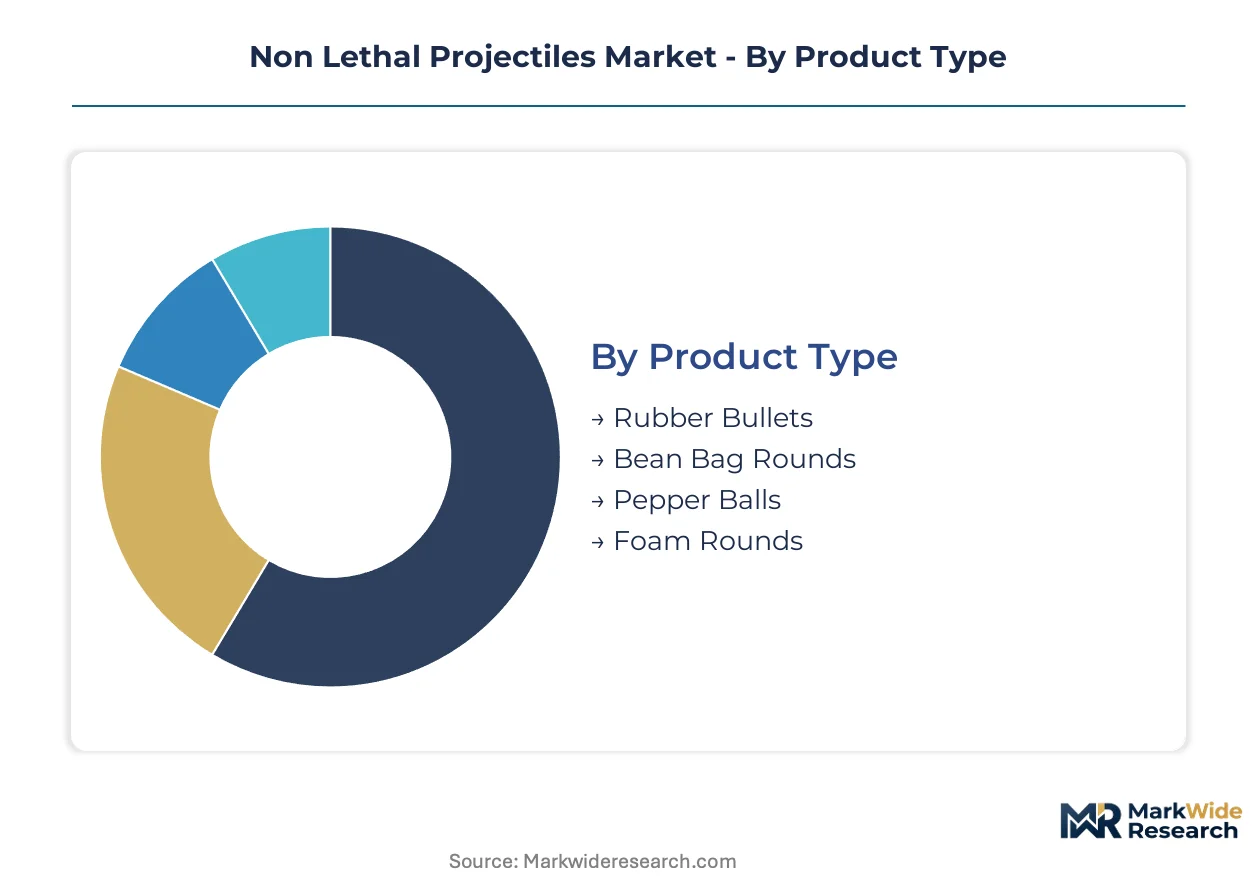
Segmentation in the non lethal projectiles market reveals divergent procurement rhythms across product categories. Replacement cycles for consumable ammunition compress against extended service intervals for launcher platforms.
Product Type:
Cycle times vary dramatically across projectile formats, with chemical irritant payloads requiring more frequent replenishment than durable kinetic rounds.
- Rubber Bullets:Solid elastomer projectiles fired from standard 37mm launchers deliver blunt force trauma at calibrated muzzle energies below lethal thresholds. US urban police departments specify these for riot line engagements where distance retention matters. Procurement volumes track protest activity cycles rather than equipment refresh schedules.
- Pepper Balls:Spherical gelatin capsules containing capsaicin powder burst on impact to create respiratory and ocular incapacitation. California and Texas SWAT units are expanding inventory for hostage rescue scenarios where chemical neutralization reduces kinetic injury risk. Reformulated payloads with extended duration are displacing tear gas in federal agency protocols.
- Bean Bag Rounds:Fabric pouches filled with lead shot deliver kinetic energy dispersion across larger surface areas. Range certification requirements drive predictable reorders.
- Foam Rounds:Lightweight polymer projectiles designed for close-range engagement with reduced penetration risk. Training applications sustain baseline demand.
Bean bag rounds dominate installed base. Pepper balls are where expansion concentrates.
Application:
Cost tier stratification separates institutional procurement from consumer-grade purchases, with law enforcement budgets absorbing premium pricing for liability-tested systems.
- Law Enforcement:Standard-issue kinetic impact munitions for patrol and specialized response units carry certification requirements that inflate unit costs. Department of Justice use-of-force mandates are institutionalizing these systems across US municipal agencies. Multi-year ammunition contracts with Safariland and Axon Enterprise lock in recurring revenue streams.
- Crowd Control:High-volume projectile deployment during civil unrest creates surge demand patterns distinct from steady-state procurement. Chicago Police Department and Los Angeles Sheriff's Department coordinate through statewide purchasing cooperatives that compress pricing negotiations.
- Military Training:Force-on-force simulation exercises at US Army and Marine Corps installations consume defense-grade non-lethal projectiles. Budget cycles align with fiscal year appropriations rather than operational incident rates.
- Self-Defense:Handheld pepper ball delivery devices for home security applications operate outside institutional certification frameworks. Margin structures favor direct-to-consumer channels.
Law enforcement absorbs the premium tier. Self-defense is climbing the fastest as civilian channel development accelerates.
Delivery Mode:
Volume concentration favors reusable launcher platforms, though handheld devices are gaining share in adjacent security applications.
- Launchers:Durable 37mm and 40mm platforms with 15-20 year service lives suppress replacement demand compared to consumable ammunition. Backward compatibility requirements constrain new format development.
- Handheld Devices:Compact CO2-powered systems for individual officer carry or civilian self-defense. Ergonomic refinements are expanding addressable market beyond institutional users.
- Grenades:Area-denial chemical irritant deployment for perimeter establishment. Specialized tactical units maintain limited inventories.
- Airsoft Guns:Replica platforms adapted for training simulation with reduced-velocity projectile delivery. Military procurement volumes are climbing with force-on-force exercise expansion.
Launchers anchor fleet investment. Handheld devices are where technology differentiation concentrates.
End User:
Customer type determines procurement authority structures, with consolidated state-level contracts displacing individual municipal negotiations.
- Police:Municipal departments and sheriff's offices constitute the core demand base. California and Illinois statewide purchasing agreements now govern acquisition for Los Angeles and Chicago agencies.
- Military:US Army and Marine Corps training installations procure through defense logistics channels with distinct specification requirements. Force-on-force simulation budgets are expanding procurement volumes.
- Security Firms:Private sector guarding operations for critical infrastructure and executive protection. Liability insurance requirements drive adoption of certified less-lethal systems.
- Civilian Users:Home defense and personal security applications outside institutional oversight. Regulatory fragmentation across US states creates channel complexity.
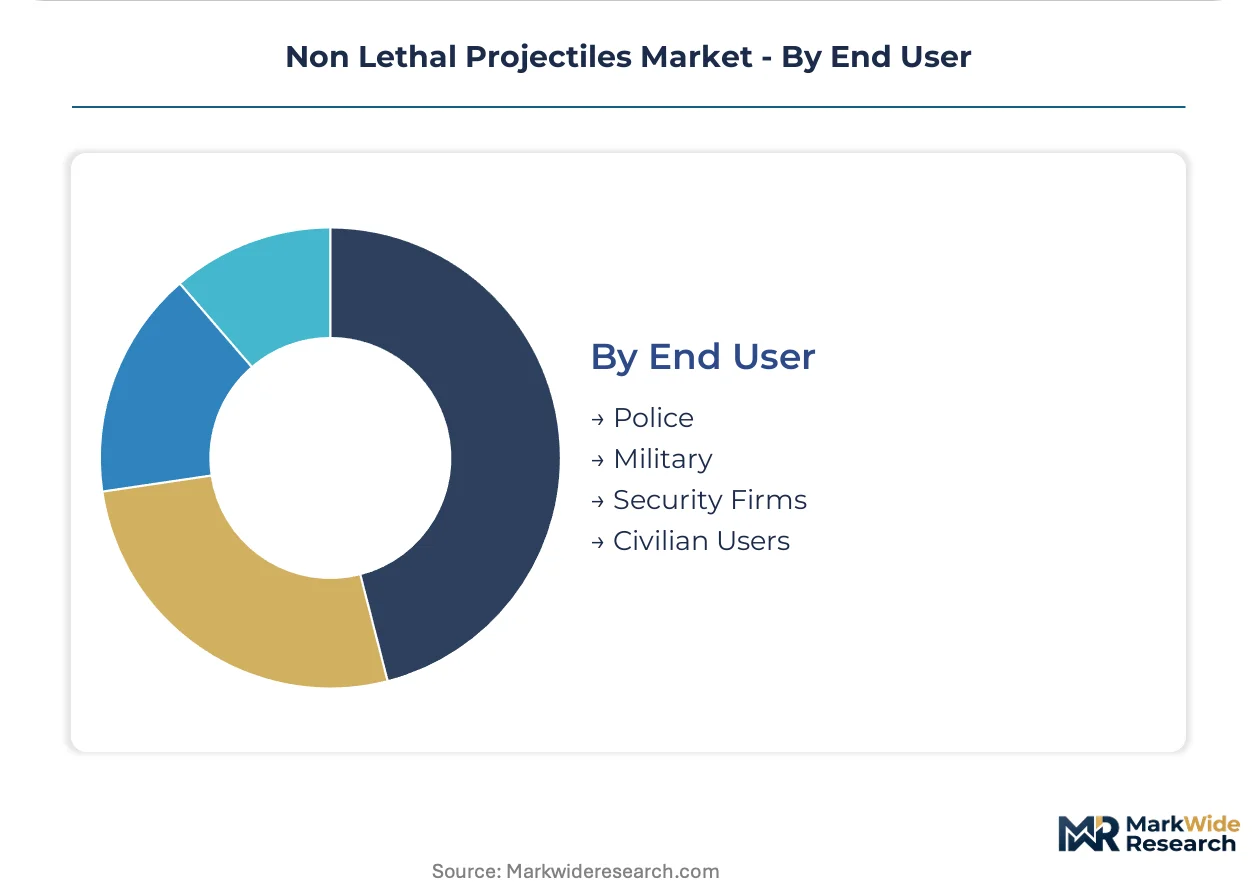
Police departments dominate procurement volume. Civilian users represent the steepest expansion trajectory as handheld device distribution matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial export surplus in non-lethal projectile systems while importing specialized chemical irritant precursors from European suppliers. Germany and France anchor European manufacturing capacity for precision-engineered kinetic munitions. China produces cost-competitive rubber and foam projectile components serving Asian security markets.
United States
DOJ use-of-force mandates drive municipal police department modernization across urban centers. NHTSA hazardous materials regulations govern interstate transport of chemical irritant payloads to remote agency locations. Los Angeles and Chicago police departments coordinate procurement through California and Illinois statewide purchasing cooperatives.
Germany
REACH chemical substance restrictions force reformulation of legacy irritant payloads for Bundespolizei and state police forces. ECHA compliance documentation requirements extend product recertification timelines for manufacturers serving German markets. Rheinmetall AG anchors defense-grade engineering standards applied to police training projectile lines from its Düsseldorf operations.
France
Gendarmerie Nationale and Police Nationale procurement sustains demand for less-lethal crowd control systems. ANSM oversight intersects with EU AI Act automated targeting restrictions shaping launcher system specifications. Paris and Lyon metropolitan police units field-test precision-guided kinetic munitions for specialized response scenarios.
United Kingdom
Home Office equipment standards drive adoption of certified kinetic impact munitions across territorial police forces. HSE workplace safety regulations govern manufacturing facility compliance for UK-based projectile producers. London Metropolitan Police and Greater Manchester Police coordinate procurement through national framework agreements.
China
Domestic security apparatus procurement sustains manufacturing scale for rubber bullet and foam round components. MIIT industrial standards and GB certification requirements structure product quality frameworks. Yangtze River Delta industrial clusters produce cost-competitive projectile components serving Asian and Middle Eastern export markets.
Non Lethal Projectiles Market Competitive Landscape
On the supply side, the industry is consolidating around bundled service contracts and recurring revenue streams rather than discrete equipment sales. Tiered competitive positioning separates defense-grade engineering specialists from commercial security equipment vendors. Two strategic archetypes dominate: integrated technology platforms combining hardware with digital accountability systems, and pure-play munitions manufacturers sustaining scale through multi-agency ammunition contracts. M&A activity concentrates on acquiring chemical formulation capabilities and launcher platform technology licensing.
Within the integrated technology tier, Axon Enterprise exemplifies the bundled ecosystem approach anchoring body-worn camera deployments with projectile system service contracts. Safariland occupies a position representing manufacturing scale across duty gear and less-lethal ammunition categories. Rheinmetall AG represents defense-grade engineering standards applied to police and military training projectile lines.
| Leading Market Players |
|---|
| Axon Enterprise |
| Safariland |
| Rheinmetall AG |
| Combined Systems Inc. |
| FN Herstal |
| Byrna Technologies |
| Genasys Inc. |
| Nonlethal Technologies |
| PepperBall Technologies |
| Others |
Value Network & Pricing Analysis
Natural rubber price volatility from Southeast Asian latex supply contracts determines both the spread between economy-grade bean bag rounds and premium precision-guided munitions and the geographic concentration of manufacturing capacity. Procurement officers at municipal police departments face compressed margins on standard kinetic impact rounds while specialized response units absorb premium pricing for chemical irritant payloads with extended incapacitation duration.
Pricing Analysis
Law enforcement agencies anchor contract-based long-term offtake pricing for less-lethal projectile systems, with three-tier pricing structure across premium, standard, and economy levels separating defense-grade training munitions from patrol-issue rounds. Price differentiation stems from certification tier under Department of Justice use-of-force protocols and geographic delivery cost to remote agency locations. Cost compression in standard rubber bullet categories is intensifying because of fluctuating elastomer input costs and consolidated state-level purchasing cooperatives. Small municipal departments exhibit highest price sensitivity, while federal agency procurement absorbs premium tier pricing for liability-tested systems.
Supply Chain Analysis
Contract manufacturing concentration for chemical irritant payload assembly rests with specialized facilities in Germany and France serving European police markets, while rubber and foam projectile component production centers on Yangtze River Delta industrial clusters in China. Raw material dependencies include Southeast Asian natural latex, capsaicin precursor chemicals from Indian pharmaceutical suppliers, and gelatin capsule housings from domestic US manufacturers. Single-source vulnerability concentrates in specialty chemical formulations subject to REACH substance restrictions. Distribution runs through defense logistics channels for military training installations and direct government sales infrastructure for consolidated state-level law enforcement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement authority as California and Illinois statewide purchasing cooperatives displace individual municipal negotiations, fragmenting pricing leverage across hundreds of small departments.
For Market Incumbents: Insulate recurring revenue streams by deepening backward integration into capsaicin precursor chemical production and securing exclusive service contracts with statewide purchasing cooperatives. Counter emerging handheld pepper ball device entrants through bundled launcher-ammunition subscription models that lock in multi-year agency commitments. For New Entrants and Emerging Players: Pursue civilian self-defense channel expansion where regulatory fragmentation across US states creates white-space opportunities outside institutional certification frameworks. Target direct-to-consumer distribution for compact CO2-powered handheld devices, leveraging ergonomic refinements to capture margin pools absent legacy launcher compatibility requirements. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors chemical formulation specialists with pre-registered REACH dossiers and established launcher platform technology licensing. Long-term viability hinges on capturing recurring ammunition revenue rather than discrete hardware sales. Monitor retendering cycles at German Bundespolizei and French Gendarmerie Nationale as inflection indicators for reformulated payload adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Formulation Reformulation | REACH-compliant capsaicin payloads secure first-mover advantage in European police retendering cycles. |
| Launcher-Ammunition Bundling | Service contracts with Axon Enterprise and Safariland lock in recurring revenue across multi-year municipal agreements. |
| Civilian Channel Development | Direct-to-consumer handheld devices bypass institutional certification timelines and capture premium margin structures. |
| Statewide Procurement Integration | California and Illinois purchasing cooperatives concentrate buyer power and squeeze regional distributor margins. |
| Precision-Guided Munition Investment | Micro-thruster stabilization technology addresses SWAT unit demand for compressed engagement ranges in hostage rescue scenarios. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and defense logistics procurement records. Interviews with law enforcement procurement officers, chemical manufacturing plant managers, and distribution channel partners were cross-checked against NHTSA hazardous materials transport databases, ECHA REACH substance registrations, and DOJ use-of-force policy documentation. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Forecast inputs include projectile format segmentation by kinetic versus chemical incapacitation mechanism, delivery mode differentiation between reusable launchers and handheld devices, and end-user stratification across police, military, security firm, and civilian channels. CAGRs derive from modeled replacement cycles for consumable ammunition against extended service intervals for launcher platforms, incorporating military training simulation budget appropriations and protest activity cycle correlations.
Sensitivities concentrate around natural rubber commodity price swings, multi-agency certification timeline extensions by individual state POST commissions, and EU AI Act automated targeting restrictions affecting launcher system specifications. Quarterly review of statewide purchasing cooperative contract awards and reformulated chemical payload toxicity documentation submissions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Tank Ammunition Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Directed Energy Weapons Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
Global Small Arms and Light Weapons (SALW) Market
Weapons and Ammunition
Guns and Accessories Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market
Weapons and Ammunition
Close-In Weapon Systems Market
Weapons and Ammunition
Medium Caliber Ammunition Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
Intercontinental Ballistic Missile Market