
 Sonobuoy Launcher Market | 2026-2036
Sonobuoy Launcher Market Size, Share, and Industry Trends Forecast 2026-2036
Sonobuoy Launcher Market Outlook
Multi-source procurement for pneumatic and electro-mechanical launch subsystems is realigning vendor relationships across NATO-aligned naval programs. L3Harris Technologies leverages its integrated avionics heritage to dominate airborne launcher retrofit contracts. Kongsberg Gruppen anchors Nordic supply chains through specialized shipborne launcher manufacturing. JSK Naval Support competes on rapid-deployment portable systems for littoral operations.
A sonobuoy launcher is a pneumatic or pyrotechnic deployment mechanism engineered to eject acoustic sensor buoys from fixed-wing aircraft, helicopters, or surface vessels at calibrated airspeeds and depths, typically operating at pressure ratings exceeding 3000 PSI and cycle times under two seconds. Its primary purpose is to establish distributed underwater detection grids for threat identification and oceanographic data capture. Airborne launchers command the largest installed base due to persistent maritime patrol aircraft modernization, while digital sonobuoy technology represents the fastest-expanding segment as navies prioritize real-time beamforming and reduced false-positive rates. Multi-mode sonobuoys concentrate margin pools where vendors bundle launcher hardware with signal-processing firmware.
FAA airworthiness directives govern launcher carriage on civil-modified military platforms in the United States, while NATO STANAG 4155 establishes interoperability benchmarks for cross-national fleet compatibility. The EU AI Act's emerging classification framework for autonomous targeting systems will shape procurement specifications for next-generation launcher-sonobuoy integration. Stakeholders must monitor how export control harmonization between ITAR and EU dual-use regulations affects cross-border subsystem sourcing.
Market Dynamics
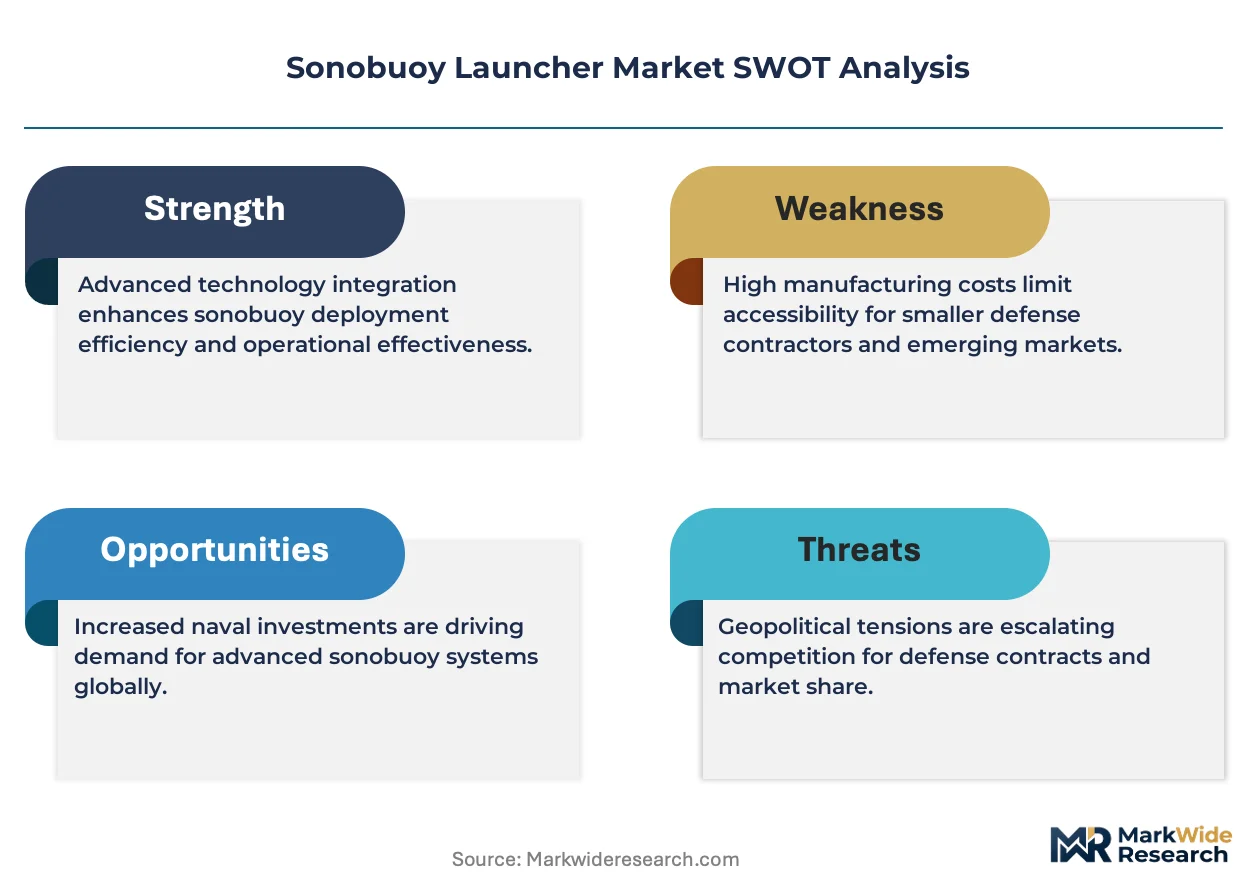
The transition from analog to multi-mode digital sonobuoy architectures is compressing launcher procurement cycles as NATO navies demand STANAG-compliant interoperability across mixed-nationality task forces. This technological inflection is redrawing vendor qualification requirements and subsystem integration standards.
Growth Catalysts
- Airborne ASW modernization:Naval aviation branches in the United States, United Kingdom, and Japan are retrofitting maritime patrol aircraft with next-generation launcher systems to extend acoustic detection ranges.
- STANAG 4155 harmonization:NATO standardization mandates for cross-national fleet compatibility are forcing legacy system replacements and opening multi-source procurement windows.
- Indo-Pacific coastal defense programs:Littoral surveillance investments across Japan, Australia, and South Korea are accelerating demand for shipborne and portable launcher configurations.
Market Restraints
- High-pressure pneumatic subsystem costs:Precision machining of 3000+ PSI-rated launch cylinders from specialty alloys creates input cost volatility tied to nickel and titanium markets.
- Dual-use export control fragmentation:Misalignment between ITAR and EU dual-use regulations generates procurement delays for cross-border subsystem sourcing.
- Legacy platform integration barriers:Analog sonobuoy stocks in active NATO inventories limit immediate digital launcher adoption rates.
Strategic Opportunities
- Unmanned platform integration:Autonomous maritime surveillance drones represent an emerging application vector for miniaturized launcher systems.
- EU AI Act tailwinds:Emerging classification frameworks for autonomous targeting systems will reshape procurement specifications for next-generation launcher-sonobuoy bundles.
- Portable rapid-deployment systems:Littoral operators in Southeast Asia are creating demand for man-portable launcher units deployable from rigid-hull inflatable boats.
Industry Challenges
- Cross-domain systems engineering talent scarcity:Integration of pneumatic, avionics, and acoustic expertise into unified product teams remains difficult.
- FAA airworthiness certification timelines:Civil-modified military platforms require extended validation cycles for launcher carriage approvals.
- Digital-legacy protocol translation:Real-time beamforming sonobuoys demand firmware architectures incompatible with existing launcher control buses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sonobuoy Launcher Market |
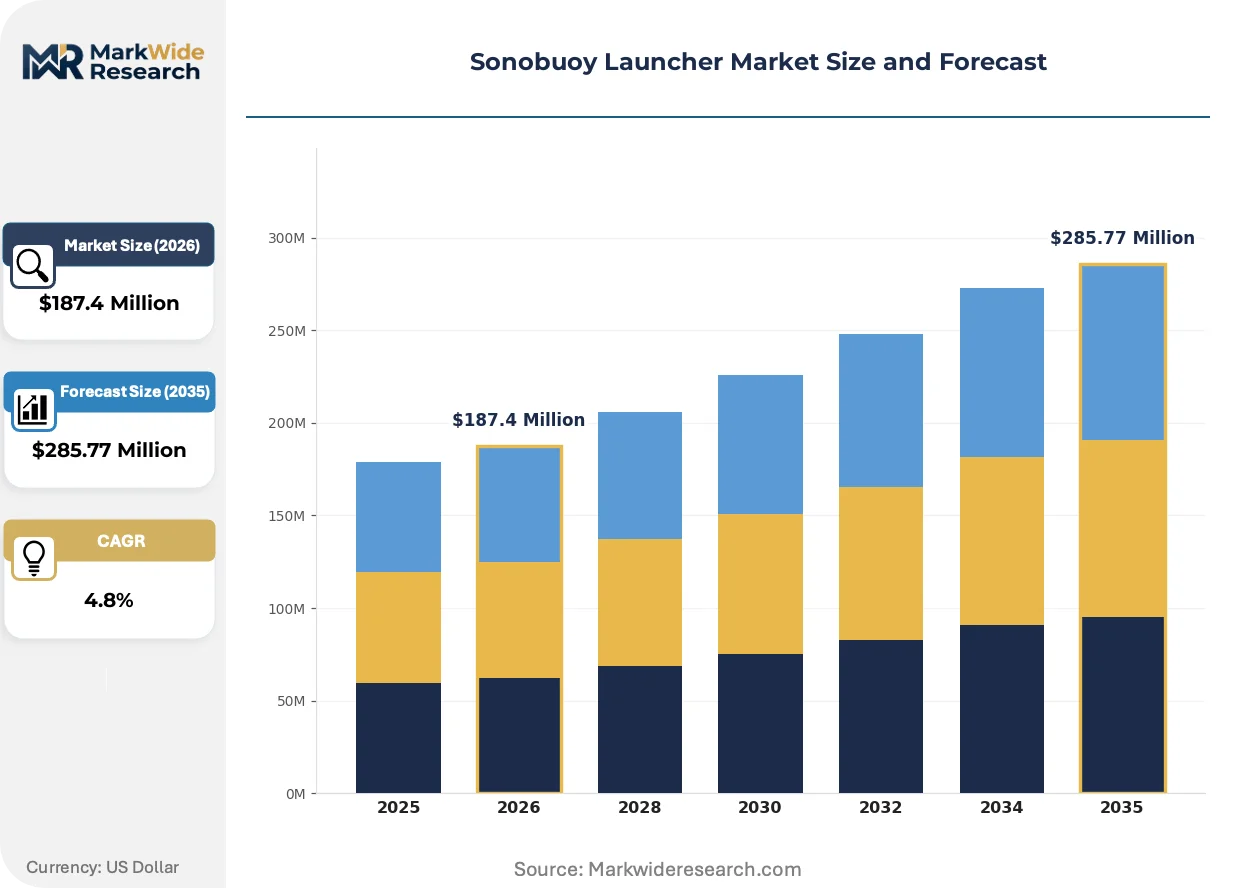
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airborne Launchers, Shipborne Launchers, Ground-based Launchers, Portable Launchers Technology: Passive Sonobuoys, Active Sonobuoys, Multi-Mode Sonobuoys, Digital Sonobuoys End User: Defense Agencies, Naval Forces, Research Institutions, Private Contractors Application: Anti-Submarine Warfare, Maritime Surveillance, Environmental Monitoring, Research & Development |
| Companies Covered | JSK Naval Support, Harris Corporation, L3Harris Technologies, Kongsberg Gruppen, Aurora Flight Science, Alkan, Marshall Aerospace, General Dynamics, Geospectrum Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sonobuoy Launcher Market Strategic Shifts
Digital beamforming and real-time signal processing are collapsing the traditional hardware-software boundary in sonobuoy systems, forcing launcher manufacturers to bundle firmware competencies with mechanical engineering. This convergence is rewriting competitive differentiation criteria.
Multi-mode digital sonobuoy technology is unifying acoustic detection, communication, and navigation functions within single buoy architectures. Maritime patrol operators in NATO-aligned fleets are adopting these systems at compressed refresh cycles. This unification is collapsing the historical separation between launcher hardware vendors and signal-processing specialists, concentrating margin pools around integrated subsystem providers.
The EU AI Act's risk-based classification framework for autonomous targeting systems is tightening procurement specifications for launcher-sonobuoy integration. Defense contractors must now document algorithmic decision pathways for acoustic threat identification. Airborne launcher segments face the steepest compliance burdens as civil-modified platforms fall under dual regulatory jurisdictions.
Integrated product-service contracts are displacing discrete hardware procurement across major naval programs. Prime contractors now bundle launcher systems with acoustic data analytics and maintenance telemetry. This shift is most visible in United Kingdom and Australian maritime patrol modernization programs, where through-life support commitments determine vendor selection.
Sonobuoy Launcher Market Segmentation
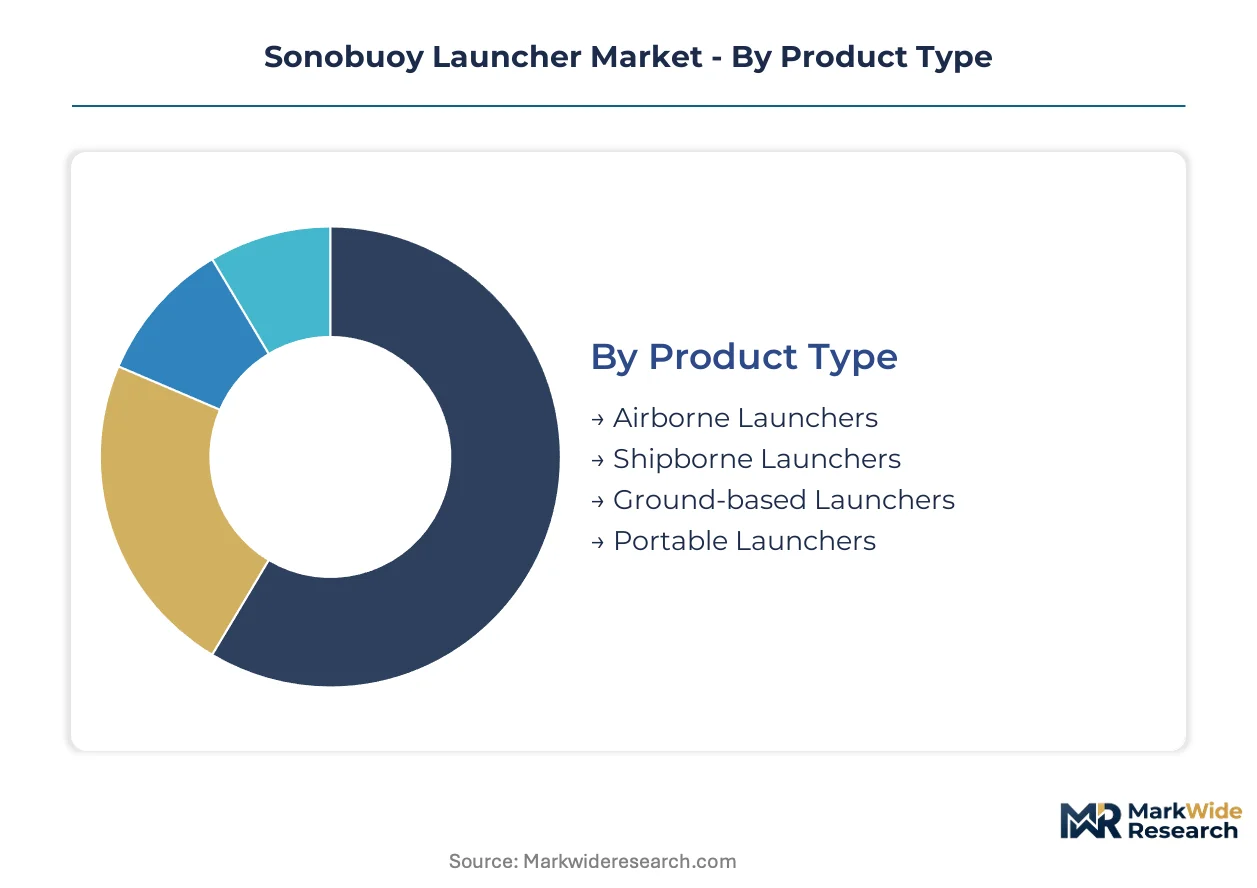
Sonobuoy launcher procurement patterns diverge sharply across deployment platforms and acoustic technologies. Understanding these splits reveals where engineering investment concentrates and which customer segments command pricing power.
Product Type:
Volume deployment favors fixed-installation systems, while premium margins attach to specialized configurations for expeditionary forces.
- Airborne Launchers:Pneumatic ejection systems rated for 3000+ PSI operation from maritime patrol aircraft fuselage stations. United States Navy P-8A Poseidon squadrons drive retrofit demand as legacy analog stocks deplete. FAA airworthiness certification timelines constrain supplier selection to established avionics integrators.
- Shipborne Launchers:Deck-mounted electro-mechanical systems with integrated magazine storage for rotary or fixed-wing drone operations. Japan Maritime Self-Defense Force destroyer modernization programs concentrate procurement for integrated ASW suites. NATO STANAG 4155 compliance requirements filter vendor pools.
- Ground-based Launchers:Fixed coastal defense installations with networked acoustic processing. South Korean coastal surveillance infrastructure expansion sustains regional demand clusters.
- Portable Launchers:Man-portable pneumatic units deployable from rigid-hull inflatable boats. Royal Australian Navy littoral combat teams prioritize rapid-deployment capabilities for archipelago operations.
Mature deployment sits with Airborne Launchers. Newer deployment is concentrated in Portable Launchers.
Technology:
Acoustic processing sophistication determines launcher firmware integration requirements and procurement cycle compression.
- Multi-Mode Sonobuoys:Unified acoustic detection, communication, and navigation architectures requiring launcher control bus upgrades for real-time beamforming. United Kingdom maritime patrol programs mandate these configurations for mixed-nationality task force interoperability. EU AI Act algorithmic documentation requirements add compliance layers.
- Digital Sonobuoys:Fully digitized signal processing with reduced false-positive rates and firmware-upgradable detection profiles. Royal Canadian Air Force CP-140 Aurora modernization exemplifies adoption acceleration. Legacy analog launcher incompatibility forces hardware refresh cycles.
- Passive Sonobuoys:Traditional acoustic listening devices with minimal launcher interface complexity. Remaining NATO inventory stocks limit near-term procurement velocity.
- Active Sonobuoys:Pinger-equipped detection buoys for precise target localization. Specialized naval aviation units in the Indo-Pacific sustain niche demand.
Established deployment rests with Passive Sonobuoys. Steepest expansion trajectory belongs to Digital Sonobuoys.
End User:
Budget scale and procurement autonomy separate sovereign naval programs from institutional research buyers.
- Naval Forces:National maritime aviation branches with through-life support contracting authority. United States, United Kingdom, and Japanese naval aviation commands dominate volume procurement with integrated product-service agreements.
- Defense Agencies:Cross-service procurement bodies managing multi-platform standardization. NATO procurement agencies enforce STANAG harmonization across member fleets.
- Research Institutions:Oceanographic and acoustic research organizations with limited batch purchasing. Scripps Institution of Oceanography and similar entities drive environmental monitoring application development.
- Private Contractors:Maritime security firms and systems integrators serving non-state surveillance requirements. Growth concentrates in Southeast Asian coastal protection services.
Institutional procurement maturity centers on Naval Forces. Emerging demand clusters within Private Contractors.
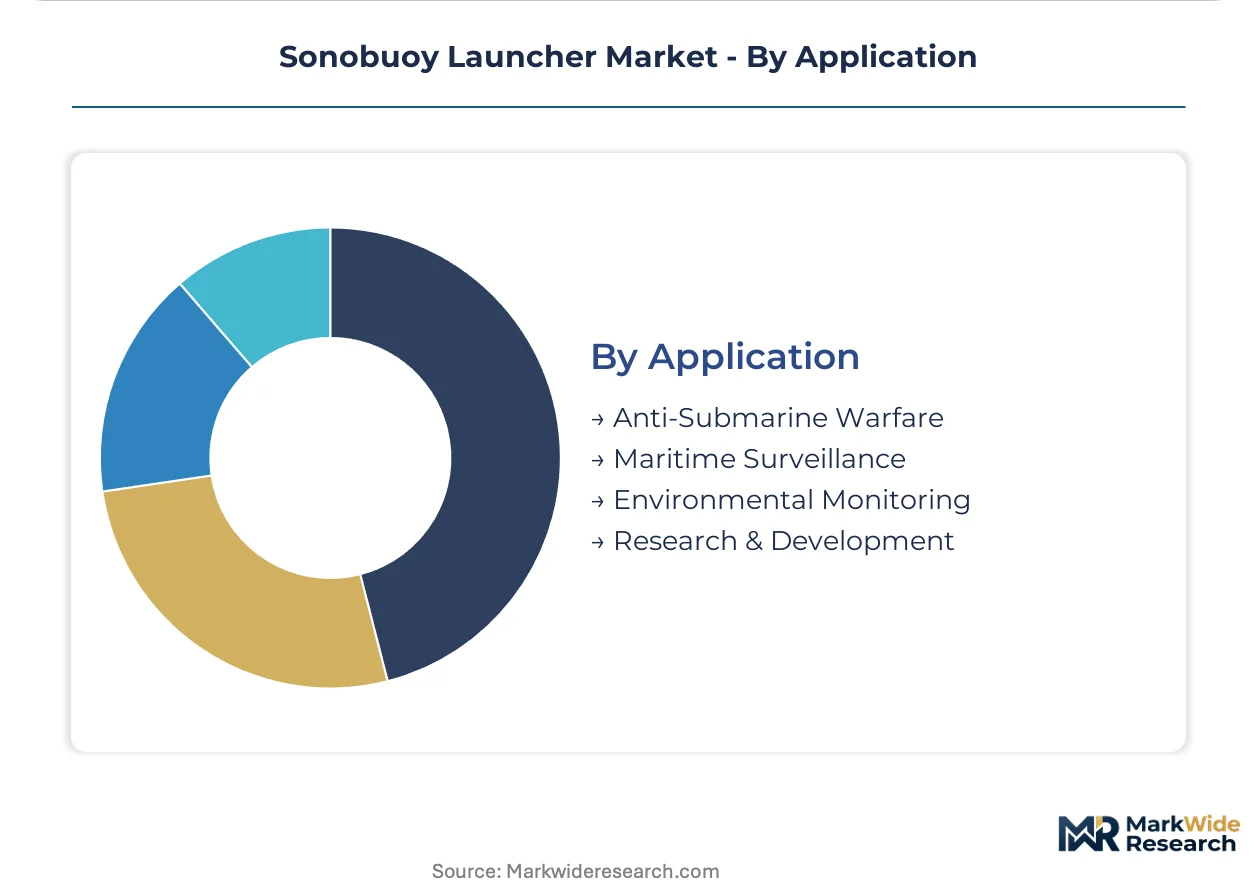
Application:
Mission-critical defense applications sustain premium pricing, while environmental and research uses expand addressable market boundaries.
- Anti-Submarine Warfare:Core military application requiring calibrated depth deployment and acoustic grid precision. United States Pacific Fleet operations against advanced diesel-electric submarine threats drive capability investment. STANAG 4155 interoperability mandates shape launcher specification.
- Maritime Surveillance:Broad-area acoustic monitoring for exclusive economic zone enforcement. Australian Border Force and similar agencies adopt multi-mode sonobuoy configurations for persistent coverage.
- Environmental Monitoring:Oceanographic data capture for climate research and marine mammal tracking. Academic and governmental research programs in Norway and Canada expand civilian application scope.
- Research & Development:Experimental acoustic technology validation and prototype deployment. Defense research establishments in France and Sweden test next-generation beamforming algorithms.
Operational maturity anchors Anti-Submarine Warfare. Application expansion is gaining share fastest in Environmental Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naval aviation modernization concentrates procurement authority in the United States, United Kingdom, and Japan, while coastal defense investments across the Indo-Pacific rim generate secondary demand clusters for portable and shipborne configurations.
United States
P-8A Poseidon maritime patrol aircraft retrofits drive airborne launcher demand as the Navy depletes legacy analog sonobuoy stocks. FAA airworthiness directives govern launcher carriage on civil-modified military platforms, extending supplier qualification timelines. San Diego and Jacksonville naval aviation clusters anchor Pacific and Atlantic fleet modernization programs.
United Kingdom
Royal Air Force P-8 Poseidon acquisitions mandate STANAG 4155-compliant launcher systems for NATO task force interoperability. Ministry of Defence through-life support contracting prioritizes integrated product-service agreements over discrete hardware procurement. Lossiemouth in Scotland hosts the primary maritime patrol operating base for North Atlantic coverage.
Japan
Japan Maritime Self-Defense Force destroyer modernization concentrates demand for integrated shipborne ASW suites with electro-mechanical launchers. Defense equipment export guideline relaxations enable deeper supply chain integration with Australian and British programs. Kure and Yokosuka naval districts coordinate procurement for fleet-wide acoustic detection upgrades.
Australia
Royal Australian Navy littoral combat teams prioritize rapid-deployment portable launchers for archipelago surveillance operations. Border Force maritime surveillance expansion adopts multi-mode sonobuoy configurations for exclusive economic zone enforcement. Darwin and Cairns sustain regional maintenance hubs for Indo-Pacific patrol coverage.
South Korea
Coastal surveillance infrastructure expansion sustains fixed ground-based launcher installations for acoustic grid coverage against submarine threats. Defense Acquisition Program Administration standardization efforts align procurement with emerging NATO digital sonobuoy protocols. Busan and Incheon anchor naval shipyard integration of launcher systems into new destroyer classes.
Sonobuoy Launcher Market Competitive Environment
Strategic partnerships dominate the current landscape as prime contractors bundle launcher hardware with acoustic data analytics and through-life support commitments. The vendor base organizes around three tiers: integrated avionics conglomerates with FAA certification heritage, specialized Nordic shipborne system fabricators, and rapid-deployment portable specialists serving littoral operators. Competitive positioning hinges on firmware integration capabilities rather than mechanical engineering alone. Technology licensing agreements and backward integration into pneumatic subsystem manufacturing represent the two dominant competitive vectors reshaping supplier relationships.
Within the integrated avionics tier, L3Harris Technologies and Harris Corporation exemplify archetypes leveraging civil aviation regulatory pathways into military retrofit contracts. Kongsberg Gruppen anchors Nordic supply chain concentration for specialized shipborne configurations. These three entities occupy positions where launcher hardware margins increasingly depend on bundled signal-processing firmware and maintenance telemetry contracts rather than discrete mechanical sales.
| Leading Market Players |
|---|
| JSK Naval Support |
| Harris Corporation |
| L3Harris Technologies |
| Kongsberg Gruppen |
| Aurora Flight Science |
| Alkan |
| Marshall Aerospace |
| General Dynamics |
| Geospectrum Technologies |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FAA-certified airborne systems and non-certified portable units manifests in both pricing stratification and supplier qualification requirements. Premium airborne launchers command sustained margins through bundled firmware and maintenance telemetry, while portable configurations compete on nickel-titanium alloy input costs and rapid-deployment cycle times.
Pricing Analysis
Volume deployment concentrates in fixed-installation shipborne systems where per-unit margins compress, while premium pricing attaches to airborne launcher retrofits with integrated avionics and STANAG 4155 compliance certification. Price differentiation rests on FAA airworthiness validation tier and firmware integration depth. Pricing pressure stems from specialty alloy cost volatility in high-pressure pneumatic cylinders. Naval aviation branches exhibit lowest price sensitivity due to through-life support contracting mandates, while Southeast Asian private contractors demonstrate acute sensitivity to unit acquisition costs.
Supply Chain Analysis
Dual-sourcing requirements for 3000+ PSI-rated launch cylinders mandate qualified suppliers in the United States, United Kingdom, and Japan to satisfy NATO procurement protocols. Manufacturing draws from specialty nickel and titanium alloy feedstocks with precision machining dependencies. Single-source vulnerability concentrates in pneumatic subsystem fabrication where ITAR-controlled technology limits vendor pools. Distribution runs through prime contractor integration channels rather than direct OEM sales to end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over pneumatic subsystem manufacturing and signal-processing firmware development determines competitive viability. Players are pursuing backward integration into high-pressure cylinder fabrication to secure supply and capture margin.
For Market Incumbents: Acquire pneumatic machining capacity in NATO-aligned geographies to reduce specialty alloy exposure and compress lead times. Consolidate firmware development teams with acoustic signal-processing specialists to defend against integrated subsystem bundling by avionics conglomerates. STANAG 4155 harmonization mandates create qualification barriers that favor incumbents with existing certification heritage. For New Entrants and Emerging Players: EU AI Act algorithmic documentation requirements in Europe open a window for compliance-native entrants to bypass legacy system retrofit burdens. Target portable rapid-deployment configurations for Southeast Asian littoral operators where procurement autonomy exceeds NATO standardization constraints. Pursue channel partnerships with rigid-hull inflatable boat manufacturers rather than direct naval procurement channels. For Investors and Strategic Acquirers: Re-rating potential sits with firmware-integrated hardware specialists given EU AI Act compliance layering and through-life support contract expansion. Long-term viability favors vendors with captive pneumatic subsystem production and NATO STANAG certification history. Watch unmanned platform integration velocity as inflection indicator for miniaturized launcher demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pneumatic Manufacturing | Captive production of 3000+ PSI cylinders reduces nickel-titanium exposure and ITAR transfer delays. |
| Firmware-Acoustic Bundling | Integrated signal-processing capabilities satisfy EU AI Act documentation requirements for NATO fleets. |
| Portable System Miniaturization | Man-portable configurations address Royal Australian Navy archipelago surveillance requirements. |
| STANAG 4155 Certification Investment | Cross-national fleet interoperability mandates filter vendor pools to qualified integrators. |
| Unmanned Platform Integration | Autonomous maritime surveillance drones create demand for reduced-weight launcher architectures. |
Study Parameters
Document review covered NATO procurement directives, FAA airworthiness certification databases, and defense agency budget disclosures, complemented by interviews with maritime patrol avionics engineers, naval procurement officers, pneumatic subsystem manufacturing managers, and acoustic signal-processing specialists. Secondary validation drew from STANAG technical specifications, ITAR-controlled technology transfer records, and EU dual-use export control harmonization frameworks. Bottom-up segment sizing triangulated against top-down fleet modernization budget allocations.
Cross-reference between historical deployment velocity and expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include platform type, acoustic technology tier, end-user procurement authority, and application mission profile. CAGRs derived from fleet refresh cycle timing and digital sonobuoy adoption trajectory. Industry-specific inputs incorporated P-8A Poseidon squadron deployment schedules and Japan Maritime Self-Defense Force destroyer modernization phasing.
The model assumes a particular technology adoption path; alternative pathways for multi-mode digital beamforming would alter the outlook if legacy analog sonobuoy depletion accelerates or stalls. Forecasts reflect documented procurement assumptions and fleet interoperability mandates. Deviation in EU AI Act implementation timing or ITAR-EU dual-use regulatory alignment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Shotgun and Rifles Market
Weapons and Ammunition
Ballistic Composite Market
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market
Weapons and Ammunition
Global Ammunition Market
Weapons and Ammunition
Airsoft Guns Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Artillery Ammunition Market
Weapons and Ammunition
Tank Ammunition Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Vehicle Mounted Anti-Tank Missile System Market
Weapons and Ammunition
Martial Art Weapon Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market
Weapons and Ammunition
Nuclear Bomb Market
Weapons and Ammunition
Cluster Munitions Market
Weapons and Ammunition
Smart Weapons Market