
 Mortar Artillery System Market | 2026-2036
Mortar Artillery System Market Size, Share, and Industry Trends Forecast 2026-2036
Mortar Artillery System Market Analysis
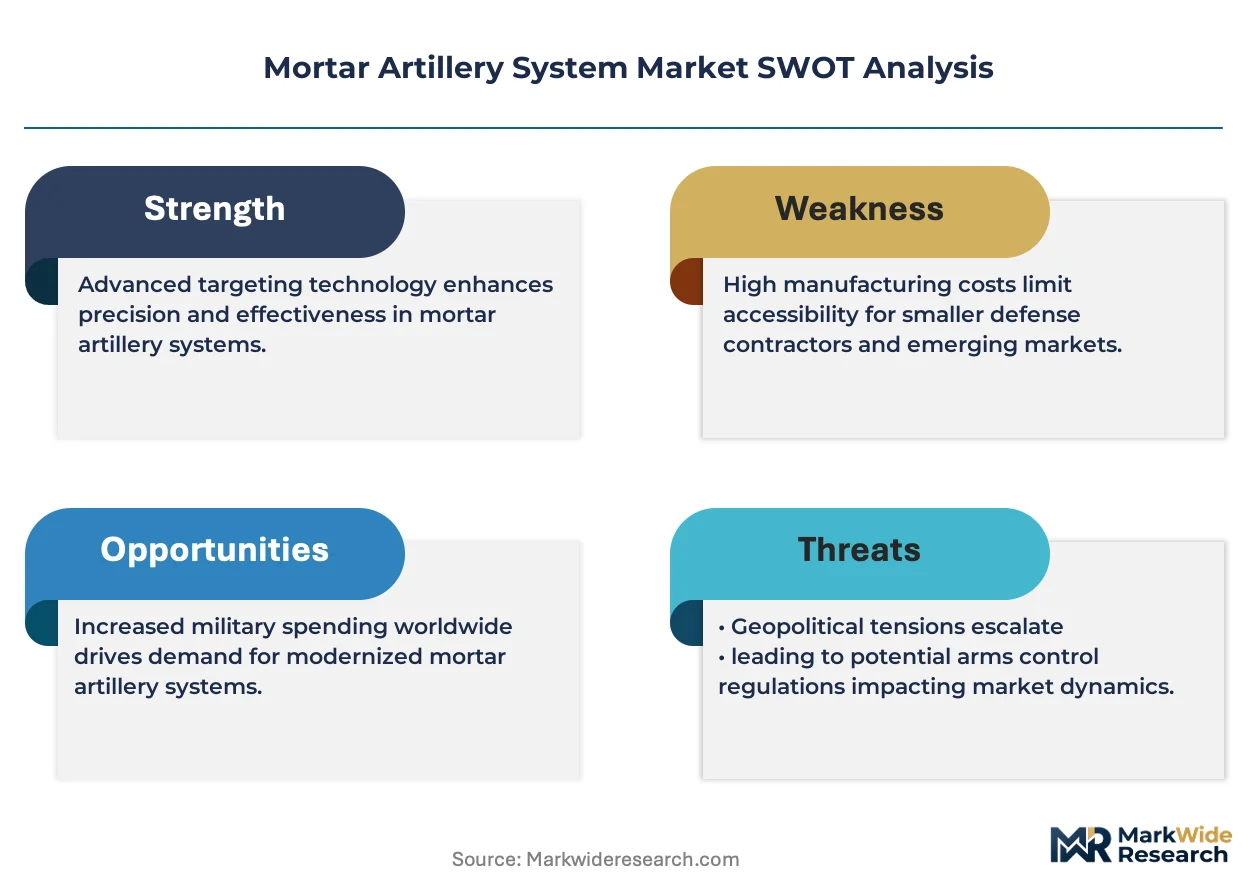
Multi-source procurement among NATO defense ministries is consolidating around a smaller pool of qualified mortar system integrators. Rheinmetall AG leverages its ammunition-to-platform verticality to capture full-stack contracts. Saab AB competes through advanced fire-control software that reduces time-to-target. Elbit Systems anchors its position with hybrid mortar turrets that retrofit existing armored vehicle hulls.
A mortar artillery system delivers indirect fire through smoothbore, muzzle-loaded tubes typically ranging from 60mm to 120mm caliber, designed to launch fin-stabilized projectiles at high angles against concealed or defilade targets. These systems serve as organic fire support for maneuver units, bridging the range gap between hand-held weapons and conventional tube artillery. Self-propelled mortars now command the largest share of new procurement budgets as armies prioritize shoot-and-scoot survivability against counter-battery radar. Digital fire control technology represents the fastest-expanding segment, integrating inertial navigation and automated ballistic computation to achieve first-round effects without manual adjustment. Heavy mortars retain entrenched demand in siege and urban warfare scenarios where explosive payload mass outweighs mobility requirements.
The U.S. Department of Defense's Joint Capabilities Integration and Development System shapes platform requirements through validated needs statements that contractors must satisfy for program entry. NATO's Standardization Agreement 2321 governs 120mm mortar ammunition interchangeability, creating regulatory pull for compliant designs across allied procurement pools. The EU Green Deal's emerging defense industrial decarbonization guidelines will likely affect propellant formulation and manufacturing energy intensity in European supply chains. Stakeholders must monitor how export control expansions under the U.S. International Traffic in Arms Regulations reshape technology transfer pathways for fire-control software and precision-guided mortar munitions.
Market Dynamics
Automated fire-control integration is compressing procurement cycles across NATO defense ministries, forcing legacy platform operators to accelerate technology refresh timelines or face operational obsolescence against peer adversaries with counter-battery detection capabilities.
Growth Catalysts
- Precision Fires Modernization:The U.S. Department of Defense's validated needs statements under JCIDS create program entry requirements that pull automated mortar platforms into active procurement pipelines.
- NATO Standardization Agreement 2321:Ammunition interchangeability mandates for 120mm mortars generate regulatory pull for compliant designs across allied procurement pools.
- Artillery Recapitalization Programs:National defense ministries in Poland, Turkey, and South Korea are executing multi-year replacement schedules for tube artillery and mortar systems.
Market Restraints
- Propellant Supply Concentration:Nitrocellulose and nitroglycerin precursor production clusters in China and Russia create input vulnerability for Western munitions manufacturers.
- Export Control Expansion:U.S. International Traffic in Arms Regulations increasingly restrict technology transfer pathways for fire-control software and precision-guided mortar munitions.
- Platform-Ammunition Mismatch:Legacy 81mm systems in active inventory resist full-stack replacement, fragmenting procurement budgets across incompatible caliber lines.
Strategic Opportunities
- Hybrid Turret Retrofit:Armored vehicle hulls in existing fleets present addressable white space for mortar turret integration without full platform replacement.
- EU Green Deal Defense Guidelines:Emerging decarbonization requirements for defense industrial supply chains will reshape propellant formulation and manufacturing energy intensity in European production.
- Urban Warfare Payload Demand:Siege scenarios and dense terrain operations sustain entrenched demand for heavy mortar explosive mass where mobility requirements yield to destructive effect.
Industry Challenges
- Ballistic Computation Talent Scarcity:Inertial navigation and automated firing solution software development requires specialized expertise that defense contractors compete aggressively to secure.
- Legacy System Integration Complexity:Digital fire-control retrofits must interface with analog command structures in active maneuver units, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mortar Artillery System Market |
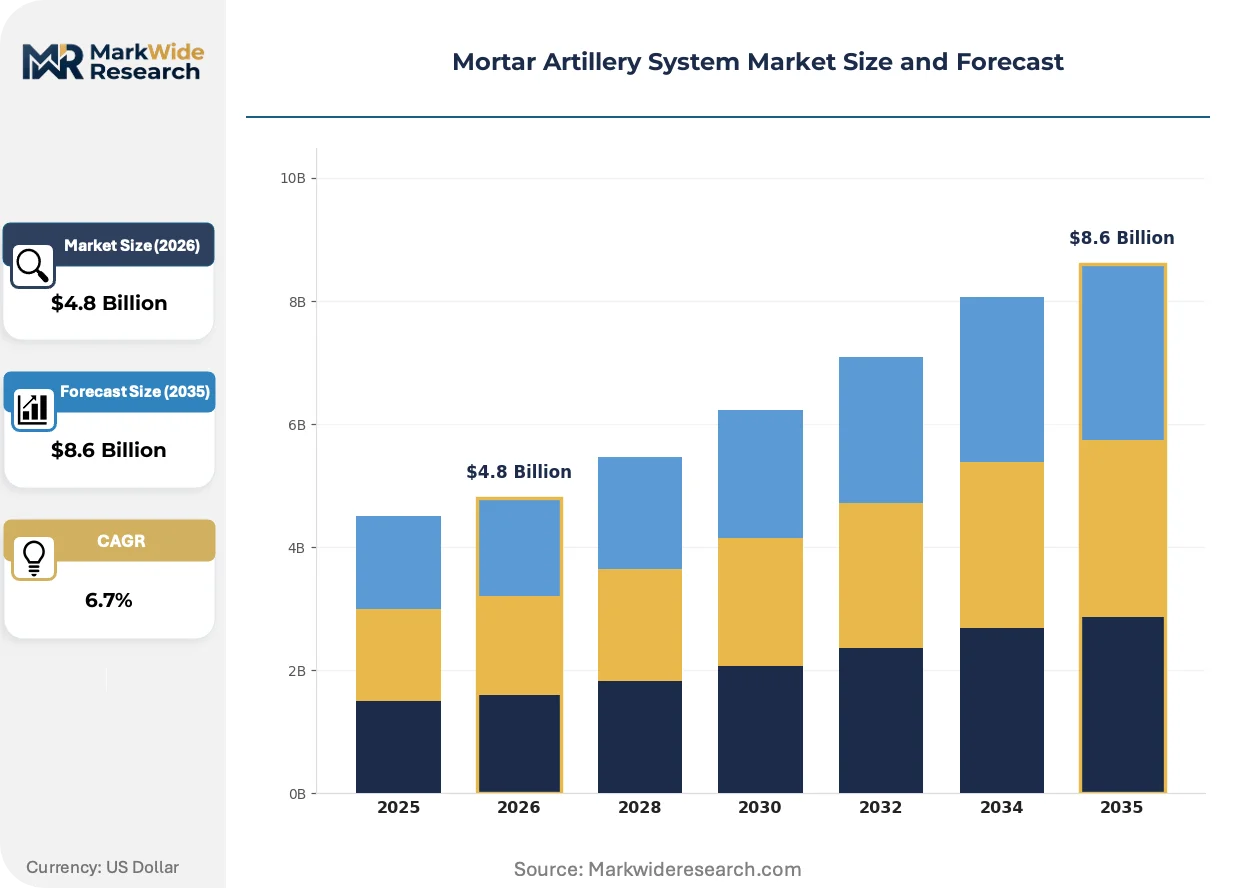
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Mortars, Self-Propelled Mortars, Heavy Mortars, Light Mortars Deployment Mode: Mobile, Stationary, Towed, Automated End User: Military, Defense Contractors, Government Agencies, International Forces Technology: Digital Fire Control, Advanced Targeting Systems, Remote Operation, Hybrid Systems |
| Companies Covered | Nammo AS, Saab AB, Rheinmetall AG, Lockheed Martin Corporation, Northrop Grumman Corporation, General Dynamics Corporation, Elbit Systems, Thales Group, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mortar Artillery System Market Emerging Trajectories
Shoot-and-scoot survivability requirements are driving convergence between mobility platforms and precision delivery systems, compressing the traditional separation between tube artillery and organic fire support assets.
Digital fire control technology integrating inertial navigation with automated ballistic computation is overtaking manual adjustment protocols in new procurement specifications. NATO member state armies are mandating first-round effects capability without observer correction, compressing training pipelines and reducing forward observer dependency. This capability compression is enabling smaller fire support teams to deliver effects previously requiring battery-level coordination.
REACH and emerging EU Green Deal defense industrial guidelines are tightening chemical substance restrictions and manufacturing energy intensity standards for European supply chains. Propellant manufacturers face reformulation requirements for nitrocellulose stabilizers and combustion byproducts. German and French defense ministries are responding with accelerated qualification programs for alternative binder chemistries in mortar ammunition production.
Consolidation around qualified system integrators is concentrating buyer power in the hands of defense ministries with multi-source procurement authority. Traditional platform specialists now compete against full-stack ammunition-to-system providers, displacing component-level vendors from prime contractor positions. This pattern is most visible in Polish and Turkish artillery recapitalization tenders, where integrated logistics support packages dominate evaluation criteria.
Mortar Artillery System Market Segmentation
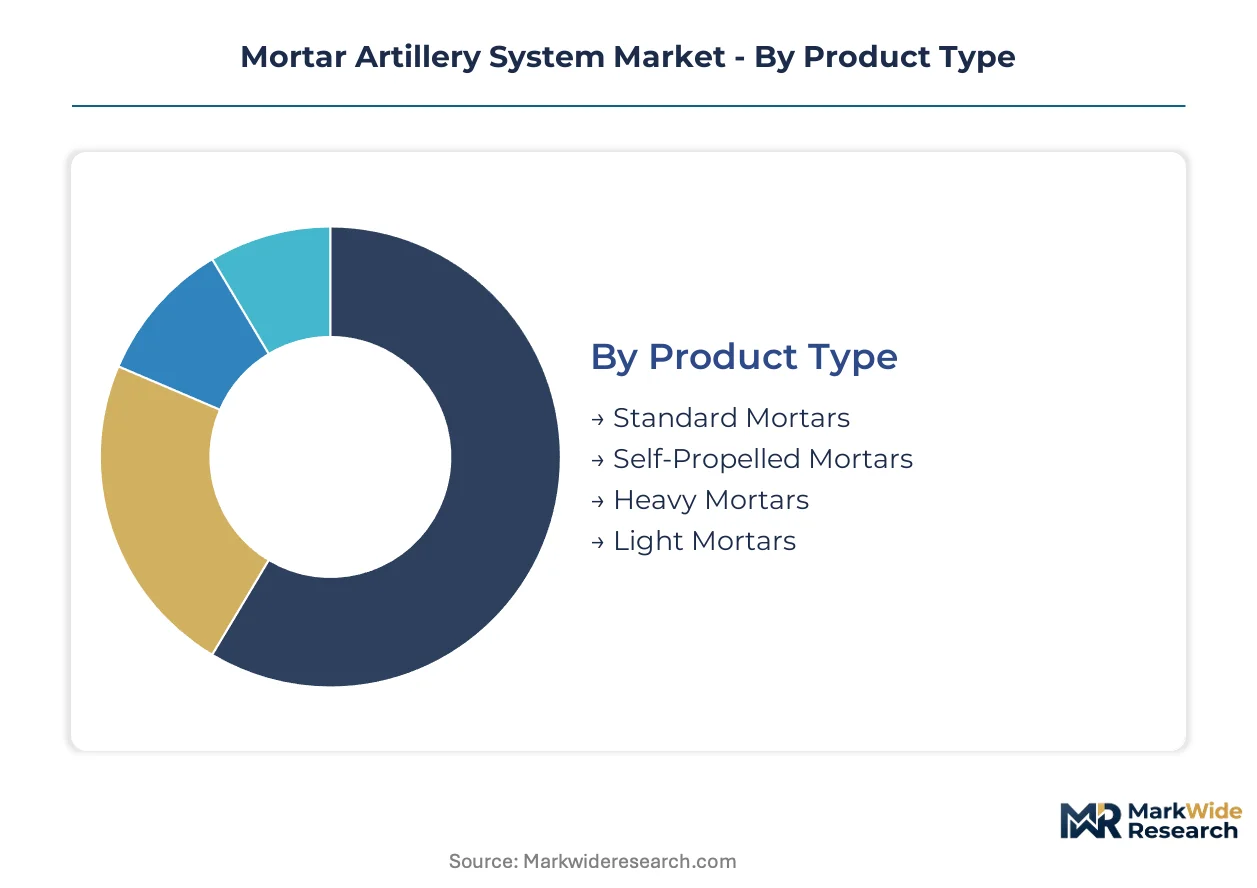
Mortar artillery procurement fragments across platform mobility, fire-control sophistication, and end-user operational requirements. Procurement officers navigate trade-offs between expeditionary lightness and payload mass, between analog reliability and digital precision. Understanding these segment boundaries clarifies where defense budgets concentrate and where technology refresh cycles accelerate.
Product Type:
Customization spans from expeditionary man-portable tubes to fully integrated armored vehicle turrets, with standardization concentrated in NATO ammunition interoperability mandates.
- Self-Propelled Mortars:These systems mount mortar tubes on wheeled or tracked chassis with integral ammunition storage and automated loading. Polish and Turkish defense ministries prioritize this category for shoot-and-scoot survivability against Russian counter-battery radar in Eastern European scenarios. Digital fire control integration compresses time-to-target below 60 seconds.
- Heavy Mortars:120mm and larger calibers deliver explosive mass for siege and urban warfare where destructive effect outweighs mobility constraints. South Korean procurement emphasizes this segment for hardened target engagement along the DMZ. Tube weight exceeds 150 kilograms, requiring vehicle transport or emplacement.
- Standard Mortars:Conventional 60mm to 81mm infantry mortars with bipod and baseplate configurations dominate active inventory across NATO maneuver units.
- Light Mortars:Sub-60mm systems designed for airborne and special operations forces prioritize dismounted portability over range and payload.
Most installed capacity flows through Standard Mortars. Expansion is steepest in Self-Propelled Mortars.
Deployment Mode:
Cost tiers separate legacy towed systems from premium automated platforms, with mobility premiums widening as counter-battery detection capabilities proliferate.
- Automated:Robotic loading, inertial navigation, and networked fire control enable reduced crew sizes and accelerated engagement sequences. U.S. Army requirements under precision fires modernization mandate first-round effects without observer correction. Platform-ammunition integration demands qualified system integrators with full-stack capabilities.
- Mobile:Vehicle-mounted but manually operated systems balance responsiveness against procurement economy. Turkish defense contractors specialize in retrofitting these configurations onto domestic armored vehicle hulls for regional export markets.
- Towed:Conventional tube-and-carriage designs persist in reserve formations and cost-constrained procurement environments.
- Stationary:Fixed emplacements for garrison defense and coastal artillery applications where mobility requirements are minimal.
Procurement volume concentrates in Mobile configurations. Technology refresh investment flows fastest into Automated systems.
End User:
Customer type determines specification stringency, with military end users driving interoperability mandates and defense contractors controlling integration complexity.
- Military:National army and marine corps formations specify platform-ammunition integration under NATO Standardization Agreement 2321 for 120mm interchangeability. Polish artillery recapitalization exemplifies multi-year replacement schedules with integrated logistics support requirements.
- Defense Contractors:Prime system integrators aggregate component procurement for government clients, concentrating buyer power through full-stack ammunition-to-platform contracts. Rheinmetall AG leverages this position in German and allied procurement pools.
- Government Agencies:Coast guard and border security organizations acquire reduced-capability variants for area denial and illumination missions.
- International Forces:Coalition and peacekeeping contingents operate under multinational funding mechanisms with equipment standardization constraints.
Budget authority concentrates with Military end users. Contractor-led procurement is expanding most quickly in Central and Eastern European markets.
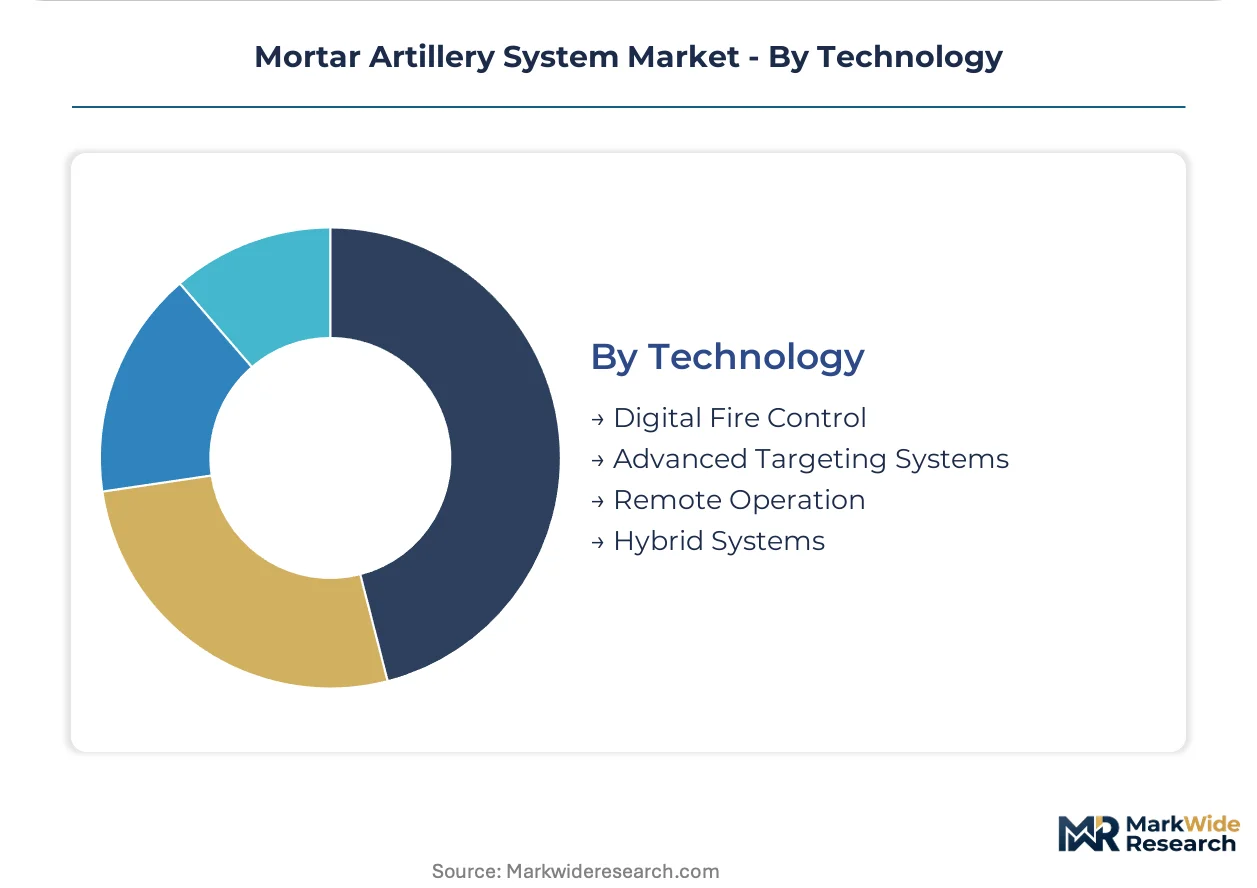
Technology:
Supply concentration in fire-control software development creates capability scarcity, with qualified vendors capturing premium positioning in digital integration contracts.
- Digital Fire Control:Inertial navigation, automated ballistic computation, and networked target acquisition replace manual firing tables. Saab AB competes through software that reduces sensor-to-shooter timelines below peer adversary counter-battery response windows. NATO armies now mandate this capability for new procurement.
- Hybrid Systems:Retrofit turrets integrating mortar tubes with existing armored vehicle hulls address white space in fleet modernization. Elbit Systems anchors market position through this approach, minimizing platform replacement costs for budget-constrained ministries.
- Advanced Targeting Systems:Laser designation and drone-cued engagement expand precision mortar applications beyond traditional area suppression.
- Remote Operation:Crew-under-armor configurations reduce vulnerability during firing sequences, particularly relevant for urban warfare exposure.
Deployment concentrates in Digital Fire Control. Hybrid Systems are gaining share fastest as retrofit demand accelerates technology refresh without full fleet replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's defense industrial corridor anchors procurement momentum for automated mortar platforms as NATO's eastern flank accelerates artillery recapitalization. The U.S. Joint Capabilities Integration and Development System validates platform requirements that shape allied procurement specifications. Turkey and South Korea operate as secondary demand centers with distinct national modernization priorities.
United States
The U.S. Department of Defense's precision fires modernization program validates automated mortar requirements through JCIDS needs statements. ITAR regulations increasingly restrict fire-control software and precision-guided munition technology transfers to allied nations. Defense contractors cluster around Washington D.C.-Maryland-Virginia corridor and Huntsville, Alabama, where system integrators compete for Army and Marine Corps procurement contracts.
Germany
Rheinmetall AG's ammunition-to-platform verticality captures full-stack contracts across German and allied defense ministries. EU Green Deal defense industrial guidelines are accelerating propellant reformulation programs for nitrocellulose stabilizers. The Düsseldorf-Cologne industrial belt concentrates mortar system manufacturing alongside qualified ammunition production facilities.
Poland
Polish defense ministries execute multi-year artillery replacement schedules prioritizing shoot-and-scoot survivability against Russian counter-battery capabilities. NATO Standardization Agreement 2321 mandates 120mm ammunition interchangeability in Polish procurement specifications. The Warsaw-Łódź defense corridor hosts emerging system integration capabilities as Poland builds indigenous mortar platform production.
Turkey
Turkish defense contractors specialize in retrofitting mobile mortar configurations onto domestic armored vehicle hulls for regional export markets. National procurement prioritizes hybrid turret integration without full platform replacement costs. Ankara-Istanbul industrial zones concentrate mortar platform manufacturing alongside ammunition production facilities serving Middle Eastern and Central Asian clients.
South Korea
South Korean procurement emphasizes heavy mortar explosive mass for hardened target engagement along the DMZ. MFDS regulatory frameworks govern defense industrial quality standards for ammunition production. The Seoul Capital Area defense industrial cluster integrates fire-control software development with precision munition manufacturing capabilities.
Mortar Artillery System Market Vendor Landscape
Global majors compete with regional champions across platform integration and ammunition supply chains, producing a tiered structure where full-stack providers displace component specialists. Consolidation concentrates buyer power in defense ministries with multi-source procurement authority. Three archetypes dominate: ammunition-to-platform integrators, fire-control software specialists, and hybrid retrofit turret providers. M&A activity targets ballistic computation talent, while strategic partnerships secure propellant supply chains against input concentration risks.
Within the full-stack integration tier, Rheinmetall AG and Elbit Systems exemplify divergent strategic positions. Rheinmetall anchors European procurement through captive ammunition production and platform manufacturing capabilities. Elbit Systems occupies a retrofit-specialist position, minimizing platform replacement costs for budget-constrained ministries. Saab AB represents the software-centric archetype, competing through reduced sensor-to-shooter timelines rather than hardware integration.
| Leading Market Players |
|---|
| Nammo AS |
| Saab AB |
| Rheinmetall AG |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| Elbit Systems |
| Thales Group |
| BAE Systems |
| Others |
Supply Flow & Price Mechanics
Nitrocellulose precursor costs cascade through mortar ammunition manufacturing, with Chinese and Russian feedstock concentration compressing margins for Western propellant suppliers while NATO Standardization Agreement 2321 compliance premiums sustain pricing tiers for qualified 120mm ammunition.
Pricing Analysis
Input-cost pass-through from nitrocellulose and nitroglycerin precursors shapes contract-based long-term offtake pricing for mortar ammunition, with quality grade and NATO STANAG 2321 certification level as primary differentiation drivers. Pricing pressure intensifies in standard mortar segments as legacy 81mm inventory resists replacement, fragmenting procurement budgets. Defense contractors exhibit lowest price sensitivity given full-stack integration requirements, while reserve formations and cost-constrained ministries drive economy-tier demand.
Supply Chain Analysis
Domestic-content mandates in Poland, Turkey, and South Korea are reshaping sourcing patterns, compelling foreign primes to establish local mortar platform assembly or forfeit tender eligibility. Nitrocellulose production draws from China and Russia, with nitroglycerin synthesis anchored in European chemical clusters. Single-source vulnerability in propellant precursors creates supply chain risk. Distribution runs through prime system integrators delivering integrated logistics support packages to defense ministries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mortar artillery system market compounds steadily as precision fires modernization programs across NATO allies generate predictable replacement demand regardless of near-term budget cycles.
For Market Incumbents: Acquire ballistic computation software talent to defend against Saab AB's sensor-to-shooter timeline compression. Backward integration into nitrocellulose precursor supply hedges Chinese input concentration. Pursue NATO STANAG 2321 certification investment to lock in allied ammunition interchangeability mandates. For New Entrants and Emerging Players: Enter via hybrid turret retrofit white space in Central and Eastern European armored vehicle fleets, where budget constraints favor platform extension over replacement. Target Polish and Turkish artillery recapitalization tenders through local partnership structures that satisfy domestic-content rules. For Investors and Strategic Acquirers: Consolidation pressure builds where fire-control software capability scarcity concentrates premium positioning among qualified vendors. Five-to-ten-year viability favors full-stack ammunition-to-platform integrators over component specialists. Watch for EU Green Deal defense industrial decarbonization guidelines as inflection indicator for propellant reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Fire-Control Software Acquisition | Captures sensor-to-shooter timeline compression capability against peer counter-battery threats. |
| Propellant Supply Backward Integration | Secures nitrocellulose precursor access against Chinese and Russian feedstock concentration. |
| Hybrid Turret Platform Integration | Addresses Polish and Turkish fleet modernization without full armored vehicle replacement. |
| NATO STANAG 2321 Certification Investment | Unlocks 120mm ammunition interchangeability compliance across allied procurement pools. |
| Local Assembly Joint Venture | Satisfies domestic-content mandates in Polish and Turkish defense tender evaluations. |
Methodological Framework
Coverage spans NATO member states, South Korea, and Turkey, with primary inputs from each region combining interviews with defense procurement officers, mortar system program managers, fire-control software engineers, and ammunition manufacturing technical directors. Secondary validation draws from U.S. Department of Defense JCIDS documentation, NATO standardization agreements, EU Green Deal defense industrial guidelines, and national defense ministry budget disclosures. Bottom-up platform and ammunition volume estimates triangulate against top-down defense spending allocation analysis.
Granularity-level modeling addresses self-propelled, heavy, standard, and light mortar categories alongside automated, mobile, towed, and stationary deployment modes. Military, defense contractor, government agency, and international force end-user segments structure demand-side disaggregation. CAGRs derive from technology refresh cycle analysis and artillery recapitalization program timelines. Fire-control software development pipeline assessment and propellant supply chain vulnerability scoring inform industry-specific forecast inputs across the projection horizon.
Inputs from defense ministry procurement databases and prime contractor program disclosures were available through the study window; gaps in classified counter-battery capability specifications and precise ammunition inventory levels introduce uncertainty bands around platform replacement timing assumptions. Forecasts reflect documented program schedules and validated needs statements under JCIDS and allied equivalents. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Shoulder Fixed Weapons Market
Weapons and Ammunition
Smoke Grenade Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
Land-Based Remote Weapon Stations Market
Weapons and Ammunition
Smart Bombs Market
Weapons and Ammunition
Intercontinental Ballistic Missile Market
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Military Helmet Market
Weapons and Ammunition
Turret System Market
Weapons and Ammunition
Airborne Weapon System Market
Weapons and Ammunition
Cruise Missile Market
Weapons and Ammunition
Electromagnetic Weapons Market
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Cluster Munitions Market