
 Skin Packaging Market | 2026-2036
Skin Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Packaging Market Intelligence
EU REACH compliance is shifting the cost-of-entry calculus for film suppliers serving European food processors. Amcor plc leverages its global resin sourcing network to sustain multi-region supply continuity for skin packaging films. Berry Global Group anchors North American tray production through integrated thermoforming operations. Sealed Air Corporation differentiates via high-barrier coextrusion technology for protein packaging applications.
Skin packaging refers to a vacuum-forming process where a flexible or rigid film is drawn tightly over a product placed on a paperboard or plastic backing, creating a skin-tight seal with oxygen barrier properties typically below 1 cc/m²/day. This technique serves primarily to extend perishable product shelf life while providing retail-ready presentation and tamper evidence. Polyethylene formulations occupy the largest material share due to cost efficiency and sealability across meat packaging applications, though polypropylene films are gaining traction in fresh produce segments where clarity and moisture resistance command premium positioning. Flexible films dominate product type demand because they conform to irregular protein cuts and enable source reduction versus rigid alternatives.
FDA food contact substance notifications govern film formulations in the United States, while EU REACH and the Packaging and Packaging Waste Regulation constrain additive chemistries and mandate recyclability targets. BIS standards in India and GB standards in China impose additional migration limits and testing protocols for imported packaging materials. Stakeholders must monitor evolving extended producer responsibility frameworks and mono-material recyclability certifications to align product development with tightening compliance requirements.
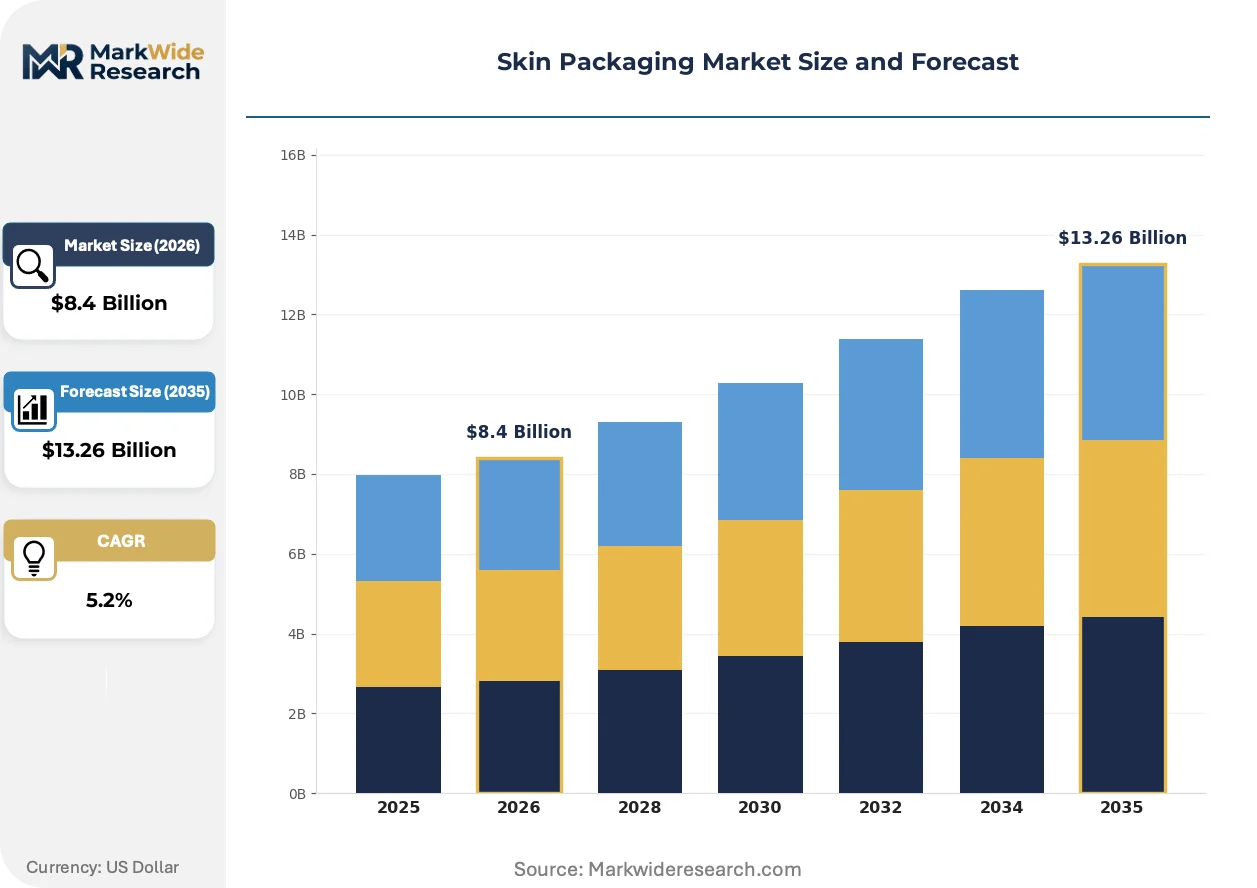
Market Dynamics
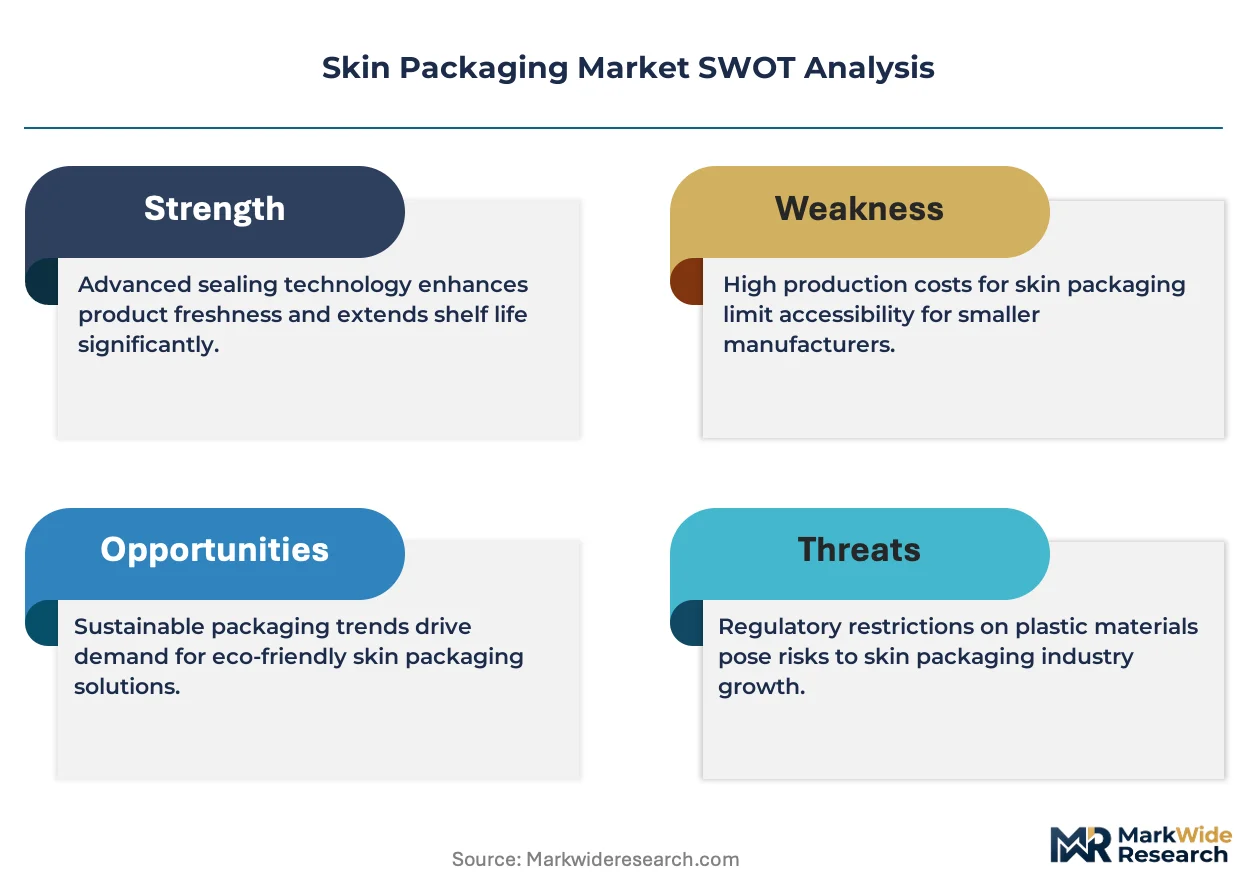
The EU Packaging and Packaging Waste Regulation is forcing film suppliers to abandon multi-layer barrier structures in favor of mono-material polyethylene and polypropylene formulations that satisfy mechanical recycling streams without sacrificing oxygen transmission rates below 1 cc/m²/day.
Growth Catalysts
- REACH-compliant additive portfolios:ECHA substance restrictions on phthalates and heavy metal catalysts are accelerating certified alternative adoption among European compounders serving fresh meat processors.
- Vacuum skin line automation:Robotic loading and vision-guided sealing systems are reducing labor content per pack and enabling 24-hour continuous operation at protein processing facilities.
- Retail shrink reduction mandates:North American supermarket chains are specifying extended-shelf-life packaging formats that cut discard rates for case-ready beef and pork.
Market Restraints
- Ethylene-vinyl alcohol resin concentration:Korean and Japanese suppliers control over 70% of high-barrier EVOH supply for coextruded films, creating geographic single-source vulnerability.
- Mono-material technical ceiling:Current polyethylene formulations cannot achieve sub-0.5 cc/m²/day oxygen transmission without nylon or EVOH layers, constraining premium protein applications.
- Extended producer responsibility fee structures:Germany's VerpackG and France's Citeo modulated fees penalize non-recyclable multi-material constructions with cost multiples versus certified mono-material alternatives.
Strategic Opportunities
- India cold chain buildout:FSSAI-mandated hygienic packaging for chilled poultry and seafood is creating first-mover advantage for barrier film suppliers establishing local slitting and distribution.
- Bio-based barrier coatings:Cellulose nanofibril and chitosan surface treatments are enabling paper-backed skin packs that bypass plastic taxation regimes in multiple European markets.
- Direct-to-consumer protein subscription channels:E-commerce fulfillment requirements for 7-10 day ambient transit resilience are specification-driving higher barrier grades than traditional retail.
Industry Challenges
- Migration testing laboratory capacity:EU 10/2011 overall migration and specific migration testing for new mono-material formulations faces 12-16 week queue times at accredited facilities.
- Thermoformer-to-film calibration complexity:Matching vacuum draw ratios and seal initiation temperatures across equipment generations requires application engineering resources that mid-tier processors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Packaging Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Rigid Films, Trays, Lidding Films Material: Polyethylene, Polyvinyl Chloride, Polypropylene, Others End User: Food, Pharmaceuticals, Electronics, Consumer Goods Application: Meat Packaging, Dairy Products, Fresh Produce, Non-Food Items |
| Companies Covered | Amcor plc, Sealed Air Corporation, Berry Global Group, MULTIVAC Sepp Haggenmüller, Klöckner Pentaplast, PROAMPAC, WestRock Company, Flexopack S.A., Plastopil Hazorea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Packaging Market Strategic Shifts & Innovations
Barrier film architecture is undergoing forced simplification as mechanical recycling targets override historical multi-layer performance optimization, while digital printing integration is collapsing minimum order quantities and lead times for private-label meat programs.
Polypropylene random copolymer formulations with nucleating agents for enhanced clarity are expanding into premium fresh produce and smoked salmon applications where retail presentation commands price premiums. German and Dutch salad processors are specifying these grades for 12-day shelf-life targets. The technology is expanding into protein segments previously dominated by polyethylene, compressing material differentiation strategies among compounders.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances in food contact materials are eliminating grease-resistant fluoropolymer coatings from paper-based skin pack backers. Paperboard suppliers are substituting plant-based wax and clay barrier treatments that require recalibration of heat-seal windows. Fresh poultry packed on modified paper backers in France and Belgium is experiencing the most acute reformulation pressure.
Brand owners are consolidating film specifications across pan-European manufacturing footprints to simplify recycler sorting and reduce EPR fee exposure. This behavior compresses the viable supplier base to compounders with multi-site REACH-compliant production and pan-European logistics networks. The shift is most visible in private-label retail meat programs sourced from centralized European processors.
Skin Packaging Market Segmentation
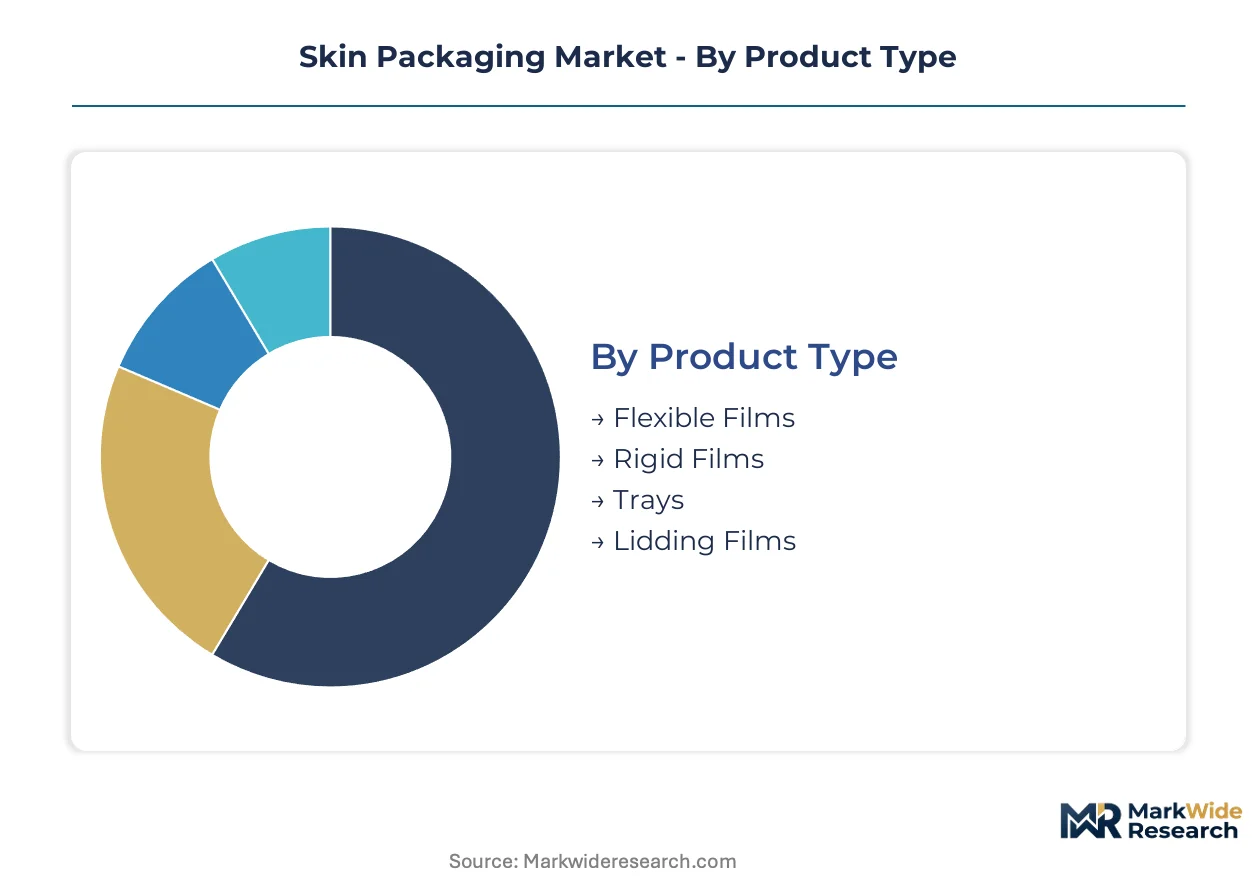
Skin packaging segmentation reveals distinct procurement patterns across protein processors, produce distributors, and pharmaceutical manufacturers. Material selection and product format choices directly determine barrier performance, recyclability compliance, and line speed economics.
Product Type:
Buyers differentiate primarily by automation compatibility and source-reduction targets rather than upfront capital cost.
- Flexible Films:Vacuum-drawn polyethylene and polypropylene webs conform to irregular meat cuts and enable 15-20% material reduction versus rigid alternatives. Fresh beef and pork processors across Germany and the Netherlands specify these grades for automated skin lines running at 80-120 packs per minute.
- Trays:Thermoformed polypropylene and crystallized PET structures provide dimensional stability for moist protein applications. North American supermarket chains mandate tray-based formats for case-ready poultry programs requiring retail display rigidity and leak resistance.
- Rigid Films:Pre-formed barrier webs serve premium smoked salmon and artisan cheese segments where presentation flatness commands price premiums.
- Lidding Films:Peelable sealant layers enable consumer-friendly opening while maintaining oxygen barrier below 1 cc/m²/day for modified atmosphere applications.
Flexible films lead volumes today; trays are gaining share fastest as retail-ready format standardization accelerates.
Material:
Compound selection hinges on recyclability certification thresholds and seal initiation temperature windows across thermoformer generations.
- Polyethylene:Linear low-density and metallocene grades dominate fresh meat applications due to cost position and broad thermoformer compatibility. EPR fee advantages under Germany's VerpackG are accelerating mono-material PE adoption for private-label retail programs.
- Polypropylene:Random copolymer formulations with nucleating agents deliver enhanced clarity for premium produce and smoked salmon. Dutch salad processors specify these grades for 12-day shelf-life targets where retail presentation drives margin capture.
- Polyvinyl Chloride:Declining share in food contact as REACH Annex XVII restrictions and retailer bans constrain fresh protein applications.
- Others:Bio-based PLA and cellulose-derived films serve niche organic and plastic-tax-exempt segments in France and Belgium.
Polyethylene maintains volume leadership; polypropylene exhibits the steepest expansion trajectory as clarity requirements penetrate protein segments.
End User:
Regulatory exposure and shelf-life extension requirements create divergent specification intensities across verticals.
- Food:Fresh meat, poultry, and seafood processors drive absolute demand, with vacuum skin lines expanding across North American protein facilities to reduce retail shrink. FDA food contact substance notifications and EU 10/2011 migration limits govern film formulation choices.
- Pharmaceuticals:Medical device and diagnostic kit manufacturers specify high-barrier formats with tamper evidence and sterile presentation. ISO 11607 compliance requirements elevate testing documentation burdens versus food applications.
- Electronics:Static-dissipative films protect circuit boards and precision components during distribution, with JIS standards in Japan and GB standards in China defining performance thresholds.
- Consumer Goods:Hardware and houseware applications prioritize cost minimization over barrier performance, utilizing thinner gauge films with reduced oxygen protection.
Food commands absolute volumes; pharmaceuticals demonstrate the highest specification premiums per square meter.
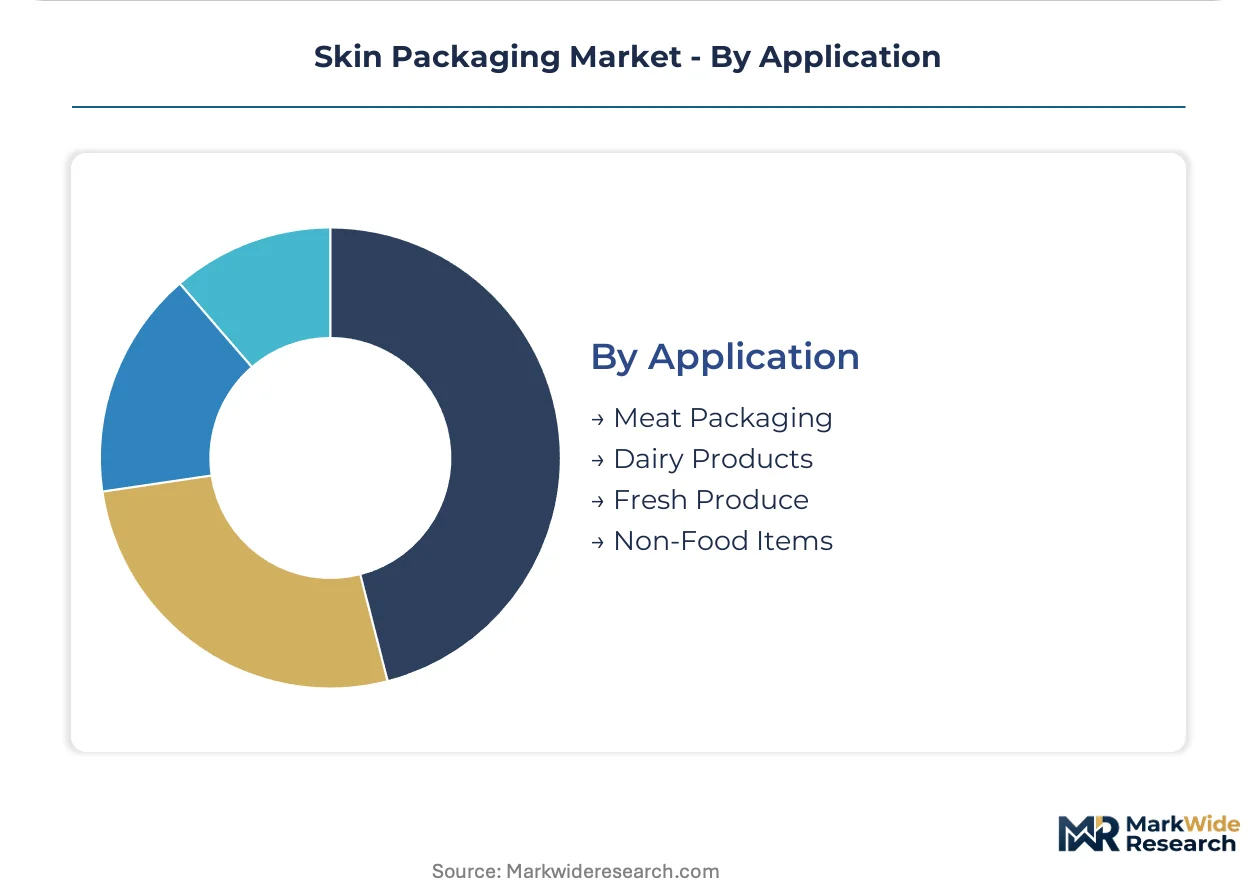
Application:
Oxygen transmission targets and moisture resistance requirements stratify material and format selection across product categories.
- Meat Packaging:Fresh beef, pork, and lamb applications demand sub-1 cc/m²/day oxygen transmission to achieve 21-28 day retail shelf life. EVOH and nylon coextrusion layers remain prevalent despite mono-material recycling pressures.
- Fresh Produce:Modified atmosphere requirements for berries and leafy greens favor perforated films and breathable structures that balance moisture retention with ethylene escape.
- Dairy Products:Cheese and butter applications utilize medium-barrier polyethylene with anti-fog additives to maintain retail clarity under refrigerated display conditions.
- Non-Food Items:Industrial components and consumer hardware utilize uncoated polyethylene with minimal barrier specifications, prioritizing cost and processability.
Meat packaging anchors current volumes; fresh produce applications are climbing fastest as premium berry and salad segments expand refrigerated distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vacuum skin packaging technology originated in post-war Germany, where MULTIVAC Sepp Haggenmüller pioneered automated thermoforming systems for protein processors. German engineering standards subsequently diffused across European meatpacking clusters and transplanted to North American protein facilities during the 1990s consolidation wave.
Germany
Fresh meat processors in Lower Saxony and Bavaria operate the densest concentration of automated skin packaging lines outside North America. The country's VerpackG extended producer responsibility framework imposes steep fee multiples on non-recyclable multi-material constructions, accelerating migration toward mono-material polyethylene formulations. MULTIVAC anchors production in Wolfertschwenden, supplying thermoforming systems to processors across the EU.
United States
Supermarket chains operating case-ready beef and pork programs mandate extended-shelf-life formats to cut retail shrink below 3%. FDA food contact substance notifications govern film additive approvals, while USDA inspection protocols influence line sanitation specifications. Nebraska and Iowa protein processing corridors host the fastest vacuum skin line installation rates.
Netherlands
Dutch salad processors specify polypropylene random copolymer grades with nucleating agents for 12-day shelf-life targets in premium retail segments. ECHA REACH Annex XVII restrictions on per- and polyfluoroalkyl substances eliminate fluoropolymer coatings from paper backers, forcing recalibration of heat-seal windows. Wageningen food technology clusters drive barrier film application research.
China
GB standards impose migration limits and testing protocols on imported packaging materials for chilled poultry and seafood distribution. Yangtze River Delta cold chain infrastructure expansion creates specification pull for barrier films with 7-10 day ambient transit resilience. Shanghai and Jiangsu province processors trial domestic film slitting operations to bypass import lead times.
India
FSSAI-mandated hygienic packaging for chilled poultry and seafood drives first-mover investment from barrier film suppliers establishing local distribution. BIS standards constrain additive chemistries for food contact applications. Maharashtra and Gujarat protein processing hubs represent the primary demand concentration as modern retail formats expand refrigerated distribution.
Skin Packaging Market Key Industry Players
The competitive structure tilts toward integrated film-to-equipment systems specialists with pan-regional regulatory compliance capabilities. Three to five compounders control high-volume polyethylene supply for fresh meat applications, while thermoformer manufacturers anchor automated line production in Germany and the United States. Strategic moves concentrate on backward integration into resin sourcing and geographic licensing of barrier coating technologies.
Within the integrated multinational tier, Amcor plc and Sealed Air Corporation exemplify archetypes with global resin sourcing networks and multi-region production footprints. MULTIVAC Sepp Haggenmüller occupies a position as the equipment-specialist anchor, representing the German engineering lineage that standardized vacuum skin system architectures. These three entities sit within distinct competitive vectors—film supply, barrier technology, and automation systems—rather than direct overlap.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Berry Global Group |
| MULTIVAC Sepp Haggenmüller |
| Klöckner Pentaplast |
| PROAMPAC |
| WestRock Company |
| Flexopack S.A. |
| Plastopil Hazorea |
| Others |
Cost & Logistics Intelligence
EU Packaging and Packaging Waste Regulation recyclability mandates gate qualified supply for skin packaging films, reserving premium-tier pricing access for compounders with certified mono-material formulations and pan-European logistics networks. Buyers without REACH-compliant certification face EPR fee multiples that compress margins and exclude them from private-label retail meat programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier performance and recyclability certification. Premium tiers command position through sub-0.5 cc/m²/day oxygen transmission rates with EVOH coextrusion, while standard grades rely on mono-material polyethylene meeting VerpackG requirements. Cost compression in economy tiers is intensifying because resin volatility and EPR fee differentials squeeze non-certified suppliers. Small protein processors exhibit highest price sensitivity, whereas multinational retailers prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and the United States anchor hub-and-spoke patterns for film inventory positioning. Manufacturing concentrates in Germany, the United States, and China, with Korean and Japanese suppliers controlling over 70% of high-barrier EVOH resin. Raw material flows draw from ethylene feedstock clusters, metallocene catalyst supply, and nucleating agent specialists. Single-source vulnerability in EVOH creates structural risk for premium barrier grades. Distribution runs through thermoformer-integrated slitting operations serving protein processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skin packaging offers margin-expansion pathways as mono-material formulation standardization reduces compounder R&D overhead and EPR fee optimization shifts buyer preference toward certified suppliers.
For Market Incumbents: Lock in barrier coating technology licensing across European thermoformer networks before REACH Annex XVII restrictions harden. Backward integration into metallocene polyethylene resin sourcing defends margin position against Korean EVOH supply volatility. Secure pan-European logistics nodes to capture private-label retail consolidation specifying centralized film procurement. For New Entrants and Emerging Players: Direct-to-consumer protein subscription channels represent the most penetrable entry vector, as e-commerce fulfillment requirements for 7-10 day ambient transit resilience drive specification gaps incumbent compounders underweight. Target Indian cold chain buildout with FSSAI-compliant slitting operations in Maharashtra and Gujarat. Lead with bio-based barrier coating partnerships to bypass plastic taxation regimes in France and Belgium. For Investors and Strategic Acquirers: Roll-up economics work for regional film slitters with thermoformer calibration expertise because equipment-to-material matching complexity fragments the mid-tier supplier base. Five-to-ten year viability hinges on EPR fee structure permanence and mechanical recycling infrastructure buildout. Watch Germany's VerpackG fee modulation announcements as the inflection signal for mono-material adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Captive polyethylene supply secures margin against Korean EVOH concentration and feedstock volatility. |
| REACH-Compliant Additive Portfolio Certification | ECHA substance restriction alignment unlocks European private-label retail meat program access. |
| Pan-European Logistics Network Expansion | Multi-site distribution reduces EPR fee exposure and recycler sorting complexity for brand owners. |
| Bio-Based Barrier Coating Development | Cellulose nanofibril surface treatments bypass plastic taxation in France and Belgium organic segments. |
| Thermoformer Equipment Partnership | Calibration-integrated film supply locks in processor switching costs across automated skin lines. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with film compounder technical directors, protein processor procurement leads, thermoformer application engineers, and EPR compliance officers with secondary validation. Sources included EU Packaging and Packaging Waste Regulation filings, ECHA REACH substance restriction updates, FDA food contact substance notifications, BIS and GB standards documentation, and customs trade data for resin and film flows. Bottom-up volume modeling and top-down market sizing triangulated segment-level outputs.
Historical reference periods anchored the projection horizon to observed automation adoption curves and regulatory implementation timelines. Segmentation modeling spanned material chemistry, product format flexibility, end-use vertical intensity, and application oxygen transmission requirements. CAGRs derived from fitted growth curves applied to installed thermoformer base expansion and shelf-life extension specification penetration. Forecast inputs incorporated EPR fee structure evolution and cold chain infrastructure investment trajectories.
Regulatory enforcement variance, resin supply disruption events, and mechanical recycling infrastructure deployment delays are the dominant revision risks for trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Postal Packaging Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
New Packages and Materials for Power Devices Market
Packaging Materials
PET Packaging Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
Bulb Packaging Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Kraft Packaging Market
Packaging Materials
Packaging Lacquering Market
Packaging Materials
Packaging Inserts Market
Packaging Materials
Cavitated Films Market