
 Cold Seal Films Market | 2026-2036
Cold Seal Films Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Seal Films Market Outlook
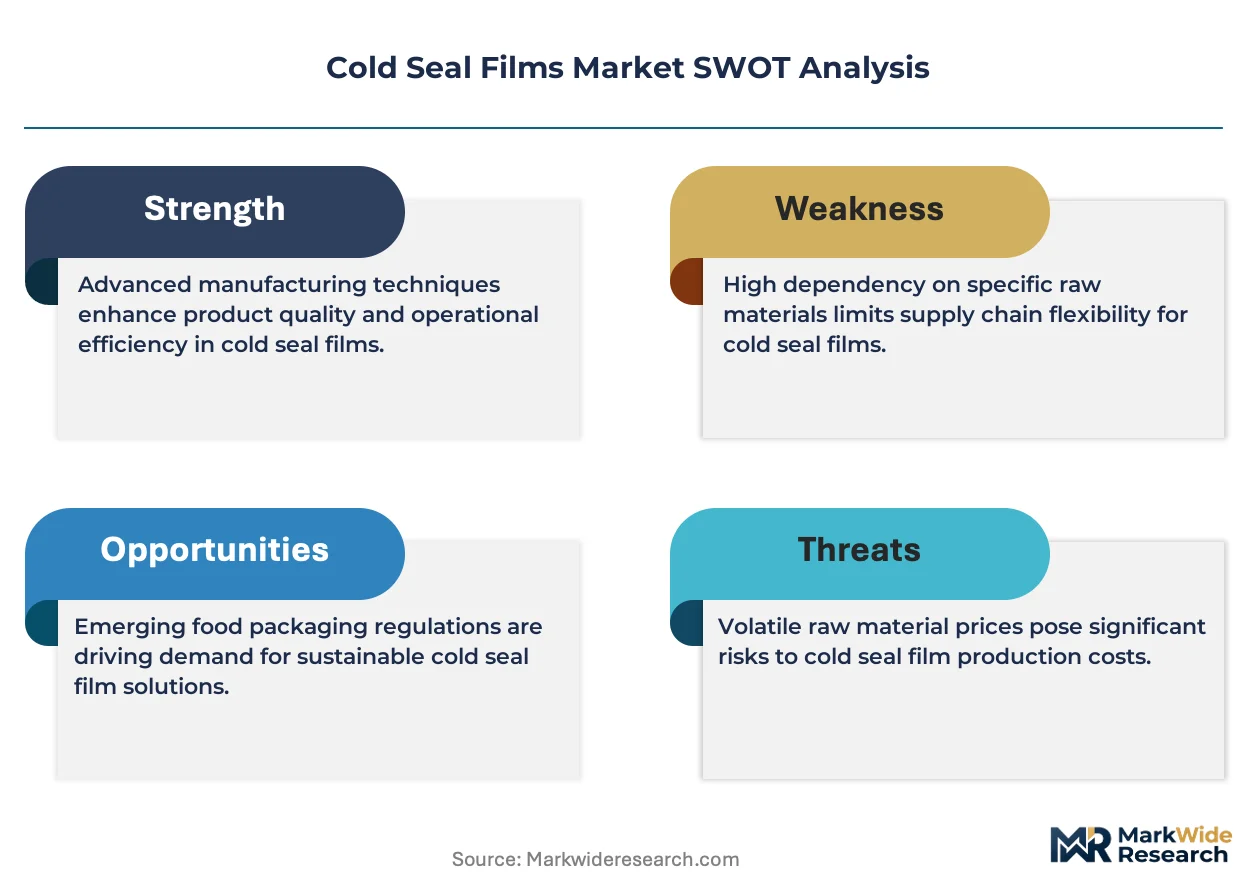
The EU Packaging and Packaging Waste Regulation is decoupling cold seal film demand from traditional multi-layer laminates across European food manufacturing. Amcor Plc leverages its global R&D network to develop recyclable mono-material cold seal solutions for chocolate and bakery segments. Mondi Group anchors its position through integrated kraft paper and film operations that reduce reliance on external substrate suppliers. Berry Global competes on manufacturing scale, operating multiple extrusion lines capable of switching between polypropylene and polyester cold seal grades.
Cold seal films are pressure-sensitive packaging substrates coated with natural rubber latex or synthetic elastomer formulations that bond to themselves without applied heat, typically achieving seal strengths of 300–800 g/25mm at 20–40 psi contact pressure for confectionery and medical pouch applications. Polypropylene cold seal films dominate volume due to their moisture barrier and compatibility with high-speed horizontal form-fill-seal equipment, while polyester grades command premium positioning in medical equipment packaging where clarity and sterilization compatibility matter. Water-based formulations are displacing solvent-based systems as REACH compliance costs and VOC emission thresholds tighten across EU manufacturing zones.
EMA food contact material regulations, REACH substance restrictions, and EU Green Deal packaging recyclability mandates collectively shape formulation choices and substrate specifications for suppliers seeking European market access. FDA food additive regulations and USDA bio-based procurement preferences influence parallel product development tracks for North American customers. Stakeholders must monitor pending revisions to extended producer responsibility schemes and decide whether to prioritize regional certification depth or pursue harmonized global product platforms.
Market Dynamics
Mono-material recyclable cold seal film development is restructuring supplier R&D priorities as EU Green Deal mandates phase out multi-layer laminates that dominate legacy confectionery packaging lines.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates for recyclable packaging structures are pulling food manufacturers toward cold-seal-compatible mono-material substrates that eliminate heat-sealing equipment requirements.
- Natural rubber latex coating chemistry:Advances in water-based elastomer formulations are reducing VOC emissions and enabling compliance with REACH substance restrictions across European manufacturing zones.
- German confectionery cluster:Retrofitting of horizontal form-fill-seal lines for cold-seal compatibility in the Rhine-Ruhr region is concentrating equipment investment and technical expertise.
Market Restraints
- Natural rubber supply concentration:Southeast Asian latex sourcing exposes coating formulators to climate-driven harvest volatility and geopolitical trade friction.
- Seal strength performance ceiling:Cold seal bonds achieve 300–800 g/25mm versus heat-seal alternatives, limiting penetration into retort and aseptic applications requiring hermetic integrity.
- REACH compliance cost escalation:Registration requirements for novel synthetic elastomers are extending development timelines and freezing formulation pipelines for mid-tier suppliers.
Strategic Opportunities
- Medical device packaging expansion:Polyester cold seal grades with sterilization compatibility are capturing share in ethylene oxide and gamma-irradiation pouch applications.
- Extended producer responsibility schemes:Pending revisions to EU EPR frameworks will reward mono-material structures with lower eco-modulation fees, tilting procurement calculus.
- Direct-to-brand technical sales:Bypassing traditional converter channels to embed cold-seal specification into OEM packaging engineering teams accelerates design-in cycles.
Industry Challenges
- Adhesive-coating technician scarcity:Formulation expertise in natural rubber latex rheology and synthetic elastomer compatibilization is concentrating at legacy suppliers, constraining new entrant scale-up.
- Line retrofit capex burden:Horizontal form-fill-seal equipment modifications for cold-seal pressure profiles require six-figure capital commitments that freeze pilot adoption timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Seal Films Market |
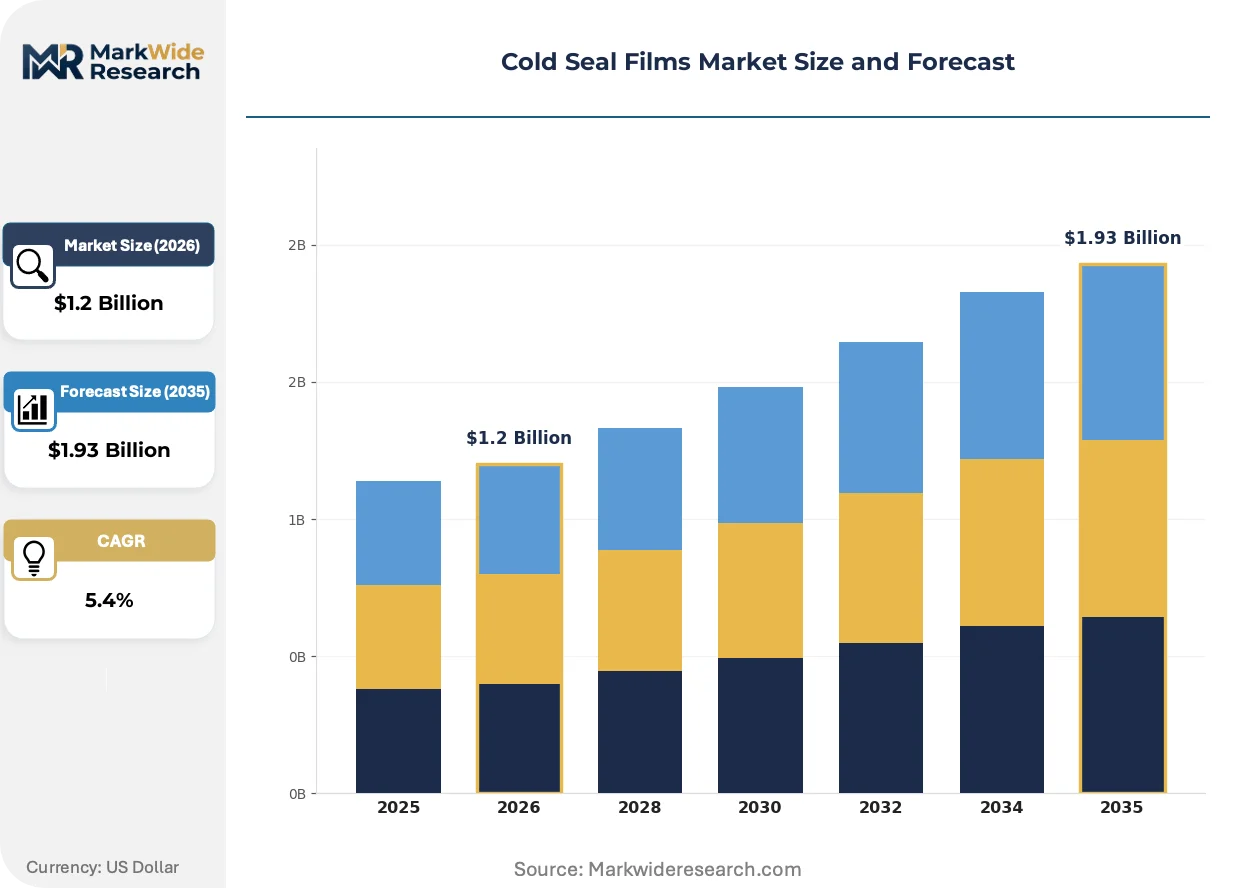
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $1.93 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyester, Cellophane, Others End User: Food Packaging, Medical Equipment, Consumer Goods, Electronics Formulation: Water-based, Solvent-based, Hot Melt, Others Technology: Co-extrusion, Laminating, Recycling, Others |
| Companies Covered | Amcor Plc, Bemis Company, Sealed Air Corporation, Berry Global, Mondi Group, Constantia Flexibles, Uflex Ltd., Toray Plastics, Clondalkin Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Seal Films Market Strategic Shifts
Water-based coating technology is compressing solvent-based system viability as regulatory emission thresholds tighten and brand sustainability commitments harden into procurement specifications.
Water-based natural rubber latex formulations are electrifying cold seal film production by eliminating solvent recovery infrastructure and reducing workplace exposure compliance costs. Confectionery and snack producers in Germany and the Netherlands are adopting these systems at accelerated pace to meet EU Green Deal packaging recyclability targets. The technology is electrifying competitive repositioning among coating suppliers as REACH registration advantages compound with carbon footprint reduction claims.
REACH substance restrictions and EU Green Deal packaging recyclability mandates are forcing multi-layer laminate obsolescence across European food contact applications. Industrial consequence includes accelerated R&D redirection toward mono-material polypropylene and polyester substrates that maintain barrier performance without adhesive interlayers. Medical equipment packaging segments are responding fastest, with ethylene oxide sterilization-compatible polyester grades capturing specification share from legacy nylon-containing structures.
Brand technical teams are embedding cold-seal specification into upstream packaging design phases rather than deferring to converter material recommendations. This procurement model compression is disrupting traditional distributor-led channel structures and favoring direct supplier-engineering relationships. The shift is most visible in German chocolate and bakery segments where Mondelēz and Bahlsen technical packaging groups specify substrate and coating chemistry directly with film producers.
Cold Seal Films Market Segmentation
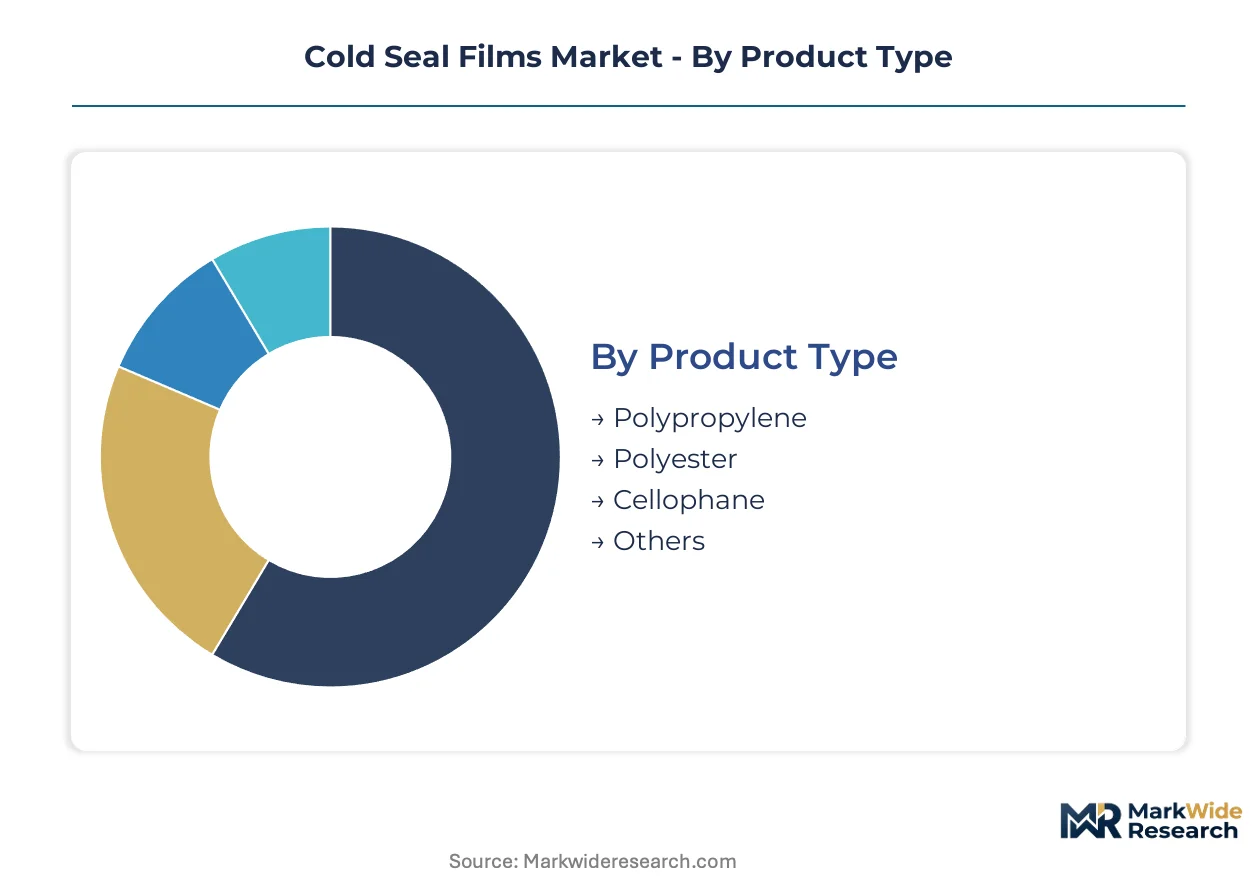
Cold seal film procurement decisions pivot on heat-seal equipment avoidance, recyclability compliance, and line speed compatibility. Substrate chemistry and coating formulation choices cascade through total cost of ownership calculations for confectionery and medical packaging engineers.
Product Type:
Barrier performance and equipment compatibility drive substrate selection across end-use applications.
- Polypropylene:Biaxially oriented polypropylene films deliver moisture barrier properties at 20-40 micron gauges compatible with high-speed horizontal form-fill-seal lines. German chocolate producers in the Rhine-Ruhr cluster specify OPP cold seal grades to eliminate heat-seal jaw maintenance and reduce energy consumption per pack.
- Polyester:PET films provide optical clarity and dimensional stability under gamma irradiation or ethylene oxide sterilization cycles. Medical device manufacturers in Switzerland and the Netherlands specify polyester cold seal structures for surgical kit pouches where hermetic integrity and sterilization compatibility are non-negotiable.
- Cellophane:Regenerated cellulose films offer biodegradable positioning for premium confectionery wraps where brand sustainability claims justify material cost premiums.
- Others:Nylon and polylactic acid substrates serve niche applications requiring puncture resistance or compostable certification.
Polypropylene leads on scale; polyester leads on momentum.
End User:
Application-specific regulatory exposure and line retrofit economics concentrate demand in food and medical verticals.
- Food Packaging:Confectionery, bakery, and snack producers leverage cold seal films to extend shelf life without capital-intensive heat-sealing infrastructure. Mondelēz and Bahlsen technical teams in Germany specify mono-material OPP structures to meet EU Green Deal recyclability mandates while maintaining 300-600 packs per minute line speeds.
- Medical Equipment:Sterilization pouch manufacturers specify polyester cold seal grades compatible with ethylene oxide and gamma irradiation protocols. Swiss and Dutch medical packaging converters prioritize seal strength consistency and particulate-free peel characteristics for surgical instrument kits.
- Consumer Goods:Personal care and household product brands adopt cold seal films for sampler sachets and promotional packs where heat-seal equipment minimization reduces contract packaging costs.
- Electronics:Static-dissipative cold seal films protect sensitive components during shipment, though penetration remains limited by moisture barrier requirements versus metallized alternatives.
Food packaging dominates volume concentration; medical equipment commands specification premium.
Formulation:
REACH compliance cost trajectories and VOC emission thresholds are decoupling coating chemistry selection from legacy solvent-based systems.
- Water-based:Natural rubber latex emulsions eliminate solvent recovery infrastructure and reduce workplace exposure compliance costs. German and Dutch confectionery producers accelerate adoption to satisfy EU Green Deal packaging recyclability targets and ECHA substance restriction protocols.
- Solvent-based:Synthetic elastomer solutions in hydrocarbon carriers retain niche positioning for ultra-high-speed lines where water-based systems exhibit insufficient green tack development.
- Hot Melt:Thermoplastic block copolymer formulations enable solvent-free coating with rapid setting characteristics for temperature-sensitive substrates.
- Others:UV-curable and moisture-cure systems serve specialty medical applications requiring instantaneous bond formation.
Water-based formulations gain share fastest; solvent-based systems defend legacy line positions.
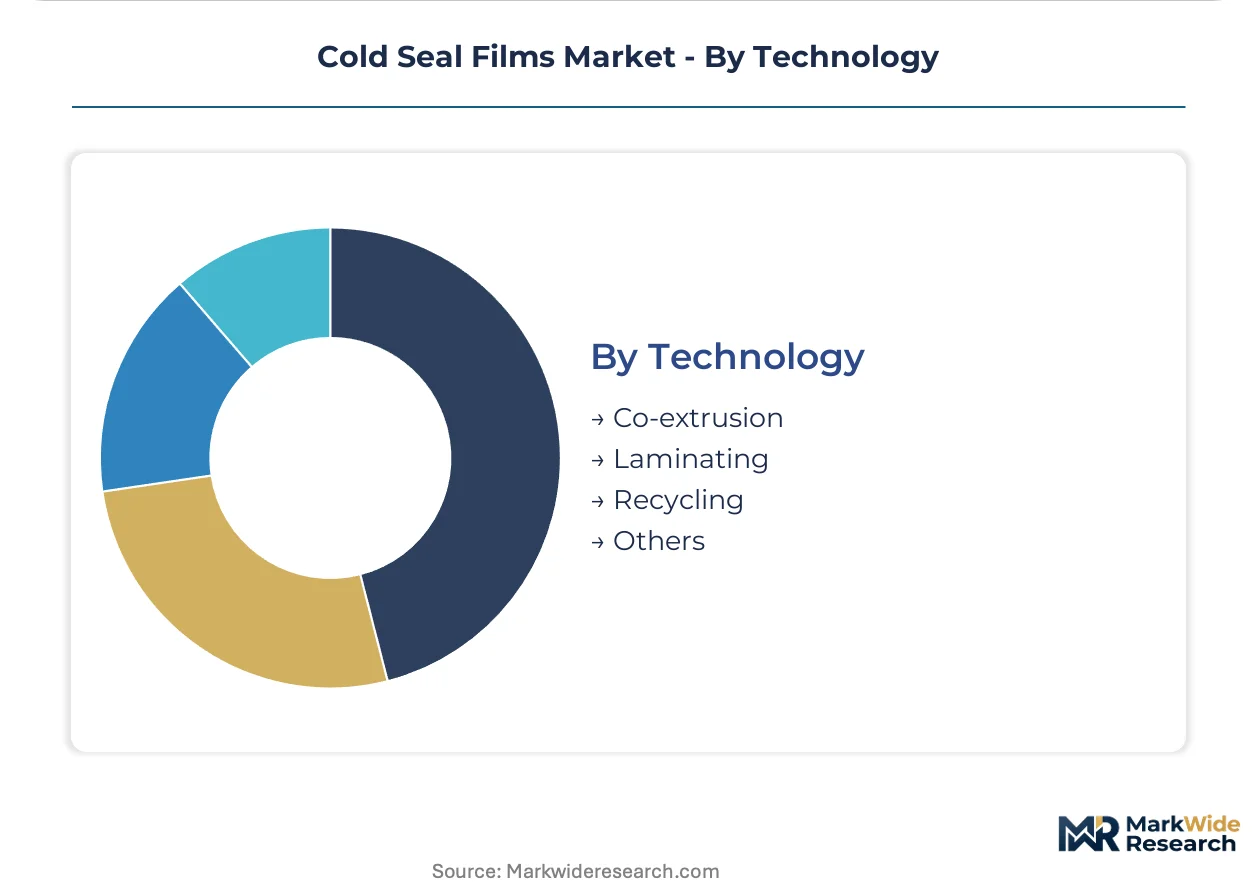
Technology:
Manufacturing process selection determines mono-material recyclability achievement and coating uniformity at production scale.
- Co-extrusion:Multi-layer cast film lines integrate sealant layers directly into substrate structure, eliminating separate coating steps. Integrated producers in Germany leverage co-extrusion to produce mono-material recyclable cold seal films that satisfy EPR eco-modulation fee reductions.
- Laminating:Adhesive and extrusion lamination processes bond pre-coated films to barrier substrates, though multi-layer constructions face obsolescence pressure under EU Packaging and Packaging Waste Regulation recyclability mandates.
- Recycling:Post-industrial scrap reprocessing technologies close material loops for polypropylene cold seal film production, supporting circular economy claims in brand sustainability reporting.
- Others:Plasma treatment and corona discharge surface activation enhance coating adhesion on low-energy substrates.
Co-extrusion anchors capacity investment; recycling technology climbs fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized adhesive-coating technicians cluster in Germany's Rhine-Ruhr industrial corridor and Switzerland's pharmaceutical packaging belt. Their expertise anchors European cold seal film specification and line retrofit execution.
Germany
Mondelēz and Bahlsen technical packaging teams specify mono-material OPP cold seal structures directly with film producers. ECHA REACH substance restrictions accelerate water-based natural rubber latex adoption. The Rhine-Ruhr cluster concentrates horizontal form-fill-seal line retrofits for confectionery applications.
Switzerland
Medical device manufacturers drive polyester cold seal demand for surgical kit sterilization pouches. Swissmedic medical device regulations enforce particulate-free peel characteristics. Basel-Zurich corridor packaging converters prioritize ethylene oxide and gamma irradiation-compatible grades.
Netherlands
Snack producers retrofit legacy lines to eliminate heat-seal jaw maintenance and energy consumption. EU Green Deal packaging recyclability mandates shape procurement specifications. Rotterdam-Antwerp logistics hub facilitates just-in-time delivery of coated film substrates.
United States
FDA food additive regulations and USDA bio-based procurement preferences influence parallel product development tracks. Confectionery brands in Chicago and Philadelphia metro areas pilot cold-seal compatibility for seasonal packaging campaigns. Midwest contract packagers evaluate pressure-sensitive systems to reduce equipment capital burdens.
Japan
Premium confectionery exporters adopt cold seal films for moisture-sensitive chocolate products destined for Southeast Asian markets. METI circular economy guidelines encourage mono-material substrate development. Kansai region packaging engineers collaborate with film suppliers on ultra-high-speed line integration.
Cold Seal Films Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the cold seal film value chain. Integrated film-coating operations command supply security advantages while specialized converters retain formulation flexibility. Three archetypes dominate: integrated multinational packaging conglomerates with captive polymer supply, regional film specialists with coating partnerships, and equipment-integrated solution providers bundling substrate and machinery. Capacity expansion and direct-to-brand technical sales represent the dominant competitive vectors reshaping channel structures.
Within the integrated multinational tier, Amcor Plc and Berry Global occupy positions defined by global extrusion network scale and multi-substrate switching capability. Mondi Group anchors the European specialist vector through kraft paper and film integration. These three exemplify divergent strategic postures: Amcor leverages R&D network breadth, Berry competes on manufacturing scale flexibility, and Mondi reduces external substrate dependence through backward integration into pulp and paper operations.
| Leading Market Players |
|---|
| Amcor Plc |
| Bemis Company |
| Sealed Air Corporation |
| Berry Global |
| Mondi Group |
| Constantia Flexibles |
| Uflex Ltd. |
| Toray Plastics |
| Clondalkin Group |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal packaging recyclability mandates gate qualified supply access and premium-tier pricing power, restricting mono-material cold seal film production to integrated coating operations with REACH-registered water-based formulations while commanding 15-25% price premiums over multi-layer laminate alternatives.
Pricing Analysis
Bundled technical specification services separate from unbundled commodity substrate supply. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and after-sales line integration support. Cost compression in standard grades is intensifying because Southeast Asian latex sourcing volatility feeds raw material uncertainty. Mid-tier converters exhibit highest price sensitivity; medical device manufacturers show lowest due to sterilization compliance non-negotiability.
Supply Chain Analysis
Natural rubber latex supply rests on Thai, Indonesian, and Vietnamese harvest cycles vulnerable to climate-driven yield fluctuations. Biaxially oriented polypropylene substrate production draws from German, Austrian, and Chinese extrusion networks. Single-source vulnerability concentrates in specialty synthetic elastomer feedstocks subject to ECHA substance restriction revisions. Distribution runs through converter-led channels in European food packaging, direct supplier-engineering relationships in German medical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with EU Packaging and Packaging Waste Regulation recyclability mandates converting compliance cost into specification premium capture.
For Market Incumbents: Cement specification control by embedding coating chemists directly into Mondelēz and Bahlsen technical packaging teams, eliminating converter intermediation. Prioritize backward integration into kraft paper pulp supply to reduce external substrate exposure. Defend against regional film specialists by accelerating water-based formulation patent filings ahead of REACH registration deadlines. For New Entrants and Emerging Players: Direct-to-brand digital specification platforms bypass legacy distributor channels and compress design-in cycles from 18 months to 6 months. Target Swiss medical device packaging converters underserved by incumbent technical sales coverage. Penetrate through sterilization compatibility certification investment rather than commodity substrate price competition. For Investors and Strategic Acquirers: Roll-up economics work for regional coating specialists with captive natural rubber latex formulation expertise because adhesive-coating technician scarcity concentrates bargaining power at legacy suppliers. Five-to-ten year viability hinges on mono-material recyclability technology transition completion. Watch EPR eco-modulation fee schedule revisions as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Coating Capacity Expansion | Eliminates solvent recovery infrastructure and satisfies ECHA VOC emission thresholds. |
| Direct-to-Brand Technical Sales Channel | Bypasses converter intermediation and accelerates specification into Mondelēz engineering teams. |
| Mono-Material Substrate Backward Integration | Captures EPR eco-modulation fee reductions through captive polypropylene extrusion supply. |
| Medical Sterilization Compatibility Certification | Unlocks Swiss and Dutch surgical kit pouch specifications with gamma irradiation validation. |
| Natural Rubber Latex Supply Partnership | Secures Thai and Indonesian harvest offtake against climate-driven volatility exposure. |
Study Parameters
Multiple input streams — primary interviews with coating formulators, horizontal form-fill-seal line engineers, and ECHA regulatory affairs specialists; secondary validation through EU Packaging and Packaging Waste Regulation impact assessments, REACH substance restriction databases, and trade customs data; plus bottom-up and top-down triangulation — were reconciled to produce segment-level estimates.
Data-stream reconciliation across substrate chemistry, coating formulation, end-use application, and regional regulatory cluster dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from equipment retrofit adoption curves and brand sustainability commitment timelines. Industry-specific forecast inputs incorporated natural rubber latex price volatility indices and EPR fee schedule proposal trajectories.
The model assumes a particular technology adoption path; alternative pathways for solvent-to-water-based coating conversion would alter the outlook. Forecasts reflect assumptions about REACH registration timeline adherence and EU Green Deal implementation pace. A small set of named triggers — EPR eco-modulation fee finalization, ECHA substance restriction list expansion, and Southeast Asian latex harvest disruption — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Trifold Packaging Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Myanmar Packaging Market
Packaging Materials
Vacuum Packaging Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Single Dose Detergent Packaging Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Mylar Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Cash Management Supplies Packaging Market
Packaging Materials
3D Printed Packaging Market
Packaging Materials
Disposable Icepacks Market
Packaging Materials
Finish Foils Market