
 Global Fresh Meat Packaging Market | 2026-2036
Global Fresh Meat Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fresh Meat Packaging Market Intelligence
Revenue from value-added packaging design and system integration is narrowing the margin gap with commodity film supply. Amcor plc leverages its extensive global manufacturing footprint to serve large multinational meat processors. Sealed Air differentiates through its portfolio of high-barrier films and automated packaging equipment. Mondi competes by offering a range of paper-based and flexible plastic solutions to meet diverse sustainability targets.
Fresh meat packaging encompasses systems and materials engineered to preserve product quality and extend shelf life. These solutions often involve multi-layer plastic films with specific oxygen and moisture barrier properties to inhibit microbial growth. Modified Atmosphere Packaging (MAP) and vacuum packaging formats constitute the largest segments by type, offering superior product protection. While conventional plastic films dominate material usage, biodegradable polymers represent the fastest-growing material segment due to sustainability mandates.
Regulatory frameworks from bodies like the US FDA and the European Food Safety Authority (EFSA) dictate permissible food-contact materials. In China, GB standards enforced by the SAMR set stringent requirements for packaging safety and labeling. Navigating these varied international standards is critical for market access and compliance. Stakeholders must now focus on balancing the high-performance requirements of meat preservation with the increasing cost and regulatory pressure for sustainable material sourcing.
Market Dynamics
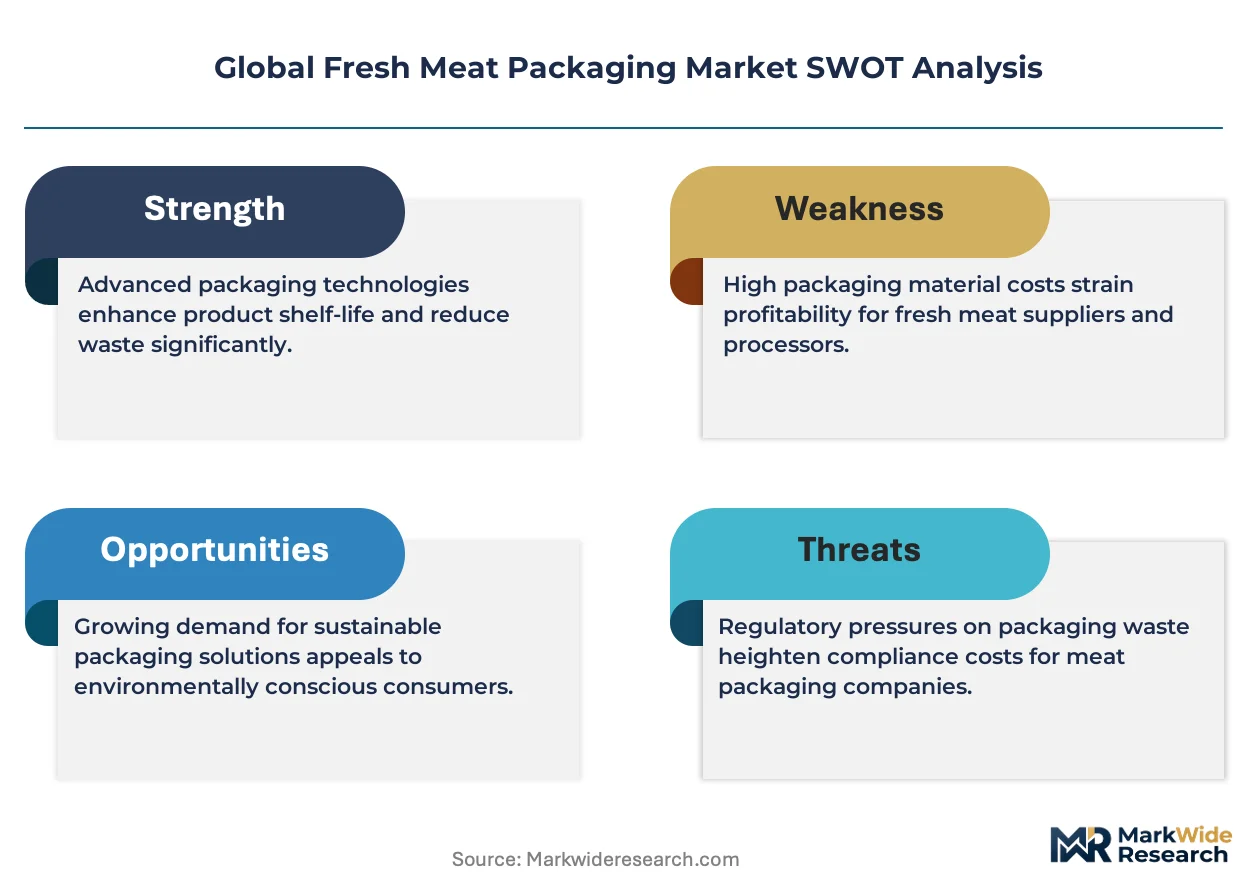
The central tension in the fresh meat packaging market is the simultaneous demand for extended shelf life, which traditionally requires complex multi-layer plastics, and the regulatory push for simplified, recyclable, and biodegradable materials to meet sustainability goals.
Growth Catalysts
- Retail Demand for Efficiency:Supermarket and hypermarket chains are increasingly demanding case-ready packaging formats from meat processors, which reduces in-store labor costs, improves merchandising consistency, and drives adoption of high-performance films and trays.
- Infrastructure Modernization:The rapid development of cold chain logistics and modern retail infrastructure in countries like China enables the distribution and sale of pre-packaged fresh meat, shifting consumption from traditional wet markets to supermarkets.
- Advanced Polymer Development:The creation of high-performance biodegradable polymers and mono-material films that meet food safety regulations provides a viable alternative to conventional plastics, aligning with stricter environmental mandates from governments and consumers.
Market Restraints
- Input Cost Volatility:The market is sensitive to fluctuations in the price of petrochemical-based resins, such as polyethylene and polypropylene, which are primary raw materials and subject to global oil price volatility, impacting manufacturer margins.
- Technical Performance Gaps:Certain biodegradable and plant-based polymers do not yet match the barrier performance and durability of conventional multi-layer plastics, limiting their use for sensitive products like high-fat red meats requiring long shelf lives.
- Regulatory Fragmentation:Navigating the divergent and complex food-contact material regulations set by bodies like the US FDA, the European Food Safety Authority (EFSA), and China's SAMR creates significant compliance costs and delays for global suppliers.
Strategic Opportunities
- Intelligent Packaging Integration:Incorporating sensors, time-temperature indicators, or freshness indicators into packaging systems offers a significant value-add by providing real-time quality assurance, reducing food waste, and enhancing consumer confidence and brand trust.
- Mono-Material Film Commercialization:Developing and scaling production of recyclable-by-design mono-material films that retain high-barrier properties presents a major opportunity to capture share from suppliers of less sustainable multi-layer laminates, especially in Europe.
- Geographic Expansion:Underpenetrated markets in Southeast Asia and Latin America offer substantial growth potential as rising incomes, urbanization, and the expansion of organized retail drive a shift towards packaged fresh meat consumption.
Industry Challenges
- High Capital Investment:Implementing advanced packaging formats like Modified Atmosphere Packaging (MAP) or vacuum skin packaging requires significant capital expenditure on specialized, automated equipment, creating a barrier to entry for smaller meat processors.
- Compliance and Certification Timelines:Securing food-contact safety approvals for novel materials from regulatory agencies is a lengthy and expensive process, slowing the pace of innovation and market introduction for new sustainable packaging solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fresh Meat Packaging Market |
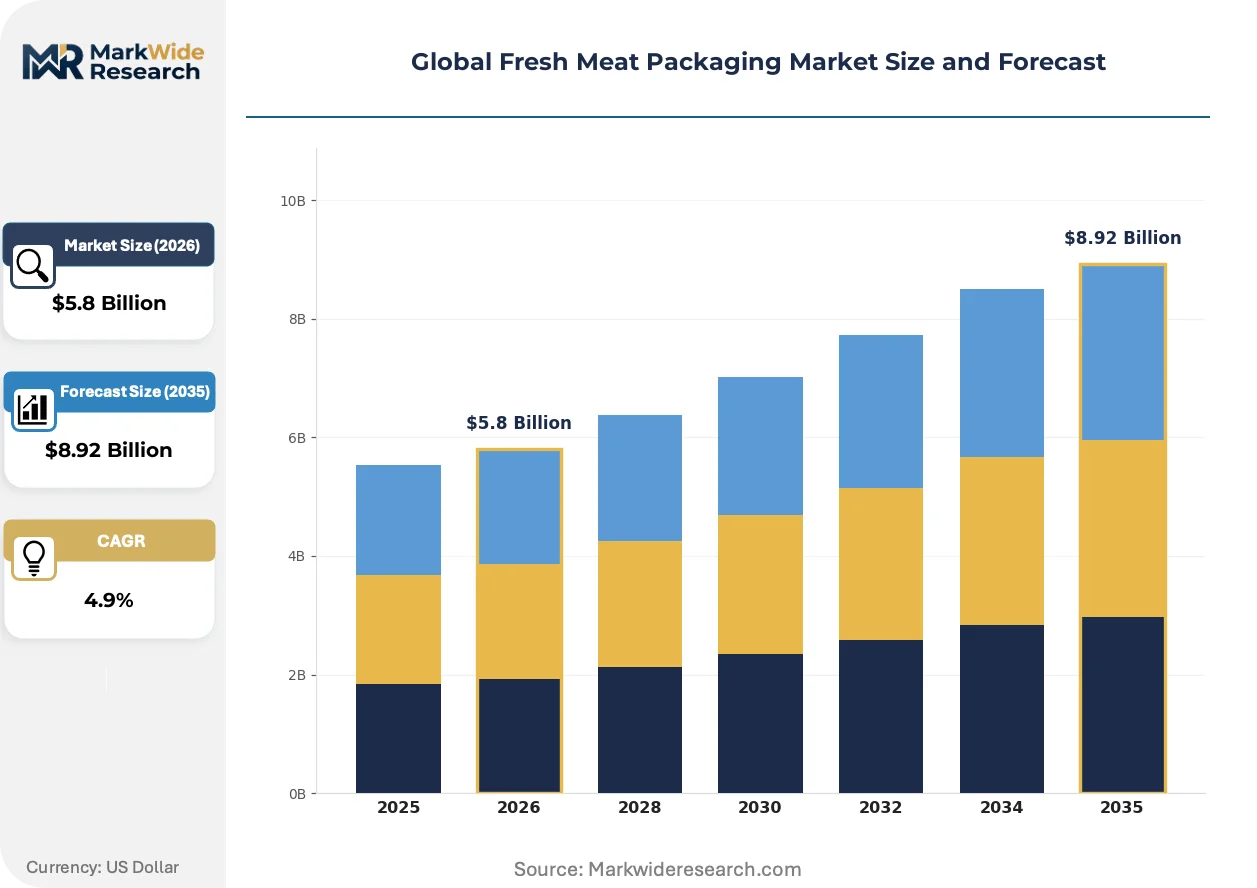
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.92 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Modified Atmosphere Packaging, Vacuum Packaging, Skin Packaging, Tray Sealing, Clamshell Packaging, Shrink Wrap Material Type: Plastic Films, Paperboard, Aluminum Foil, Biodegradable Polymers, Multi-layer Laminates, Corrugated Fiberboard Application: Retail Chains, Food Service Providers, Meat Processing Units, Specialty Butchers, Institutional Catering End User: Supermarkets, Restaurants, Hospitality Sector, Food Distributors, Meat Exporters |
| Companies Covered | Amcor plc, Berry Global Inc, Sealed Air, Mondi, Sonoco Products Company, Winpak Ltd, Coveris, Crown Holdings, Bolloré Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fresh Meat Packaging Market Strategic Shifts & Innovations
Material science and automation are converging to solve the dual challenge of extending product shelf life while meeting aggressive sustainability and circular economy targets, fundamentally altering packaging design and supply chain relationships in the meat industry.
High-barrier mono-material films, typically based on polyethylene, provide oxygen and moisture protection that rivals traditional multi-layer laminates. Meat processors and private-label brand owners are adopting these structures to meet retailer mandates for recyclability. This innovation is collapsing the long-held trade-off between barrier performance and circularity, challenging the market position of non-recyclable mixed-plastic packaging.
The European Union's Packaging and Packaging Waste Regulation (PPWR) establishes ambitious targets for material recyclability and the inclusion of recycled content. This policy is forcing a fundamental redesign of many conventional meat packaging formats, especially trays and flexible films made from multiple, unrecyclable layers. The flexible packaging segment is most affected, responding with new investments in chemical recycling and mono-material film development.
A significant behavioral shift is occurring as large retailers increasingly source case-ready, shelf-ready packaged meat directly from processors. This model disintermediates traditional in-store butchery and back-of-store packaging operations, pushing value-added activities upstream to the supplier. This trend is most visible across North American and Western European grocery channels, where it is driven by the pursuit of labor efficiency and improved product consistency.
Global Fresh Meat Packaging Market Segmentation
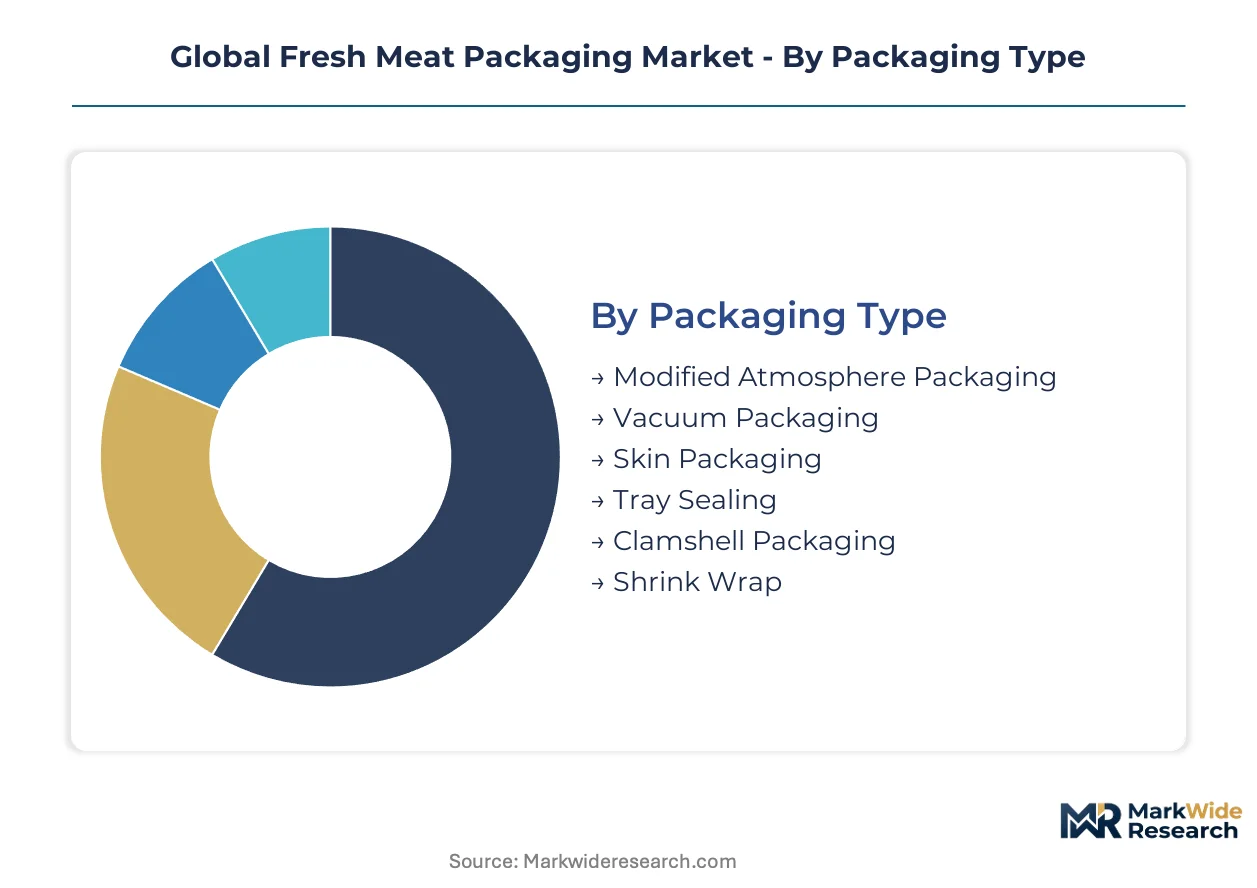
Understanding the segmentation of the global fresh meat packaging market reveals the diverse requirements across product preservation, material innovation, and end-user channels. This detailed breakdown highlights where investment and technological development are concentrated, particularly as sustainability mandates reshape traditional packaging solutions.
Packaging Type:
The diversity of packaging types directly impacts product preservation and market reach for fresh meat products.
- Modified Atmosphere Packaging:This technique involves altering the gas composition within the package, typically by reducing oxygen and increasing nitrogen or carbon dioxide, to significantly extend the shelf life of fresh meat by inhibiting microbial growth. Demand concentrates in large retail chains across North America and Europe, driven by the need for consistent product quality and reduced spoilage.
- Vacuum Packaging:This method removes air from the package before sealing, creating an anaerobic environment that prevents oxidation and suppresses the growth of aerobic bacteria, thereby preserving freshness and color. Meat processors globally utilize vacuum packaging for bulk shipments and extended storage periods, particularly for red meats and processed meat products.
- Skin Packaging:A film is heated and draped over the product and tray, sealing tightly around the meat to create a second skin, enhancing visual appeal and preventing purge.
- Tray Sealing:This involves sealing a film across the top of a pre-formed tray, often used for portioned fresh meats, providing a secure and hygienic barrier.
- Clamshell Packaging:Rigid, hinged containers, typically made from PET or PP, offer robust protection and clear visibility for consumer-facing fresh meat products.
- Shrink Wrap:A polymer film is loosely applied to the product and then heated, causing it to shrink tightly around the meat, offering protection and tamper evidence.
Modified Atmosphere Packaging holds installed capacity. Vacuum Packaging is rotating up the share rankings.
Material Type:
Material composition determines barrier properties and environmental impact across the market.
- Plastic Films:These materials, primarily polyethylene (PE), polypropylene (PP), and PET, offer excellent barrier properties against oxygen and moisture, crucial for extending the shelf life of fresh meat. Conventional plastic films maintain market dominance due to their cost-effectiveness and proven performance in preservation.
- Biodegradable Polymers:Derived from renewable resources like starch or polylactic acid (PLA), these polymers are designed to decompose naturally, addressing growing environmental concerns and regulatory pressures. Biodegradable polymers exhibit the steepest expansion trajectory, particularly in European markets, driven by circular economy initiatives.
- Paperboard:Often laminated or coated for barrier properties, paperboard provides structural rigidity and a printable surface, commonly used for trays or outer packaging.
- Aluminum Foil:Offering superior barrier protection against light, moisture, and oxygen, aluminum foil is used in specialized applications requiring maximum preservation or as part of multi-layer structures.
- Multi-layer Laminates:These combine different material layers (e.g., plastic, foil, paper) to achieve optimized barrier, strength, and sealing properties, though often presenting recycling challenges.
- Corrugated Fiberboard:Primarily used for secondary or tertiary packaging, corrugated fiberboard provides structural support and protection during transportation and storage of packaged meat.
Conventional plastic films maintain market dominance. Biodegradable polymers exhibit the steepest expansion trajectory.
Application:
The application landscape reflects varied operational requirements for fresh meat packaging.
- Retail Chains:Supermarkets and hypermarkets demand case-ready packaging formats that optimize shelf presentation and reduce in-store labor, driving the adoption of high-performance films and trays. Retail chains drive substantial packaging volume, especially in North America and Western Europe, where organized retail infrastructure is mature.
- Meat Processing Units:These facilities utilize packaging solutions for both raw materials and finished products, requiring systems that ensure hygiene, extend shelf life, and facilitate efficient distribution. Meat processing units represent a critical node for packaging innovation, integrating automated equipment for high-volume output.
- Food Service Providers:Restaurants, catering companies, and institutional kitchens require packaging that ensures freshness and portion control for bulk or pre-portioned meat cuts.
- Specialty Butchers:These smaller-scale operations often prioritize aesthetic appeal and personalized packaging, sometimes utilizing more traditional or custom solutions.
- Institutional Catering:Large-scale catering operations for schools, hospitals, or corporate campuses require robust, hygienic, and often bulk packaging for meat components.
Retail chains drive substantial packaging volume. Food service providers are expanding their packaging requirements.
End User:
End-user channels dictate specific packaging formats and logistical demands.
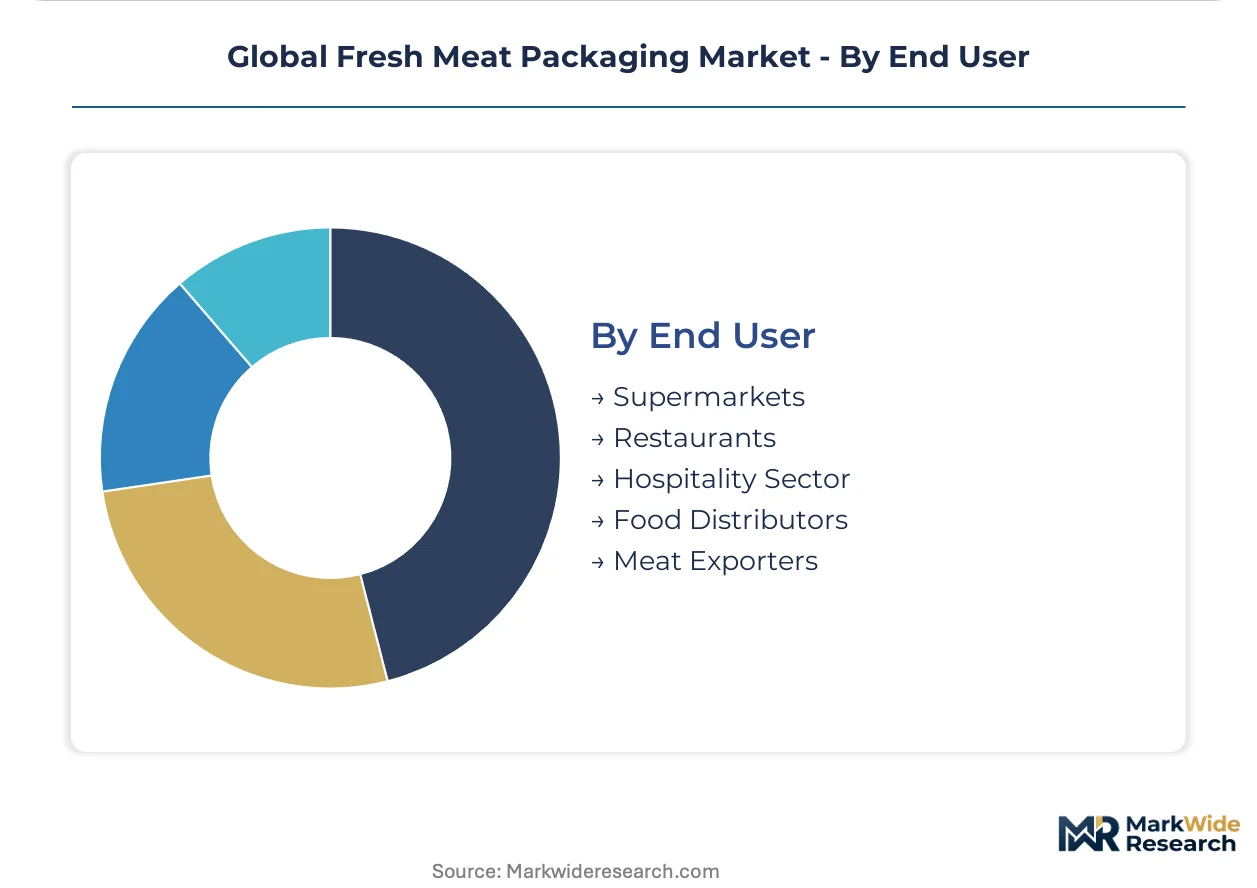
- Supermarkets:These large-format stores are primary consumers of pre-packaged fresh meat, driving demand for visually appealing, extended shelf-life solutions suitable for cold chain display. Supermarkets represent a primary consumption point, particularly for case-ready formats, across developed economies.
- Food Distributors:These entities manage the logistics between processors and various retail or food service outlets, requiring robust and efficient packaging for transport and storage. Food distributors facilitate broad market access, necessitating durable and stackable packaging.
- Restaurants:Commercial kitchens utilize packaging for fresh meat deliveries, prioritizing ease of storage, portion control, and maintaining product quality until preparation.
- Hospitality Sector:Hotels and resorts require diverse packaging for their culinary operations, ranging from bulk deliveries to individual portion packs for guest services.
- Meat Exporters:Companies engaged in international trade rely on high-barrier, long-shelf-life packaging solutions to withstand extended transit times and varying environmental conditions.
Supermarkets represent a primary consumption point. Meat exporters require specialized long-haul packaging solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for fresh meat packaging varies significantly across global geographies. While developed markets prioritize convenience and sustainability, emerging economies focus on basic preservation and cold chain integration. This differential shapes packaging demand and material innovation in diverse regions.
China
Demand for pre-packaged fresh meat in China stems from rapid urbanization and the expansion of organized retail. The State Administration for Market Regulation (SAMR) enforces GB standards, setting stringent requirements for food packaging safety and labeling. Major cold chain and retail infrastructure development in cities like Shanghai and Beijing drives adoption of advanced packaging solutions.
United States
Retail chains drive substantial packaging volume in the United States, demanding case-ready formats for efficiency and consistent merchandising. The US FDA dictates permissible food-contact materials, ensuring product safety and consumer confidence. Meat processing units in states like Nebraska and Iowa are integrating automated packaging equipment to meet high-volume output requirements.
Germany
Sustainability mandates heavily influence packaging choices in Germany, with a strong push for recyclable and biodegradable materials. The European Food Safety Authority (EFSA) provides regulatory oversight for food-contact materials across the EU. Packaging innovation clusters around cities like Düsseldorf and Munich, focusing on mono-material films and advanced barrier solutions.
Brazil
Brazil's position as a major global meat exporter necessitates robust, long-shelf-life packaging solutions for international transit. The national health surveillance agency, ANVISA, regulates food packaging materials to ensure product integrity. Packaging suppliers in São Paulo and Rio Grande do Sul are developing specialized solutions for bulk shipments and extended storage periods.
Australia
Consumer preferences in Australia increasingly favor visually appealing and hygienic fresh meat packaging, particularly for premium cuts. The Therapeutic Goods Administration (TGA) provides guidelines that influence packaging material safety and compliance. Meat processors in regions like Queensland and New South Wales adopt advanced Modified Atmosphere Packaging to extend product freshness.
Global Fresh Meat Packaging Market Key Industry Players
Capability concentration sits with one tier of specialized film manufacturers; scale advantage sits with another tier of diversified packaging conglomerates. The market structure exhibits a tiered consolidation, with large players leveraging global footprints and smaller innovators focusing on niche sustainable solutions. Strategic archetypes include high-barrier film specialists, integrated equipment providers, and flexible material innovators. Dominant competitive moves involve portfolio diversification and strategic partnerships for sustainable material development.
At the scale-driven end, Amcor plc represents a global packaging powerhouse, leveraging its extensive manufacturing network to serve multinational meat processors. Sealed Air exemplifies a specialist in high-barrier films and automated packaging equipment, occupying a position of technological differentiation. Mondi, a European-based provider, sits within the archetype of diversified material solutions, offering both paper-based and flexible plastic options to meet varied sustainability targets.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc |
| Sealed Air |
| Mondi |
| Sonoco Products Company |
| Winpak Ltd |
| Coveris |
| Crown Holdings |
| Bolloré Group |
| Others |
Cost & Logistics Intelligence
Global cold chain logistics costs, influenced by fuel prices, directly impact fresh meat packaging pricing. This volatility feeds into material input costs, affecting margins for film suppliers and eventually retail shelf prices.
Pricing Analysis
Long-term offtake agreements characterize pricing for commodity plastic films supplied to large meat processors. Price differentiation stems from specialized barrier performance for extended shelf life and certified sustainable material solutions. Input cost volatility, particularly for petrochemical-based resins, creates pricing pressure across the conventional film segment. Retail chains seeking case-ready formats exhibit moderate price sensitivity, balancing cost with efficiency gains, while smaller processors prioritize lowest cost commodity films.
Supply Chain Analysis
Environmental regulatory restrictions, particularly in Europe, increasingly limit the free flow of non-recyclable multi-layer plastic packaging materials. Supply concentration for conventional plastic films centers in Asia, while advanced biodegradable polymers largely originate from European and North American developers. The supply chain relies heavily on petrochemical-based resins and specialized barrier additives, creating dependency on global oil price stability. Commodity price volatility for base polymers represents a structural supply chain risk, impacting manufacturing costs and downstream packaging availability. Distribution primarily runs through specialized food distributors who manage logistics between processors and diverse retail or food service outlets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fresh meat packaging market presents a fragmentation opportunity, driven by diverse retailer mandates for recyclability and consumer demand for transparency. This shift creates numerous niches for specialized material solutions and integrated packaging systems.
For Market Incumbents: Build technological moats through accelerated R&D in high-performance mono-material films. Expand automated packaging equipment integration services to counter rising labor costs for retail chains. This strategy defends against new entrants leveraging sustainable materials that currently face technical performance gaps. Leverage existing global manufacturing footprints to scale production of compliant solutions quickly.
For New Entrants and Emerging Players: Build out specialized portfolios targeting the rapidly expanding sustainable packaging segment. Focus on underpenetrated markets in Southeast Asia and Latin America, where organized retail is growing. The most penetrable segment involves offering cost-effective, certified recyclable solutions to mid-sized meat processors. A go-to-market angle emphasizing full regulatory compliance and supply chain transparency will differentiate offerings.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists in advanced polymer science and automation integration. Long-term viability rests on companies capable of balancing high-performance preservation with circular economy principles. Acquisition targets should include innovators in mono-material film development and intelligent packaging solutions. The signal to watch is the widespread commercialization of biodegradable polymers matching conventional plastic performance.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Polymer R&D | Develop high-performance mono-material films to meet recyclability mandates. |
| Automated Equipment Integration | Reduce labor costs for retail chains and enhance processing efficiency. |
| Geographic Market Expansion | Capture demand in underpenetrated Southeast Asian and Latin American markets. |
| Sustainability Certification Investment | Gain market access and consumer trust in environmentally conscious regions like Europe. |
| Intelligent Packaging Development | Offer real-time quality assurance and reduce food waste for brand owners. |
Research Approach
A spread of perspectives from meat processors, retail chain procurement managers, packaging material scientists, and regulatory compliance officers converged on the working assumptions. Primary interviews were combined with secondary validation from sources like US FDA guidelines, EFSA reports, and industry association publications. This approach facilitated bottom-up data collection and top-down market sizing for comprehensive analysis. Triangulation across diverse data points ensured robustness in market insights.
Demand-supply balance models underpinned the analytical framework across the analysis window. The framework segmented the market by packaging type, material type, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected impacts of key market drivers. Key forecast inputs included petrochemical resin price forecasts and shifts in consumer sustainability preferences.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large diversified packaging conglomerates or novel material innovators would shift outcomes. Forecasts reflect prevailing assumptions regarding regulatory stability and technological progression. Material shifts in global trade policies or disruptive material innovations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Frozen Food Packaging Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
APAC Canned Food Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
Hot Drinks Packaging Market
Food Packaging
Poultry Packaging Market
Food Packaging
Bamboo Plate Market
Food Packaging
Coffee Capsules and Pod Packaging Market
Food Packaging
Disposable Food Containers Market
Food Packaging
Transparent Food Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Chocolate Packaging Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Meal Kit Packaging Market