
 Brightness Enhancement Films Market | 2026-2036
Brightness Enhancement Films Market Size, Share, and Industry Trends Forecast 2026-2036
Brightness Enhancement Films Market Outlook
Software-defined optical tuning is consolidating what display OEMs purchase as a bundled service layer rather than discrete film commodities. 3M leverages its patent portfolio in micro-replication to sustain premium positioning across high-resolution monitor supply chains. Samsung SDI anchors domestic Korean panel demand through captive backward integration into optical film production. Mitsubishi Chemical Corporation specializes in coated film variants for automotive-grade durability requirements.
Brightness enhancement films are multi-layer optical components, typically 50-250 micrometers thick, engineered with prismatic or micro-lens surface structures that redirect off-axis light toward the viewer axis to improve display luminance without additional power draw. Polymer films dominate commercial volumes due to roll-to-roll manufacturing scalability and flexibility in large-format LCD and OLED backlight units. Micro-structured technology leads in value contribution where sub-20-micron feature precision commands pricing premiums from display manufacturers. Nano-technology segments are gaining traction in mini-LED diffusion plates where particle-based light management competes with surface relief approaches.
The EPA regulates perfluorinated substance emissions in US film coating operations, while REACH restricts certain phthalate plasticizers in European polymer substrates. China's MEE enforces volatile organic compound discharge limits at optical film extrusion facilities in Jiangsu and Guangdong provinces. Korea's MFDS maintains biocompatibility standards for healthcare display applications that filter into film material selection criteria. Stakeholders must monitor how evolving dual carbon goals across East Asian manufacturing hubs reshape energy intensity requirements for extrusion and coating processes.
Market Dynamics
Display manufacturers in Shenzhen, Chengdu, and Hefei are consolidating optical film procurement into multi-year framework agreements, compressing supplier margins while locking in volume commitments that reshape competitive positioning across East Asian supply chains.
Growth Catalysts
- Mini-LED backlight diffusion:Panel makers in China's display corridor are scaling micro-structured polymer films for mini-LED arrays, creating specification pull for sub-20-micron precision substrates.
- REACH chemical compliance:ECHA substrate tightening in the European Union is filtering non-compliant Asian suppliers from premium automotive and medical display supply chains.
- Captive backward integration:Korean panel producers are bringing optical film production in-house, reducing import dependency and stabilizing input costs for high-resolution monitor manufacturing.
Market Restraints
- Petrochemical input volatility:Biaxially-oriented polyethylene terephthalate (BOPET) resin prices fluctuate with crude oil benchmarks, squeezing extrusion margins for independent film converters.
- MEE discharge enforcement:China's volatile organic compound limits at Jiangsu and Guangdong extrusion facilities are forcing capital expenditure into scrubber systems and solvent recovery.
- Nano-particle substitution:Quantum dot diffusion plates are capturing share in premium television backlights where color gamut performance outweighs pure luminance gains.
Strategic Opportunities
- Automotive-grade durability specifications:Coated film variants meeting JIS and ISO vibration standards are opening infotainment and head-up display applications in Japanese and German OEM supply chains.
- Software-defined optical tuning:Display OEMs are purchasing brightness management as bundled service layers rather than discrete commodities, enabling recurring revenue models for film suppliers with embedded sensor integration.
- Healthcare display biocompatibility:Korea's MFDS standards for surgical and diagnostic monitors are creating certified-material premiums that filter into film substrate selection criteria.
Industry Challenges
- Micro-replication talent scarcity:Precision tooling engineers capable of sub-20-micron feature design are concentrated among a handful of Japanese and German equipment suppliers, constraining capacity expansion.
- Dual carbon compliance timelines:East Asian manufacturing hubs are imposing energy intensity caps on extrusion and coating processes before low-carbon process technologies reach commercial maturity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brightness Enhancement Films Market |
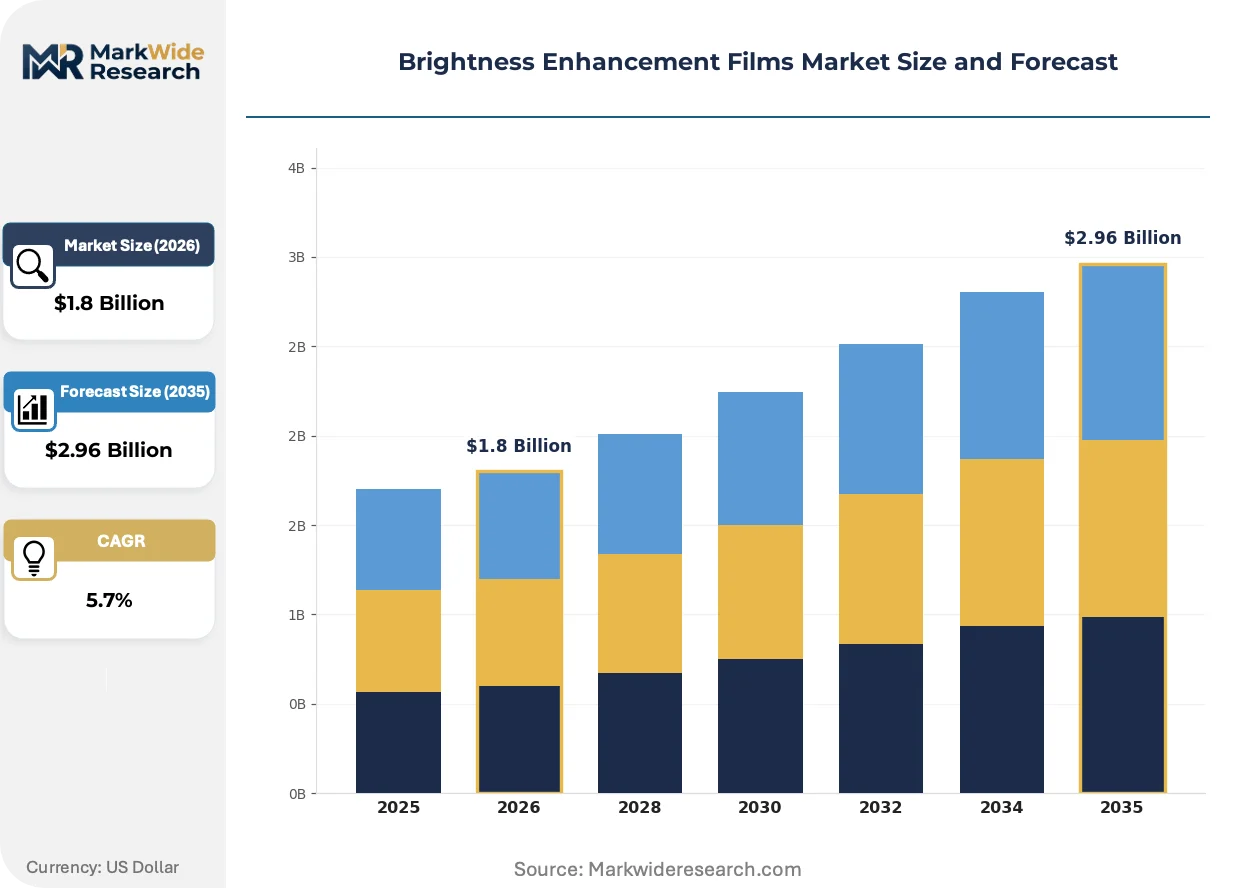
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Films, Glass Films, Coated Films, Laminated Films End User: Consumer Electronics, Automotive, Healthcare, Signage Technology: Optical Technology, Micro-Structured Technology, Nano-Technology, Liquid Crystals Application: Displays, Lighting, Projectors, Monitors |
| Companies Covered | Samsung SDI, SKC Haas Display Films, 3M, Shinwha, Nitto Denko Corporation, Kolon Industries, LG Chem, MNtech, Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brightness Enhancement Films Market Strategic Shifts
Optical film technology is fragmenting across three vectors: surface relief structures competing with particle-based diffusion, regulatory chemistry constraints forcing material reformulation, and procurement consolidation compressing traditional distribution channels.
Prismatic micro-lens arrays are converging with roll-to-roll nano-imprint lithography to enable sub-10-micron feature replication at production speeds previously limited to coarser geometries. Automotive display manufacturers in Germany and Japan are qualifying these structures for head-up projection systems where angular luminance uniformity is critical. The structural consequence is converging with equipment supplier consolidation, as only Tokyo-based and Munich-based tooling houses possess the metrology capabilities for production-scale validation.
REACH restrictions on phthalate plasticizers are forcing polymer substrate reformulation across European supply chains, with ECHA compliance timelines compressing qualification windows for Asian exporters. Film converters serving medical and automotive end-uses are shifting toward bio-based polyester alternatives and non-phthalate plasticizer systems. The segment most affected is coated film variants for healthcare displays, where MFDS biocompatibility requirements in Korea are layering additional certification burdens onto already-constrained material pipelines.
Chinese panel manufacturers are unbundling optical film procurement from backlight unit assembly, establishing direct supplier relationships that displace traditional module integrators. This channel restructuring concentrates purchasing power among BOE, CSOT, and Tianma, compressing distributor margins while demanding just-in-time delivery to Shenzhen, Chengdu, and Hefei production campuses. The geography where this disintermediation is most visible is the Pearl River Delta, where logistics providers are reconfiguring warehouse networks to serve direct-to-factory film delivery.
Brightness Enhancement Films Market Segmentation
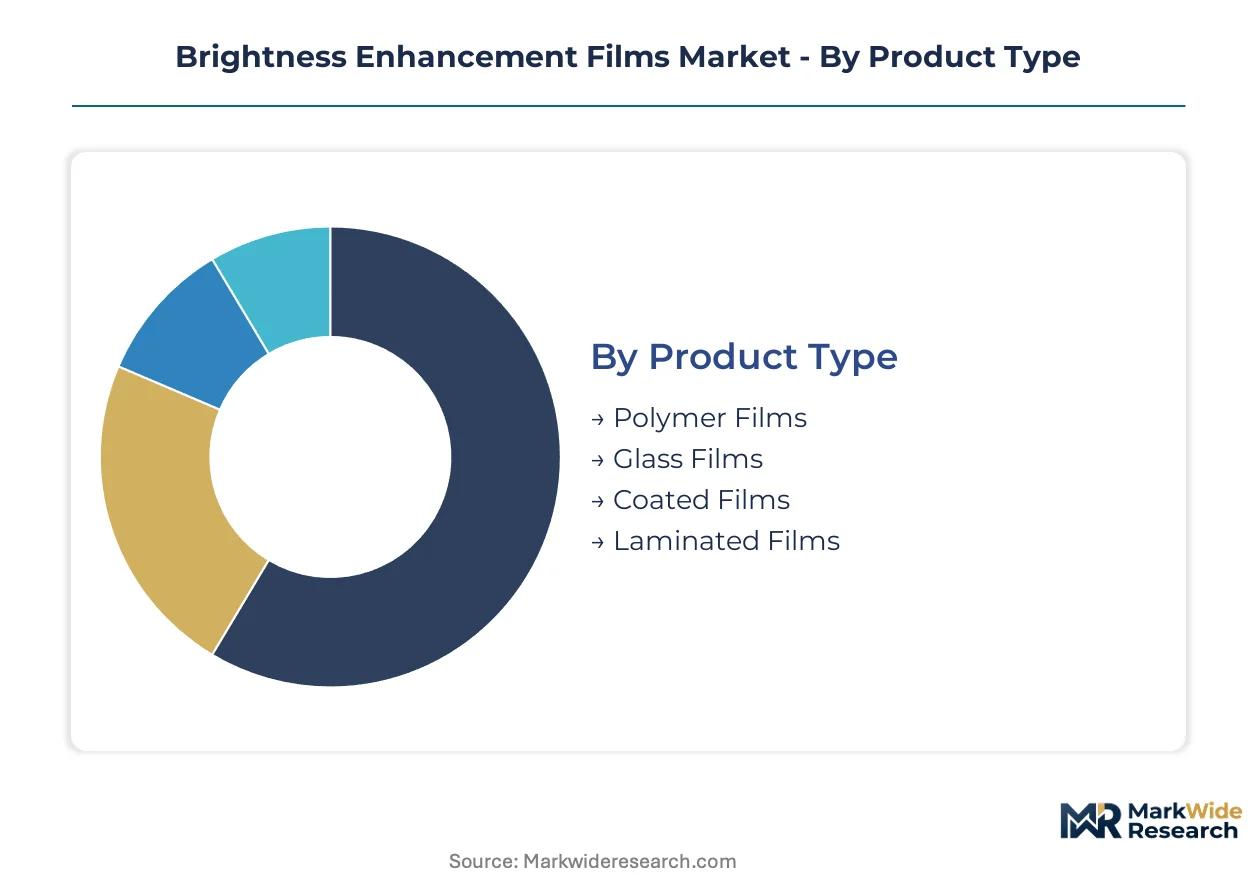
Upgrade cycles in display manufacturing reshape procurement patterns across every film specification tier. Understanding how technical requirements fragment by product construction, end-use durability demands, and precision thresholds enables suppliers to align capacity investments with where specification premiums concentrate.
Product Type:
Replacement timelines in LCD and OLED manufacturing favor substrates that balance optical performance with roll-to-roll process compatibility.
- Polymer Films:Biaxially-oriented polyethylene terephthalate (BOPET) and polycarbonate substrates dominate commercial volumes through extrusion scalability and flexibility in large-format backlight units. Demand concentrates in China's display corridor—Shenzhen, Chengdu, and Hefei—where panel makers are consolidating procurement into multi-year framework agreements that compress supplier margins while locking in volume commitments.
- Coated Films:Surface-treated variants incorporate anti-reflective, hard-coat, or conductive layers through vacuum deposition or wet coating processes. Automotive-grade specifications from German and Japanese OEMs are pulling coated film demand toward JIS and ISO vibration standards for infotainment and head-up display applications.
- Glass Films:Thin-glass substrates offer thermal stability and dimensional precision for high-luminance direct-lit backlights. Cost and fragility constrain adoption to premium monitor segments.
- Laminated Films:Multi-layer constructions bond prismatic and diffuser films into single-unit backlight components. Integration reduces assembly steps for display module integrators.
Polymer films sit at the top of the volume ranking, with coated films climbing the fastest as automotive and medical certifications layer premium specifications onto substrate requirements.
End User:
Cost-to-performance thresholds diverge sharply across customer categories, with certification burdens and volume scale creating distinct margin architectures.
- Consumer Electronics:Television, smartphone, and tablet manufacturers drive baseline demand through high-volume, price-sensitive procurement. China's panel producers—BOE, CSOT, and Tianma—are unbundling optical film purchasing from backlight assembly, establishing direct supplier relationships that displace traditional module integrators.
- Automotive:Infotainment, instrument cluster, and head-up display applications demand vibration resistance, thermal cycling durability, and angular luminance uniformity. REACH chemical compliance in the European Union and JIS standards in Japan are filtering non-compliant Asian suppliers from premium automotive supply chains.
- Healthcare:Surgical and diagnostic monitors require biocompatibility certifications under Korea's MFDS standards. Material selection criteria filter through to film substrate specifications, creating certified-material premiums.
- Signage:Commercial and outdoor display applications prioritize weather resistance and extended operational lifetimes over optical precision. Volume scale trails consumer electronics by an order of magnitude.
Consumer electronics commands the largest volume position, though automotive is expanding most quickly as display penetration into vehicle interiors accelerates.
Technology:
Feature precision and manufacturing throughput determine which light-management approaches capture specification premiums.
- Micro-Structured Technology:Prismatic or micro-lens surface structures redirect off-axis light toward the viewer axis, engineered with sub-20-micron feature precision. 3M leverages its patent portfolio in micro-replication to sustain premium positioning across high-resolution monitor supply chains.
- Nano-Technology:Particle-based light management competes with surface relief approaches in mini-LED diffusion plates. Quantum dot diffusion plates are capturing share in premium television backlights where color gamut performance outweighs pure luminance gains.
- Optical Technology:Conventional refractive and reflective film designs serve cost-optimized display segments where manufacturing simplicity outweighs efficiency maximization.
- Liquid Crystals:Tunable birefringent layers enable dynamic brightness adjustment through voltage control. Complexity and cost limit deployment to specialized applications.
Micro-structured technology maintains the dominant volume position, while nano-technology is gaining share fastest as mini-LED backlight architectures proliferate.
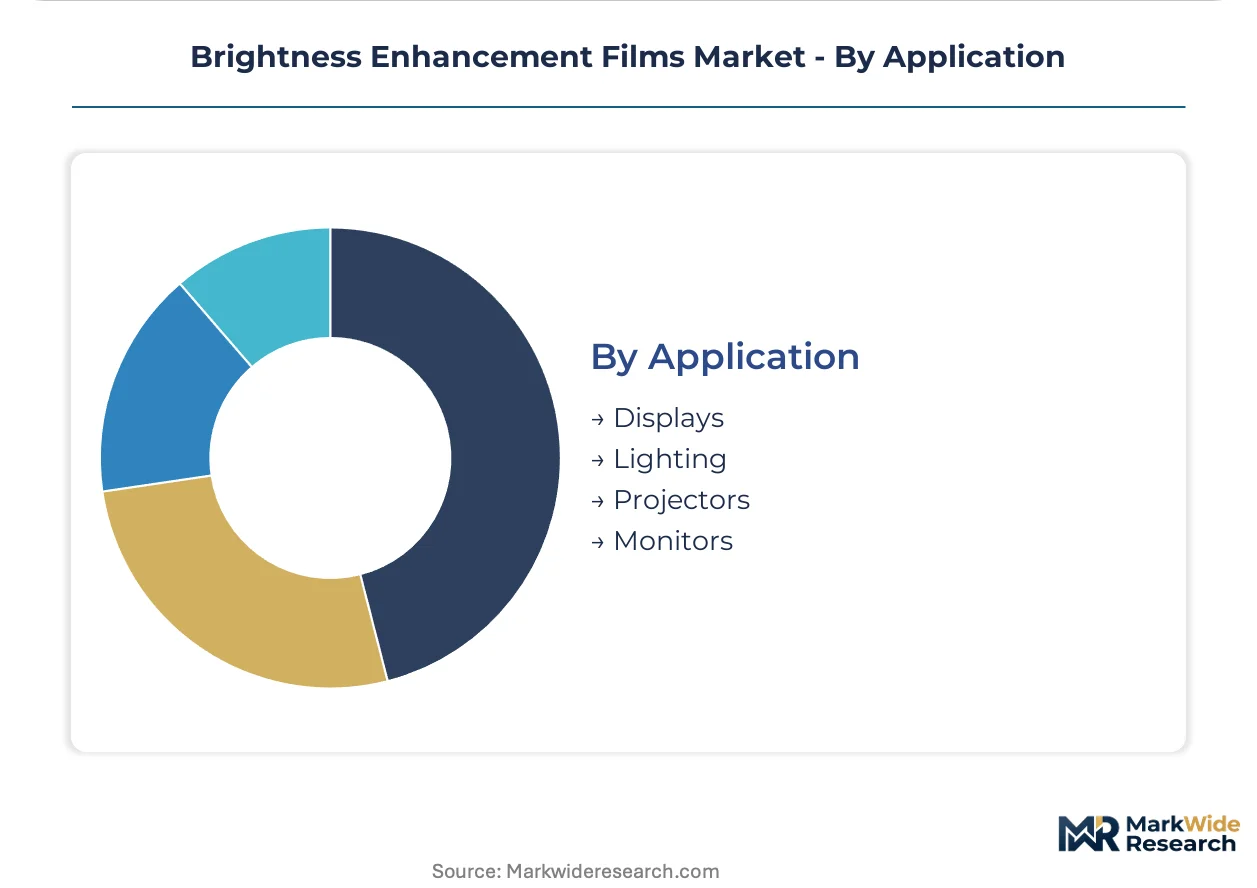
Application:
Display format and viewing environment dictate luminance uniformity requirements and film layer complexity.
- Displays:LCD and OLED televisions, smartphones, and tablets constitute the core demand base. Roll-to-roll manufacturing scalability enables polymer films to serve large-format requirements.
- Monitors:High-resolution desktop and professional displays command sub-20-micron precision specifications. Korean panel producers are bringing optical film production in-house through captive backward integration.
- Lighting:LED luminaire applications leverage brightness enhancement for directional output control. Specification intensity trails display applications.
- Projectors:Head-up display and pico-projector systems require angular luminance uniformity for off-axis viewing. Automotive qualification timelines extend development cycles.
Displays occupy the top volume tier, with monitors showing the steepest expansion trajectory as professional and gaming segments drive resolution upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands procurement volume while South Korea drives captive production integration, creating divergent supply chain models across East Asia's display corridor.
China
Panel manufacturers BOE, CSOT, and Tianma are consolidating optical film procurement into multi-year framework agreements that compress supplier margins while locking in volume commitments. MEE enforces volatile organic compound discharge limits at extrusion facilities in Jiangsu and Guangdong provinces. The display manufacturing corridor spanning Shenzhen, Chengdu, and Hefei is unbundling film purchasing from backlight unit assembly, establishing direct supplier relationships that displace traditional module integrators.
South Korea
LCD panel manufacturers are expanding procurement of micro-structured polymer films while bringing optical film production in-house through captive backward integration. MFDS maintains biocompatibility standards for healthcare display applications that filter into film material selection criteria. Samsung SDI anchors domestic panel demand through integrated optical film production serving high-resolution monitor supply chains.
Japan
Automotive display manufacturers are qualifying prismatic micro-lens arrays for head-up projection systems where angular luminance uniformity is critical. METI oversees industrial standards coordination while JIS vibration specifications govern infotainment and instrument cluster applications. Tokyo-based tooling houses possess the metrology capabilities for production-scale validation of sub-10-micron feature replication.
United States
EPA regulates perfluorinated substance emissions in film coating operations, reshaping material formulation requirements for suppliers serving North American display assembly. Professional and gaming monitor segments drive resolution upgrades that command sub-20-micron precision specifications. Equipment suppliers concentrate precision tooling engineering capabilities that constrain capacity expansion across the industry.
Germany
REACH chemical compliance administered by ECHA tightens substrate material requirements, filtering non-compliant Asian suppliers from premium automotive and medical display supply chains. German OEMs are pulling coated film demand toward ISO vibration standards for infotainment applications. Munich-based tooling houses compete with Japanese counterparts in production-scale metrology for micro-replication validation.
Brightness Enhancement Films Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates and independent film converters occupying distinct competitive tiers. Market structure consolidates around patent-protected micro-replication technology and roll-to-roll manufacturing scale, creating barriers for new entrants lacking precision tooling relationships. Three archetypes dominate: diversified materials conglomerates with captive display supply, specialized optical film pure-plays, and vertically integrated panel producers. Competitive moves center on backward integration into substrate production and strategic patent licensing to defend positioning in high-resolution monitor supply chains.
Within the diversified materials tier, Mitsubishi Chemical Corporation and LG Chem exemplify integrated chemical conglomerates leveraging polymer substrate capabilities into optical film value chains. Samsung SDI represents the vertically integrated panel producer archetype, anchoring domestic Korean demand through captive optical film production. 3M occupies the branded specialist position, sustaining premium positioning through micro-replication patent portfolios across high-resolution monitor applications. These three companies illustrate how geographic origin and corporate structure shape competitive positioning without converging on identical strategic postures.
| Leading Market Players |
|---|
| Samsung SDI |
| SKC Haas Display Films |
| 3M |
| Shinwha |
| Nitto Denko Corporation |
| Kolon Industries |
| LG Chem |
| MNtech |
| Mitsubishi Chemical Corporation |
| Others |
Value Chain & Pricing Dynamics
Chinese panel OEMs—BOE, CSOT, and Tianma—are compressing supplier margins through multi-year framework agreements that lock in volume commitments while stripping away pricing premiums previously captured by module integrators.
Pricing Analysis
Capacity additions in China's Jiangsu and Guangdong provinces are reshaping price floors for biaxially-oriented polyethylene terephthalate substrates. Three-tier pricing structure across automotive-certified, consumer-grade, and economy levels separates REACH-compliant European supply from standard Asian output. Cost compression in consumer electronics tiers is intensifying because BOE and Tianma are unbundling procurement from backlight assembly. Television manufacturers exhibit highest price sensitivity, while German automotive OEMs absorbing ISO vibration certification premiums show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Tokyo-based and Munich-based tooling houses possessing sub-10-micron metrology capabilities for production-scale validation. Optical film manufacturing draws from South Korea, Japan, and China, with BOPET resin feeds tethered to crude oil benchmarks and phthalate plasticizer formulations facing REACH substitution timelines. Tariff exposure on coated film imports into the European Union filters non-compliant Asian suppliers from premium automotive supply chains. Distribution runs through direct-to-factory delivery networks reconfigured around Shenzhen, Chengdu, and Hefei production campuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns for suppliers navigating REACH chemical compliance as ECHA substrate tightening filters non-compliant competitors from medical and automotive certification pipelines.
For Market Incumbents: Deepen captive backward integration into optical film production to offset margin compression from Chinese procurement consolidation. Samsung SDI's integrated model demonstrates how in-house substrate supply stabilizes input costs against petrochemical volatility. Invest in sub-20-micron micro-replication tooling relationships with Japanese equipment houses to defend precision specification premiums. For New Entrants and Emerging Players: Nano-technology diffusion plates for mini-LED backlights offer the most penetrable wedge against established prismatic film suppliers. Target healthcare display applications where Korea's MFDS biocompatibility standards create certified-material premiums that offset volume scale disadvantages. Lead with software-defined optical tuning bundled service layers rather than commodity film transactions. For Investors and Strategic Acquirers: Korean chemical conglomerates are the most active acquirer in this space, seeking optical film capabilities to complete captive display supply chains. Five-to-ten year viability hinges on positioning within automotive-grade specification pipelines as display penetration into vehicle interiors accelerates. Watch for ECHA enforcement actions against phthalate plasticizers as inflection signal for bio-based polyester substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Samsung SDI's captive optical film supply stabilizes Korean panel input costs against resin volatility. |
| REACH-Compliant Material Reformulation | ECHA phthalate restrictions force bio-based polyester alternatives in European medical display supply chains. |
| Direct Supplier Relationship Establishment | BOE's unbundled procurement from backlight assembly compresses distributor margins across Pearl River Delta logistics networks. |
| Sub-10-Micron Feature Replication Investment | Roll-to-roll nano-imprint lithography convergence enables automotive head-up display qualification for German OEMs. |
| Software-Defined Optical Tuning Development | Embedded sensor integration shifts revenue models from discrete film commodities to recurring brightness management services. |
Study Parameters
Multiple input streams—primary interviews with optical film plant managers and display OEM procurement leads, secondary validation through SEC filings and customs trade data, and technical specification review—were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed polymer substrate R&D directors at Mitsubishi Chemical Corporation and LG Chem, distribution channel partners serving Shenzhen and Hefei production corridors, and regulatory affairs specialists tracking ECHA and MEE compliance timelines.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation modeled by product construction tier, end-use durability specification, feature precision threshold, and regional manufacturing cluster. CAGRs were derived from production capacity trajectories at Jiangsu and Guangdong extrusion facilities, mini-LED diffusion plate adoption curves, and automotive display content-per-vehicle expansion assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to dual carbon compliance timelines across East Asian manufacturing hubs and quantum dot substitution rates in premium television backlights. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
Book Wraps Market
Packaging Materials
Desiccant Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Production Page Volume Market
Packaging Materials
Packaging Lacquering Market
Packaging Materials
Printable Self-Adhesive Vinyl Films Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Heat Shrink Packaging Market
Packaging Materials
Corrugated Wraps Market
Packaging Materials
Foam Trays Market
Packaging Materials
Corrugated Wrap Around Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Composite Packaging Market
Packaging Materials
Bakeable Trays Market