
 Vacuum Skin Packaging Market | 2026-2036
Vacuum Skin Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Skin Packaging Market Outlook
ISO 22000 certification for food safety management systems is rotating as a gatekeeping standard that determines supplier eligibility with major protein processors. Sealed Air leverages its thermoforming equipment integration to anchor long-term contracts with North American meatpackers. Mondi Group sustains competitive positioning through captive kraft paper and barrier film production across Central European mills. Berry Global differentiates via multi-layer EVOH and PE film extrusion capabilities that serve both retail and foodservice channels.
Vacuum skin packaging employs a pre-formed tray and a top film heated and drawn by vacuum to conform tightly around a food product, creating an oxygen-depleted environment that inhibits microbial growth and preserves color; typical barrier constructions incorporate EVOH or PVDC layers achieving oxygen transmission rates below 1 cc/m²/day. Meat Products applications dominate volume due to premium beef and lamb retail programs, while Ready-to-Eat Meals represent the fastest-growing category as chilled prepared food manufacturers adopt skin packs to replace modified atmosphere formats. Plastic Films command the largest material share, though Composites are gaining ground where puncture resistance and printability requirements intensify.
The FDA regulates vacuum skin packaging for ready-to-eat and raw proteins under 21 CFR Parts 110 and 117, with Hazard Analysis and Critical Control Points plans mandatory for all suppliers to US food manufacturers. The EU F-Gas Regulation and REACH restrictions on perfluorinated substances are reshaping barrier film chemistry, pushing converters toward bio-based and recyclable mono-material structures. Stakeholders must monitor how EFSA evolves its guidance on food contact materials and whether US state-level extended producer responsibility laws outpace federal standardization.
Market Dynamics
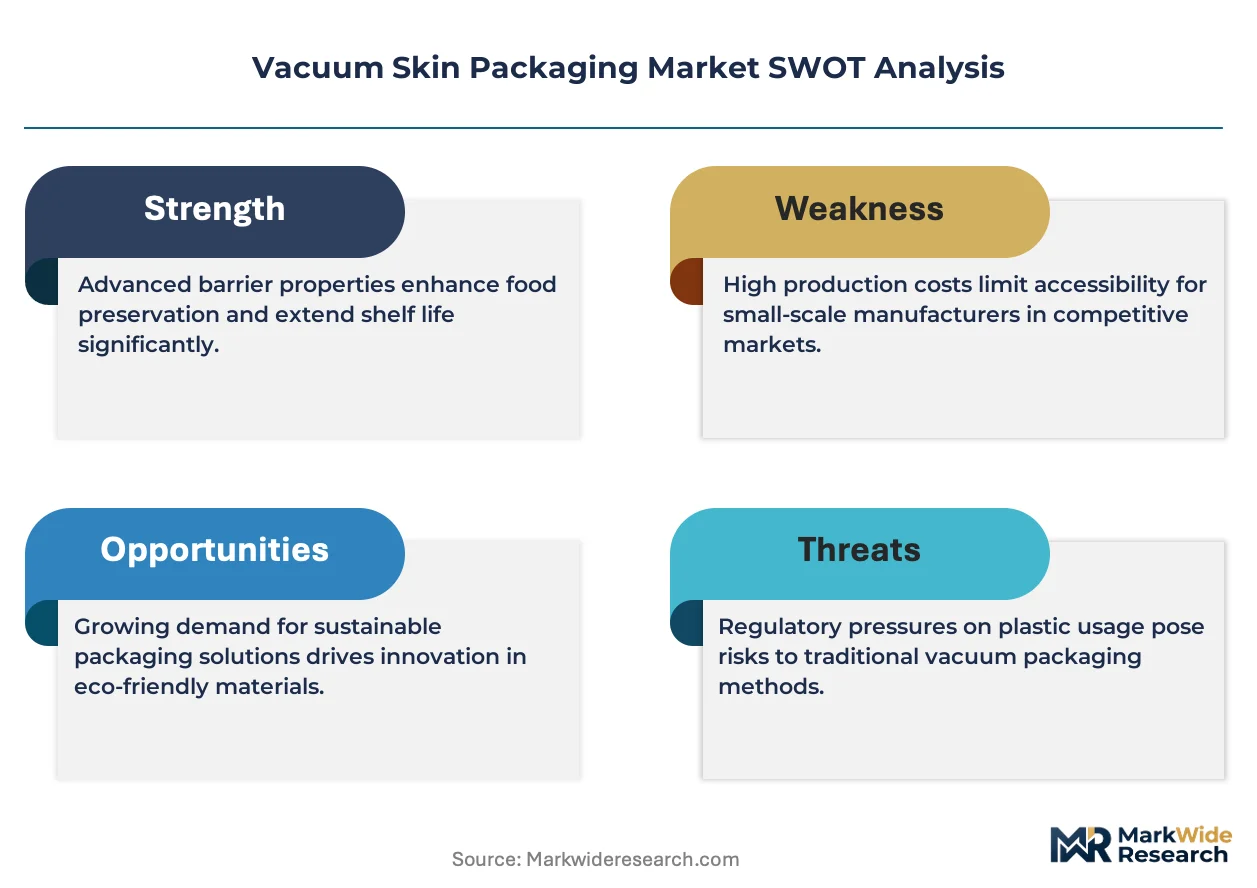
The EU Packaging and Packaging Waste Regulation is forcing converters to redesign multi-layer barrier films into recyclable mono-material structures, compressing margins for legacy equipment while opening contract windows for integrated film-tray system suppliers.
Growth Catalysts
- Protein processor consolidation:Major beef and lamb packers in Germany and the Netherlands are standardizing vacuum skin formats across retail programs, pulling film specifications toward high-barrier EVOH constructions.
- REACH restrictions on perfluorinated substances:ECHA's tightening limits on PFAS in food contact materials are accelerating R&D into bio-based barrier chemistries that maintain sub-1 cc/m²/day oxygen transmission rates.
- Chilled ready-meal expansion:European food manufacturers are displacing modified atmosphere packaging with skin packs to extend shelf life and enable premium case-ready presentation in discount supermarket channels.
Market Restraints
- Resin cost volatility:EVOH and PVDC barrier polymers face price swings tied to ethylene and vinyl alcohol feedstock markets, constraining converter margin stability.
- Thermoforming equipment concentration:High-capacity vacuum skin lines cluster with a limited set of European and North American machinery builders, creating bottlenecks for mid-tier processors seeking capacity expansion.
- Multi-layer recycling incompatibility:Current barrier film constructions combining PE, EVOH, and tie layers resist mechanical recycling under EU circular economy targets, exposing producers to extended producer responsibility fees.
Strategic Opportunities
- Mono-material barrier innovation:Convergence of high-density polyethylene with advanced surface coating technologies enables full-film recyclability without sacrificing oxygen barrier performance.
- Foodservice channel penetration:Vacuum skin formats for portion-controlled proteins and sous-vide preparations remain underdeveloped relative to retail, offering volume expansion as institutional buyers adopt case-ready packaging.
- Digital printing integration:Inline variable-data printing on top films supports retailer-specific SKU proliferation and regulatory traceability requirements under EU food information regulations.
Industry Challenges
- ISO 22000 certification timelines:Protein processors demand third-party food safety management system verification, stretching 12-18 month onboarding cycles for new film suppliers.
- Legacy thermoforming retrofit complexity:Existing modified atmosphere packaging lines require substantial mechanical and control system modifications to accommodate skin pack film handling and vacuum draw profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Skin Packaging Market |
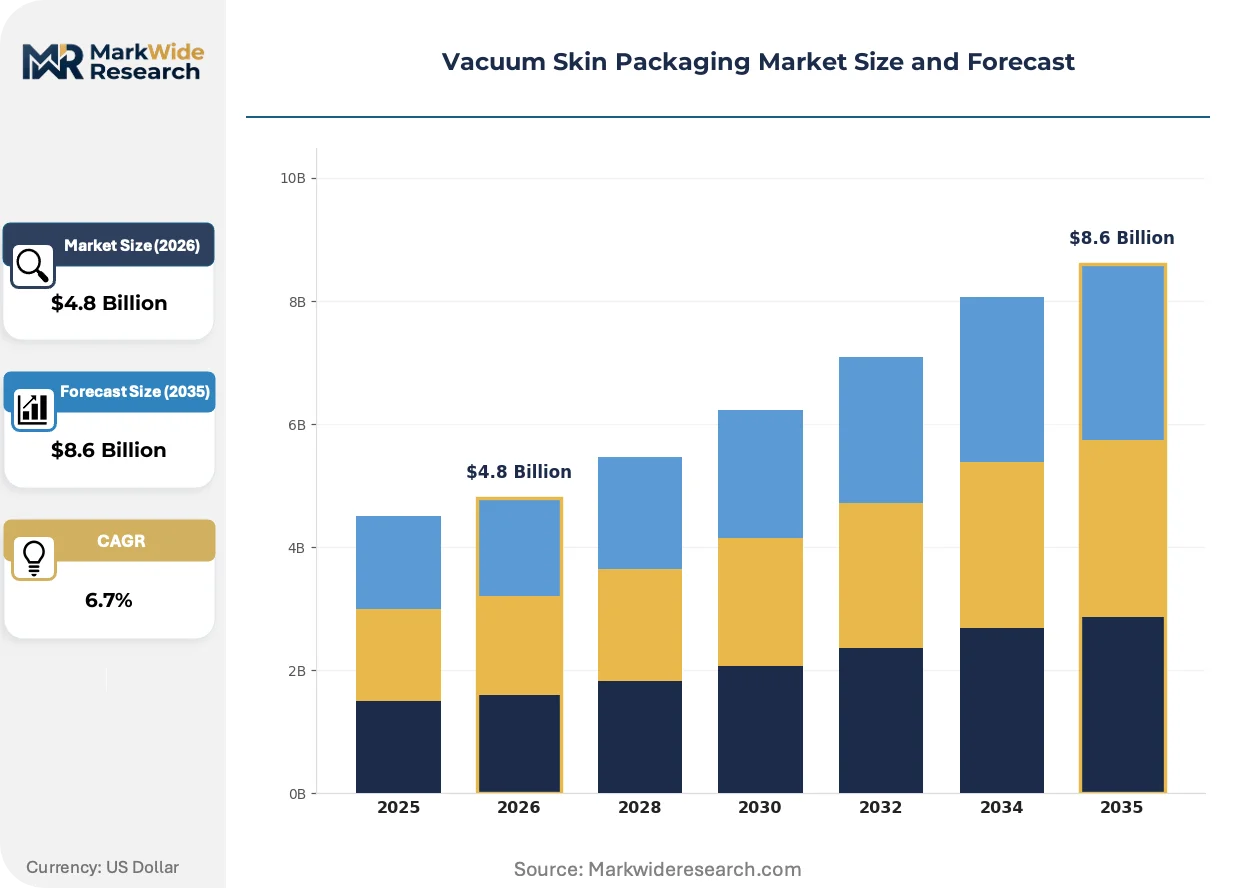
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Products, Seafood, Dairy Products, Ready-to-Eat Meals Material: Plastic Films, Foil, Paper, Composites End User: Food Manufacturers, Retailers, Food Service Providers, Consumers Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | Berry Global, Mondi Group, Sealed Air, Linpac Packaging, Schur Flexibles, Amcor, Coveris, Plastopil, Winpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Skin Packaging Market Strategic Shifts
Barrier film chemistry is rotating toward recyclable mono-material constructions as regulatory pressure compounds with retailer sustainability mandates, while equipment automation and digital integration reshape production economics.
High-barrier mono-material films incorporating advanced polyethylene surface treatments are bifurcating the converter landscape. Premium meatpackers in Germany and Austria are specifying these constructions for private-label programs. The technology is compressing demand for conventional multi-layer EVOH laminates in standardized retail formats while creating premium pricing tiers for certified recyclable alternatives.
REACH annex revisions and the EU F-Gas Regulation are restricting fluorinated barrier chemistries and high-global-warming-potential process gases. Film extruders are reformulating adhesive and coating layers to eliminate perfluorinated substances. Ready-to-eat meal manufacturers face the tightest compliance timelines, with EFSA guidance on food contact materials driving accelerated substitution programs.
Retail buyer concentration is compressing supplier negotiation cycles. Discount supermarket chains in Germany and the Netherlands are consolidating film specifications across protein categories, displacing fragmented regional converter relationships. Procurement teams now mandate lifecycle carbon data and recyclability certifications alongside unit cost metrics, with compliance requirements most stringent for beef and lamb premium lines.
Vacuum Skin Packaging Market Segmentation
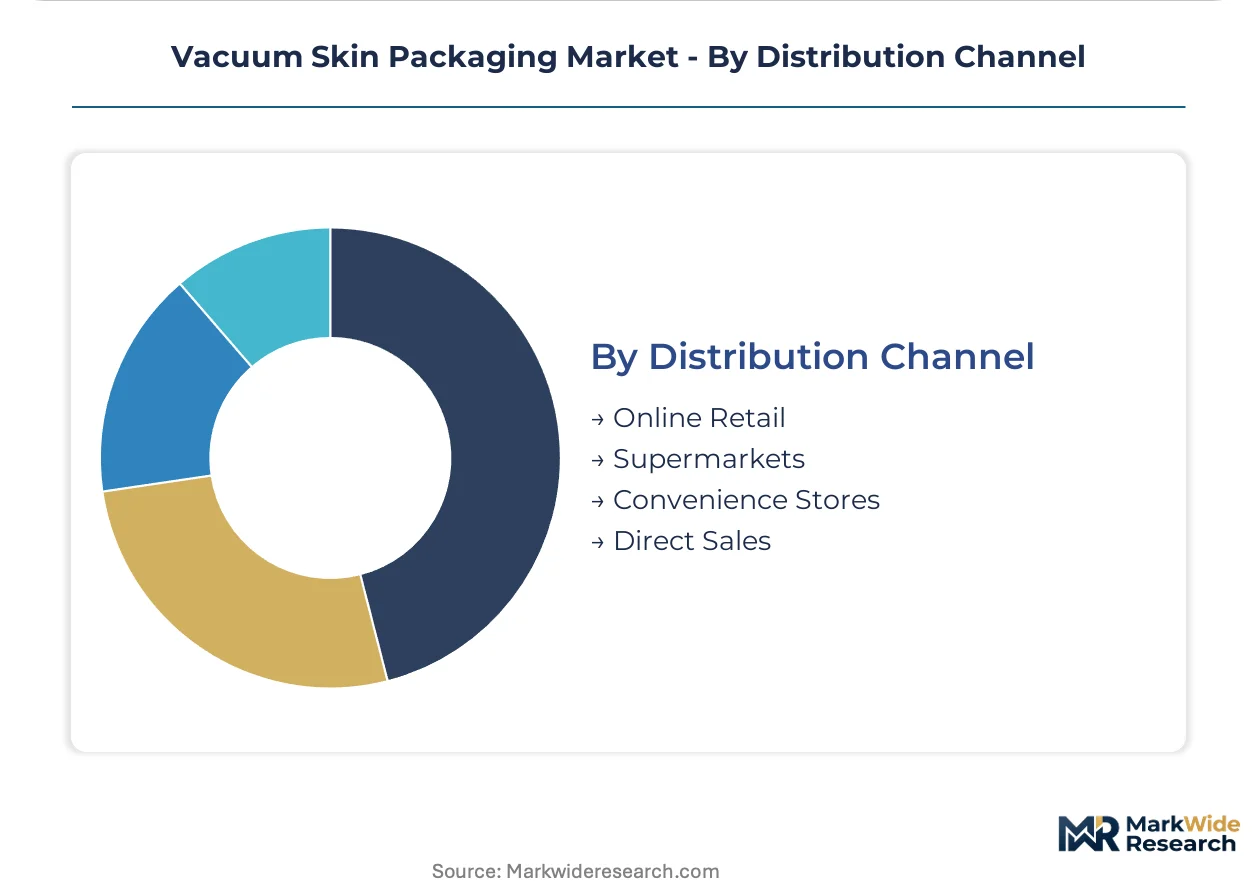
Channel mix dynamics in vacuum skin packaging diverge sharply by product perishability and retail format requirements. Protein processors route premium cuts through supermarkets with standardized barrier specifications, while foodservice channels favor portion-controlled formats with distinct sealing profiles.
Product Type:
Supermarket chains and discount retailers drive volume concentration in premium protein segments, whereas foodservice procurement pulls specialized formats for institutional kitchens.
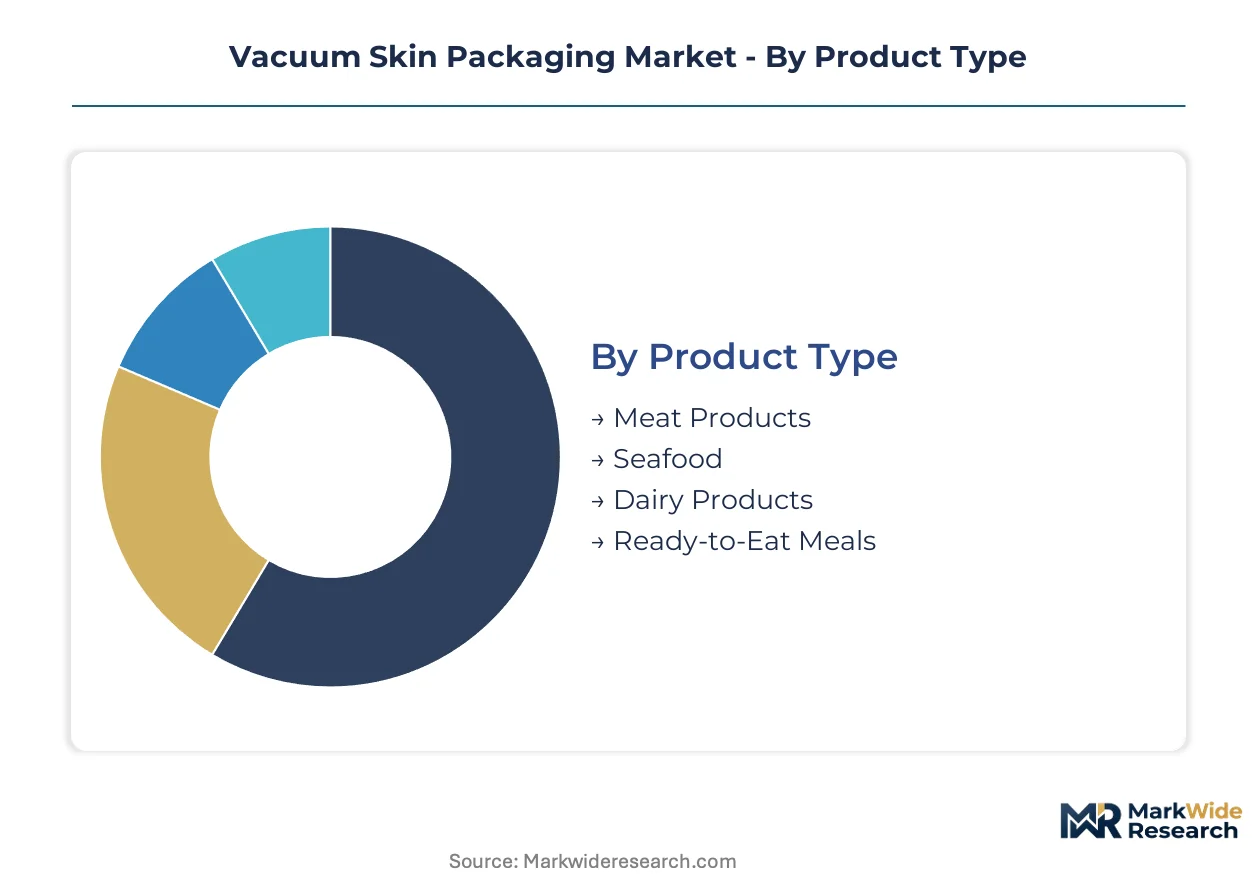
- Meat Products:Beef and lamb programs dominate supermarket shelf space with high-barrier EVOH constructions achieving sub-1 cc/m²/day oxygen transmission. German retail chains standardize specifications across private-label lines, compressing supplier margins while locking in multi-year contracts.
- Ready-to-Eat Meals:Chilled prepared food manufacturers displace modified atmosphere packaging with skin formats to enable premium case-ready presentation. Discount channels in the Netherlands accelerate adoption as meal-kit providers specify extended shelf-life performance.
- Seafood:Puncture-resistant composites address bone-in fish and shellfish applications for foodservice distributors.
- Dairy Products:Cheese and fresh pasta segments adopt skin packs for moisture control in convenience store channels.
By volume, Meat Products leads. By growth pace, Ready-to-Eat Meals is climbing the fastest.
Material:
Cost tiers stratify around barrier performance requirements and recyclability compliance obligations under EU circular economy mandates.
- Plastic Films:Multi-layer PE-EVOH-PE laminates command the largest share, though mono-material HDPE with advanced surface coatings gains traction among German meatpackers seeking recyclability certification. Resin cost volatility constrains converter pricing power.
- Composites:Kraft paper-barrier film combinations address printability and puncture resistance demands in premium retail programs. Mondi's captive Central European mill network supplies standardized specifications to Austrian and German processors.
- Foil:Aluminum layers serve high-oxygen-sensitivity applications in specialty cheese and cured meat segments.
- Paper:Limited adoption concentrates in artisanal and organic product lines with minimal barrier requirements.
Plastic Films retains volume leadership. Composites show the steepest expansion trajectory as sustainability mandates intensify.
End User:
Customer type determines specification complexity, with food manufacturers demanding ISO 22000-certified systems and retailers prioritizing format standardization.
- Food Manufacturers:Protein processors in Germany and the Netherlands consolidate procurement across beef, lamb, and poultry categories. Third-party food safety management system verification stretches supplier onboarding to 12-18 months.
- Retailers:Discount supermarket chains mandate lifecycle carbon data and recyclability certifications alongside unit cost metrics, with compliance most stringent for premium beef and lamb lines.
- Food Service Providers:Institutional buyers adopt portion-controlled proteins and sous-vide preparations, a channel segment still underdeveloped relative to retail.
- Consumers:Direct-to-home meal-kit subscriptions drive small-format skin pack demand with variable SKU requirements.
Food Manufacturers dominate procurement volume. Food Service Providers are gaining share fastest as institutional buyers convert to case-ready formats.
Distribution Channel:
Geographic concentration in German-speaking markets shapes channel development, with supermarket format standardization outpacing online retail infrastructure.
- Supermarkets:German and Austrian retail chains anchor demand through centralized procurement and private-label program consolidation. Format standardization enables scale economies in film extrusion and thermoforming equipment utilization.
- Direct Sales:Protein processors supply institutional buyers and food manufacturers under long-term contracts with integrated film-tray system specifications. Sealed Air's equipment integration anchors multi-year agreements with North American meatpackers.
- Online Retail:Meal-kit providers and specialty protein e-commerce drive demand for variable-data printing and short-run flexibility.
- Convenience Stores:Limited penetration concentrates in grab-and-go prepared meals with abbreviated shelf-life requirements.
Supermarkets lead by volume. Online Retail is expanding most quickly as direct-to-consumer protein subscriptions proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German discount supermarket chains concentrate procurement power and compress supplier margins across protein packaging categories. Retail buyer consolidation in the Netherlands and Austria pulls film specifications toward standardized high-barrier constructions. Protein processor integration in North America locks in multi-year equipment-film system contracts.
Germany
Discount supermarket chains standardize vacuum skin formats across private-label beef and lamb programs. The EU Packaging and Packaging Waste Regulation mandates recyclability targets that reshape converter R&D priorities. Bavarian meatpacking clusters near Munich and Nuremberg consolidate procurement specifications, locking in multi-year film supply agreements.
United States
North American protein processors anchor demand through integrated thermoforming equipment and film supply contracts. FDA regulations under 21 CFR Parts 110 and 117 require Hazard Analysis and Critical Control Points compliance for all packaging suppliers. Midwest meatpacking corridors in Nebraska and Iowa standardize vacuum skin adoption across case-ready retail programs.
Netherlands
Chilled ready-meal manufacturers displace modified atmosphere packaging with skin formats for discount channel distribution. The EU F-Gas Regulation restricts fluorinated barrier chemistries and process gases in film extrusion. Food manufacturing clusters around Rotterdam and Utrecht accelerate adoption as meal-kit providers specify extended shelf-life performance.
China
Domestic protein processors expand vacuum skin adoption for premium beef and seafood retail programs. SAMR food contact material standards and GB compliance requirements shape barrier film import specifications. Yangtze River Delta packaging converters near Shanghai scale thermoforming capacity to serve supermarket modernization campaigns.
United Kingdom
Supermarket private-label consolidation drives format standardization across fresh meat and poultry categories. REACH restrictions on perfluorinated substances accelerate substitution programs for barrier film chemistries. Midlands food manufacturing corridors standardize specifications as retailers mandate lifecycle carbon data alongside unit cost metrics.
Vacuum Skin Packaging Market Competitive Environment
Player mix skews toward integrated film-tray system suppliers and specialized barrier film converters. The vendor base separates into three tiers: multinational packaging conglomerates with captive equipment integration, regional converters with backward integration into resin and substrate production, and niche specialists in mono-material recyclable constructions. Dominant competitive moves include strategic partnerships between film suppliers and thermoforming equipment builders, plus capacity expansion in Central European mill networks to serve German retail standardization.
Among integrated packaging conglomerates, Sealed Air anchors the equipment-film system tier through thermoforming line integration. Mondi Group exemplifies the captive substrate model with Central European mill network control. Berry Global occupies a position within multi-layer extrusion specialists serving both retail and foodservice channel requirements.
| Leading Market Players |
|---|
| Berry Global |
| Mondi Group |
| Sealed Air |
| Linpac Packaging |
| Schur Flexibles |
| Amcor |
| Coveris |
| Plastopil |
| Winpak |
| Others |
Value Chain & Pricing Dynamics
Twelve-to-eighteen-month supplier onboarding cycles for ISO 22000 certification compress pricing flexibility for new film entrants while anchoring incumbent power with German meatpackers and Dutch chilled-meal manufacturers who command volume-tier discounts.
Pricing Analysis
Cost-plus contracts indexed to ethylene and vinyl alcohol feedstock indices dominate barrier film procurement between European converters and protein processors. Three-tier pricing structure across premium recyclable mono-materials, standard multi-layer EVOH laminates, and economy-grade PE constructions separates certified sustainable lines from commodity alternatives. Pricing pressure stems from EU extended producer responsibility fees that compress margins on non-recyclable multi-layer constructions. Discount supermarket chains in Germany exhibit highest price sensitivity, while premium beef and lamb programs absorb sustainability premiums with least negotiation leverage.
Supply Chain Analysis
Germany and the Netherlands anchor high-barrier film extrusion and thermoforming equipment manufacturing for European protein packaging. EVOH barrier polymers draw from ethylene feedstock markets, while kraft paper substrates rest on Nordic pulp supply chains. Single-source vulnerability concentrates in high-capacity vacuum skin line builders clustered among limited European machinery houses. Distribution runs through centralized procurement desks at retail chains rather than fragmented regional converter relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modified atmosphere packaging retains residual share in chilled ready-meals that vacuum skin formats must displace through shelf-life and presentation advantages.
For Market Incumbents: Secure multi-year equipment-film system contracts with North American meatpackers before captive thermoforming integration spreads. Anchor backward control over barrier resin supply to offset EVOH price volatility that threatens margin stability in standardized retail specifications. For New Entrants and Emerging Players: Differentiate on mono-material recyclable certifications for Dutch discount supermarket private-label programs where sustainability mandates outpace incumbent converter adaptation. Target foodservice sous-vide and portion-controlled protein segments still underdeveloped relative to retail saturation. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because protein processor procurement concentration favors integrated film-tray system suppliers with captive equipment relationships. Watch EFSA guidance evolution on food contact materials as the signal for accelerated substitution windows that reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier R&D Investment | REACH restrictions on PFAS accelerate bio-based chemistry substitution timelines for ready-to-eat compliance. |
| Thermoforming Equipment Integration | Sealed Air's captive machinery relationships lock in multi-year protein processor contracts across Midwest meatpacking corridors. |
| Central European Mill Network Expansion | Mondi's captive kraft paper production secures standardized composite specifications for Austrian and German retail chains. |
| Digital Printing Capability Addition | Inline variable-data systems support retailer SKU proliferation under EU food information traceability mandates. |
| Foodservice Channel Development | Institutional sous-vide and portion-control formats remain underpenetrated relative to retail case-ready saturation. |
Study Parameters
A spread of perspectives from film extrusion plant managers, protein processor procurement leads, retail category buyers, thermoforming equipment engineers, and EFSA regulatory affairs specialists converged on the working assumptions driving barrier film demand projections. Primary fieldwork combined with secondary validation from EU Packaging and Packaging Waste Regulation filings, REACH annex revision tracking, and SEC disclosures from listed packaging conglomerates. Bottom-up volume modeling across material tiers triangulated against top-down protein packaging spend analysis.
Segmentation dimensions modeled include product type, material construction, end-user vertical, and distribution channel across the projection horizon. CAGRs derived from elasticity-adjusted volume trajectories incorporating EVOH resin price indices and thermoforming capacity expansion schedules. Forecast inputs weighted German retail standardization timelines and Dutch chilled-meal format conversion rates.
Forecasts assume regulatory continuity in EU F-Gas and REACH regimes; material policy shifts would require re-modeling barrier chemistry substitution curves. Recalibration cycles align with EFSA guidance updates and state-level extended producer responsibility law adoptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Patisserie Packaging Market
Packaging Solutions
India Packaging Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Advanced Packaging Market
Packaging Solutions
Global E-Commerce Packaging Market
Packaging Solutions
Europe Contract Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
Supplements and Nutrition Packaging Market
Packaging Solutions
Void Fill Packaging Systems Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
Airless Packaging Market