
 Bulb Packaging Market | 2026-2036
Bulb Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bulb Packaging Market Intelligence
The European Union's Green Deal and its emphasis on recyclable materials is expanding the market for sustainable bulb packaging solutions. Global Packaging Alliance leverages its scale to offer recycled content paperboard options to large lighting manufacturers. Shenzhen Green Plastic Products Co., Ltd specializes in developing compostable plastic alternatives for niche applications. FORMA Structural Packaging differentiates through custom-engineered molded pulp designs that provide enhanced shock absorption for premium LED bulbs.
Bulb packaging refers to the protective enclosures, including boxes, sleeves, and clamshells, designed to secure light bulbs during transit, storage, and retail display. These materials must meet specific drop-test standards and often feature clear windows made from PET to allow product visibility while preventing breakage. Cardboard and paperboard materials dominate due to cost-effectiveness and recyclability, particularly for lighting manufacturers and wholesalers. While blister packs remain a common packaging format in retail, molded pulp solutions are gaining share for high-value LED products.
The market operates under packaging waste directives like the EU's Packaging and Packaging Waste Regulation and US state-level Extended Producer Responsibility laws. Additionally, ISO 18604 standards for packaging material recycling influence design choices for manufacturers aiming for compliance in multiple jurisdictions. Future material selection will hinge on balancing protection, cost, and escalating regulatory requirements for circularity.
Market Dynamics
The central tension shaping the bulb packaging market is the collision between escalating sustainability mandates, such as the EU Green Deal, and the fundamental requirement for cost-effective, damage-resistant materials capable of withstanding global supply chain stresses.
Growth Catalysts
- LED Technology Adoption:The transition to fragile, high-value LED bulbs necessitates packaging with superior shock absorption, driving demand for engineered solutions like molded pulp and custom paperboard inserts over simple sleeves.
- Regulatory Mandates for Circularity:The EU Green Deal and its associated circular economy policies are compelling lighting brands to adopt recyclable mono-materials like paperboard, boosting the market for sustainable packaging formats.
- Manufacturing Concentration:Demand is intensifying within China's lighting and electronics manufacturing clusters, where large-scale producers require standardized, retail-ready packaging solutions that support automated assembly and global export.
Market Restraints
- Input Cost Volatility:Fluctuating prices for recycled paperboard pulp and compostable biopolymers create margin pressure for packaging converters, making it difficult to offer stable, long-term pricing to lighting manufacturers.
- Performance Gaps in Sustainable Alternatives:Sustainable clear films made from cellulose or PLA often lack the optical clarity, durability, and moisture resistance of traditional PET, hindering their use for retail window applications.
- Threat from Minimalist Packaging:A push by some retailers and environmental groups for package-free or drastically reduced secondary packaging threatens the overall volume demand for conventional bulb boxes and clamshells.
Strategic Opportunities
- Smart Packaging Integration:Incorporating QR codes or NFC tags into paperboard packaging offers opportunities for brand authentication, consumer engagement, and providing detailed recycling instructions, adding value beyond simple protection.
- Expansion into Horticultural Lighting:The burgeoning indoor and vertical farming sector requires specialized, durable, and often moisture-resistant packaging for high-wattage grow lights, representing a new application frontier.
- Geographic Expansion in Southeast Asia:As lighting manufacturing diversifies beyond China, emerging production hubs in countries like Vietnam and Thailand present an underpenetrated market for specialized packaging suppliers.
Industry Challenges
- Regulatory Fragmentation:Designing packaging that simultaneously complies with the EU's Packaging and Packaging Waste Regulation and disparate state-level Extended Producer Responsibility (EPR) laws in the United States creates significant compliance complexity and cost.
- Inconsistent Recycled Feedstock:Securing a consistent supply of high-quality, contamination-free recycled paper and pulp is a major operational hurdle, impacting the structural integrity and appearance of finished packaging products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulb Packaging Market |
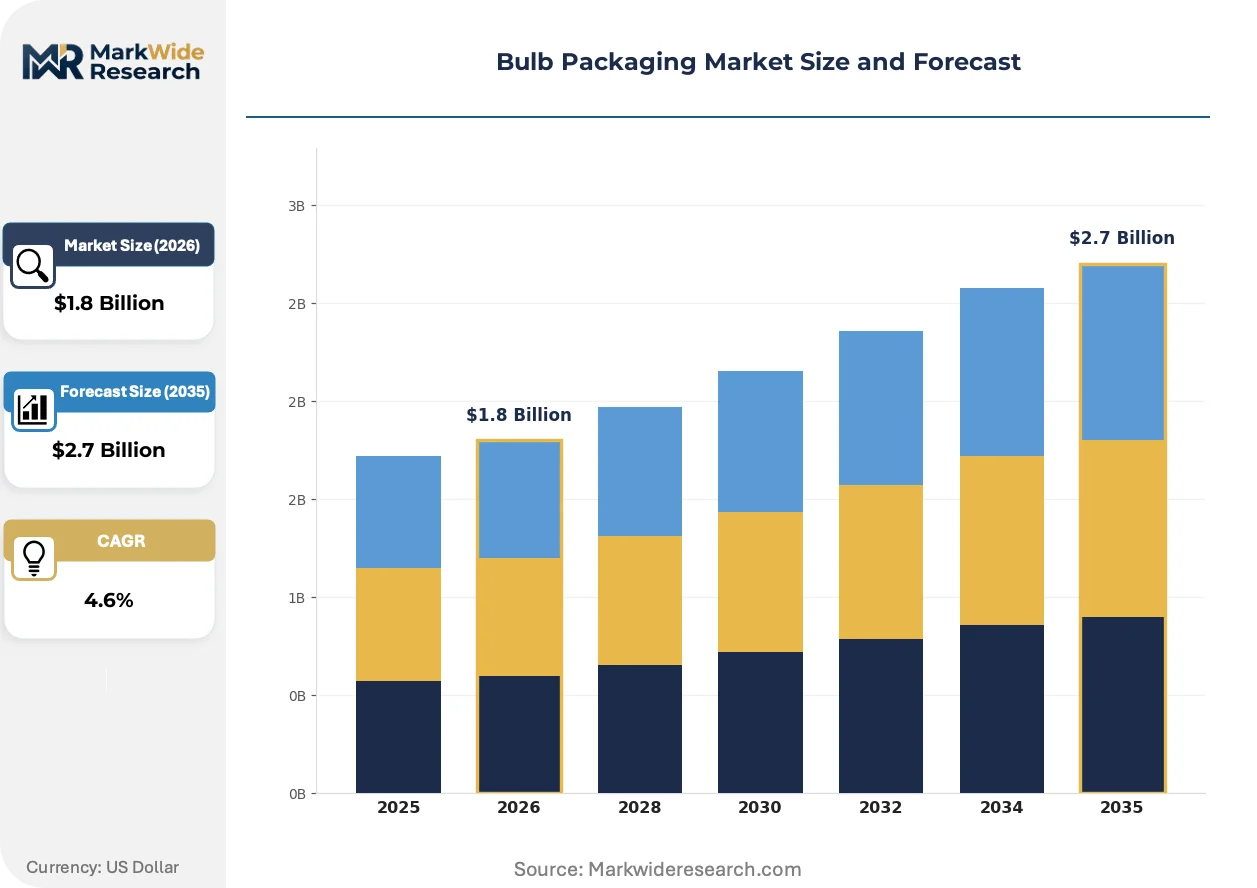
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Plastic, Foam, PET, Paperboard, Molded Pulp Packaging Format: Blister Pack, Clamshell, Box, Tube, Sleeve, Tray End User Industry: Lighting Manufacturers, Electrical Installers, Retailers, Distributors, Wholesalers, Online Sellers Distribution Channel: Direct Sales, E-commerce Platforms, Specialty Stores, Hypermarkets, Wholesale Markets, Independent Dealers |
| Companies Covered | Global Packaging Alliance, Global Printing & Packaging Co. Pvt. Ltd, Shenzhen Kaii Packaging Product Co., Ltd, Shenzhen Green Plastic Products Co., Ltd, FORMA Structural Packaging, Shenzhen Shunbaoda Plastic MFG Co., Ltd, Display4sale, Uniko Duggal, 40 Visual, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulb Packaging Market Strategic Shifts & Innovations
Material science is at the forefront of innovation, as packaging converters race to develop solutions that meet stringent new environmental regulations without compromising on product protection or cost-effectiveness. This push is creating a clear divergence between commodity and performance-tier materials.
Molded Pulp Solutions
Engineered molded pulp, derived from recycled paper or other natural fibers, provides custom-formed, highly protective cradles for delicate bulbs. Premium LED manufacturers are adopting this material to safeguard high-value products during shipping and handling. Consequently, molded pulp is overtaking traditional expanded polystyrene (EPS) foam and plastic clamshells for high-end protective applications.
Recycled Content Mandates
The EU's Packaging and Packaging Waste Regulation (PPWR) sets specific targets for the use of recycled content in packaging and promotes designs that facilitate easier recycling. This directive effectively curtails the use of composite materials and certain plastics in blister packs and windowed boxes. The paperboard and molded pulp segments are the primary beneficiaries, as lighting companies redesign packaging to ensure continued market access in Europe.
Procurement Consolidation
Large lighting corporations and big-box retailers are reducing their number of packaging suppliers to a select group of global partners. This strategy aims to standardize quality, ensure compliance across international markets, and leverage volume purchasing. This trend disadvantages smaller, regional converters unable to match the scale, R&D capabilities, or global compliance expertise demanded by these large accounts, particularly in North America and the EU.
Bulb Packaging Market Segmentation
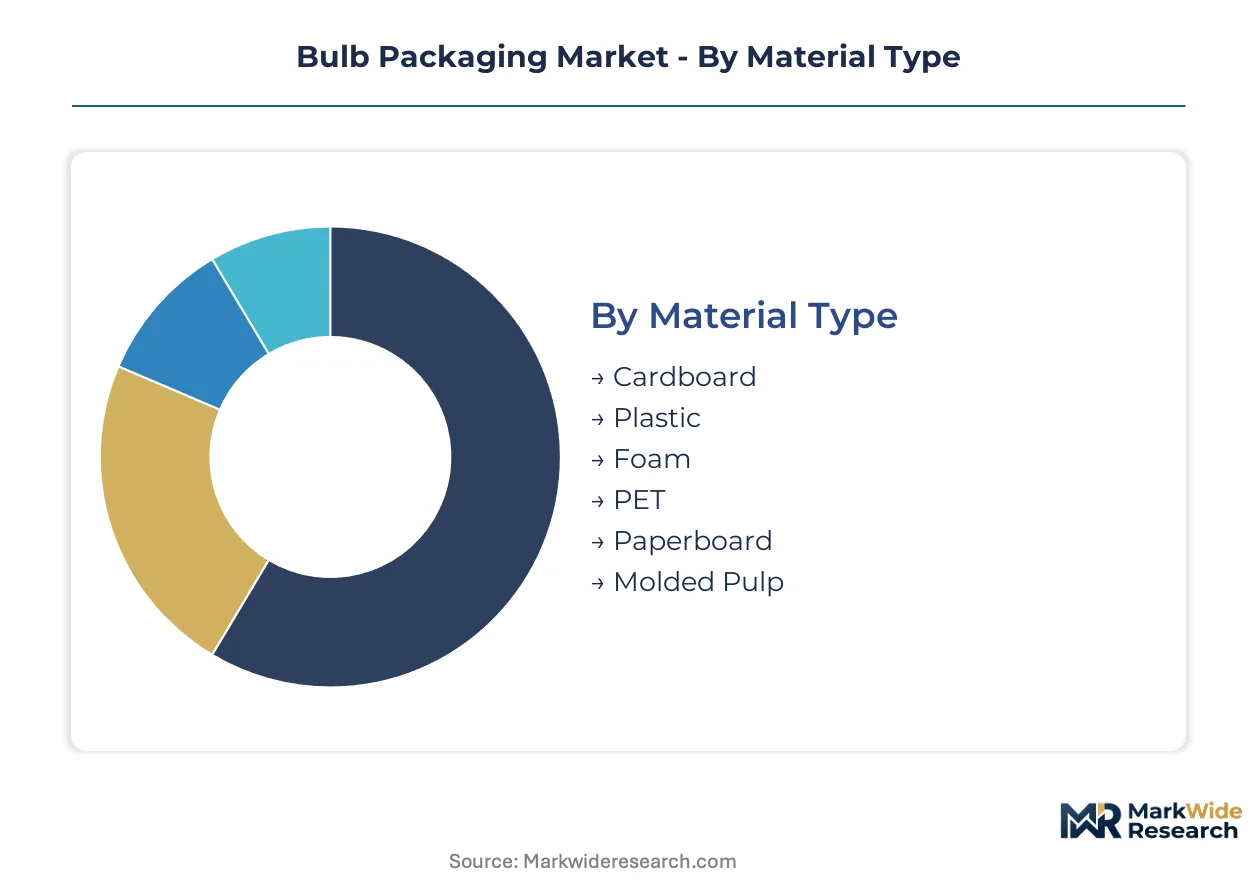
The bulb packaging market segments highlight the diverse material science and application requirements across the lighting industry. Understanding these segments helps manufacturers tailor protective solutions for both high-volume commodity lamps and high-value, fragile LED components. Material and format choices directly influence cost, protection levels, and environmental compliance.
Material Type:
The material type segmentation broadly separates high-volume, cost-effective solutions from premium, performance-driven alternatives.
- Paperboard:This material dominates the market due to its cost-effectiveness, printability, and recyclability. Demand is particularly strong in China's manufacturing clusters for standard incandescent and fluorescent bulbs, driven by requirements for automated packaging lines.
- Molded Pulp:Engineered molded pulp offers superior shock absorption and custom fit for delicate products. Premium LED manufacturers in Europe and North America increasingly adopt molded pulp to protect high-value bulbs, displacing traditional plastic foams and clamshells.
- Cardboard:Corrugated cardboard provides robust protection for bulk packaging and larger bulb formats. It finds extensive use in wholesale distribution and for shipping multiple-unit packs.
- Plastic:Various plastic types, including polypropylene and PVC, offer durability and moisture resistance. These are often used for specialized bulb types requiring enhanced protection against environmental factors.
- Foam:Expanded polystyrene (EPS) foam provides excellent cushioning against impact and vibration. It is typically employed for very fragile or irregularly shaped bulbs, though its use is declining due to environmental concerns.
- PET:Polyethylene terephthalate (PET) is primarily used for clear windows in blister packs or boxes. It provides product visibility and maintains structural integrity, especially in retail environments.
Today's leader: Paperboard. Tomorrow's challenger: Molded Pulp.
Packaging Format:
Packaging formats reflect the balance between product visibility, protection needs, and retail presentation efficiency.
- Box:Boxes are the most prevalent format, offering full enclosure, substantial surface area for branding, and stackability. Large lighting manufacturers globally use boxes for automated assembly and efficient logistics, particularly for standard and smart LED bulbs.
- Blister Pack:Blister packs combine a rigid backing card with a thermoformed plastic bubble, providing product visibility and tamper evidence. This format remains common in retail for individual bulbs in North America and parts of Europe, despite regulatory pressure on plastic use.
- Clamshell:Clamshells are two-piece hinged plastic containers that fully enclose the product. They offer excellent visibility and protection for higher-value, fragile bulbs but face increasing scrutiny under plastic waste directives.
- Sleeve:Sleeves are minimalist paperboard or plastic wrappers that cover a portion of the bulb, often leaving the bulb exposed. They are cost-effective for less fragile bulbs or as secondary packaging for multi-packs.
- Tube:Tube packaging, typically cylindrical, provides robust protection for elongated or fluorescent bulbs. These are often made from cardboard or plastic and are common in industrial and commercial lighting applications.
- Tray:Trays are flat, often thermoformed or molded pulp inserts designed to hold multiple bulbs securely within a larger box. They facilitate efficient packing and prevent contact damage during transit.
The shift towards sustainable materials is reshaping preferences for packaging formats, favoring paper-based solutions over plastic-intensive designs.
End User Industry:
Demand patterns for bulb packaging are primarily driven by the specific needs and purchasing power of various industry players.
- Lighting Manufacturers:These entities represent the largest direct consumers of bulb packaging, requiring solutions for primary packaging of their products. They prioritize cost-effectiveness, automated compatibility, and compliance with international shipping standards.
- Retailers:Retailers, especially large chains, influence packaging specifications through private label brands and shelf-ready display requirements. They focus on visual appeal, product visibility, and ease of merchandising for consumer sales.
- Distributors:Distributors handle large volumes of bulbs from various manufacturers, requiring durable and stackable packaging for efficient warehousing and transport. Their focus is on bulk packaging solutions that protect products through multiple handling points.
- Wholesalers:Wholesalers supply to smaller retailers and contractors, often needing multi-pack or bulk packaging that is easy to store and transport. Cost-efficiency and robust protection for high-volume orders are paramount for them.
- Electrical Installers:Installers typically purchase bulbs in bulk or multi-packs for specific projects. They value packaging that is easy to open, dispose of, and protects bulbs until installation.
- Online Sellers:E-commerce platforms require packaging optimized for individual parcel shipping, emphasizing robust protection against drops and vibrations. Minimalistic, frustration-free packaging is also a growing preference for online consumers.
The evolving regulatory landscape around packaging waste is significantly influencing procurement decisions across all end-user industries.
Distribution Channel:
Distribution channels dictate the specific protective features and presentation requirements for bulb packaging, influencing material and design choices.
- E-commerce Platforms:This channel demands highly protective, lightweight, and often compact packaging suitable for individual parcel shipping. Packaging must withstand multiple handling points and potential drops, with a growing emphasis on sustainable materials for consumer perception.
- Wholesale Markets:Wholesale markets primarily deal with bulk quantities, requiring durable, stackable, and cost-effective packaging for efficient storage and transport to businesses. Packaging for these markets often focuses on protection and volume efficiency over individual retail presentation.
- Direct Sales:Direct sales from manufacturers to large clients or project sites often involve customized packaging solutions. These solutions prioritize specific protection needs for high-value or specialized bulbs, ensuring safe delivery to the end user.
- Hypermarkets:Hypermarkets, or large retail stores, require packaging with strong visual appeal and shelf-ready display capabilities. Packaging must attract consumers while providing adequate protection against in-store handling and theft.
- Specialty Stores:Specialty lighting stores often stock premium or niche bulbs, favoring packaging that conveys quality and brand value. These channels may accept more elaborate or unique packaging designs.
- Independent Dealers:Independent dealers purchase from wholesalers or distributors and serve local customers. They require packaging that is easy to handle, store, and often prefer multi-packs for convenience and value.
The fastest-growing trajectory in distribution is through e-commerce platforms, which consistently reshape packaging requirements for individual unit protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The bulb packaging industry initially scaled alongside the mass production of incandescent and fluorescent lamps, particularly in regions with established manufacturing bases. This foundational period emphasized cost-effectiveness and basic product protection for high-volume consumer markets. Today, global demand patterns reflect both legacy production hubs and new regulatory pressures.
China
China's vast lighting and electronics manufacturing clusters drive significant demand for bulb packaging, particularly for automated assembly lines. The nation's GB standards influence material choices and production processes. Shenzhen and the Pearl River Delta region remain central to large-scale packaging production and global export.
Germany
Germany's focus on high-value LED products and stringent environmental policies shapes its bulb packaging market. The EU Green Deal and PPWR compel manufacturers to adopt recyclable mono-materials. Industrial centers in Southern Germany are innovating in custom-engineered packaging solutions for premium lighting brands.
United States
The United States market requires versatile packaging for diverse retail channels and a growing e-commerce sector. State-level Extended Producer Responsibility (EPR) laws increasingly influence packaging design. Manufacturing hubs in the Midwest are adapting to produce more sustainable options for major lighting brands.
Vietnam
Vietnam is emerging as a significant manufacturing hub for lighting products, driving new demand for protective bulb packaging solutions. The country's evolving national environmental policies encourage sustainable material use. Industrial parks around Ho Chi Minh City are attracting packaging suppliers to support the expanding export-oriented sector.
India
India's expanding domestic lighting market and infrastructure development projects fuel demand for cost-effective and robust bulb packaging. The Bureau of Indian Standards (BIS) guides packaging quality and safety requirements. Industrial zones in Maharashtra are witnessing increased activity in paperboard and corrugated packaging manufacturing.
Bulb Packaging Market Key Industry Players
Premium-margin players sit above commodity-margin players across product protection and material innovation in the bulb packaging market. The industry exhibits a tiered structure, with specialized providers offering high-performance solutions for delicate LED bulbs. Strategic archetypes include custom molded pulp specialists, large-scale paperboard converters, and niche compostable plastic innovators. Competitive moves often involve strategic partnerships to secure sustainable material supply chains and geographic expansion into emerging manufacturing hubs.
Global Packaging Alliance represents large-scale paperboard converters, leveraging its extensive network to serve major lighting manufacturers with standardized and recyclable options. Shenzhen Green Plastic Products Co., Ltd. exemplifies the niche innovators, specializing in compostable plastic alternatives for specific applications, particularly in regions with strong sustainability mandates. FORMA Structural Packaging occupies a position among premium solution providers, known for custom-engineered molded pulp designs that enhance shock absorption for high-value LED products, often displacing traditional plastic foams in Europe and North America.
| Leading Market Players |
|---|
| Global Packaging Alliance |
| Global Printing & Packaging Co. Pvt. Ltd |
| Shenzhen Kaii Packaging Product Co., Ltd |
| Shenzhen Green Plastic Products Co., Ltd |
| FORMA Structural Packaging |
| Shenzhen Shunbaoda Plastic MFG Co., Ltd |
| Display4sale |
| Uniko Duggal |
| 40 Visual |
| Others |
Cost & Logistics Intelligence
LED technology adoption simultaneously reshapes cost economics and concentrates specialized packaging supply. This shift necessitates higher-performance materials, influencing procurement strategies and pricing across the bulb packaging market.
Pricing Analysis
Contract-based pricing structures dominate the bulb packaging market, especially for large lighting manufacturers. Price differentiation stems from material quality grade, customization level, and volume scale. Pricing softness reflects input cost volatility for recycled paperboard pulp, creating margin pressure for packaging converters. Lighting manufacturers, particularly those producing commodity bulbs, exhibit high price sensitivity, while premium LED brands prioritize protection and design.
Supply Chain Analysis
Logistics and freight costs significantly impact bulb packaging supply chains, particularly for bulky materials like paperboard and molded pulp. Geographic supply concentration centers in China, Vietnam, and Germany, reflecting global manufacturing hubs. The supply chain relies heavily on recycled paper and plastic resins as primary inputs. Commodity price volatility for these raw materials presents a structural supply chain risk. Distribution runs through a globalized network of packaging converters and regional logistics hubs, serving diverse end-user industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bulb packaging market functions as a stable compounder, driven by the continuous global transition to LED lighting and escalating sustainability mandates.
For Market Incumbents:To counter regulatory fragmentation, large packaging converters must invest in modular designs compliant with multiple global standards. Consolidate material sourcing to secure consistent supply of high-quality recycled content, mitigating input cost volatility. Expand R&D into next-generation compostable biopolymers for niche applications. Leverage existing global networks to offer standardized sustainable solutions to multinational lighting brands.
For New Entrants and Emerging Players:Begin with specialized solutions for high-growth, underserved segments like horticultural lighting, focusing on moisture resistance and durability. Target emerging manufacturing hubs in Southeast Asia, such as Vietnam, with localized production capabilities. Differentiate through custom-engineered molded pulp designs offering superior product protection for high-value LED components. Focus on certifications like ISO 18604 to gain market entry and build credibility.
For Investors and Strategic Acquirers:Valuations sit cheapest among regional packaging converters lacking global compliance expertise or proprietary sustainable material technologies. Seek out custom molded pulp specialists with established intellectual property in shock absorption and design for high-value LED products. A key signal to watch is the consistent enforcement of recycled content mandates in major markets like the EU, driving demand for compliant packaging solutions. Focus on companies with robust R&D pipelines in circular materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Bio-based Clear Films | This initiative provides sustainable alternatives to PET for retail window applications. |
| Expand Molded Pulp Capacity in Europe | This move supports premium LED manufacturers adhering to EU Green Deal mandates. |
| Integrate QR Codes for Traceability | This enhancement offers brand authentication and detailed recycling instructions for consumers. |
| Form Strategic Partnerships in Southeast Asia | This action capitalizes on lighting manufacturing diversification beyond China. |
| Invest in Automated Packaging Line Compatibility | This ensures seamless integration for large lighting manufacturers requiring efficient assembly. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to construct this market analysis. The study involved extensive discussions with industry stakeholders, including lighting manufacturers, packaging converters, retailers, and distributors, to gather qualitative insights. Secondary validation drew from regulatory filings, trade association reports, and customs data, ensuring a robust bottom-up and top-down triangulation of market figures.
The forecast framework cross-referenced historical market data with expert panel input to project future trends across the analysis window. Segmentation dimensions modeled included material type, packaging format, end-user industry, distribution channel, and regional production hubs. Compound annual growth rates were derived by analyzing the interplay of LED adoption rates, recycled content mandates, and evolving consumer preferences for sustainable packaging throughout the forecast period.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts and rapid, disruptive technological breakthroughs in lighting or packaging materials. Forecasts reflect assumptions documented through extensive research and analysis. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
PET Material Packaging Market
Packaging Materials
Production Page Volume Market
Packaging Materials
Sterilization Roll Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Foam Trays Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Refrigerator Door Seal Gaskets Market
Packaging Materials
Global Liquid Packaging Market
Packaging Materials
Textile Packaging Market
Packaging Materials
Cold Chain Packaging Materials Market
Packaging Materials
PVC Packing Straps Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
MDO Films Market
Packaging Materials
Global Food Processing Seals Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Laminated Tubes Market