
 Packaging Inserts Market | 2026-2036
Packaging Inserts Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Inserts Market Analytics
Aftermarket insert customization revenue is fragmenting across specialized converters and integrated packaging groups. Smurfit Kappa leverages its European corrugated network to control recycled paper insert supply chains. Sealed Air sustains technology leadership in automated inflatable systems for void-fill applications. DS Smith anchors its position through design-led protective inserts targeting premium electronics brands.
Packaging inserts are engineered components placed inside primary or secondary packaging to stabilize, cushion, present, or communicate product information during transit and shelf display; common specifications include basis weights from 150–400 gsm for paperboard inserts and densities of 1–3 lb/ft³ for expanded polystyrene foam cushions, with die-cutting, thermoforming, and injection molding as dominant fabrication methods. Foam material types command premium margins in electronics and pharmaceutical end uses where shock absorption and contamination control are critical. Automated insertion methods are expanding fastest as labor costs rise and throughput requirements tighten across fulfillment centers. Paper-based formats remain the mature volume backbone, though plastic alternatives retain share in moisture-sensitive applications.
The EPA governs recycled content claims under its Comprehensive Procurement Guidelines, while the EU Packaging and Packaging Waste Regulation mandates extended producer responsibility schemes that reshape material selection across export-bound supply chains. FDA compliance requirements for pharmaceutical inserts impose serialization and tamper-evidence standards that filter equipment investment decisions. Stakeholders must monitor how divergent recycling infrastructure investments across North American and European jurisdictions reshape total cost of ownership for multi-material insert designs.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material substitution decisions across export supply chains, compressing lead times for compliant insert designs while automated fulfillment centers demand higher throughput compatibility.
Growth Catalysts
- E-commerce fulfillment automation:Robotic pick-and-place systems require standardized insert dimensions, driving demand for precision-die-cut paperboard formats in German and Dutch distribution hubs.
- Extended producer responsibility schemes:The EU mandate on material recovery quotas is accelerating recycled-content adoption in corrugated and molded fiber inserts across member states.
- Pharmaceutical serialization requirements:FDA tamper-evidence standards for drug packaging are expanding demand for integrated insert-and-label combinations in US-based contract manufacturing.
Market Restraints
- Recycled pulp supply concentration:European recovered paper markets cluster in Nordic and German mills, exposing converters to price volatility when export demand from Asia surges.
- Multi-material recycling infrastructure gaps:Laminated paper-plastic hybrid inserts face limited sorting compatibility with existing municipal waste streams in North American jurisdictions.
- Biodegradable polymer performance ceilings:PLA and PHA foams remain structurally inferior to expanded polystyrene for high-impact electronics cushioning below 10°C.
Strategic Opportunities
- Indian pharmaceutical export growth:CDSCO-aligned serialization mandates for cold-chain biologics are creating demand for temperature-stable insert materials in Mumbai and Hyderabad manufacturing corridors.
- Digital printing convergence:Variable-data inkjet on corrugated inserts enables batch-specific regulatory text without plate changes, compressing pharmaceutical changeover times.
- Direct-to-consumer unboxing optimization:Premium cosmetics brands in France and Italy are commissioning design-led insert systems as shareable social media assets.
Industry Challenges
- Automation engineering talent scarcity:Fulfillment centers in the US and Germany struggle to source technicians capable of calibrating vision-guided insert placement systems.
- Cross-border regulatory misalignment:Divergent FDA and EMA serialization formats force dual-sku insert inventories for multinational pharmaceutical shippers.
- Legacy ERP integration friction:Mid-tier converters face capex barriers connecting digital print workflows to existing MRP systems for lot-traceable insert production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Inserts Market |
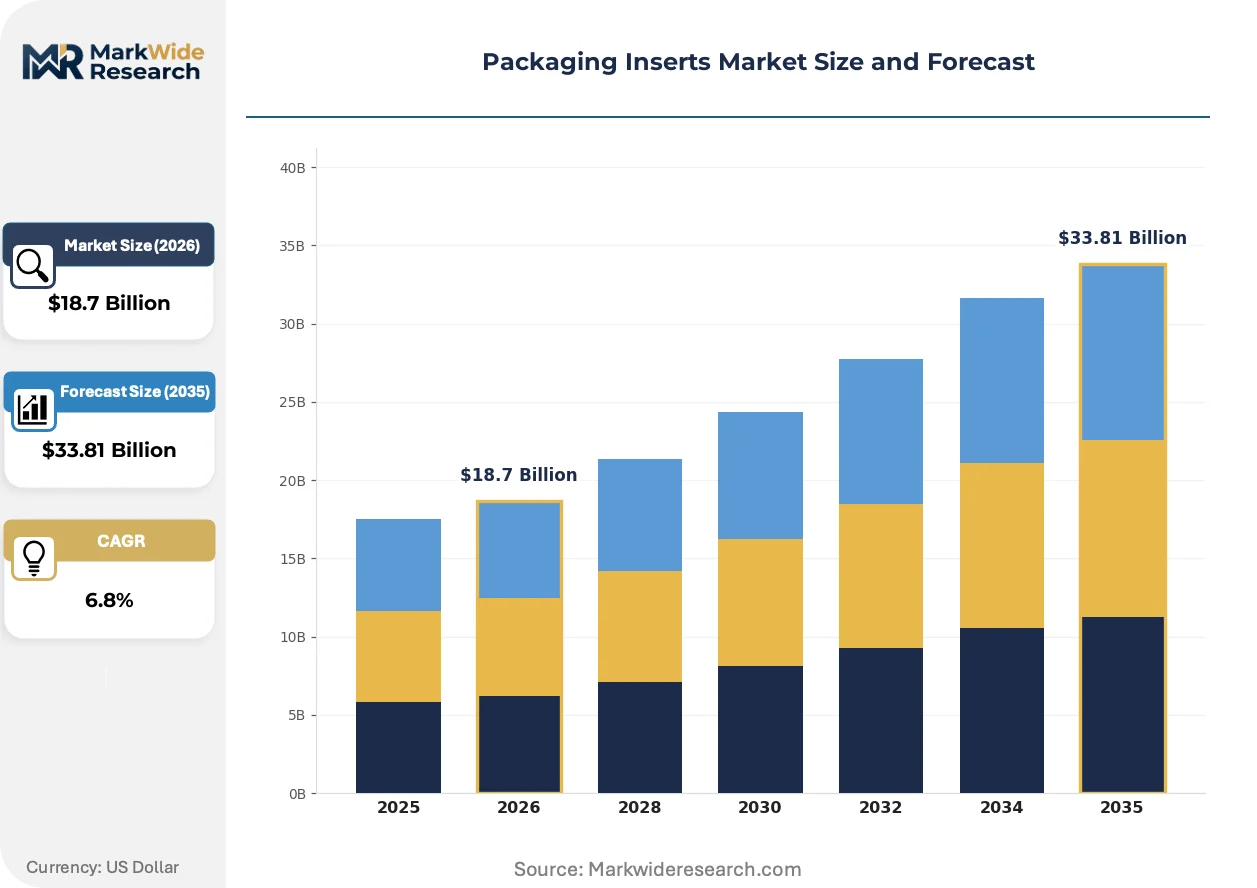
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Plastic, Foam, Metal Insertion Method: Manual, Automated, Semi-Automated, Robotic End Use: Food & Beverage, Cosmetics, Electronics, Pharmaceuticals Packaging Format: Boxed, Bagged, Padded, Tubed |
| Companies Covered | Smurfit Kappa, Sealed Air, DS Smith, Sonoco Products Company, Pregis LLC, Reflex Packaging Inc., Mondi Group, Cascades Inc., Innerpak Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Inserts Market Evolving Landscape
Computational design tools and regulatory pressure on material circularity are converging to reshape how protective and communicative inserts are engineered, produced, and recovered across end-use verticals.
Generative design software is virtualizing structural optimization for protective inserts, allowing algorithms to iterate rib patterns and wall thicknesses that minimize material use while maintaining drop-test performance. Appliance and consumer electronics manufacturers in South Korea and Japan are adopting these tools to reduce foam densities by 15-30% without prototyping cycles. The technology is virtualizing the traditional mold-flow simulation bottleneck, compressing development timelines from weeks to days.
The EU Green Deal's packaging waste reduction targets are tightening recycled-content thresholds and banning specific single-use formats by 2030. This policy architecture is redirecting R&D investment toward fiber-based alternatives and solvent-free adhesive systems in German and French converter networks. Pharmaceutical and food-contact applications face the steepest compliance ramps, with EFSA migration testing protocols now extending to insert-to-product surface contact scenarios.
Unboxing experience design is emerging as a discrete purchasing criterion for direct-to-consumer brands, displacing purely functional procurement specifications. Beauty and wellness companies in California and New York are commissioning insert systems with nested product cradles, peel-reveal messaging sequences, and QR-linked digital content. This behavior concentrates spend in design-forward converter relationships rather than commodity die-cut suppliers, elevating margin capture for studios with industrial design capabilities.
Packaging Inserts Market Segmentation
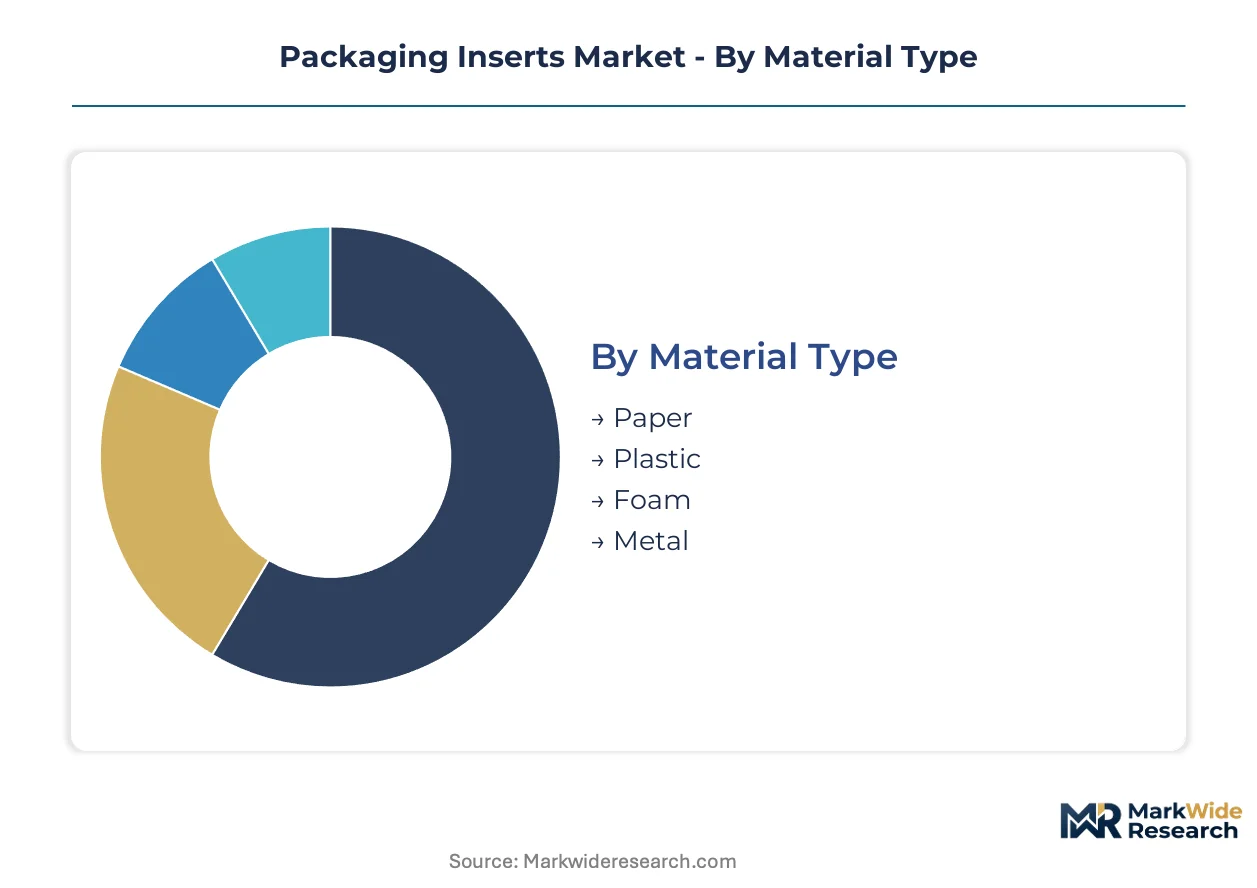
Packaging insert procurement varies sharply by operational context, with material selection and insertion method decisions driven by product fragility, regulatory exposure, and fulfillment velocity requirements. Segment boundaries blur where hybrid formats emerge, yet distinct cost-performance trade-offs govern buyer behavior across end-use verticals.
Material Type:
After-sales service intensity diverges materially across substrate categories, with foam and plastic formats demanding specialized recovery programs while paper-based systems integrate into standard municipal streams.
- Paper:Corrugated and solid fiberboard inserts dominate volume through recycled-content grades of 150–400 gsm basis weight. German distribution centers specify FSC-certified kraft liners for e-commerce void-fill applications where automated case erectors process standardized die-cut dimensions. By volume, paper leads. By growth pace, molded fiber alternatives are climbing the fastest as EU Green Deal mandates tighten.
- Plastic:Polyethylene terephthalate (PET) and polypropylene (PP) thermoformed trays retain share in moisture-sensitive pharmaceutical and food-contact applications where fiber alternatives risk dimensional instability. Dutch cold-chain logistics operators specify multi-layer barrier films for temperature-sensitive biologics where condensation control is critical.
- Foam:Expanded polystyrene (EPS) and polyurethane (PU) cushions command premium positioning in electronics and medical device packaging where drop-test performance below 10°C is non-negotiable.
- Metal:Aluminum and steel insert formats serve niche aerospace and precision instrumentation applications requiring electromagnetic shielding or static dissipation properties.
Material substitution pressure from extended producer responsibility schemes is compressing plastic share in European export supply chains while foam retains defensive positioning in high-value electronics corridors.
Insertion Method:
Capital intensity and labor cost differentials stratify the competitive landscape, with automated and robotic systems capturing investment flows in high-throughput fulfillment environments while manual methods persist in short-run, high-mix operations.
- Manual:Hand-placement of inserts persists in artisanal cosmetics and premium gift packaging where tactile assembly supports unboxing experience design. French perfume houses in Grasse maintain manual insertion for limited-edition releases where robotic standardization would compromise brand ritual.
- Automated:Pneumatic and servo-driven insertion systems process 200+ cases per minute in German and Dutch distribution hubs serving pan-European e-commerce networks. Robotic pick-and-place integration demands precision-toleranced insert dimensions within ±0.5 mm to prevent jamming in vision-guided feeding mechanisms.
- Semi-Automated:Operator-fed systems with automated placement cycles bridge volume gaps for mid-tier converters serving regional pharmaceutical contract manufacturers.
- Robotic:Collaborative robots with force-torque sensing execute delicate insert placement for irregular product geometries in electronics assembly-to-order operations.
Semi-automated formats retain installed base dominance among mid-market converters, yet robotic installations are expanding most quickly as labor scarcity intensifies across US and German fulfillment labor markets.
End Use:
Regulatory exposure and product value density create divergent procurement specifications, with pharmaceutical and electronics applications imposing the most stringent material traceability and performance certification requirements.
- Food & Beverage:Fiber-based inserts with grease-resistant coatings serve quick-service restaurant packaging and meal-kit subscription boxes where FDA and EFSA migration limits govern direct food contact scenarios.
- Cosmetics:Design-forward unboxing systems with nested cradles and peel-reveal sequences command premium positioning among direct-to-consumer beauty brands in California and New York.
- Electronics:Anti-static foam and corrugated combinations protect high-value consumer devices and industrial components through multi-drop distribution networks. South Korean appliance manufacturers specify generative-designed rib patterns that reduce material density 15–30% without compromising impact absorption.
- Pharmaceuticals:Integrated insert-and-label combinations with serialization compliance support FDA tamper-evidence mandates and EMA track-and-trace requirements for US and EU export shipments.
Electronics generates the highest absolute insert spend per unit, though pharmaceutical applications are gaining share fastest as serialization mandates expand across Indian and Southeast Asian manufacturing corridors.
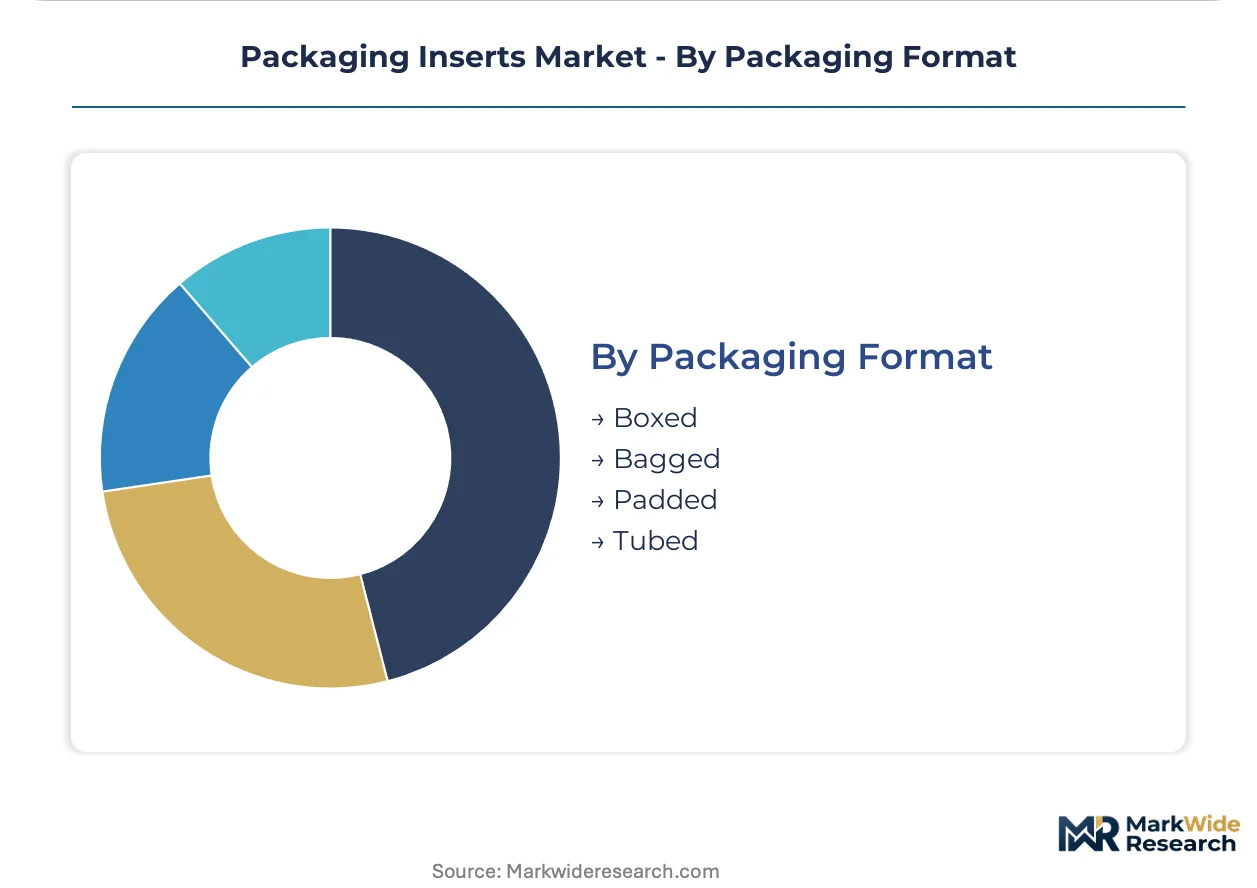
Packaging Format:
Dimensional standardization and protective performance requirements vary by primary container geometry, with boxed formats commanding systems integration complexity while flexible formats demand specialized conformable materials.
- Boxed:Rigid corrugated cases accommodate the full spectrum of insert materials and insertion methods, from simple folded paperboard separators to multi-component foam-and-film cushioning systems. German automated packaging lines process standardized RSC case formats with insert placement tolerances matched to robotic end-effector specifications.
- Bagged:Flexible polyethylene and polypropylene mailers require low-profile paper or thin-gauge foam inserts that compress during sealing without creasing or tearing. E-commerce apparel and soft-goods fulfillment centers in the Netherlands specify tissue-fiber inserts that double as presentation layers.
- Padded:Bubble-lined and foam-lined envelopes integrate protective layers as primary container elements rather than discrete inserts, blurring category boundaries in lightweight electronics and accessory shipping.
- Tubed:Cylindrical paperboard and composite tubes serve premium spirits, cosmetics, and industrial components where rolled or disc-shaped inserts stabilize contents against axial and radial movement.
Boxed formats retain volume leadership across all material categories, yet bagged configurations are expanding most quickly as apparel e-commerce penetration deepens and flexible packaging automation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for commodity paperboard inserts peaks in high-volume e-commerce corridors, while premium foam specifications in electronics and pharmaceutical cold-chain applications show inelastic demand even under cost pressure.
United States
FDA tamper-evidence mandates for pharmaceutical serialization drive integrated insert-and-label procurement among contract manufacturers near Philadelphia and New Jersey. EPA Comprehensive Procurement Guidelines govern recycled-content claims for paperboard formats. The Midwest distribution corridor spanning Ohio and Illinois anchors automated insertion equipment deployments serving pan-American e-commerce networks.
Germany
EU Packaging and Packaging Waste Regulation enforcement compresses lead times for compliant corrugated designs across Bavarian and North Rhine-Westphalian converter networks. Extended producer responsibility quotas accelerate molded fiber substitution for plastic formats. The Rhine-Main logistics cluster around Frankfurt operates Europe's densest concentration of vision-guided robotic insert placement systems.
China
Dual carbon policy targets and GB standards for packaging recyclability redirect investment toward fiber-based alternatives in Yangtze River Delta manufacturing zones. NMPA pharmaceutical serialization requirements expand demand for track-and-trace compatible insert systems. Shenzhen and Dongguan electronics assembly corridors sustain premium foam cushioning specifications despite material substitution pressure elsewhere.
India
CDSCO-aligned serialization mandates for cold-chain biologics create demand for temperature-stable insert materials in Mumbai and Hyderabad pharmaceutical manufacturing corridors. BIS standards for food-contact packaging govern migration limits in fiber-based formats. The Delhi-NCR logistics hub is expanding automated fulfillment infrastructure for domestic e-commerce penetration.
Japan
METI circular economy roadmaps and JIS packaging standards drive lightweighting investments in consumer electronics protective formats. PMDA pharmaceutical track-and-trace requirements mirror FDA serialization complexity for export-bound shipments. The Chubu region around Nagoya anchors generative design tool adoption for appliance insert optimization.
Packaging Inserts Market Competitive Landscape
Capability concentration sits with design-led specialists commanding premium positioning in pharmaceutical and cosmetics unboxing applications; scale advantage sits with integrated packaging groups leveraging continental corrugated networks for cost-competitive e-commerce fulfillment. The vendor base stratifies across three archetypes: fiber-based commodity converters, automated protective systems engineers, and experience-design studios serving direct-to-consumer brands. Dominant competitive moves include backward integration into recovered pulp supply chains and technology licensing partnerships for digital print workflows.
Within the integrated packaging tier, Smurfit Kappa and DS Smith exemplify scale-driven positions anchored in European corrugated infrastructure. Sealed Air occupies a distinct archetype as a protective systems specialist with technology leadership in automated inflatable formats. These three represent the structural fault lines between fiber-based volume plays and engineered protective solutions, with each archetype pursuing divergent capability investments rather than direct segment overlap.
| Leading Market Players |
|---|
| Smurfit Kappa |
| Sealed Air |
| DS Smith |
| Sonoco Products Company |
| Pregis LLC |
| Reflex Packaging Inc. |
| Mondi Group |
| Cascades Inc. |
| Innerpak Inc. |
| Others |
Value Network & Pricing Analysis
Nordic and German recovered paper mills anchor raw material supply for European corrugated insert converters, concentrating margin capture upstream while downstream packaging groups compete on automated fulfillment compatibility and design-led service tiers. This upstream clustering exposes mid-tier converters to pulp price volatility when Asian export demand surges, compressing their ability to pass through cost increases to e-commerce fulfillment customers locked into annual contract structures.
Pricing Analysis
After-sales insert customization and recovery program revenue drives lifetime value differentiation across supplier tiers. Three-tier pricing structure across premium, standard, and economy levels separates generative-design studios serving cosmetics unboxing experiences from commodity die-cut suppliers and automated protective systems engineers. Cost compression in standard paperboard formats is intensifying because EU Green Deal recycled-content mandates require capital-intensive coating and barrier technology upgrades. Pharmaceutical and cold-chain logistics buyers show the least price sensitivity due to FDA and EMA serialization compliance requirements, while apparel e-commerce fulfillment centers negotiate aggressively on void-fill paperboard specifications.
Supply Chain Analysis
Extended payment terms from German and Dutch distribution hub operators strain converter working capital cycles, particularly for mid-tier suppliers lacking supply-chain finance facilities. Raw material sourcing draws from Swedish and Finnish pulp mills, German recovered paper processors, and Chinese molded fiber equipment manufacturers. Single-source vulnerability concentrates in Nordic bleached kraft pulp for pharmaceutical-grade inserts. Distribution runs through Rhine-Main logistics clusters and pan-European courier networks, with secondary nodes emerging in US Midwest distribution corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automation engineering talent for vision-guided insert placement systems represents the critical capability gap constraining fulfillment center expansion, with technician scarcity in Germany and the US Midwest creating bottlenecks that favor suppliers with in-house training academies and certified service networks.
For Market Incumbents: Harden defensive positioning through backward integration into recovered pulp supply chains and captive production of solvent-free adhesive systems for EU Green Deal compliance. Consolidate design-forward converter relationships in French and Italian cosmetics corridors before experience-design studios scale industrial design capabilities. Capacity addition in Indian pharmaceutical manufacturing zones around Mumbai and Hyderabad captures CDSCO serialization mandate timing. For New Entrants and Emerging Players: Mid-market semi-automated insertion equipment for regional pharmaceutical contract manufacturers represents the most penetrable entry point, bridging the gap between manual assembly and fully robotic systems. Temperature-stable insert materials for Indian cold-chain biologics offer a second white-space target with lower incumbent saturation. Go-to-market positioning should emphasize rapid ERP integration capabilities to address legacy MRP connection friction among mid-tier converters. For Investors and Strategic Acquirers: Capital is best deployed toward design-led protective insert specialists with pharmaceutical serialization expertise and established EMA track-and-trace compliance frameworks. Long-term viability hinges on regulatory adaptation velocity rather than scale economies alone. Watch for inflection when EU member state extended producer responsibility enforcement timelines accelerate material substitution decisions in export supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Pulp | Smurfit Kappa's Nordic mill network secures FSC-certified kraft liner supply for German automated packaging lines. |
| Generative Design Tool Adoption | South Korean appliance manufacturers reduce foam densities 15-30% through algorithmic rib pattern optimization. |
| Digital Print Workflow Licensing | Variable-data inkjet on corrugated inserts compresses pharmaceutical batch changeover times without plate changes. |
| Robotic Insert Placement Deployment | Frankfurt logistics clusters operate Europe's densest concentration of vision-guided systems for e-commerce fulfillment. |
| Molded Fiber Capacity Expansion | EU Green Deal packaging waste reduction targets redirect R&D investment toward fiber-based plastic alternatives. |
Research Methodology
Cross-validation between converter production data and fulfillment center equipment procurement records anchors the qualitative findings in operational reality. Primary interviews with corrugated plant managers, pharmaceutical packaging engineers, e-commerce logistics directors, and aftermarket service heads combined with secondary validation from EU Packaging and Packaging Waste Regulation filings, EPA Comprehensive Procurement Guidelines, FDA drug packaging guidance documents, and customs trade data. Bottom-up capacity modeling and top-down demand estimation triangulate volume figures across the analysis window.
Calibration against historical insertion equipment deployment rates and material substitution elasticities shapes the projection framework. Segmentation dimensions include material type, insertion method, end-use vertical, and packaging format, with regulatory compliance tier modeled as an industry-specific overlay. CAGRs derive from trend extrapolation moderated by policy enforcement timelines and technology adoption S-curves. Forecast inputs incorporate EU Green Deal packaging waste reduction targets and CDSCO serialization mandate implementation pacing.
Macroeconomic conditions sit as an overlay; deviation in pulp commodity prices, cross-border logistics costs, or capital equipment investment cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology performance maturation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Twist Tie Market
Packaging Materials
Reel in Box Market
Packaging Materials
Latin America Single-Use Packaging Market
Packaging Materials
Global Liquid Packaging Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
Mylar Market
Packaging Materials
Standard Liner Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
VCI Films Market
Packaging Materials
Organic Substrate Packaging Material Market
Packaging Materials
Cavitated Films Market
Packaging Materials
Packaging Supplies Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Box and Carton Overwrap Films Market
Packaging Materials
Tube Packaging Market
Packaging Materials
Cohesive Packaging Market