
 PET Packaging Market | 2026-2036
PET Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
PET Packaging Market Analysis
Buyer concentration among multinational beverage and food brand owners is pivoting toward consolidated procurement contracts with fewer packaging vendors. Amcor plc leverages its integrated film-to-bottle manufacturing network to capture these consolidated accounts. Berry Global sustains competitive pressure through geographic density in North American blow molding operations. Graham Packaging Company anchors its position with dedicated on-site production partnerships at major beverage bottling facilities.
PET packaging comprises polyethylene terephthalate containers formed through stretch blow molding, injection molding, or thermoforming of resin with intrinsic viscosity typically ranging from 0.70 to 0.84 dL/g, engineered to provide gas barrier properties for carbonated and non-carbonated contents. Bottles dominate product type volumes due to entrenched beverage industry specifications, while trays represent the fastest-expanding category as fresh protein and produce retailers adopt modified-atmosphere configurations. Rigid packaging commands the largest share within packaging type classifications, though resealable formats are gaining structural importance in personal care and household segments where dispensing convenience drives repeat purchase.
FDA food-contact notification requirements and EU REACH compliance obligations constrain resin additive selections and recycling stream certifications for suppliers accessing regulated jurisdictions. EFSA evaluations of recycled PET processes for food-contact applications are reshaping investment priorities for European converters. Stakeholders must monitor evolving extended producer responsibility frameworks and deposit-return system expansions to align capacity planning with collection infrastructure development cycles.
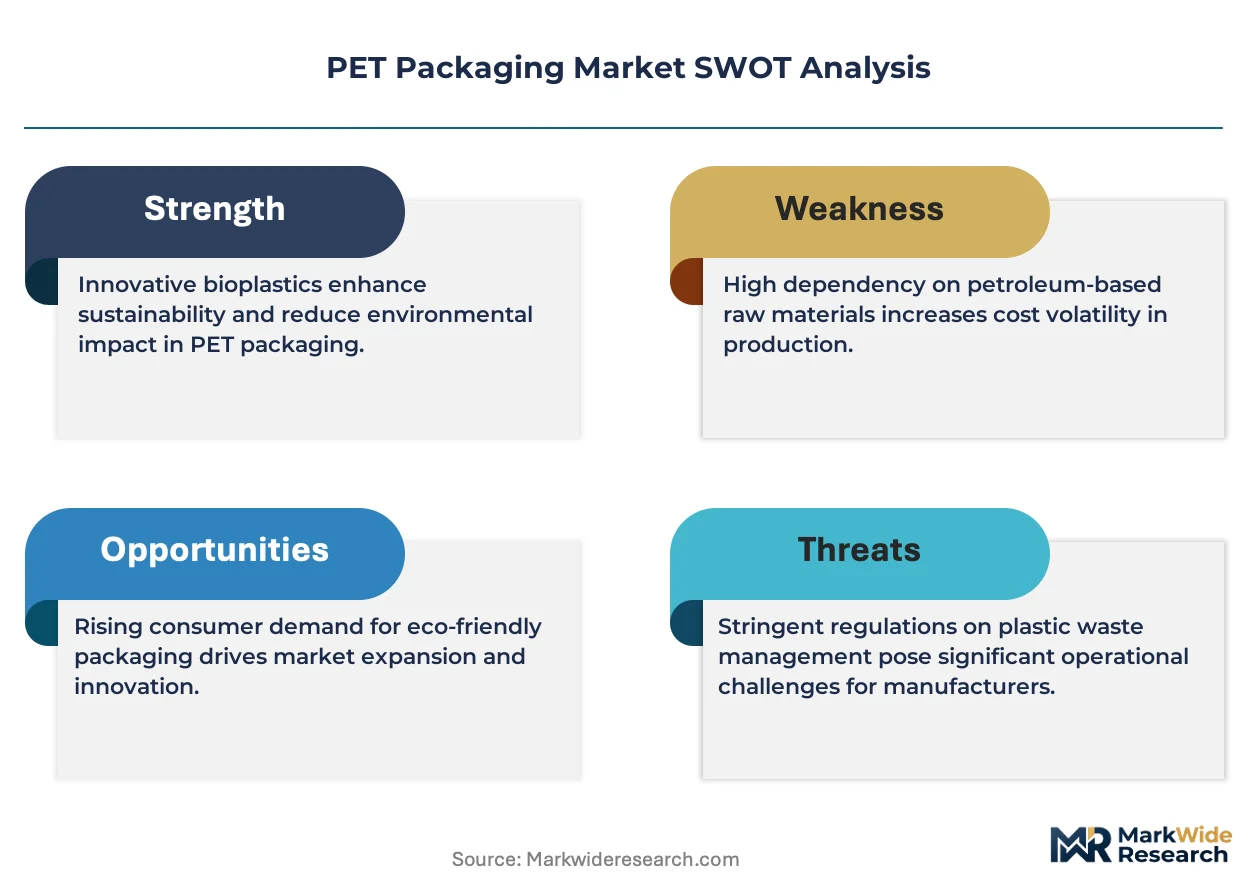
Market Dynamics
Consolidated procurement contracts among multinational beverage and food brand owners are compressing vendor counts and forcing converters to integrate film-to-bottle capabilities or risk volume attrition.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recycled content targets for PET bottles are accelerating investment in rPET processing infrastructure across European converter networks.
- India urban retail expansion:Organized retail penetration in Tier-1 and Tier-2 cities is driving packaged food and beverage container demand at double-digit rates.
- Stretch blow molding automation:High-speed electric machine platforms are reducing cycle times and enabling thinner-wall designs without sacrificing top-load strength.
Market Restraints
- PTA-MEG feedstock volatility:Purified terephthalic acid and monoethylene glycol prices fluctuate with crude oil and paraxylene spreads, compressing converter margins unpredictably.
- Collection infrastructure gaps:Inadequate post-consumer PET recovery systems in emerging economies limit rPET feedstock availability for food-contact applications.
- Aluminum can substitution:Beverage brand owners are expanding canning lines for sparkling water and craft beverages, displacing PET in premium carbonated segments.
Strategic Opportunities
- ASEAN underpenetration:Vietnam, Indonesia, and Philippines packaged food sectors remain below 40% PET conversion rates for shelf-stable applications.
- Modified-atmosphere trays:Fresh protein retailers in North America and Europe are adopting barrier-coated PET thermoforms to replace EPS and PVC.
- Deposit-return system expansion:California, Oregon, and New York are implementing or expanding bottle bill frameworks that improve rPET quality and supply security.
Industry Challenges
- Food-contact certification timelines:EFSA and FDA novel substance notifications for recycled content additives require 18-36 month evaluation cycles, delaying product launches.
- Blow molding technician scarcity:Electric machine programming and lightweighting process engineering expertise concentrates among aging workforces in mature markets.
- Legacy equipment integration:Hybrid rPET processing lines must accommodate varying intrinsic viscosity and contamination levels without retrofitting entire extrusion systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Packaging Market |
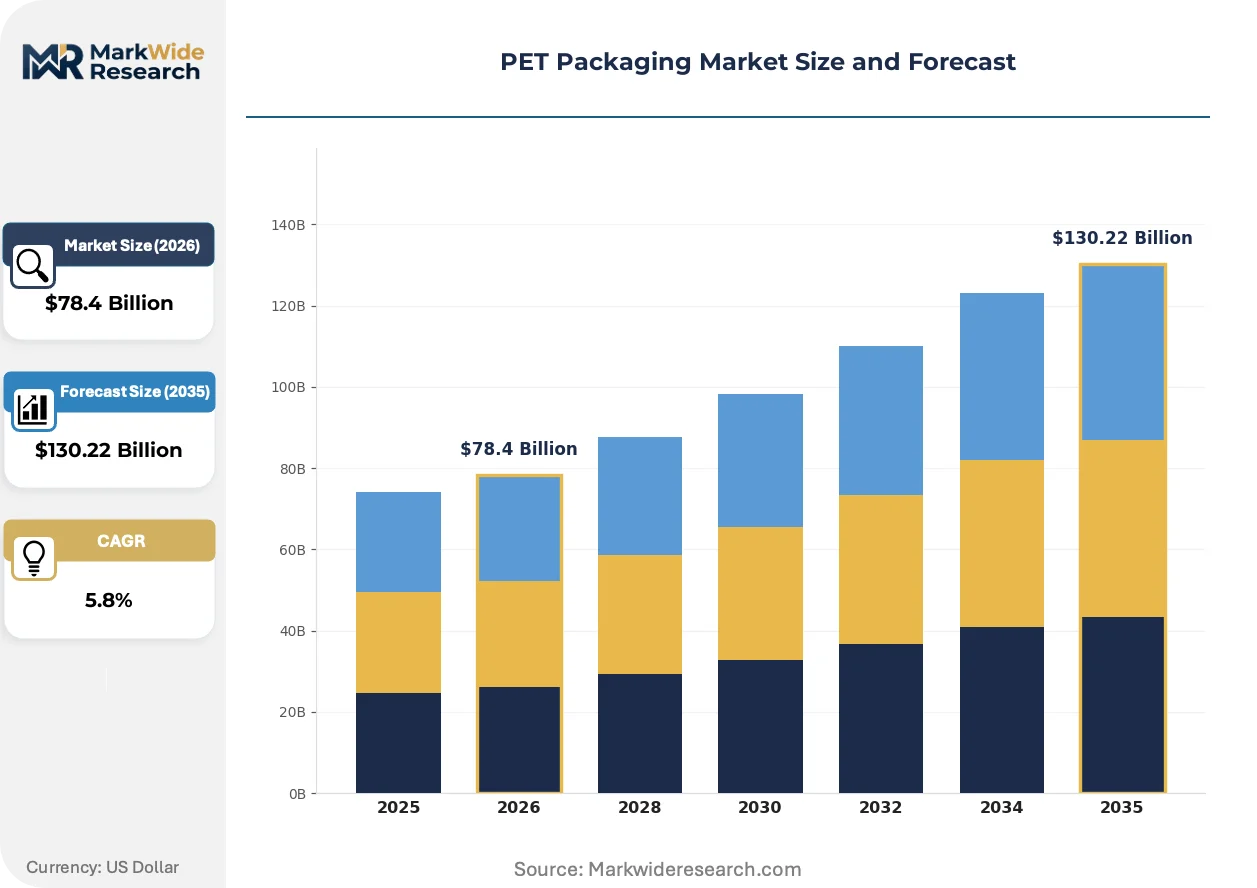
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Trays, Containers End User: Food and Beverage, Personal Care, Pharmaceuticals, Household Products Packaging Type: Flexible Packaging, Rigid Packaging, Resealable Packaging, Tamper-Evident Packaging Technology: Blow Molding, Injection Molding, Thermoforming, Extrusion |
| Companies Covered | Amcor plc, Berry Global, Graham Packaging Company, Silgan Holdings Inc., Gerresheimer AG, Huhtamäki Oyj, Resilux NV, Sonoco Products Company, CCL Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Packaging Market Emerging Trajectories
Active and intelligent packaging functionalities are migrating from premium pharmaceuticals into mainstream food and beverage PET formats, driven by shelf-life extension demands and supply chain transparency mandates.
Barrier coating technologies utilizing plasma-enhanced chemical vapor deposition are converging with monolayer PET bottle production to deliver oxygen transmission rates below 0.1 cc per bottle per day. Craft brewers and functional beverage formulators in Germany and the Netherlands are piloting these systems to replace multilayer structures. This convergence is compressing the cost premium between high-barrier and standard PET from 35% to under 15% at commercial scale.
REACH restrictions on intentionally added microplastics are compelling European converters to reformulate additives and masterbatch compositions for colorants and slip agents. The regulation forces substitution of conventional polymer processing aids with bio-based alternatives certified under OK Compost INDUSTRIAL standards. Personal care and household product segments with frequent formulation changes face the steepest compliance cost escalation.
Brand owner procurement teams are consolidating annual volume commitments under master service agreements spanning multiple container formats and geographic production sites. This behavior disrupts spot-market converters and elevates integrated suppliers with multi-plant networks. The shift is most visible in North American carbonated soft drink and bottled water categories, where three bottlers now control over 60% of contractual PET volume.
PET Packaging Market Segmentation
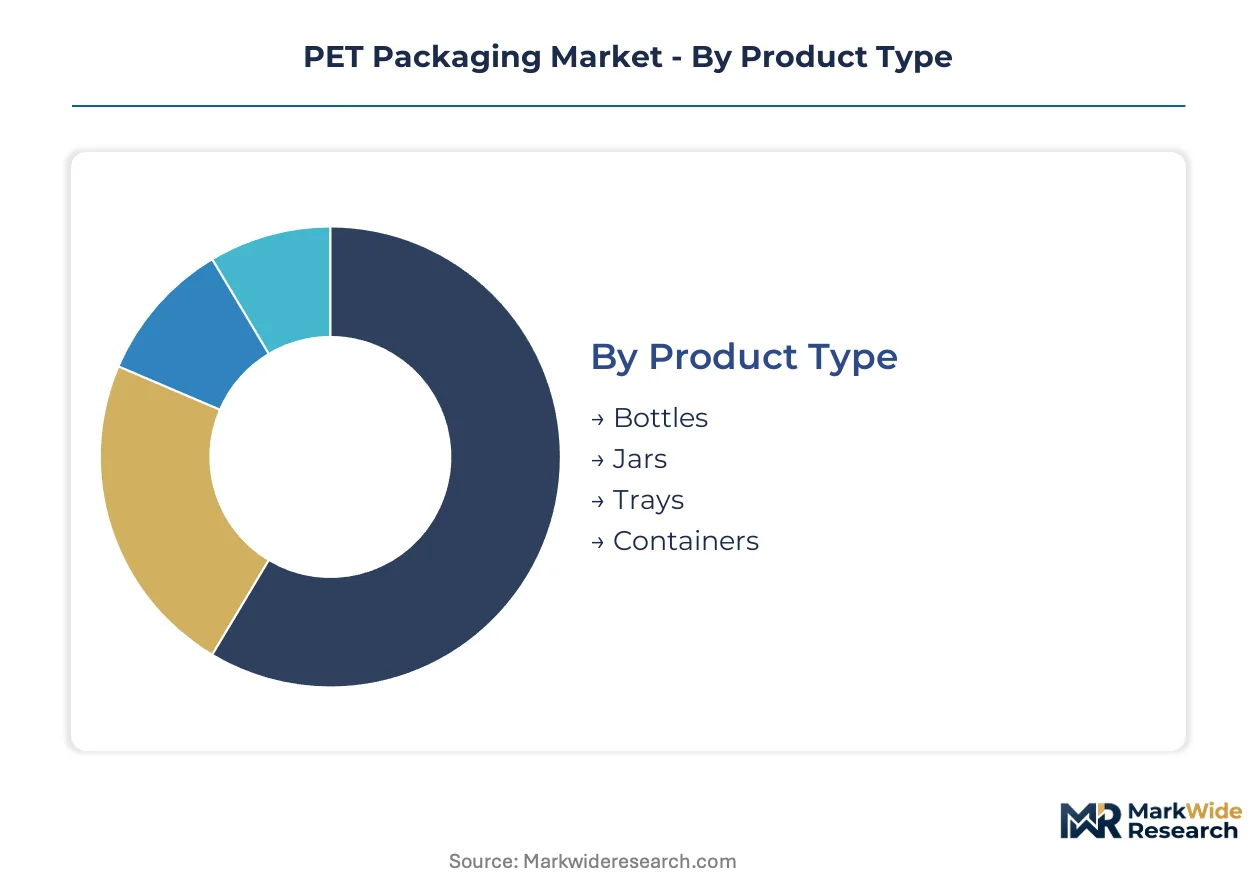
PET packaging purchasing decisions hinge on container performance specifications, regulatory compliance tiers, and line integration requirements. Brand owners evaluate segments through total cost of ownership lenses that weigh material efficiency against shelf-life extension capabilities.
Product Type:
Brand owners prioritize container geometry based on carbonation retention needs, distribution durability, and retail shelf presence requirements.
- Bottles:Stretch blow-molded containers with biaxial orientation achieve tensile strength above 55 MPa and barrier properties for carbonated beverages. Demand concentrates in India where urban retail expansion and packaged water consumption drive double-digit uptake rates. FDA food-contact notification requirements constrain additive selections for converters accessing US beverage accounts.
- Trays:Thermoformed structures with modified-atmosphere barrier coatings replace EPS and PVC in fresh protein retail applications. European retailers including German and Dutch supermarket chains are adopting these formats fastest as EFSA evaluations reshape recycled content investment priorities.
- Jars:Wide-mouth injection-stretch blow molded containers serve viscous food products and personal care formulations with dispensing convenience requirements.
- Containers:General-purpose rigid formats encompass non-standard geometries for industrial and bulk food applications with lower volume scale.
Volume sits with bottles; growth tilts toward trays.
End User:
Customer procurement consolidation patterns vary sharply across end-use verticals, with beverage accounts driving largest contract values and pharmaceutical buyers imposing strictest certification timelines.
- Food and Beverage:Multinational brand owners are consolidating annual volume commitments under master service agreements spanning multiple container formats. North American carbonated soft drink and bottled water categories exhibit highest procurement concentration, with three bottlers controlling majority contractual PET volume.
- Personal Care:Frequent formulation changes and REACH restrictions on intentionally added microplastics compel European converters to reformulate additives and masterbatch compositions, elevating compliance cost escalation.
- Pharmaceuticals:Active and intelligent packaging functionalities are migrating into mainstream formats, driven by shelf-life extension demands and supply chain transparency mandates from regulators.
- Household Products:Resealable formats gain structural importance where dispensing convenience drives repeat purchase behavior in concentrated cleaning formulations.
Revenue concentrates in food and beverage; margin expansion tilts toward pharmaceuticals.
Packaging Type:
Structural rigidity versus flexibility trade-offs determine line compatibility and downstream handling automation requirements.
- Rigid Packaging:Dominates product type classifications through bottles, jars, and containers formed via stretch blow molding and injection molding with intrinsic viscosity ranging 0.70 to 0.84 dL/g. EU Single-Use Plastics Directive mandatory recycled content targets are accelerating rPET processing infrastructure investment across European converter networks.
- Resealable Packaging:Closure-integrated formats gain structural importance in personal care and household segments where dispensing convenience drives repeat purchase and brand loyalty.
- Flexible Packaging:Film-based formats serve secondary wrapping and bundling applications with lower unit value but higher throughput velocity.
- Tamper-Evident Packaging:Security-featured formats serve pharmaceutical and premium food applications with regulatory authentication requirements.
Shipment volume favors rigid; value-per-unit expansion favors resealable.
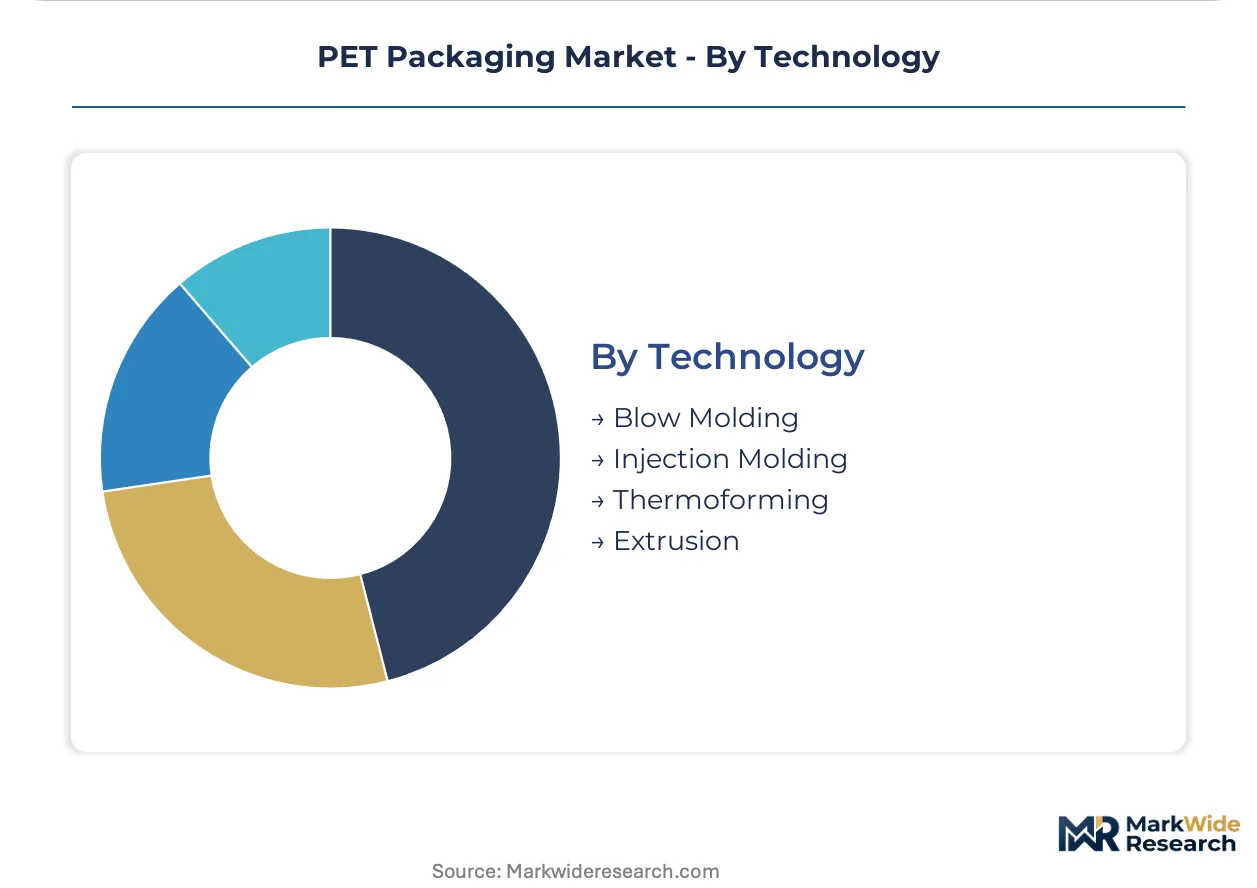
Technology:
Equipment capital intensity and technician scarcity shape converter technology selection and geographic deployment strategies.
- Blow Molding:High-speed electric machine platforms reduce cycle times and enable thinner-wall designs without sacrificing top-load strength. Stretch blow molding automation is compressing cost premiums between high-barrier and standard PET from 35% to under 15% at commercial scale.
- Thermoforming:Barrier coating technologies utilizing plasma-enhanced chemical vapor deposition converge with monolayer production to deliver oxygen transmission rates below 0.1 cc per bottle per day for craft brewers and functional beverage formulators.
- Injection Molding:Preform production and wide-mouth jar manufacturing require precise temperature control and dwell time management for optical clarity.
- Extrusion:Sheet and film production for thermoforming feedstock and flexible packaging substrates operates at higher throughput rates with lower per-unit capital intensity.
Installed capacity concentrates in blow molding; capability investment tilts toward thermoforming.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration among multinational beverage brand owners is reshaping geographic production footprints, with converters prioritizing proximity to high-volume bottling clusters and deposit-return infrastructure.
United States
Carbonated soft drink and bottled water bottlers in Georgia and Texas are consolidating annual volume commitments under multi-site master service agreements. California, Oregon, and New York are implementing expanded bottle bill frameworks that improve rPET feedstock quality. Chicago and Dallas-Fort Worth metropolitan areas host dense networks of stretch blow molding operations serving regional distribution.
Germany
German retailers including REWE and EDEKA are adopting modified-atmosphere PET thermoforms for fresh protein applications at accelerating rates. EFSA evaluations of recycled PET processes for food-contact applications are reshaping converter investment priorities across Baden-Württemberg and Bavaria. The Rhine-Ruhr industrial corridor concentrates plasma-enhanced barrier coating pilot installations for craft beverage applications.
India
Urban retail expansion in Mumbai, Delhi-NCR, and Bangalore is driving packaged water and edible oil container demand at double-digit rates. FSSAI food-contact compliance requirements are constraining additive selections for converters accessing organized retail channels. The Gujarat industrial belt hosts expanding preform manufacturing capacity serving western and southern markets.
China
Carbonated beverage and functional drink formulators in Guangdong and Zhejiang provinces are specifying thinner-wall bottle designs enabled by high-speed electric blow molding platforms. SAMR food-contact material standards are tightening migration testing protocols for recycled content applications. The Yangtze River Delta maintains the highest concentration of integrated film-to-bottle manufacturing networks.
Brazil
São Paulo-based beverage bottlers are expanding PET line capacity to serve growing sparkling water and juice segments. ANVISA pharmaceutical packaging regulations are elevating certification requirements for converters supplying sterile barrier applications. The Campinas industrial cluster anchors southeastern Brazil's blow molding equipment maintenance and technician training infrastructure.
PET Packaging Market Vendor Landscape
North American producers anchor one tier; European specialists hold differentiated positions in pharmaceutical and barrier-coated formats. The vendor base compresses around integrated converters with multi-plant networks capable of serving consolidated procurement contracts. Three strategic archetypes dominate: integrated multinational suppliers, regional blow molding specialists, and on-site production partners. Competitive moves concentrate on backward integration into rPET processing and geographic densification near major bottling clusters.
Within the integrated multinational tier, Amcor plc and Berry Global exemplify archetypes built on multi-plant network scale and film-to-bottle capability breadth. Graham Packaging Company occupies a position representing dedicated on-site production partnerships at major beverage facilities. These three entities anchor competitive dynamics as procurement consolidation favors suppliers with cross-format flexibility and geographic reach.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Graham Packaging Company |
| Silgan Holdings Inc. |
| Gerresheimer AG |
| Huhtamäki Oyj |
| Resilux NV |
| Sonoco Products Company |
| CCL Industries Inc. |
| Others |
Supply Flow & Price Mechanics
Paraxylene contract price movements on Asian spot markets cascade through purified terephthalic acid converters into three distinct PET resin pricing tiers, with beverage brand procurement consolidation compressing spot-market premiums and elevating long-term offtake contract value.
Pricing Analysis
Volume concentrates in standard-grade bottle resin sold under annual master service agreements, while margin expansion accrues to food-contact certified rPET and high-barrier coated grades. Pricing stratifies across premium, standard, and economy tiers based on intrinsic viscosity consistency and FDA notification status. Cost compression in standard resin is intensifying because PTA-MEG feedstock volatility transfers unpredictably to converter margins. Private-label beverage bottlers exhibit highest price sensitivity; pharmaceutical and fresh protein retail buyers demonstrate lowest sensitivity due to certification lock-in requirements.
Supply Chain Analysis
Ocean freight rate volatility from Asia to North America and Europe has restructured regional sourcing strategies, with converters prioritizing geographic density over lowest-unit-cost procurement. Raw material supply concentrates in China, Saudi Arabia, and South Korea for paraxylene and PTA; rPET flake supply draws from Germany, California, and Japan where deposit-return infrastructure matures. Single-source vulnerability in specialty additive masterbatches from German and Swiss suppliers elevates regulatory compliance risk. Distribution runs through integrated film-to-bottle manufacturing networks serving consolidated multinational accounts, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PET packaging sector is consolidating around backward integration into rPET processing capabilities, with converters racing to secure food-contact certified recycled feedstock ahead of EU Single-Use Plastics Directive enforcement deadlines.
For Market Incumbents: Acquire rPET decontamination and solid-state polymerization assets in Germany or California to secure EFSA and FDA food-contact certification ahead of capacity shortages. Lock in long-term offtake agreements with deposit-return system operators to defend against aluminum can substitution in sparkling water segments. Expand on-site production partnerships at Indian and Vietnamese bottling clusters before regional blow molding specialists capture procurement consolidation contracts. For New Entrants and Emerging Players: EU Single-Use Plastics Directive in Europe opens a window for barrier-coated tray specialists to displace EPS and PVC in fresh protein retail. Target Vietnamese and Indonesian shelf-stable food segments where PET conversion rates remain below forty percent and organized retail penetration is accelerating. Lead with modified-atmosphere thermoforming capability paired with plasma-enhanced barrier coating pilots to bypass incumbent blow molding scale advantages. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European converters with EFSA-reviewed rPET processes and stranded preform manufacturing assets in mature markets. Long-term viability hinges on food-contact certification moats and deposit-return system integration depth. Watch California and New York bottle bill implementation timelines as inflection indicators for rPET feedstock quality and supply security.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Processing | EFSA and FDA food-contact certifications lock in premium pricing tiers for certified converters. |
| Barrier Coating Technology Deployment | Plasma-enhanced chemical vapor deposition enables craft brewer adoption in Germany and Netherlands. |
| On-Site Production Partnership Expansion | Dedicated facilities at major beverage bottling clusters capture procurement consolidation contracts. |
| Geographic Densification in India | Tier-1 and Tier-2 urban retail expansion drives double-digit packaged water and edible oil container demand. |
| Deposit-Return System Integration | California and New York bottle bill frameworks improve rPET feedstock quality and supply predictability. |
Methodological Framework
Multi-period observation of PTA-MEG spread volatility, rPET flake pricing differentials, and beverage procurement contract tenors anchored the trend analysis, supplemented by interviews with blow molding equipment engineers, resin procurement managers at multinational brand owners, EFSA regulatory affairs specialists, and Indian organized retail category buyers. Secondary validation drew from FDA food-contact notification databases, EU REACH substance restriction updates, customs trade data on PET resin and preform flows, and SEC filings of integrated packaging suppliers. Bottom-up capacity modeling across converter networks triangulated against top-down demand projections from beverage and fresh protein retail segments.
Segment-weighting applied product type splits between bottles, trays, and jars; end-use concentration in food and beverage versus pharmaceutical and personal care; packaging type rigidity classifications; and technology differentiation across blow molding, thermoforming, and injection molding platforms. CAGRs were derived from installed equipment capacity trajectories, urban retail penetration curves in India and ASEAN markets, and regulatory deadline impacts on rPET investment cycles. Forecast inputs incorporated stretch blow molding automation adoption rates and barrier coating cost compression timelines.
The model assumes a particular technology adoption path for plasma-enhanced barrier deposition; alternative pathways for monolayer scavenger additive integration would alter the outlook for high-barrier PET cost structures. Forecasts reflect assumptions about EU Single-Use Plastics Directive enforcement consistency, deposit-return system expansion pacing, and feedstock volatility transmission mechanisms. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Postal Packaging Market
Packaging Materials
Food Grade Sealant Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Europe Airless Packaging Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Crimped End Mailing Tubes Market
Packaging Materials
Shrink Packaging Market
Packaging Materials
Thermal Transfer Roll Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Trifold Packaging Market
Packaging Materials
Printable Self-Adhesive Vinyl Films Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Non-Plastic Punnets Market