
 Skin Packaging Equipment Market | 2026-2036
Skin Packaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Packaging Equipment Market Analytics
Multi-source procurement toward integrated automation suppliers is recalibrating how food processors evaluate capital expenditures. MULTIVAC leverages its German engineering base to dominate high-throughput thermoforming lines for protein applications. Illig competes through modular platform designs that reduce changeover downtime across European dairy and ready-meal plants. Sealed Air Corporation anchors North American aftermarket service networks, sustaining long-term revenue through consumables bundling rather than equipment margins alone.
Skin packaging equipment forms a tight film barrier over product-bearing trays using vacuum-drawn thermoplastic webs, typically operating at forming temperatures between 80°C and 160°C depending on substrate gauge and seal-layer composition. The machinery serves primarily to eliminate oxygen exposure, collapse headspace, and create retail-ready presentation surfaces for perishables. Tray sealers and vacuum skin packaging systems capture the dominant share of installed base value, as protein processors prioritize hermetic seal integrity over speed-centric flow wrapper alternatives. Automated thermoforming lines represent the fastest-expanding technology segment, displacing manual systems in mid-volume plants where labor availability constrains output.
FDA food contact substance notifications govern sealant layer approvals in the United States, while EU REACH and the Packaging and Packaging Waste Regulation constrain phthalate-containing PVC formulations across European sales territories. These frameworks elevate compliance costs for equipment configured to run restricted substrates, redirecting R&D investment toward polypropylene and PET-compatible forming stations. Stakeholders must monitor evolving extended producer responsibility schemes, as fee structures tied to recyclability ratings will increasingly influence equipment specification criteria and retrofit timelines.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing equipment replacement cycles as processors scramble to retrofit thermoforming lines for recycled-content compatibility before mandates tighten.
Growth Catalysts
- Automation imperatives in protein processing:Meat and poultry facilities are expanding vacuum skin packaging capacity to eliminate oxygen exposure and collapse headspace, extending shelf life by weeks.
- REACH constraints on phthalate formulations:The EU's chemical restrictions are redirecting capital toward polypropylene and PET-compatible forming stations, creating replacement demand across installed bases.
- German machinery cluster density:Equipment buyers leverage proximity to engineering talent and component suppliers in Baden-Württemberg and Bavaria for faster commissioning and service response.
Market Restraints
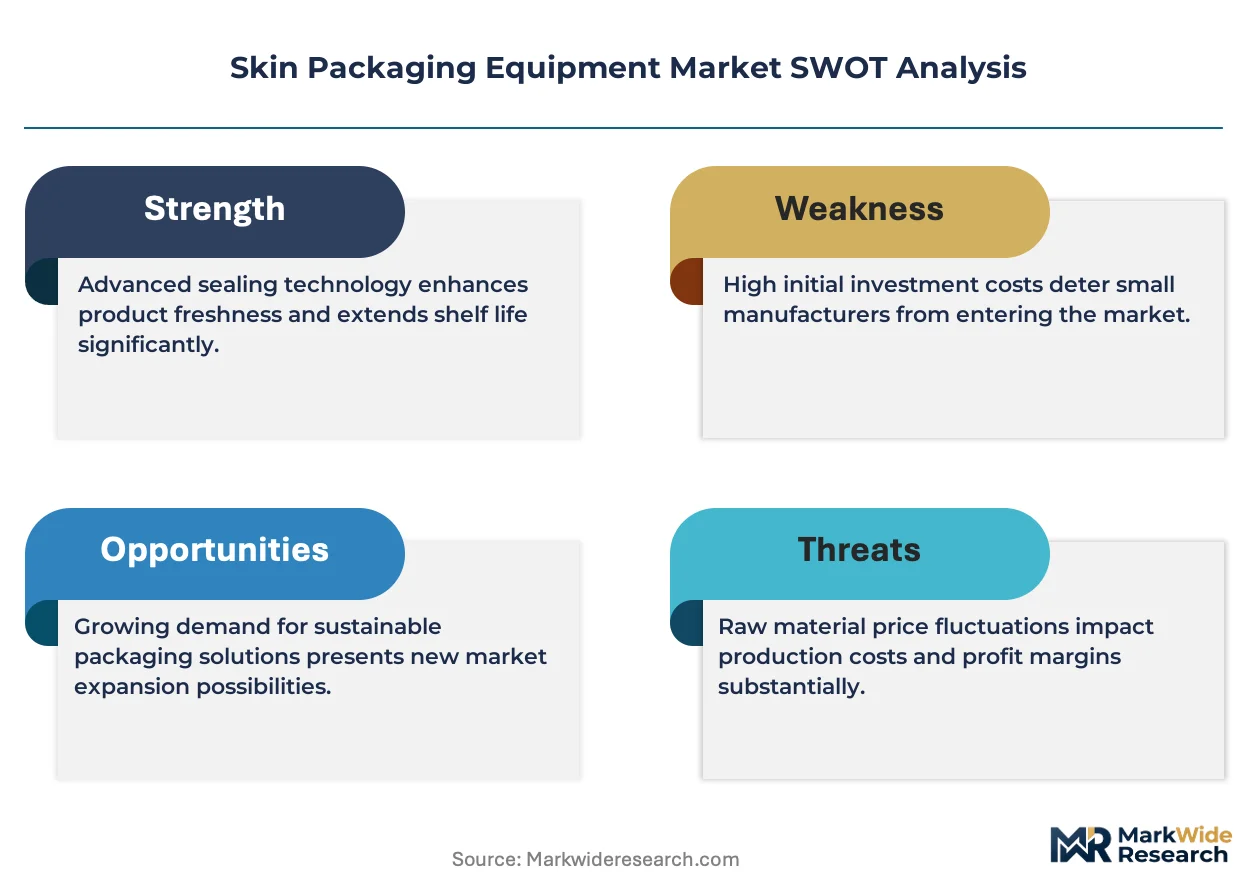
- Substrate cost volatility:Ethylene and propylene feedstock fluctuations squeeze margins for equipment configured to run multilayer barrier films.
- Supply concentration in precision tooling:Forming die and seal-bar fabrication concentrates among a handful of German and Swiss specialists, creating bottlenecks for custom line configurations.
- Technical limitation in thin-gauge recycled PET:Current thermoforming stations struggle to maintain hermetic seal integrity below 250-micron gauges with post-consumer content exceeding 30%.
Strategic Opportunities
- Underpenetrated ready-meal segment:European dairy and prepared food plants represent untapped demand for modular skin packaging platforms with rapid changeover capability.
- Extended producer responsibility tailwinds:Fee structures tied to recyclability ratings in France and Italy are accelerating specification of mono-material-compatible equipment.
- Technology convergence of thermoforming and digital printing:Inline decoration systems for retail-ready trays are opening premium positioning for mid-volume processors.
Industry Challenges
- Control systems integration complexity:Legacy tray sealers lack the I/O architecture to synchronize with modern MES and track-and-trace platforms without costly retrofits.
- Certification timeline compression:FDA food contact substance notifications for novel sealant layers now stretch 18-24 months, delaying line startups for US-bound protein exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Packaging Equipment Market |
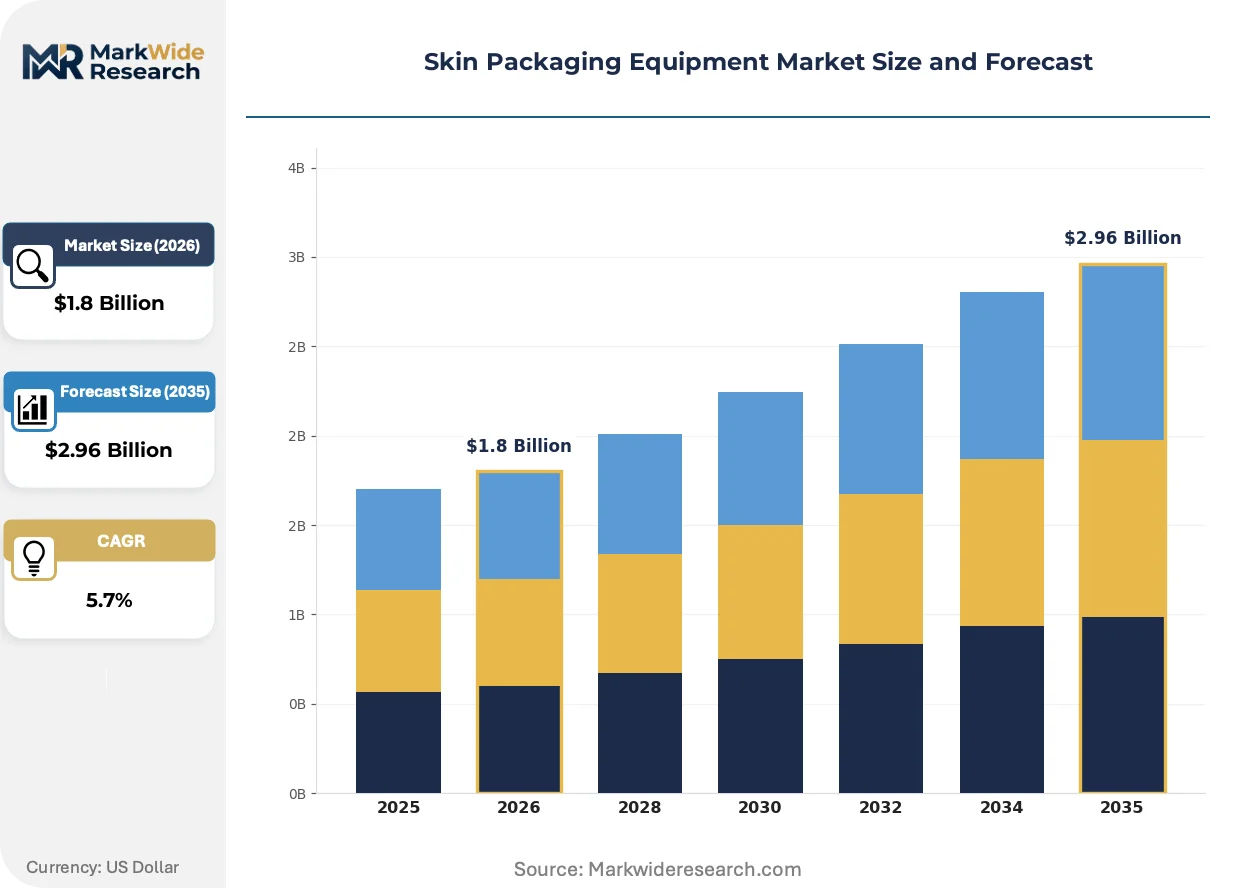
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Wrappers, Tray Sealers, Vacuum Skin Packaging, Lidding Machines Material: Polyethylene, Polypropylene, PVC, PET End User: Food, Consumer Goods, Healthcare, Industrial Technology: Thermoforming, Pressure Sealing, Automated Systems, Manual Systems |
| Companies Covered | MULTIVAC, PAC Machinery, Illig, Tekkra, Standard Industrial Products, JLS Machine Systems, G.MONDINI SPA, Amcor plc, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Packaging Equipment Market Evolving Landscape
Equipment architecture is pivoting from standalone machines toward connected production cells. Three forces are compressing development cycles and redefining competitive differentiation.
Electroactive polymer seal-bar heating is absorbing thermal management functions previously handled by cartridge and ceramic elements. Protein processors in Germany and the Netherlands are piloting these systems for sub-second temperature ramping. The technology is absorbing maintenance labor and energy costs while enabling real-time seal-profile adjustment.
EU REACH Annex XVII restrictions on PVC plasticizers are forcing equipment reconfigurations across European sales territories. Thermoforming OEMs are redesigning forming stations to handle polyolefin sealant webs with equivalent barrier performance. Ready-meal and fresh produce segments are absorbing the compliance burden fastest, with retrofit orders outpacing new line investments.
Buyers are unbundling aftermarket service from initial equipment contracts. North American protein processors now procure consumables, spare parts, and technical support through separate vendor relationships rather than single-source bundles. This fragmentation is visible most acutely in the US Southeast, where regional service networks compete against OEM-direct coverage.
Skin Packaging Equipment Market Segmentation
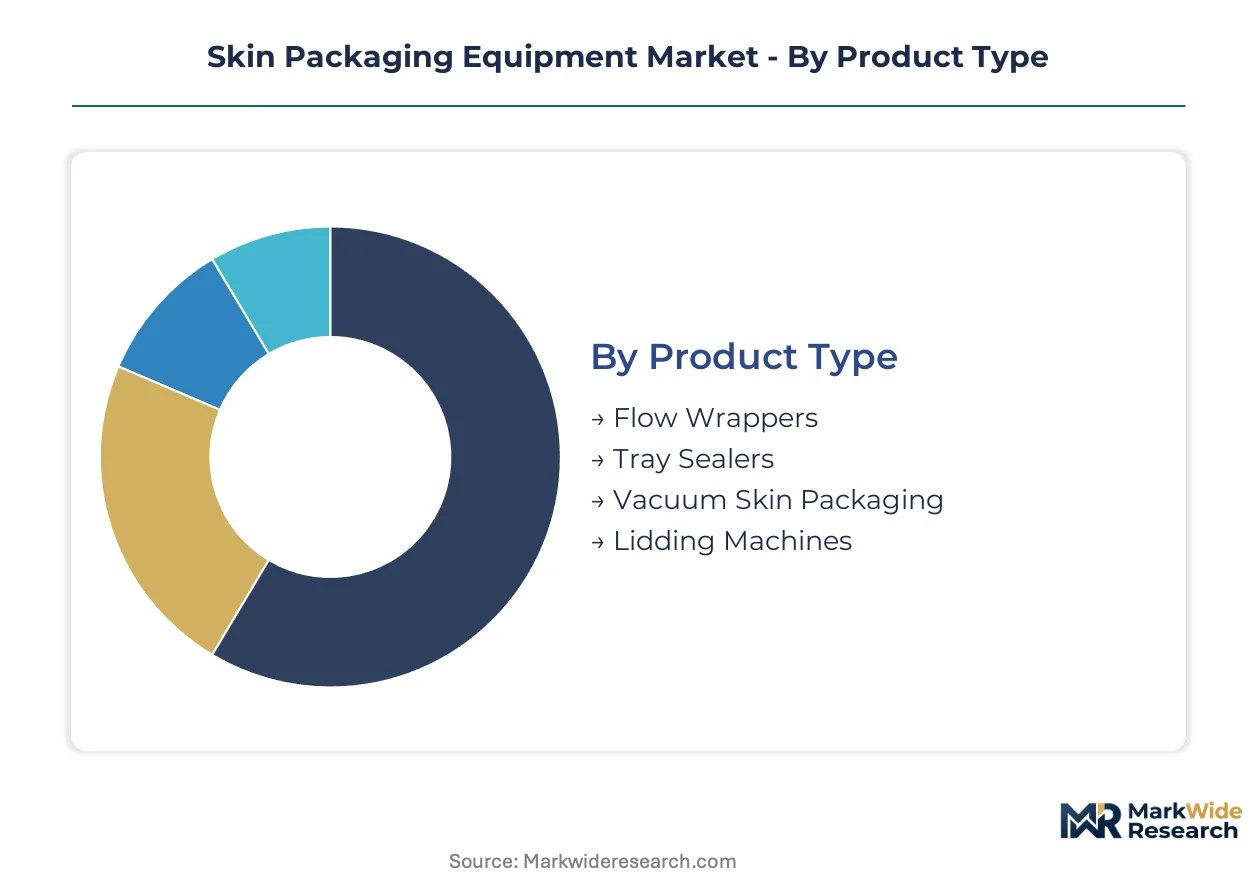
Equipment specification in skin packaging diverges sharply by product geometry, substrate compatibility, and throughput requirements. Processors match machinery type to shelf-life targets, regulatory constraints, and line integration complexity.
Product Type:
Thermoforming architecture determines seal integrity, oxygen transmission rates, and changeover flexibility across protein and ready-meal applications.
- Tray Sealers:These systems apply pre-formed trays with vacuum-drawn top webs, operating at throughputs exceeding 120 cycles per minute in high-volume poultry plants. German processors deploy these for hermetic sealing of modified atmosphere packaging in retail-ready formats. Demand concentrates where oxygen exclusion below 0.5% is mandatory for fresh meat distribution.
- Vacuum Skin Packaging:Film barriers collapse directly onto product contours using deep-draw thermoplastic webs, eliminating headspace entirely. Netherlands-based seafood exporters favor this technology for premium shelf presentation and extended logistics windows. The format commands specification where retail differentiation justifies higher packaging costs per unit.
- Flow Wrappers:Continuous motion systems wrap products in flexible film with longitudinal and end seals, suited to uniform geometry items at speed.
- Lidding Machines:These apply pre-cut lidstock to filled trays, common in dairy portion packs and single-serve ready meals.
Mature deployment sits with tray sealers in centralized protein processing. Newer deployment is concentrated in vacuum skin packaging for premium retail channels.
Material:
Substrate selection governs forming temperature profiles, seal-layer compatibility, and post-consumer recyclability under tightening EPR schemes.
- PET:This polyester offers clarity and barrier performance for retail visibility, though thin-gauge recycled content above 30% strains thermoforming station calibration. French and Italian EPR fee structures now reward mono-material PET configurations, redirecting capital from multilayer alternatives.
- Polypropylene:Polyolefin sealant webs substitute for restricted phthalate-containing formulations under REACH Annex XVII. Equipment buyers in Germany and the Netherlands retrofit forming stations to handle PP seal layers with equivalent oxygen barrier performance. The material climbs fastest where regulatory compliance timelines compress replacement cycles.
- Polyethylene:Lower-cost polyolefin with moderate barrier properties, dominant in volume-driven applications with shorter shelf-life requirements.
- PVC:Legacy substrate facing phasedown across EU sales territories due to plasticizer restrictions; equipment reconfiguration away from PVC is accelerating.
Polyethylene dominates current installed base volume. Polypropylene gains share fastest where REACH compliance mandates substrate transition.
End User:
Application environment dictates hygiene classification, validation requirements, and line integration architecture.
- Food:Protein processors specify stainless steel construction, washdown-rated controls, and USDA/FDA compliance for raw meat contact. Automated thermoforming lines displace manual systems in mid-volume plants where labor availability constrains output.
- Healthcare:Sterile barrier packaging for medical devices demands validated seal integrity and traceability systems. Swiss and German equipment serves this segment with ISO 11607-compliant forming stations.
- Consumer Goods:Electronics and hardware applications prioritize tamper evidence and retail presentation over oxygen barrier performance.
- Industrial:Corrosion protection and component containment drive specification in automotive and aerospace supply chains.
Food commands the dominant share of equipment revenue. Healthcare represents the steepest expansion trajectory as sterile barrier demand outpaces general industrial packaging.
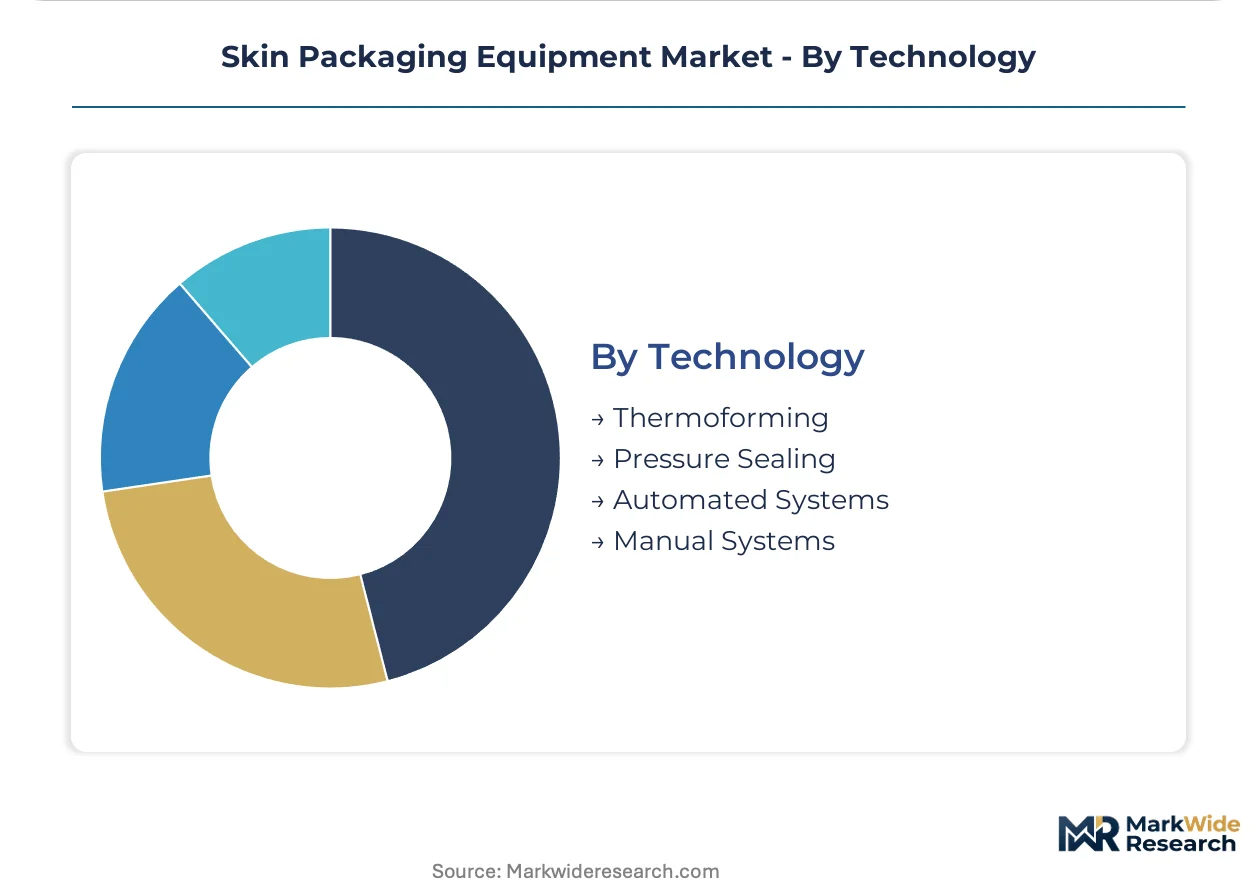
Technology:
Automation level determines labor content, throughput consistency, and integration feasibility with MES and track-and-trace platforms.
- Thermoforming:Vacuum-drawn web systems form trays inline from reel stock, collapsing capital cost per unit at volume. German machinery clusters in Baden-Württemberg anchor European supply for high-throughput protein lines. The technology absorbs R&D investment for recycled-content compatibility.
- Automated Systems:Servo-driven forming stations with recipe-managed changeover reduce downtime in multi-SKU plants. Dairy and ready-meal processors in France specify these for rapid format switching between shift runs.
- Pressure Sealing:Mechanical compression systems for lidding applications where vacuum draw is unnecessary or prohibited.
- Manual Systems:Entry-level equipment for low-volume or artisanal production; retrofit demand to automated alternatives is accelerating.
Thermoforming anchors high-volume protein processing. Automated systems penetrate fastest where labor costs and SKU proliferation coincide.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates where protein processing automation intersects with stringent packaging regulations. Germany absorbs the dominant share of European capital expenditure, while the United States and Netherlands anchor transatlantic demand for shelf-life extension technologies.
Germany
Baden-Württemberg and Bavaria host dense machinery clusters serving export markets across Europe and beyond. ECHA REACH Annex XVII restrictions on phthalate plasticizers are compressing replacement cycles for thermoforming lines. MULTIVAC and Illig anchor engineering talent pools in these regions, accelerating commissioning timelines for recycled-content compatible systems.
United States
FDA food contact substance notifications govern sealant layer approvals for protein processors expanding vacuum skin packaging capacity. The Southeast region exhibits acute aftermarket service fragmentation as buyers unbundle consumables from initial equipment contracts. USDA compliance requirements for raw meat contact sustain specification of stainless steel construction and washdown-rated controls.
Netherlands
Seafood exporters in this market favor vacuum skin packaging for premium shelf presentation and extended logistics windows. EU Packaging and Packaging Waste Regulation mandates are redirecting capital toward mono-material PET configurations. Rotterdam-area processors pilot electroactive polymer seal-bar heating systems for sub-second temperature ramping.
France
Extended producer responsibility fee structures tied to recyclability ratings are accelerating specification of mono-material-compatible equipment. Dairy and ready-meal plants in this territory represent untapped demand for modular platforms with rapid changeover capability. Île-de-France processors absorb the compliance burden fastest, with retrofit orders outpacing new line investments.
Italy
EPR schemes in this market reward mono-material PET configurations, redirecting capital from multilayer alternatives. Food processors specify automated thermoforming lines to displace manual systems where labor availability constrains output. Northern industrial districts concentrate mid-volume plants pursuing technology convergence of thermoforming and digital printing for retail-ready trays.
Skin Packaging Equipment Market Competitive Landscape
Retrofit orders for regulatory compliance dominate the current landscape as processors scramble to meet tightening recycled-content mandates before deadlines. The vendor base concentrates among German engineering specialists and North American service networks, creating tiered competitive positions based on geographic proximity and aftermarket coverage. Two strategic archetypes prevail: integrated automation suppliers bundling equipment with consumables, and modular platform specialists optimizing for rapid format changeover. M&A activity and technology licensing arrangements represent the dominant competitive moves as players seek expanded substrate compatibility portfolios.
Among German-based machinery fabricators, MULTIVAC and Illig exemplify contrasting archetypes within the premium equipment tier. MULTIVAC occupies a position anchored in high-throughput thermoforming lines for protein applications, while Illig represents modular platform designs reducing changeover downtime. Sealed Air Corporation sits within the North American aftermarket service network archetype, sustaining long-term revenue through consumables relationships rather than equipment margins alone.
| Leading Market Players |
|---|
| MULTIVAC |
| PAC Machinery |
| Illig |
| Tekkra |
| Standard Industrial Products |
| JLS Machine Systems |
| G.MONDINI SPA |
| Amcor plc |
| Sealed Air Corporation |
| Others |
Value Network & Pricing Analysis
Ethylene and propylene feedstock indices cascade through multilayer barrier film costs, compressing margins for equipment configured to run premium thermoforming substrates and forcing buyers toward polyolefin-compatible systems with lower total cost of ownership.
Pricing Analysis
Volume-driven tray sealer lines command thin equipment margins offset by consumables bundling, while vacuum skin packaging systems capture premium positioning through hermetic seal certification and after-sales service tiers. Price differentiation rests on automation level and REACH-compliant substrate compatibility, with German-engineered thermoforming stations extracting brand premiums. Cost compression in mid-volume segments intensifies as regional service networks compete against OEM-direct coverage. Protein processors exhibit highest price sensitivity due to thin operating margins, whereas healthcare sterile barrier buyers prioritize validation documentation over capital expenditure minimization.
Supply Chain Analysis
Single-source vulnerability sits with forming die and seal-bar fabrication concentrated among Baden-Württemberg and Bavarian specialists, creating bottlenecks for custom line configurations. Precision tooling draws from German and Swiss engineering clusters, while electroactive polymer heating elements feed from Netherlands-based component suppliers. Tariff exposure on precision-machined aluminum tooling threatens commissioning timelines for North American buyers. Distribution runs through OEM-direct channels for high-throughput protein lines and fragmented regional service networks for aftermarket consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation mandates are compressing replacement cycles, forcing capital-constrained equipment fabricators toward distressed exits or acquisition by integrated automation suppliers.
For Market Incumbents: To counter unbundling of aftermarket service relationships, anchor recurring revenue through consumables subscription models and deepen backward integration into precision tooling fabrication. Acquire distressed regional service networks in the US Southeast to rebuild bundled coverage density. For New Entrants and Emerging Players: Launch via modular platform designs targeting Italian and French dairy processors with rapid changeover requirements. White-space opportunity concentrates in mid-volume ready-meal plants seeking mono-material PET compatibility without German-engineered price premiums. Pursue technology licensing from Netherlands-based electroactive polymer specialists to bypass R&D timeline disadvantages. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated thermoforming specialists with installed base retrofit exposure in Germany and France. Five-to-ten year viability hinges on recycled-content compatibility certification breadth. Monitor EPR fee structure implementation timelines as inflection signal for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit-First Platform Development | Captures compressed replacement cycles driven by REACH Annex XVII plasticizer restrictions. |
| Consumables Subscription Bundling | Reconstructs recurring revenue streams as North American buyers unbundle aftermarket relationships. |
| Electroactive Polymer Seal-Bar Integration | Absorbs thermal management functions previously handled by ceramic cartridge elements. |
| Mono-Material PET Compatibility Certification | Unlocks French and Italian EPR fee advantage for processors seeking recyclability ratings. |
| Regional Service Network Acquisition | Rebuilds coverage density in fragmented US Southeast protein processing corridor. |
Research Methodology
Independent corroboration across OEM engineering directors, protein processor plant managers, and aftermarket service heads underwrites the qualitative findings. Primary fieldwork encompassed thermoforming equipment procurement leads at dairy and ready-meal processors, precision tooling fabricators in Baden-Württemberg, and sterile barrier validation specialists serving Swiss medical device manufacturers. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, ECHA REACH Annex XVII restriction timelines, FDA food contact substance notification databases, and SEC filings of publicly traded packaging equipment suppliers. Bottom-up equipment shipment tallies and top-down protein processing capacity expansion estimates were triangulated to anchor volume projections.
Rate-of-change decomposition across thermoforming, tray sealing, and vacuum skin packaging technologies informed the analytical framework. Segmentation dimensions modeled include equipment automation level, substrate material compatibility, end-use application environment, and geographic regulatory cluster. CAGRs were derived from installed base replacement timelines, greenfield capacity announcements, and compliance-driven retrofit order pipelines. Industry-specific forecast inputs encompassed ethylene-propylene spread volatility and EPR scheme implementation schedules across France, Italy, and Germany.
Feedstock price volatility, regulatory timeline slippage, and precision tooling supply bottlenecks are the dominant revision risks. Forecasts reflect documented assumptions regarding REACH enforcement intensity and mono-material PET technical performance thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Strap Dispenser Market
Packaging Equipment
Flexible End-Load Cartoner Market
Packaging Equipment
Basket Granulator Extruder Market
Packaging Equipment
Packer Market
Packaging Equipment
Aerosol Dispensing Systems Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Labeling Equipment Market
Packaging Equipment
Bespoke Dispenser Market
Packaging Equipment
Refrigerated Display Cases Market
Packaging Equipment
High Resolution Dispensing Systems and Equipment Market
Packaging Equipment
Shrink Wrap Sealers Market
Packaging Equipment
Strapping and Banding Equipment Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Thermal Impulse Sealers Market
Packaging Equipment
Linear Net Weighing Machines Market