
 Tamper Evident Shrink Bands Market | 2026-2036
Tamper Evident Shrink Bands Market Size, Share, and Industry Trends Forecast 2026-2036
Tamper Evident Shrink Bands Market Analytics
Pharmaceutical-grade specification tiers is bifurcating the competitive landscape into compliance-focused and cost-optimized supply camps. CCL Industries Inc. leverages vertical integration across film extrusion and printed decoration to sustain premium positioning in regulated end uses. Berry Global Inc. anchors North American volume through manufacturing scale and multi-site distribution networks. Fuji Seal International, Inc. differentiates via technology leadership in thin-gauge high-strength formulations for Asian export markets.
Tamper evident shrink bands are heat-activated polymer sleeves, typically 30–50 micron thickness, that contract around container closures to provide visible breach indication through perforation patterns or printed warning graphics. Their primary commercial purpose is to deter product tampering and support brand authentication in consumer-packaged goods. Polyolefin compositions now lead material selection due to clarity and recyclability advantages over legacy PVC, while pharmaceutical applications command the fastest expansion trajectory driven by track-and-trace compliance requirements. Food and beverages remains the mature volume base where margin pools are thinner and procurement emphasizes unit cost over feature complexity.
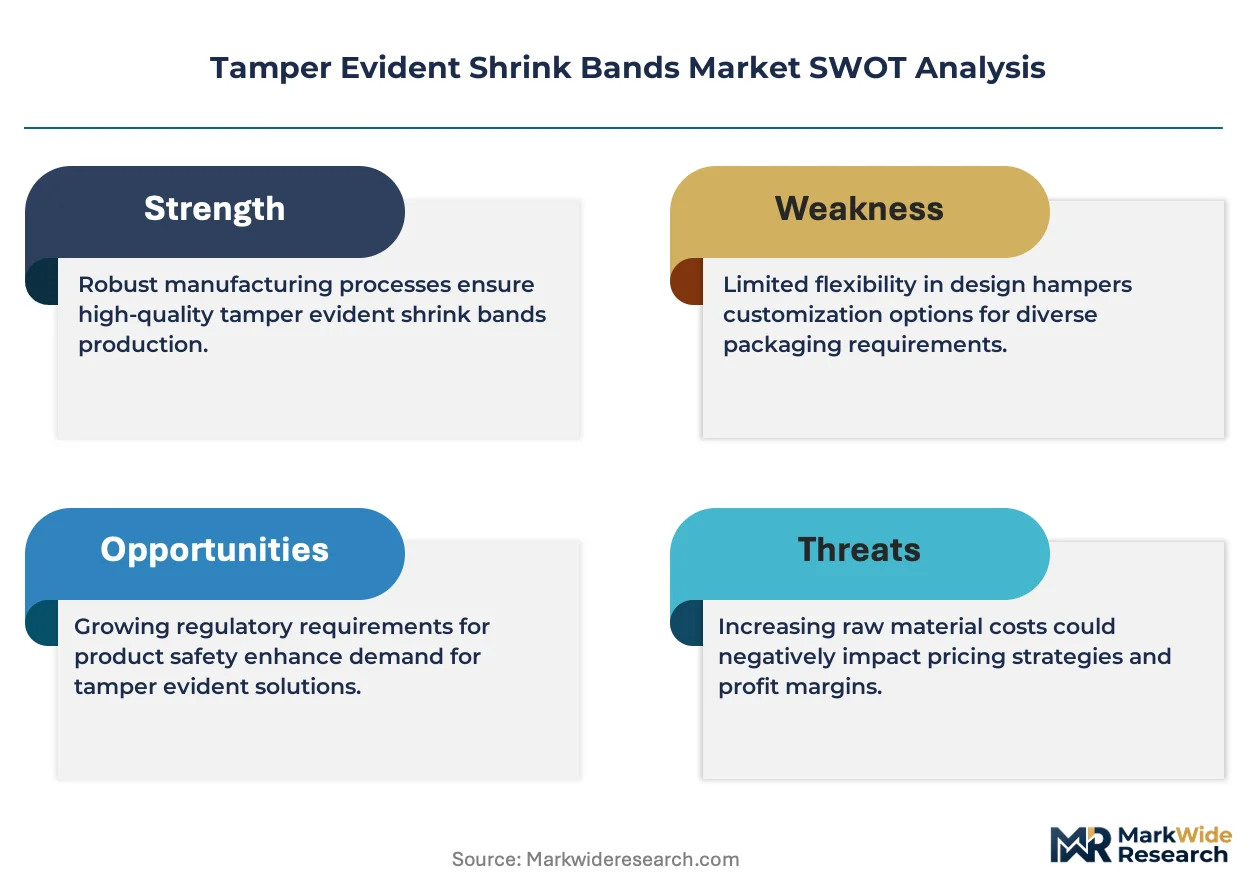
FDA 21 CFR Part 11 and the Drug Supply Chain Security Act shape pharmaceutical demand by mandating unit-level verification and tamper evidence as market access conditions. EPA guidelines on vinyl chloride emissions and REACH restrictions on phthalate plasticizers are accelerating PVC displacement toward polyolefin and PET alternatives. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and their material sorting implications for band recyclability.
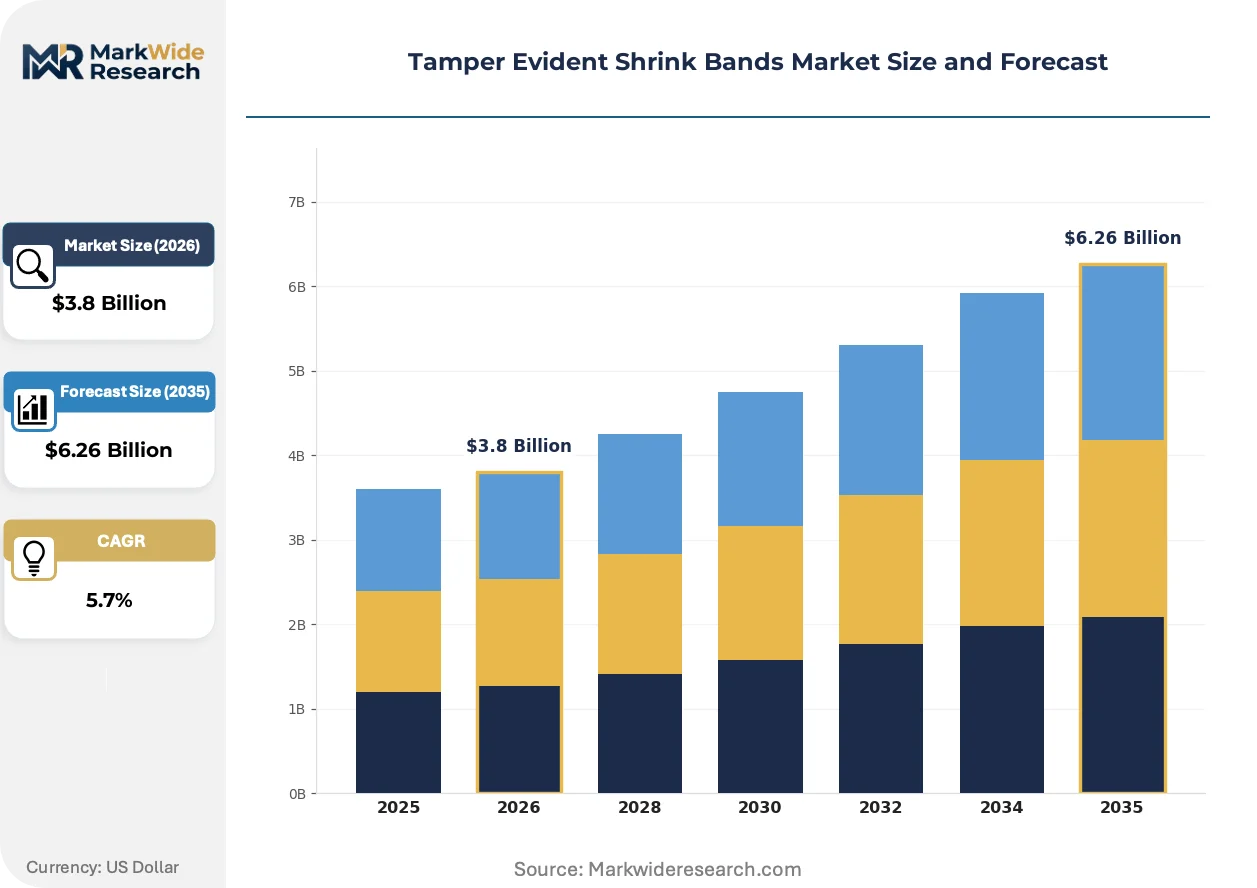
Market Dynamics
Polyolefin material migration is restructuring competitive advantage across the Tamper Evident Shrink Bands Market, as FDA serialization mandates and REACH phthalate restrictions simultaneously compress PVC viability and reward clarity-compliant suppliers with pharmaceutical procurement access.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Unit-level verification mandates in pharmaceutical packaging are converting tamper evidence from optional feature to market-access prerequisite, pulling premium-grade band volumes into compliance-tier supply chains.
- Thin-gauge polyolefin extrusion:Downgauging to 30-micron films while maintaining seal integrity is reducing resin consumption per unit and enabling cost parity with legacy PVC in high-volume food applications.
- United States contract packaging expansion:Third-party pharmaceutical packaging services in New Jersey, Pennsylvania, and North Carolina are consolidating procurement power and standardizing band specifications across generic drug portfolios.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock fluctuations directly compress polyolefin film margins, exposing non-integrated converters to quarterly cost renegotiation with pharmaceutical buyers.
- Extrusion equipment concentration:High-output blown film lines for pharmaceutical-grade clarity bands concentrate in Germany, Italy, and the United States, creating geographic supply risk for Asian and Latin American formulators.
- Heat-seal compatibility limitations:Polyolefin's narrower sealing temperature window versus PVC requires precise heat-tunnel calibration, raising retrofit costs for beverage bottlers with legacy steam-shrink infrastructure.
Strategic Opportunities
- India pharmaceutical export manufacturing:CDSCO's alignment with FDA quality standards is positioning Mumbai and Hyderabad as contract packaging hubs for North American generic drug shipments, creating demand for serialization-ready band supply.
- Digital printing convergence with shrink sleeve decoration:HP Indigo and Xeikon press installations at mid-size converters enable short-run customized tamper graphics without plate costs, opening craft beverage and nutraceutical segments.
- EU Green Deal packaging recyclability mandates:PP and PET-G shrink band formulations that sort cleanly in European mechanical recycling streams will capture preferential placement with multinational CPG brands facing extended producer responsibility compliance.
Industry Challenges
- Pharmaceutical-grade cleanroom certification timelines:ISO 15378 and FDA 21 CFR Part 211 compliance audits for film extrusion facilities extend 12-18 months, delaying new entrant market access despite technical capability.
- Legacy heat-tunnel integration complexity:Beverage bottlers with 1980s-era steam tunnels face $200,000-$400,000 capital requirements to achieve polyolefin's precise temperature control, slowing material transition in cost-sensitive segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tamper Evident Shrink Bands Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, PVC, PET, Others Application: Food & Beverages, Pharmaceuticals, Personal Care, Household Products End User: Manufacturers, Retailers, Distributors, E-Commerce Feature: Customizable, Eco-Friendly, Heat Shrinkable, Block Strain |
| Companies Covered | Berry Global Inc., CCL Industries Inc., Fuji Seal International, Inc., Klöckner Pentaplast Group, Bonset America Corporation, Traco Manufacturing, Inc., Hind Polymers, ATW Manufacturing Company, American Film & Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tamper Evident Shrink Bands Market Evolving Landscape
Material science breakthroughs and regulatory serialization requirements are converging to redefine performance benchmarks and procurement criteria across pharmaceutical and food packaging applications.
Cross-linked polyolefin shrink films with 70% shrink force at 90°C are supplanting PVC in parenteral drug vial applications where optical clarity and low extractables are non-negotiable. Contract packaging organizations in the United States are adopting these films at accelerated qualification cycles to meet FDA November 2024 unit-level traceability deadlines. The technology is compressing PVC's residual pharmaceutical share to legacy over-the-counter applications where regulatory scrutiny remains lighter.
REACH Annex XVII restrictions on phthalate plasticizers in consumer goods packaging are compelling European converters to eliminate PVC formulations entirely by 2026. ECHA's enforcement guidance treats shrink bands as articles subject to SVHC disclosure, forcing brand owners to document supply chain composition. Pharmaceutical and personal care segments in Germany, France, and the Netherlands are responding fastest, with PET-G and oriented PP films capturing reformulation specifications.
Consolidated procurement by pharmaceutical contract packagers is compressing supplier bases and unbundling decoration from tamper evidence. Large generic drug producers in the United States now specify printed bands with integrated 2D DataMatrix codes as single-source requirements, displacing separate label-and-band combinations. This pattern concentrates most visibly in New Jersey's pharmaceutical packaging corridor, where three contract packagers account for majority regional band volume.
Tamper Evident Shrink Bands Market Segmentation
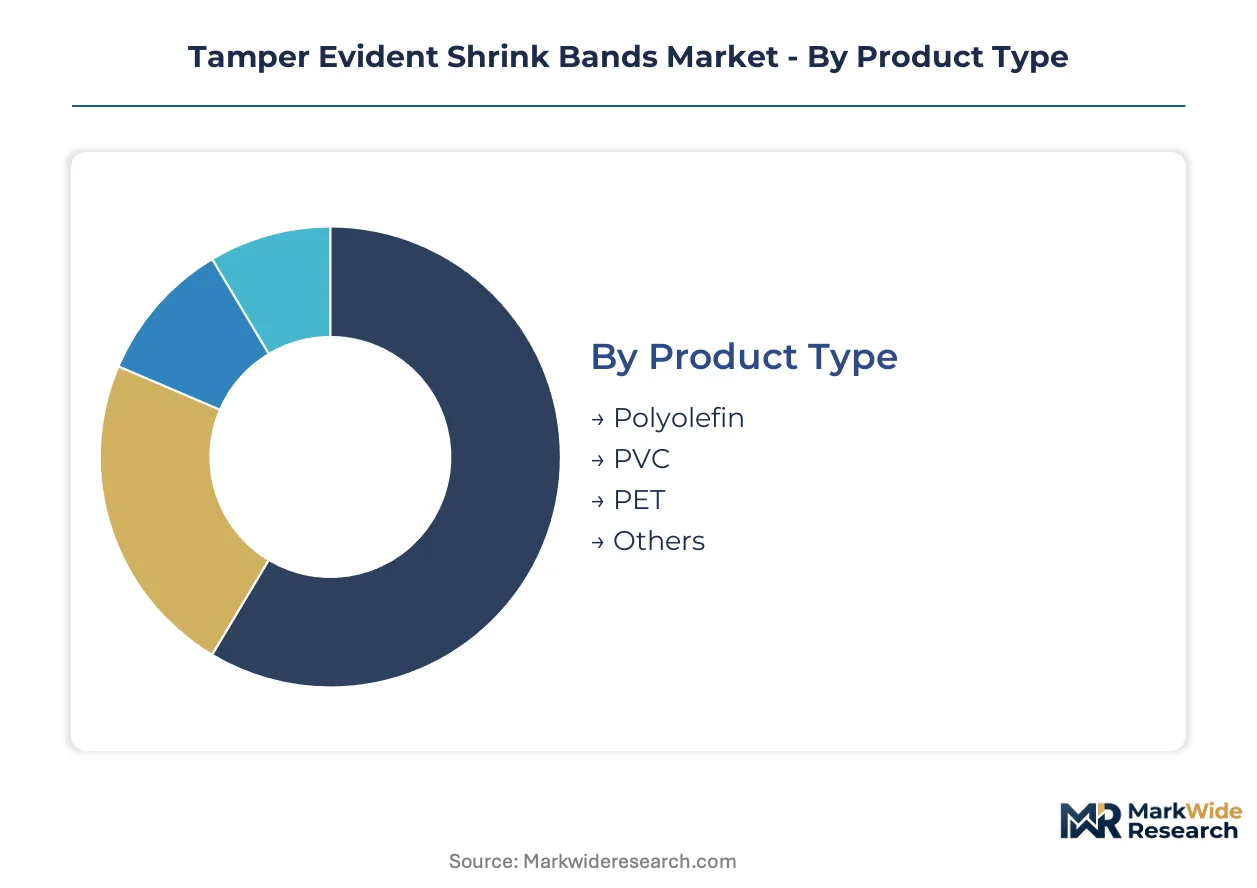
Segmentation in the tamper evident shrink bands market reveals how material chemistry, regulatory compliance tiers, and channel economics partition value capture. Procurement patterns diverge sharply between pharmaceutical serialization mandates and cost-driven food packaging volumes.
Product Type:
Margin pools concentrate in pharmaceutical-grade clarity films where FDA compliance and low extractables command price premiums over commodity food-packaging grades.
- Polyolefin:Cross-linked formulations deliver 70% shrink force at 90°C with optical clarity matching PVC. Pharmaceutical contract packagers in the United States are accelerating qualification cycles to meet FDA unit-level traceability requirements, displacing legacy materials in parenteral vial applications.
- PVC:Legacy formulations retain residual share in over-the-counter applications where regulatory scrutiny remains lighter. REACH Annex XVII phthalate restrictions are compressing European demand, with German and French converters completing phase-out transitions by 2026.
- PET:Glycol-modified variants (PET-G) offer heat-seal compatibility with existing steam-tunnel infrastructure. Beverage bottlers facing $200,000-$400,000 retrofit costs for polyolefin precision are adopting PET-G as a bridge material.
- Others:PLA and bio-based alternatives occupy niche sustainability positioning for premium organic food brands.
Polyolefin holds installed capacity. PET is rotating up the share rankings.
Application:
Application segmentation tracks divergent procurement logics: pharmaceutical buyers prioritize compliance documentation while food and beverage procurement emphasizes unit cost and line speed compatibility.
- Food & Beverages:High-volume bottling operations in carbonated soft drinks and condiments drive procurement scale. Downgauging to 30-micron films has achieved cost parity with legacy PVC, though heat-tunnel retrofit requirements slow material transition in 1980s-era steam infrastructure.
- Pharmaceuticals:Serialization-ready bands with integrated 2D DataMatrix codes are displacing separate label-and-band combinations. New Jersey's pharmaceutical packaging corridor concentrates demand, with three contract packagers accounting for majority regional volume.
- Personal Care:Premium cosmetic brands leverage tamper evidence for brand authentication in direct-to-consumer channels.
- Household Products:Bleach and cleaning chemical applications prioritize chemical resistance and perforation reliability over optical clarity.
Food and beverages holds installed capacity. Pharmaceuticals is climbing the fastest.
End User:
Channel concentration is restructuring supplier relationships, with contract packaging consolidation compressing vendor bases and unbundling decoration from tamper evidence functions.
- Manufacturers:In-house packaging lines at generic drug producers and beverage bottlers specify direct procurement of printed bands with integrated serialization codes.
- Retailers:Private-label food and personal care brands are standardizing band specifications across supplier portfolios to simplify quality assurance.
- Distributors:Industrial chemical and janitorial supply channels prioritize perforation reliability and chemical resistance over printed decoration.
- E-Commerce:Direct-to-consumer nutraceutical and premium cosmetic shipments are driving demand for tamper evidence that photographs clearly for unboxing verification.
Manufacturers holds installed capacity. E-commerce is gaining share fastest.
Feature:
Feature differentiation is migrating from physical perforation patterns to digital integration and sustainability certification as procurement criteria evolve.
- Customizable:Digital printing convergence at mid-size converters enables short-run customized tamper graphics without plate costs, opening craft beverage and nutraceutical segments.
- Eco-Friendly:PP and PET-G formulations that sort cleanly in European mechanical recycling streams capture preferential placement with multinational CPG brands facing extended producer responsibility compliance.
- Heat Shrinkable:Precise temperature window requirements for polyolefin are raising retrofit costs for legacy steam-tunnel infrastructure.
- Block Strain:High-shrink-force formulations for irregular container geometries command premium positioning in specialty pharmaceutical vial applications.
Heat shrinkable holds installed capacity. Eco-friendly is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian pharmaceutical exporters are shipping serialization-ready shrink bands to United States contract packagers, while German converters supply REACH-compliant formulations across European personal care supply chains.
United States
FDA Drug Supply Chain Security Act deadlines are pulling premium-grade band volumes into compliance-tier supply chains. Generic drug producers in New Jersey, Pennsylvania, and North Carolina are consolidating procurement power across contract packaging networks. Three contract packagers in New Jersey's pharmaceutical corridor now account for majority regional band volume.
Germany
REACH Annex XVII phthalate restrictions are compressing PVC demand as converters complete phase-out transitions by 2026. ECHA enforcement guidance treats shrink bands as articles subject to SVHC disclosure requirements. Industrial clusters in North Rhine-Westphalia and Baden-Württemberg are pivoting toward PET-G and oriented PP film extrusion.
India
CDSCO alignment with FDA quality standards is positioning Mumbai and Hyderabad as contract packaging hubs for North American generic drug shipments. Domestic formulators are qualifying serialization-ready bands for export manufacturing. Maharashtra and Telangana pharmaceutical clusters are driving specification upgrades across supplier bases.
China
NMPA track-and-trace requirements for domestic pharmaceutical distribution are expanding tamper evidence adoption beyond export-oriented production. Yangtze River Delta and Pearl River Delta converters are scaling thin-gauge polyolefin capacity. Zhejiang and Jiangsu provinces are capturing regional supply chain reconfiguration.
Japan
METI packaging recyclability guidelines are favoring polyolefin and PET-G formulations over legacy PVC in consumer goods applications. PMDA pharmaceutical serialization mandates are tightening specification requirements for domestic drug packaging. Osaka-based converters are supplying high-clarity bands for parenteral drug vial applications.
Tamper Evident Shrink Bands Market Competitive Landscape
Listed leaders compete with private specialists across film extrusion and printed decoration capabilities. The supplier base organizes around three tiers: integrated multinationals with captive resin production, regional converters with pharmaceutical-grade certification, and commodity specialists serving food and beverage volumes. Competitive positioning hinges on backward integration into polymer compounding, qualification speed for serialization-ready formats, and cleanroom certification status for regulated end uses. M&A activity targets mid-size converters with established FDA audit trails, while capacity expansion concentrates in polyolefin film extrusion for pharmaceutical clarity specifications.
Within the integrated multinational tier, CCL Industries Inc. and Berry Global Inc. exemplify divergent scale strategies, with the former leveraging in-house production of printed decoration and the latter anchoring North American volume through multi-site distribution networks. Fuji Seal International, Inc. occupies a position representing technology leadership in thin-gauge formulations for Asian export markets. Klöckner Pentaplast Group and Bonset America Corporation sit within the specialized film extrusion archetype, serving converters and brand owners with substrate supply rather than finished band fabrication. Private specialists including Traco Manufacturing, Inc., Hind Polymers, ATW Manufacturing Company, and American Film & Machinery represent regional fabrication capacity across diverse geographic markets.
| Leading Market Players |
|---|
| Berry Global Inc. |
| CCL Industries Inc. |
| Fuji Seal International, Inc. |
| Klöckner Pentaplast Group |
| Bonset America Corporation |
| Traco Manufacturing, Inc. |
| Hind Polymers |
| ATW Manufacturing Company |
| American Film & Machinery |
| Others |
Value Network & Pricing Analysis
Polyolefin displacement of PVC formulations simultaneously redraws supply geography toward North American and European extrusion hubs and compresses pricing premiums previously commanded by legacy material clarity grades. Pharmaceutical contract packagers in New Jersey and Pennsylvania now capture volume leverage as resin qualification cycles favor suppliers with integrated FDA audit trails, while food-grade converters face margin compression from thin-gauge downgauging economics.
Pricing Analysis
Cross-linked polyolefin formulations command 15-25% premiums over legacy PVC clarity grades, with PET-G bridge materials occupying intermediate positioning for beverage bottlers avoiding heat-tunnel retrofit capital. Pricing stratifies across pharmaceutical-grade ISO 15378 certification, food-grade standard specifications, and unprinted economy tiers for industrial chemical applications. Cost compression in food-grade segments intensifies as 30-micron downgauging achieves resin parity with PVC, though pharmaceutical buyers show lowest price sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
German and Italian blown film extrusion capacity creates a chokepoint for pharmaceutical-grade clarity bands, constraining Asian and Latin American formulator access to high-output lines. Supply draws from ethylene and propylene feedstock streams anchored in United States Gulf Coast and Middle Eastern petrochemical complexes, with resin price volatility transmitting directly to converter margins. Single-source vulnerability concentrates in cleanroom-certified extrusion facilities, while distribution runs through pharmaceutical contract packaging networks in New Jersey, Pennsylvania, and North Carolina consolidating procurement power.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Serialization-ready band supply represents a service-attach opportunity expanding faster than commodity film fabrication, as qualification documentation and regulatory compliance support command recurring revenue streams beyond unit sales.
For Market Incumbents: Fortify backward integration into polymer compounding to defend margin position against resin price volatility, while accelerating cleanroom certification capacity additions in United States pharmaceutical corridors to capture contract packaging consolidation. Cross-linked polyolefin R&D investment and FDA 21 CFR Part 211 audit trail maintenance represent critical defensive levers against emerging Asian competitors. For New Entrants and Emerging Players: Digital printing service gaps at mid-size converters create white-space openings for short-run customized tamper graphics without plate costs, particularly in craft beverage and direct-to-consumer nutraceutical channels. Target e-commerce verification photography requirements as the most penetrable feature segment, with HP Indigo press partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward mid-size converters with established FDA audit trails and existing pharmaceutical-grade certification, as M&A activity concentrates on qualification speed advantages over greenfield capacity buildout. Long-term viability over a multi-year horizon favors suppliers with backward integration into film extrusion and printed decoration capabilities; the signal to watch is CDSCO-FDA alignment progress in Indian export manufacturing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | CCL Industries leverages captive resin production to buffer margin compression from ethylene feedstock volatility. |
| Cleanroom Certification Capacity Expansion | ISO 15378-compliant extrusion lines in New Jersey capture contract packaging procurement consolidation. |
| Digital Printing Technology Partnership | HP Indigo press installations enable short-run craft beverage customization without plate cost barriers. |
| Serialization-Ready Format Qualification | FDA Drug Supply Chain Security Act compliance converts tamper evidence from optional feature to market-access prerequisite. |
| Asian Export Manufacturing Footprint | Mumbai and Hyderabad pharmaceutical clusters position suppliers for CDSCO-aligned North American generic drug shipments. |
Research Methodology
A spread of perspectives from pharmaceutical packaging engineers, contract procurement managers, film extrusion plant operators, and regulatory affairs specialists converged on the working assumptions underlying supply and demand projections. Primary fieldwork combined structured interviews with secondary validation through FDA 21 CFR filings, ECHA REACH registration databases, CDSCO quality standard circulars, and SEC 10-K disclosures from listed packaging converters. Bottom-up volume builds from end-use application segments triangulated against top-down resin consumption estimates from petrochemical trade associations.
Segmentation dimensions modeled span material chemistry tiers, application compliance grades, end-user channel structures, and feature integration levels across the projection horizon. CAGRs derive from regression analysis of historical pharmaceutical packaging expenditure patterns and food and beverage capital equipment replacement cycles, with cross-linking technology adoption curves and serialization mandate implementation timelines as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA Drug Supply Chain Security Act enforcement and REACH Annex XVII phthalate restriction timelines; material policy shifts in either regime would require re-modeling of material substitution trajectories and pharmaceutical procurement specifications. Practitioners should keep alternative scenarios live as state-level extended producer responsibility frameworks and NMPA track-and-trace expansion timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Latin America Single-Use Packaging Market
Packaging Materials
Sterilization Roll Market
Packaging Materials
Global Strapping Market
Packaging Materials
Thailand Packaging Market
Packaging Materials
Urn Liners Market
Packaging Materials
VCI Packaging Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Foam Trays Market
Packaging Materials
Middle East and Africa Single-Use Packaging Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
Coconut Wraps Market
Packaging Materials
PVC Packing Straps Market
Packaging Materials
Lid Laminates Market
Packaging Materials
Nigeria Packaging Market