
 New Packages and Materials for Power Devices Market | 2026-2036
New Packages and Materials for Power Devices Market Size, Share, and Industry Trends Forecast 2026-2036
New Packages and Materials for Power Devices Market Outlook
Automotive OEM procurement is rotating from traditional silicon-based power modules toward wide-bandgap packages as electrification programs expand. Infineon Technologies anchors European supply through captive silicon carbide substrate capacity and module assembly in Austria. STMicroelectronics leverages vertically integrated gallium nitride R&D from its French and Italian facilities to differentiate in high-frequency traction inverters. Texas Instruments competes through proprietary copper-clip packaging technology that improves thermal cycling reliability for under-the-hood applications.
New packages and materials for power devices encompass engineered housings, die-attach substrates, thermal interface materials, and encapsulants designed to manage heat dissipation above 175°C junction temperatures while maintaining electrical isolation for semiconductor switches. These systems enable higher power density in compact footprints critical for electric drivetrains and grid-scale inverters. Power modules dominate value capture due to their integration complexity and thermal management requirements, while silicon carbide material types command premium positioning as wafer costs decline and 800V architectures proliferate. Electric vehicle applications absorb the fastest volume growth, though industrial automation sustains steadier replacement cycles with less price volatility.
REACH substance restrictions in Europe constrain traditional epoxy molding compound formulations, while China's GB standards mandate accelerated reliability testing for automotive power modules sold domestically. The US EPA and NHTSA coordinate on lifecycle emissions rules that indirectly favor efficient wide-bandgap packages by tightening energy conversion loss thresholds. Stakeholders must monitor how Japan's METI updates JIS thermal characterization standards, as these protocols cascade into procurement specifications across Asian supply chains and determine qualified vendor lists for tier-one module assemblers.
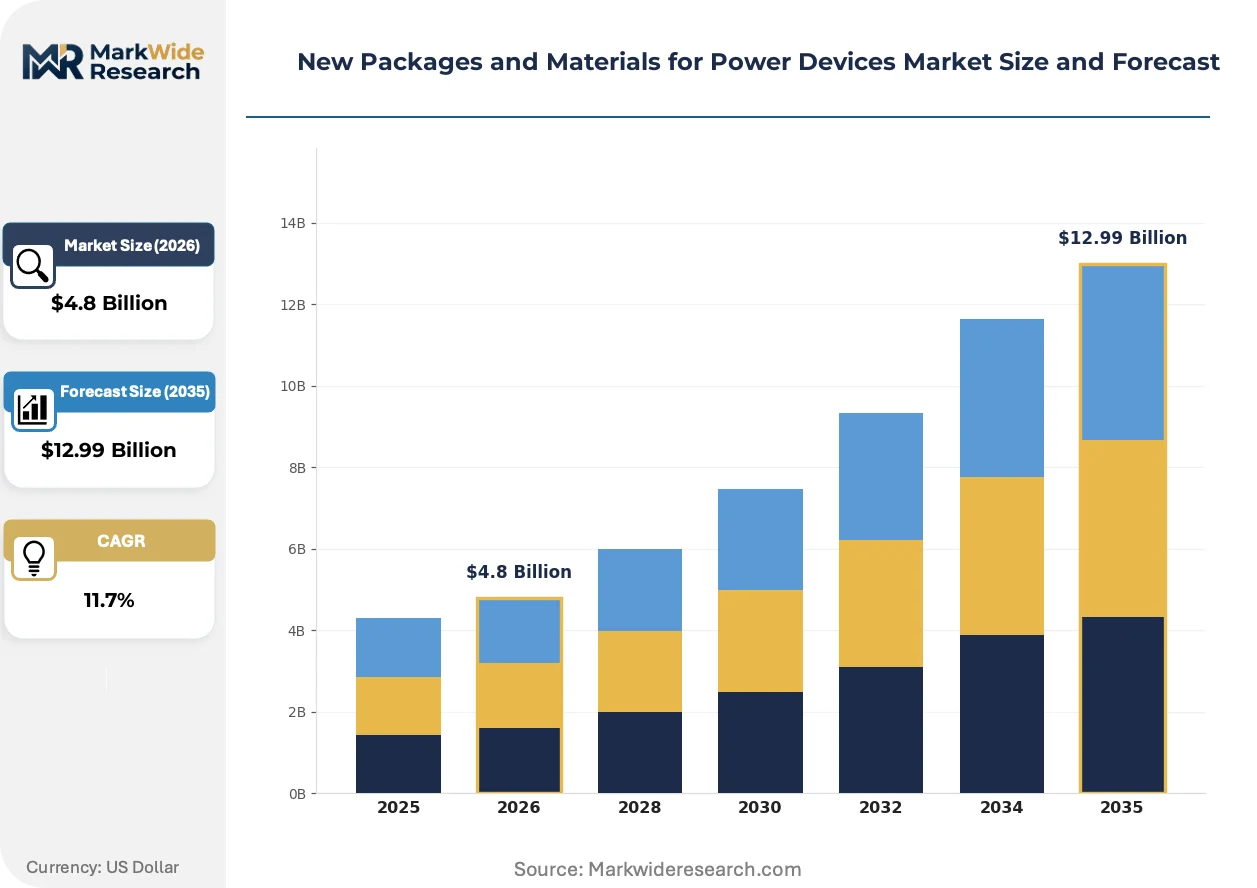
Market Dynamics
Silicon carbide substrate transitions are compressing qualification timelines for automotive power module suppliers, forcing packaging houses to validate thermal cycling performance under 800V electrical stress before securing volume contracts with electrification programs.
Growth Catalysts
- 800V Architecture Proliferation:Electric vehicle platforms above 400V demand ceramic substrates and silver-sintered die-attach materials that withstand higher switching frequencies. Tier-one drivetrain suppliers in Germany's automotive corridor are qualifying these packages for series production.
- REACH Substance Restrictions:ECHA's tightening limits on halogenated flame retardants in epoxy molding compounds are accelerating R&D into bio-based encapsulant formulations. European module assemblers must reformulate by 2026 to maintain market access.
- China's NMPA Certification:Domestic GB standards for automotive power modules now mandate accelerated thermal shock testing. Foreign suppliers seeking qualification must establish local testing partnerships or joint ventures with Chinese substrate manufacturers.
Market Restraints
- Silicon Carbide Wafer Cost Concentration:Six-inch SiC substrate supply concentrates among three merchant vendors, creating input cost volatility that compresses gross margins for packaging houses unable to secure long-term supply agreements.
- Copper Thermal Interface Material Shortage:High-purity copper foil for direct-bonded substrates faces allocation constraints from electronics and battery sectors simultaneously, extending lead times for power module prototypes.
- Silver Sintering Equipment Capex:Transition from solder die-attach to silver sintering requires press systems exceeding two million dollars per line, creating a capital barrier for mid-tier assemblers serving industrial automation.
Strategic Opportunities
- India's PLI Scheme for Semiconductors:Production-linked incentives for compound semiconductor fabs create a greenfield opportunity for packaging joint ventures serving domestic solar inverter and railway traction markets.
- Aviation Electrification:FAA certification pathways for more-electric aircraft are opening procurement channels for lightweight silicon nitride substrates in auxiliary power units, with thermal management requirements distinct from automotive.
- Grid-Scale Storage Integration:FERC interconnection rule reforms are compressing project timelines for utility-scale battery inverters, pulling demand for high-reliability modules that withstand decade-long service intervals without maintenance.
Industry Challenges
- Silver Sintering Process Control:Maintaining void-free bond lines below five microns requires thermal profile expertise scarce among traditional solder technicians, forcing retraining investments at module assembly lines.
- Multi-Physics Simulation Talent:Coupled electro-thermal-mechanical modeling for package reliability prediction demands engineers fluent in both semiconductor physics and computational fluid dynamics, a skill intersection with limited labor supply.
- JIS Thermal Characterization Alignment:METI's pending updates to junction-to-case measurement protocols are creating certification uncertainty, with Asian module houses delaying new product introductions until test standards stabilize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Packages and Materials for Power Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Modules, Thermistors, Capacitors, Inductors Material Type: Silicon, Gallium Nitride, Silicon Carbide, Ceramic Application: Electric Vehicles, Renewable Energy, Industrial Automation, Consumer Electronics Packaging Type: Surface Mount, Through-Hole, Leadless, Dual In-Line |
| Companies Covered | Infineon Technologies, STMicroelectronics, Texas Instruments, Mitsubishi Electric, Fuji Electric, onsemi, Semikron Danfoss, StarPower, BYD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Packages and Materials for Power Devices Market Strategic Shifts
Packaging architectures are fragmenting between legacy wire-bonded modules and emerging clip-based and embedded-die configurations, with thermal management materials becoming the primary differentiation lever as junction temperatures push past 200°C.
Silver sintering paste is decomposing the traditional solder die-attach hierarchy in high-power modules. Automotive inverter suppliers are qualifying sintered joints for 250°C continuous operation, a threshold impossible with lead-free solder alloys. This thermal headroom is decomposing the historical trade-off between power density and reliability, enabling smaller module footprints without derating.
REACH authorization requirements for bisphenol-A derivatives are forcing encapsulant suppliers to commercialize phenolic and silicone-alternative formulations. European power module houses face reformulation deadlines that coincide with automotive platform requalification cycles, compressing validation windows. Industrial inverter manufacturers are accelerating alternative material adoption to avoid supply disruption.
Electric vehicle OEMs are consolidating supplier panels from twelve qualified module sources to four strategic partners per platform. Tier-one drivetrain integrators are responding with captive packaging investments and exclusive die-attach material partnerships. This concentration is most visible in Germany, where Volkswagen, BMW, and Mercedes-Benz have each announced dedicated power module supply agreements with single-source packaging houses.
New Packages and Materials for Power Devices Market Segmentation
Segmentation in power device packaging reveals how thermal performance requirements and substrate material economics fragment procurement patterns across automotive and industrial end-uses. Each dimension exposes distinct supplier qualification barriers and pricing power concentrations.
Product Type:
Substitution pressure from integrated wide-bandgap solutions threatens discrete component categories most exposed to module consolidation trends.
- Power Modules:Integrated assemblies combining multiple semiconductor dies with ceramic substrates, baseplates, and encapsulants in single thermal management systems. German automotive OEMs in the Dresden-Munich corridor are consolidating supplier panels to three-to-four strategic partners per electrification platform, concentrating volume among assemblers with captive silicon carbide substrate access. Power modules anchor the volume base while thermistors gain share at the steepest rate.
- Thermistors:Temperature-sensitive resistive elements providing junction temperature feedback for active thermal management algorithms. Demand concentrates in 800V traction inverters where real-time temperature sensing prevents thermal runaway during fast-charging cycles.
- Capacitors:DC-link and snubber components managing voltage ripple in switching circuits.
- Inductors:Magnetic energy storage elements filtering high-frequency noise from wide-bandgap switching transitions.
Module integration is displacing discrete component procurement in high-power applications above 50kW.
Material Type:
Cost tier stratification separates premium wide-bandgap substrates from commodity silicon in pricing and qualification timelines.
- Silicon Carbide:Wide-bandgap semiconductor material enabling 175°C+ junction temperatures with switching losses one-tenth of silicon equivalents. Six-inch wafer supply concentrates among three merchant vendors, creating input cost volatility that compresses packaging house margins without long-term supply agreements. Silicon carbide anchors the volume base while gallium nitride gains share at the steepest rate.
- Gallium Nitride:High-electron-mobility transistor material optimized for frequencies above 100kHz in onboard chargers and DC-DC converters. STMicroelectronics leverages vertically integrated R&D from French and Italian facilities to differentiate in high-frequency traction inverters.
- Silicon:Mature semiconductor substrate dominating cost-sensitive industrial automation below 400V operating voltages.
- Ceramic:Aluminum oxide and aluminum nitride substrates providing electrical isolation with thermal conductivity above 170W/mK for direct-bonded copper applications.
Silicon retains dominance in replacement-cycle industrial markets while wide-bandgap materials capture all incremental automotive electrification investment.
Application:
Customer type divergence separates automotive qualification intensity from industrial automation's steadier replacement economics.
- Electric Vehicles:Traction inverters, onboard chargers, and DC-DC converters demanding compact footprints above 400V architectures. 800V platform proliferation is pulling ceramic substrate and silver-sintered die-attach demand from tier-one drivetrain suppliers in Germany. Electric vehicles anchor the volume base while renewable energy gains share at the steepest rate.
- Renewable Energy:Grid-scale solar inverters and wind turbine converters requiring decade-long service intervals without maintenance. FERC interconnection rule reforms are compressing project timelines for utility-scale battery inverters.
- Industrial Automation:Motor drives and power supplies with less volatile pricing and longer supplier relationships than automotive.
- Consumer Electronics:Low-power adapters and chargers below 100W where cost minimization dominates thermal performance.
Automotive applications absorb capital investment while industrial segments provide margin stability through replacement cycles.
Packaging Type:
Supply concentration in high-reliability surface mount and leadless formats contrasts with fragmented through-hole availability.
- Surface Mount:Solderable packages enabling automated assembly with direct thermal path to printed circuit boards. REACH substance restrictions on halogenated flame retardants in epoxy molding compounds are accelerating reformulation timelines for European module assemblers. Surface mount anchors the volume base while leadless packages gain share at the steepest rate.
- Leadless:QFN and DFN configurations eliminating wire bonds for improved thermal cycling reliability in under-the-hood applications. Texas Instruments competes through proprietary copper-clip technology variants in this category.
- Through-Hole:Pin-insertion packages retained in high-voltage industrial equipment for mechanical robustness.
- Dual In-Line:Legacy through-hole format with limited new design-ins outside replacement markets.
Surface mount dominates new design activity while leadless formats capture share in thermally stressed automotive locations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao-Jinan high-speed rail corridor underwrites China's eastern seaboard dominance in power module assembly, while Germany's Rhine-Main-Danube waterway network anchors European substrate logistics for automotive qualification programs.
China
Domestic EV production exceeding six million units annually pulls ceramic substrate demand through BYD and StarPower assembly lines. NMPA's updated GB standards for automotive power modules mandate accelerated thermal shock testing protocols that foreign suppliers must satisfy through local joint ventures. The Yangtze River Delta cluster around Shanghai concentrates silver sintering paste production and die-attach equipment manufacturing.
Germany
Volkswagen, BMW, and Mercedes-Benz electrification programs each consolidate supplier panels to single-source packaging houses per platform. ECHA's REACH substance restrictions on halogenated flame retardants force epoxy molding compound reformulation by 2026. The Dresden-Munich automotive semiconductor corridor hosts Infineon Technologies' captive silicon carbide substrate capacity and module assembly operations.
United States
Texas Instruments' copper-clip packaging technology competes for under-the-hood thermal cycling applications in Detroit Three electrification programs. EPA and NHTSA coordinate lifecycle emissions rules that tighten energy conversion loss thresholds favoring wide-bandgap packages. The Pacific Northwest grid interconnect infrastructure pulls demand for utility-scale inverter modules serving FERC-interconnection reform timelines.
Japan
Mitsubishi Electric and Fuji Electric anchor domestic supply for industrial automation replacement cycles with steadier pricing than automotive segments. METI's pending JIS thermal characterization updates create certification uncertainty delaying new product introductions. The Kyushu silicon carbide wafer production cluster supplies substrate inputs to packaging houses across East Asian supply chains.
India
PLI scheme production-linked incentives for compound semiconductor fabs attract packaging joint venture proposals targeting domestic solar inverter and railway traction markets. Central Electricity Authority regulations for grid-scale storage mandate decade-long service intervals without maintenance. The Gujarat-Maharashtra industrial corridor concentrates projected module assembly capacity for renewable energy integration.
New Packages and Materials for Power Devices Market Competitive Environment
Concentration sits with diversified semiconductor conglomerates and captive automotive suppliers. Three merchant vendors control six-inch silicon carbide substrate supply, creating tiered access that separates premium module assemblers from cost-pressured competitors. Strategic archetypes include vertically integrated substrate-to-module houses, fabless packaging specialists with exclusive material partnerships, and automotive-captive assemblers with single-source platform agreements. Dominant competitive moves span exclusive die-attach material partnerships and captive substrate capacity investments.
Among European diversified conglomerates, Infineon Technologies and STMicroelectronics exemplify the vertically integrated archetype through in-house silicon carbide substrate production and gallium nitride R&D respectively. Texas Instruments occupies a position representing North American packaging technology differentiation through proprietary thermal management approaches. These three anchors demonstrate how geographic R&D clustering and captive supply control shape competitive positioning without requiring equivalent scale in module assembly volume.
| Leading Market Players |
|---|
| Infineon Technologies |
| STMicroelectronics |
| Texas Instruments |
| Mitsubishi Electric |
| Fuji Electric |
| onsemi |
| Semikron Danfoss |
| StarPower |
| BYD |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for six-inch silicon carbide wafers lock in both substrate access and price visibility for German automotive module assemblers, insulating tier-one suppliers from spot-market volatility while compressing margins for packaging houses without captive supply. These contractual structures concentrate pricing power among three merchant wafer vendors, forcing downstream players to absorb input cost swings or surrender volume to integrated competitors.
Pricing Analysis
Volume-discount tiering structures separate strategic automotive partnerships from transactional industrial procurement. Three-tier pricing stratifies across automotive-qualified modules, industrial-grade replacements, and cost-optimized consumer electronics packages. Price differentiation hinges on thermal cycling certification grade and volume scale, with automotive OEMs commanding steepest discounts through multi-year platform commitments. Cost compression in standard-grade silicon modules intensifies as Chinese packaging houses expand capacity. Industrial automation buyers exhibit highest price sensitivity due to replacement-cycle economics, while aviation electrification programs show least sensitivity given FAA certification barriers.
Supply Chain Analysis
Inbound logistics costs from Yangtze River Delta ports to European module assembly lines fluctuate with container availability on Asia-North Europe trade lanes, compressing landed cost predictability for ceramic substrate shipments. Geographic supply concentration centers on China for silver sintering paste production, Japan for silicon carbide wafer fabrication, and Germany for automotive module qualification. Raw material dependencies include high-purity copper foil for direct-bonded substrates, ceramic aluminum nitride for thermal management, and silver nanoparticle paste for die-attach. Single-source vulnerability runs through six-inch SiC substrate supply. Distribution feeds from captive substrate production through tier-one assembler hubs to OEM drivetrain integration plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across packaging architectures and material qualification timelines creates niche entry points for specialists, as 800V platform proliferation splinters procurement requirements beyond the capacity of consolidated incumbents to serve all thermal performance tiers simultaneously.
For Market Incumbents: Secure captive silicon carbide substrate capacity through long-term wafer supply agreements or backward integration into six-inch boule production, insulating margin structures from merchant vendor pricing power. Infineon Technologies' Austrian module assembly operations demonstrate how upstream control over substrate inputs defends positioning against emerging Chinese packaging houses. Accelerate REACH-compliant encapsulant reformulation ahead of ECHA's halogenated flame retardant deadlines to avoid automotive platform disqualification. For New Entrants and Emerging Players: Lead with silver sintering process expertise targeting India's PLI-supported compound semiconductor packaging ventures, where domestic solar inverter and railway traction demand outpaces qualified local supply. Aviation electrification auxiliary power units represent the most penetrable segment, with thermal management requirements distinct from automotive and lighter FAA certification pathways than main propulsion systems. Establish joint ventures with Chinese substrate manufacturers to satisfy NMPA GB standard testing mandates for automotive market access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among packaging houses with exclusive die-attach material partnerships locking automotive OEMs into multi-platform supply agreements. Long-term viability over the projection horizon favors vertically integrated substrate-to-module specialists over fabless assemblers exposed to wafer cost volatility. Target acquisition archetypes include mid-tier European packaging houses with REACH-compliant material portfolios and established automotive qualification records. Watch for JIS thermal characterization standard stabilization as the inflection signal triggering delayed new product introductions across Asian supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Silicon Carbide Substrate Investment | Backward integration into six-inch wafer production secures input cost predictability for German automotive module assemblers. |
| Silver Sintering Process Qualification | Void-free die-attach capability above 250°C continuous operation unlocks 800V traction inverter procurement from tier-one drivetrain suppliers. |
| REACH-Compliant Encapsulant Reformulation | Bio-based epoxy molding compound development maintains European market access ahead of ECHA halogenated flame retardant restrictions. |
| India PLI Packaging Joint Venture | Domestic module assembly capacity addresses CEA-mandated decade-long service intervals for grid-scale solar inverter deployments. |
| Aviation Electrification Certification Pathway | FAA qualification for silicon nitride substrates in auxiliary power units opens procurement distinct from automotive thermal requirements. |
Study Parameters
The analysis maps power module architectures, die-attach material categories, ceramic substrate grades, and encapsulant formulations, each validated through packaging house engineering directors, automotive OEM procurement leads, Tier 1 drivetrain supplier quality managers, and silver sintering equipment manufacturers. Primary interviews combined with secondary validation from SEC semiconductor company filings, ECHA REACH substance restriction updates, NMPA GB standard documentation, and METI JIS thermal characterization drafts. Bottom-up substrate wafer supply modeling and top-down automotive electrification platform demand estimates underwent triangulation.
Consistency checks validated volume and value outputs against IHS Markit vehicle production databases, IEA grid-scale inverter deployment tracking, and customs records for ceramic substrate trade flows. The analytical framework segments by product type, material substrate, end-use application, and packaging format across the projection horizon. CAGRs derived from coupled adoption curves for 800V architectures and silver sintering process penetration. Industry-specific forecast inputs include silicon carbide wafer cost decline trajectories and REACH reformulation timeline constraints.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification investment, stable silicon carbide substrate supply expansion, or unaltered REACH substance restriction timelines would require recalibration. Forecasts reflect documented assumptions regarding wide-bandgap adoption rates and regulatory standard evolution. Technology substitution toward gallium nitride in onboard chargers, trade policy disruptions affecting ceramic substrate logistics, or JIS thermal characterization standard delays represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Food Grade Sealant Market
Packaging Materials
Tube Packaging Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Cargo Moisture Control Products Market
Packaging Materials
Middle East and Africa Single-Use Packaging Market
Packaging Materials
Chemical Packaging Market
Packaging Materials
Global Thin Wall Packaging Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Punnet Packaging Market
Packaging Materials
Protein Packaging Market
Packaging Materials
Expendable Packaging Market
Packaging Materials
Asia - Pacific Disposable Tableware Market
Packaging Materials
Cork Packaging Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Twist Tie Market