
 Food Grade Sealant Market | 2026-2036
Food Grade Sealant Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Sealant Market Analytics
NSF H1-certified silicone formulations is reorganizing procurement priorities across European dairy and beverage processing facilities. Henkel AG & Co. KGaA leverages its adhesive-sealant portfolio to dominate food-safe bonding applications in German automation lines. Wacker Chemie AG anchors silicone supply through captive silicone polymer production in Burghausen. Dow Inc. competes on fluorosilicone expertise for thermal cycling resistance in industrial ovens.
Food grade sealants are elastomeric or thermoset compounds formulated to comply with migration limits under FDA 21 CFR 177.2600 and EU Regulation 10/2011, serving primarily to create impermeable barriers in processing equipment, packaging seams, and cold-storage envelopes where microbial ingress must be prevented. Silicone sealants lead product type revenue due to their operational temperature span from minus sixty to plus two hundred degrees Celsius and established compliance pedigree, while polyurethane sealants represent the fastest-growing category driven by demand for high-strength flexible bonds in automated packaging lines. Application segmentation shows food processing equipment assembly commanding the largest volume share, though packaging sealant demand is accelerating as aseptic and modified-atmosphere formats multiply across European retail channels.
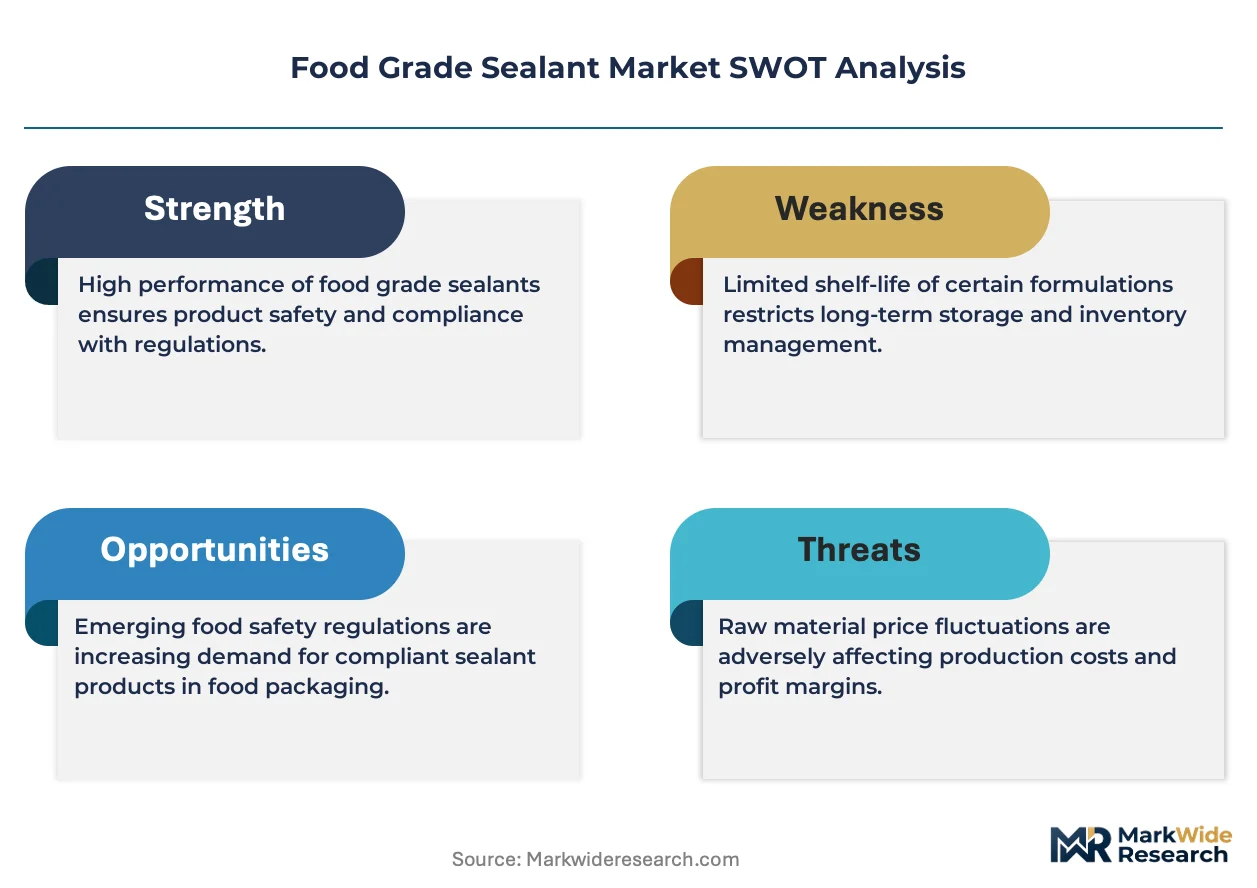
FDA migration testing protocols, EU Regulation 10/2011 on plastic materials in contact with food, and NSF/ANSI 61 potable water standards collectively define formulation boundaries and certification costs for sealant producers seeking multi-jurisdiction market access. Germany's Federal Institute for Risk Assessment enforces additional national scrutiny on silicone volatile organic compound profiles, tightening entry for uncertified imports. Stakeholders must monitor evolving EU Green Deal chemical restriction lists and decide whether to front-run compliance investments or segment regional product portfolios.
Market Dynamics
NSF H1 certification requirements are restructuring procurement priorities across European dairy and beverage processing facilities, forcing facility operators to replace legacy sealant inventories with migration-compliant formulations ahead of EU hygiene audits.
Growth Catalysts
- EU Regulation 10/2011 migration limits:Dairy processors in Germany and France must upgrade to compliant silicone formulations, creating replacement demand across aging processing infrastructure.
- Aseptic packaging expansion:Modified-atmosphere packaging lines for ready-to-eat meals require high-integrity seals that prevent microbial ingress during extended shelf-life distribution.
- Silicone polymer supply security:Captive production facilities in Bavaria reduce import dependency for critical raw materials serving Central European formulators.
Market Restraints
- Silicone volatile organic compound scrutiny:Germany's Federal Institute for Risk Assessment imposes additional national testing protocols beyond EU baselines, extending certification timelines for imported formulations.
- Fluorosilicone raw material concentration:Thermal cycling-resistant grades depend on specialized fluoroelastomer feedstocks with limited European manufacturing capacity.
- Polyurethane substitution threat:High-strength flexible bonds in automated packaging lines increasingly favor polyurethane systems for mechanical durability in high-speed line conditions.
Strategic Opportunities
- Italian artisan dairy modernization:Small-scale cheese producers face compliance gaps with current NSF certification coverage, opening service-model opportunities for certified application contractors.
- Cold-storage envelope retrofits:Energy efficiency mandates under EU Green Deal chemical restriction lists accelerate sealant replacement in refrigerated logistics infrastructure.
- Digital compliance documentation:Blockchain-tracked certification records streamline multi-jurisdiction audits for sealant producers serving both FDA and EU regulated facilities.
Industry Challenges
- Formulation chemist scarcity:Migration testing expertise under FDA 21 CFR 177.2600 and EU protocols requires specialized training pipelines that European technical universities have not scaled to match demand.
- Dual-certification capex burden:Producers seeking simultaneous FDA and EU market access must maintain parallel testing laboratories, duplicating validation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Sealant Market |
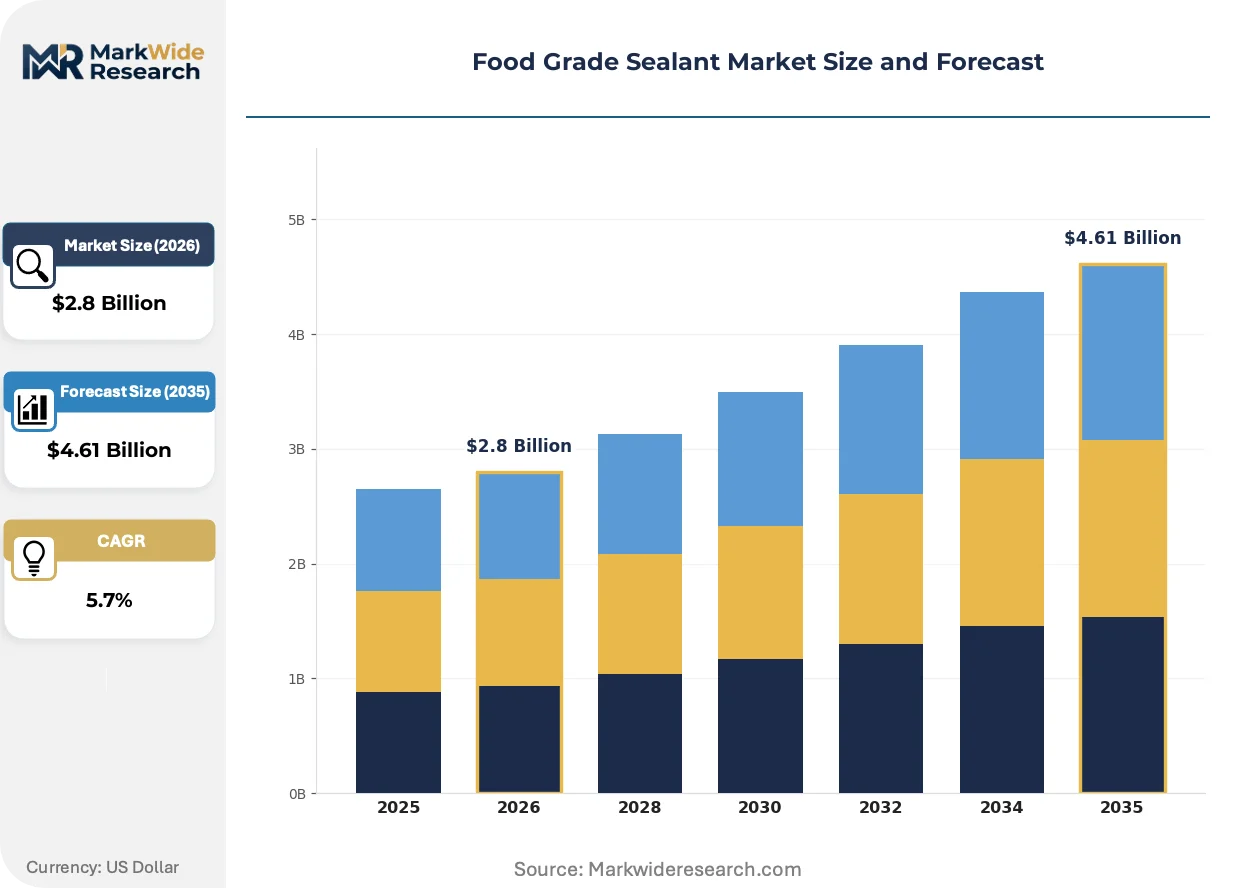
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Sealants, Polyurethane Sealants, Acrylic Sealants, Epoxy Sealants Application: Food Processing, Packaging, Equipment Assembly, Storage Solutions End User: Food Manufacturers, Retailers, Distribution Centers, Restaurants Certification: FDA Approved, NSF Certified, BRC Compliant, ISO Certified |
| Companies Covered | 3M Company, H.B. Fuller Company, Henkel AG & Co. KGaA, Sika AG, Dow Inc., Shin-Etsu Chemical, Elkem Silicones, Wacker Chemie AG, CHT Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Sealant Market Evolving Landscape
Active reformulation toward low-migration silicone architectures is compressing product development cycles while regulatory digitization and procurement centralization reshape how processing facilities source certified materials.
Advanced fluorosilicone compounds with enhanced thermal cycling resistance are miniaturizing the performance gap between industrial-grade and food-grade sealants in high-temperature oven applications. German baking equipment manufacturers now specify these formulations for continuous operation above 180 degrees Celsius. The technology is miniaturizing the traditional compromise between temperature tolerance and migration safety that previously forced equipment designers to separate thermal and food-contact zones.
REACH authorization procedures for siloxane compounds are accelerating substitution research across European formulator laboratories. The industrial consequence is a pipeline of experimental bio-based sealant chemistries seeking pre-registration under ECHA evaluation protocols. German and French producers most affected by downstream user notification requirements are consolidating regulatory affairs functions to manage substance volume tracking.
Consolidated procurement through centralized technical buying teams at multinational dairy cooperatives is displacing decentralized plant-level sealant purchasing. Direct manufacturer relationships now dominate volume contracting for NSF-certified grades, compressing distributor margins in the German market. This pattern is most visible in Bavarian and Baden-Württemberg processing clusters where cooperative-owned facilities have standardized specification libraries.
Food Grade Sealant Market Segmentation
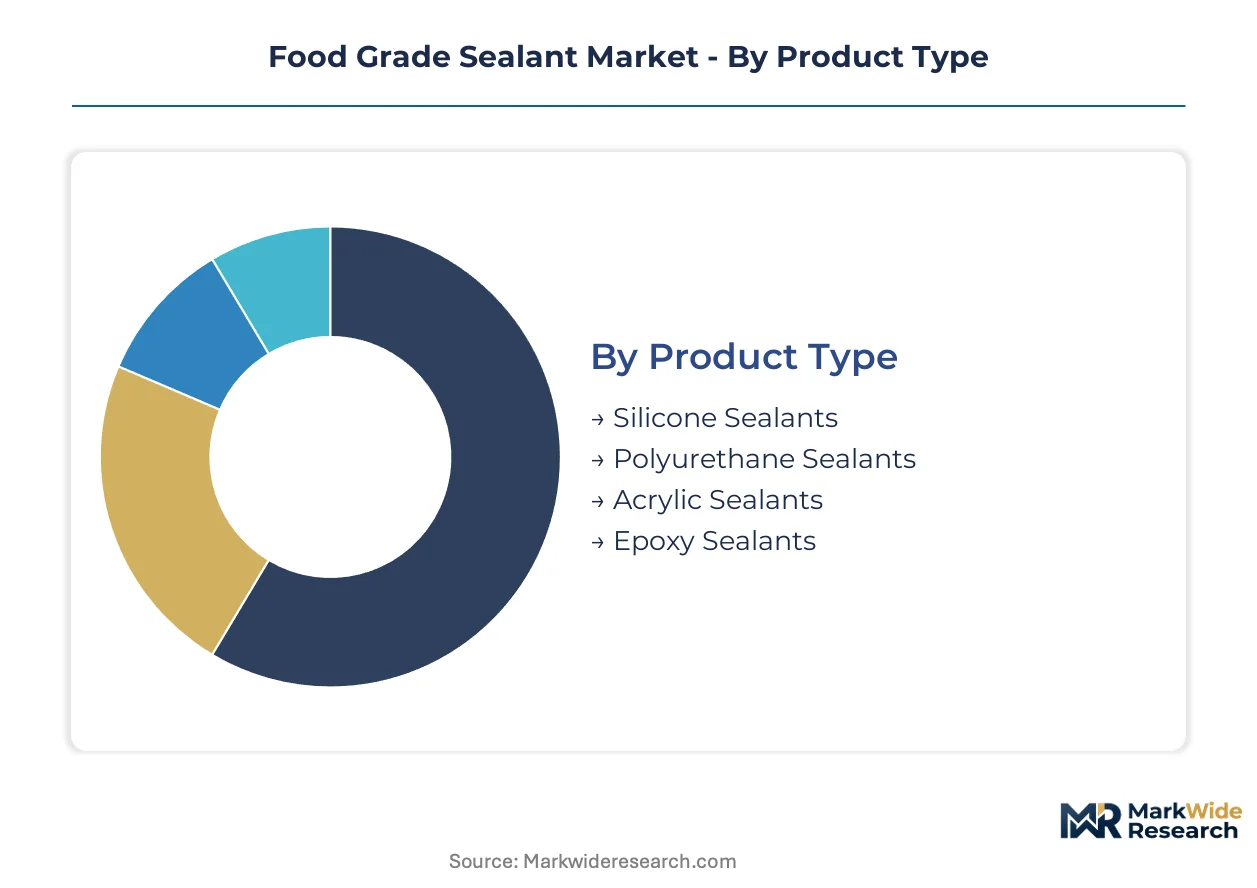
Food grade sealant procurement channels diverge sharply by certification tier and end-use scale. Dairy cooperatives in Germany centralize technical buying for NSF-certified silicone, while smaller Italian cheese producers rely on regional distributors for FDA-compliant imports.
Product Type:
Channel mix varies by polymer chemistry: silicone flows through direct manufacturer relationships at dairy cooperatives, polyurethane reaches packaging OEMs via specialized industrial distributors, acrylic and epoxy serve maintenance contractors through construction supply chains.
- Silicone Sealants:Elastomeric formulations span operational temperatures from minus sixty to plus two hundred degrees Celsius with established FDA 21 CFR 177.2600 and EU Regulation 10/2011 compliance pedigrees. German dairy processing facilities in Bavaria and Baden-Württemberg concentrate procurement through cooperative technical buying teams, driven by NSF H1 certification mandates ahead of EU hygiene audits.
- Polyurethane Sealants:Thermoset systems deliver high-strength flexible bonds for automated packaging lines operating at high speeds. Demand concentrates at modified-atmosphere packaging OEMs serving European ready-to-meal retail channels, where mechanical durability under thermal cycling creates specification pressure.
- Acrylic Sealants:Water-based formulations serve cold-storage envelope retrofits with lower temperature tolerance but faster cure times.
- Epoxy Sealants:Rigid thermoset systems anchor equipment baseplates and flooring joints in processing facilities requiring chemical resistance.
By volume, silicone sealants lead. By growth pace, polyurethane formulations are climbing the fastest.
Application:
Cost tier stratification separates capital equipment specifications from maintenance procurement, with aseptic packaging commanding premium pricing and storage retrofits competing on installed cost.
- Food Processing:Equipment gasketing and joint sealing in dairy, beverage, and meat processing infrastructure. German facilities face replacement cycles driven by EU Regulation 10/2011 migration limit enforcement, creating sustained demand for compliant silicone inventories.
- Packaging:Aseptic and modified-atmosphere format seals preventing microbial ingress during extended shelf-life distribution. European retail channel expansion for ready-to-eat meals accelerates specification of high-integrity barrier materials.
- Equipment Assembly:Original equipment manufacturing of mixers, ovens, and conveyance systems for food production lines.
- Storage Solutions:Cold-storage envelope sealing for refrigerated logistics infrastructure under EU Green Deal energy efficiency mandates.
Equipment assembly commands current volume share. Packaging applications show the steepest expansion trajectory.
End User:
Customer type determines contract structure: multinational food manufacturers negotiate frame agreements, while independent restaurants purchase through maintenance contractors.
- Food Manufacturers:Dairy cooperatives and beverage processors operating automated production lines at scale. Centralized procurement functions at Bavarian and Baden-Württemberg facilities have standardized NSF-certified specification libraries, displacing decentralized plant-level purchasing.
- Retailers:Private-label food producers and supermarket chains with captive processing operations. Modified-atmosphere packaging requirements for extended shelf-life products drive sealant specification in ready-to-eat meal production.
- Distribution Centers:Refrigerated logistics operators retrofitting cold-storage envelopes for energy efficiency compliance.
- Restaurants:Commercial kitchen equipment maintenance and small-scale food service operations.
Food manufacturers dominate current procurement volume. Retailer captive operations are gaining share fastest.
Certification:
Margin structure stratifies sharply by compliance tier: multi-jurisdiction certifications command substantial premia over single-market approvals.
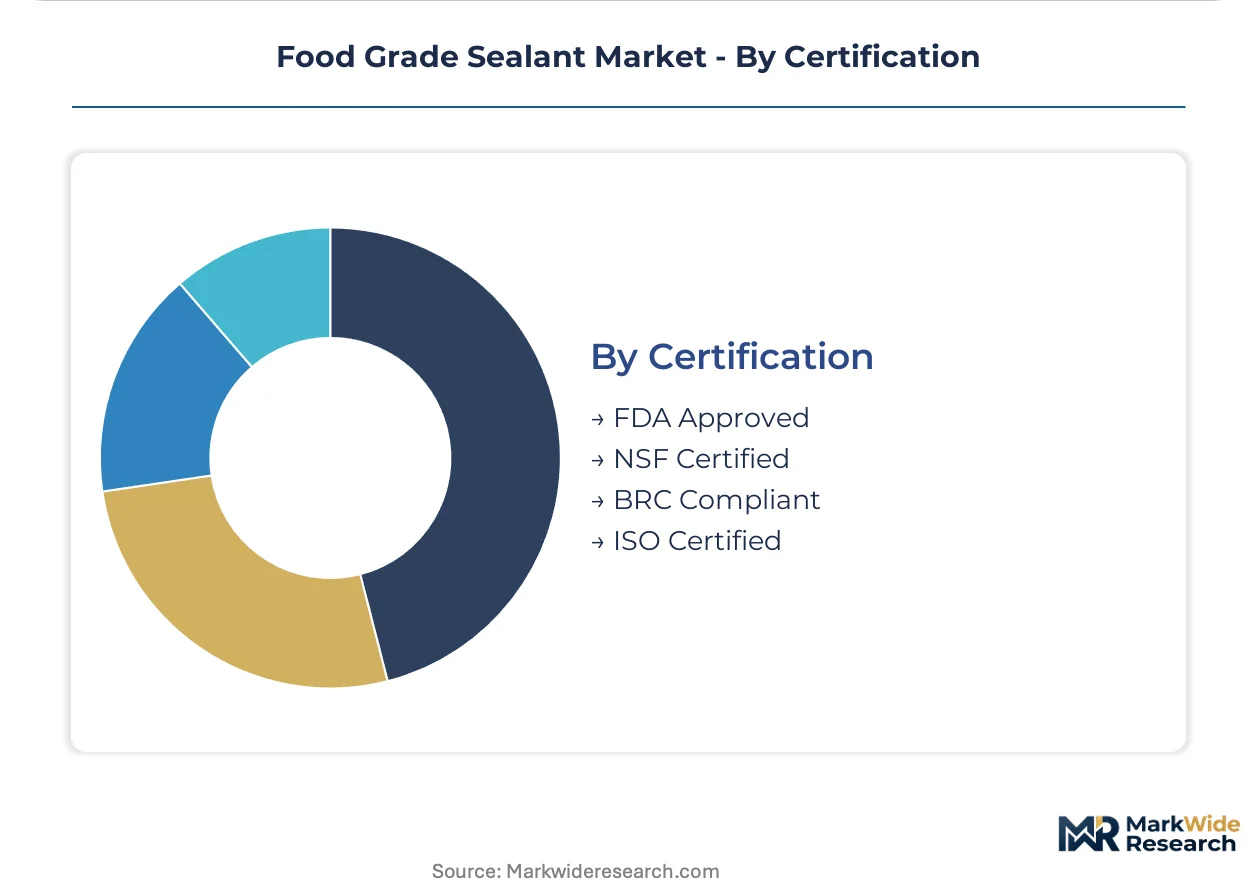
- FDA Approved:Migration testing under 21 CFR 177.2600 for United States market access. Formulators seeking dual EU and FDA certification must maintain parallel testing laboratories, duplicating validation infrastructure and compressing margins on non-premium grades.
- NSF Certified:H1 lubricant incidental contact and ANSI 61 potable water standards. German dairy processors face procurement priority restructuring ahead of hygiene audits, with Bavarian facilities leading replacement demand.
- BRC Compliant:British Retail Consortium global food safety standards for supplier certification.
- ISO Certified:Quality management and food safety management system standards.
NSF certification leads by current specification frequency. FDA dual-approval formulations are expanding most quickly as formulators target transatlantic market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive silicone polymer production in Bavaria and Burghausen anchors European supply security for food-grade formulators. German facilities concentrate procurement through cooperative technical buying teams. Dairy processing clusters in France and Italy face parallel compliance deadlines under EU Regulation 10/2011.
Germany
Dairy cooperatives in Bavaria and Baden-Württemberg centralize procurement for NSF H1-certified silicone ahead of hygiene audits. Germany's Federal Institute for Risk Assessment imposes additional VOC testing protocols beyond EU baselines. The Burghausen chemical cluster anchors captive silicone polymer supply for Central European formulators.
France
Modified-atmosphere packaging lines for ready-to-eat meals drive specification of high-integrity polyurethane sealants. EFSA migration limit enforcement accelerates replacement cycles across aging cheese processing infrastructure. The Auvergne-Rhône-Alpes dairy cluster faces procurement priority restructuring to meet EU Regulation 10/2011 deadlines.
Italy
Artisan cheese producers in Emilia-Romagna and Lombardy confront compliance gaps with current NSF certification coverage. REACH authorization procedures for siloxane compounds accelerate substitution research at formulator laboratories. Small-scale producers in the Po Valley increasingly rely on regional distributors for FDA-compliant imports.
United States
FDA 21 CFR 177.2600 migration testing requirements structure procurement for dairy and beverage processing equipment. Automated packaging OEMs in the Midwest specify high-strength flexible bonds for high-speed line conditions. The Wisconsin dairy processing corridor concentrates demand for thermal cycling-resistant fluorosilicone formulations.
China
GB standards for food-contact materials tighten entry requirements for imported sealant formulations. NMPA compliance protocols drive domestic formulators toward parallel certification infrastructure. Yangtze River Delta packaging equipment manufacturers specify silicone sealants for aseptic format production lines.
Food Grade Sealant Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the food-grade sealant market. Integrated chemical conglomerates with captive silicone polymer production dominate premium NSF-certified tiers, while specialized formulators compete on application-specific customization. Three archetypes structure competitive positioning: polymer producers with backward integration into raw material supply, formulation specialists with certification depth across FDA and EU protocols, and regional distributors with technical service capabilities for maintenance contractors. Consolidation through cooperative procurement centralization and direct manufacturer relationships displaces traditional distributor channels in volume segments.
Among German-based chemical conglomerates, Henkel AG & Co. KGaA and Wacker Chemie AG occupy positions anchored by adhesive-sealant portfolio breadth and captive silicone production respectively. Dow Inc. represents the transatlantic archetype with fluorosilicone expertise for thermal cycling applications. These three entities exemplify how polymer control and multi-jurisdiction certification infrastructure separate premium-tier competitors from formulation-dependent challengers.
| Leading Market Players |
|---|
| 3M Company |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Sika AG |
| Dow Inc. |
| Shin-Etsu Chemical |
| Elkem Silicones |
| Wacker Chemie AG |
| CHT Group |
| Others |
Value Network & Pricing Analysis
Polyurethane substitution in high-speed packaging lines is compressing silicone premium tiers while rerouting procurement toward Central European formulators with captive polymer supply. This input shift simultaneously concentrates supply geography in Bavaria and Burghausen while forcing price realignment across NSF-certified grades.
Pricing Analysis
EU Regulation 10/2011 migration limits dictate the pricing tier structure across food-grade sealant procurement, separating NSF H1-certified silicone premiums from uncertified economy grades. Price differentiation hinges on dual-certification infrastructure costs and volume scale at cooperative buying teams. Cost compression in standard silicone tiers is intensifying because polyurethane alternatives erode mechanical durability premiums. Small-scale Italian cheese producers exhibit highest price sensitivity, while German dairy cooperatives prioritize compliance over unit cost.
Supply Chain Analysis
Germany and France anchor European silicone polymer production for food-grade formulators, with Burghausen captive supply feeding Central European certification pipelines. Raw material flows draw from specialized fluoroelastomer feedstocks and siloxane compounds facing REACH authorization pressure. Single-source vulnerability concentrates in thermal cycling-resistant grades with limited European manufacturing capacity. Distribution runs through direct manufacturer relationships at multinational dairy cooperatives, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food grade sealant procurement is evolving into a service-attach opportunity as certified application contracting and digital compliance documentation expand faster than base material sales. Recurring revenue from blockchain-tracked certification records and technical service retainers now outpaces hardware growth trajectories.
For Market Incumbents: Secure backward integration into siloxane compound supply to offset REACH authorization risks and defend margin position against polyurethane substitution in packaging lines. Consolidate regulatory affairs functions to manage substance volume tracking across ECHA evaluation protocols. Channel control through cooperative technical buying team relationships protects volume share in Bavarian and Baden-Württemberg processing clusters. For New Entrants and Emerging Players: Anchor in Italian artisan dairy modernization gaps where NSF certification coverage remains incomplete and service-model opportunities outpace product-only competition. Emilia-Romagna and Lombardy small-scale producers represent the most penetrable geography. A go-to-market angle pairing FDA-compliant imports with certified application contracting bypasses direct confrontation with integrated German incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward formulation specialists with dual FDA-EU certification infrastructure and established relationships with cooperative procurement functions. Long-term viability over the next decade rests on regulatory compliance depth rather than commodity polymer access. The signal to watch is consolidation velocity among regional distributors as direct manufacturer relationships displace traditional channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Supply | Captive polymer production in Burghausen reduces import dependency for Central European formulators facing REACH pressure. |
| Dual Certification Infrastructure Investment | Parallel FDA and EU testing laboratories enable transatlantic market access for premium-grade silicone formulations. |
| Digital Compliance Documentation Platform | Blockchain-tracked certification records streamline multi-jurisdiction audits for producers serving regulated facilities. |
| Certified Application Contracting Service Model | Technical service retainers for Italian artisan dairy producers address compliance gaps while generating recurring revenue. |
| Cooperative Procurement Relationship Consolidation | Direct manufacturer agreements with Bavarian dairy cooperatives displace distributor margins and secure volume commitments. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at dairy processing facilities, procurement leads at packaging OEMs, regulatory affairs directors at formulator laboratories, and aftermarket service heads at industrial distributors, then refined through secondary validation against ECHA substance volume tracking data, EU customs trade records, FDA 21 CFR filing databases, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up demand modeling across equipment assembly, packaging, and storage retrofit applications was triangulated with top-down supply analysis of captive polymer capacity.
Variance in projected outcomes decomposes across certification tier penetration, polymer chemistry substitution rates, and regional procurement centralization velocity. Segmentation dimensions modeled include product type chemistry, application equipment versus packaging versus storage, end-user scale from artisan to multinational, and certification jurisdiction coverage. CAGRs were derived from trend extrapolation of replacement cycle timing and compliance deadline enforcement patterns, with specific weighting for EU Green Deal energy efficiency mandate acceleration and NSF H1 audit schedule density.
Material uncertainties — regulatory restriction list revisions, fluoroelastomer feedstock supply disruptions, and polyurethane mechanical performance breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions about migration limit enforcement consistency and cooperative procurement function expansion. Recalibration cycles align with material shifts in ECHA authorization timelines and EU hygiene audit scheduling.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Middle East and Africa Single-Use Packaging Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
US Packaging Market
Packaging Materials
VCI Packaging Market
Packaging Materials
PET Strap Market
Packaging Materials
Single-Use Packaging Market
Packaging Materials
Skin Packaging Market
Packaging Materials
Cold Form Foil Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Face Stock Films Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
Cavitated Films Market
Packaging Materials
Thermoformed Tubs Market
Packaging Materials
Finish Foils Market