
 Wrapping Tissues Market | 2026-2036
Wrapping Tissues Market Size, Share, and Industry Trends Forecast 2026-2036
Wrapping Tissues Market Analytics
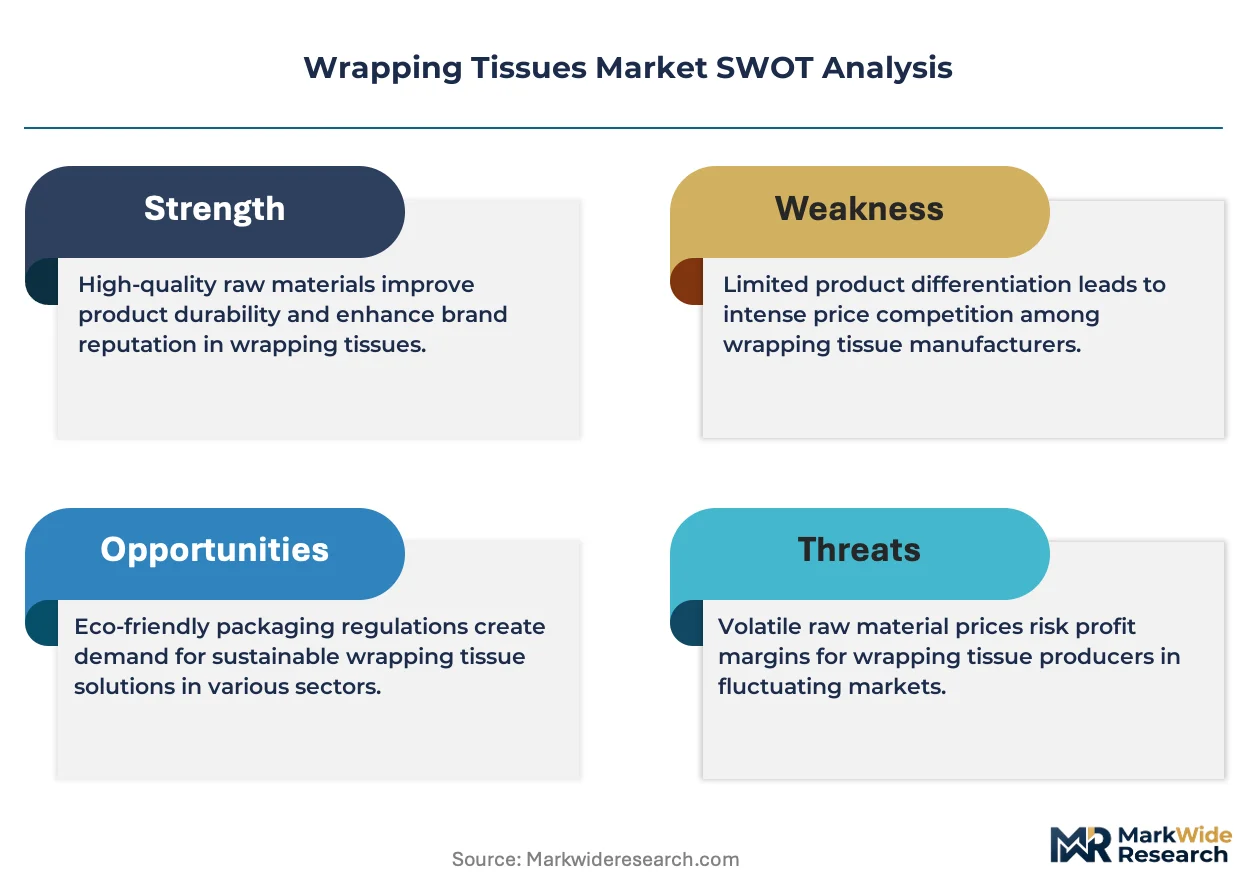
North American specialty paper capacity is hardening as integrated producers respond to sustained e-commerce fulfillment demand. Seaman Paper Co. leverages its long-fiber expertise to dominate premium gift-wrapping segments. Mondi Group anchors European supply through certified kraft tissue operations. Twin Rivers Paper Company competes on lightweight caliper consistency for industrial protective applications.
Wrapping tissues are thin, flexible paper sheets engineered from bleached or unbleached wood pulp, recycled fiber, or kraft stock, typically calipered below 40 gsm and treated for grease resistance or decorative finish, serving primary functions in product protection, presentation, and cushioning across retail and logistics chains. Pulp-based grades sustain margin pools in food-contact and luxury packaging where FDA and EU food-safety compliance commands price premiums. Recycled paper and kraft paper segments are expanding fastest in e-commerce void-fill and industrial wrapping as brand owners pursue visible sustainability credentials without sacrificing burst strength.
FDA food-contact regulations, EU REACH chemical restrictions, and FSC chain-of-custody certification collectively shape material sourcing, converter qualification, and market access for wrapping tissue suppliers serving multinational brand portfolios. The EU Packaging and Packaging Waste Regulation tightens recycled content mandates and extended producer responsibility schemes, forcing converters to revalidate fiber provenance and end-of-life pathways. Stakeholders must monitor how diverging transatlantic sustainability timelines reshape supplier qualification criteria and capital allocation across tissue converting assets.
Market Dynamics
E-commerce fulfillment velocity is compressing order-to-delivery windows, forcing converters to stock lightweight protective tissues closer to regional distribution nodes. This demand pulse is reshaping mill-capacity allocation and inventory positioning across North American and European supply networks.
Growth Catalysts
- FSC Chain-of-Custody Mandates:EU Packaging and Packaging Waste Regulation requires verified sustainable sourcing, pulling premium tissue volumes toward certified pulp streams in Germany and France.
- Industrial Protective Applications:Automotive parts suppliers in Mexico and Poland are adopting acid-free tissue layers to prevent corrosion during ocean transit.
- Grease-Resistant Barrier Chemistry:Fluorocarbon-free coatings are penetrating food-contact wrapping segments as FDA compliance thresholds tighten on PFAS content.
Market Restraints
- Bleached Softwood Pulp Volatility:Scandinavian pulp contract prices swing with energy-cost passthroughs, squeezing converter margins on specification-grade tissues.
- China Recycled Fiber Import Bans:Beijing's National Sword policy has stranded post-consumer OCC streams, forcing Southeast Asian mills to absorb displaced volumes.
- Mechanical Recycling Limitations:Multi-layer barrier films laminated to tissue substrates block standard pulping recovery, raising disposal costs for brand owners.
Strategic Opportunities
- Indian E-commerce Cold Chain:Temperature-sensitive pharmaceutical deliveries in Maharashtra and Karnataka lack adequate insulated void-fill, creating specification gaps for thermal tissue laminates.
- Digital Print Personalization:Web-to-gift platforms in the UK and Netherlands are contracting short-run decorative tissue runs, displacing mass-produced seasonal inventory.
- Extended Producer Responsibility Credits:France's Citeo eco-modulation scheme rewards mono-material tissue designs with fee reductions, incentivizing format simplification.
Industry Challenges
- Colorfastness Chemist Shortage:Formulators who can balance vegetable-based dyes with wet-strength resins are scarce in Midwest US converting corridors.
- ISO 17025 Lab Accreditation Timelines:Migration testing for food-contact tissues now stretches fourteen months at overloaded European certification bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wrapping Tissues Market |
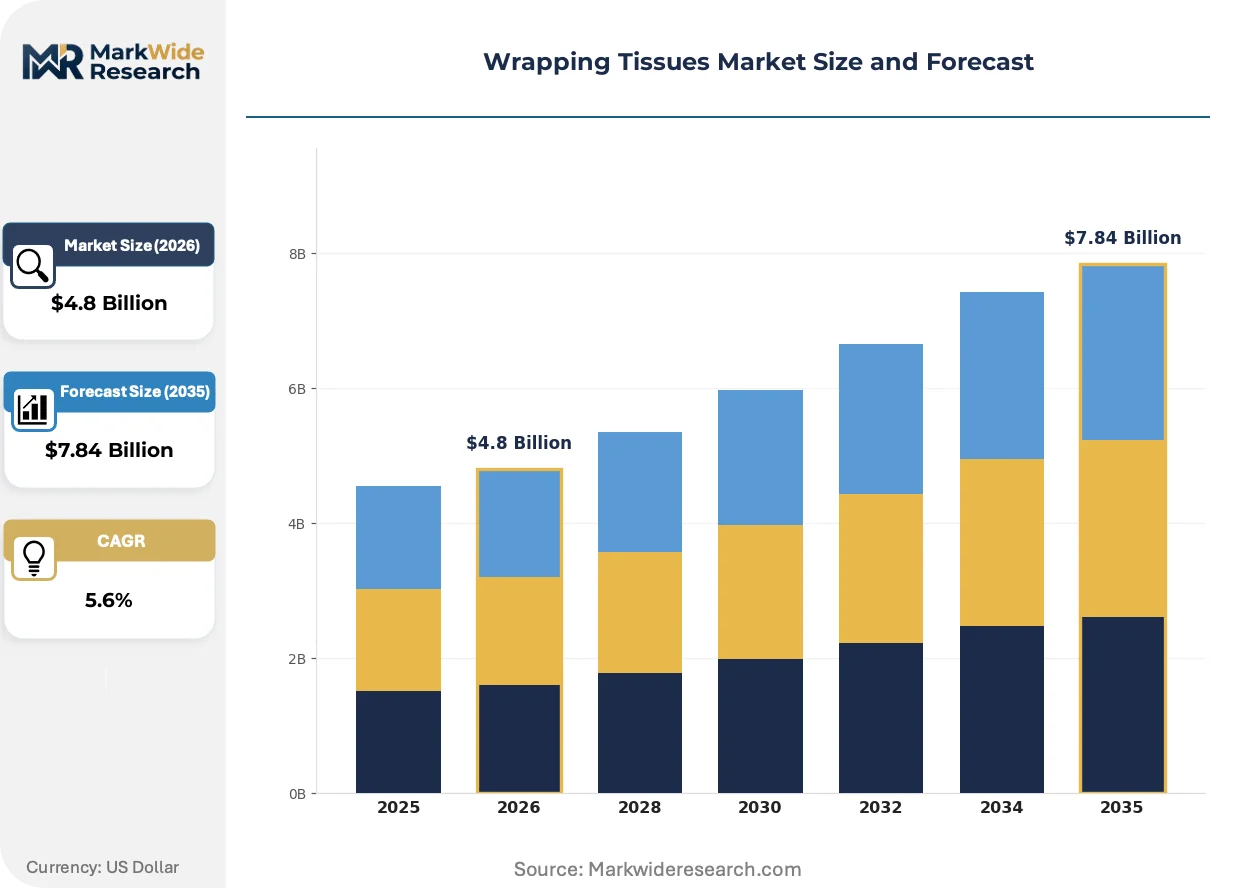
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Pulp, Recycled Paper, Kraft Paper, Tissue Paper Application Area: Food Packaging, Gift Wrapping, Industrial Use, Decorative Purposes End User: Retailers, Manufacturers, E-commerce, Event Organizers Distribution Channel: Direct Sales, Online Stores, Retail Outlets, Wholesale |
| Companies Covered | Flower City Tissue Mills Co, Seaman Paper Co., Twin Rivers Paper Company, MPI PAPERMILLS Inc., Innovative Packaging Group, Inc., NASHVILLE WRAPS, Mondi Group, Smurfit Kappa Group, Asia Pulp & Paper (APP), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wrapping Tissues Market Evolving Landscape
Material science breakthroughs and regulatory chemistry bans are converging to redefine performance benchmarks across protective and presentation tissue grades. Converters must now engineer multifunctional substrates that satisfy both mechanical specifications and evolving compliance frameworks.
Cellulose nanofibril reinforcement is overtaking traditional wet-strength resins in high-performance industrial wraps. Tier-one automotive suppliers in Germany and Japan are qualifying these bio-based additives for precision component packaging. The shift is compressing demand for synthetic polyamide additives while opening premium pricing tiers for forest-certified nanocellulose sources.
REACH restrictions on formaldehyde-releasing agents are forcing adhesive reformulation across European tissue laminators. Crosslinking chemistries derived from citric acid and polycarboxylic polymers are displacing conventional wet-end additives. Food-contact wrapping segments in France and Italy face the steepest requalification burdens as existing product registrations expire under the updated hazard classification.
Subscription-box procurement is consolidating buyer power among direct-to-consumer brands, compressing supplier rosters to three approved converters per category. Legacy spot-buying through paper merchants is retreating to secondary sourcing for overflow volume. This concentration is most visible in California and New York metro fulfillment zones where unboxing experience ratings directly influence contract renewals.
Wrapping Tissues Market Segmentation
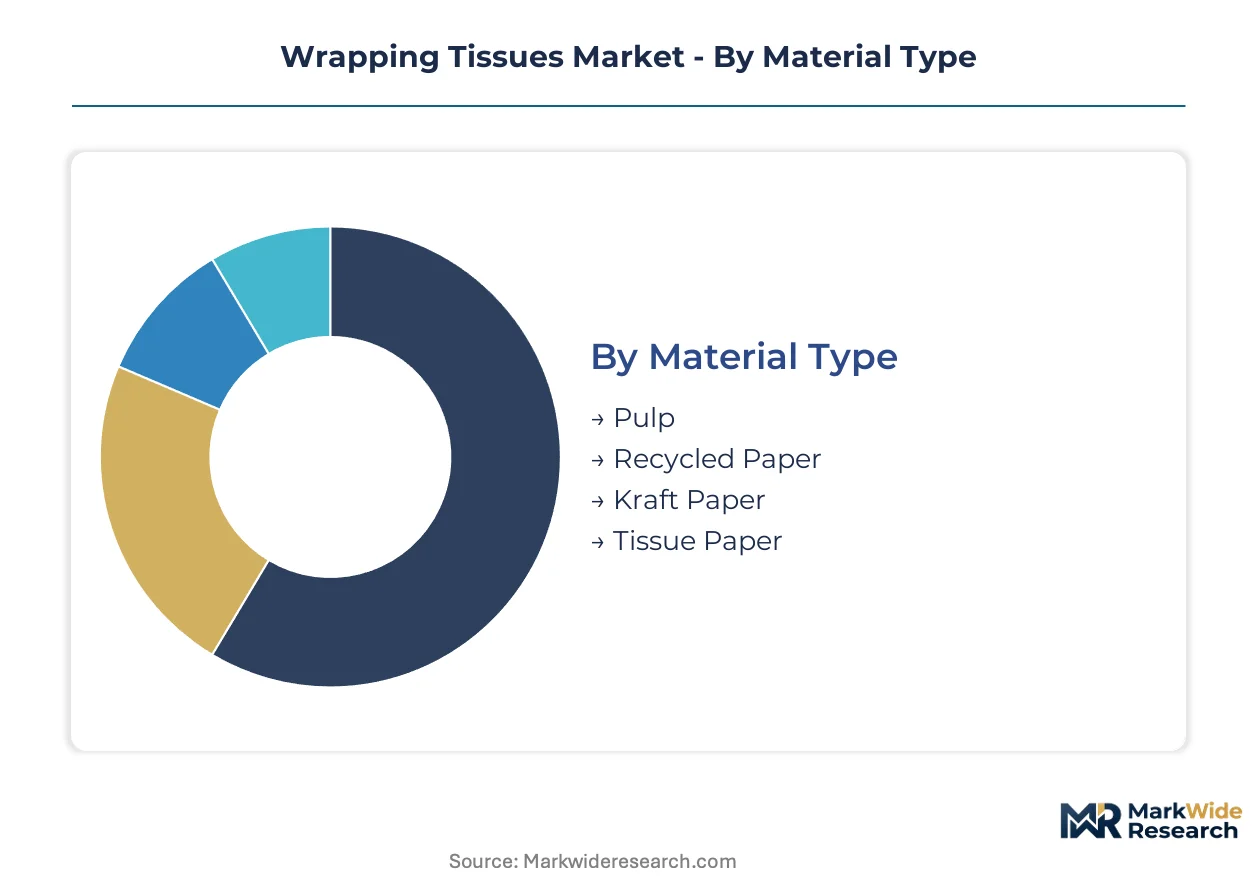
Wrapping tissue specifications diverge sharply across end-use contexts, with food-contact grades demanding FDA and EFSA compliance while gift and industrial segments prioritize caliper consistency and printability. Material sourcing decisions cascade through converter qualification requirements, distribution economics, and final price positioning.
Material Type:
Supply concentration in bleached softwood pulp channels shapes margin structures across all downstream grades.
- Pulp:Virgin bleached kraft pulp delivers sub-40 gsm caliper with controlled porosity for grease-resistant food-contact applications. German pharmaceutical and luxury cosmetics brands specify FSC-certified grades to satisfy EU Green Deal procurement mandates.
- Recycled Paper:Post-consumer fiber streams face quality inconsistency after China's National Sword restrictions disrupted global OCC flows. E-commerce void-fill demand in Poland and Mexico absorbs expanding volumes where visual sustainability credentials outweigh absolute performance specifications.
- Kraft Paper:Unbleached long-fiber stock provides tear resistance for industrial protective wraps.
- Tissue Paper:Lightweight decorative grades serve premium gift-wrapping segments.
Pulp absorbs the bulk of installed capacity; recycled paper is expanding most quickly.
Application Area:
Cost tier separation between commodity protective wraps and specification-grade presentation tissues defines converter investment priorities.
- Food Packaging:Fluorocarbon-free barrier coatings now dominate FDA-compliant segments as PFAS thresholds tighten. French and Italian converters face steep requalification burdens under REACH formaldehyde restrictions.
- Gift Wrapping:Digital print personalization is displacing mass-produced seasonal inventory in UK and Netherlands web-to-gift platforms. Short-run decorative tissue contracts now command premium pricing over standard coated grades.
- Industrial Use:Acid-free tissue layers prevent corrosion on automotive components during ocean transit.
- Decorative Purposes:Colorfast vegetable-based dyes balance aesthetic requirements with sustainability positioning.
Food packaging commands the highest specification premiums; gift wrapping is climbing the fastest on personalization demand.
End User:
Volume concentration among consolidated e-commerce fulfillment networks is compressing supplier rosters.
- Retailers:Department store chains in Germany and France specify mono-material tissue designs to capture Citeo eco-modulation fee reductions.
- Manufacturers:Tier-one automotive suppliers in Japan qualify cellulose nanofibril-reinforced wraps for precision component packaging.
- E-commerce:Subscription-box procurement consolidates buyer power among direct-to-consumer brands.
- Event Organizers:Corporate gifting programs drive seasonal demand spikes.
E-commerce absorbs the bulk of lightweight protective tissue capacity; manufacturers are expanding specifications fastest on industrial performance requirements.
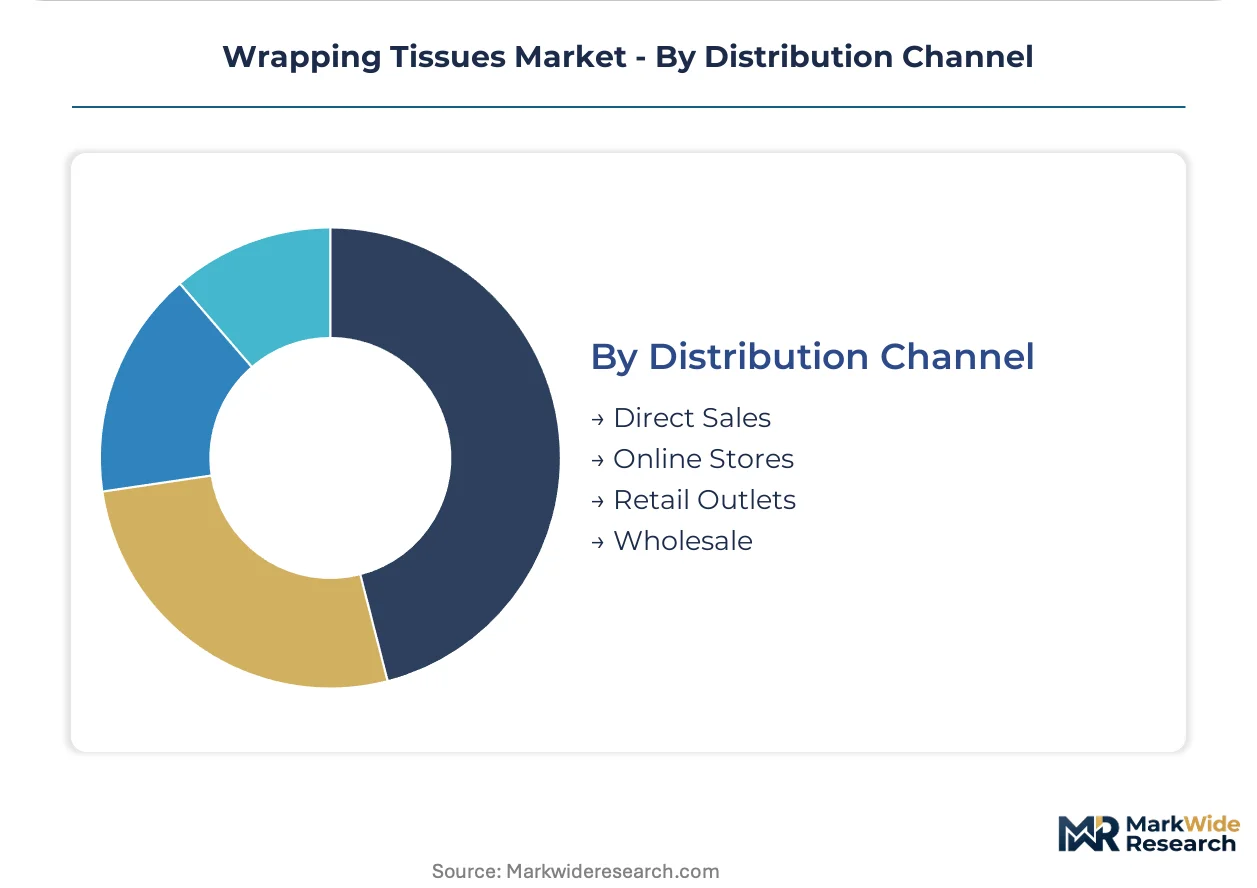
Distribution Channel:
Customer type stratification between spot-buying merchants and contracted fulfillment networks determines inventory positioning.
- Direct Sales:Converter-direct relationships dominate specification-grade food-contact and automotive protective segments.
- Online Stores:Web-to-gift platforms in California and New York metro zones tie contract renewals to unboxing experience ratings.
- Retail Outlets:Stationery and craft channels serve consumer gift-wrapping demand.
- Wholesale:Paper merchants retreat to secondary sourcing for overflow volume as subscription-box consolidation advances.
Direct sales holds the bulk of premium specification volume; online stores are gaining share fastest on personalization services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian bleached softwood pulp exports anchor tissue-grade fiber supply for premium wrapping specifications across key converting clusters.
United States
E-commerce fulfillment velocity in California and New York metro zones compresses order-to-delivery windows for protective tissue suppliers. FDA food-contact regulations govern barrier coating compliance for subscription-box void-fill applications. Seaman Paper Co. leverages long-fiber expertise from its Midwest operations to dominate premium gift-wrapping segments serving department store chains.
Germany
Premium gift-wrapping culture and strict packaging waste regulations create concentrated demand for FSC-certified tissue grades. EU Green Deal procurement mandates and the Packaging and Packaging Waste Regulation enforce verified sustainable sourcing across converter supply chains. Automotive parts suppliers in Baden-Württemberg adopt acid-free tissue layers for precision component protection during ocean transit.
China
Beijing's National Sword policy stranded post-consumer OCC streams, forcing domestic mills to absorb displaced recycled fiber volumes. The country's national environmental regulator enforces dual carbon goals that reshape pulp sourcing decisions. Yangtze River Delta converters face quality inconsistency challenges as they pivot toward domestic recycled fiber integration for e-commerce void-fill production.
France
Citeo eco-modulation fee reductions reward mono-material tissue designs, incentivizing format simplification among retail procurement teams. REACH restrictions on formaldehyde-releasing agents force adhesive reformulation across tissue laminators serving food-contact segments. Paris-based web-to-gift platforms contract short-run decorative tissue runs, displacing mass-produced seasonal inventory with digital print personalization.
India
Temperature-sensitive pharmaceutical deliveries in Maharashtra and Karnataka lack adequate insulated void-fill, creating specification gaps for thermal tissue laminates. The country's food safety regulator enforces compliance thresholds for food-contact wrapping applications. Mumbai and Bengaluru e-commerce cold chain operators represent emerging demand pockets for protective tissue solutions in pharmaceutical logistics.
Wrapping Tissues Market Competitive Landscape
Global majors compete with regional champions across certification-grade fiber access and converter qualification speed. Integrated producers with captive pulp supply dominate specification-grade segments where FDA and EU food-safety compliance commands price premiums. Three archetypes define competitive positioning: Scandinavian pulp-anchored integrated mills, North American long-fiber specialists, and Asia-Pacific scale players with recycled fiber integration. Capacity expansion and strategic partnerships constitute the dominant competitive moves as converters reposition inventory closer to regional distribution nodes.
Within the integrated-mill tier, Mondi Group and Smurfit Kappa Group exemplify European supply anchoring through certified kraft tissue operations. Seaman Paper Co. occupies a position among North American long-fiber specialists leveraging expertise for premium gift-wrapping dominance. These three entities represent distinct geographic and capability archetypes rather than direct segment overlap, with each converter's positioning reflecting regional fiber access and end-use specification requirements.
| Leading Market Players |
|---|
| Flower City Tissue Mills Co |
| Seaman Paper Co. |
| Twin Rivers Paper Company |
| MPI PAPERMILLS Inc. |
| Innovative Packaging Group, Inc. |
| NASHVILLE WRAPS |
| Mondi Group |
| Smurfit Kappa Group |
| Asia Pulp & Paper (APP) |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters across Wisconsin and Bavaria anchor premium tissue supply, their conservative balance sheets limiting capacity expansion despite sustained e-commerce demand. This ownership pattern reinforces pricing discipline through selective order acceptance rather than volume chasing.
Pricing Analysis
Warranty-backed FDA compliance certification is bundled into premium pulp-grade contracts while recycled fiber tiers sell unbundled. Three-tier pricing structure across FSC-certified premium, standard bleached kraft, and economy recycled grades separates pharmaceutical buyers from gift-wrapping retailers from e-commerce void-fill users. Price differentiation hinges on certification tier and volume scale. Cost compression in standard grades is intensifying because Scandinavian pulp contract prices swing with energy-cost passthroughs. E-commerce subscription-box buyers exhibit highest price sensitivity; German pharmaceutical and luxury cosmetics brands show least.
Supply Chain Analysis
Regional distribution centers in California, New York metro, and Baden-Württemberg compress order-to-delivery windows for protective tissue. Geographic supply concentrates in Sweden, Germany, and the United States. Raw material dependencies center on bleached softwood pulp, recycled OCC fiber streams, and cellulose nanofibril additives. Single-source vulnerability runs through Scandinavian pulp contract concentration. Distribution runs through converter-direct relationships for specification grades and paper merchant channels for overflow spot-buying.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bleached softwood pulp capacity constraints prop pricing power as integrated mills prioritize pharmaceutical and food-contact contracts over commoditized void-fill grades.
For Market Incumbents: Anticipate margin compression from fluorocarbon-free coating requalification costs by accelerating cellulose nanofibril R&D partnerships with German automotive suppliers. Lock in long-fiber supply agreements with Scandinavian pulp producers before contract renewal cycles. Certification investment in extended producer responsibility schemes represents the critical defensive lever against emerging Polish and Mexican converters. For New Entrants and Emerging Players: EU Packaging and Packaging Waste Regulation in Germany and France opens a window for mono-material tissue designs capturing Citeo eco-modulation fee reductions. Target Indian pharmaceutical cold chain void-fill in Maharashtra and Karnataka where thermal tissue laminate specifications remain undefined. Pursue web-to-gift platform partnerships in the Netherlands and UK as the primary go-to-market angle for short-run digital print personalization. For Investors and Strategic Acquirers: Distressed-cycle entries favor Midwest US converters with stranded mechanical recycling assets and undervalued FSC chain-of-custody certifications. Long-term viability centers on fiber flexibility across virgin and recycled streams. Watch for inflection when Chinese domestic recycled fiber integration achieves quality parity with pre-National Sword OCC standards.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorocarbon-Free Coating Transition | REACH formaldehyde restrictions in France and Italy force adhesive reformulation across food-contact laminators. |
| Cellulose Nanofibril Integration | Tier-one automotive suppliers in Germany and Japan qualify bio-based additives for precision component packaging. |
| Regional Distribution Node Expansion | California and New York metro fulfillment zones compress inventory positioning for subscription-box procurement. |
| FSC Chain-of-Custody Certification | EU Green Deal mandates pull premium tissue volumes toward verified sustainable pulp streams. |
| Digital Print Personalization Capacity | UK and Netherlands web-to-gift platforms displace mass-produced seasonal inventory with short-run contracts. |
Research Methodology
Independent corroboration across converter procurement directors, tissue mill operations managers, and e-commerce fulfillment planners underwrites the qualitative findings. Primary interviews with sustainability compliance officers at German pharmaceutical brands and French food-contact laminators combined with secondary validation from FDA food-contact guidance documents, EU Packaging and Packaging Waste Regulation filings, and FSC chain-of-custody audit records. Bottom-up volume modeling triangulates against top-down pulp consumption estimates from Scandinavian trade associations.
Rate-of-change decomposition separates volume growth from price realization across the projection horizon. The analytical framework models material type, application area, end user, and distribution channel dimensions alongside regional regulatory cluster differentiation. CAGRs derive from segmented volume trajectories calibrated to pulp contract price elasticity and e-commerce fulfillment velocity assumptions. Industry-specific inputs include cellulose nanofibril adoption curves in automotive protective wraps and fluorocarbon-free coating penetration in food-contact segments.
The model assumes a particular technology adoption path; alternative pathways for cellulose nanofibril reinforcement would alter the outlook if wet-strength resin displacement accelerates beyond modeled rates. Forecasts reflect assumptions about EU recycled content mandate enforcement and Chinese domestic recycled fiber quality convergence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Box and Carton Overwrap Films Market
Packaging Materials
VCI Films Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Child Resistant Zipper Market
Packaging Materials
Floppy Disk Liner Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Europe Consumer Packaging Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Packaging Materials Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Global Strapping Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Window Packaging Market