
 Silicone Potting Compounds Market | 2026-2036
Silicone Potting Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Potting Compounds Market Intelligence
Direct procurement channels between silicone potting compound suppliers and tier-one automotive electronics manufacturers is rewriting traditional distributor relationships. Dow leverages its integrated silicone feedstock operations to sustain cost advantages across high-volume thermal management grades. Henkel AG & Co. KGaA anchors its position through specialized formulations serving aerospace encapsulation requirements. Momentive Performance Materials Inc differentiates via electronic-grade purity protocols that meet stringent semiconductor packaging standards.
Silicone potting compounds are two-part or single-part elastomeric systems formulated from polydimethylsiloxane backbones with silica fillers, curing through condensation or addition mechanisms to form flexible, thermally stable protective barriers. These materials typically operate across temperature ranges from minus fifty-five to two hundred degrees Celsius while maintaining dielectric strength exceeding fifteen kilovolts per millimeter, serving primarily to protect electronic assemblies from moisture, vibration, and thermal cycling damage. Two-part compounds dominate current volume due to their adjustable cure profiles and deep-section reliability, while ultraviolet-curable formulations represent the fastest-expanding technology segment as miniaturized consumer electronics demand rapid processing without thermal stress. Thermally conductive compounds command premium positioning as electric vehicle inverters and charging infrastructure drive specialized filler loading requirements.
The EPA governs volatile organic compound emissions from silicone curing processes, while REACH mandates full substance registration and hazard communication throughout European supply chains, and China's MEE enforces dual carbon goals that constrain energy-intensive methylchlorosilane production. These frameworks compel reformulation investments, shift manufacturing location decisions, and elevate compliance costs that filter through to end-product pricing. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could impact certain specialty silicone additives and assess alternative curing catalysts before regulatory deadlines compress formulation timelines.
Market Dynamics
Electric vehicle powertrain electrification is compressing qualification cycles for thermally conductive silicone potting compounds as battery management system protection shifts from commodity specification to performance-critical sourcing.
Growth Catalysts
- REACH substance registration mandates:Full material disclosure requirements across European supply chains are forcing reformulation transparency that rewards suppliers with pre-registered additive portfolios.
- Semiconductor packaging miniaturization:Die-shrink trends in China's advanced packaging facilities demand ultra-pure electronic-grade silicones with sub-ppm ionic contamination thresholds.
- India's electronics manufacturing clusters:PLI scheme incentives for mobile phone and component assembly are pulling specialized potting compound volumes into Tamil Nadu and Karnataka production zones.
Market Restraints
- Methylchlorosilane feedstock concentration:China's MEE dual carbon enforcement constrains energy-intensive upstream silicone monomer production, creating intermediate supply bottlenecks.
- Per- and polyfluoroalkyl substance restrictions:Evolving EPA and ECHA limitations on certain specialty silicone additives compress formulation flexibility for high-performance grades.
- Thermal conductivity ceiling:Filler loading limits in addition-cure systems cap heat dissipation performance below what silicon carbide power modules require.
Strategic Opportunities
- UV-curable formulation penetration:Miniaturized consumer electronics assembly in South Korean and Vietnamese facilities favors rapid-cure technologies that eliminate thermal stress on sensitive components.
- Automotive direct procurement channels:Tier-one electronics manufacturers are bypassing traditional distributors, creating margin capture potential for compound suppliers with in-house application engineering.
- India's emerging defense electronics:Indigenous avionics and radar programs under the country's offset policies specify aerospace-grade encapsulation with traceable supply chains.
Industry Challenges
- Formulation-to-cure process certification:Automotive OEMs require 18-24 month validation timelines for new potting compounds, compressing product development ROI windows.
- Specialized application engineering talent:Deep expertise in thermal interface material design for power electronics remains concentrated among a narrow technical workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Potting Compounds Market |
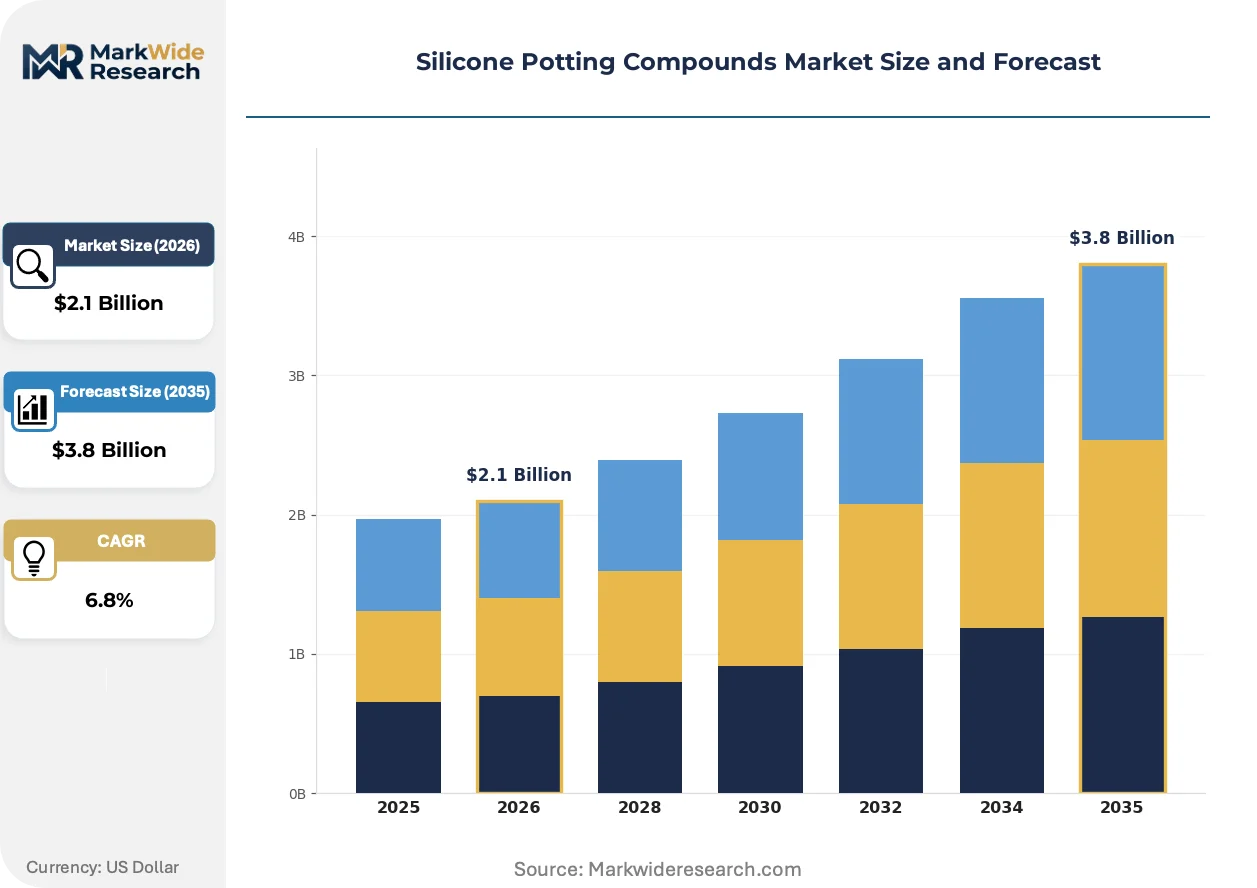
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Part Compounds, Single-Part Compounds, Ultraviolet-Curable Compounds, Thermally Conductive Compounds End User: Consumer Electronics, Automotive, Aerospace, Industrial Equipment Application: Sealing, Encapsulation, Electrical Insulation, Thermal Management Technology: Room Temperature Vulcanization, Heat Cure, Electronic Grade, Specialty Formulations |
| Companies Covered | Dow, Henkel AG & Co. KGaA, 3M, Momentive Performance Materials Inc, ELANTAS GmbH, Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., CHT Group, Master Bond Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Potting Compounds Market Strategic Shifts & Innovations
Silicone potting compound technology trajectories center on curing speed acceleration, thermal performance enhancement, and supply chain transparency mechanisms that reshape competitive positioning.
Ultraviolet-curable silicone formulations are digitizing production workflows for miniaturized consumer electronics assembly. South Korean and Vietnamese contract manufacturers are adopting these systems at accelerating rates to eliminate oven-cure bottlenecks. The technology is digitizing quality control protocols through real-time cure monitoring and automated dispensing integration.
REACH candidate list expansion and EPA TSCA Section 6 activity are forcing systematic substitution of legacy catalyst systems and certain filler surface treatments. Industrial consequence includes multi-year reformulation investments and elevated testing documentation burdens. Semiconductor packaging suppliers in Germany and the Netherlands are responding fastest, driven by customer-mandated full material disclosure requirements.
Direct technical partnerships between compound suppliers and automotive electronics engineers are displacing traditional specification-through-distributor models. Tier-one inverter and battery management system manufacturers in Germany's automotive corridor now require embedded application support, not just material supply. This pattern concentrates most visibly among powertrain electrification programs where thermal management performance carries warranty liability exposure.
Silicone Potting Compounds Market Segmentation
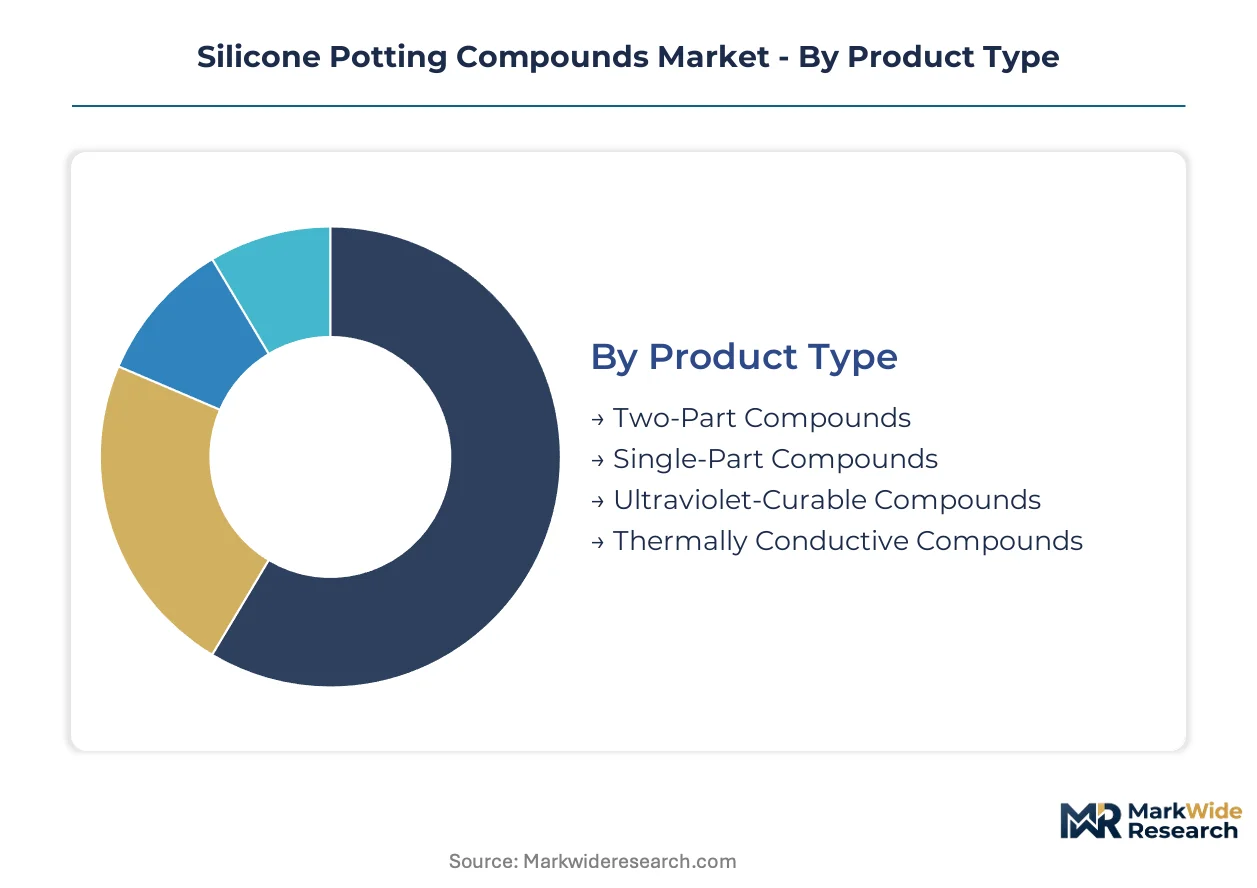
Segmentation in silicone potting compounds reveals how formulation chemistry, thermal performance tiers, and end-use certification requirements create distinct commercial battlegrounds. Each dimension carries different margin structures, qualification timelines, and technical barriers that reshape supplier positioning.
Product Type:
Cost tier differentiation separates commodity formulations from performance-optimized systems, with filler loading and cure chemistry driving price positioning.
- Two-Part Compounds:Adjustable cure profiles through platinum or tin catalyst systems enable deep-section reliability in thick encapsulation layers. Battery management system manufacturers in Germany specify these grades for warranty-critical thermal cycling protection.
- Thermally Conductive Compounds:Boron nitride or aluminum oxide filler loadings exceeding sixty percent by weight achieve thermal conductivity above three watts per meter-kelvin. Electric vehicle inverter suppliers in China demand these formulations for silicon carbide power module packaging.
- Single-Part Compounds:Moisture-cure alkoxy systems suit thin-section sealing where dispensing simplicity outweighs cure speed requirements.
- Ultraviolet-Curable Compounds:Acrylate-functional silicones polymerize in seconds under LED or mercury arc exposure, eliminating thermal stress on miniaturized components.
Two-part compounds command the established base. The steepest expansion runs through ultraviolet-curable formulations.
End User:
Application maturity separates sectors with eighteen-month qualification cycles from those accepting faster material switches.
- Automotive:Powertrain electrification has elevated potting compounds from commodity electrical protection to thermal management infrastructure. Tier-one suppliers in Germany's automotive electronics corridor now require embedded application engineering support alongside material supply.
- Consumer Electronics:Miniaturized assembly in South Korean and Vietnamese contract manufacturing facilities favors rapid-cure technologies. UV-curable silicones are digitizing production workflows through automated dispensing integration.
- Aerospace:Outgassing specifications per ASTM E595 and flame resistance ratings constrain formulation flexibility. India's indigenous avionics programs under defense offset policies specify traceable supply chains.
- Industrial Equipment:Motor drive and power supply encapsulation tolerates longer cure schedules in exchange for cost efficiency.
Automotive anchors volume concentration. Consumer electronics is gaining share fastest through assembly automation.
Application:
Functional performance requirements determine filler selection, cure chemistry, and certification burden.
- Thermal Management:Heat dissipation demands push filler loadings toward processing limits in addition-cure systems. Electric vehicle charging infrastructure in Germany and China specifies these grades for power density optimization.
- Encapsulation:Complete electrical assembly embedding requires ionic purity below ten parts per million for semiconductor packaging. Advanced packaging facilities in the Netherlands enforce sub-ppm contamination thresholds.
- Electrical Insulation:Dielectric strength exceeding fifteen kilovolts per millimeter protects high-voltage busbars and connector assemblies.
- Sealing:Gasket replacement and environmental protection prioritize adhesion to varied substrates over thermal performance.
Encapsulation carries the deepest qualification requirements. Thermal management is expanding most quickly through electrification demand.
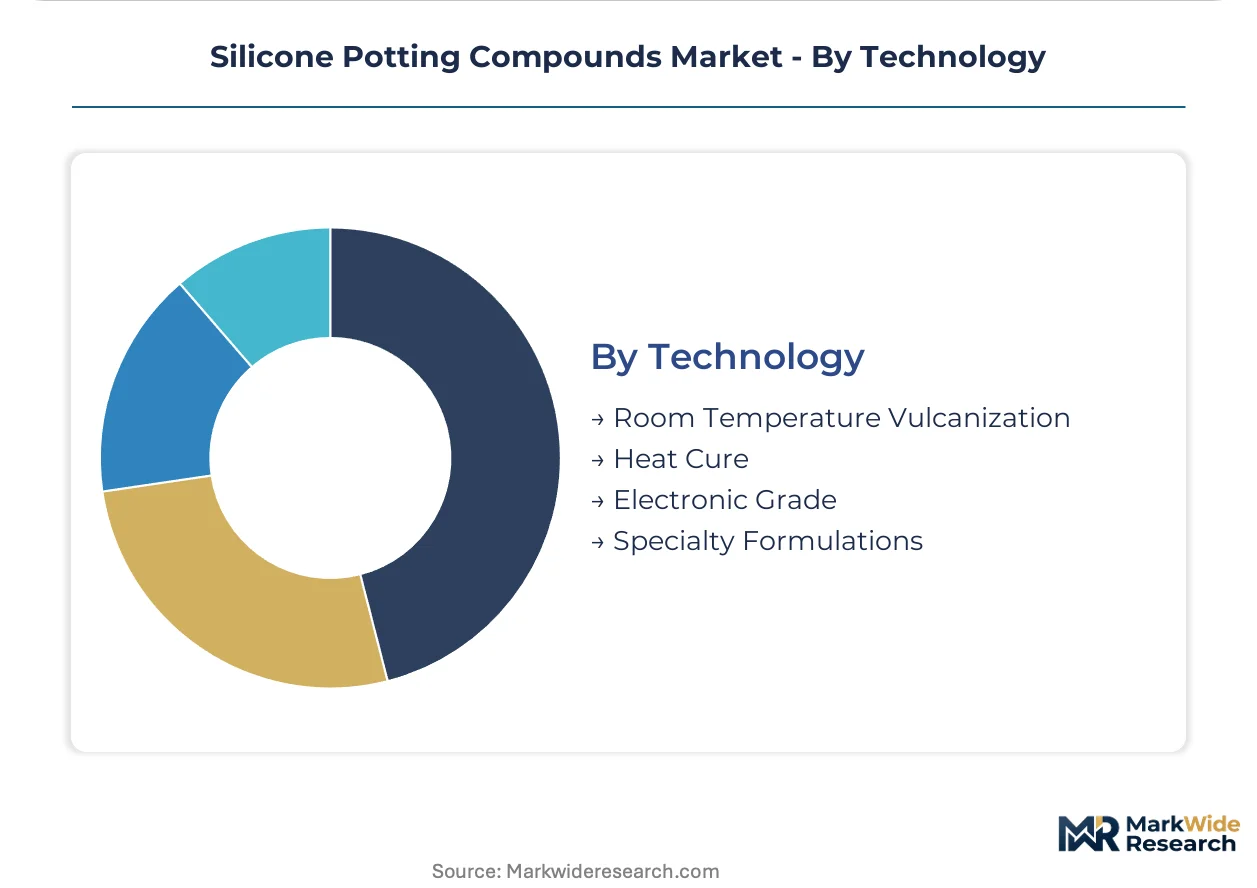
Technology:
Process compatibility and purity grade separate established industrial applications from emerging high-reliability specifications.
- Electronic Grade:Ultra-low ionic contamination and controlled outgassing meet semiconductor packaging and aerospace requirements. REACH candidate list expansion is forcing systematic substitution of legacy catalyst systems in German and Dutch supply chains.
- Room Temperature Vulcanization:Condensation-cure tin or titanium systems suit field repair and prototype applications without oven infrastructure.
- Heat Cure:Addition-cure platinum catalysis achieves complete conversion without byproduct evolution, essential for deep sections.
- Specialty Formulations:Radiation-resistant or chemically resistant modifications serve nuclear instrumentation and oilfield electronics.
Heat cure dominates production volume. Electronic grade is climbing the fastest through advanced packaging miniaturization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives in India and dual carbon enforcement in China are redirecting silicone potting compound procurement patterns across major manufacturing economies. REACH substance registration mandates in Europe and EPA chemical safety protocols in the United States are tightening compliance requirements. Industrial clusters in Germany, China, and India now anchor demand concentration for thermally conductive formulations.
Germany
Battery management system protection and silicon carbide power module packaging drive specification-grade demand from tier-one automotive electronics manufacturers. KBA vehicle certification requirements and ECHA REACH candidate list expansion force systematic catalyst substitution in industrial formulations. Bavaria's automotive electronics corridor concentrates inverter and charging infrastructure development, with direct procurement channels displacing traditional distributor relationships.
China
Semiconductor packaging miniaturization and electric vehicle charging infrastructure deployment pull high-purity electronic-grade volumes into advanced manufacturing facilities. MEE dual carbon goals constrain energy-intensive methylchlorosilane monomer production, creating upstream supply bottlenecks. Yangtze River Delta packaging facilities enforce sub-ppm ionic contamination thresholds for die-shrink applications in consumer electronics assembly.
India
Mobile phone component assembly and indigenous defense electronics programs generate specialized potting compound demand across Tamil Nadu and Karnataka production zones. PLI scheme incentives for electronics manufacturing cluster development attract material suppliers with traceable supply chain capabilities. Bengaluru's emerging semiconductor packaging ecosystem is qualifying electronic-grade formulations for export-oriented contract assembly.
United States
Electric vehicle powertrain electrification and aerospace encapsulation requirements sustain demand for thermally conductive and outgassing-compliant formulations. EPA TSCA Section 6 activity and evolving chemical safety protocols compress formulation timelines for specialty silicone additives. Michigan's automotive electronics development corridor and California's semiconductor design clusters specify embedded application engineering support from compound suppliers.
South Korea
Miniaturized consumer electronics assembly and rapid-cure processing requirements accelerate ultraviolet-curable silicone adoption in contract manufacturing facilities. MFDS industrial chemical registration and semiconductor-grade purity standards govern material qualification for advanced packaging applications. Seoul Capital Area electronics assemblers are digitizing production workflows through automated dispensing integration and real-time cure monitoring systems.
Silicone Potting Compounds Market Key Industry Players
On the supply side, the industry is consolidating around integrated feedstock operators and specialized formulation houses with certification depth. Three strategic archetypes dominate: diversified chemical conglomerates with captive silicone monomer supply, mid-cap specialists focused on aerospace and semiconductor-grade purity protocols, and regional compounders serving cost-sensitive industrial segments. Capacity expansion in thermally conductive grades and direct technical partnerships with automotive electronics engineers represent the dominant competitive moves reshaping channel relationships.
Within the integrated chemical conglomerate tier, Dow and Wacker Chemie AG exemplify supply chain control through backward integration into methylchlorosilane production. Henkel AG & Co. KGaA and Momentive Performance Materials Inc occupy positions emphasizing application engineering depth and electronic-grade purity certification respectively. Shin-Etsu Chemical Co., Ltd. anchors the Asia-Pacific supply base with materials science capabilities spanning semiconductor and automotive specifications.
| Leading Market Players |
|---|
| Dow |
| Henkel AG & Co. KGaA |
| 3M |
| Momentive Performance Materials Inc |
| ELANTAS GmbH |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| CHT Group |
| Master Bond Inc. |
| Others |
Cost & Logistics Intelligence
REACH substance registration mandates and China's MEE dual carbon enforcement together determine both pricing tier spreads and supply chain shape in silicone potting compounds. Regulatory chokepoints on methylchlorosilane feedstock and catalyst systems compress formulation flexibility while concentrating premium-grade sourcing power among pre-registered suppliers.
Pricing Analysis
Certification level creates the primary spread across silicone potting compound tiers. Electronic-grade formulations meeting sub-ppm ionic contamination thresholds command substantial premiums over industrial grades, with automotive thermal management specifications occupying a mid-tier position. Price differentiation hinges on filler loading percentages and cure chemistry complexity, with thermally conductive boron nitride formulations priced above standard encapsulation grades. Cost compression in commodity two-part compounds is intensifying as Chinese methylchlorosilane supply constraints elevate raw material baselines. Tier-one automotive electronics manufacturers exhibit lowest price sensitivity due to warranty liability exposure, while industrial equipment buyers prioritize cost efficiency over performance certification.
Supply Chain Analysis
Methylchlorosilane monomer production concentrates in China, Germany, and the United States as the upstream anchor for silicone potting compound manufacturing. Formulation houses draw from silica filler networks spanning Brazil and Norway alongside platinum catalyst supply chains rooted in South Africa and Russia. Single-source vulnerability runs through China's Yangtze River Delta, where MEE dual carbon enforcement constrains energy-intensive monomer output. Distribution runs through direct technical partnerships with tier-one automotive and semiconductor packaging customers, displacing traditional distributor relationships in high-value segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone potting compound markets fragment across electrification-driven thermal management demand, creating specialized niches for formulation expertise and certification depth. Battery management system protection and semiconductor packaging miniaturization reward suppliers with pre-registered additive portfolios and embedded application engineering capabilities.
For Market Incumbents: Pre-empt regulatory compression on legacy catalyst systems by accelerating REACH-compliant reformulation investments before candidate list expansion deadlines. Deepen backward integration into methylchlorosilane feedstock to insulate margin positions against China's MEE supply constraints. Capture channel control through direct technical partnerships with German automotive electronics engineers, displacing distributor intermediaries in warranty-critical powertrain applications. For New Entrants and Emerging Players: India's PLI scheme electronics manufacturing clusters in Tamil Nadu and Karnataka represent the most penetrable entry point for specialized potting compound suppliers with traceable supply chain documentation. UV-curable formulation gaps in South Korean contract manufacturing facilities offer second-mover advantages through rapid-cure automation integration. Go-to-market positioning should anchor in application engineering support rather than commodity material supply, mirroring tier-one automotive procurement expectations. For Investors and Strategic Acquirers: ECHA REACH candidate list expansion reshapes the acquisition landscape toward mid-cap specialists with pre-registered additive portfolios and electronic-grade purity protocols. Long-term viability centers on formulation houses with demonstrated automotive qualification timelines and semiconductor packaging contamination control capabilities. The signal to watch is tier-one OEM validation pipeline depth as an indicator of sustained margin capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methylchlorosilane | Captive monomer supply insulates margin positions against China's MEE dual carbon enforcement constraints. |
| Electronic-Grade Purity Certification | Sub-ppm ionic contamination protocols unlock semiconductor packaging demand in Netherlands advanced facilities. |
| UV-Curable Formulation Expansion | Rapid-cure technologies eliminate oven bottlenecks in South Korean consumer electronics contract manufacturing. |
| Direct Automotive Procurement Channels | Embedded application engineering support captures tier-one battery management system specification-grade demand. |
| REACH-Compliant Catalyst Substitution | Pre-registered additive portfolios avoid reformulation disruption from ECHA candidate list expansion timelines. |
Research Approach
Operator-level perspectives from silicone compound plant managers, tier-one automotive electronics procurement leads, semiconductor packaging R&D directors, and distribution channel partners anchored the qualitative base. Primary fieldwork combined with secondary validation from SEC filings, customs and trade data, ACC and Cefic industry reports, and ECHA substance registration databases. Bottom-up volume modeling across formulation grades and end-use segments triangulated against top-down market sizing from methylchlorosilane feedstock throughput analysis.
Scenario-bracketing around regulatory enforcement intensity and electric vehicle powertrain electrification pace structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry type, thermal conductivity tier, end-use certification requirement, and regional manufacturing cluster. CAGRs derived from elasticity-adjusted demand curves incorporating silicon carbide power module adoption rates and miniaturized electronics assembly automation trends.
Macroeconomic conditions sit as an overlay; deviation in automotive production cycles or semiconductor capital expenditure would shift the trajectory. Forecasts reflect documented assumptions on methylchlorosilane supply elasticity and REACH compliance timeline adherence. Cross-checking against IHS Markit vehicle production databases and SEMI capital equipment forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Quinidine Sulfate Market
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
Compounding Systems Market
Specialty Compounds
Global Color Masterbatch Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
Global Molding Compounds Market
Specialty Compounds
Stannous Chloride Market
Specialty Compounds
Saudi Arabia Masterbatch Market
Specialty Compounds
Organoclay Market
Specialty Compounds
Global Stable Isotope Labeled Compounds Market
Specialty Compounds
Gypsum-Free Plaster Market
Specialty Compounds
Polyurea Market
Specialty Compounds
United States Caustic Potash Market
Specialty Compounds
Global Stannic Chloride Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market