
 Specialty Silicone Market | 2026-2036
Specialty Silicone Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Silicone Market Outlook
Multi-source procurement for siloxane feedstocks is decoupling from traditional petrochemical supply chains as buyers diversify away from concentrated Asian monomer sources. Dow leverages backward integration into quartz-derived silicon metal to sustain cost stability across elastomer lines. Wacker Chemie AG anchors its position through captive chlorosilane production at its Burghausen complex. Shin-Etsu Chemical Co. Ltd dominates ultra-high-purity electronic-grade silicones through proprietary distillation protocols.
Specialty silicone denotes a class of organosilicon polymers engineered with tailored molecular weights, crosslink densities, and functional group substitutions for performance-critical environments. These materials typically contain siloxane backbones with methyl, phenyl, or vinyl substituents, cured through platinum-catalyzed hydrosilylation or condensation mechanisms to achieve thermal stability from minus sixty to over two hundred degrees Celsius. Elastomers command the largest value pool due to their irreplaceability in medical implants and aerospace seals, while fluids represent the fastest-expanding category driven by thermal management demand in data center liquid cooling. Healthcare applications concentrate margin capture because biocompatibility certification creates steep qualification barriers that protect incumbent suppliers.
EMA medical device regulations and REACH substance restrictions shape formulation chemistry by mandating extractable limits and phthalate-free curing systems in European markets. FDA device master file requirements and ISO 10993 biocompatibility standards govern US market access for implantable silicone components. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as fluorosilicone alternatives face parallel regulatory scrutiny across both jurisdictions.
Market Dynamics
Medical device manufacturers are consolidating silicone sourcing around vertically integrated suppliers capable of certifying extractable limits under EMA medical device regulations and FDA device master file requirements simultaneously.
Growth Catalysts
- Implantable component demand:Cardiovascular and orthopedic device OEMs are specifying platinum-cured elastomers for long-term implant applications, creating specification lock-in effects that protect qualified suppliers.
- Data center liquid cooling:Thermal management fluids with engineered viscosity profiles are displacing glycol-water mixtures in hyperscale server farms, with Dow and Wacker Chemie AG capturing specification roles at major cloud infrastructure operators.
- REACH and RoHS compliance tightening:European purity mandates for healthcare-grade formulations are eliminating non-compliant Asian imports, concentrating margin capture among Burghausen and Midland production complexes.
Market Restraints
- Siloxane monomer concentration:Six Asian producers control over seventy percent of D4 and D5 cyclic siloxane supply, exposing Western formulators to freight cost volatility and tariff exposure.
- Platinum catalyst cost structure:Hydrosilylation curing systems require platinum group metals whose price correlation with automotive catalytic converter demand creates input cost instability.
- Fluorosilicone substitution ceiling:Per- and polyfluoroalkyl substance restrictions under ECHA evaluation are limiting high-performance fluorosilicone adoption in aerospace and automotive sealing despite superior fuel resistance.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO medical device rules harmonization with ISO 13485 is enabling qualified silicone tubing suppliers to displace PVC in domestic bioprocessing equipment.
- Automotive battery thermal interface materials:Two-part thermally conductive gap fillers are automating into electric vehicle pack assembly lines, with Germany and South Korea representing concentrated qualification activity.
- Japan METI carbon neutrality roadmap:Biomass-derived siloxane feedstock incentives are creating first-mover positioning for producers investing in rice husk ash silicon metal extraction.
Industry Challenges
- ISO 10993-5 and -10 testing backlog:Cytotoxicity and irritation study capacity constraints at certified laboratories are extending implantable silicone component qualification timelines by eight to fourteen months.
- Legacy condensation-cure equipment stranded:Platinum-catalyzed addition-cure chemistry requires cleanroom mixing and dispensing infrastructure that mid-tier converters lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Silicone Market |
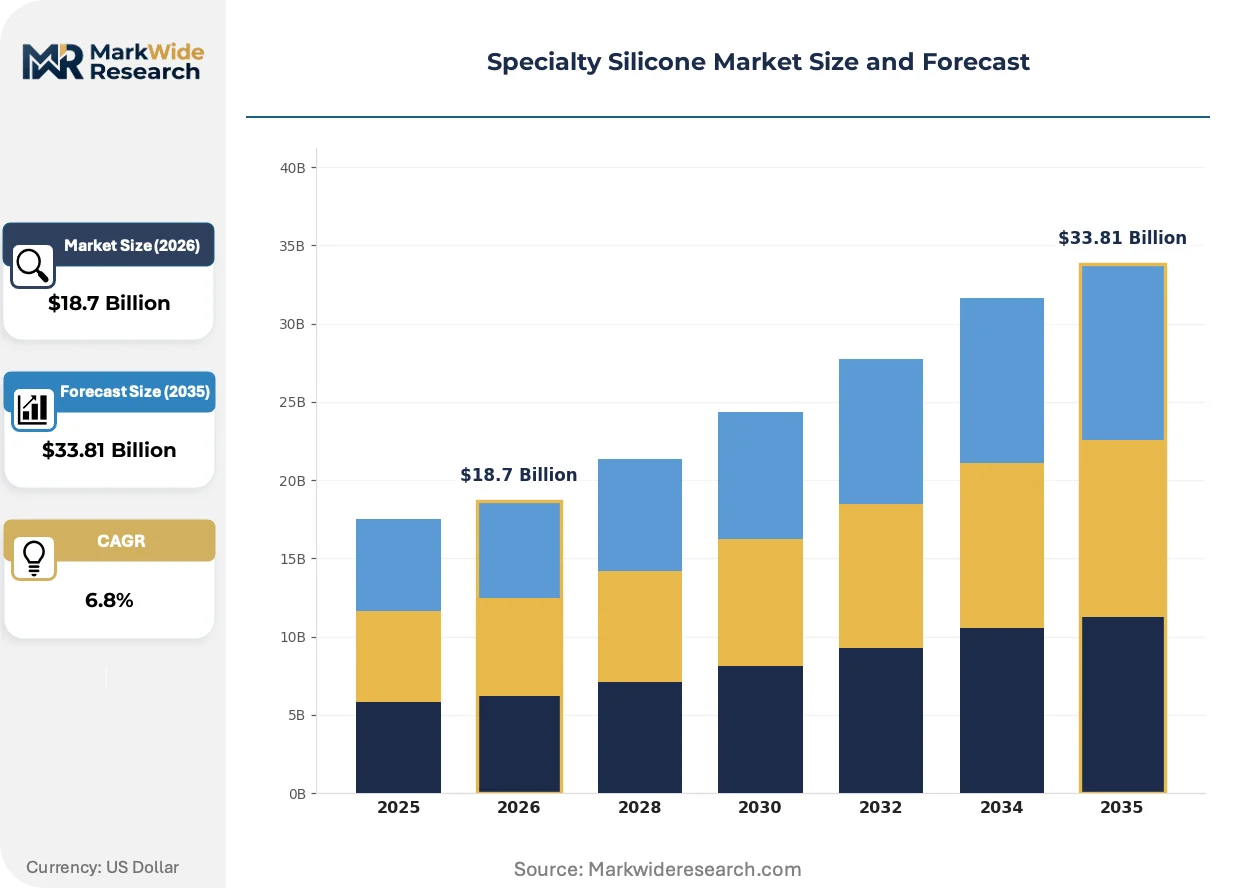
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastomers, Resins, Fluids, Sealants Application: Aerospace, Automotive, Electronics, Healthcare End User: Manufacturers, Distributors, Contractors, Retailers Form: Liquid, Gel, Solid, Paste |
| Companies Covered | Dow, Momentive, Wacker Chemie AG, Shin-Etsu Chemical Co. Ltd, Elkem ASA, Evonik Industries AG, CHT Germany GmbH, AB Specialty Silicones, KCC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Silicone Market Strategic Shifts
Formulation chemistry is pivoting toward bio-based feedstocks and automated precision dispensing as regulatory scrutiny tightens on residual extractables and manufacturing reproducibility.
Platinum-catalyzed liquid silicone rubber injection molding is automating micro-component production for drug-delivery devices and minimally invasive surgical instruments. Medical device OEMs in Germany and Switzerland are qualifying multi-cavity tooling with in-line vision inspection, compressing cycle times while maintaining cavity-to-cavity consistency within tight tolerances. This automation is enabling single-use silicone valve production at costs competitive with thermoplastic alternatives.
EMA's 2023 update to the Medical Device Regulation substance restrictions is forcing reformulation of tin-catalyzed condensation systems in European markets. Manufacturers are migrating toward platinum-cured addition chemistry or non-tin condensation catalysts to maintain CE marking eligibility, with wound care and respiratory device segments experiencing the most acute compliance pressure. German notified bodies are processing technical documentation revisions with twelve-to-eighteen-month review queues.
Device master file consolidation is concentrating procurement authority among fewer silicone converters with dual FDA-EMA qualification capabilities. Large medical device OEMs are reducing qualified supplier lists from twelve-to-fifteen vendors to three-to-five strategic partners, with chemistry control and regulatory documentation quality outweighing unit price in sourcing decisions. This consolidation is most visible in cardiovascular implant supply chains serving the US and EU markets.
Specialty Silicone Market Segmentation
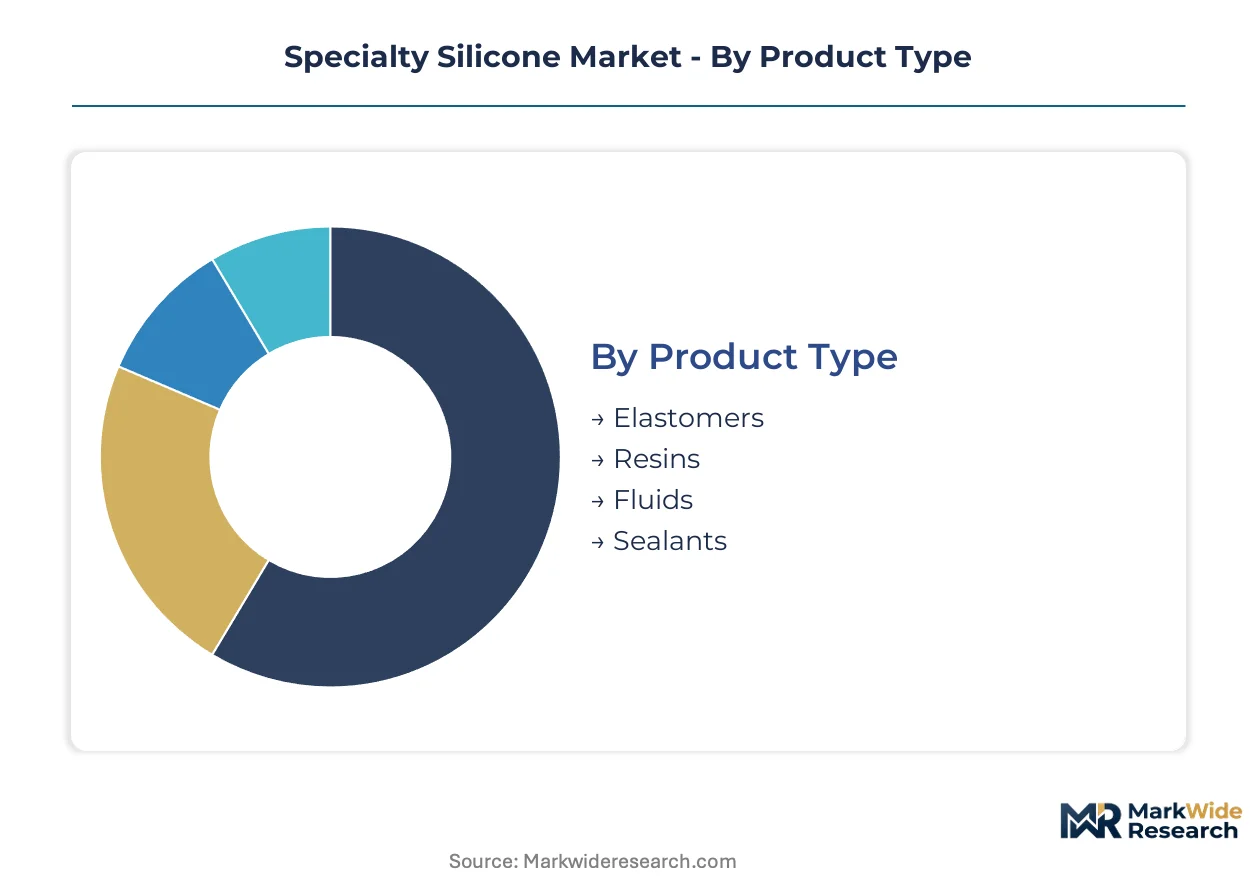
Specialty silicone procurement decisions pivot on molecular architecture, curing chemistry, and certification grade rather than commodity pricing. Each segmentation axis reveals distinct margin pools and qualification barriers that reshape competitive positioning across medical, automotive, and electronics verticals.
Product Type:
Customization intensity spans from standardized fluids to highly engineered elastomers with implant-grade extractable limits.
- Elastomers:Platinum-cured silicone rubbers with tunable durometer and crosslink density serve long-term implant applications and aerospace seals. Cardiovascular device OEMs in Germany and Switzerland specify these for pacemaker lead insulation, creating specification lock-in that protects qualified suppliers against price competition.
- Fluids:Low-viscosity polydimethylsiloxane oils and modified siloxanes with engineered thermal conductivity profiles displace glycol-water mixtures in hyperscale data center liquid cooling. Dow and Wacker Chemie AG have captured specification roles at major cloud infrastructure operators in the US and Germany.
- Resins:Rigid siloxane polymers with phenyl or vinyl substitutions provide thermal stability for electronics encapsulation and LED potting applications.
- Sealants:One-part moisture-cure and two-part addition-cure formulations serve construction glazing and automotive assembly with varying movement capability ratings.
Most installed capacity flows through Elastomers. Expansion is steepest in Fluids.
Application:
End-use concentration determines regulatory exposure and margin capture potential across this category.
- Healthcare:Implantable components, drug-delivery systems, and respiratory devices demand ISO 10993 biocompatibility certification and FDA device master file documentation. EMA Medical Device Regulation substance restrictions and REACH compliance requirements eliminate non-compliant imports, concentrating procurement among vertically integrated suppliers with dual FDA-EMA qualification capabilities.
- Electronics:Thermal interface materials, encapsulants, and semiconductor-grade coatings require ultra-high-purity formulations with controlled ionic content. Shin-Etsu Chemical dominates this segment through proprietary distillation protocols at its Japan facilities.
- Automotive:Battery thermal management gap fillers and gasketing materials face qualification timelines tied to electric vehicle platform launches in Germany and South Korea.
- Aerospace:Fuel-resistant fluorosilicone seals confront substitution ceilings as ECHA evaluates per- and polyfluoroalkyl substance restrictions across European markets.
Healthcare commands the steepest qualification barriers. Electronics is gaining share fastest on data center and semiconductor capital expansion.
End User:
Channel structure separates specification authority from fulfillment execution across the value chain.
- Manufacturers:Medical device OEMs and automotive Tier 1s maintain direct relationships with silicone formulators for certified material streams, consolidating qualified supplier lists from twelve-to-fifteen vendors to three-to-five strategic partners.
- Distributors:Technical distributors stock standard grades for electronics and industrial applications, providing formulation guidance and small-lot availability.
- Contractors:Construction and MRO channels move sealant and adhesive volumes through applicator networks with regional coverage requirements.
- Retailers:Consumer-facing channels serve DIY and small commercial accounts with pre-packaged general-purpose grades.
Direct procurement from Manufacturers captures the highest margin pool. Distributor engagement is expanding most quickly in Asian electronics manufacturing clusters.
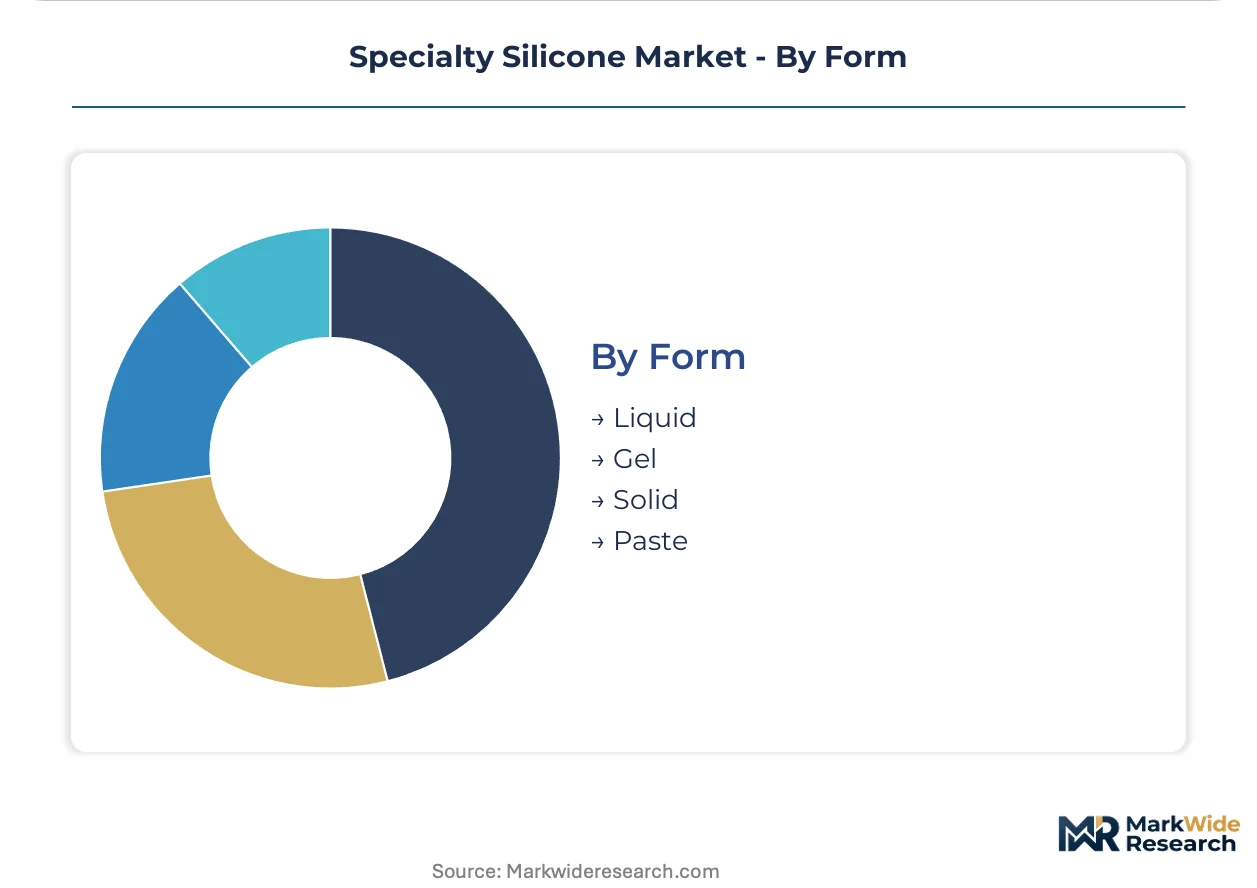
Form:
Physical state dictates processing equipment requirements and automation compatibility across converting operations.
- Liquid:Two-part pumpable systems enable automated dispensing and liquid silicone rubber injection molding for micro-component production with in-line vision inspection.
- Solid:Millable gums and high-consistency rubbers require two-roll milling and compression molding infrastructure typical of legacy converter operations.
- Gel:Soft, minimally crosslinked materials provide cushioning and vibration damping for wearable medical devices and electronics protection.
- Paste:Thixotropic non-sag formulations permit overhead and vertical application in construction and automotive assembly without tooling or fixturing.
Solid forms retain the largest installed equipment base. Liquid forms are climbing the fastest on medical device automation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's chemical processing corridor along the Rhine anchors specialty silicone demand through automotive OEMs and medical device manufacturers requiring REACH-compliant formulations.
Germany
Automotive battery thermal interface materials and implantable cardiovascular devices drive specification-grade silicone consumption. EMA Medical Device Regulation substance restrictions and REACH compliance mandates eliminate non-compliant imports, concentrating procurement among Burghausen and Leverkusen production complexes with captive chlorosilane capabilities.
United States
Hyperscale data center liquid cooling systems and FDA-regulated implantable components absorb high-purity elastomer and fluid volumes. FDA device master file requirements and ISO 10993 biocompatibility standards govern market access, with Midland, Michigan and silicone valley clusters in New England serving qualified medical device OEMs.
Japan
Semiconductor-grade encapsulants and ultra-high-purity electronic coatings sustain demand from Tokyo-Osaka electronics manufacturing belts. METI carbon neutrality roadmap incentives for biomass-derived siloxane feedstocks are accelerating rice husk ash silicon metal extraction investments in Chubu and Kyushu regions.
India
Domestic pharmaceutical manufacturing expansion and bioprocessing equipment modernization are displacing PVC with platinum-cured silicone tubing. CDSCO medical device rules harmonization with ISO 13485 enables qualified suppliers to capture share in Maharashtra and Gujarat pharmaceutical clusters.
South Korea
Electric vehicle battery pack assembly automation and semiconductor capital expansion concentrate demand for thermally conductive gap fillers and high-purity coatings. MFDS medical device regulations and automotive platform qualification timelines in Seoul-Incheon and Busan-Ulsan industrial zones favor vertically integrated formulators.
Specialty Silicone Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-based feedstock differentiation and automated precision dispensing capabilities. The market structure reflects moderate consolidation around integrated chemical conglomerates with captive siloxane supply, alongside specialized converters serving medical certification niches. Strategic archetypes include backward-integrated material suppliers, dual-qualified medical device component specialists, and regional distribution-focused formulators. Dominant competitive moves center on regulatory qualification consolidation and capacity expansion into battery thermal management materials.
Among Germany-based integrated producers, Wacker Chemie AG and Evonik Industries AG exemplify the captive supply archetype through in-house chlorosilane and silicon metal production. Dow represents the multinational diversified chemical conglomerate model with quartz-derived silicon metal integration spanning multiple continents. These three anchors demonstrate how geographic production clustering and regulatory dual-qualification capabilities create defensive positioning against Asian monomer supply concentration.
| Leading Market Players |
|---|
| Dow |
| Momentive |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co. Ltd |
| Elkem ASA |
| Evonik Industries AG |
| CHT Germany GmbH |
| AB Specialty Silicones |
| KCC Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH and RoHS compliance mandates in Europe gate qualified supply access while anchoring premium-tier pricing for healthcare-grade silicone formulations. Buyers seeking implantable component certification face steep extractable-limit testing costs that stratify the supply base into dual-qualified incumbents and excluded imports.
Pricing Analysis
Platinum group metal cost pass-through from automotive catalytic converter demand creates input instability for hydrosilylation-cured elastomers. Three-tier pricing structure across implant-grade, industrial-grade, and standard-grade levels reflects ISO 10993 certification investment and FDA device master file documentation burden. Cost compression in standard-grade fluids is intensifying because Asian D4/D5 monomer suppliers compete on volume scale. Contract manufacturers serving medical device OEMs exhibit lowest price sensitivity due to specification lock-in effects.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for data center thermal management fluids and automotive battery gap fillers. Manufacturing concentrates in Germany, the United States, and Japan where chlorosilane and silicon metal production anchor formulation capabilities. Siloxane monomer supply draws from concentrated Asian sources, creating tariff exposure and freight cost volatility for Western formulators. Distribution runs through vertically integrated producers with captive feedstock supply and technical distributors serving electronics and industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
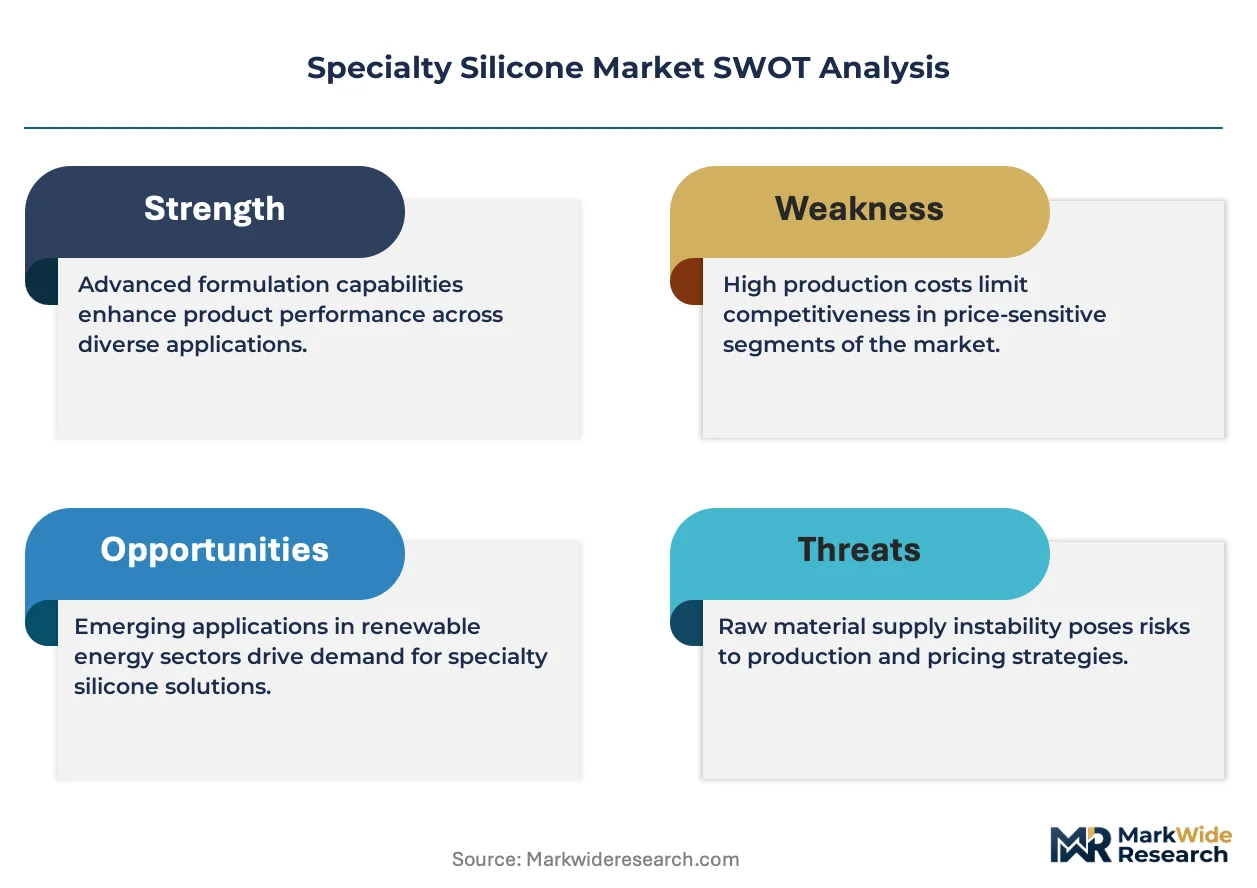
The specialty silicone market functions as a stable compounder where medical device regulatory qualification barriers protect incumbent margins through specification lock-in cycles.
For Market Incumbents: Deepen backward integration into quartz-derived silicon metal or chlorosilane production to insulate margins from D4/D5 monomer price volatility. Expand cleanroom liquid silicone rubber injection molding capacity in Germany and the United States to capture device master file consolidation among cardiovascular and orthopedic OEMs. For New Entrants and Emerging Players: Technical distributors serving Indian pharmaceutical manufacturing clusters offer the most penetrable channel for platinum-cured silicone tubing displacement of PVC bioprocessing equipment. Target CDSCO-qualified supply partnerships with Maharashtra and Gujarat-based drug manufacturers as the go-to-market anchor. For Investors and Strategic Acquirers: Roll-up economics work for regional medical device component specialists because ISO 10993-5 and -10 testing backlogs extend qualification timelines and strand mid-tier competitors without capital for cleanroom infrastructure. Watch ECHA per- and polyfluoroalkyl substance restriction decisions as the inflection signal for fluorosilicone substitution ceiling relief.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Metal | Dow and Wacker Chemie AG anchor cost stability through quartz-derived feedstock control at Midland and Burghausen complexes. |
| Dual FDA-EMA Qualification Investment | Device master file consolidation among cardiovascular OEMs rewards suppliers with simultaneous US and European regulatory access. |
| Automated Liquid Silicone Rubber Deployment | Multi-cavity tooling with in-line vision inspection compresses cycle times for single-use valve production at German medical device converters. |
| Bio-Based Siloxane Feedstock Development | METI carbon neutrality roadmap incentives in Japan accelerate rice husk ash silicon metal extraction investments in Chubu region. |
| Battery Thermal Interface Material Capacity | Two-part thermally conductive gap fillers automate into electric vehicle pack assembly lines serving German and South Korean OEM platforms. |
Study Parameters
Multiple input streams — primary interviews with silicone formulators and medical device procurement leads, secondary validation through FDA device master file databases and EMA regulatory submission records, and customs trade data for siloxane monomer flows — were reconciled to construct segment-level demand estimates. Plant managers at chlorosilane production facilities, technical directors at elastomer converters, and GPO contracts managers at US hospital systems provided operational perspective. Bottom-up modeling of end-use consumption and top-down cross-check against producer capacity announcements ensured triangulation integrity.
Data-stream reconciliation across product type, application grade, curing chemistry, and regional production hub dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted demand modeling incorporating electric vehicle platform launch timelines and hyperscale data center capex cycles. Semiconductor capital expansion and pharmaceutical manufacturing modernization served as industry-specific volume drivers.
Revisions become necessary when ECHA substance restriction decisions, platinum group metal price shocks, or Asian monomer supply disruptions materialize outside base-case assumptions. Forecasts reflect documented elasticity parameters and qualification timeline benchmarks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Jesmonite Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Absorbent Booms and Socks Market
Specialty Materials
Open Cell Foam Market
Specialty Materials
Global PE Films Market
Specialty Materials
Electrode Paste Market
Specialty Materials
Niobium Pentoxide Market
Specialty Materials
Nanocapsules Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Conductive Plastics Market
Specialty Materials
Europe Acrylic Sheet Market
Specialty Materials
United States Neoprene Market