
 Silicone Additives Market | 2026-2036
Silicone Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Additives Market Intelligence
Specialty chemical distribution is narrowing as regional distributors consolidate around technical service capabilities. Dow leverages backward integration into siloxane feedstocks to control cost positions across sealant-grade additives. Wacker Chemie AG anchors European supply through integrated production at its Burghausen complex. Momentive Performance Materials competes on electronics-grade purity specifications for semiconductor encapsulation.
Silicone additives encompass organofunctional silanes, silicone polyethers, and modified siloxanes formulated at 0.1-5.0% loading levels to modify surface tension, rheology, or crosslink density in polymer systems. Flow improvers dominate volume demand in high-solids coatings where substrate wetting failures carry rework penalties. Defoamers represent the fastest-expanding product class in waterborne architectural coatings as formulators eliminate mineral oil alternatives. Electronics applications concentrate margin pools where Shin-Etsu Chemical and Gelest supply ultra-low-ionic-content grades for conformal coatings.
REACH registration requirements in Europe compel full toxicological dossiers for siloxane substances above one-tonne annual thresholds. EPA TSCA Section 5 premanufacture notifications govern new silicone additive introductions in the United States. China's MEE enforces volatile organic compound emission standards in coating operations across the Yangtze River Delta. Stakeholders must monitor regulatory divergence between jurisdictions where divergent hazard classifications threaten unified product portfolios.
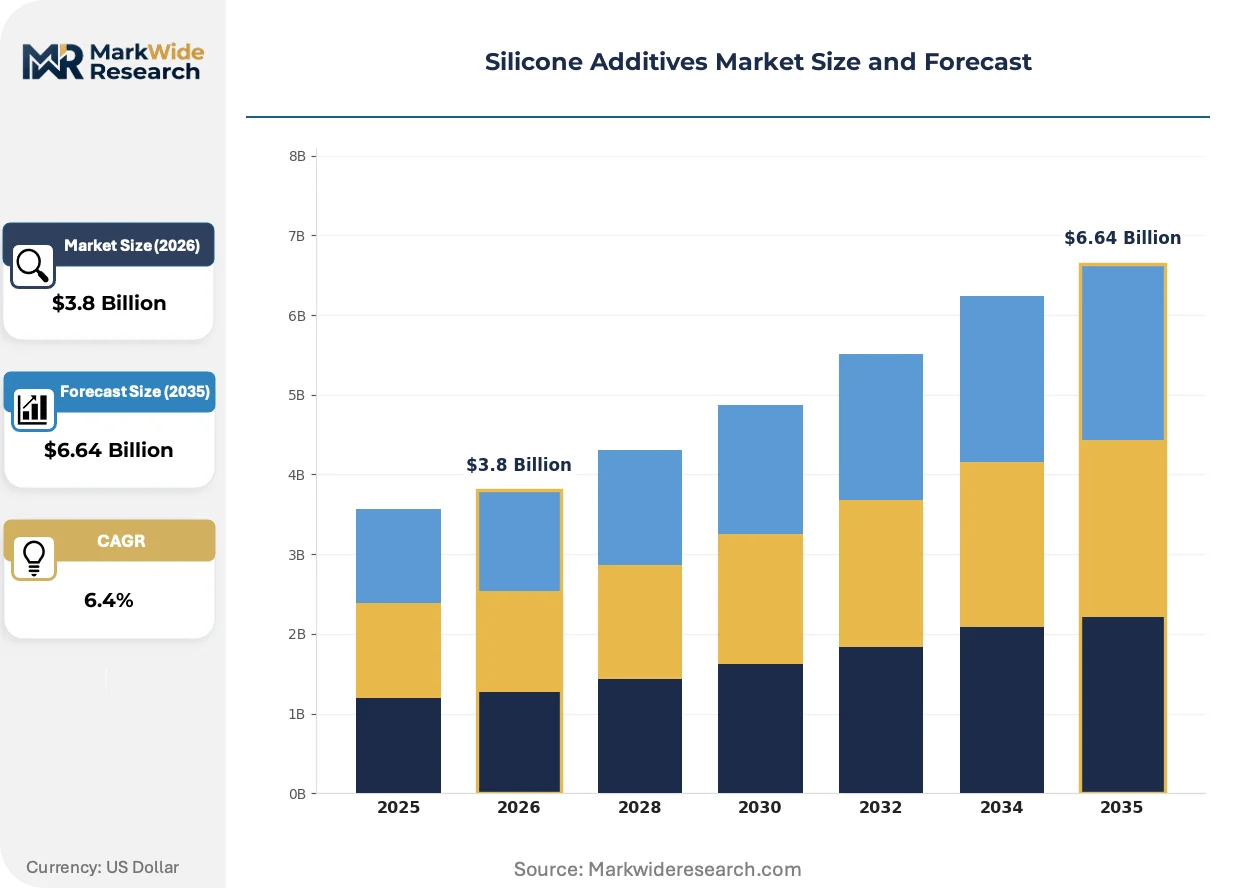
Market Dynamics
REACH compliance deadlines are compressing formulation windows across European coatings operations, forcing additive suppliers to accelerate toxicological dossier completion while Asian manufacturing clusters expand siloxane capacity to capture displaced volume.
Growth Catalysts
- Waterborne architectural coatings mandate:China's MEE volatile organic compound emission standards in the Yangtze River Delta are eliminating mineral oil defoamers and redirecting procurement toward silicone-based alternatives.
- Semiconductor encapsulation purity requirements:Electronics-grade silicone additives with ultra-low ionic content are capturing specification locks in conformal coating formulations for advanced packaging nodes.
- High-solids coatings penetration:Flow improver demand concentrates in automotive refinish and industrial maintenance applications where substrate wetting failures trigger costly rework penalties.
Market Restraints
- Siloxane feedstock concentration:Backward integration into methylchlorosilane precursors limits viable supplier entrants to those with captive chlorosilane production or long-term offtake agreements with Chinese petrochemical complexes.
- EPA TSCA Section 5 friction:New chemical notifications for organofunctional silanes impose 90-day review cycles that delay product introductions and compress commercialization timelines.
- Hybrid organic-inorganic substitutes:Fluorosurfactant manufacturers are reformulating short-chain perfluorinated compounds to regain traction in coatings surface tension modification.
Strategic Opportunities
- India coating operations expansion:Domestic production capacity for architectural and automotive coatings is scaling in Gujarat and Maharashtra, creating first-mover positioning for silicone additive technical service networks.
- EU Green Deal chemistry:The Chemicals Strategy for Sustainability is accelerating substitution timelines for substances of very high concern, advantaging silicone platforms with favorable environmental fate profiles.
- 3D printing resin modification:Silicone polyethers are enabling controlled shrinkage and surface finish in photopolymer formulations for dental and industrial prototyping applications.
Industry Challenges
- Formulation chemist scarcity:Technical service capabilities require hybrid expertise in polymer rheology and regulatory dossier preparation that outpaces European and North American training pipeline output.
- Multi-jurisdiction registration synchronization:Divergent hazard classifications between ECHA REACH, EPA TSCA, and China's MEE chemical inventories force portfolio fragmentation and duplicate testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Additives Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Improvers, Defoamers, Crosslinkers, Adhesion Promoters, Anti-Settling Agents Application: Sealants, Coatings, Personal Care, Electronics, Textile Processing End User: Construction Contractors, Electronics Manufacturers, Cosmetic Brands, Textile Processors, Packaging Producers Packaging Type: Drums, Carboys, Totes, Bulk Bags, Intermediate Bulk Containers |
| Companies Covered | Elkem ASA, Evonik Industries AG, Dow, BASF SE, KCC Corporation, Wacker Chemie AG, Momentive Performance Materials, Gelest, Inc., Shin-Etsu Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Additives Market Strategic Shifts & Innovations
Silicone additive innovation is pivoting from commodity defoamer supply toward engineered surface control systems that integrate with automated coating application equipment and real-time viscosity monitoring.
Reactive silicone polyether technology is collapsing the traditional separation between flow control and substrate wetting functions in high-solids formulations. Automotive OEM paint shops are adopting these dual-purpose additives to reduce tank farm complexity and shorten color change cycles. The structural consequence is compressing SKU counts among tier-one additive suppliers.
ECHA's restriction roadmap for cyclic siloxanes (D4, D5, D6) is forcing reformulation of personal care and coating applications where these materials previously served as carriers. Downstream formulators are accelerating qualification of linear siloxane alternatives and volatile methylsiloxane-free systems. European sealant manufacturers bear the highest compliance burden, with substitution timelines tightening through 2027.
Specification-driven procurement is consolidating buyer power among multinational coatings formulators who unbundle technical service from product supply. Regional distributors are responding by embedding formulation laboratories within key accounts in Germany and the United States. This pattern is most pronounced in automotive refinish, where BASF and PPG operating companies now require direct supplier technical integration.
Silicone Additives Market Segmentation
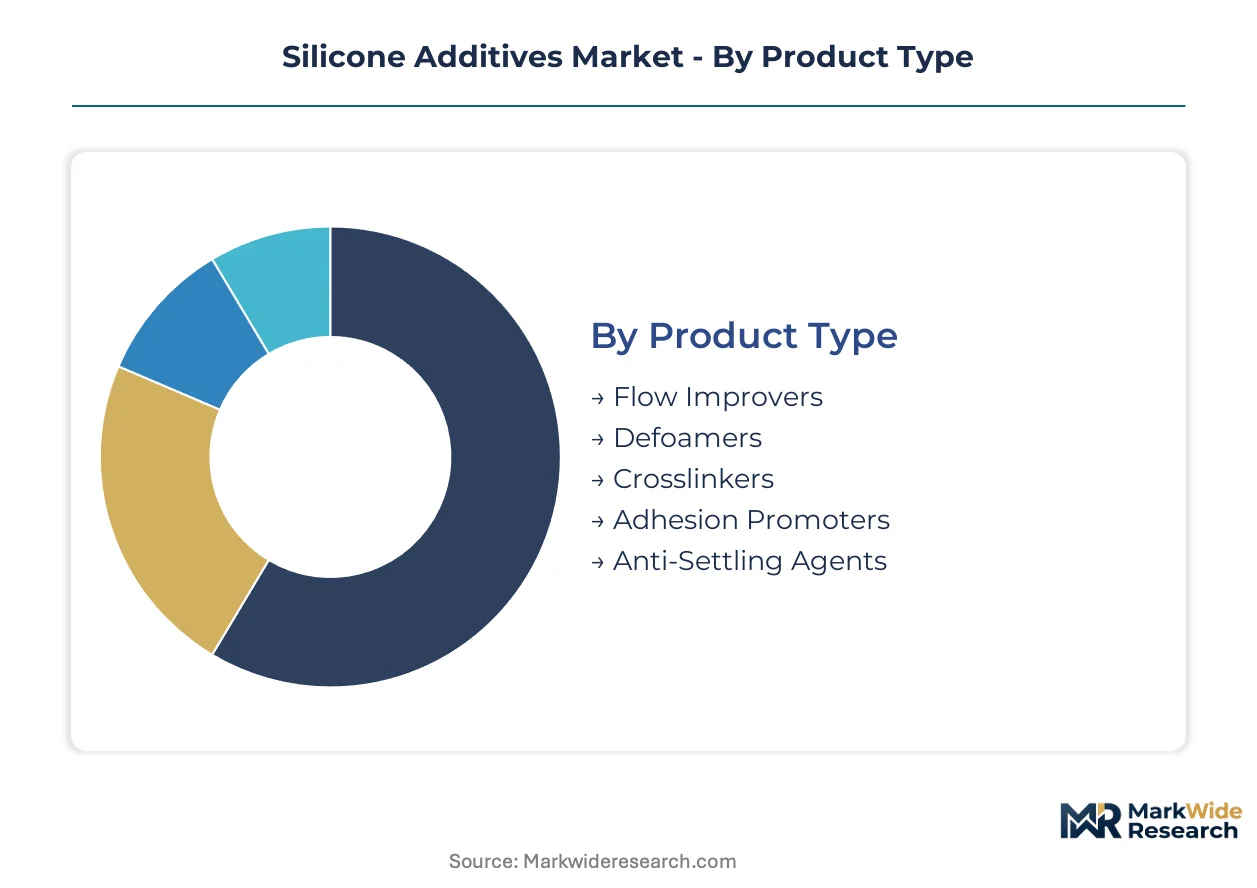
Silicone additives serve divergent functional requirements across polymer systems, with formulation chemistry dictating product selection. Segmentation reveals how technical specifications cascade through supply chains to shape procurement patterns and margin structures.
Product Type:
Flow improvers and defoamers anchor the use-case spectrum, spanning high-solids coatings to waterborne architectural systems.
- Flow Improvers:Organofunctional silanes and silicone polyethers reduce surface tension to prevent substrate wetting failures in automotive refinish operations. Demand concentrates in Germany's automotive OEM paint shops where color change cycle compression rewards dual-purpose additive systems.
- Defoamers:Modified siloxanes formulated at 0.1-2.0% loading eliminate foam in waterborne coatings without the volatile organic compound burden of mineral oil alternatives. China's MEE emission standards in the Yangtze River Delta are redirecting procurement toward silicone-based defoamers as formulators abandon legacy options.
- Crosslinkers:Organofunctional silanes control cure kinetics in moisture-cured sealants for construction applications.
- Adhesion Promoters:Silane coupling agents bridge organic polymers and inorganic substrates in electronics encapsulation.
- Anti-Settling Agents:Fumed silica dispersions maintain pigment suspension in high-pigment-volume-concentration coatings.
Established volume favors flow improvers; emerging adoption favors defoamers as regulatory deadlines compress substitution timelines.
Application:
Cost tier stratification separates specification-locked electronics grades from commodity construction sealants.
- Coatings:Architectural and industrial formulations consume the broadest product range, with flow control and defoaming functions commanding formulation priority. Automotive refinish specifications in the United States now require direct supplier technical integration, compressing distributor margins.
- Electronics:Conformal coatings for semiconductor encapsulation demand ultra-low-ionic-content grades with purity specifications that lock in supplier relationships. Shin-Etsu Chemical and Gelest anchor this segment where qualification cycles exceed 18 months.
- Sealants:Construction-grade silicones rely on crosslinker packages for moisture-cure kinetics in building envelope applications.
- Personal Care:Cyclic siloxane restrictions under ECHA's D4/D5/D6 roadmap are forcing reformulation toward linear siloxane carriers.
- Textile Processing:Softening and water-repellency finishes utilize amino-functional siloxanes for fabric hand modification.
Premium pricing concentrates in electronics; volume scale concentrates in coatings.
End User:
Customer type determines technical service intensity and contract structure across the value chain.
- Construction Contractors:Asia-Pacific building envelope specialists drive formulation demand through sealant procurement. China's coastal manufacturing provinces cluster silicone polymer capacity near downstream applicators, shortening logistics loops.
- Electronics Manufacturers:Semiconductor packaging houses and PCB assemblers impose purity specifications that filter supplier pools to ultra-low-ionic-content specialists. Qualification requirements in this segment create 24-36 month supplier lock-in effects.
- Cosmetic Brands:Personal care formulators navigate ECHA cyclic siloxane restrictions while maintaining sensory performance in skin and hair applications.
- Textile Processors:Fabric finishing houses in India and Bangladesh utilize silicone softeners for garment hand modification.
- Packaging Producers:Food-contact and industrial packaging coatings employ silicone additives for slip and release functions.
Direct technical integration dominates electronics; distributor intermediation persists in construction.
Packaging Type:
Volume scale and hazard classification dictate container selection through the supply chain.
- Drums:Standard 200-liter steel and plastic drums serve mid-volume coatings formulators with established material handling infrastructure. This format dominates European and North American distribution where palletized logistics networks are mature.
- Totes:Intermediate volume containers reduce drum handling labor in high-throughput automotive paint operations. PPG and BASF operating companies in Germany and the United States specify totes for color-matching facilities.
- Carboys:Smaller-volume glass and plastic containers serve laboratory and pilot-scale formulation work.
- Bulk Bags:Powdered anti-settling agents and fumed silica derivatives ship in flexible intermediate bulk containers for compounding operations.
- Intermediate Bulk Containers:Reusable IBC totes with integrated pumping systems serve just-in-time coating production lines.
Drum formats retain share in fragmented formulator bases; tote adoption climbs in consolidated automotive supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE enforcement in China anchors the dominant geography where coastal manufacturing provinces cluster silicone polymer capacity near downstream sealant and electronics producers. Regulatory divergence between ECHA REACH, EPA TSCA, and China's MEE forces portfolio fragmentation across multinational suppliers.
China
Yangtze River Delta coating operations drive defoamer demand as MEE volatile organic compound standards eliminate mineral oil alternatives. The country's emission enforcement redirects procurement toward silicone-based systems. Jiangsu and Zhejiang provinces concentrate siloxane production near sealant formulators in Shanghai-Ningbo corridor.
Germany
Automotive OEM paint shops in Bavaria and Baden-Württemberg compress color change cycles through dual-purpose additive adoption. ECHA's restriction roadmap for D4/D5/D6 cyclic siloxanes forces reformulation timelines through 2027. Burghausen complex anchors European supply with integrated siloxane production serving sealant manufacturers.
United States
EPA TSCA Section 5 premanufacture notifications impose 90-day review cycles on organofunctional silane introductions. Electronics-grade purity specifications in semiconductor packaging concentrate procurement among ultra-low-ionic-content specialists. Automotive refinish specifications in Michigan and Ohio require direct supplier technical integration.
India
Domestic coating capacity scaling in Gujarat and Maharashtra creates first-mover positioning for technical service networks. BIS standards govern chemical imports while state-level pollution control boards enforce volatile organic compound limits. Mundra and Hazira industrial corridors cluster new architectural and automotive coating operations.
Japan
Semiconductor encapsulation demand in Kyushu and Kansai regions locks in supplier relationships through 18-24 month qualification cycles. METI chemical management policies align with international hazard classification frameworks. Osaka-Tokyo industrial belt concentrates electronics-grade silicone additive consumption for conformal coating applications.
Silicone Additives Market Key Industry Players
Backward-integrated petrochemical conglomerates and specialty chemical specialists split the market into distinct capability tiers. Consolidation pressures concentrate around technical service intensity and regulatory dossier completion speed. Three archetypes dominate: siloxane feedstock owners with captive chlorosilane production, formulation-integrated distributors with embedded laboratories, and purity-focused specialists serving electronics qualification requirements. Competitive moves center on regional distributor consolidation and accelerated toxicological registration completion.
Within the feedstock-integrated tier, Dow and Wacker Chemie AG exemplify archetypes combining upstream siloxane control with downstream formulation partnerships. Momentive Performance Materials occupies a position emphasizing electronics-grade purity specifications. These three entities represent the structural segmentation where backward integration, regional technical presence, and qualification-locked specialization define competitive positioning.
| Leading Market Players |
|---|
| Elkem ASA |
| Evonik Industries AG |
| Dow |
| BASF SE |
| KCC Corporation |
| Wacker Chemie AG |
| Momentive Performance Materials |
| Gelest, Inc. |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Overcapacity in Jiangsu and Zhejiang siloxane production clusters compresses spot pricing for methylchlorosilane feedstocks while simultaneously eroding supplier leverage in contract negotiations with coatings formulators. This utilization dynamic rewards backward-integrated producers with captive chlorosilane supply and squeezes toll manufacturers dependent on merchant markets.
Pricing Analysis
Geographic price spreads widen between coastal Chinese manufacturing hubs and European automotive paint corridors, reflecting divergent energy input costs and logistics burdens. Three-tier pricing structure across electronics-grade, sealant-grade, and commodity architectural tiers separates ultra-low-ionic-content specialists from construction-grade volume suppliers. Pricing pressure stems from fluorosurfactant reformulation campaigns targeting coatings surface tension modification. Construction contractors in Asia-Pacific exhibit highest price sensitivity; semiconductor packaging houses lock in premium grades through multi-year qualification cycles.
Supply Chain Analysis
Extended payment terms from multinational coatings formulators now stretch to 90-120 days, forcing regional distributors to rely on supply-chain finance facilities from integrated petrochemical conglomerates. Manufacturing concentrates in China, Germany, and the United States where siloxane capacity clusters near downstream sealant and electronics producers. Feedstock supply draws from methylchlorosilane precursors, organofunctional silane intermediates, and high-purity silicon metal. Single-source vulnerability concentrates in Jiangsu province where environmental enforcement intermittently idles chlorosilane trains. Distribution runs through formulation-integrated technical service networks in automotive refinish and distributor intermediation in construction sealants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone additive incumbents face substitution defense imperatives as fluorosurfactant manufacturers reformulate short-chain perfluorinated compounds to recapture coatings surface tension modification share.
For Market Incumbents: Pre-empt fluorosurfactant incursion by accelerating dual-purpose additive R&D that collapses flow control and substrate wetting functions, while embedding formulation laboratories within PPG and BASF operating companies to deepen technical integration lock-in. Backward integration into siloxane feedstocks remains essential for cost position defense against Chinese petrochemical complex expansions. For New Entrants and Emerging Players: Build out technical service networks in Gujarat and Maharashtra coating corridors before established distributors consolidate first-mover positioning, targeting domestic architectural and automotive formulators with localized formulation support. India coating operations expansion offers the most penetrable white space given BIS import governance complexity that filters out pure trading houses lacking technical capabilities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronics-grade purity segments where qualification infrastructure and cleanroom manufacturing requirements create barriers. Long-term viability favors acquisition targets combining ultra-low-ionic-content production with existing 18-24 month qualification locks at semiconductor packaging houses. Watch for ECHA D4/D5/D6 restriction timeline acceleration as inflection signal for linear siloxane substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstocks | Dow and Wacker Chemie AG leverage captive methylchlorosilane production to defend margin positions against merchant market volatility. |
| Embedded Formulation Laboratory Expansion | Regional distributors in Germany and the United States co-locate technical service capabilities within automotive OEM paint shops to compress color change cycles. |
| Electronics-Grade Purity Qualification Acceleration | Shin-Etsu Chemical and Gelest extend 24-36 month supplier lock-in effects through ultra-low-ionic-content certification for conformal coating applications. |
| Linear Siloxane Substitution Capacity Buildout | European sealant manufacturers accelerate D4/D5/D6 alternative qualification to meet ECHA restriction roadmap deadlines through 2027. |
| India Technical Service Network Establishment | First-mover distributors capture Gujarat and Maharashtra coating operations expansion with localized formulation support and BIS compliance expertise. |
Research Approach
A standing panel of technical R&D directors at coatings formulators, procurement leads at semiconductor packaging houses, distribution channel partners in European construction sealants, and plant managers at siloxane production complexes provided ongoing calibration across the study. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration dossiers. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Scenario-bracketing framed analytical projections across the modeling period, with segmentation dimensions including functional additive type, end-use application tier, purity grade specification, and regional production hub clustering. CAGRs derived from weighted average of historical trajectory analysis and demand driver elasticity modeling. Forecast inputs incorporated REACH registration completion timelines, MEE emission standard enforcement intensity, and semiconductor node advancement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese petrochemical conglomerates or accelerated fluorosurfactant reformulation campaigns would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Inhibited Propylene Glycol Market
Additives
Global Lubricating Oil Additives Market
Additives
Tackifier Market
Additives
Global Ester Gum Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
Global Slip Additives Market
Additives
Agrochemicals Additives Market
Additives
Extruded Inclusions Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Hexyl Acetate Market
Additives
North America Fuel Additives Market
Additives
Global Silica-Based Matting Agents Market
Additives
Inorganic Filler Market
Additives
Lactic Acid Ester Market
Additives
Liquid Silage Additive Market
Additives
Ethoxyquin Market