
 Polyurea Market | 2026-2036
Polyurea Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurea Market Analysis
Asset-light leasing models for spray-application equipment is fragmenting competitive access across the polyurea value chain. PPG Industries leverages its distribution breadth to sustain contractor loyalty in protective coatings. Huntsman Corporation anchors its position through captive isocyanate supply. Rhino Linings Corporation specializes in mobile application systems that reduce customer capital barriers.
Polyurea denotes a thermoset elastomer formed by reaction of an isocyanate component with a synthetic resin blend through step-growth polymerization, yielding coatings with gel times under six seconds and tensile strength exceeding 2,500 psi. Spray coatings dominate volume throughput due to their speed on large-area infrastructure jobs, while pure polyurea formulations command premium positioning where chemical resistance specifications are non-negotiable. Hybrid polyurea segments are gaining fastest in flooring as cost-sensitive buyers accept modest performance trade-offs.
EPA regulations on volatile organic compound emissions constrain solvent-based alternatives and redirect specification toward compliant polyurea systems. OSHA workplace exposure limits for isocyanates shape application protocols and personal protective equipment requirements on job sites. REACH registration obligations in Europe filter non-compliant imports and consolidate supplier bases. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation fragmentation that erodes manufacturing scale economics.
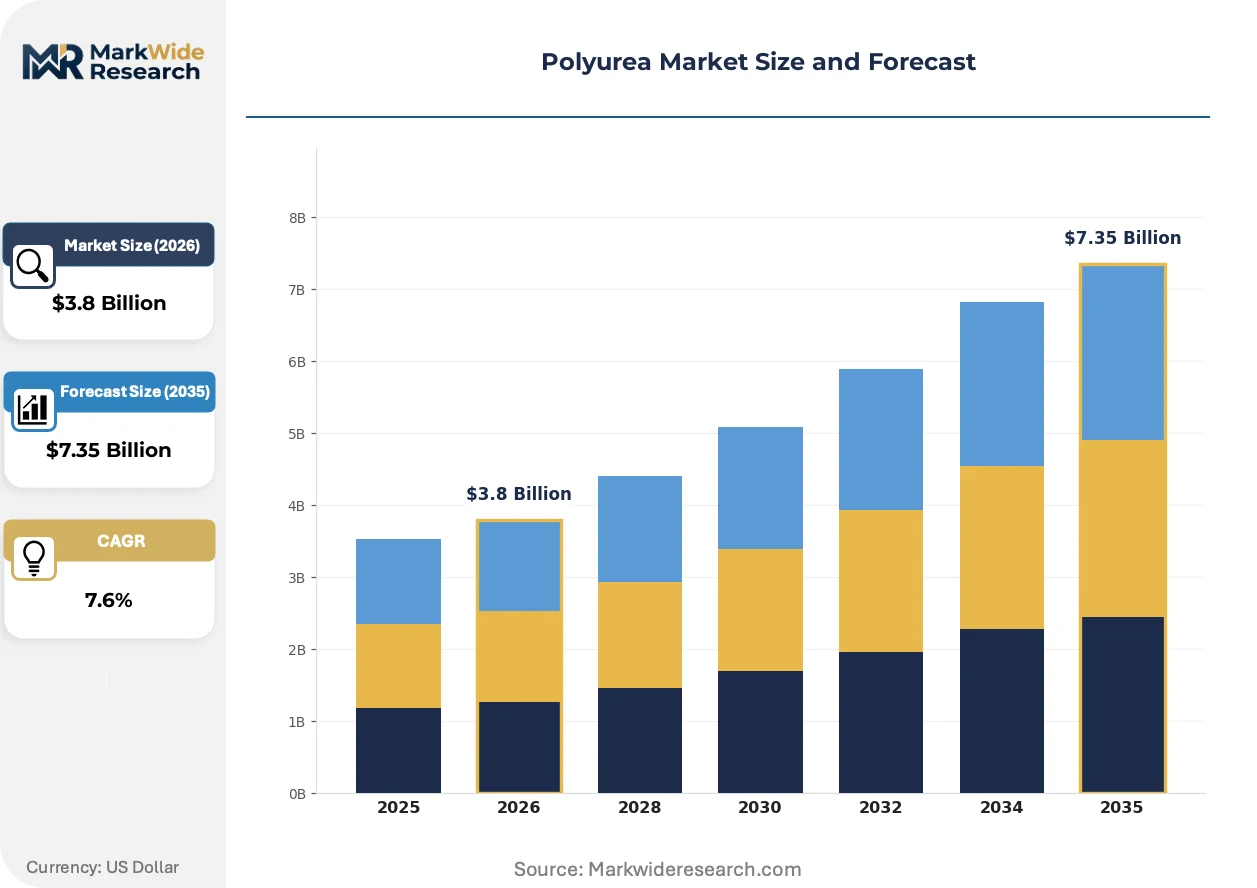
Market Dynamics
Waterproofing demand from commercial infrastructure renewal is compressing project timelines and favoring spray-applied systems with sub-60-second cure times. EPA VOC regulations and OSHA isocyanate exposure limits are simultaneously constraining formulation choices and reshaping contractor certification requirements.
Growth Catalysts
- Infrastructure Stimulus Programs:Federal highway and bridge rehabilitation allocations in the United States are accelerating coating procurement for expansion joint and deck sealing applications.
- REACH Compliance Thresholds:European registration obligations for isocyanate-containing formulations are filtering non-compliant imports and consolidating specification authority among pre-registered suppliers.
- Hybrid Formulation Advances:Cost-optimized polyurea-urethane hybrids are penetrating flooring segments where buyers accept modest elongation trade-offs for 15-20% material cost reduction.
Market Restraints
- MDI Supply Concentration:Isocyanate feedstock production clusters in the US Gulf Coast and Northeast China create geographic vulnerability to weather-related supply interruptions.
- Capital Intensity:Mobile spray rigs and plural-component proportioning equipment require $45,000-$120,000 upfront investment, limiting contractor entry in developing markets.
- Substitution Pressure:Epoxy and polyurethane cement systems retain specification share in secondary containment and industrial flooring where chemical resistance demands are moderate.
Strategic Opportunities
- Secondary Containment in Chemical Processing:EPA Spill Prevention, Control, and Countermeasure rule updates are mandating impermeable liner systems for above-ground tank farms.
- Rental Equipment Channels:Asset-light leasing models for Graco and Gusmer spray rigs are reducing customer capital barriers and expanding addressable contractor bases.
- Marine Coating Convergence:Combination polyurea-epoxy systems are penetrating ship deck and offshore platform applications where corrosion-under-insulation protection is critical.
Industry Challenges
- Certification Bottlenecks:SSPC and NACE coating inspector credentials require 2-3 year experience accumulation, constraining qualified applicator availability for complex infrastructure jobs.
- Formulation Fragmentation:Divergent VOC limits between California Air Resources Board, Ozone Transport Commission states, and federal EPA thresholds force multi-SKU production runs that erode manufacturing scale economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurea Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray Coatings, Liquid Coatings, Roll Coatings, Pre-Polymer Technology: Pure Polyurea, Hybrid Polyurea, Modified Polyurea, Aromatic Polyurea Application: Waterproofing, Flooring, Joint Fillers, Protective Coatings End User: Construction, Automotive, Marine, Industrial |
| Companies Covered | BASF SE, PPG Industries, Inc., The Sherwin-Williams Company, Covestro AG, Sika AG, Huntsman Corporation, Rhino Linings Corporation, LINE-X Protective Coatings, Nukote Coating Systems International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurea Market Emerging Trajectories
Formulation chemistry is converging with application robotics and real-time cure monitoring to compress project timelines and reduce material waste. Three developments are restructuring competitive positioning.
Aliphatic polyurea topcoats are hybridizing with conventional aromatic base coats to deliver color-stable finishes for architectural and transportation applications. Automotive OEMs and mass transit authorities are specifying these systems for exterior equipment housings and railcar underbodies. This hybridizing architecture is collapsing the traditional separation between protective and aesthetic coating tiers.
EPA National Emission Standards for Hazardous Air Pollutants for surface coating operations are tightening permissible isocyanate emissions from spray application booths. Industrial finishers in Ohio, Texas, and Michigan are retrofitting ventilation and thermal oxidizer systems to maintain operating permits. High-volume infrastructure contractors are migrating toward low-pressure plural-component equipment to reduce overspray and airborne concentrations.
Facility owners are unbundling material supply from installation labor and soliciting separate bids for polyurea membrane systems. General contractors on commercial roofing and parking structure projects are awarding standalone material procurement contracts to distributors with stocking locations near job sites. This disaggregation is most pronounced in Texas, Florida, and California where project density supports regional distributor competition.
Polyurea Market Segmentation
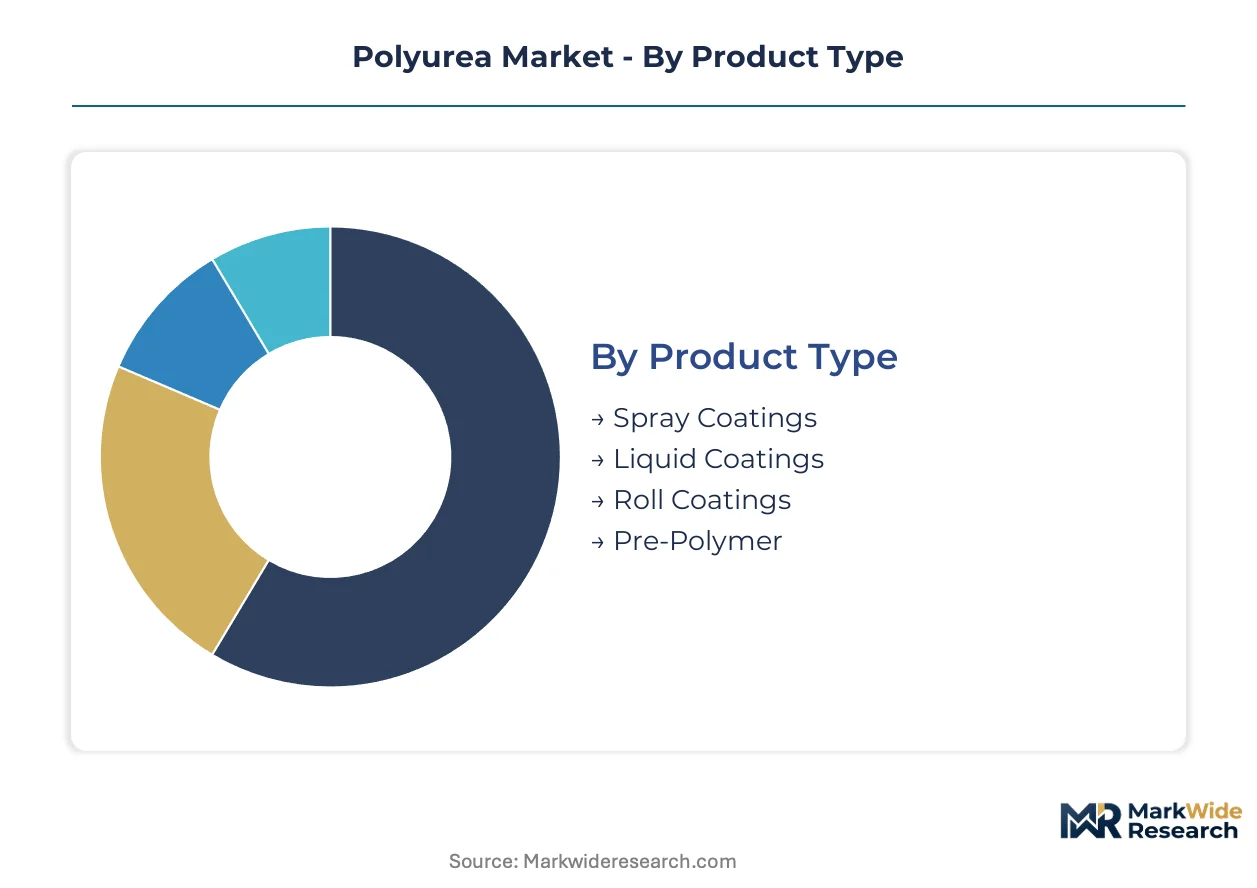
Polyurea market segmentation reveals how formulation chemistry, application method, and end-use requirements create distinct value tiers. Specification engineers select systems based on cure speed demands, chemical exposure profiles, and capital equipment constraints.
Product Type:
Application method determines labor productivity, equipment investment thresholds, and surface geometry accessibility across infrastructure projects.
- Spray Coatings:Plural-component systems deliver sub-60-second gel times through heated proportioning equipment. Bridge deck waterproofing in the United States and highway expansion joint sealing in Germany concentrate procurement volume here, driven by compressed construction windows and EPA VOC compliance mandates.
- Liquid Coatings:Brush or roller-applied formulations suit confined spaces and detail work where overspray control is critical. Secondary containment lining in Texas chemical processing facilities and tank farm refurbishment in Louisiana anchor demand, constrained by longer cure cycles that extend project timelines.
- Roll Coatings:Factory-applied systems bond to prepared substrates under controlled conditions. Prefabricated membrane panels for commercial roofing in Florida and parking structure decks in California utilize this format, limited by field seam integrity requirements.
- Pre-Polymer:Partially reacted resin systems extend pot life for manual application in ambient conditions. Small-scale repair work and maintenance coating in developing markets favor this format, trading performance specifications for logistical simplicity.
Established volume favors Spray Coatings; emerging adoption favors Pre-Polymer.
Technology:
Raw material chemistry stratifies performance guarantees, color stability, and formulation cost structures.
- Pure Polyurea:Systems containing only amine-terminated resin and isocyanate components achieve tensile strength exceeding 2,500 psi with zero VOC content. Chemical processing secondary containment in Texas and offshore platform corrosion protection in the North Sea specify these systems where failure tolerance is zero, despite 20-30% cost premiums over hybrid alternatives.
- Hybrid Polyurea:Polyurethane-modified formulations incorporate polyol components to reduce raw material costs. Industrial flooring in cost-sensitive commercial construction across China and warehouse facilities in Mexico represent the steepest expansion trajectory, accepting modest elongation trade-offs for material savings.
- Modified Polyurea:Additive-enhanced systems target specific performance vectors like UV resistance or thermal stability. Mass transit exterior equipment housings and railcar underbodies in automotive OEM specifications utilize these formulations.
- Aromatic Polyurea:Cost-optimized systems using aromatic isocyanates discolor under UV exposure but retain mechanical properties. Concealed infrastructure applications—tunnel linings, buried pipelines, and sub-grade waterproofing—absorb this volume.
Specification authority concentrates in Pure Polyurea; volume growth concentrates in Hybrid Polyurea.
Application:
Functional performance requirements dictate membrane thickness, surface preparation standards, and warranty terms.
- Waterproofing:Below-grade and exposed membrane systems prevent moisture ingress in building envelopes. Commercial construction in the United States and infrastructure renewal in Germany drive procurement, with EPA stormwater regulations mandating impermeable designs for parking structures and plaza decks.
- Flooring:High-build seamless systems withstand mechanical abrasion and chemical spill exposure. Food processing facilities in California and pharmaceutical manufacturing in New Jersey specify these surfaces, constrained by OSHA slip-resistance requirements and FDA sanitation protocols.
- Joint Fillers:Elastomeric sealants accommodate structural movement in concrete and steel assemblies. Highway expansion joints and airport runway repairs in Texas and Florida utilize rapid-cure formulations to minimize traffic disruption.
- Protective Coatings:Barrier systems prevent substrate corrosion or chemical attack. Marine vessel ballast tanks and industrial equipment housings in Louisiana and Houston anchor demand, with salt spray exposure dictating aliphatic topcoat specifications.
Project density favors Waterproofing; specification complexity favors Protective Coatings.
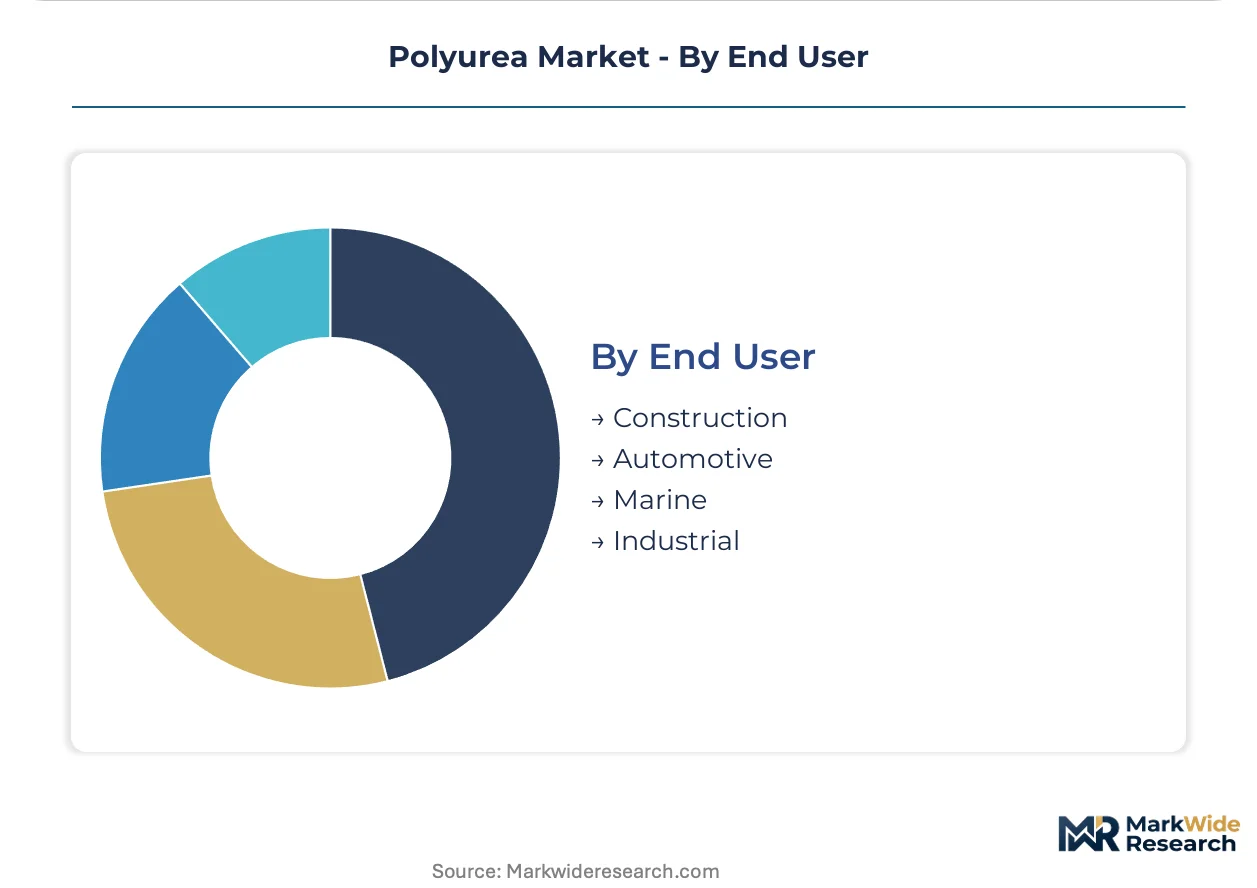
End User:
Capital deployment cycles, regulatory exposure, and contractor base maturity vary sharply across customer categories.
- Construction:General contractors and specialty waterproofing firms deploy polyurea in commercial roofing, parking structures, and building envelope applications. Federal infrastructure stimulus in the United States and municipal renewal programs in Germany concentrate procurement volume here.
- Automotive:OEMs and tier suppliers specify coatings for underbody protection, bed liners, and exterior equipment housings. Mass transit authorities in Chicago and freight rail operators in Nebraska represent emerging specification sources.
- Marine:Shipyards and offshore platform operators demand corrosion-under-insulation protection and deck surfacing. Gulf Coast fabrication yards in Texas and Louisiana and North Sea platform operators in Norway drive technology requirements.
- Industrial:Chemical processors, power generation facilities, and manufacturing plants specify secondary containment and equipment protection. EPA Spill Prevention, Control, and Countermeasure rule enforcement in Ohio and Texas accelerates tank farm lining procurement.
Procurement scale favors Construction; specification technicality favors Industrial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infrastructure stimulus programs and chemical processing regulations are redirecting polyurea procurement toward jurisdictions with enforceable coating standards and active construction pipelines.
United States
Federal highway rehabilitation allocations and EPA stormwater mandates are accelerating bridge deck waterproofing contracts. OSHA isocyanate exposure protocols shape contractor certification requirements across job sites. The Gulf Coast chemical corridor in Texas and Louisiana concentrates secondary containment lining demand from tank farm operators.
China
Municipal infrastructure renewal and industrial flooring expansion in manufacturing hubs are driving spray coating volume. MEE enforcement of VOC limits in the Yangtze River Delta is filtering non-compliant formulation imports. The Pearl River Delta manufacturing cluster absorbs hybrid polyurea systems for cost-sensitive warehouse applications.
Germany
REACH registration obligations for isocyanate-containing formulations are consolidating specification authority among pre-registered suppliers. Federal transport infrastructure budgets support highway expansion joint sealing programs. The Ruhr industrial region and Bavarian chemical processing belt anchor protective coatings procurement.
India
Commercial construction growth in pharmaceutical and food processing facilities is creating waterproofing and flooring demand. BIS standards for construction chemicals are gradually formalizing quality thresholds for imported systems. The Maharashtra-Gujarat industrial corridor and Bangalore-Telangana pharma clusters represent emerging specification sources.
Brazil
Mining infrastructure investment and agricultural processing facility construction are generating protective coatings demand. ANVISA sanitation protocols for food contact surfaces influence flooring system selection in meat and grain processing plants. The São Paulo-Minas Gerais industrial axis concentrates contractor capacity and distributor networks.
Polyurea Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct access routes to end users. The vendor base stratifies between integrated chemical conglomerates with captive resin supply and application-focused specialists with equipment-leasing capabilities. Two dominant archetypes emerge: formulation-scale players leveraging backward integration into isocyanate production, and service-model players reducing customer capital barriers through mobile application systems. Competitive moves concentrate on distribution network expansion and asset-light equipment financing programs.
Among formulation-scale players, BASF SE and Covestro AG exemplify the integrated chemical archetype with upstream control over core resin inputs. Huntsman Corporation occupies a parallel position through captive MDI supply chains. These three entities anchor the supply-side structure by controlling feedstock access that constrains competitor formulation flexibility.
| Leading Market Players |
|---|
| BASF SE |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Covestro AG |
| Sika AG |
| Huntsman Corporation |
| Rhino Linings Corporation |
| LINE-X Protective Coatings |
| Nukote Coating Systems International |
| Others |
Supply Flow & Price Mechanics
The Houston-Rotterdam chemical shipping corridor carries MDI feedstock costs that cascade through formulation pricing, concentrating margin pressure on non-integrated compounders while rewarding captive isocyanate producers with pricing power across specification tiers.
Pricing Analysis
Certification level creates the primary spread between specification tiers, with SSPC-QP8 accredited applicators commanding 15-25% premiums over uncertified competitors. Three-tier pricing structure across premium pure polyurea, standard hybrid formulations, and economy pre-polymer systems reflects performance guarantee differentiation. Cost compression in hybrid segments is intensifying because Chinese manufacturers are expanding Pearl River Delta capacity. Commercial construction contractors exhibit highest price sensitivity, while chemical processors in Texas and Louisiana prioritize failure tolerance over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for aromatic isocyanate imports. MDI production concentrates in the US Gulf Coast, Northeast China, and the Antwerp-Rotterdam chemical cluster. Raw material portfolios draw from aniline, formaldehyde, and propylene oxide feedstocks. Single-source vulnerability persists for specialty amine-terminated resins used in aliphatic topcoats. Distribution runs through regional stocking distributors with spray rig leasing capabilities in Texas, Florida, and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyurea incumbents face substitution pressure from fast-cure polyurethane cement systems in industrial flooring, requiring active defense of specification authority in chemical containment applications.
For Market Incumbents: Harden certification control by acquiring SSPC-QP8 training providers to constrain qualified applicator supply. Deepen captive isocyanate positions through long-term offtake agreements with MDI producers in the US Gulf Coast. Defend against epoxy-urethane hybrid substitutes by embedding polyurea in EPA SPCC rule compliance documentation for tank farm operators. For New Entrants and Emerging Players: India's Maharashtra-Gujarat industrial corridor offers the most penetrable geography, with BIS standards still formalizing and local applicator certification scarce. Target pharmaceutical manufacturing flooring in Bangalore-Telangana clusters where FDA sanitation protocols favor seamless systems. Enter through asset-light equipment leasing partnerships with Graco distributors to bypass capital barriers. For Investors and Strategic Acquirers: REACH registration deadlines for isocyanate-containing formulations reshape the acquisition landscape by filtering non-compliant imports and consolidating specification authority. Five-to-ten year viability favors integrated compounders with captive resin supply or application specialists with mobile equipment fleets. Monitor EPA National Emission Standards enforcement in Ohio, Texas, and Michigan as inflection indicator for ventilation retrofit demand and low-pressure equipment migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Feedstock | Captive isocyanate supply insulates Huntsman and BASF from Gulf Coast weather disruptions. |
| SSPC-QP8 Certification Program Expansion | Qualified applicator scarcity in infrastructure projects sustains contractor pricing power. |
| Low-Pressure Plural-Component Equipment Launch | Graco and Gusmer systems reduce overspray to meet EPA NESHAP emission thresholds. |
| Regional Distributor Stocking Network | Texas and Florida stocking locations capture unbundled material procurement contracts. |
| Hybrid Polyurea-Urethane Formulation Development | Cost-optimized systems penetrate Chinese warehouse flooring with 15-20% material savings. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with spray application contractors, chemical procurement managers at downstream processors, SSPC certification directors, and regional distribution heads; and secondary validation through customs trade data, EPA enforcement records, SEC 10-K chemical segment disclosures, and REACH registration databases. Bottom-up triangulation against top-down macroeconomic indicators anchored volume and value estimates.
Forecast inputs span formulation chemistry tiers, application method equipment requirements, end-use regulatory exposure, and regional infrastructure stimulus intensity across the projection horizon. Modeled segmentation dimensions include pure-hybrid-modified technology tiers, spray-liquid-roll application formats, and construction-industrial-marine end-user categories. CAGRs derive from elasticity-adjusted demand curves incorporating VOC compliance cost pass-through and isocyanate supply concentration effects.
Practitioners should monitor MDI production disruption events, EPA NESHAP enforcement acceleration, and REACH registration deadline compliance rates for early signals warranting forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
High Performance Foam Market
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Propoxylates Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Saudi Arabia Masterbatch Market
Specialty Compounds
Carbon Black for Packaging Market
Specialty Compounds
India Sealants Market
Specialty Compounds
Global Quaternary Ammonium Compounds Market
Specialty Compounds
Specialty Sorbents Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Thioglycolate Market
Specialty Compounds
Lithopone Market