
 Stannous Chloride Market | 2026-2036
Stannous Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Stannous Chloride Market Analytics
The capital-intensity gap between integrated tin smelters and merchant chemical producers is collapsing as energy and environmental compliance costs equalize. Yunnan Tin Group leverages captive tin concentrate access to sustain cost leadership across powder and solution grades. Showa Kako Corporation anchors its position through pharmaceutical-grade specialization, competing on purity certification rather than volume scale.
Stannous chloride is a tin(II) chloride compound, typically supplied as anhydrous crystals or dihydrate solid, functioning as a reducing agent, catalyst precursor, and tin-plating bath constituent across industrial processes. The powder segment dominates volume due to its use in electroplating fluxes and dye mordants, while solution grades command margin premiums in pharmaceutical and high-purity electronics applications. Electronics-oriented demand for ultra-high-purity grades is expanding fastest as semiconductor packaging shifts toward lead-free solder systems.
REACH registration requirements in Europe and China's GB standards under SAMR enforcement are elevating analytical documentation burdens for importers and domestic producers alike. EPA hazardous substance reporting in the United States adds parallel compliance layers for water treatment and agricultural formulations. Stakeholders must monitor how evolving tin supply chain due-diligence rules intersect with carbon border mechanisms to reshape sourcing economics and qualification timelines.
Market Dynamics
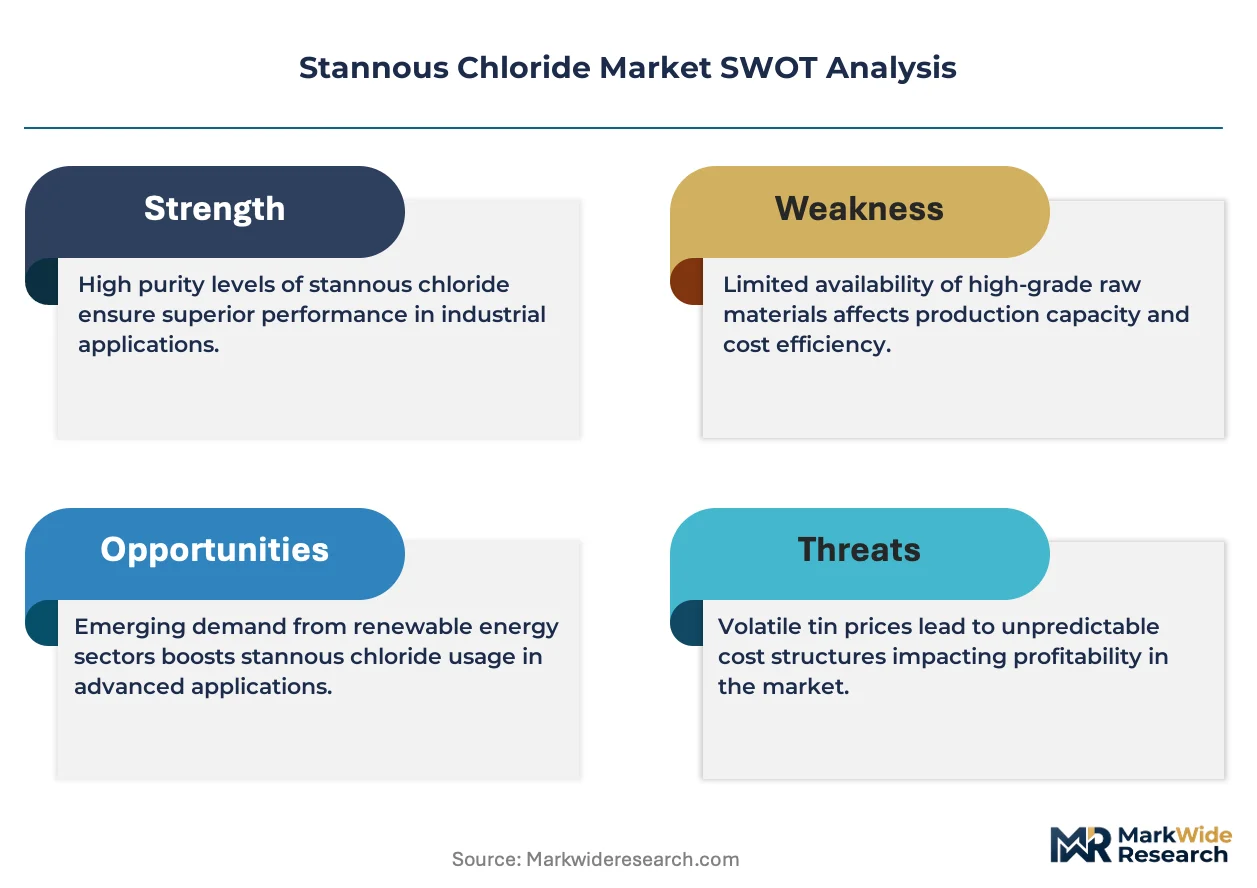
Electronics packaging migration toward lead-free solder systems is compressing qualification timelines for ultra-high-purity stannous chloride grades, forcing suppliers to synchronize analytical documentation with semiconductor OEM audit cycles.
Growth Catalysts
- REACH registration tiers:ECHA's substance evaluation protocols in Europe are filtering out non-compliant traders, concentrating volume among qualified chemical processors with full analytical dossiers.
- Semiconductor substrate metallization:Advanced packaging architectures for AI accelerators require tin-based barrier layers with sub-ppm metallic impurity ceilings, pulling pharmaceutical-grade specifications into electronics.
- Yunnan-Tin Smelter corridor:Co-location of chlor-alkali chlorine supply with tin concentrate refining in southwestern China sustains integrated cost structures unavailable to merchant producers elsewhere.
Market Restraints
- Tin concentrate supply concentration:Indonesian export licensing volatility and Myanmar ore access disruptions expose non-integrated processors to raw material rationing.
- Energy cost equalization:Carbon border adjustment mechanisms in Europe and China's dual carbon goals are eroding the historical power-cost advantage of coal-dependent chlor-alkali operations.
- Organotin substitution in agriculture:Triphenyltin-based fungicides face progressive withdrawal under EU F-Gas and biocidal product regulations, eliminating a legacy outlet for stannous chloride-derived intermediates.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for semiconductor and component manufacturing are attracting tin chemical suppliers to establish analytical laboratories near Gujarat and Tamil Nadu fabrication clusters.
- Closed-loop tin recovery:Urban mining partnerships with printed circuit board recyclers in South Korea and Taiwan offer captive concentrate streams decoupled from primary mining geopolitics.
- Pharmaceutical-grade export arbitrage:GMP-certified producers in Japan and Switzerland can access premium pricing in Southeast Asian generic API manufacturing where local purity capabilities remain underdeveloped.
Industry Challenges
- ICP-MS analytical capacity scarcity:Semiconductor OEMs now require 99.999% grade certification with full elemental impurity profiling, stretching third-party laboratory turnaround times beyond contract negotiation windows.
- Dual-use export control alignment:Stannous chloride's application in tin-based chemical weapon precursors triggers additional licensing layers under national strategic goods regulations, complicating cross-border shipment documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stannous Chloride Market |
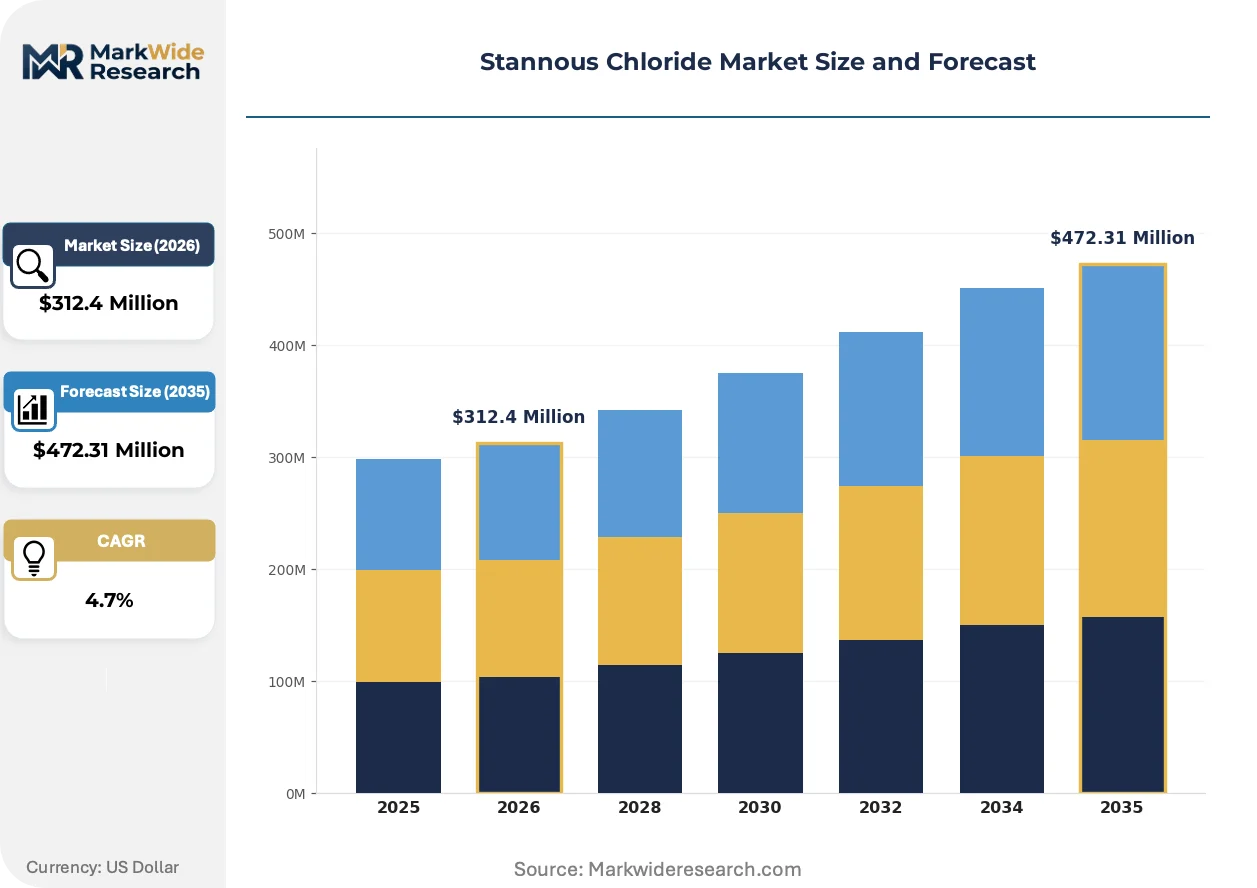
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Solution, Tablets Application: Food Preservation, Water Treatment, Pigment Production, Electronics End User: Chemical Industry, Pharmaceuticals, Agriculture, Manufacturing Purity Grade: 99%, 98%, 95%, Others |
| Companies Covered | Yunnan Tin Group, Mason Corporation, ACIMA Specialty Chemicals, Showa America, Showa Kako Corporation, Liuzhou China Tin Group Co., Ltd., TIB Chemicals, GFS Chemicals, William Blythe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stannous Chloride Market Evolving Landscape
Vapor-phase deposition chemistries and closed-loop water treatment systems are converging to redefine purity benchmarks and environmental performance expectations across stannous chloride applications.
Spray pyrolysis precursors for transparent conductive oxide coatings are decomposing traditional liquid-phase plating demand in display manufacturing. Panel fabricators in South Korea have adopted aerosol delivery systems for indium tin oxide alternatives, compressing solution-grade volume requirements while elevating anhydrous powder specifications for precursor synthesis.
China's GB standards under SAMR enforcement are mandating real-time effluent monitoring for tin-plating operations, compelling bath chemical suppliers to reformulate additive packages. Yangtze River Delta electroplating clusters are retrofitting centralized waste treatment infrastructure, favoring stannous chloride vendors with documented environmental management system certifications.
Consolidated procurement through semiconductor chemical management firms is displacing direct mill relationships for mid-tier electronics manufacturers. Large Taiwan-based foundries now delegate stannous chloride qualification and inventory management to specialized chemical logistics providers, compressing supplier bases to three or four approved global sources per manufacturing node.
Stannous Chloride Market Segmentation
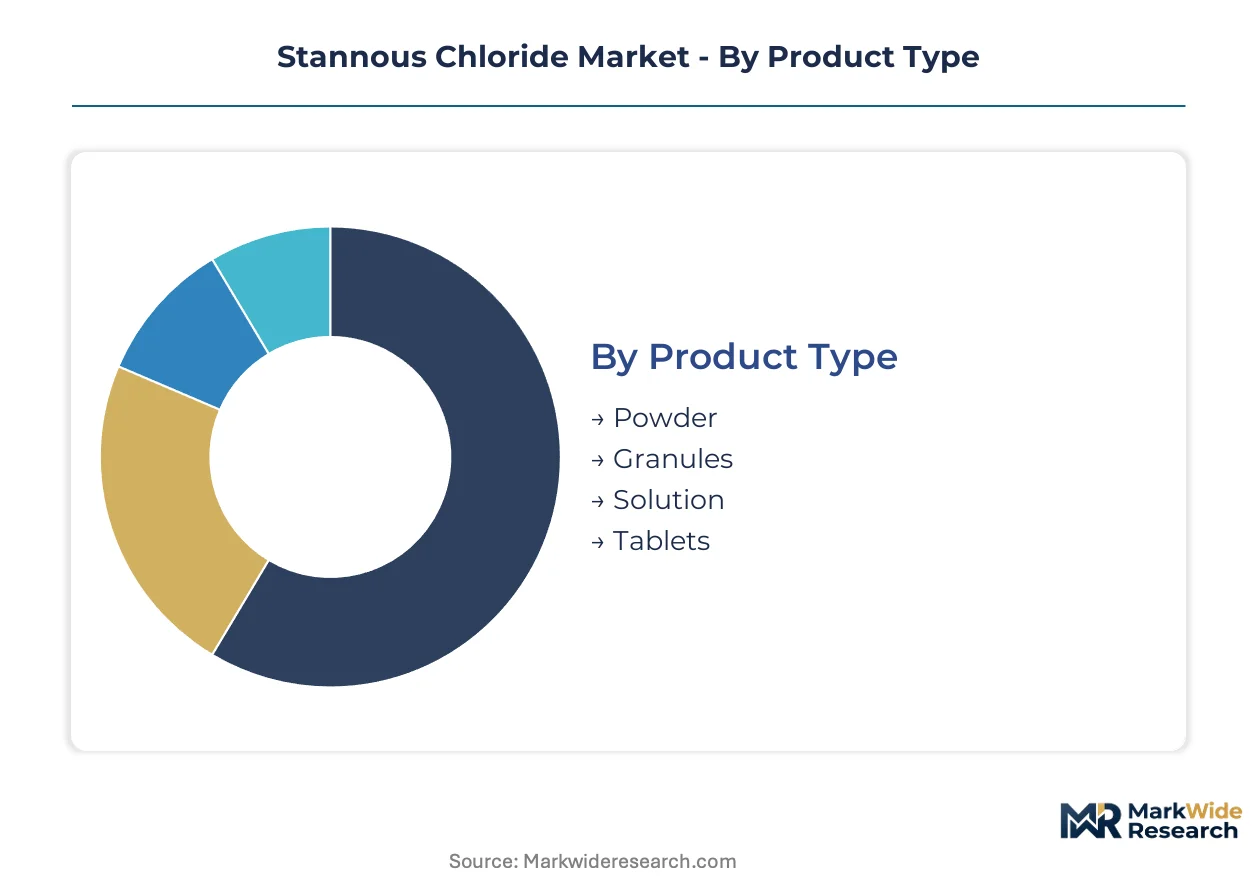
Stannous chloride procurement channels diverge sharply by physical form and purity threshold, with electroplating distributors handling commodity powder while semiconductor chemical management firms gatekeep ultra-high-purity solutions. Understanding these channel boundaries illuminates where margin extraction concentrates versus where volume flows.
Product Type:
Powder and granule grades move through industrial chemical distributors serving electroplating clusters, while solution and tablet forms require pharmaceutical or electronics-qualified channels with documented cold-chain or analytical capabilities.
- Powder:Anhydrous or dihydrate crystalline forms serve as reducing agents in tin-plating baths and dye mordants. Demand concentrates in China's Yangtze River Delta electroplating clusters, where SAMR-mandated effluent monitoring is forcing bath reformulation toward higher-purity grades.
- Solution:Aqueous preparations with precise tin(II) concentration for pharmaceutical reducing applications and semiconductor barrier-layer deposition. Electronics chemical management firms in Taiwan and South Korea now control procurement for advanced packaging nodes, compressing supplier bases to three or four approved sources.
- Granules:Coarse particulate form for controlled-release agricultural applications and water treatment systems. EPA hazardous substance reporting requirements in the United States shape distributor qualification protocols.
- Tablets:Compressed solid dosage form for laboratory reagent standards and specialized pharmaceutical synthesis. Swissmedic and PMDA certification requirements govern import channels into Switzerland and Japan.
Powder dominates installed base. Solution is where expansion concentrates.
Application:
Cost tier stratification separates commodity water treatment from premium electronics applications, with purity certification costs determining viable supplier participation.
- Electronics:Ultra-high-purity grades for lead-free solder precursors and semiconductor packaging metallization. AI accelerator substrate manufacturing in South Korea and Taiwan is pulling pharmaceutical-grade specifications into electronics with sub-ppm metallic impurity ceilings.
- Water Treatment:Stannous chloride reduces hexavalent chromium in industrial effluent streams. China's MEE enforcement of real-time monitoring in Yangtze River Delta plating clusters sustains steady demand for technical-grade powder.
- Food Preservation:Antioxidant applications in canned goods packaging face regulatory pressure from EFSA and FDA alternative assessments, compressing formulation flexibility.
- Pigment Production:Tin-based ceramic colorants for glazes and coatings. REACH registration tiers in Europe filter out non-compliant traders, concentrating supply among qualified chemical processors.
Water treatment anchors volume stability. Electronics commands the steepest expansion trajectory.
End User:
Customer type determines contract structure, with chemical industry spot purchasing contrasting pharmaceutical long-term supply agreements tied to audit cycles.
- Chemical Industry:Merchant producers and electroplating compounders purchasing technical grades on spot or quarterly contracts. Indonesian export licensing volatility exposes non-integrated processors to raw material rationing.
- Pharmaceuticals:API manufacturers requiring GMP-certified reducing agents with full elemental impurity profiling. ICP-MS analytical capacity scarcity stretches third-party laboratory turnaround times beyond contract negotiation windows.
- Manufacturing:Electronics OEMs and component fabricators qualifying stannous chloride through semiconductor chemical management firms. India's PLI scheme for electronics is attracting tin chemical suppliers to establish analytical laboratories near Gujarat and Tamil Nadu clusters.
- Agriculture:Legacy outlet for triphenyltin-derived fungicides facing progressive withdrawal under EU F-Gas and biocidal product regulations.
Chemical industry holds broadest supplier relationships. Pharmaceuticals is where margin premiums concentrate.
Purity Grade:
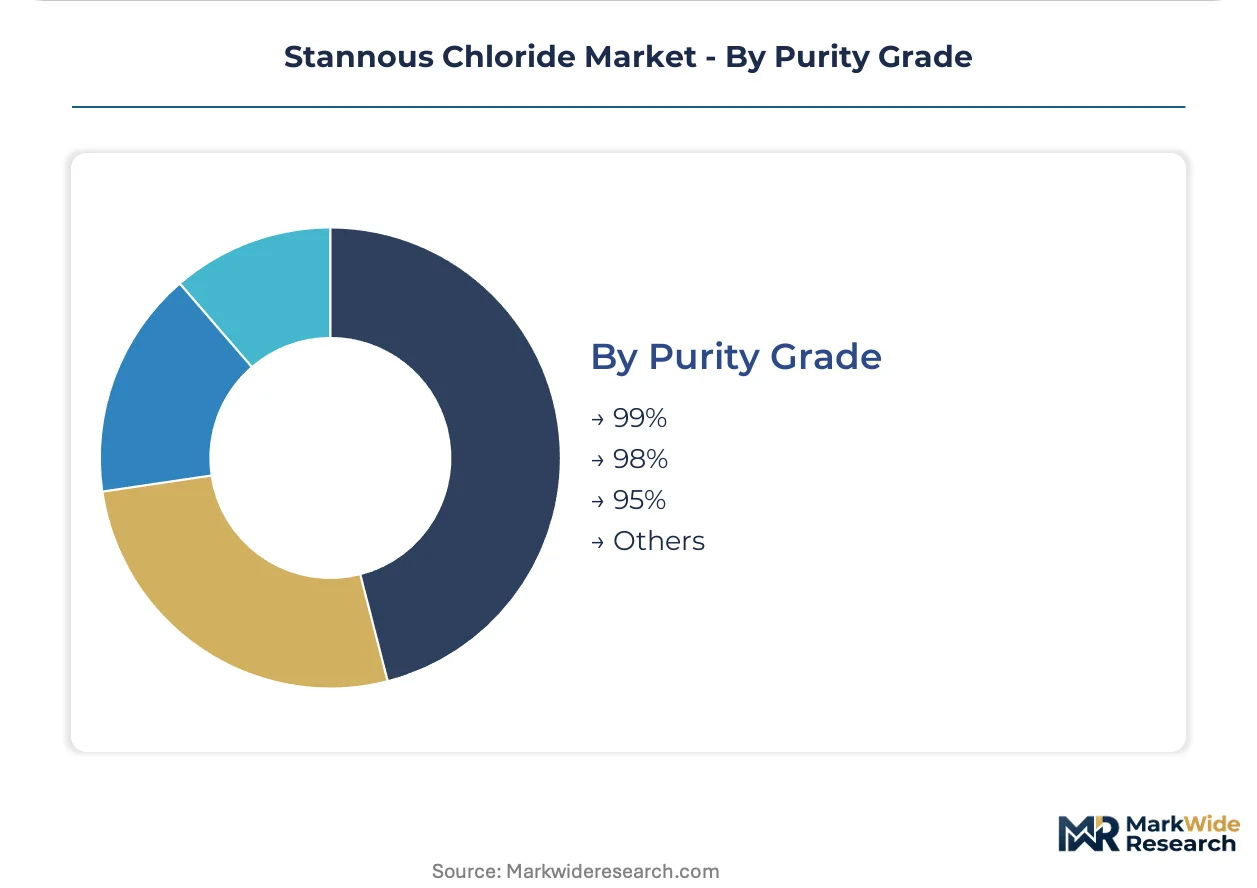
Grade stratification directly maps to end-use qualification requirements, with 99% and 98% tiers separated by analytical documentation burdens rather than production cost alone.
- 99%:Ultra-high-purity grade for semiconductor packaging and pharmaceutical synthesis. Closed-loop tin recovery partnerships with printed circuit board recyclers in South Korea and Taiwan offer captive concentrate streams decoupled from primary mining geopolitics.
- 98%:High-purity grade for electronics plating and specialty chemical synthesis. Carbon border adjustment mechanisms in Europe and China's dual carbon goals are eroding historical power-cost advantages for coal-dependent chlor-alkali operations producing this tier.
- 95%:Technical grade for water treatment and pigment applications. Yunnan Tin Group's captive tin concentrate access sustains cost leadership unavailable to merchant producers elsewhere.
- Others:Custom specifications for research institutions and niche industrial processes. Dual-use export control alignment for tin-based chemical weapon precursors triggers additional licensing layers under national strategic goods regulations.
98% purity anchors mid-market volume. 99% purity is where supplier qualification barriers concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's electroplating clusters exhibit acute price sensitivity to energy and tin concentrate costs, while semiconductor chemical management firms in Taiwan and South Korea absorb substantial purity premiums without volume elasticity.
China
Yangtze River Delta electroplating clusters consume technical-grade powder for tin-plating baths while SAMR-enforced GB standards mandate real-time effluent monitoring. The dual carbon goals are accelerating chlor-alkali plant retrofits in Jiangsu and Zhejiang provinces. Yunnan Tin Group leverages captive concentrate access in southwestern China to sustain integrated cost structures unavailable to merchant producers.
South Korea
AI accelerator substrate manufacturing pulls pharmaceutical-grade specifications into electronics with sub-ppm metallic impurity ceilings. MFDS certification requirements govern pharmaceutical-grade imports while semiconductor OEMs delegate procurement to chemical management firms. Seoul Capital Area foundries compress supplier bases to three or four approved global sources per manufacturing node.
Japan
PMDA-certified producers command premium pricing in Southeast Asian generic API manufacturing where local purity capabilities remain underdeveloped. METI oversight of strategic goods regulations adds licensing layers for tin-based chemical precursors. Osaka-based chemical specialists anchor high-purity solution production for domestic pharmaceutical and electronics sectors.
United States
EPA hazardous substance reporting shapes distributor qualification protocols for water treatment and agricultural formulations. Electronics OEMs in Texas and Arizona rely on imported ultra-high-purity grades as domestic ICP-MS analytical capacity scarcity stretches certification timelines. Closed-loop tin recovery partnerships with printed circuit board recyclers offer concentrate streams decoupled from primary mining geopolitics.
Germany
REACH registration tiers filter out non-compliant traders, concentrating volume among qualified chemical processors with full analytical dossiers. ECHA substance evaluation protocols elevate analytical documentation burdens for importers and domestic producers. KBA oversight intersects with carbon border adjustment mechanisms to reshape sourcing economics for chlor-alkali-dependent production.
Stannous Chloride Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated tin smelters commanding raw material economics and pharmaceutical-grade specialists capturing purity premiums. The market structure concentrates volume among three to four approved suppliers per semiconductor manufacturing node while fragmenting across electroplating distributors for commodity powder. Strategic archetypes span captive concentrate-integrated producers, GMP-certified pharmaceutical specialists, and regional electroplating chemical distributors. Dominant competitive moves include backward integration into tin concentrate access and portfolio diversification toward closed-loop urban mining partnerships.
Among Asia-Pacific-based integrated producers, Yunnan Tin Group and Liuzhou China Tin Group Co., Ltd. exemplify the captive concentrate archetype, while Showa Kako Corporation occupies a position within the pharmaceutical-grade specialization tier. TIB Chemicals and GFS Chemicals represent regional merchant chemical processors competing on analytical documentation and qualification speed rather than vertical control over raw material inputs.
| Leading Market Players |
|---|
| Yunnan Tin Group |
| Mason Corporation |
| ACIMA Specialty Chemicals |
| Showa America |
| Showa Kako Corporation |
| Liuzhou China Tin Group Co., Ltd. |
| TIB Chemicals |
| GFS Chemicals |
| William Blythe |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Yangtze River Delta electroplating clusters and Yunnan Tin Group lock in both tin concentrate supply access and eighteen-month price visibility, insulating integrated producers from Indonesian export licensing volatility while exposing merchant chemical processors to spot market rationing.
Pricing Analysis
Analytical certification service contracts now drive lifetime value for ultra-high-purity grades, with semiconductor chemical management firms in Taiwan bundling ICP-MS documentation into multi-year supply agreements. Three-tier pricing structure across pharmaceutical-grade, electronics-qualified, and technical-grade levels separates 99% purity solutions commanding substantial premiums from commodity powder. Pricing pressure stems from carbon border adjustment mechanisms eroding historical power-cost advantages for coal-dependent chlor-alkali operations. Water treatment distributors exhibit acute price sensitivity to energy pass-through costs, while semiconductor OEMs absorb purity premiums without volume elasticity.
Supply Chain Analysis
China and Indonesia anchor global tin concentrate supply, with Myanmar ore access disruptions periodically constraining feedstock for non-integrated processors. Chlor-alkali chlorine, tin concentrate, and analytical reagents constitute critical input dependencies. Single-source vulnerability concentrates in Indonesian export licensing corridors. Distribution runs through semiconductor chemical management firms gatekeeping ultra-high-purity solutions, while industrial chemical distributors handle commodity powder for electroplating clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-layer expansion in analytical certification and closed-loop tin recovery outpaces hardware margin growth, reframing stannous chloride procurement as a compliance-anchored recurring revenue opportunity rather than transactional chemical supply.
For Market Incumbents: Secure captive concentrate access through urban mining partnerships with South Korean and Taiwanese printed circuit board recyclers, decoupling supply from primary mining geopolitics. Deepen analytical laboratory footprints near India's Gujarat and Tamil Nadu fabrication clusters before PLI scheme maturation attracts competing qualification capacity. Reinforce GMP certification moats against emerging pharmaceutical-grade specialists in Southeast Asia. For New Entrants and Emerging Players: Cold-chain solution distribution gaps in Southeast Asian generic API manufacturing present immediate white-space opportunity, where local purity capabilities remain underdeveloped and Swissmedic-certified imports command substantial arbitrage. Target analytical laboratory services as the most penetrable entry vector, piggybacking on semiconductor OEM audit cycle compression. Lead with ICP-MS capacity partnerships rather than production scale. For Investors and Strategic Acquirers: GMP-certified pharmaceutical-grade specialists with documented semiconductor qualification pathways represent the priority acquisition archetype, capturing dual-use pricing power across electronics and API synthesis. Long-term viability hinges on carbon-adjusted chlor-alkali positioning and closed-loop concentrate access. Watch Indonesian export licensing volatility as inflection indicator for integrated versus merchant producer valuation spreads.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tin Concentrate | Yunnan Tin Group's captive supply anchors cost leadership unavailable to merchant competitors. |
| ICP-MS Analytical Laboratory Expansion | Taiwan-based chemical management firms compress supplier bases to three approved sources per node. |
| Closed-Loop Urban Mining Partnership | South Korean printed circuit board recyclers offer concentrate streams decoupled from Myanmar ore disruptions. |
| Pharmaceutical-Grade Certification Investment | PMDA and Swissmedic pathways unlock premium pricing in underdeveloped Southeast Asian API markets. |
| Carbon-Adjusted Chlor-Alkali Retrofit | Jiangsu and Zhejiang province dual carbon compliance sustains qualification for European CBAM-exposed exports. |
Research Methodology
A standing panel of chlor-alkali plant managers, semiconductor procurement leads at Taiwan-based foundries, pharmaceutical API manufacturing directors, and electroplating cluster technical supervisors provided ongoing calibration against operational realities. Primary interview findings triangulated with customs trade data, China GB standards enforcement records, SEC 10-K chemical processor filings, and ECHA REACH registration databases. Bottom-up grade-specific volume estimates reconciled against top-down tin consumption models across solder precursor and plating chemical applications.
Consistency checks validated volume and value outputs against chlor-alkali capacity utilization benchmarks and semiconductor packaging material intensity ratios across the analysis window. Segmentation modeling incorporated purity grade tier, end-use industry concentration, physical form factor, and regional regulatory cluster dimensions. CAGRs derived from grade-specific demand elasticity coefficients applied to electronics packaging migration curves and water treatment enforcement trajectories. Tin concentrate supply disruption scenarios and carbon border adjustment phase-in schedules fed sensitivity testing.
Underlying assumptions cover sustained Indonesian export licensing volatility, REACH tier enforcement stability, and semiconductor node migration pacing, with deviation risk concentrated in Myanmar ore access restoration or accelerated organotin substitution in agriculture. Recalibration cycles align with material shifts in SAMR effluent monitoring enforcement, ECHA substance evaluation protocols, and AI accelerator substrate manufacturing ramp rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Silicone Potting Compounds Market
Specialty Compounds
Lauramidopropyl Betaine Market
Specialty Compounds
US Non-Commercial Acrylic Paints Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
N-Propyl Propionate Market
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
Thioglycolate Market
Specialty Compounds
High Performance Foam Market
Specialty Compounds
Middle East and Africa Specialty Chemicals Market
Specialty Compounds
Kokum Butter Market
Specialty Compounds
Chromium Phosphate Market
Specialty Compounds
North America Customized Premixes Market