
 Compounds Market | 2026-2036
Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Compounds Market Outlook
Specialty chemical producers in Germany's Rhine-Ruhr cluster is repositioning global supply chains toward high-performance polymer blends. BASF SE leverages its integrated Verbund site in Ludwigshafen to sustain captive feedstock advantages across organic and inorganic compound lines. Dow, Inc. anchors North American manufacturing scale through Gulf Coast crackers and downstream compounding assets. DuPont de Nemours, Inc. differentiates in healthcare-grade polymer blends where FDA master file requirements create qualification barriers.
Compounds are chemically homogeneous or heterogeneous substances formed by combining two or more elements or molecules through synthesis, blending, or reaction processes, with purity grades ranging from technical to pharmaceutical specification and molecular weights spanning small-molecule APIs to high-MW polymer matrices. Their primary purpose is to serve as functional inputs where precise chemical properties determine end-product performance in downstream manufacturing. Organic compounds lead absolute volume in pharmaceutical applications where API intermediates command formulation premiums, while polymer blends represent the fastest-expanding structural segment as lightweighting mandates in automotive and packaging displace monolithic materials. Inorganic compounds remain a mature margin pool anchored by agricultural and industrial mineral demand with limited pricing power.
EPA toxicity evaluations under TSCA and REACH substance restrictions in Europe are elevating compliance costs for compound importers while creating preference for domestic-certified suppliers. FDA's updated guidance on extractables and leachables for container-closure systems is reshaping qualification protocols for healthcare-grade compounds. ISO 10993 biocompatibility standards and USP Class VI certification now function as de facto market access filters in medical device and pharmaceutical end uses. Stakeholders must monitor regulatory divergence between EPA and ECHA hazard classifications as dual-registration requirements threaten to fragment formulation strategies across Atlantic supply chains.
Market Dynamics
REACH compliance tightening purity thresholds for imported chemical mixtures is forcing reformulation investments across European supply chains while pharmaceutical developers escalate API intermediate specifications.
Growth Catalysts
- Pharmaceutical formulation demand:Drug developers are escalating purity requirements for intermediates used in sterile injectables and biologic containers.
- REACH substance restrictions:ECHA's evolving candidate list is redirecting procurement toward domestic-certified suppliers with verified compliance documentation.
- Lightweighting mandates:Automotive OEMs in Germany's industrial corridor are accelerating polymer blend adoption to meet fleet emission targets.
Market Restraints
- Feedstock volatility:Crude-derived naphtha and natural gas liquids expose margin structures to commodity swings in Gulf Coast cracking economics.
- Supply concentration risk:Captive Verbund production around Ludwigshafen limits third-party access to high-purity organic intermediates at scale.
- Biocompatibility certification barriers:ISO 10993 and USP Class VI timelines extend qualification cycles for healthcare-grade compound entrants.
Strategic Opportunities
- Healthcare-grade polymer expansion:FDA master file requirements create qualification moats for producers with extractables-leachables documentation.
- Dual-registration arbitrage:Divergence between EPA TSCA and ECHA hazard classifications favors suppliers with parallel certification capabilities.
- Container-closure system reformulation:Updated FDA guidance on leachables is opening replacement cycles for legacy pharmaceutical packaging compounds.
Industry Challenges
- Cross-Atlantic formulation fragmentation:Divergent hazard classifications between EPA and ECHA are forcing parallel product lines and duplicated toxicology studies.
- Biocompatibility testing capacity:ISO 10993 and USP Class VI laboratory bottlenecks are extending time-to-market for medical device compound qualifications.
- Legacy system integration:Pharmaceutical compound buyers face ERP reconfiguration costs to track batch-level REACH compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compounds Market |
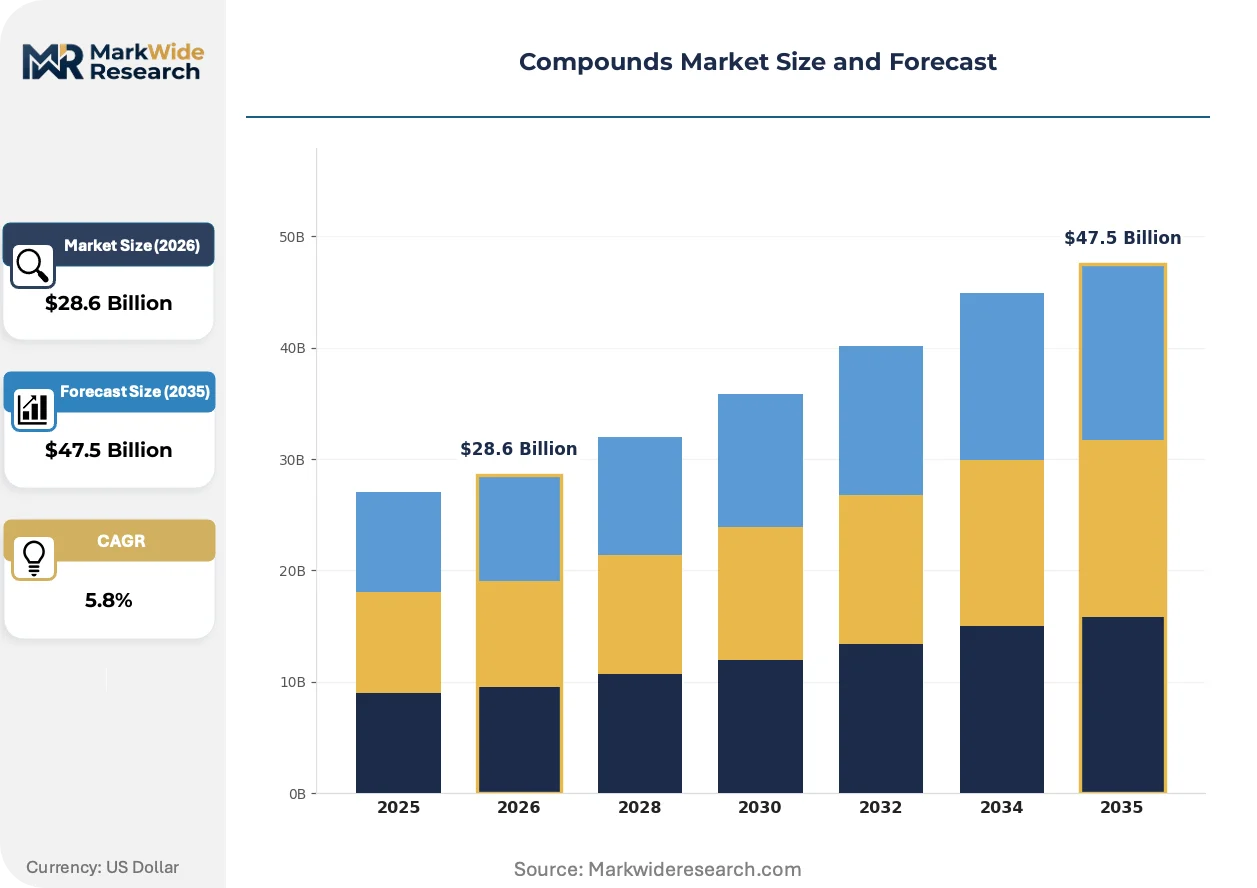
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Compounds, Inorganic Compounds, Polymer Blends, Chemical Mixtures Application: Pharmaceuticals, Agriculture, Food Additives, Cosmetics End Use Industry: Healthcare, Manufacturing, Food Processing, Personal Care Packaging Type: Bottles, Drums, Bags, Pallets |
| Companies Covered | BASF SE, SABIC, Dow, Inc., LyondellBasell Industries Holdings B.V., DuPont de Nemours, Inc., Asahi Kasei Corporation, Covestro AG, KURARAY CO., LTD., RTP Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compounds Market Strategic Shifts
High-performance polymer blends are absorbing formulation complexity as end-users consolidate multi-property requirements into single-material solutions.
Reactive extrusion technology is absorbing compounding steps previously handled through batch synthesis. Automotive tier suppliers in Germany's Rhine-Ruhr cluster are adopting continuous compounding lines to reduce lot-to-lot variability in glass-filled nylon blends. This compression of process steps is absorbing capital that previously flowed to discrete blending equipment.
REACH authorization requirements for Substances of Very High Concern are forcing substitution investments across adhesive and coating compound portfolios. ECHA's 2024-2025 sunset date cluster is compressing reformulation timelines for phthalate-based plasticizers. Medical device manufacturers are accelerating biobased alternative qualifications to preempt supply discontinuities.
Specification-driven procurement is consolidating supplier panels as pharmaceutical and automotive buyers reduce qualified vendor lists. Tier-1 compound distributors are absorbing technical service functions previously performed by manufacturer field teams. This channel consolidation is most visible in Germany's chemical corridor where buyers prioritize suppliers with integrated regulatory documentation capabilities.
Compounds Market Segmentation
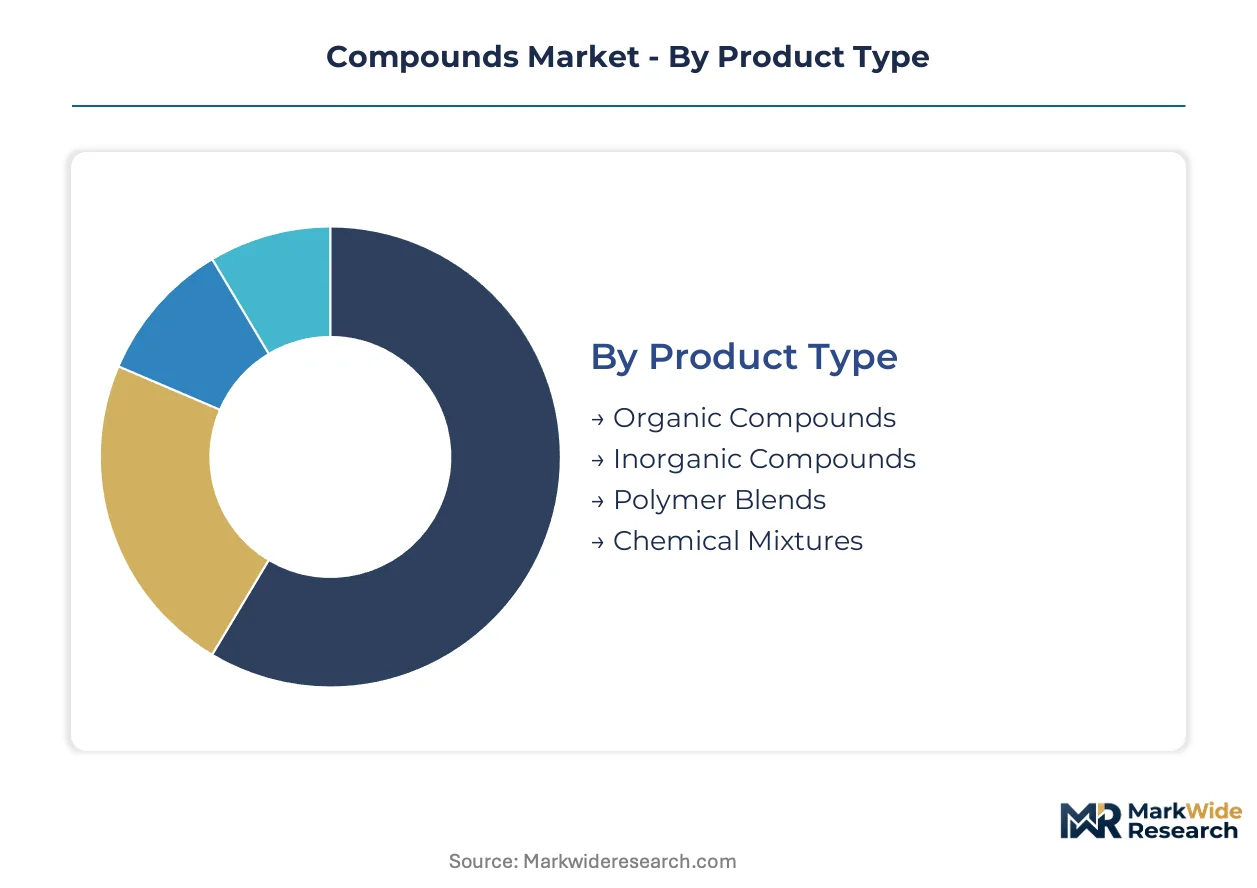
Segmentation in the compounds market reveals how formulation requirements diverge across end-use specifications, regulatory exposure, and supply chain integration depth. Understanding these splits enables suppliers to align certification investments with margin concentration points.
Product Type:
Standalone compound categories serve discrete formulation steps, while embedded blends integrate multiple functional properties into unified material systems.
- Organic Compounds:Carbon-based molecular structures spanning API intermediates, solvents, and reactive monomers with purity grades from technical to pharmaceutical specification. Demand concentrates in sterile injectable formulations where FDA extractables-leachables protocols command premium sourcing from Germany's Ludwigshafen chemical corridor.
- Polymer Blends:Multi-component matrices combining engineering plastics with fillers, impact modifiers, or flame retardants to consolidate mechanical and thermal properties. Automotive OEMs in Germany's Rhine-Ruhr cluster are accelerating adoption to meet fleet lightweighting mandates, absorbing formulation complexity previously handled through multi-material assemblies.
- Inorganic Compounds:Mineral-derived substances including oxides, salts, and acids serving agricultural and industrial mineral demand with mature margin structures.
- Chemical Mixtures:Formulated preparations combining multiple active and inert components for specialized process applications.
Organic compounds lead volumes today; polymer blends are gaining share fastest.
Application:
Application segmentation tracks how regulatory stringency stratifies procurement behavior across end-use categories.
- Pharmaceuticals:High-purity intermediates for drug synthesis, sterile manufacturing, and container-closure systems where USP Class VI and ISO 10993 biocompatibility function as market access filters. REACH authorization timelines for Substances of Very High Concern are compressing reformulation cycles for legacy plasticizers in European packaging applications.
- Agriculture:Fertilizer additives, pesticide formulations, and soil treatment compounds with established supply relationships and limited pricing power.
- Food Additives:Preservatives, emulsifiers, and colorants subject to EFSA and FDA food contact substance reviews.
- Cosmetics:Active ingredients and formulation bases for personal care products navigating divergent EU and US cosmetic ingredient regulations.
Pharmaceutical applications command the steepest margin premiums; food additive procurement is expanding most quickly under clean-label reformulation pressures.
End Use Industry:
End-use segmentation reflects how customer technical capabilities determine the service intensity required from compound suppliers.
- Healthcare:Medical devices, pharmaceutical packaging, and diagnostic consumables where FDA master file documentation creates qualification barriers for new entrants.
- Manufacturing:Industrial processing aids, coatings, and structural materials with volume-driven procurement and consolidated supplier panels.
- Food Processing:Sanitation chemicals, processing aids, and packaging compounds subject to national food safety authority oversight.
- Personal Care:Consumer product formulations with shorter qualification cycles but intensifying biobased substitution requirements.
Healthcare absorbs the highest regulatory compliance costs; personal care is climbing the fastest on sustainability-driven ingredient swaps.
Packaging Type:
Packaging segmentation captures how material hazard profiles and volume scales determine logistics configuration.
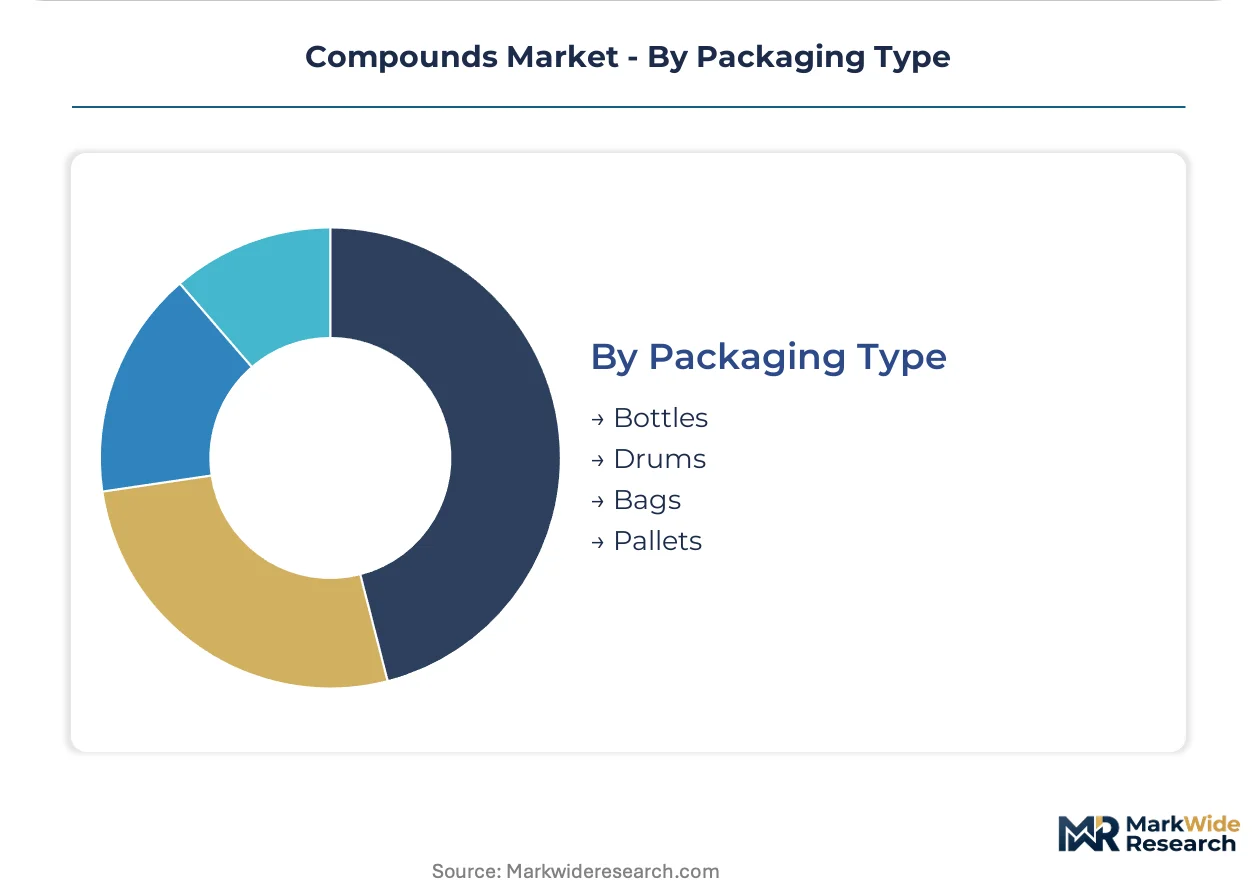
- Bottles:Rigid containers for liquid compounds and laboratory reagents with standardized closure specifications.
- Drums:Intermediate bulk packaging for industrial quantities of solvents, resins, and process chemicals.
- Bags:Flexible containment for powdered and granular compounds with moisture barrier requirements.
- Pallets:Unitized loads for high-volume shipments to integrated manufacturing sites.
Drums dominate intermediate chemical logistics; specialized bottle formats for pharmaceutical-grade materials are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ludwigshafen chemical corridor commands premium compound volumes while the United States anchors Gulf Coast cracking capacity; both face diverging regulatory pressures from ECHA and EPA that reshape procurement geography.
United States
Pharmaceutical packaging reformulation and automotive lightweighting drive demand for high-purity intermediates and engineered polymer blends. FDA's updated extractables-leachables guidance compresses qualification timelines for container-closure systems. The Texas-Louisiana Gulf Coast corridor concentrates ethylene crackers and downstream compounding assets where Dow anchors North American manufacturing scale.
Germany
REACH authorization deadlines for Substances of Very High Concern force substitution investments across adhesive and coating portfolios. ECHA's 2024-2025 sunset date cluster accelerates phthalate plasticizer phase-outs. The Rhine-Ruhr industrial cluster around Leverkusen and Ludwigshafen hosts BASF's integrated Verbund site sustaining captive feedstock advantages for organic compound lines.
China
Dual carbon goals and industrial upgrading policies redirect capacity toward high-performance polymer grades for electric vehicle and renewable energy applications. NMPA alignment with ICH guidelines elevates documentation requirements for pharmaceutical-grade imports. The Yangtze River Delta concentration around Shanghai absorbs specialty compound investments serving domestic automotive OEMs.
Japan
Medical device export dependence sustains demand for USP Class VI certified compounds and ISO 10993 biocompatibility documentation. METI's chemical management policies under CSCL tighten hazard communication for imported mixtures. The Kansai region around Osaka maintains precision compounding capabilities for healthcare-grade polymer formulations.
India
CDSCO's phased implementation of ICH Q3D guidelines for elemental impurities elevates purity specifications for API intermediates. PLI scheme incentives for active pharmaceutical ingredients attract backward integration investments from formulation houses. Gujarat's Dahej and Ankleshwar industrial zones concentrate import-dependent compound processing for domestic pharmaceutical manufacturing.
Compounds Market Competitive Environment
German producers anchor the integrated Verbund tier; US Gulf Coast specialists hold cracking-advantaged positions; Japanese and Korean fabricators occupy precision-compounding niches. The market structures around three archetypes: captively integrated majors with backward control over feedstock, regional compounders with formulation service depth, and technology licensors with specialty catalyst or process packages. Capacity expansion and strategic partnerships dominate competitive moves as firms seek to bridge regulatory compliance capabilities across Atlantic supply chains.
Within the integrated major tier, BASF SE and Dow, Inc. exemplify divergent geographic anchoring strategies that shape competitive positioning. BASF's Ludwigshafen presence represents the European regulatory-compliance archetype with parallel REACH documentation capabilities. Dow's Gulf Coast concentration embodies the feedstock-advantaged North American model. DuPont de Nemours, Inc. occupies a qualification-intensive position where FDA master file holdings create barriers for healthcare-grade polymer entrants.
| Leading Market Players |
|---|
| BASF SE |
| SABIC |
| Dow, Inc. |
| LyondellBasell Industries Holdings B.V. |
| DuPont de Nemours, Inc. |
| Asahi Kasei Corporation |
| Covestro AG |
| KURARAY CO., LTD. |
| RTP Company |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical buyers consolidating qualified vendor lists around REACH-certified suppliers in Germany's chemical corridor are forcing compound producers to absorb documentation costs and pass through certification premiums. This procurement concentration rewards integrated Verbund operators with captive compliance capabilities while squeezing standalone compounders on margin.
Pricing Analysis
Distributor margins of 15-25% separate pharmaceutical-grade compound prices from direct OEM contract rates. Three-tier pricing structure across pharmaceutical, technical, and industrial specification levels reflects ISO 10993 and USP Class VI certification investments. Pricing pressure stems from feedstock volatility in Gulf Coast cracking economics. Automotive OEMs exhibit highest price sensitivity; sterile injectable formulators show least.
Supply Chain Analysis
Specialized workforce availability in Germany's Rhine-Ruhr cluster, the Texas-Louisiana Gulf Coast, and Japan's Kansai region determines high-purity compound production capacity. Supply chains draw from crude-derived naphtha, natural gas liquids, and specialty catalyst packages. Single-source vulnerability concentrates around Ludwigshafen's captive Verbund infrastructure. Distribution runs through tier-1 distributors with integrated regulatory documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through healthcare-grade certification premiums that offset feedstock volatility. Pharmaceutical formulation complexity and automotive lightweighting mandates create dual premium-tier demand pools.
For Market Incumbents: Lock in regulatory compliance advantages by deepening ISO 10993 documentation capabilities and securing REACH authorization for substitute plasticizers ahead of ECHA sunset deadlines. BASF's integrated Verbund model demonstrates how captive feedstock control defends against commodity margin compression. Prioritize container-closure system reformulation contracts as FDA extractables-leachables guidance opens replacement cycles. For New Entrants and Emerging Players: Launch via technical service partnerships with mid-size pharmaceutical contract manufacturers seeking dual-sourcing alternatives to German Verbund suppliers. Healthcare-grade polymer blends for biologic containers represent the most penetrable white space, as FDA master file requirements create qualification moats that favor documentation-heavy entrants over commodity compounders. For Investors and Strategic Acquirers: Asymmetric upside sits with regional compounders possessing parallel EPA-ECHA certification capabilities that bridge Atlantic regulatory divergence. Five-to-ten year viability favors suppliers with extractables-leachables testing infrastructure and biocompatibility laboratory relationships. Watch for REACH authorization timeline acceleration as the inflection signal for substitution investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | BASF's Ludwigshafen Verbund demonstrates captive naphtha supply insulation from Gulf Coast volatility. |
| Healthcare-Grade Certification Investment | ISO 10993 and USP Class VI documentation creates FDA master file barriers for sterile injectable compound supply. |
| Dual-Registration Capability Buildout | Parallel EPA TSCA and ECHA REACH compliance positions suppliers for cross-Atlantic procurement consolidation. |
| Reactive Extrusion Technology Deployment | Continuous compounding lines in Germany's Rhine-Ruhr cluster reduce lot-to-lot variability for automotive OEMs. |
| Long-Term Supply Agreement with Pharma | Container-closure system reformulation contracts capture FDA guidance-driven replacement demand. |
Study Parameters
Multiple input streams — plant manager interviews, pharmaceutical procurement lead discussions, distribution channel partner consultations, and regulatory affairs director exchanges — were reconciled against customs trade data, Cefic industry reports, SEC chemical company filings, and ECHA substance registration databases. Bottom-up volume modeling across grade tiers and end-use industries was cross-validated through top-down market sizing.
Historical shipment patterns were cross-referenced against panel input from technical R&D directors and OEM procurement teams to establish baseline demand. Segmentation modeling spanned organic compound purity grades, polymer blend performance tiers, packaging formats, and regional production hub clusters. CAGRs were derived through trend extrapolation modified by REACH authorization timeline impacts and automotive lightweighting mandate adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA substance restriction acceleration or Gulf Coast feedstock disruption scenarios. Forecasts reflect documented assumptions regarding regulatory harmonization and pharmaceutical outsourcing continuity. Material deviation in REACH sunset date clustering or FDA guidance issuance timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Low Density Sheet Moulding Compound (SMC) Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Additive Masterbatch Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
Europe Microencapsulation Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market
Specialty Compounds
Global Customized Premixes Market
Specialty Compounds
Spackling Paste Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
White Carbon Black Market
Specialty Compounds
EPDM Sealing Strip Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Arsenical Compounds Market