
 Middle East and Africa Polypropylene Compounds Market | 2026-2036
Middle East and Africa Polypropylene Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Polypropylene Compounds Market Intelligence
Compound modification services are reshaping margin distribution across the Middle East and Africa polypropylene compounds value chain, with producers capturing returns downstream from base resin sales. SABIC leverages its fully integrated petrochemical complex in Jubail to control feedstock costs and compound formulation simultaneously. Borouge anchors high-performance automotive grades through its Abu Dhabi manufacturing base, while Borealis AG specializes in advanced catalyst technologies that enable tailored melt-flow characteristics for regional processors.
Polypropylene compounds consist of polypropylene resin base combined with fillers, reinforcements, impact modifiers, and stabilizers to achieve specified mechanical, thermal, or electrical properties, typically processed via twin-screw extrusion to homogenize dispersed phases. These materials serve primarily as metal replacements and performance upgrades in injection-molded components requiring dimensional stability and chemical resistance. Impact copolymer grades dominate automotive bumper and interior applications due to their superior low-temperature toughness, while injection molding as a process channel captures the largest volume share because of its compatibility with complex geometries and high throughput rates. Random copolymer formulations exhibit the fastest structural expansion in transparent packaging segments across the Gulf Cooperation Council states.
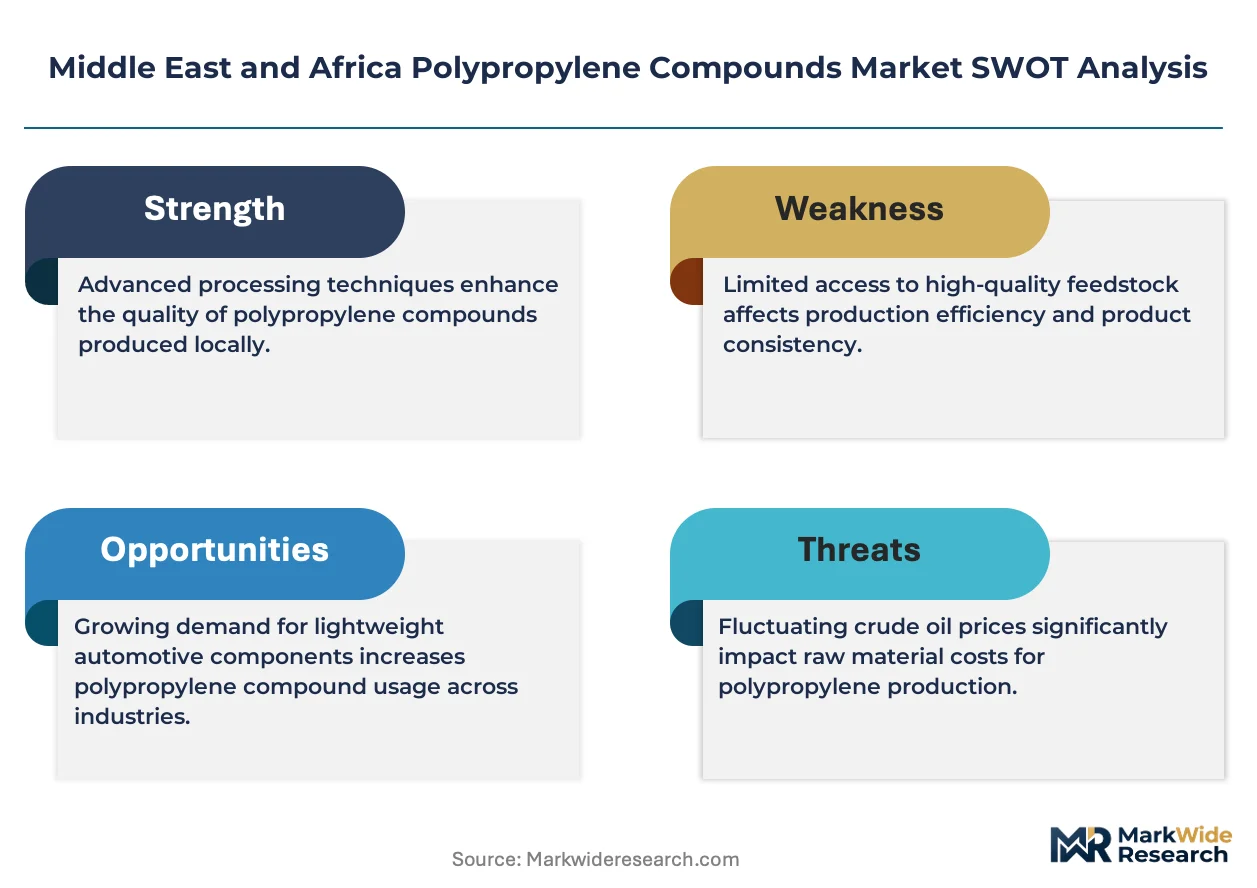
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations and South African Bureau of Standards (SABS) automotive material specifications govern product compliance and market access for compounders operating across the region. The EU Green Deal's carbon border adjustment mechanism exerts indirect pressure on Middle Eastern exporters to document embedded emissions in compound shipments destined for European automotive supply chains. Stakeholders must monitor catalyst technology licensing terms and feedstock cost differentials between naphtha and propane dehydrogenation routes to preserve margin sustainability amid shifting cracker economics.
Market Dynamics
Automotive lightweighting mandates across South Africa and Nigeria are compressing substitution cycles for metal components, forcing compounders to accelerate impact copolymer qualification timelines and localize technical service capabilities.
Growth Catalysts
- EU Green Deal carbon border adjustments:European automotive OEMs now require embedded emissions documentation for Middle Eastern compound shipments, creating competitive differentiation for producers with verified low-carbon feedstock.
- Jubail-Yanbu industrial corridor concentration:Saudi Arabia's integrated petrochemical complexes deliver captive propylene feedstock at structural cost advantages versus naphtha-dependent importers.
- Impact copolymer technology:Advanced reactor-grade formulations achieve low-temperature ductility without post-reactor compounding, reducing conversion costs for bumper and interior Tier-1 suppliers.
Market Restraints
- Propane dehydrogenation feedstock volatility:PDH economics swing with liquefied petroleum gas pricing, compressing margin predictability for non-integrated compounders in the Gulf Cooperation Council.
- European REACH compliance burden:Substance of Very High Concern declarations and SCIP database entries add documentation costs exceeding regional administrative capacity.
- Long-fiber thermoplastic substitution:Glass-mat reinforced thermoplastics and direct-LFT processes capture structural automotive load-bearing applications from mineral-filled polypropylene.
Strategic Opportunities
- Nigerian automotive assembly localization:Pan-African Automotive Pact tariff structures incentivize compound stocking and technical service presence in Lagos-Abuja corridor.
- Random copolymer transparent packaging:Food contact clarity requirements in UAE and Saudi retail channels drive virgin resin displacement in dairy and deli containers.
- Post-consumer recycled feedstock integration:Extended Producer Responsibility frameworks emerging in South Africa create offtake agreements for mechanically recycled polypropylene flake.
Industry Challenges
- Twin-screw extrusion process engineering:Dispersive mixing optimization for nanoclay and glass fiber combinations requires scarce compounding technologists across regional technical institutes.
- SASO-SABS dual certification timelines:Parallel conformity assessment procedures for Saudi and South African automotive approvals extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Polypropylene Compounds Market |
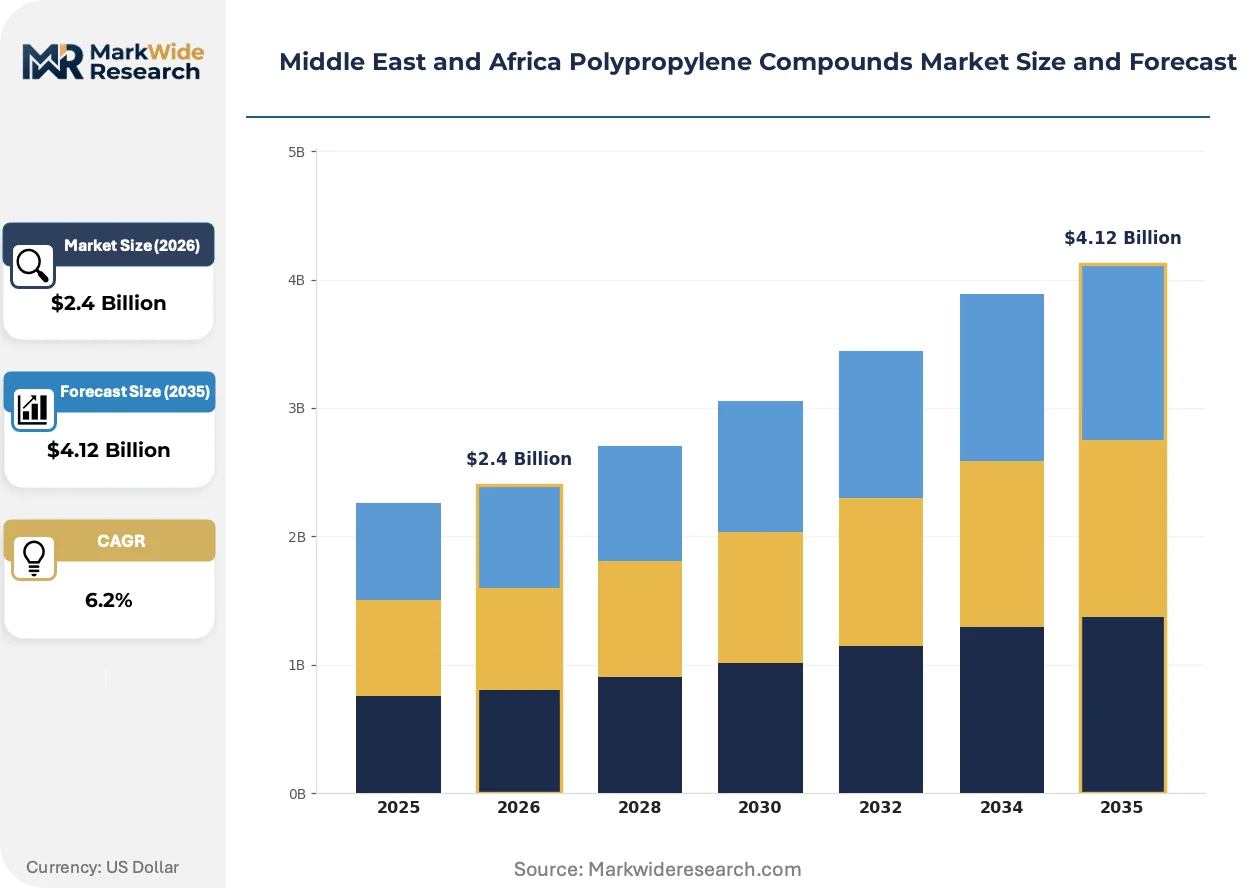
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impact Copolymer, Random Copolymer, Homopolymer, Blends End User: Automotive, Packaging, Consumer Goods, Electrical Application: Injection Molding, Blow Molding, Film Extrusion, Fiber Production Technology: Catalytic Polymerization, Gas-phase Polymerization, Bulk Polymerization, Solution Polymerization |
| Companies Covered | SABIC, Borouge, LyondellBasell Industries Holdings B.V., Borealis AG, Exxon Mobil Corporation, TotalEnergies, Sumitomo Chemical Co., Ltd., EuP Egypt, Petro Rabigh, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Polypropylene Compounds Market Strategic Shifts & Innovations
Material formulation priorities are pivoting from cost-driven mineral filling toward performance-engineered reinforcement systems that satisfy simultaneous lightweighting and recyclability targets.
Long-fiber-reinforced polypropylene compounds are migrating from compression-molded GMT sheets toward direct inline compounding for injection-molded structural automotive components. German and Japanese OEM technical centers in South Africa now specify 20-40mm fiber lengths for front-end modules and door carriers. This migration from legacy short-fiber injection grades is compressing the supplier base toward compounders with dedicated LFT pultrusion lines.
EU Green Deal carbon border adjustment mechanism documentation requirements are forcing Middle Eastern exporters to implement mass-balance accounting for Scope 3 emissions. Compounders serving European automotive supply chains must now validate cradle-to-gate carbon intensity through third-party certification. Random copolymer grades for transparent packaging face the steepest compliance burden due to complex additive supply chain tracing.
Consolidated procurement by pan-African automotive Tier-1 suppliers is displacing fragmented distributor networks with direct mill relationships and vendor-managed inventory programs. Faurecia and Lear Corporation operations in Morocco and South Africa now negotiate annual volume agreements with compounders, bypassing regional trading houses. This concentration is most visible in bumper fascia and instrument panel compounds where specification lock-in creates switching costs.
Middle East and Africa Polypropylene Compounds Market Segmentation
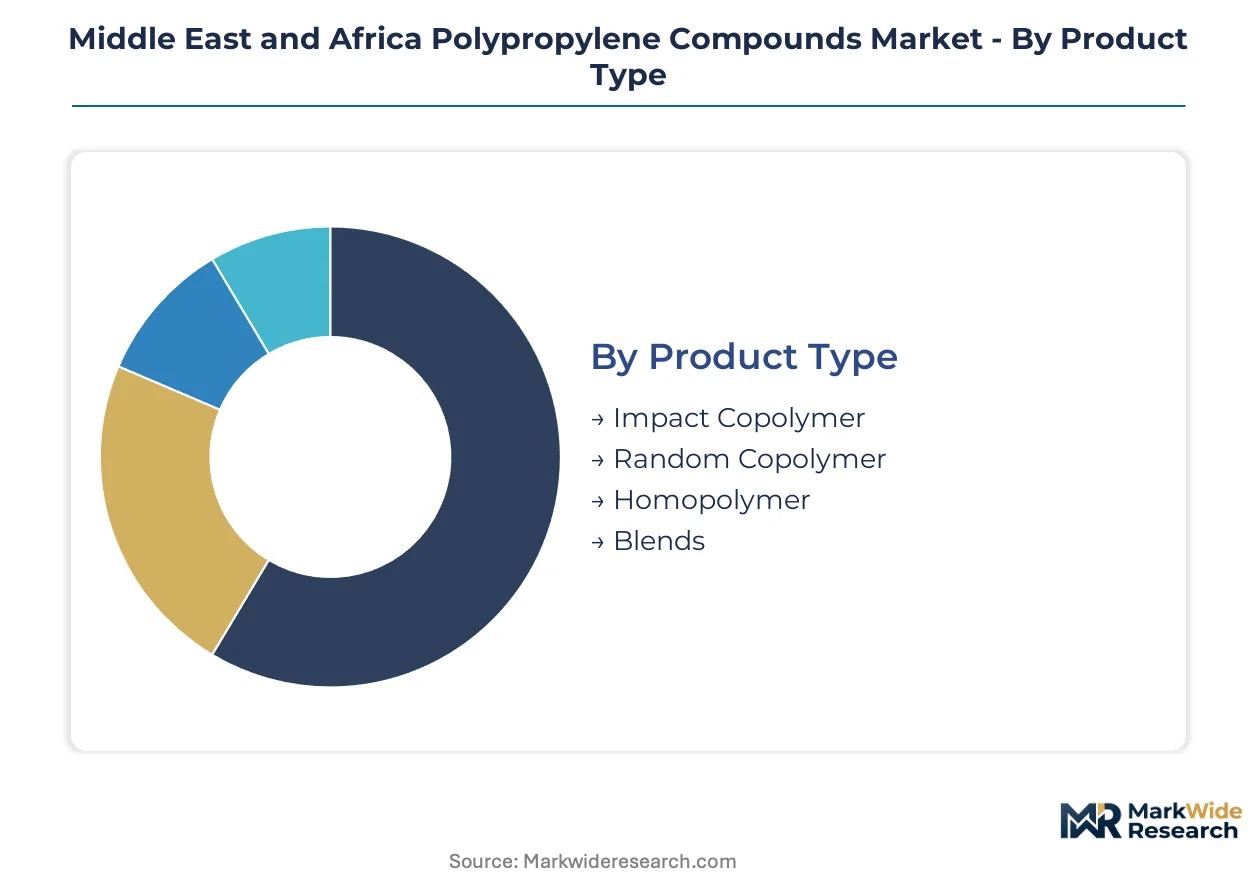
Polypropylene compounds in the Middle East and Africa exhibit distinct technical service requirements across formulation types, with compounding complexity dictating aftermarket support intensity. Specification lock-in between Saudi automotive Tier-1s and compounders creates durable segmentation patterns resistant to rapid supplier switching.
Product Type:
After-sales service intensity escalates with formulation complexity, as reinforced grades demand ongoing processing optimization support at customer molding operations.
- Impact Copolymer:Reactor-grade formulations combine ethylene-propylene rubber domains within continuous polypropylene matrices to deliver sub-zero ductility without secondary compounding. Saudi Arabia's bumper fascia manufacturers in Jubail Industrial City specify these grades for instrument panels and door trims where crash performance is non-negotiable.
- Random Copolymer:Ethylene incorporation disrupts crystalline regularity to yield optical clarity alongside moderate stiffness. UAE retail packaging converters in Dubai Industrial Park displace polystyrene in dairy containers where shelf visibility drives purchase decisions.
- Homopolymer:Isotactic polypropylene with maximum crystallinity serves rigid applications in South African appliance housings.
- Blends:Alloy formulations with thermoplastic elastomers target soft-touch automotive interiors.
By volume, Impact Copolymer leads. By growth pace, Random Copolymer is ahead.
End User:
Customer procurement scale separates segments, with pan-African automotive contracts commanding dedicated technical account management unavailable to fragmented packaging converters.
- Automotive:South Africa's OEM assembly plants and Nigerian emerging vehicle production drive specification-intensive demand for reinforced compounds. Faurecia and Lear operations in Morocco and Rosslyn negotiate direct mill relationships with compounders, bypassing distributor networks entirely.
- Packaging:Gulf Cooperation Council food contact regulations shape random copolymer specifications for clarity and migration compliance.
- Consumer Goods:Appliance manufacturers in Egypt and Turkey source homopolymer grades for rigid housing components.
- Electrical:Wire and cable insulation applications in Saudi infrastructure projects require flame-retardant compounded formulations.
Automotive commands premium pricing power. Packaging delivers volume scale.
Application:
Process equipment investment thresholds create tiered entry barriers, with twin-screw extrusion lines separating integrated compounders from toll processors.
- Injection Molding:Complex geometries in automotive interiors and appliance housings demand precise melt-flow control. Nigerian assembly localization under the Pan-African Automotive Pact accelerates stocking point requirements for injection-grade compounds in the Lagos-Abuja corridor.
- Blow Molding:Random copolymer grades achieve parison stability for pharmaceutical and personal care containers.
- Film Extrusion:Biaxially oriented polypropylene films serve flexible food packaging across Saudi retail channels.
- Fiber Production:Carpet backing and geotextile applications consume high-melt-flow homopolymer grades.
Injection Molding dominates value capture. Blow Molding climbs fastest on packaging substitution.
Technology:
Licensing cost structures and catalyst royalty burdens differentiate process economics, with gas-phase routes offering capital efficiency versus solution polymerization's product breadth.
- Catalytic Polymerization:Ziegler-Natta and metallocene catalyst systems enable precise molecular weight distribution control. Borouge's Abu Dhabi operations leverage advanced catalyst technologies from Borealis to tailor melt-flow characteristics for regional processors serving European automotive OEMs.
- Gas-phase Polymerization:Fluidized bed reactors deliver propylene conversion without hydrocarbon diluent recovery.
- Bulk Polymerization:Liquid propylene serves as its own reaction medium in Jubail-Yanbu corridor installations.
- Solution Polymerization:Dissolved polymer processes enable specialty elastomeric grades with narrow composition distribution.
Gas-phase Polymerization holds installed capacity leadership. Catalytic Polymerization expands most quickly on performance premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging converters in the Gulf Cooperation Council states exhibit the highest price elasticity, while South African automotive Tier-1s absorb premium pricing for specification-locked impact copolymer grades.
Saudi Arabia
Jubail Industrial City and Yanbu anchor the region's lowest-cost polypropylene compound production through fully integrated petrochemical complexes. SASO technical regulations govern food contact and automotive material certifications, creating compliance entry barriers for non-integrated importers. The Eastern Province corridor concentrates reactor-grade impact copolymer output for bumper fascia manufacturers serving domestic assembly and export markets.
United Arab Emirates
Dubai Industrial Park and Jebel Ali free zone host packaging converters displacing polystyrene with random copolymer grades in dairy and deli applications. MOHAP food contact regulations and Emirates Authority for Standardization and Metrology specifications shape clarity and migration compliance requirements. Abu Dhabi's downstream manufacturing base leverages Borouge production for high-performance automotive compounds destined for European OEM supply chains.
South Africa
Rosslyn and Durban automotive assembly plants drive specification-intensive demand for reinforced compounds under the African Continental Free Trade Area localization incentives. SABS automotive material specifications and the National Regulator for Compulsory Specifications govern product compliance and market access. The Gauteng industrial corridor concentrates technical service capabilities for impact copolymer qualification timelines compressed by lightweighting mandates.
Nigeria
Lagos-Abuja corridor assembly localization under the Pan-African Automotive Pact accelerates compound stocking requirements for injection molding operations. The Standards Organisation of Nigeria manages conformity assessment procedures that extend product launch cycles for imported formulations. Apapa port logistics and inland distribution networks shape procurement patterns for non-integrated compounders serving emerging vehicle production.
Egypt
Alexandria and Suez Canal Economic Zone industrial zones host appliance manufacturers sourcing homopolymer grades for rigid housing components. Egyptian Organization for Standardization and Quality specifications align with Gulf Cooperation Council technical regulations for regional market access. Domestic compounding operations face feedstock cost pressures from naphtha-dependent propylene routes versus integrated Gulf producers.
Middle East and Africa Polypropylene Compounds Market Key Industry Players
Integrated petrochemical conglomerates and specialized compounders split the market between feedstock-cost leadership and formulation-technical differentiation. Saudi Arabia's Jubail-Yanbu corridor concentrates capacity among producers with captive propylene supply, while European and Asian multinationals anchor premium automotive specification positions through catalyst licensing and technical service density. Three strategic archetypes dominate: state-affiliated integrated producers, technology-licensed regional compounders, and global specialty material suppliers. Capacity expansion and backward integration into propylene feedstock represent the dominant competitive moves.
Within the integrated producer tier, SABIC and Borouge exemplify state-affiliated structures with Jubail and Abu Dhabi manufacturing bases controlling feedstock and formulation simultaneously. Borealis AG occupies a technology-licensed position, anchoring advanced catalyst capabilities that enable tailored melt-flow characteristics for regional processors. These three entities represent distinct strategic positions: full integration, regional scale with technology transfer, and specialty catalyst IP licensing.
| Leading Market Players |
|---|
| SABIC |
| Borouge |
| LyondellBasell Industries Holdings B.V. |
| Borealis AG |
| Exxon Mobil Corporation |
| TotalEnergies |
| Sumitomo Chemical Co., Ltd. |
| EuP Egypt |
| Petro Rabigh |
| Others |
Cost & Logistics Intelligence
Apapa port logistics corridors connecting Lagos to inland Nigerian assembly plants impose freight cost differentials that compound feedstock advantages for integrated Jubail-Yanbu producers while forcing non-captive compounders into price-competitive stocking strategies near demand clusters.
Pricing Analysis
After-sales technical service contracts and processing optimization support capture lifetime value beyond base resin transactions. Pricing stratifies across reactor-grade impact copolymer premiums, standard injection molding grades, and economy mineral-filled compounds. Cost compression in non-integrated toll compounding is intensifying because PDH feedstock volatility compresses margin predictability. Packaging converters in the Gulf Cooperation Council states exhibit highest price sensitivity, while South African automotive Tier-1s absorb premium pricing for specification-locked grades.
Supply Chain Analysis
Tariff exposure between European Union member states and Middle Eastern exporters under the carbon border adjustment mechanism dominates supply chain risk planning. Feedstock concentration in Saudi Arabia, the United Arab Emirates, and South Africa anchors regional propylene supply. Production draws from naphtha cracking, propane dehydrogenation, and refinery off-gas streams. Single-source vulnerability in catalyst technology licensing from Borealis and LyondellBasell creates concentration risk. Distribution runs through direct mill relationships with pan-African automotive Tier-1s, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of twin-screw extrusion process engineers with nanoclay dispersive mixing expertise constrains capacity expansion timelines and creates acquisition premiums for technical teams.
For Market Incumbents: Insulate specification-locked positions in South African automotive bumpers and instrument panels by embedding technical service teams at Faurecia and Lear molding operations. Deepen upstream control over propylene feedstock through PDH unit investments or long-term offtake contracts to neutralize naphtha cost volatility threatening margin sustainability. For New Entrants and Emerging Players: Nigerian automotive assembly corridors between Lagos and Abuja present underpenetrated demand for injection-grade compounds as Pan-African Automotive Pact localization accelerates. Target stocking point establishment with vendor-managed inventory programs for emerging Tier-2 suppliers lacking direct mill access. Lead with random copolymer transparent packaging qualifications in UAE dairy applications where polystyrene displacement creates specification openings. For Investors and Strategic Acquirers: Regional compounders with captive catalyst licensing and established SABS-SASO dual certification capabilities represent priority acquisition archetypes. Long-term viability hinges on feedstock integration depth and automotive specification lock-in durability. Monitor EU Green Deal embedded emissions documentation requirements as inflection indicator for competitive repositioning toward low-carbon feedstock verification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | PDH unit investments in Jubail-Yanbu corridor neutralize naphtha cost volatility for compounders. |
| Long-term Supply Agreement | Annual volume contracts with Faurecia and Lear operations displace fragmented distributor networks. |
| Joint Venture | Technology licensing partnerships with Borealis enable tailored melt-flow characteristics for regional processors. |
| Capacity Expansion | Twin-screw extrusion line additions in Nigerian Lagos-Abuja corridor accelerate localization timelines. |
| Green Manufacturing Transition | Mass-balance accounting for Scope 3 emissions satisfies EU Green Deal carbon border adjustment requirements. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with polymer plant managers, automotive Tier-1 procurement leads, packaging converter technical directors, and catalyst licensing specialists. Secondary validation drew from customs and trade flow databases, SABIC and Borouge technical disclosures, SASO and SABS regulatory filings, and European automotive OEM supplier quality manuals. Bottom-up volume builds from grade-level consumption estimates were triangulated against top-down petrochemical capacity assessments.
Calibration against historical propylene price spreads and automotive production volumes anchored the analytical framework across the analysis window. Segmentation dimensions modeled include copolymer grade tier, end-use industry vertical, processing technology type, and regional production hub cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trends. Industry-specific forecast inputs incorporated PDH economics sensitivity and REACH compliance cost trajectories.
Macroeconomic conditions sit as an overlay; deviation in liquefied petroleum gas pricing, naphtha cracking margins, or euro-dollar exchange rates would shift the trajectory. Forecasts reflect documented assumptions regarding automotive lightweighting mandate adoption rates and Extended Producer Responsibility framework implementation timelines in South Africa. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Sulfur Hexafluoride Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Eggshell Membrane Derivatives Market
Specialty Compounds
Global Color Masterbatch Market
Specialty Compounds
Galactoarabinan Market
Specialty Compounds
Scratch-Resistant Compound Market
Specialty Compounds
Middle East and Africa Color Masterbatch Market
Specialty Compounds
Microcapsules Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
Global Black Masterbatch Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
Lentein Market
Specialty Compounds
Filler Masterbatch Market