
 Compounding Systems Market | 2026-2036
Compounding Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Compounding Systems Market Outlook
USP 797 and USP 800 qualification cycles is bifurcating the vendor landscape into certified automation providers and legacy manual-equipment suppliers. Baxter International leverages its integrated IV therapy portfolio to sustain hospital system contracts across North America. Grifols anchors its position through plasma-derived therapy compounding expertise, while B. Braun Medical competes on European regulatory alignment and aseptic filling scale.
Compounding systems encompass electromechanical and pneumatic equipment designed to measure, mix, sterilize, and dispense pharmaceutical preparations with precision tolerances typically within 0.1 milliliter for IV admixtures, serving the core purpose of eliminating human error in sterile and hazardous drug preparation. Automated Compounding Systems now dominate capital expenditure budgets as hospitals seek to reduce microbial contamination risk, while Manual Compounding Systems retain share in low-volume oral and topical formulations where batch flexibility outweighs throughput requirements. Software Integration represents the fastest-growing technology segment as facilities demand real-time barcode verification and electronic batch records to satisfy traceability mandates.
FDA enforcement of 503B outsourcing facility standards and USP 800 hazardous drug handling requirements directly shapes equipment procurement timelines and validation protocols for American operators, while EU GMP Annex 1 revisions from the EMA impose equivalent barrier-isolation and environmental monitoring demands across European compounding pharmacies. Stakeholders must weigh capital intensity against compliance exposure when selecting between retrofitting manual suites and deploying fully automated isolator-based systems.
Market Dynamics
Automated aseptic compounding technology is compressing the installed base of manual equipment as hospitals confront microbial contamination liability and USP 800 hazardous drug exposure mandates. Capital allocation now favors closed-system isolators over open-front biological safety cabinets in sterile preparation suites.
Growth Catalysts
- EU GMP Annex 1 revisions:German pharmaceutical manufacturers are retrofitting barrier-isolation technology to satisfy EMA sterility assurance requirements, triggering replacement cycles across European hospital pharmacies.
- Oncology volume concentration:United States cancer centers are consolidating chemotherapy preparation into centralized 503B outsourcing facilities equipped with robotic compounding systems.
- Barcode verification integration:Real-time electronic batch recording is becoming mandatory for IV admixture traceability, pulling software-enabled compounding platforms into hospital capital budgets.
Market Restraints
- Stainless steel supply volatility:Pharmaceutical-grade 316L stainless steel price swings constrain isolator fabrication timelines and inflate equipment quotations.
- Validation protocol complexity:FDA 503B facility qualification cycles extend 18-24 months, freezing procurement decisions and compressing vendor cash conversion.
- Manual compounding persistence:Low-volume oral and topical formulations retain economic viability in community pharmacies, limiting automation penetration in non-sterile segments.
Strategic Opportunities
- Home infusion expansion:United States payers are reimbursing ambulatory infusion therapy, creating demand for portable compounding units in specialty pharmacy networks.
- Biologics cold-chain convergence:Integration of aseptic compounding with temperature-controlled logistics opens contract manufacturing opportunities for cell and gene therapy preparers.
- Indian hospital modernization:CDSCO quality mandate enforcement is accelerating private healthcare investment in automated sterile preparation infrastructure across tertiary care centers.
Industry Challenges
- Pharmacy technician certification gaps:USP 797 and USP 800 operator competency requirements outpace vocational training program output, constraining facility staffing.
- Legacy system integration friction:Hospital information systems require custom middleware development to connect isolator-based compounding platforms with existing electronic health record architectures.
- Environmental monitoring calibration:Continuous particle counting and viable air sampling equipment demands specialized metrology support that strains in-house biomedical engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compounding Systems Market |
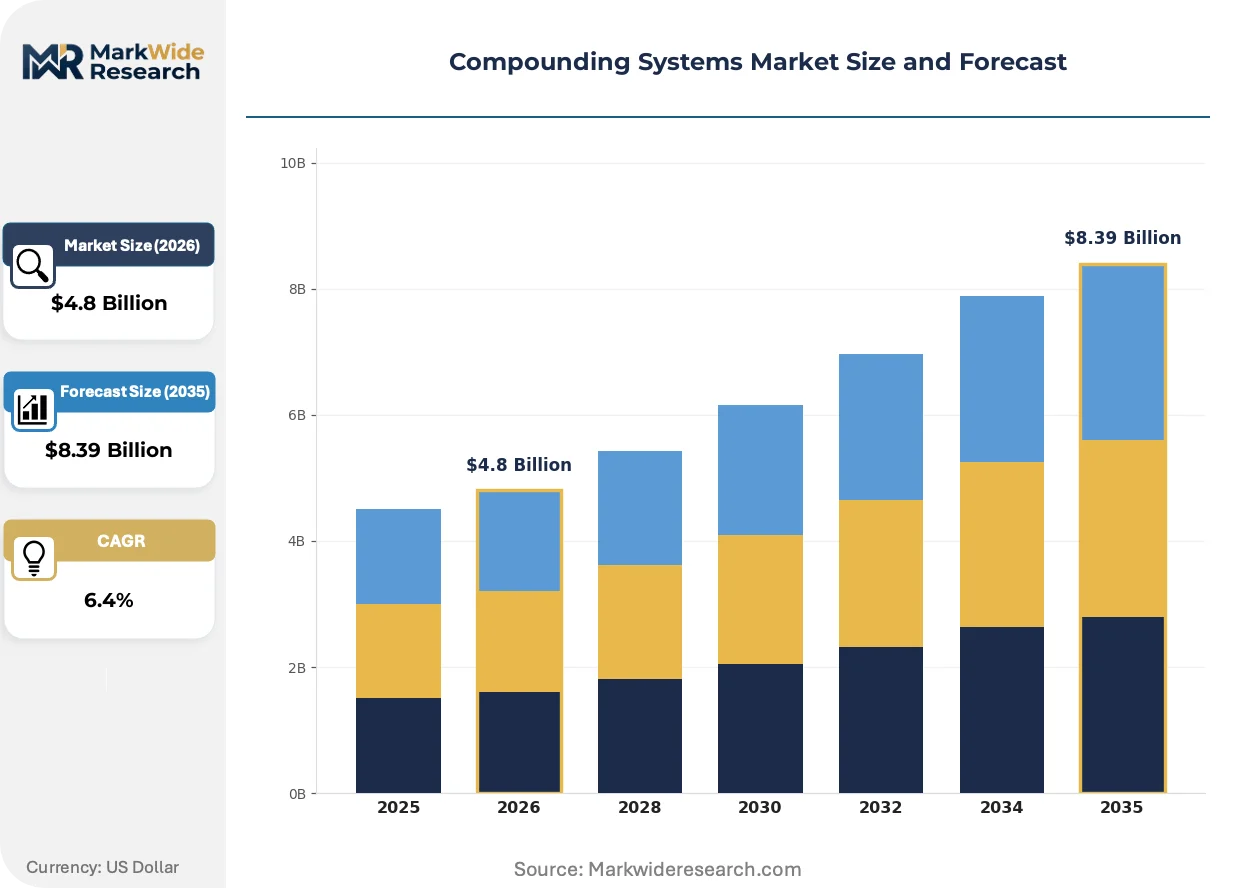
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Compounding Systems, Manual Compounding Systems, Capping Systems, Filling Systems Application: Aseptic Preparation, IV Therapy, Oral Compounding, Oncology Compounding End User: Pharmacies, Hospitals, Home Healthcare, Compounding Pharmacies Technology: Microbial Risk Reduction, Closed System Transfer Devices, Software Integration, Quality Control Systems |
| Companies Covered | Baxter International Inc, Grifols, B. Braun Medical Inc, ICU Medical, Omnicell, COMECER S.p.A., ARxIUM, EQUASHIELD, Fagron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compounding Systems Market Strategic Shifts
Closed System Transfer Devices are redefining hazardous drug handling protocols by eliminating open-air manipulation during chemotherapy preparation. Equipment vendors are embedding gravimetric verification and vision-based inspection into next-generation platforms.
Robotic arm-based compounding workstations is supplanting semi-automated peristaltic pump systems in high-volume hospital pharmacies. United States health systems with 500+ bed capacity are deploying these units to achieve 99.9% dose accuracy rates. The technology is compressing pharmacy labor hours per IV admixture while expanding 24-hour sterile preparation capacity without proportional headcount expansion.
EMA enforcement of EU GMP Annex 1 barrier-isolation standards is mandating physical separation between operators and sterile products. European compounding facilities are installing restricted access barrier systems with integrated vaporized hydrogen peroxide decontamination cycles. Oncology and biologic preparation suites in Germany, France, and Italy face the most aggressive retrofit timelines as national regulators align inspection protocols with the revised guideline.
Specialty pharmacy buyers are consolidating procurement through group purchasing organizations that bundle compounding equipment with consumables and service contracts. Traditional capital-equipment distributors are losing direct hospital relationships as these intermediaries capture specification influence. The United States exhibits the most pronounced channel compression, with three national GPOs controlling access to the majority of acute-care pharmacy capital budgets.
Compounding Systems Market Segmentation
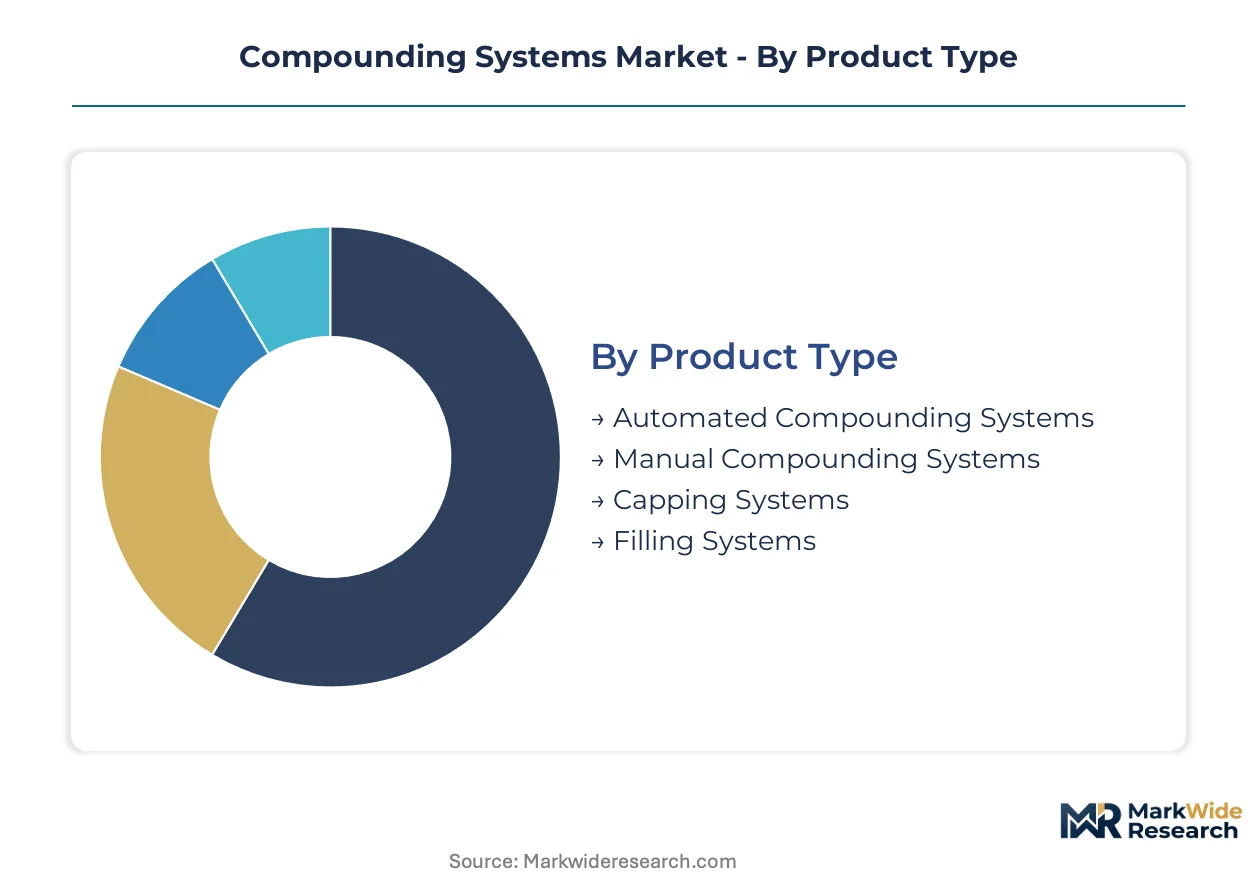
Compounding systems procurement diverges sharply across regulatory exposure levels. Product selection now tracks directly to sterile versus non-sterile handling requirements and hazardous drug classification under USP 800 and EU GMP Annex 1.
Product Type:
FDA 503B facility standards and EMA sterility mandates are compressing the viable equipment base toward validated automation platforms.
- Automated Compounding Systems:Electromechanical platforms with gravimetric verification and barcode scanning achieve precision tolerances within 0.1 milliliter for IV admixtures. United States hospital systems with centralized sterile preparation suites are prioritizing robotic workstations to satisfy USP 797 microbial contamination limits and reduce pharmacy technician exposure liability.
- Manual Compounding Systems:Open-front biological safety cabinets and laminar airflow workbenches retain economic viability for low-volume oral and topical formulations. Community pharmacies in Germany and France continue deploying these units where batch flexibility outweighs throughput requirements and capital constraints block automation migration.
- Capping Systems:Vial and bag sealing equipment with torque verification prevents sterility breaches in finished product handling.
- Filling Systems:Peristaltic and syringe pump technologies deliver precise liquid volumes into final containers across sterile and non-sterile applications.
Established volume favors Automated Compounding Systems; emerging adoption favors Manual Compounding Systems in cost-constrained settings.
Application:
End-use demand concentrates where parenteral therapy volume intersects with hazardous drug handling mandates.
- Aseptic Preparation:Barrier-isolation technology with vaporized hydrogen peroxide decontamination cycles eliminates human contact with sterile products. German pharmaceutical manufacturers are retrofitting restricted access barrier systems to comply with EMA enforcement of EU GMP Annex 1 sterility assurance standards.
- Oncology Compounding:Closed System Transfer Devices from ICU Medical and EQUASHIELD displace open-handling protocols for chemotherapy preparation. United States cancer centers are consolidating this activity into centralized 503B outsourcing facilities equipped with robotic compounding platforms to minimize hazardous drug exposure.
- IV Therapy:Large-volume parenteral admixture preparation dominates hospital pharmacy operational hours and capital allocation.
- Oral Compounding:Patient-specific dosage forms for pediatric and geriatric populations sustain demand in community pharmacy settings.
Regulatory pressure elevates Aseptic Preparation; reimbursement expansion drives Oncology Compounding.
End User:
Procurement authority and validation requirements vary substantially across institutional settings.
- Hospitals:Acute-care systems with 500+ bed capacity deploy robotic arm-based workstations to achieve 99.9% dose accuracy rates and expand 24-hour sterile preparation capacity. United States health systems bundle compounding equipment procurement through group purchasing organizations that capture specification influence from traditional distributors.
- Compounding Pharmacies:503B outsourcing facilities face 18-24 month FDA qualification cycles that freeze equipment decisions and compress vendor cash conversion. These operators require integrated software platforms for electronic batch records and real-time traceability compliance.
- Pharmacies:Retail and community settings retain manual processes for non-sterile formulations with lower regulatory exposure.
- Home Healthcare:Ambulatory infusion therapy reimbursement is creating demand for portable compounding units in United States specialty pharmacy networks.
Capital intensity concentrates in Hospitals; regulatory flexibility persists in Pharmacies.
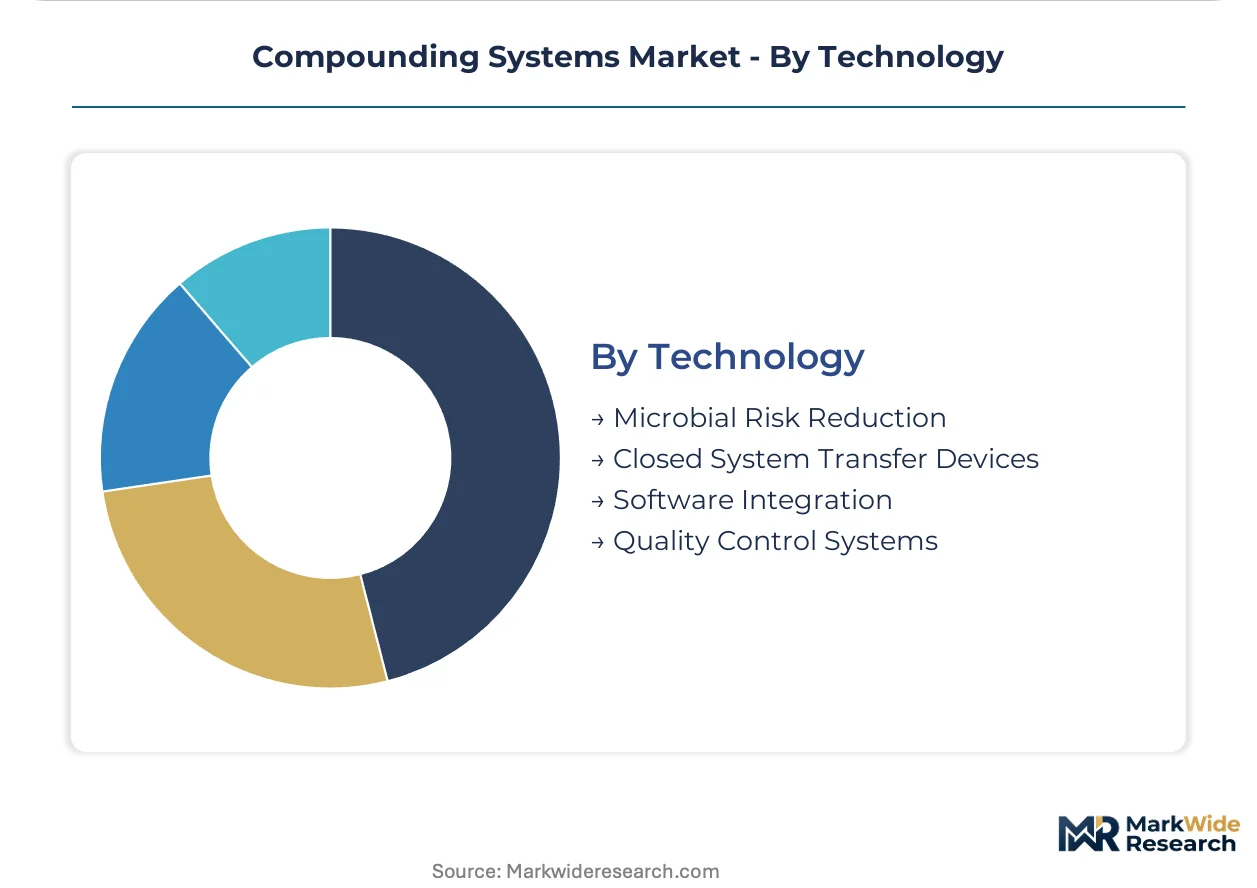
Technology:
Software-enabled verification is climbing the fastest as facilities confront traceability mandates.
- Software Integration:Real-time barcode verification and electronic batch recording platforms connect isolator-based compounding systems to hospital information architectures. Custom middleware development requirements create integration friction that strains in-house biomedical engineering capacity.
- Closed System Transfer Devices:Mechanical barrier technology eliminates open-air manipulation during hazardous drug preparation. These devices are redefining oncology compounding protocols across United States hospital pharmacies.
- Microbial Risk Reduction:Continuous particle counting and viable air sampling equipment demands specialized metrology support.
- Quality Control Systems:Vision-based inspection and gravimetric verification modules embed directly into next-generation compounding platforms.
Compliance urgency favors Software Integration; safety mandates elevate Closed System Transfer Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of 503B outsourcing facility standards and EU GMP Annex 1 revisions from the EMA are accelerating equipment replacement cycles across hospital pharmacies and contract manufacturers in multiple jurisdictions.
United States
Hospital systems with 500+ bed capacity are deploying robotic arm-based workstations to satisfy USP 797 microbial contamination limits. FDA qualification cycles for 503B facilities extend 18-24 months, freezing procurement decisions and compressing vendor cash conversion. Three national group purchasing organizations now control access to the majority of acute-care pharmacy capital budgets, bundling compounding equipment with consumables and service contracts.
Germany
Pharmaceutical manufacturers are retrofitting barrier-isolation technology to comply with EMA sterility assurance requirements under revised EU GMP Annex 1. Oncology and biologic preparation suites in Frankfurt, Munich, and Hamburg face aggressive retrofit timelines as national regulators align inspection protocols. Restricted access barrier systems with integrated vaporized hydrogen peroxide decontamination cycles are displacing open-front biological safety cabinets.
India
CDSCO quality mandate enforcement is accelerating private healthcare investment in automated sterile preparation infrastructure across tertiary care centers. The national pharmaceutical regulator is tightening compliance expectations for hospital pharmacy operations. Mumbai, Delhi-NCR, and Bangalore clusters are seeing concentrated demand for electromechanical compounding platforms with gravimetric verification capabilities.
Japan
PMDA alignment with international GMP standards is driving hospital pharmacy modernization in the Tokyo and Osaka metropolitan areas. METI industrial policy supports domestic medical device manufacturing, creating procurement preferences for locally validated automation platforms. Regional health systems are consolidating chemotherapy preparation into centralized facilities equipped with closed-system isolator technology.
United Kingdom
MHRA post-Brexit regulatory autonomy is maintaining alignment with EU GMP Annex 1 sterility standards while introducing separate national inspection protocols. London and Southeast England health systems are prioritizing software-enabled compounding platforms for real-time barcode verification. NHS procurement frameworks are bundling equipment decisions with long-term service and validation support contracts.
Compounding Systems Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with integrated IV therapy portfolios and specialized compounding automation vendors with isolator expertise. The vendor base separates into three strategic tiers: global hospital supply conglomerates anchoring multi-year system contracts, mid-cap automation specialists competing on regulatory validation speed, and regional equipment fabricators serving cost-constrained community pharmacy segments. Dominant competitive moves include strategic partnerships for software integration capabilities and geographic expansion through distributor network capture in emerging hospital markets.
Within the diversified conglomerate tier, Baxter International Inc and B. Braun Medical Inc represent archetypal players leveraging integrated therapy portfolios to sustain hospital system relationships across North America and Europe. Grifols occupies a distinct position anchored through plasma-derived therapy compounding expertise. Among specialized automation vendors, ICU Medical and EQUASHIELD exemplify the closed-system transfer device segment that is displacing open-handling protocols in oncology compounding. ARxIUM and Omnicell sit within the robotic workstation tier competing on dose accuracy and 24-hour operational capacity. COMECER S.p.A. represents European isolator fabrication capabilities aligned with EMA barrier-isolation mandates. Fagron exemplifies the 503B outsourcing facility operator segment driving demand for validated automation platforms.
| Leading Market Players |
|---|
| Baxter International Inc |
| Grifols |
| B. Braun Medical Inc |
| ICU Medical |
| Omnicell |
| COMECER S.p.A. |
| ARxIUM |
| EQUASHIELD |
| Fagron |
| Others |
Value Chain & Pricing Dynamics
FDA 503B facility qualification standards gate both supplier certification and price stratification across compounding equipment tiers, forcing buyers to pay premiums for validated automation platforms while locking out uncertified fabricators from hospital procurement channels entirely.
Pricing Analysis
Certification level (FDA-grade/CE-marked/ISO-validated) creates the primary spread between equipment tiers. Three-tier pricing structure across premium isolator systems, standard robotic workstations, and economy manual suites dominates procurement. Cost compression in the economy tier is intensifying because community pharmacies face capital constraints blocking automation migration. Hospital systems with centralized sterile preparation suites exhibit the least price sensitivity, while independent 503B outsourcing facilities negotiate aggressively on validation timelines.
Supply Chain Analysis
Strait of Hormuz transit underwrites energy costs for pharmaceutical-grade 316L stainless steel smelting, creating input price volatility that ripples through isolator fabrication. Supply concentrates in Germany, Italy, and the United States for precision electromechanical components. Raw material dependencies span medical-grade stainless steel, vaporized hydrogen peroxide sterilization chemicals, and barcode scanning modules. Single-source vulnerability in robotic arm actuators threatens equipment delivery timelines. Distribution runs through group purchasing organizations that bundle hardware with consumables and service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated isolator engineering talent pools are thinning faster than vocational training programs can replenish them, creating a capability bottleneck that constrains facility expansion timelines and inflates specialist labor premiums across hospital pharmacy and contract manufacturing segments.
For Market Incumbents: Compound defensive moats by deepening backward integration into pharmaceutical-grade stainless steel supply and accelerating FDA pre-submission pathways for next-generation isolator platforms. Robotic workstation vendors face margin compression from mid-cap automation specialists competing on validation speed. Certification investment in EU GMP Annex 1 alignment anchors multi-year contracts with German pharmaceutical manufacturers retrofitting barrier-isolation technology. For New Entrants and Emerging Players: Anchor in India's tertiary care center modernization wave, where CDSCO enforcement is accelerating automated sterile preparation infrastructure investment. Home infusion therapy reimbursement expansion in the United States specialty pharmacy network represents the most penetrable white-space target. Software-enabled barcode verification platforms offer a go-to-market angle that sidesteps capital-intensive hardware fabrication. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed compounding automation specialists that consolidated during the last regulatory cycle. Long-term viability hinges on software integration capabilities that connect isolator platforms to hospital information architectures. Acquisition target archetypes include mid-cap isolator fabricators with EMA validation track records. The signal to watch is FDA enforcement intensity against 503B outsourcing facilities, which accelerates replacement demand for validated equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | FDA 510(k) and CE marking pathways secure hospital procurement eligibility before competitors complete validation cycles. |
| Software Integration Partnership | Electronic health record middleware development reduces installation friction for robotic compounding workstations. |
| Consumables Bundling Strategy | Closed System Transfer Device attachment to isolator contracts captures recurring revenue from oncology compounding suites. |
| Geographic Distributor Capture | Regional equipment fabricator acquisition in India accelerates CDSCO-compliant sterile preparation infrastructure deployment. |
| Biologics Cold-Chain Convergence | Temperature-controlled logistics integration opens contract manufacturing opportunities for cell and gene therapy preparers. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with hospital pharmacy directors, GPO contracts managers, biomedical engineers, and 503B facility operators; and secondary validation against FDA 503B registration databases, EMA GMP inspection records, hospital procurement contract filings, and equipment vendor SEC disclosures. Bottom-up and top-down triangulation cross-checked installed base estimates against capital expenditure surveys and regulatory qualification timelines.
Across the analysis window, the forecasting framework modeled demand by product type (automated systems, manual systems, capping/filling equipment), application (aseptic preparation, oncology compounding, IV therapy), end user (hospitals, compounding pharmacies, home healthcare), and technology tier (software integration, closed system transfer devices, microbial risk reduction). CAGRs derived from regression analysis of historical replacement cycles mapped against regulatory enforcement intensity curves and hospital capital budget allocation patterns.
Material uncertainties — stainless steel commodity price swings, FDA inspection backlog fluctuations, and pharmacy technician certification program output gaps — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EU GMP Annex 1 enforcement timelines and USP 800 hazardous drug handling mandate implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Polymer Clay Market
Specialty Compounds
Global Specialty Amines Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Methyl Anthranilate Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Furniture Foam Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Saudi Arabia Collagen Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Saudi Arabia Masterbatch Market
Specialty Compounds
Low Density Sheet Moulding Compound (SMC) Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market