
 Heat Shrink Tubing Market | 2026-2036
Heat Shrink Tubing Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Shrink Tubing Market Analysis
Buyer concentration in the automotive wire harness sector is shifting as tier-one suppliers consolidate purchasing across fewer, larger platform programs. TE Connectivity leverages its captive connector-tubing integration to sustain pricing power in high-voltage electric vehicle architectures. Sumitomo Electric Industries anchors its position through fluoropolymer specialization for aerospace and mass-transit applications. 3M competes on material science breadth, extending its adhesive-lined portfolio into subsea and offshore energy markets where mechanical protection standards intensify.
Heat shrink tubing comprises cross-linked polymeric sleeves that contract radially when heated, typically recovering to half or less of their supplied diameter while maintaining dielectric strength and environmental sealing. Polyolefin formulations dominate volume production due to cost efficiency and broad temperature ratings, though fluoropolymer variants command premium positioning in aerospace and chemical exposure applications. Adhesive-lined tubing captures above-average margins by combining mechanical protection with moisture sealing in a single installation step. Multi-layer constructions are gaining share in telecommunications infrastructure where fiber-optic cable assemblies require both crush resistance and thermal cycling durability.
UL certification requirements and SAE standards govern product qualification across North American automotive and industrial channels, while REACH and RoHS compliance in Europe restricts halogenated flame retardants and drives reformulation investments. China's GB standards and MIIT directives for new energy vehicles impose additional testing protocols on high-voltage insulation systems. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance costs for multi-standard certification increasingly determine which material platforms achieve scale economics.
Market Dynamics
High-voltage electric vehicle architectures are forcing rapid reformulation of insulation materials as OEMs consolidate platform programs and demand thinner-wall, higher-temperature ratings from fewer qualified suppliers.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated gases accelerates procurement of low-GWP fluoropolymer alternatives for aerospace wire harnessing programs across German and French manufacturing corridors.
- China MIIT directives:Mandatory GB standards testing for new energy vehicle high-voltage systems concentrates demand for adhesive-lined tubing in Shenzhen and Shanghai battery pack assembly zones.
- Cross-linked polyolefin platforms:Cost-efficient temperature ratings above 125°C enable volume substitution of rubber and tape wrapping in commercial vehicle cable harnesses.
Market Restraints
- Raw material concentration:Polyolefin resin supply clusters in US Gulf Coast and Middle Eastern petrochemical complexes expose converters to freight and duty volatility.
- REACH compliance friction:ECHA restrictions on halogenated flame retardants force multi-year reformulation cycles before products qualify for European automotive platforms.
- Silicone cold-shrink substitution:Field-installable silicone sleeves bypass heating equipment requirements in temporary repairs and mobile infrastructure applications.
Strategic Opportunities
- India PLI scheme for auto components:Localized cable assembly investments in Tamil Nadu and Gujarat create demand for halogen-free tubing meeting BIS certification timelines.
- Subsea fiber-optic protection:Multi-layer adhesive-lined constructions penetrate offshore wind and telecom burial applications where mechanical crush resistance commands premium positioning.
- Japan METI carbon neutrality roadmap:Mass-transit infrastructure renewal prioritizes fluoropolymer tubing with verified life-cycle assessments for Shinkansen and urban rail electrification.
Industry Challenges
- Polymer compounding expertise scarcity:Formulation chemists capable of balancing cross-link density with adhesive compatibility command compensation premiums that strain mid-cap converter margins.
- Multi-standard certification timelines:Simultaneous UL, SAE, and GB qualification cycles extend product launch windows by 18-24 months for platforms targeting export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Shrink Tubing Market |
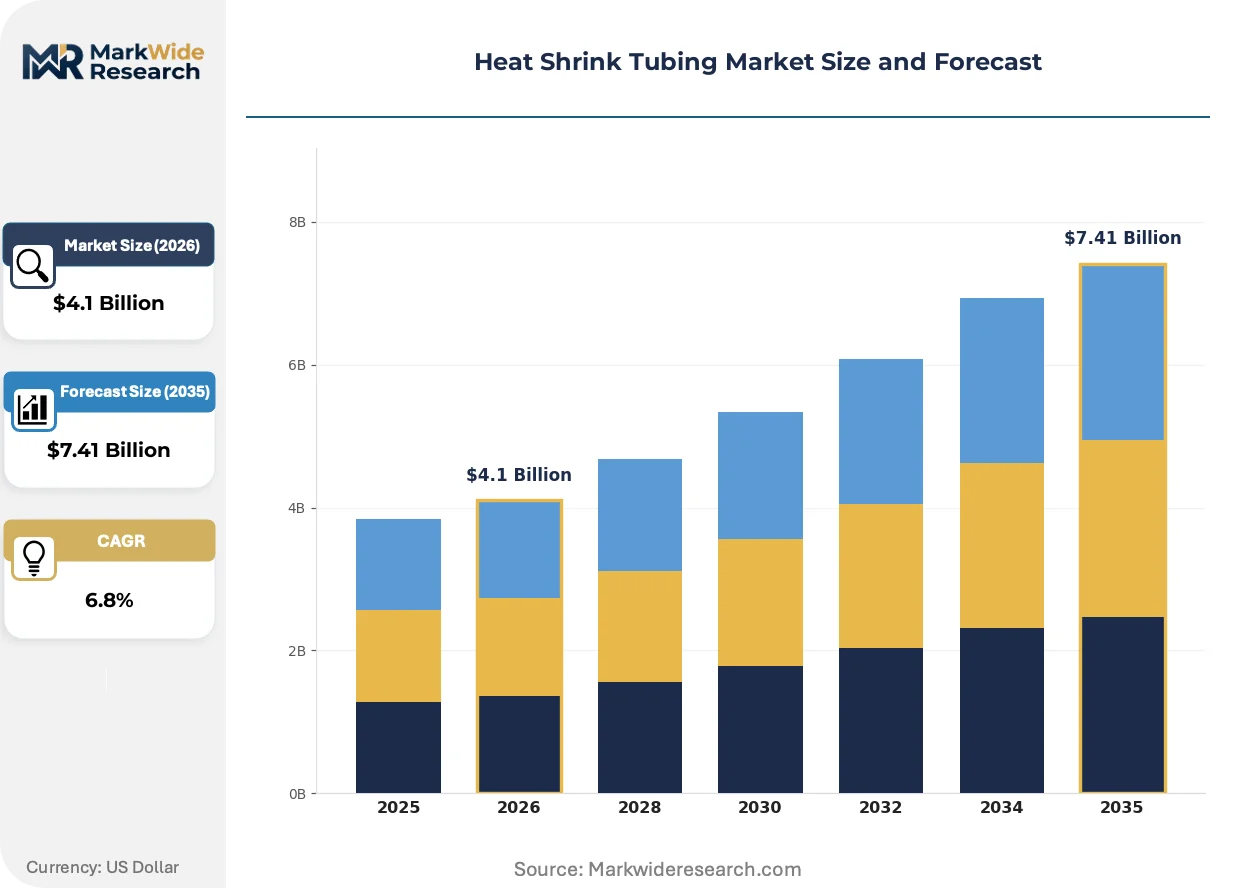
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Tubing, Rigid Tubing, Multi-Layer Tubing, Adhesive-Lined Tubing Material: Polyolefin, PVC, Fluoropolymer, Rubber Application: Electrical Insulation, Wire Bundling, Mechanical Protection, Aerospace End User: Automotive, Electronics, Telecommunications, Industrial |
| Companies Covered | TE Connectivity, 3M, Sumitomo Electric Industries, HellermannTyton, ABB, Alpha Wire, Panduit, Prysmian Group, Amphenol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Shrink Tubing Market Emerging Trajectories
Material science convergence with installation automation is compressing labor content and expanding addressable applications beyond traditional electrical insulation into structural composite and medical device markets.
Dual-wall adhesive-lined constructions are expanding into subsea cable protection and renewable energy infrastructure where simultaneous moisture sealing and mechanical abrasion resistance eliminate secondary taping operations. Offshore wind developers in the North Sea and South China Sea specify these constructions for inter-array cable burial depths exceeding three meters. The technology is expanding into markets previously served by rigid conduit and cast resin systems.
REACH and RoHS amendments are restricting brominated and chlorinated flame retardants in European automotive and industrial channels, compelling compounders to validate phosphorus-nitrogen synergist systems at equivalent dielectric performance. German KBA type-approval processes now require extended aging documentation for alternative chemistries. Suppliers with early ECHA registration dossiers capture qualification timelines that lock out later entrants.
Platform consolidation among tier-one wire harness suppliers concentrates specification authority with fewer procurement teams at TE Connectivity, Yazaki, and Lear Corporation. Long-term supply agreements now bundle tubing, connectors, and application tooling into single-source contracts that compress spot-market volumes. This concentration is most visible in German and Chinese automotive corridors where OEMs delegate full subsystem responsibility. Smaller converters respond by specializing in aftermarket cut-length distribution and same-day fulfillment for maintenance operations.
Heat Shrink Tubing Market Segmentation
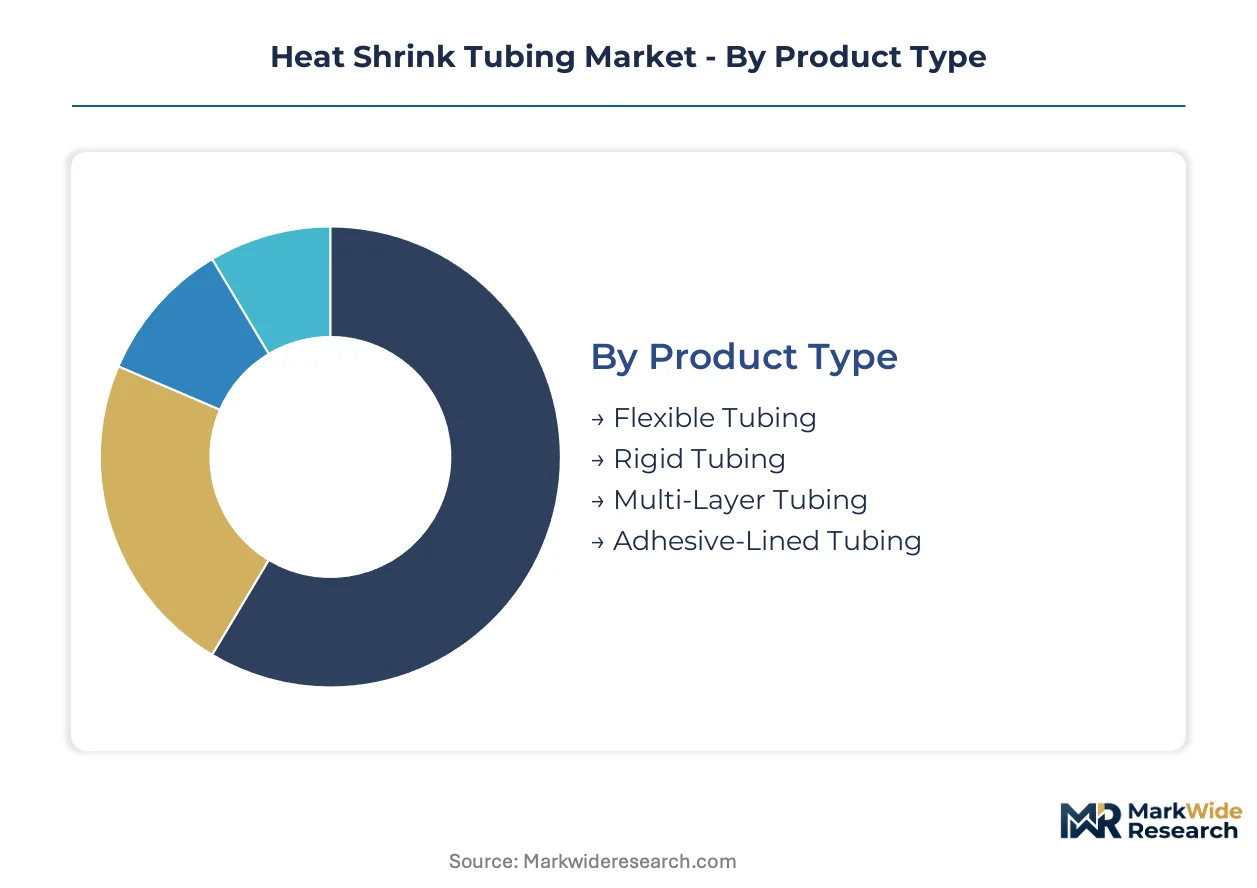
Segmentation in heat shrink tubing reveals how material science specialization and installation method upgrades drive purchasing decisions across automotive, aerospace, and subsea cable markets. Platform consolidation among tier-one wire harness suppliers concentrates volume in fewer qualified formulations while creating openings for premium multi-layer constructions.
Product Type:
Upgrade cycles in wire harness assembly are displacing single-layer constructions with adhesive-lined and multi-layer alternatives that combine sealing and mechanical protection in one installation step.
- Flexible Tubing:Cross-linked polyolefin formulations dominate volume production with temperature ratings exceeding 125°C, capturing procurement from German automotive cable assembly corridors where cost-efficient harness consolidation is accelerating.
- Adhesive-Lined Tubing:Dual-wall constructions integrate thermoplastic adhesive layers that melt and flow during recovery, sealing against moisture ingress; Shenzhen and Shanghai battery pack assembly zones specify these for high-voltage electric vehicle architectures under MIIT GB standards testing protocols.
- Rigid Tubing:Semi-rigid polyolefin variants provide enhanced abrasion resistance for commercial vehicle engine compartments and industrial machinery cable routing.
- Multi-Layer Tubing:Complex constructions combining fluoropolymer outer layers with adhesive inner walls penetrate offshore wind inter-array cable burial applications where crush resistance and thermal cycling durability command premium positioning.
Flexible tubing sits at the top of the volume ranking, with adhesive-lined tubing climbing the fastest as high-voltage platform consolidation demands integrated sealing solutions.
Material:
Cost tier differentiation separates commodity polyolefin volumes from fluoropolymer premiums, with regulatory reformulation investments widening the gap between REACH-compliant and legacy halogenated systems.
- Polyolefin:Cross-linked polyethylene and polypropylene platforms deliver the lowest per-meter cost with broad chemical resistance, anchoring procurement in commercial vehicle harnesses and industrial cable management where temperature ratings above 125°C enable rubber substitution.
- Fluoropolymer:PTFE, FEP, and PVDF formulations withstand temperatures exceeding 200°C and aggressive chemical exposure; aerospace wire harnessing programs across German and French manufacturing corridors specify these grades under EU F-Gas Regulation phase-down timelines for low-GWP alternatives.
- PVC:Plasticized vinyl compounds retain share in cost-sensitive consumer electronics and building wire applications despite regulatory pressure on plasticizer chemistries.
- Rubber:Silicone and EPDM elastomer tubing serves niche applications requiring extreme flexibility and cold-temperature performance in Arctic infrastructure and mass-transit systems.
Polyolefin formulations capture the highest shipment volumes, while fluoropolymer grades are expanding most quickly as aerospace and chemical processing procurement prioritizes thermal endurance.
Application:
Application segmentation tracks how installation automation and subsystem integration are compressing labor content while elevating performance specifications in safety-critical end uses.
- Electrical Insulation:Dielectric strength maintenance under radial contraction remains the core functional requirement, with thin-wall high-temperature ratings gaining specification in consolidated electric vehicle platform programs.
- Mechanical Protection:Abrasion and crush resistance specifications intensify in subsea fiber-optic burial and renewable energy infrastructure where multi-layer adhesive-lined constructions displace rigid conduit and cast resin systems.
- Wire Bundling:Harness organization and strain relief applications in automotive and industrial channels favor flexible polyolefin cut-length distribution with color-coding for circuit identification.
- Aerospace:FAA and EASA certification requirements govern fluoropolymer and adhesive-lined specifications for commercial and defense aircraft wire harnessing where weight reduction and fire-smoke toxicity standards drive material selection.
Electrical insulation maintains the largest application share, with mechanical protection gaining share fastest as offshore wind and telecom burial specifications multiply.
End User:
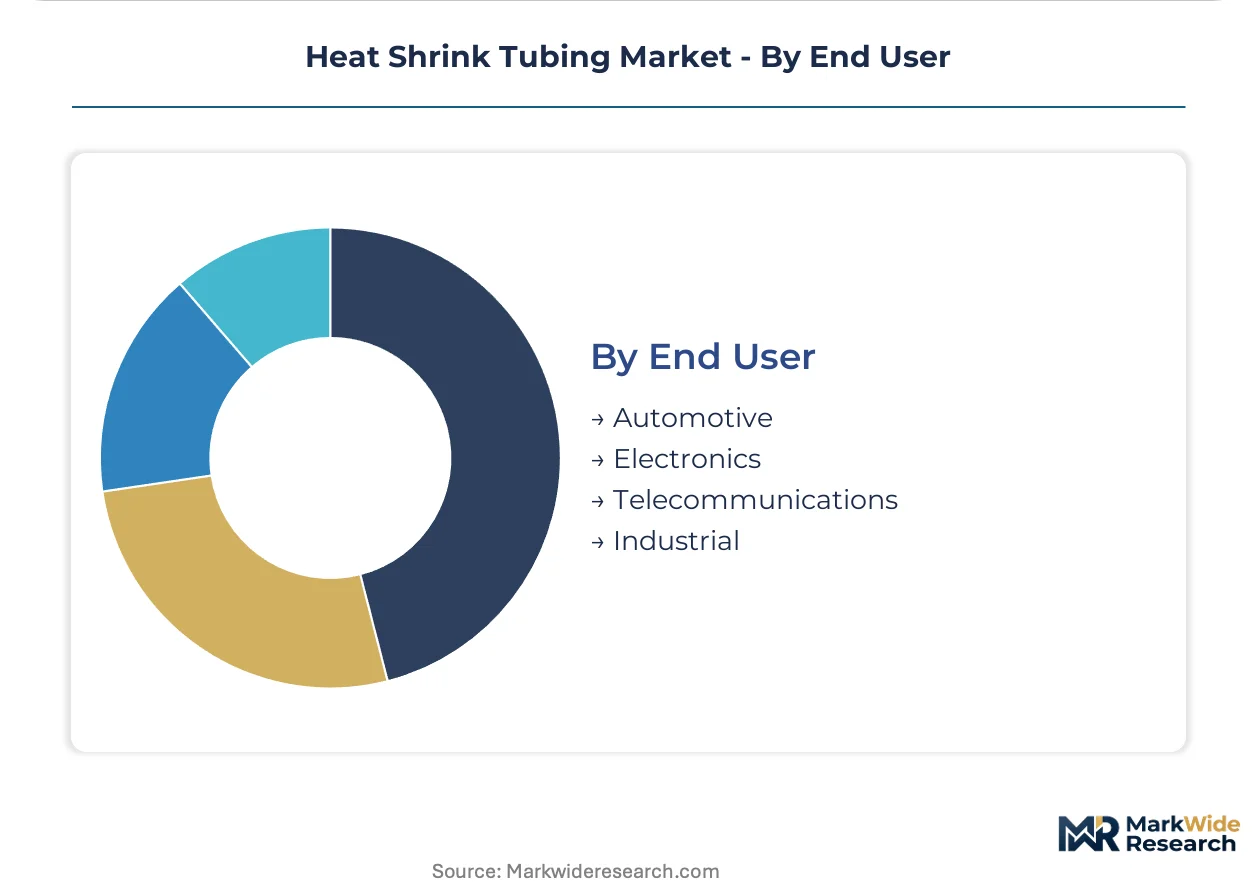
Customer-type concentration concentrates specification authority with fewer procurement teams at tier-one suppliers, compressing spot-market volumes while aftermarket cut-length distribution captures maintenance operations.
- Automotive:TE Connectivity, Yazaki, and Lear Corporation bundle tubing, connectors, and application tooling into single-source contracts covering German and Chinese OEM platform programs; high-voltage architectures demand thinner-wall, higher-temperature ratings from qualified suppliers.
- Industrial:Factory automation, process control, and heavy machinery channels specify halogen-free formulations meeting IEC and NFPA standards for confined-space installations.
- Electronics:Consumer device and appliance manufacturers prioritize cost-efficient flexible polyolefin for internal wire organization and strain relief.
- Telecommunications:Fiber-optic cable assembly and data center infrastructure procurement favors multi-layer constructions with crush resistance and thermal cycling durability for dense cable routing.
Automotive end users command the highest procurement volumes, with telecommunications representing the steepest expansion trajectory as data center and subsea cable investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands aerospace wire harness procurement volumes that exceed China's automotive cable assembly demand, though Shenzhen battery pack zones are closing the gap through MIIT-mandated high-voltage testing protocols.
Germany
KBA type-approval processes now require extended aging documentation for phosphorus-nitrogen flame retardant systems. The EU F-Gas Regulation accelerates procurement of low-GWP fluoropolymer alternatives across Baden-Württemberg and Bavaria manufacturing corridors. Stuttgart and Munich anchor aerospace wire harnessing programs where adhesive-lined and fluoropolymer grades dominate platform specifications.
China
MIIT GB standards testing for new energy vehicle high-voltage systems concentrates demand for adhesive-lined tubing. Dual carbon goals under MEE directives push compounders toward halogen-free formulations in Yangtze River Delta production zones. Shenzhen and Shanghai battery pack assembly zones specify integrated sealing solutions for consolidated electric vehicle architectures.
United States
UL certification requirements and SAE standards govern product qualification across automotive and industrial channels. EPA oversight of petrochemical complexes affects polyolefin resin supply clusters along the US Gulf Coast. Houston and Detroit corridors host tier-one wire harness supplier consolidation where bundled tubing-connector contracts compress spot-market volumes.
Japan
METI carbon neutrality roadmap prioritizes fluoropolymer tubing with verified life-cycle assessments for mass-transit infrastructure renewal. JIS standards compliance governs Shinkansen and urban rail electrification specifications. Kanto and Kansai manufacturing belts concentrate procurement for high-temperature rail applications.
India
PLI scheme for auto components drives localized cable assembly investments requiring halogen-free tubing meeting BIS certification timelines. CEA directives on electrical safety standards influence industrial procurement patterns. Tamil Nadu and Gujarat industrial corridors attract tier-one supplier capacity for domestic OEM platform programs.
Heat Shrink Tubing Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material science and installation tooling vectors. Market structure tilts toward consolidation as tier-one wire harness suppliers bundle procurement into single-source agreements covering tubing, connectors, and application equipment. Three archetypes dominate: integrated connector-tubing platforms, fluoropolymer specialization houses, and adhesive-lined technology developers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as converters seek qualified supply positions in consolidated automotive platform programs.
Among diversified industrial technology groups, TE Connectivity and 3M occupy positions spanning material science breadth and captive connector integration. Sumitomo Electric Industries exemplifies the fluoropolymer specialization archetype through its anchored presence in aerospace and mass-transit applications. These three entities represent the competitive tension between scale-driven platform bundling and targeted material expertise in high-performance segments.
| Leading Market Players |
|---|
| TE Connectivity |
| 3M |
| Sumitomo Electric Industries |
| HellermannTyton |
| ABB |
| Alpha Wire |
| Panduit |
| Prysmian Group |
| Amphenol |
| Others |
Supply Flow & Price Mechanics
Polyethylene resin price indices on the US Gulf Coast and Singapore commodity exchanges cascade through converter margins into three-tier pricing stratification across premium fluoropolymer, standard adhesive-lined, and economy flexible polyolefin grades. German automotive procurement teams leverage long-term offtake contracts to compress spot-market premiums, while Chinese battery pack assemblers accept shorter-term pricing to secure MIIT-compliant formulations.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade polyolefin tubing. Three-tier pricing separates aerospace-certified fluoropolymer from automotive-grade adhesive-lined from economy flexible constructions, with certification level and volume scale as primary differentiation drivers. Cost compression in the economy tier is intensifying because Middle Eastern resin exports displace regional compounders. Aftermarket distributors exhibit highest price sensitivity; aerospace wire harness programs show least.
Supply Chain Analysis
Direct-to-OEM channels handle tier-one wire harness supplier demand, while specialized distributors serve aftermarket cut-length requirements. Raw material supply draws from US Gulf Coast, Saudi Arabian, and Singaporean petrochemical complexes, with cross-linked polyolefin resin, fluoropolymer pellets, and thermoplastic adhesive pellets as critical inputs. Single-source vulnerability concentrates in fluoropolymer feedstock where limited qualified compounders serve aerospace certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Heat Shrink Tubing Market functions as a stable compounder where regulatory-driven material reformulation sustains replacement demand across automotive platform cycles.
For Market Incumbents: Deepen captive supply of halogen-free compound formulations to lock out REACH-compliant competitors. Secure ECHA registration dossiers early to compress qualification timelines that exclude later entrants. Add compounding capacity in Tamil Nadu to defend margin position against India PLI scheme localization. For New Entrants and Emerging Players: Capture subsea fiber-optic protection contracts where multi-layer adhesive-lined specifications displace rigid conduit. Penetrate India's BIS certification pipeline before tier-one suppliers localize. Lead with same-day cut-length fulfillment for maintenance operations that incumbents neglect. For Investors and Strategic Acquirers: Asymmetric upside sits with fluoropolymer specialization houses holding aerospace platform qualifications. Long-term viability hinges on sustained EU F-Gas Regulation phase-down timelines and Japan METI infrastructure renewal cycles. Watch Shinkansen electrification procurement volumes as inflection signal for mass-transit fluoropolymer demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyolefin Compounding | Captive resin formulation secures REACH compliance ahead of ECHA restriction timelines. |
| Long-term Supply Agreement with Tier-One Harness Suppliers | TE Connectivity and Yazaki bundled contracts compress spot-market volatility exposure. |
| Joint Venture in India PLI Corridor | Tamil Nadu cable assembly investments require localized BIS-certified halogen-free capacity. |
| Green Manufacturing Transition to Low-GWP Fluoropolymers | German KBA type-approval now mandates phosphorus-nitrogen flame retardant documentation. |
| Acquisition of Specialist Adhesive-Lined Technology Developer | Dual-wall construction expertise commands premium positioning in Shenzhen battery pack zones. |
Methodological Framework
Bottom-up wire harness modeling reconciled against top-down resin production tracking forms the analytical core. Primary interviews with tier-one supplier procurement directors, compounder R&D leads, automotive platform engineers, and aftermarket distribution managers combined with secondary validation from customs trade data, SEC 10-K filings, and MIIT GB standards documentation. Cross-referencing UL certification registries with SAE specification databases enabled triangulation of qualified supplier volumes.
Historical trendline analysis of aerospace wire harness procurement and automotive platform consolidation patterns informed projection frameworks across material type, application, and end-use segmentation. CAGRs derived from installation automation penetration curves and high-voltage architecture adoption rates. Fluoropolymer grade premiums and adhesive-lined substitution elasticities served as industry-specific forecast inputs.
Raw material price volatility, regulatory amendment timelines, and silicone cold-shrink substitution rates are the dominant revision risks. Forecasts reflect documented assumptions regarding REACH enforcement intensity and China MIIT testing protocol expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
FRP Pipe Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
Stainless Steel Welded Pipes Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Hydrogen Tube Skids Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Steel Pipe Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Qatar PVC Pipe Market
Pipes and Tubes
HDPE Pipes Market
Pipes and Tubes
Gathering Pipeline Market
Pipes and Tubes
Bahrain PVC Pipes Market
Pipes and Tubes
GCC CPVC Pipes Market