
 Saudi Arabia Masterbatch Market | 2026-2036
Saudi Arabia Masterbatch Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Masterbatch Market Intelligence
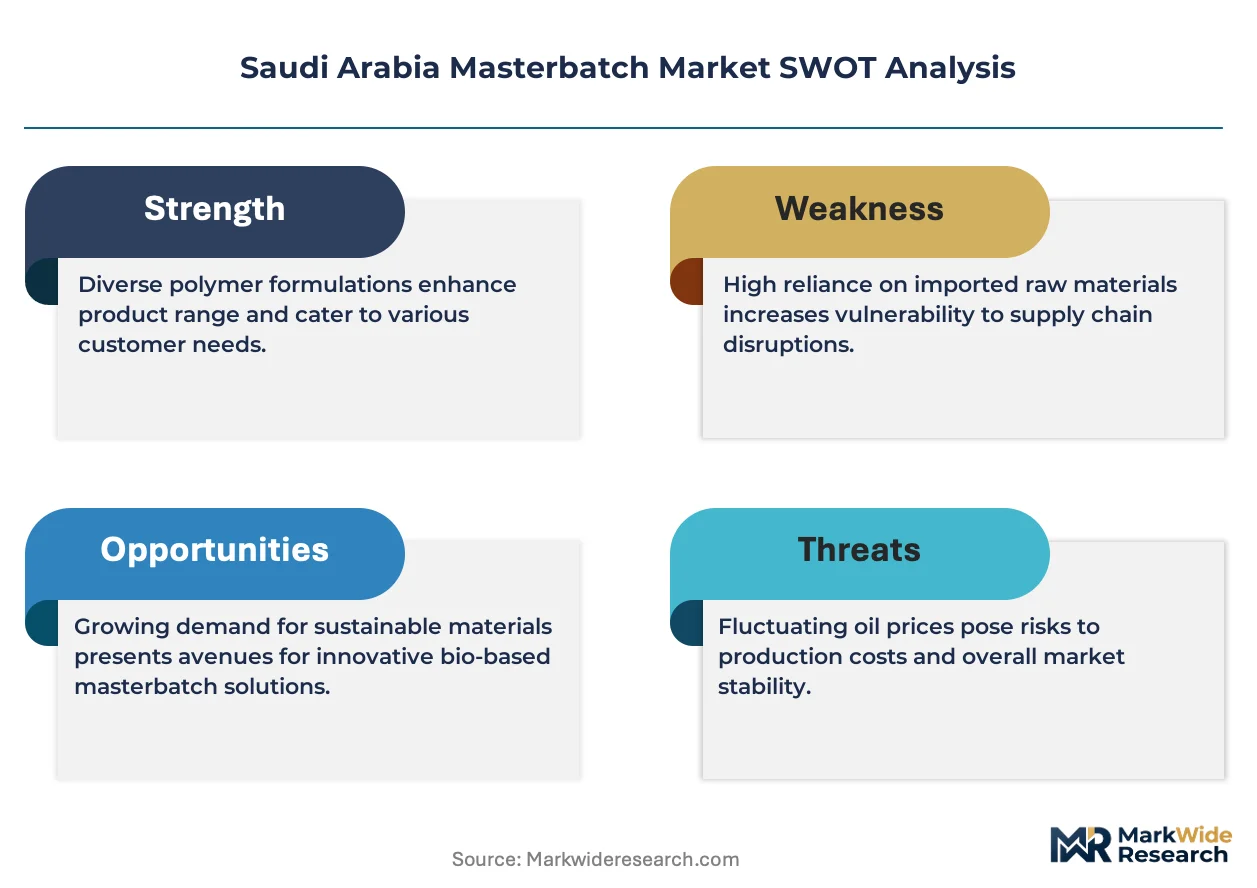
SASO technical regulations for plastic product safety is broadening the cost-of-entry calculus for imported masterbatch formulations. Clariant leverages its regional compounding infrastructure to sustain formulation leadership across color and additive portfolios. SABIC anchors domestic supply through captive polymer feedstock access and integrated masterbatch production at its Jubail complexes.
Masterbatch denotes concentrated mixtures of pigments, additives, or fillers dispersed in a polymer carrier resin, typically dosed at 1-5 wt% during thermoplastic processing to impart color, UV stability, or functional properties. Black masterbatch dominates volume consumption due to carbon black loading in polyethylene films for agricultural and geomembrane applications, while additive masterbatch commands premium positioning as processors seek halogen-free flame retardancy and anti-fog functionality for food packaging. Injection molding represents the largest application outlet, though blow molding for rigid container demand is expanding fastest among conversion technologies.
SASO mandates compliance with Gulf Standardization Organization (GSO) polymer contact regulations, while the Saudi Food and Drug Authority (SFDA) governs food-contact additive migration limits. These frameworks compel reformulation investments and restrict uncertified import channels. Stakeholders must monitor evolving SASO enforcement protocols and SFDA notification requirements to secure sustained market access.
Market Dynamics
SASO's phased enforcement of GSO polymer contact standards is compressing formulation approval timelines and forcing domestic compounding investments, restructuring competitive entry economics for imported masterbatch portfolios.
Growth Catalysts
- Flexible packaging film expansion:Converters in Jubail Industrial City are scaling blown film lines for agricultural mulch and food-grade laminates, pulling concentrated masterbatch demand for UV stabilization and oxygen barrier functionality.
- SFDA food-contact migration mandates:Tighter additive leachate thresholds for polyethylene terephthalate containers are compelling reformulation toward compliant carrier resins and certified pigment systems.
- Carbon black loading in geomembranes:Eastern Province infrastructure projects for water containment and landfill lining specify high-loading black masterbatch for polyethylene sheet durability, anchoring volume consumption.
Market Restraints
- Titanium dioxide pigment volatility:Feedstock cost swings for rutile and anatase grades compress margin predictability for white masterbatch producers serving Saudi converters.
- Import dependency for specialty additives:Halogen-free flame retardant and anti-fog chemistries concentrate among European and East Asian suppliers, exposing buyers to currency and logistics risk.
- SASO certification bottlenecks:Extended laboratory testing queues for polymer additive safety dossiers delay product registration and market entry for uncertified formulations.
Strategic Opportunities
- Neom and Red Sea Project construction:Giga-project infrastructure and tourism zone development will generate step-change demand for geomembrane, pipe, and cable jacketing applications requiring functional masterbatch.
- Recycled content mandates:Anticipated SASO circular economy regulations for post-consumer polyethylene incorporation will create pull for compatibilizer and odor-scavenging additive masterbatches.
- Digital color matching services:Cloud-based spectrophotometry and AI-driven formulation tools can compress custom color development cycles for Saudi brand owners and packaging designers.
Industry Challenges
- Polymer processing technologist scarcity:Specialized expertise in twin-screw extrusion and dispersion optimization for high-loading formulations remains concentrated among expatriate workforces in Jubail and Yanbu.
- Legacy ERP integration with batch traceability:Mid-scale compounders face capital and timeline pressure to deploy manufacturing execution systems capable of SASO-mandated lot tracking and recall documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Masterbatch Market |
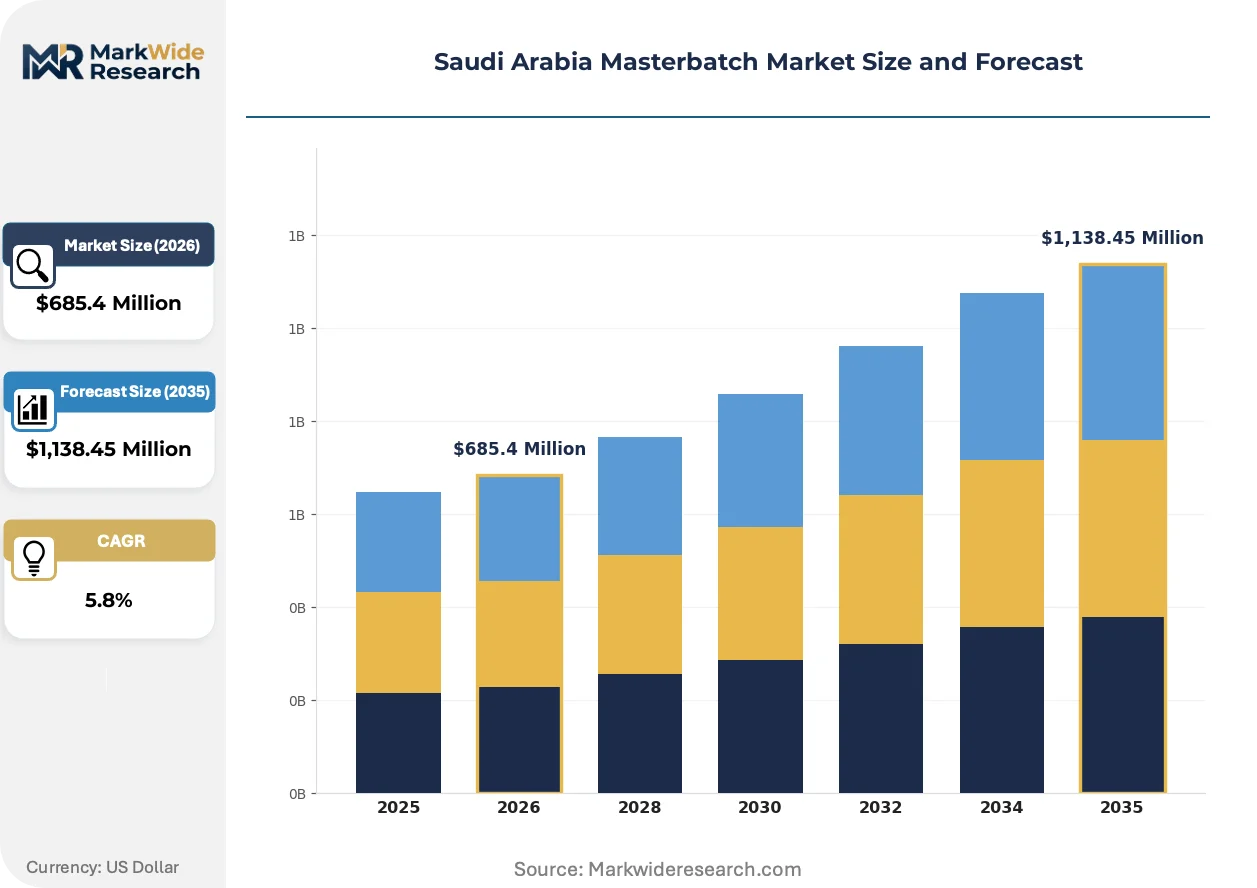
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Masterbatch, White Masterbatch, Color Masterbatch, Additive Masterbatch End User: Packaging, Automotive, Consumer Goods, Electrical & Electronics Form: Granules, Pellets, Powders, Liquid Application: Injection Molding, Blow Molding, Extrusion, Films |
| Companies Covered | Clariant, Cabot Corporation, SABIC, Pure Polymers, Al-Hussan Plastic Co., Astra Polymers, Ampacet Corporation, Ingenia Polymers Co. Ltd., Avient Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Masterbatch Market Strategic Shifts & Innovations
Masterbatch formulation science is converging with digital manufacturing controls and circular material specifications, compressing development cycles while expanding functional performance boundaries for Saudi processors.
Multi-functional additive concentrates are unifying previously separate processing aids, stabilizers, and surface modifiers into single-pellet systems. Blow molding converters for rigid containers are adopting these integrated formulations to reduce dosing complexity and inventory SKUs. This unification is compressing the traditional tiering between commodity color concentrates and premium functional grades, enabling mid-market processors to access performance previously gated by formulation expertise.
SASO's alignment with GSO 2231 for plastic product safety is tightening documentary evidence requirements for additive migration testing. The regulation compels compounders to maintain accredited laboratory partnerships and structured technical files for each formulation variant. Food-contact packaging segments are responding by consolidating supplier relationships toward vertically integrated compounders with captive testing capabilities.
Brand owners in Riyadh and Jeddah are compressing color development cycles through direct collaboration with masterbatch technical service teams, bypassing traditional distributor-mediated specification processes. This disintermediation is most visible in personal care and dairy packaging verticals, where seasonal promotional launches demand four-week turnaround from concept to production batch approval.
Saudi Arabia Masterbatch Market Segmentation
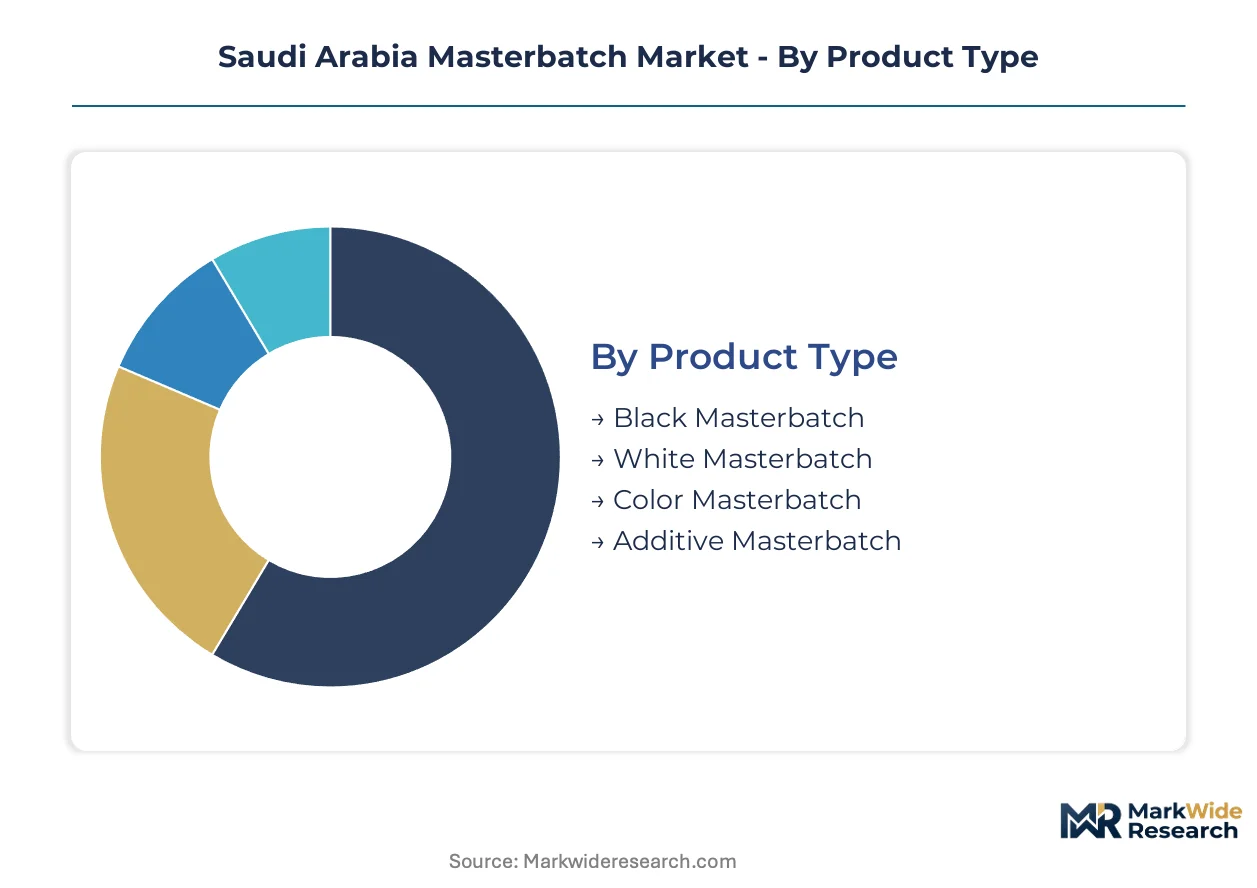
Masterbatch segmentation in Saudi Arabia reflects the interplay between petrochemical feedstock proximity, SASO compliance requirements, and conversion technology specialization across the Eastern Province industrial corridor. Distinct product categories serve fundamentally different value chains—from commodity black concentrates for geomembranes to precision additive systems for food-contact packaging.
Product Type:
Black and white masterbatches operate as standalone commodity inputs with high volume throughput, while color and additive grades embed deeper into customer-specific formulation partnerships.
- Black Masterbatch:Carbon black concentrates dispersed in polyethylene or polypropylene carriers, formulated at 20-50% pigment loading for UV absorption and weathering resistance. Demand concentrates in Eastern Province infrastructure projects—Jubail Industrial City geomembrane producers specify high-loading grades for water containment and landfill lining applications, anchored by SABIC captive polymer supply.
- White Masterbatch:Titanium dioxide-based concentrates in PE, PP, or PS carriers, delivering opacity and brightness at 30-70% TiO2 loading. Riyadh and Jeddah packaging converters drive procurement for dairy containers and personal care bottles, though rutile feedstock cost volatility compresses margin predictability for compounders serving these accounts.
- Color Masterbatch:Custom pigment dispersions matched to brand-specific Pantone specifications, requiring spectrophotometric calibration and lot-to-lot consistency.
- Additive Masterbatch:Functional concentrates delivering flame retardancy, anti-fog, anti-static, or oxygen barrier properties through active chemistry rather than color.
Volume placements concentrate in Black Masterbatch; the faster expansion belongs to Additive Masterbatch.
End User:
Customer segmentation tracks the divergence between high-volume packaging procurement with standardized specifications and automotive or electronics accounts demanding certified migration compliance.
- Packaging:Flexible film converters and rigid container molders across Jubail, Riyadh, and Jeddah represent the dominant demand pool. Blown film lines for agricultural mulch and food-grade laminates pull UV stabilization and oxygen barrier masterbatches, while SFDA migration mandates compel reformulation toward compliant carrier resins.
- Automotive:Interior and under-hood component suppliers specify heat-stabilized and UV-resistant concentrates for polypropylene fascia and bumper applications.
- Consumer Goods:Appliance housings, furniture components, and housewares molders source color-matched grades with processing aid integration.
- Electrical & Electronics:Cable jacketing and connector manufacturers require halogen-free flame retardant masterbatches meeting Gulf Standardization Organization safety protocols.
Packaging commands the dominant share of volume; Electrical & Electronics posts the steepest expansion trajectory as infrastructure electrification accelerates.
Form:
Physical form selection hinges on dosing equipment compatibility, dust containment requirements, and dispersion efficiency across extrusion and molding platforms.
- Granules:Irregular-shaped particles produced via strand pelletizing, offering cost-efficient dosing for non-critical color applications in large-volume extrusion.
- Pellets:Precision-cut cylindrical or spherical particles with consistent dimensions for automated gravimetric feeding systems. Injection molding operations across Yanbu and Jubail prefer pelletized grades for dispersion uniformity in thin-wall packaging.
- Powders:Micronized masterbatch for rotational molding and PVC compounding where melt incorporation challenges exist.
- Liquid:Pumpable dispersions for continuous dosing in extrusion lines handling transparent films or sheet where pellet melting delays create defects.
Pellet form dominates current placements; Liquid masterbatch is climbing the fastest as blown film line speeds increase.
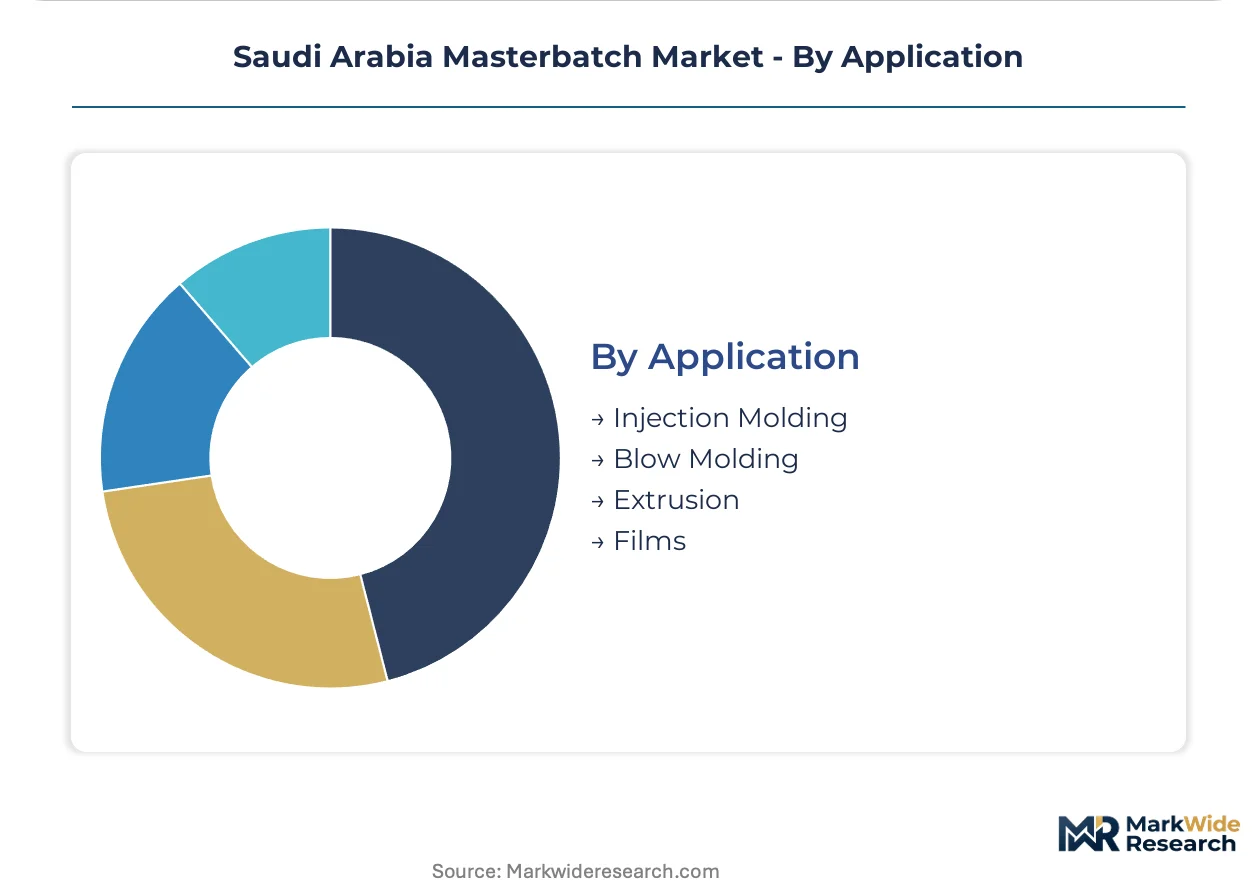
Application:
Conversion technology segmentation reveals divergent masterbatch performance requirements—shear stability for injection molding versus dispersion tolerance for film extrusion.
- Injection Molding:High-shear processing of polypropylene and polyethylene articles demands masterbatches with thermal stability above 280°C and rapid pigment dispersion to prevent streaking. Riyadh automotive and consumer goods molders represent the core demand cluster.
- Blow Molding:Extrusion blow molding for HDPE containers and stretch blow molding for PET bottles requires masterbatches with balanced melt flow for parison stability. Jeddah dairy and beverage packaging converters are scaling this application most aggressively.
- Extrusion:Pipe, profile, and sheet extrusion across Neom and Red Sea Project sites pulls high-loading black and functional additive grades.
- Films:Blown and cast film lines for agricultural mulch, stretch wrap, and barrier laminates require UV stabilizer and anti-fog masterbatches with low gel formation.
Injection Molding anchors volume consumption; Blow Molding is gaining share fastest among conversion technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City's special economic zone incentives concentrate masterbatch production capacity within the Eastern Province petrochemical corridor. Royal Commission for Jubail and Yanbu tax holidays and subsidized utility rates pull compounding investments toward this coastal cluster. Domestic formulation capabilities are expanding fastest in zones with captive polymer feedstock access.
Eastern Province
Blown film converters serving agricultural mulch and geomembrane applications dominate masterbatch procurement volumes. SASO polymer contact regulations enforce GSO 2231 compliance for all locally produced formulations. Jubail Industrial City houses integrated masterbatch operations leveraging SABIC polyethylene supply for carbon black concentrates.
Riyadh
Injection molding operations for automotive fascia and consumer goods housings require heat-stabilized color concentrates with thermal stability above 280°C. SFDA notification requirements govern food-contact additive migration limits for dairy packaging processors. Second Industrial City compounders are scaling custom color matching services for personal care brand owners.
Western Region
Jeddah's rigid container manufacturers specify UV-resistant masterbatches for beverage and dairy packaging exposed to Red Sea coastal humidity. Saudi Food and Drug Authority mandates tightened leachate thresholds for polyethylene terephthalate containers. King Abdullah Economic City logistics infrastructure enables just-in-time masterbatch delivery to blow molding converters.
NEOM Northwest
Giga-project infrastructure development will generate demand for geomembrane, pipe, and cable jacketing applications requiring functional additive concentrates. Anticipated SASO circular economy regulations for post-consumer polyethylene incorporation will pull compatibilizer masterbatches. Oxagon industrial zone planning includes dedicated polymer compounding facilities for construction-grade formulations.
Saudi Arabia Masterbatch Market Key Industry Players
Domestic producers anchored by SABIC captive feedstock access hold one tier; European and North American specialists with certified food-contact portfolios occupy another. The vendor base stratifies across three tiers: integrated petrochemical giants with backward polymer control, regional compounders with SASO testing capabilities, and import-dependent distributors serving niche color matching. Strategic moves center on domestic compounding investments to bypass certification bottlenecks and cloud-based color formulation services to compress development cycles.
Within the integrated petrochemical tier, SABIC and Clariant exemplify divergent sourcing strategies. SABIC leverages captive polyethylene production at Jubail complexes for high-volume black masterbatch supply. Clariant, a Swiss specialty chemicals company, sustains formulation leadership through regional compounding infrastructure and accredited laboratory partnerships. Cabot Corporation, a US-based materials science company, anchors carbon black concentrate supply for geomembrane and agricultural film applications.
| Leading Market Players |
|---|
| Clariant |
| Cabot Corporation |
| SABIC |
| Pure Polymers |
| Al-Hussan Plastic Co. |
| Astra Polymers |
| Ampacet Corporation |
| Ingenia Polymers Co. Ltd. |
| Avient Corporation |
| Others |
Cost & Logistics Intelligence
Carbon black pigment costs cascade from European and North American specialty chemical producers through three distinct pricing tiers—premium certified grades for SFDA-compliant food packaging, standard industrial grades for geomembrane applications, and economy spot-market concentrates for non-critical agricultural film. This input-cost architecture compresses margin flexibility for Saudi compounders lacking backward integration into carbon black production.
Pricing Analysis
Short lead-time premiums command substantial markups as Jeddah blow molding converters pay elevated rates for four-week color-matching turnaround versus standard eight-week cycles. Three-tier pricing structure across premium, standard, and economy levels separates SASO-certified food-contact formulations from industrial-grade carbon black concentrates and uncertified import alternatives. Pricing pressure stems from titanium dioxide feedstock volatility as rutile ore costs swing unpredictably for white masterbatch producers. Packaging converters in Riyadh exhibit highest price sensitivity, while Neom infrastructure contractors absorb premium functional additive costs without volume negotiation.
Supply Chain Analysis
Halogen-free flame retardant chemistry rests on German, Swiss, and Japanese specialty additive producers, creating import dependency for Saudi cable jacketing and electronics housing manufacturers. Carbon black concentrates draw from United States, Belgium, and South Korean producers, while titanium dioxide pigment feeds from Chinese and Australian mineral processors. Single-source vulnerability concentrates in anti-fog and oxygen barrier additive categories where two European suppliers dominate global capacity. Distribution runs through Jubail Industrial City compounders with captive SABIC polymer access, then fans to Riyadh injection molders and Jeddah blow molding converters via King Abdullah Economic City logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-functional additive masterbatches are displacing single-property concentrates as Saudi processors seek inventory simplification and dosing efficiency across blown film and blow molding lines.
For Market Incumbents: Cement formulation leadership by deepening captive laboratory partnerships for SASO GSO 2231 compliance documentation, insulating against certification bottlenecks that delay rival market entry. Expand pelletizing capacity in Jubail Industrial City to capture Neom geomembrane and infrastructure cable demand before project construction peaks. Vertical integration into carbon black compounding represents the critical lever for margin defense against titanium dioxide volatility. For New Entrants and Emerging Players: Digital color matching platforms offer the most penetrable wedge for Riyadh and Jeddah personal care packaging brand owners seeking compressed development cycles. Target mid-scale blow molding converters in Second Industrial City with cloud-based spectrophotometry services bypassing traditional distributor relationships. White-space opportunity concentrates in compatibilizer masterbatches for anticipated SASO recycled content mandates. For Investors and Strategic Acquirers: Clariant's sustained regional compounding investments signal that accredited laboratory infrastructure is the leading indicator that formulation capabilities are consolidating toward vertically integrated specialists. Long-term viability favors compounders with captive polymer feedstock access and SFDA testing partnerships over import-dependent distributors. Acquisition target archetype: mid-scale Eastern Province compounders with SASO certification backlog and underutilized twin-screw extrusion capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Black Compounding | SABIC's Jubail complexes anchor domestic supply against import cost volatility. |
| Accredited Laboratory Partnership Expansion | SFDA migration testing capabilities compress rival registration timelines. |
| Digital Color Matching Platform Launch | Cloud-based spectrophotometry disintermediates distributor-mediated specification processes. |
| Compatibilizer Masterbatch Development | Anticipated SASO circular economy regulations create first-mover positioning. |
| Neom Infrastructure Supply Agreement | Oxagon industrial zone construction pulls geomembrane and cable jacketing demand. |
Research Approach
Independent corroboration across masterbatch plant managers in Jubail and Yanbu, procurement leads at Eastern Province packaging converters, and distribution channel partners in King Abdullah Economic City underwrites the qualitative findings. Secondary validation draws from SASO technical regulation filings, SABIC annual disclosures, Gulf Standardization Organization polymer contact standards, and customs trade data for carbon black and titanium dioxide imports. Bottom-up demand modeling triangulates against top-down petrochemical feedstock consumption patterns.
Rate-of-change decomposition across the analysis window segments volume trajectories by product type, end-use industry, conversion technology, and regional industrial cluster. CAGRs derive from weighted average of segment-level growth rates calibrated to polymer processing capacity expansion announcements. Key forecast inputs include blown film line installation rates in Jubail Industrial City and SFDA notification timelines for food-contact additive approvals.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended SASO certification queues or abrupt titanium dioxide supply disruptions. Assumptions reflect current regulatory enforcement intensity and petrochemical feedstock pricing regimes. A small set of named triggers—SASO circular economy regulation promulgation, Neom construction acceleration, and European halogen-free flame retardant supply constraints—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Germany Collagen Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
GCC Specialty Chemicals Market
Specialty Compounds
Furniture Foam Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Global Black Masterbatch Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Hydrotalcite Market
Specialty Compounds
Putty Fillers Market
Specialty Compounds
United States Caustic Potash Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
EPDM Sealing Strip Market
Specialty Compounds
Potassium Derivatives Market