
 United States Caustic Potash Market | 2026-2036
United States Caustic Potash Market Size, Share, and Industry Trends Forecast 2026-2036
United States Caustic Potash Market Intelligence
Sodium hydroxide is shifting toward caustic potash in specialized food-grade and pharmaceutical applications where potassium ion compatibility reduces downstream processing costs. Occidental Chemical Corporation leverages integrated chlor-alkali infrastructure across the Gulf Coast to secure feedstock economics. ASHTA Chemicals anchors its position through membrane-cell technology leadership and consistent flake-grade output. Tessenderlo Group competes via European process expertise transferred to its North American operations.
Caustic potash, chemically potassium hydroxide (KOH), is an inorganic compound produced through electrolysis of potassium chloride brine in mercury-free membrane cells, typically yielding 90% purity flake or 45-50% liquid solution concentrations. Its primary industrial purpose centers on pH regulation, saponification reactions, and potassium nutrient delivery across agricultural and chemical processing systems. Liquid formulations dominate volume throughput in water treatment and fertilizer blending due to handling efficiency, while flake grades command margin premiums in pharmaceutical and personal care applications where dissolution control matters. The agriculture end-user segment sustains baseline demand through seasonal potassium replenishment cycles, though chemical industry procurement is diversifying into high-purity pellets for specialty catalyst manufacturing.
EPA standards under the Safe Drinking Water Act and OSHA permissible exposure limits shape product handling protocols and purity certification requirements for domestic manufacturers. FDA food additive regulations and USP monograph compliance create tiered qualification barriers that filter marginal suppliers from pharmaceutical and food processing channels. Stakeholders must monitor membrane-cell energy intensity against rising industrial electricity rates in the Ohio River Valley and Texas Gulf Coast production zones.
Market Dynamics
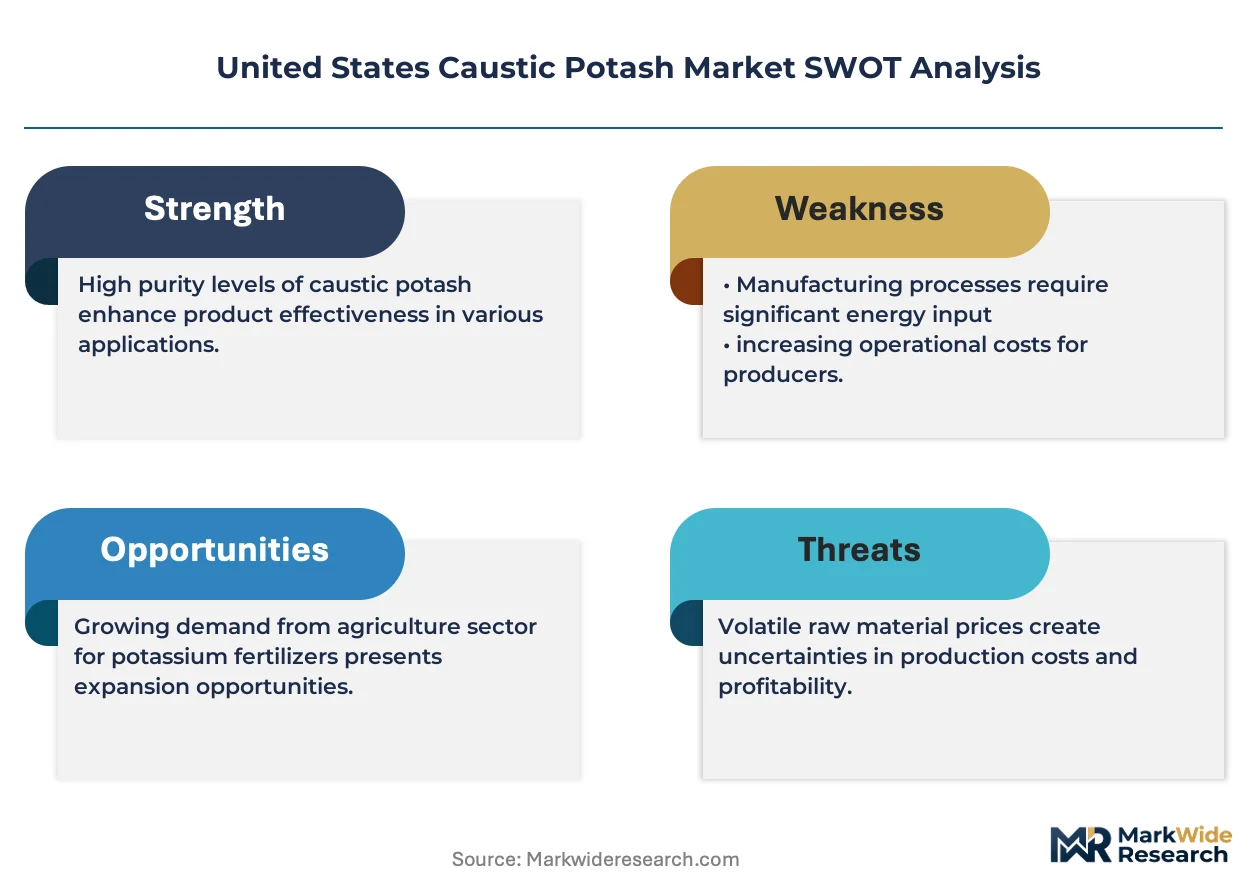
Membrane-cell electrolysis technology is consolidating production economics across the Ohio River Valley, compressing legacy mercury-cell capacity while tightening EPA purity mandates reshape qualification barriers for municipal and pharmaceutical buyers.
Growth Catalysts
- EPA Safe Drinking Water Act mandates:Municipal water treatment facilities are upgrading pH regulation systems to meet stricter contaminant limits, expanding specification-grade caustic potash procurement volumes.
- Potassium-based fertilizer blending:Midwest agricultural cooperatives are intensifying seasonal replenishment cycles as soil potassium depletion accelerates in high-yield corn-soy rotations.
- Membrane-cell technology diffusion:Mercury-free electrolysis platforms are displacing legacy production assets, enabling flake-grade output consistency for pharmaceutical and personal care channels.
Market Restraints
- Potassium chloride feedstock volatility:Saskatchewan potash mining concentration exposes domestic KOH producers to rail logistics disruptions and Canadian supply contract renegotiations.
- Industrial electricity rate escalation:Ohio River Valley and Texas Gulf Coast manufacturing zones face rising grid costs that compress membrane-cell operating margins.
- Sodium hydroxide substitution in commodity applications:Caustic soda retains cost advantage in non-potassium-sensitive pH regulation, limiting KOH penetration in mass-market water treatment.
Strategic Opportunities
- Food-grade certification expansion:FDA direct food additive status for KOH in cocoa processing and olive curing is opening specialty ingredient channels beyond traditional industrial buyers.
- High-purity pellet formats:Catalyst manufacturing and battery electrolyte applications are demanding low-carbonate pellet grades that command margin premiums over standard flake.
- Pharmaceutical USP monograph compliance:USP-grade KOH qualification is filtering marginal suppliers, creating consolidation opportunities for membrane-cell operators with validated quality systems.
Industry Challenges
- Electrolysis technician skill scarcity:Membrane-cell maintenance and brine purification optimization require specialized chlor-alkali expertise concentrated among retiring workforce cohorts.
- Multi-agency certification timelines:Simultaneous EPA, FDA, and USP qualification processes extend product launch cycles for new purity grades or facility expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Caustic Potash Market |
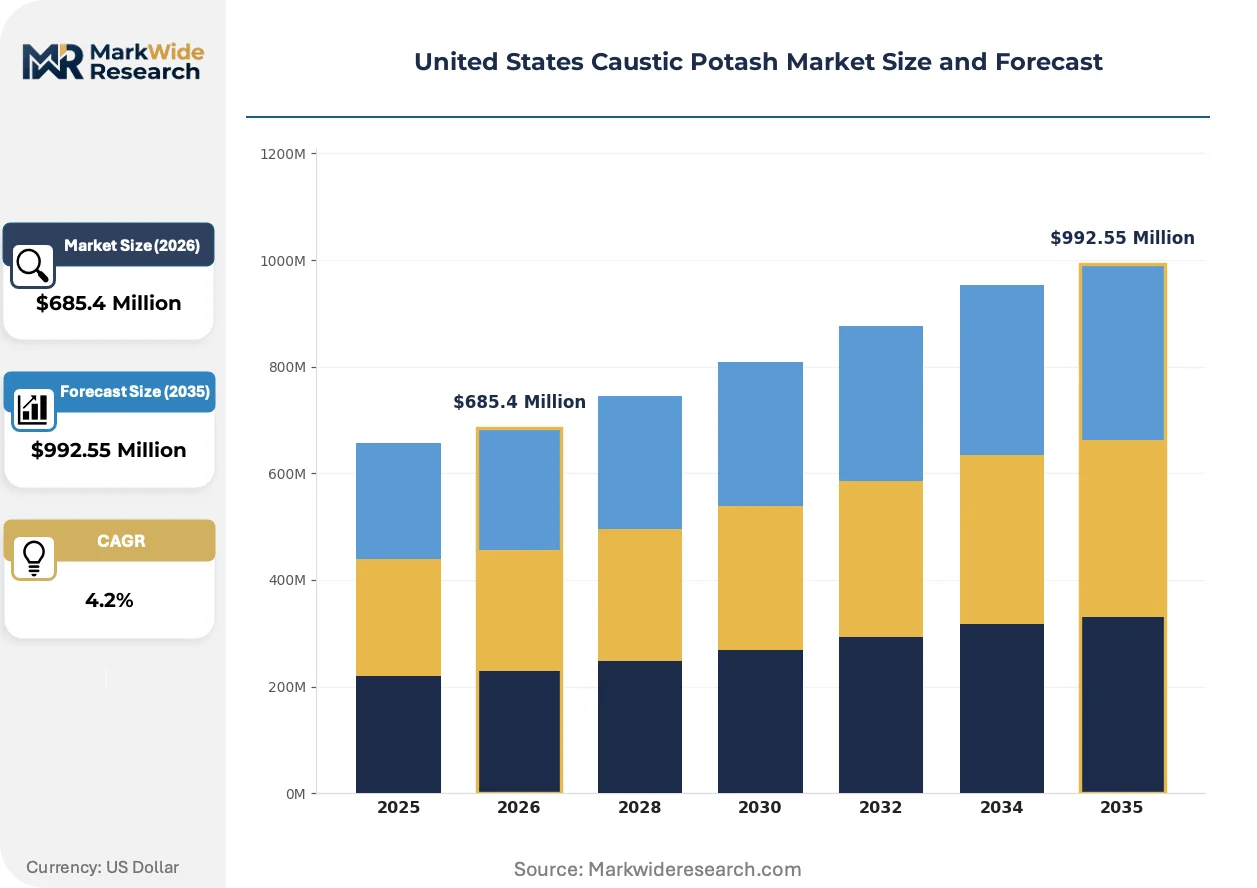
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Solid, Liquid, Pellets Application: Fertilizers, Pharmaceuticals, Food Processing, Water Treatment End User: Agriculture, Chemical Industry, Manufacturing, Personal Care Distribution Channel: Wholesale, Retail, Direct Sales, Online |
| Companies Covered | Tessenderlo Group, Armand Products Company, Occidental Chemical Corporation, Intercontinental Chemical Corporation, ASHTA Chemicals, Olin Corporation, The Mosaic Company, Cogent Chemical, FMC Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Caustic Potash Market Strategic Shifts & Innovations
Electrification of chemical process heat and digital twin deployment in brine electrolysis are compressing energy intensity while predictive maintenance platforms reshape asset utilization economics across domestic production corridors.
Advanced membrane-cell architectures with reinforced perfluorinated ionomer layers are unifying current efficiency and product purity in single-reactor designs. Specialty chemical manufacturers operating catalyst and pharmaceutical lines are adopting these platforms at replacement cycle pace. The technology is unifying previously separate purification stages, reducing capital footprint for USP-grade flake production.
OSHA permissible exposure limit revisions for potassium hydroxide aerosols are tightening workplace monitoring protocols and respiratory protection mandates. Chlor-alkali facilities are retrofitting ventilation and containment systems to meet the stricter 8-hour time-weighted average thresholds. Food processing and personal care compounders face the steepest compliance adaptation costs due to open-handling operations.
Direct procurement contracts between agricultural cooperatives and Ohio River Valley producers are displacing traditional distributor intermediaries in fertilizer-grade liquid KOH channels. Large Midwest grain handlers are negotiating seasonal volume commitments with membrane-cell operators, securing freight-advantaged supply against Gulf Coast import competition. This pattern concentrates most visibly across Illinois, Indiana, and Iowa corn-belt procurement offices.
United States Caustic Potash Market Segmentation
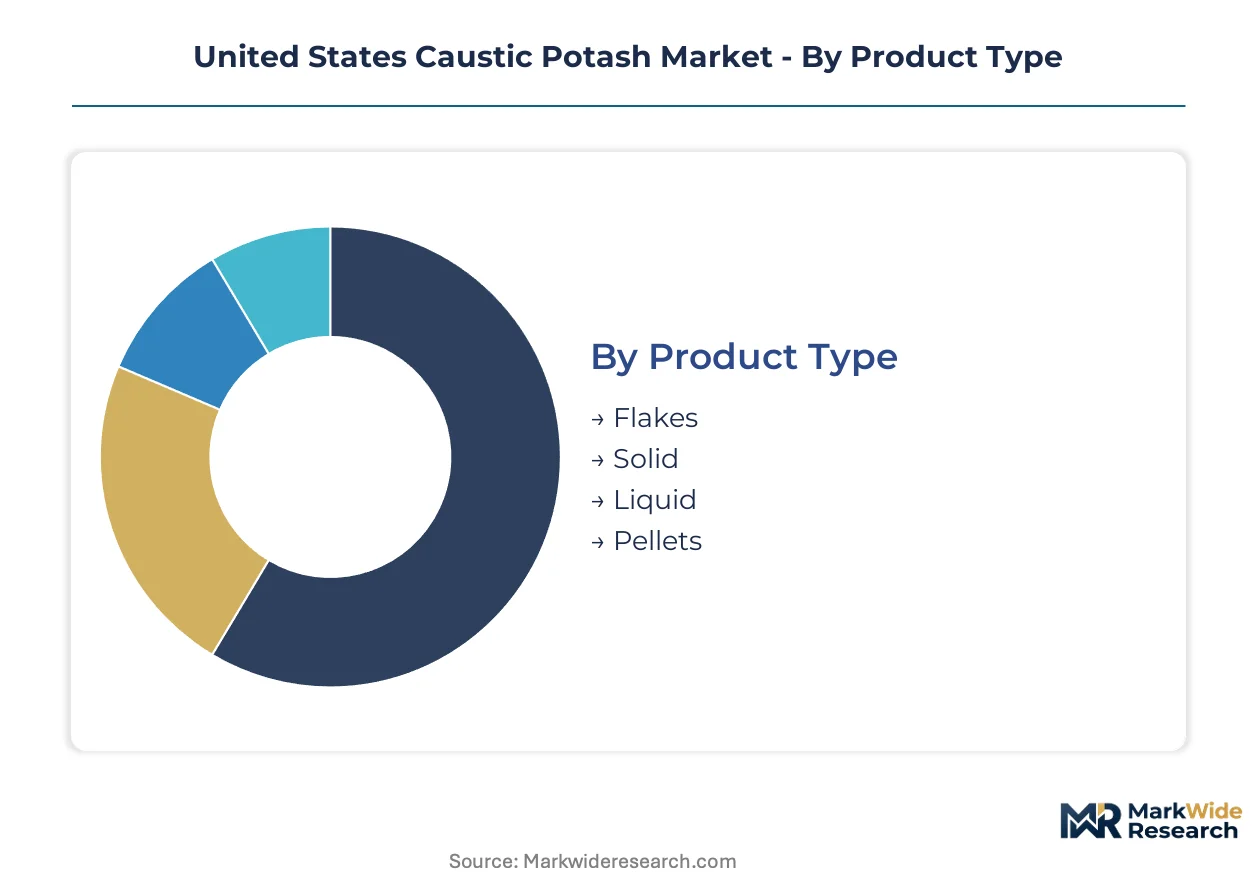
Caustic potash procurement patterns diverge sharply across physical formats and purity grades. Buyers select product types based on dissolution kinetics and handling infrastructure. Application-driven demand concentrates in regulated channels with tiered certification barriers.
Product Type:
Buyers prioritize dissolution control and storage footprint when selecting among physical formats.
- Flakes:Thin, crystalline sheets with 90% purity deliver controlled dissolution rates for pharmaceutical compounding and personal care formulation. Midwest chemical processors favor flake grades for catalyst manufacturing where carbonate contamination must stay below 0.5%. Premium pricing reflects validated USP monograph compliance and membrane-cell production consistency.
- Liquid:45-50% aqueous solutions dominate volume throughput in agricultural fertilizer blending and municipal water treatment. Ohio River Valley membrane-cell operators supply bulk liquid to Illinois and Iowa cooperatives via dedicated tanker contracts. Handling efficiency and reduced dust exposure drive procurement preference over solid formats in high-volume applications.
- Solid:Dense block or lump formats serve industrial pH regulation in steel pickling and battery manufacturing where slow-release alkalinity is acceptable.
- Pellets:Spherical, low-dust granules command margin premiums in automated handling systems for food processing and specialty catalyst production.
Liquid leads on scale; pellets lead on momentum.
Application:
Regulatory certification requirements segment buyers into tiered qualification pathways.
- Fertilizers:Potassium hydroxide supplies ionic potassium for corn-soy rotation replenishment across the Midwest corn belt. Seasonal procurement spikes align with spring planting windows. Ohio River Valley producers secure direct contracts with grain handlers, bypassing traditional distributor markups.
- Water Treatment:EPA Safe Drinking Water Act mandates drive specification-grade procurement for pH adjustment and corrosion control. Municipal facilities in the Ohio River Valley and Texas Gulf Coast upgrade systems to meet stricter contaminant limits.
- Pharmaceuticals:USP-grade material for active pharmaceutical ingredient synthesis and laboratory reagent preparation.
- Food Processing:FDA direct food additive status enables cocoa alkalization and olive curing applications with validated purity documentation.
Fertilizers lead on scale; pharmaceuticals lead on momentum.
End User:
Volume concentration and margin capture split across commodity and specialty procurement patterns.
- Agriculture:Midwest cooperatives and grain handlers drive baseline demand through seasonal potassium replenishment cycles. Direct procurement agreements with membrane-cell operators displace distributor intermediaries.
- Chemical Industry:Catalyst manufacturers and battery electrolyte producers demand high-purity pellet and flake grades. Specialty chemical processors in the Ohio River Valley corridor absorb premium-priced material for precision pH control.
- Manufacturing:Industrial pH regulation in textiles, petroleum refining, and metal finishing operations.
- Personal Care:Saponification reactions for liquid soap and cosmetic formulation require food-grade or USP-certified flake material.
Agriculture leads on scale; chemical industry leads on momentum.
Distribution Channel:
Supply chain configuration determines freight economics and inventory carrying costs for buyers.
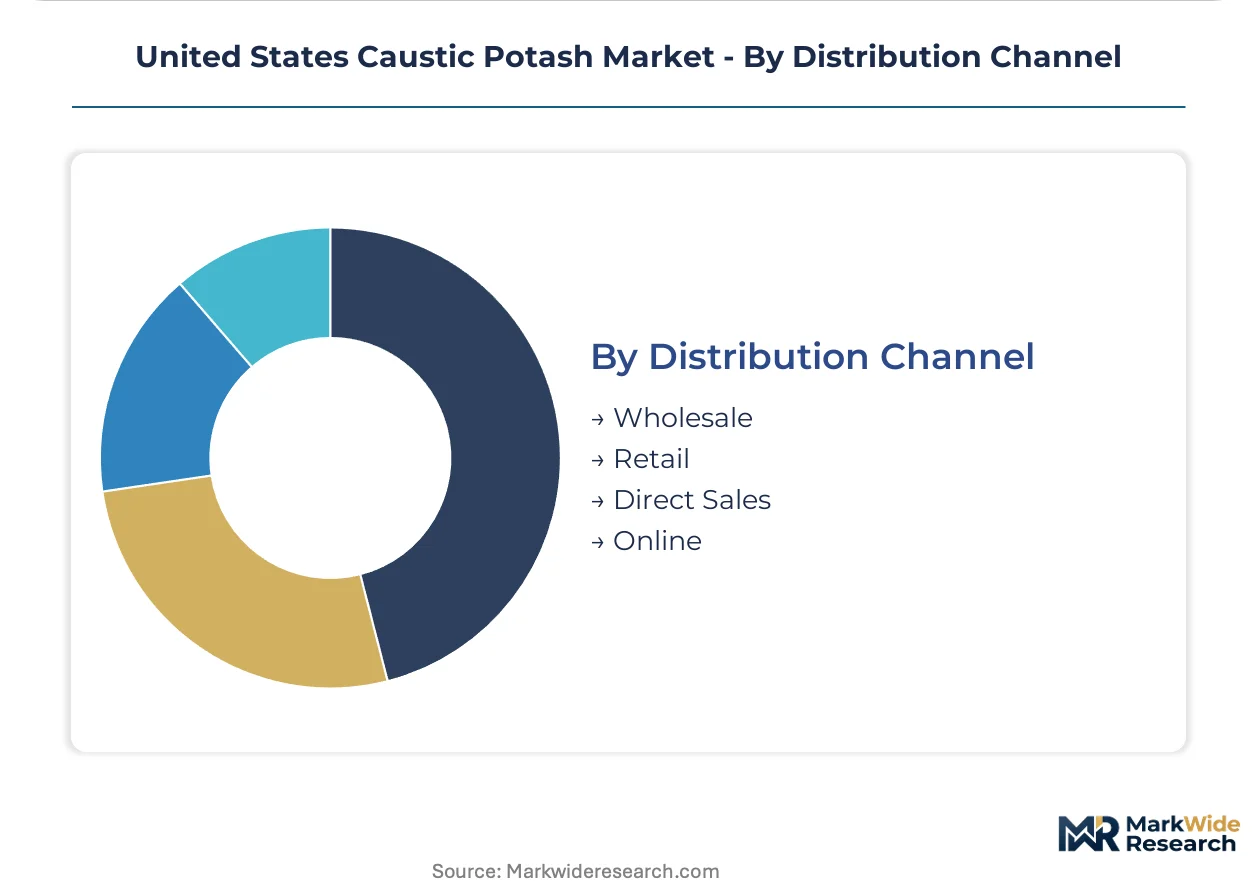
- Direct Sales:Large agricultural cooperatives negotiate seasonal volume commitments with Ohio River Valley producers, securing rail-advantaged supply and bypassing distributor margins. Illinois, Indiana, and Iowa procurement offices concentrate this pattern.
- Wholesale:Regional distributors stock liquid and flake grades for smaller chemical processors and water treatment facilities lacking tank farm infrastructure.
- Retail:Limited channel serving small-scale personal care compounders and laboratory end-users via packaged flake and pellet formats.
- Online:Emerging channel for specialty-grade samples and documentation-heavy pharmaceutical procurement with digital certificate transfer.
Direct sales leads on scale; online leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ohio River Valley chemical manufacturing corridor anchors United States caustic potash production capacity, with membrane-cell operators concentrated across Ohio, Kentucky, and West Virginia. EPA water treatment mandates and Midwest agricultural procurement patterns shape sub-regional demand distribution. Production economics favor locations with integrated chlor-alkali infrastructure and rail access to Saskatchewan potash feedstock sources.
Ohio River Valley
Membrane-cell electrolysis facilities in Ohio and Kentucky supply bulk liquid caustic potash to Illinois and Iowa agricultural cooperatives. EPA Safe Drinking Water Act compliance upgrades drive municipal procurement from Cincinnati and Louisville water authorities. The Huntington-Ashland metropolitan area hosts specialty flake production for pharmaceutical channels.
Texas Gulf Coast
Integrated chlor-alkali complexes along the Houston Ship Channel leverage feedstock economics for fertilizer-grade liquid output. OSHA permissible exposure limit revisions are forcing ventilation retrofits at Baytown and Beaumont processing sites. Corpus Christi chemical terminals handle import competition from Mexican and Asian suppliers.
Midwest Agricultural Belt
Illinois, Indiana, and Iowa grain handlers negotiate direct procurement contracts with Ohio River Valley producers, bypassing traditional distributors. Seasonal potassium replenishment cycles for corn-soy rotations concentrate demand in spring planting windows. Des Moines and Indianapolis cooperative offices coordinate volume commitments with membrane-cell operators.
Southeast Manufacturing Corridor
Personal care and food processing compounders in Georgia and North Carolina source USP-grade flake for saponification and cocoa alkalization applications. FDA direct food additive compliance requirements filter supplier qualification to validated membrane-cell producers. Atlanta distribution hubs consolidate freight logistics for smaller regional processors.
Pacific Northwest
Specialty battery electrolyte and catalyst manufacturers in Oregon and Washington demand high-purity pellet grades with carbonate contamination below 0.5%. Portland-area chemical processors absorb premium-priced material for precision pH control applications. Limited domestic production forces reliance on Ohio River Valley rail shipments.
United States Caustic Potash Market Key Industry Players
Global majors compete with regional champions across membrane-cell technology and feedstock integration. The United States caustic potash market exhibits consolidated structure around integrated chlor-alkali operators with legacy infrastructure advantages. Three archetypes dominate: Gulf Coast integrated petrochemical conglomerates, Ohio River Valley membrane-cell specialists, and European multinationals with transferred process expertise. Competitive dynamics center on backward integration into potassium chloride supply and USP-grade certification expansion.
Among integrated operators, Occidental Chemical Corporation exemplifies the Gulf Coast archetype with captive feedstock economics. ASHTA Chemicals anchors the Ohio River Valley specialist tier through membrane-cell technology leadership. Tessenderlo Group represents European process expertise transferred to North American operations. These three occupy positions across the technology-certification matrix, with differentiation concentrated in flake-grade consistency and multi-agency qualification breadth.
| Leading Market Players |
|---|
| Tessenderlo Group |
| Armand Products Company |
| Occidental Chemical Corporation |
| Intercontinental Chemical Corporation |
| ASHTA Chemicals |
| Olin Corporation |
| The Mosaic Company |
| Cogent Chemical |
| FMC Corporation |
| Others |
Cost & Logistics Intelligence
Midwest agricultural cooperatives concentrate procurement volumes in the United States caustic potash market, anchoring a contract-based pricing model where seasonal volume commitments secure freight-advantaged supply against spot-market volatility. This buyer concentration reinforces membrane-cell operators' pricing power in liquid fertilizer-grade channels while fragmenting negotiation leverage for smaller municipal and pharmaceutical accounts.
Pricing Analysis
Potassium chloride feedstock costs pass through directly to caustic potash contract structures, with Saskatchewan mining concentration exposing domestic producers to rail logistics surcharges and Canadian supply renegotiations. Pricing stratifies across USP-grade flake, food-certified pellet, and standard liquid tiers, with certification level and dissolution control driving premium capture. Margins are tightening due to Ohio River Valley electricity rate escalation compressing membrane-cell operating economics. Agricultural cooperatives exhibit highest price sensitivity through direct procurement negotiations, while pharmaceutical compounders absorb premiums for validated USP monograph compliance.
Supply Chain Analysis
Regional distribution centers across Illinois, Indiana, and Iowa consolidate liquid caustic potash from Ohio River Valley membrane-cell facilities before seasonal redistribution to cooperative tank farms. Supply concentrates in the United States through domestic membrane-cell capacity, with Canadian potassium chloride feedstock and limited Mexican import competition completing the sourcing map. The supply chain rests on rail-borne potassium chloride from Saskatchewan potash mines, membrane-cell electrolysis equipment, and EPA-certified transportation containers. Single-source vulnerability in Saskatchewan mining concentration poses structural risk to feedstock security. Distribution runs through direct tanker contracts for agricultural volumes and wholesale distributor networks for smaller industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States caustic potash market functions as a stable compounder, with EPA water treatment mandates and Midwest agricultural potassium replenishment cycles delivering predictable demand baselines across economic cycles.
For Market Incumbents: Cement membrane-cell technology leadership through USP-grade certification expansion and validated quality system investments that filter marginal competitors from pharmaceutical channels. Prioritize backward integration into potassium chloride supply contracts with Saskatchewan mining operators to hedge rail logistics disruption risk. Defensive consolidation should target Ohio River Valley capacity additions that secure freight advantage into Illinois and Iowa cooperative procurement offices against Gulf Coast import competition. For New Entrants and Emerging Players: Enter via high-purity pellet production for battery electrolyte and specialty catalyst applications, where carbonate contamination specifications below 0.5% command margin premiums and filter established commodity producers. The Pacific Northwest battery manufacturing corridor represents the most penetrable geography, with limited domestic pellet capacity forcing reliance on Ohio River Valley rail shipments. A go-to-market angle anchored in automated handling system compatibility and low-dust granule formats differentiates against legacy flake suppliers. For Investors and Strategic Acquirers: Integrated chlor-alkali conglomerates represent the most active acquirer category in this space, seeking membrane-cell technology assets to complete backward integration into potassium hydroxide from captive chlorine-alkali platforms. Long-term viability rests on 5-10 year EPA regulatory continuity and Midwest agricultural soil potassium depletion trends. Acquisition targets should display validated USP monograph compliance and direct procurement relationships with agricultural cooperatives. The signal to watch is OSHA permissible exposure limit enforcement intensity, which accelerates ventilation retrofit capital requirements and consolidates operating scale toward compliant facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potassium Chloride Supply | Captive feedstock economics from Saskatchewan mining contracts insulate membrane-cell operators from rail logistics volatility. |
| USP-Grade Certification Expansion | FDA and USP monograph compliance filters marginal suppliers from pharmaceutical and food processing channels. |
| Membrane-Cell Capacity Addition in Ohio River Valley | Freight-advantaged supply positioning secures direct procurement contracts with Illinois and Iowa agricultural cooperatives. |
| High-Purity Pellet Production Investment | Automated handling compatibility and low-carbonate specifications command premium pricing in battery electrolyte applications. |
| Direct Sales Channel Development | Seasonal volume commitments with Midwest grain handlers displace distributor intermediaries and capture margin compression. |
Research Approach
Multiple input streams — chlor-alkali plant manager interviews, agricultural cooperative procurement lead discussions, pharmaceutical compounder technical assessments, and membrane-cell technology supplier consultations — were reconciled against customs trade data, ACC industry reports, EPA enforcement databases, and SEC 10-K filings from integrated chemical operators. Bottom-up volume aggregation across product formats and purity grades was triangulated against top-down market sizing from production capacity analysis and feedstock consumption patterns.
Data-stream reconciliation anchored the analytical framework across the analysis window, with segmentation modeled by physical format, application channel, end-user industry, and regional production hub. CAGRs were derived from trend extrapolation of membrane-cell technology diffusion rates, EPA compliance upgrade timelines, and agricultural potassium replenishment cycle intensity. Forecast inputs incorporated electricity rate escalation scenarios in Ohio River Valley manufacturing zones and Saskatchewan potash mining output projections.
The model holds under stable EPA regulatory enforcement and uninterrupted Saskatchewan rail logistics; deviation in OSHA exposure limit revisions or Canadian supply contract disruptions would shift volume and value trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Lithopone Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Superacids Market
Specialty Compounds
Global Polymer Clay Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Polyimide Coatings Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Organoclay Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Global Zinc Acetylacetonate Market
Specialty Compounds
Specialty Sorbents Market
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market
Specialty Compounds
Potassium Hydrogen Sulphite Market