
 Global Color Masterbatch Market | 2026-2036
Global Color Masterbatch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Color Masterbatch Market Analysis
The EU Green Deal's packaging sustainability targets are expanding demand for color masterbatches compatible with post-consumer recycled polymers. Clariant AG leverages its specialty additives portfolio to serve automotive OEMs transitioning to mono-material designs. Ampacet Corporation sustains manufacturing scale across North American compounding facilities. Tosaf Compounds Ltd. anchors regional supply through Israeli production hubs serving Mediterranean packaging converters.
Color masterbatch denotes a concentrated mixture of pigments and additives dispersed in a polymer carrier, typically containing 15-50% colorant by weight, engineered for let-down ratios of 1-5% during injection molding or extrusion. Polymer-based concentrates dominate volume due to broad compatibility with polyethylene and polypropylene processing. Specialty masterbatches command premium positioning through functional additives combining UV stabilization with metallic effects. Packaging applications absorb the largest share of output, though automotive interior segments show the fastest structural expansion driven by cabin customization trends.
REACH registration requirements in Europe and FDA food-contact compliance in the United States shape formulation chemistry and market access conditions for cross-border suppliers. China's SAMR enforces GB standards for plastic articles in food packaging, directly influencing export-oriented masterbatch specifications. Stakeholders must monitor evolving extended producer responsibility frameworks and biopolymer compatibility requirements as these regulatory vectors increasingly determine product development priorities and geographic market eligibility.
Market Dynamics
Recycled-content mandates under the EU Green Deal and China's dual carbon goals are restructuring procurement priorities across packaging converters, forcing reformulation investments that favor masterbatches compatible with post-consumer resin streams.
Growth Catalysts
- EU Green Deal packaging targets:Mandatory recycled-content thresholds for plastic packaging are expanding procurement of color masterbatches engineered for PCR polymer compatibility across European converter networks.
- Electric vehicle interior customization:Automotive OEMs in Germany and South Korea are specifying specialty masterbatches with metallic effects and UV stabilization for cabin differentiation.
- China's dual carbon framework:National emissions reduction targets are accelerating domestic masterbatch demand for lightweight packaging that reduces transport-related carbon intensity.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings compress margin stability for standard white and pastel masterbatch formulations.
- REACH registration burdens:ECHA compliance timelines and dossier costs create market-access friction for non-EU specialty additive suppliers.
- Mono-material substitution pressure:Simplified packaging designs reduce complexity requirements, threatening premium multi-layer masterbatch applications.
Strategic Opportunities
- Biopolymer compatibility gap:PLA and PHA processing requirements remain underserved by incumbent masterbatch carriers, opening formulation development space.
- India packaging modernization:FSSAI food-contact compliance investments by domestic converters are expanding addressable market for certified masterbatch suppliers.
- Digital color-matching platforms:Cloud-based spectrophotometry tools enable remote formulation services, compressing traditional distributor-led technical sales cycles.
Industry Challenges
- Colorimetric expertise scarcity:Formulation chemists with dual competency in polymer rheology and pigment dispersion are concentrated among legacy European and Japanese suppliers.
- Multi-certification stacking:Simultaneous FDA, REACH, and GB standard compliance extends product development timelines for cross-border masterbatch portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Color Masterbatch Market |
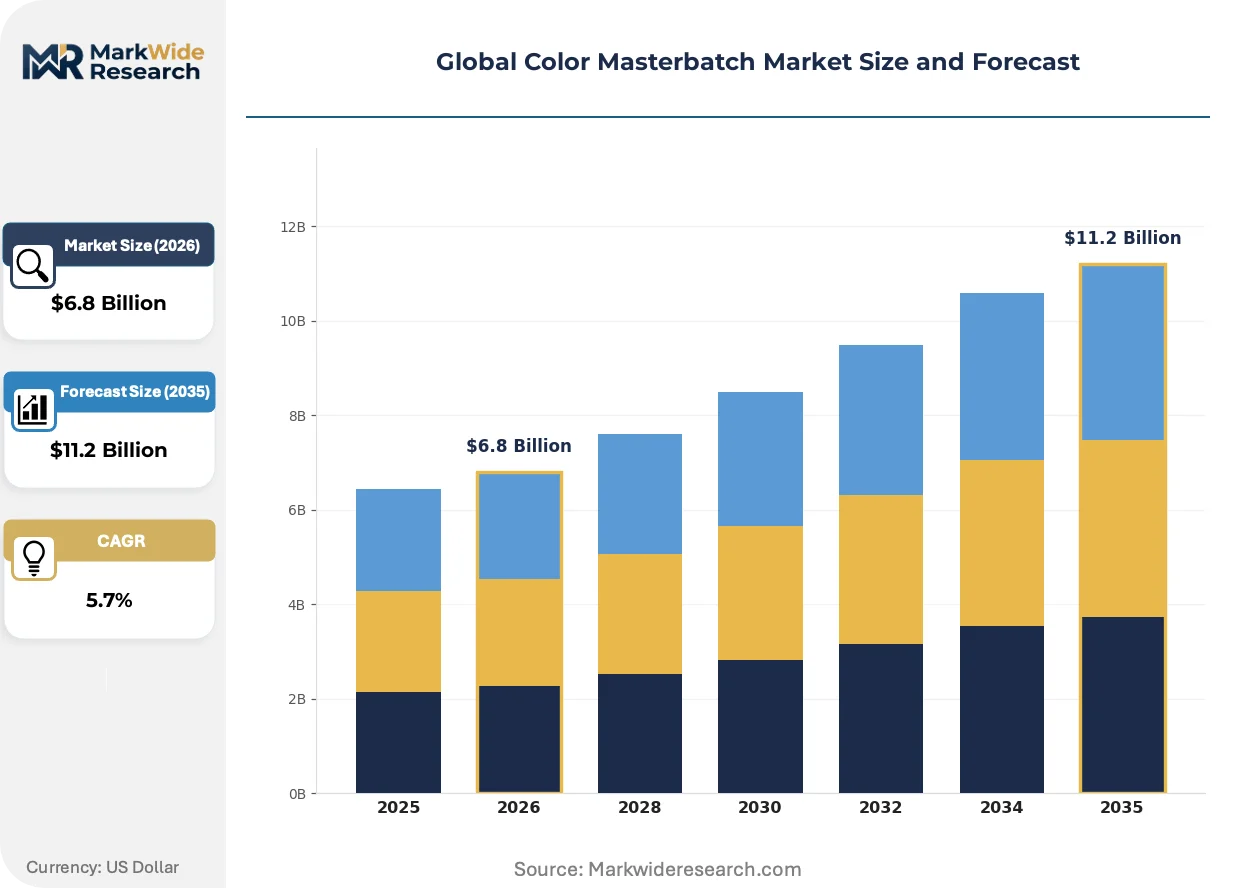
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-Based, Water-Based, Specialty, Additive Masterbatches Application: Packaging, Automotive Components, Consumer Goods, Textiles End User: Manufacturers, Distributors, Retailers, OEMs Formulation Type: Concentrates, Compounds, Solutions, Others |
| Companies Covered | LyondellBasell Industries N.V., Clariant AG, Avient Corporation, Penn Color Inc., BASF SE, Ampacet Corporation, Tosaf Compounds Ltd., Plastika Kritis S.A., Cabot Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Color Masterbatch Market Emerging Trajectories
Formulation chemistry and digital service models are converging to reshape how color concentrates are specified, tested, and delivered to compounders and converters.
Laser-marking additive masterbatches are electrifying traceability applications in automotive and medical device polymers. Tier-1 suppliers in South Korea are adopting these formulations for direct-part-marking compliance with MFDS device regulations. The technology is compressing demand for secondary label adhesives and surface-printing equipment.
REACH authorization restrictions on legacy pigments are forcing substitution investments across European masterbatch houses. ECHA's sunset date scheduling for chromium-based colorants is redirecting R&D expenditure toward organic high-performance alternatives. Automotive exterior applications face the steepest reformulation curves given durability specifications.
Converter procurement departments are consolidating supplier panels and demanding ISO-certified color consistency guarantees. Large packaging groups in Germany and the United States are replacing spot-buying relationships with multi-year masterbatch agreements tied to volume commitments. Technical service integration and on-site color laboratory access have become primary selection criteria.
Global Color Masterbatch Market Segmentation
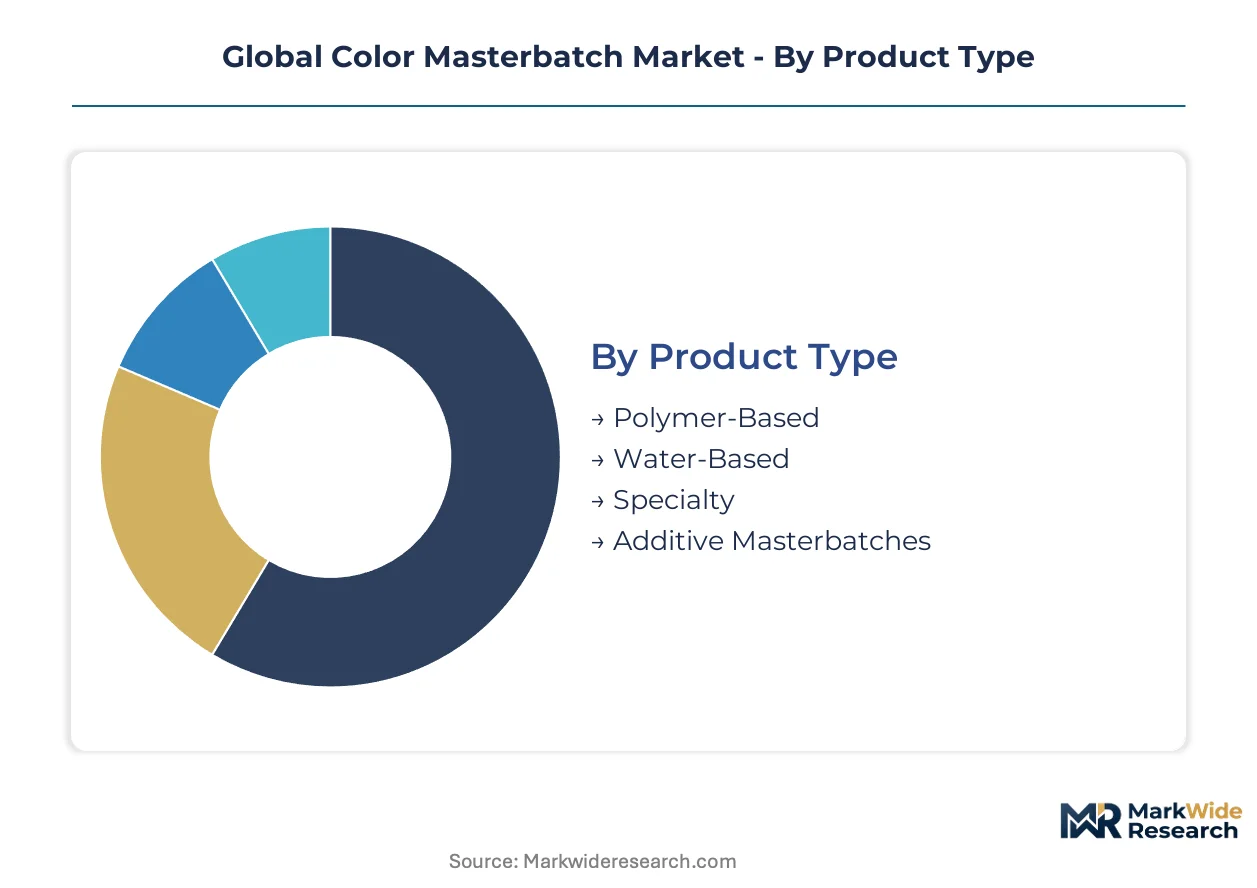
Color masterbatch segmentation reveals how formulation chemistry, application requirements, and supply chain position determine pricing power and technical service intensity. Understanding these category boundaries helps suppliers allocate R&D resources and identify white-space opportunities in underserved processing technologies.
Product Type:
Standardization dominates at the commodity end while specialty formulations command premium positioning through functional complexity and regulatory certification burdens.
- Polymer-Based:These concentrates disperse pigments within polyethylene, polypropylene, or polystyrene carriers at 15-50% colorant loading. German automotive suppliers and Chinese packaging converters consume the largest volumes, driven by compatibility requirements with recycled resin streams under EU Green Deal and dual carbon mandates.
- Specialty:Functional additive combinations merge metallic effects with UV stabilization or laser-marking capability for electric vehicle interiors and medical device traceability. South Korean Tier-1 automotive suppliers specify these formulations for MFDS-compliant direct-part marking, compressing demand for secondary labeling equipment.
- Water-Based:Aqueous dispersion systems serve textile dyeing and non-woven applications where solvent-based carriers face emissions restrictions.
- Additive Masterbatches:Concentrated functional additives without colorant—flame retardants, antistats, antiblock agents—extend polymer performance in regulated end-uses.
Gaining share fastest: Specialty. Leading the category by volume: Polymer-Based.
Application:
End-use differentiation separates commodity packaging converters from automotive OEMs demanding colorimetric precision and multi-certification documentation.
- Packaging:Food-contact compliance drives formulation selection, with FDA and GB standard stacking extending development timelines. European converters prioritize post-consumer recycled polymer compatibility to meet mandatory recycled-content thresholds.
- Automotive Components:Cabin customization trends in Germany and South Korea specify metallic effects and UV-stable formulations for interior differentiation. ECHA sunset dates for chromium-based pigments force reformulation investments across exterior applications.
- Consumer Goods:Appliance housings and electronics enclosures require color consistency across global manufacturing footprints.
- Textiles:Non-woven and fiber applications favor water-based or low-VOC formulations under emissions regulations.
Steepest expansion trajectory: Automotive Components. Largest volume absorption: Packaging.
End User:
Procurement sophistication varies sharply across the value chain, from technical specification by OEMs to price-driven spot purchasing by distributors.
- OEMs:Automotive and appliance manufacturers demand ISO-certified color consistency guarantees, on-site laboratory access, and multi-year volume agreements. German packaging groups now replace spot-buying with technical service-integrated contracts.
- Manufacturers:Compounders and converters balance formulation performance against let-down ratio economics in high-volume extrusion and injection molding operations.
- Distributors:Inventory-carrying intermediaries serve fragmented regional converter bases with standard color palettes and rapid delivery.
- Retailers:Private-label packaging specifiers increasingly dictate sustainability credentials upstream to masterbatch suppliers.
Contract sophistication concentrates with: OEMs. Fastest procurement modernization: Manufacturers.
Formulation Type:
Physical form determines processing flexibility, inventory handling requirements, and compatibility with downstream compounding equipment.
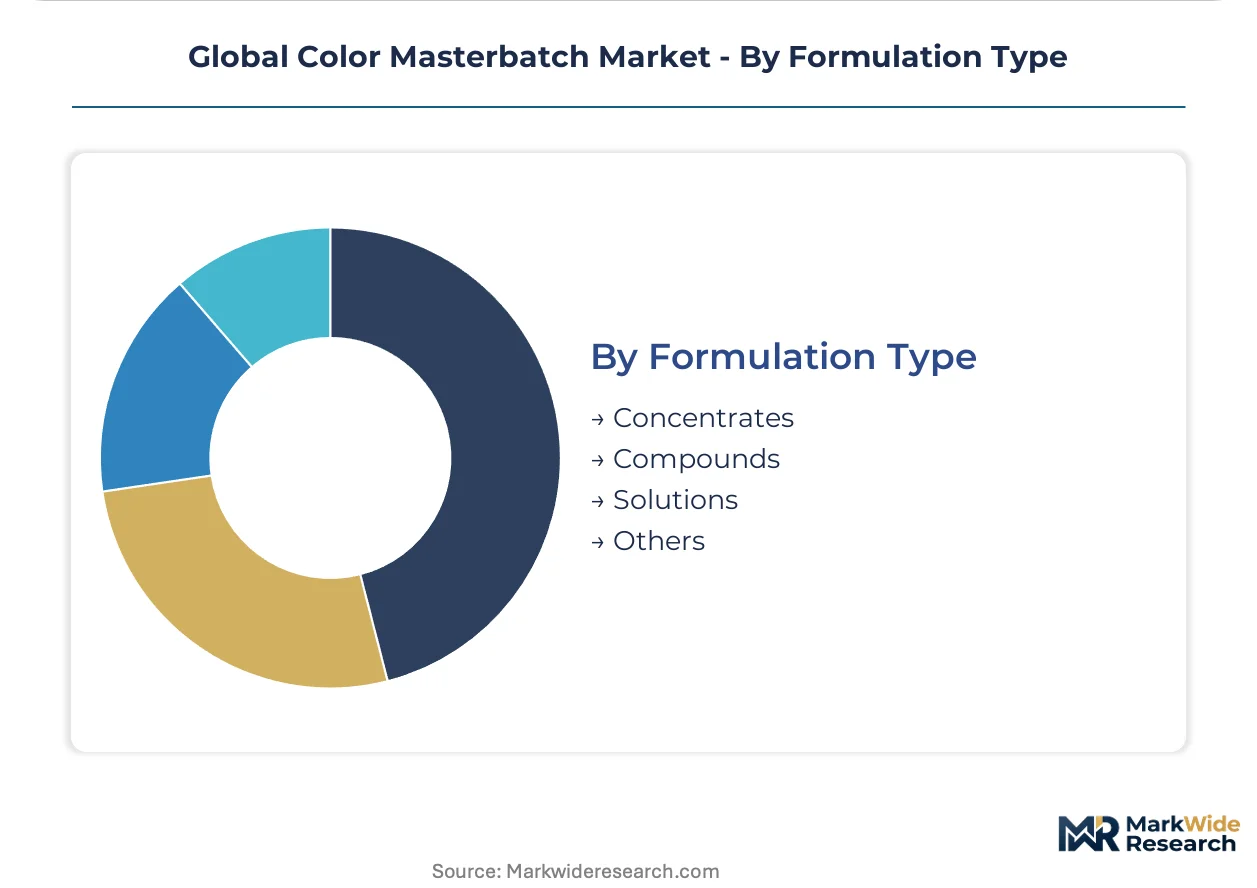
- Concentrates:High-pigment-load pellets designed for 1-5% let-down ratios dominate polyethylene and polypropylene processing. Broad compatibility sustains volume leadership across packaging converter networks in the United States and China.
- Compounds:Pre-colored polymer resins eliminate let-down operations for small-batch processors and color-critical applications.
- Solutions:Liquid dispersions serve continuous extrusion lines and specialized coating applications where pellet feeding creates dispersion challenges.
- Others:Emerging solid and semi-solid formats address biopolymer processing requirements and novel additive delivery mechanisms.
Expanding most quickly: Solutions. Dominant physical form: Concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and China while consumption concentrates across packaging hubs in the United States and automotive corridors in South Korea. This geographic split shapes trade flows and regulatory compliance investments.
United States
Food-contact packaging converters in Illinois and Ohio drive formulation demand for FDA-compliant masterbatches. The FDA's food additive regulations govern pigment migration limits in polyethylene containers. Chicago-area compounders are expanding technical service laboratories to support multi-year supply agreements with national packaging groups.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify specialty masterbatches for electric vehicle interior differentiation. ECHA's REACH authorization timelines force reformulation away from chromium-based pigments. Stuttgart's Tier-1 supplier cluster is investing in laser-marking additive systems for direct-part traceability.
China
Packaging modernization in Guangdong and Zhejiang provinces absorbs standard polymer-based concentrates. SAMR enforces GB standards for plastic articles in food packaging, directly influencing export-oriented masterbatch specifications. The Yangtze River Delta hub is scaling production for lightweight packaging serving e-commerce logistics.
South Korea
Electric vehicle manufacturers in Seoul and Busan prioritize cabin customization through metallic-effect masterbatches. MFDS device regulations mandate traceability solutions for medical polymers. The Busan-Ulsan automotive corridor is adopting laser-marking formulations to eliminate secondary labeling equipment.
India
Domestic packaging converters in Maharashtra and Gujarat are upgrading FSSAI food-contact compliance capabilities. The FSSAI's plastic packaging safety standards are tightening additive migration thresholds. Mumbai-Pune industrial belt compounders are certifying masterbatch portfolios for export to Middle Eastern markets.
Global Color Masterbatch Market Vendor Landscape
The competitive structure tilts toward diversified chemical conglomerates with captive polymer supply chains. Three tiers separate global formulation houses, regional compounding specialists, and niche additive developers. Capacity expansion and strategic partnerships dominate competitive moves as players secure PCR-compatible carrier resin access.
Within the diversified chemical tier, Clariant AG and BASF SE exemplify formulation breadth spanning standard concentrates through specialty functional additives. Ampacet Corporation anchors North American manufacturing scale across compounding facilities. Regional specialists including Tosaf Compounds Ltd. and Plastika Kritis S.A. occupy positions serving Mediterranean and Southern European packaging converters with technical service-integrated supply relationships.
| Leading Market Players |
|---|
| LyondellBasell Industries N.V. |
| Clariant AG |
| Avient Corporation |
| Penn Color Inc. |
| BASF SE |
| Ampacet Corporation |
| Tosaf Compounds Ltd. |
| Plastika Kritis S.A. |
| Cabot Corporation |
| Others |
Supply Flow & Price Mechanics
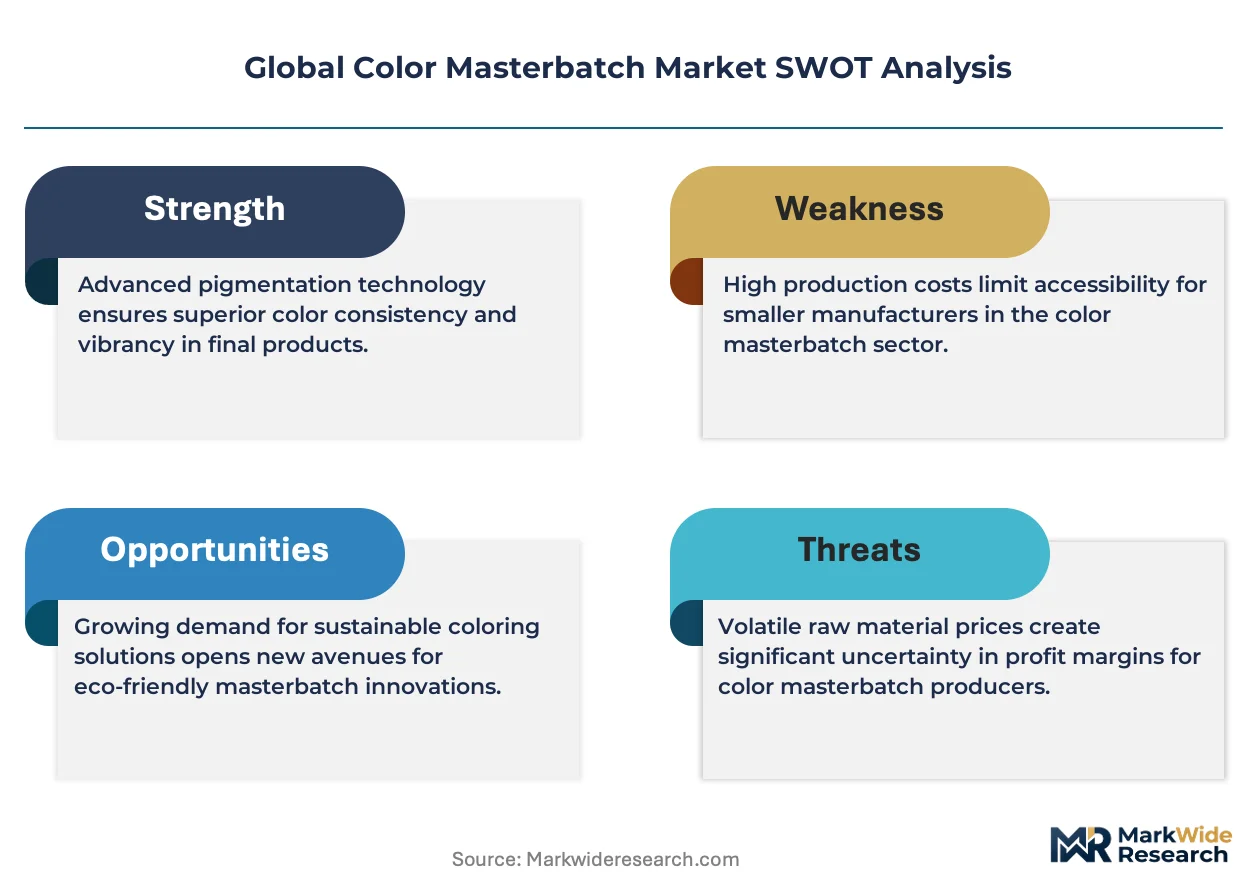
EU Green Deal recycled-content mandates gate qualified supply and premium-tier pricing access, forcing converters to pay certification premiums for PCR-compatible formulations while excluding uncertified competitors from automotive and food-contact procurement.
Pricing Analysis
Yield-guaranteed color consistency anchors value-based pricing for automotive OEMs demanding ISO-certified batch-to-batch uniformity. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered specialty formulations from commodity concentrates. Cost compression in standard grades intensifies because titanium dioxide feedstock volatility squeezes compounder margins. Small-batch converters show highest price sensitivity; German automotive Tier-1s demonstrate lowest sensitivity due to specification-locked supply agreements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese titanium dioxide refiners and German specialty additive houses. Production gravity centers on Germany, China, and the United States, with pigment synthesis anchored in coastal Chinese chemical parks and compounding concentrated in Bavarian industrial corridors. The supply chain draws from titanium dioxide, organic pigments, and polymer carrier resins as core inputs. Tariff exposure on Chinese pigment imports constitutes the dominant structural risk. Distribution runs through technical service-integrated direct sales for OEMs and inventory-carrying distributors for fragmented converter bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH registration dossiers and FDA food-contact certifications erect barrier-to-entry moats that reward incumbent investments and punish undercapitalized challengers.
For Market Incumbents: To counter titanium dioxide cost volatility and margin compression in standard grades, deepen backward integration into pigment synthesis or secure long-term offtake agreements with Chinese refiners. Prioritize certification stacking investments that lock out regional competitors from automotive and medical device supply chains.
For New Entrants and Emerging Players: Launch via digital color-matching platforms serving mid-size packaging converters underserved by legacy distributor networks. Target biopolymer compatibility gaps in PLA and PHA processing where incumbent carriers fail. White-space concentrates in Indian FSSAI-certified formulations for domestic converters upgrading compliance capabilities.
For Investors and Strategic Acquirers: ECHA sunset date announcements for chromium-based pigments are the leading indicator that reformulation-intensive specialty houses will command scarcity premiums. Long-term viability favors diversified players with captive polymer supply and multi-regional certification portfolios. Acquisition targets should demonstrate ISO-certified color laboratories and multi-year OEM contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | Captive titanium dioxide supply insulates margin stability against Chinese refinery price swings. |
| Multi-Certification Portfolio Investment | Simultaneous FDA, REACH, and GB compliance opens cross-border automotive and food-contact procurement. |
| Digital Color-Matching Platform Launch | Cloud-based spectrophotometry compresses technical sales cycles for mid-size converter accounts. |
| Biopolymer Carrier Development | PLA and PHA-compatible formulations address underserved sustainable packaging demand clusters. |
| Regional Compounding Capacity Expansion | Proximity production in India and Southeast Asia reduces logistics costs for export-oriented converters. |
Methodological Framework
Document review covered customs and trade flow databases, ECHA REACH registration filings, and FDA food additive petitions, complemented by interviews with masterbatch plant managers, automotive OEM procurement leads, packaging converter technical directors, and distribution channel partners. Secondary validation drew from SEC 10-K disclosures of listed chemical conglomerates, Cefic industry statistics, and SAMR GB standard documentation. Bottom-up volume modeling triangulated against top-down value estimates derived from production capacity and average selling price assumptions.
Historical volume trajectories cross-referenced against expert panel inputs shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, end-use industry vertical, formulation physical form, and regional regulatory cluster. CAGRs were derived from weighted regression of historical demand patterns and policy-mandated substitution timelines. Industry-specific forecast inputs incorporated EU Green Deal recycled-content threshold schedules and ECHA pigment authorization sunset calendars.
Pigment feedstock price shocks, unanticipated ECHA regulatory acceleration, and biopolymer adoption curve revisions are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about policy implementation timelines and substitution elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Global Specialty Amines Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
Global Stannic Chloride Market
Specialty Compounds
Global Masterbatch Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Organoclay Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Acetyl Tyrosine Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Global Antifreeze Proteins Market
Specialty Compounds
Specialty Sorbents Market