
 Global Specialty Oilfield Chemicals Market | 2026-2036
Global Specialty Oilfield Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Oilfield Chemicals Market Outlook
Buyer concentration among offshore operators is pivoting toward integrated service contracts that bundle production chemicals with field management. Halliburton leverages its integrated project delivery model to anchor long-term supply agreements in deepwater basins. Baker Hughes competes through advanced chemistry platforms that reduce operational risk for independent producers. Nouryon differentiates via bio-based demulsifier formulations that meet stricter discharge protocols.
Specialty oilfield chemicals comprise purpose-engineered surfactants, polymers, and inhibitors formulated to perform under high-pressure, high-temperature reservoir conditions exceeding 150°C and 10,000 psi. These chemicals maintain wellbore integrity, separate oil-water emulsions, and maximize hydrocarbon recovery from mature and unconventional reservoirs. Corrosion inhibitors and friction reducers command the largest share of product-type revenue due to their non-discretionary role in asset protection, while enhanced oil recovery applications represent the fastest-growing application segment as operators target stranded reserves. Innovative formulations incorporating pseudoplastic rheology modifiers are displacing conventional systems in high-salinity environments.
The EPA regulates offshore chemical discharge through National Pollutant Discharge Elimination System permits, while REACH restricts hazardous substance use in European offshore operations. Brazil's national petroleum regulator mandates environmental compliance plans for pre-salt development, directly shaping chemical selection criteria for service providers. Stakeholders must monitor evolving biodegradability standards and carbon-intensity disclosure requirements that will determine formulation eligibility in major offshore provinces.
Market Dynamics
Deepwater operators are consolidating chemical procurement under integrated service contracts, compressing supplier margins while demanding higher performance accountability from formulation providers across the Permian Basin, North Sea, and offshore Brazil.
Growth Catalysts
- Pre-salt development mandates:Brazil's national petroleum regulator requires environmental compliance plans for pre-salt fields, creating sustained demand for biodegradable demulsifiers and corrosion inhibitors in ultra-deepwater operations.
- REACH substance restrictions:ECHA's tightening hazardous substance classifications are accelerating reformulation investments, opening market share for European suppliers with advanced green chemistry capabilities.
- HPHT reservoir complexity:Reservoir conditions exceeding 150°C and 10,000 psi are forcing operators to replace conventional systems with purpose-engineered pseudoplastic rheology modifiers and thermally stable polymers.
Market Restraints
- Ethylene oxide supply volatility:Key surfactant feedstock prices fluctuate with Gulf Coast petrochemical outages, squeezing margin predictability for demulsifier and scale inhibitor producers.
- Specialty additive import dependence:North American friction reducer manufacturers rely on concentrated Asian supply for polyacrylamide powder, exposing procurement to shipping bottlenecks and tariff uncertainty.
- Biodegradability testing timelines:EPA's extended aquatic toxicity validation protocols delay new product registrations by 18-24 months, freezing commercialization schedules for novel chemistries.
Strategic Opportunities
- Carbonate reservoir EOR:Middle Eastern operators are piloting low-salinity waterflooding combined with surfactant-polymer blends to unlock stranded reserves in mature carbonate formations.
- Integrated chemical-field management bundles:Deepwater contractors in offshore Brazil and West Africa are consolidating chemical supply with real-time monitoring services, creating multi-year contract vehicles.
- EPA Green Chemistry Challenge recognition:Formulations earning federal environmental design awards gain preferential positioning in operator pre-qualification processes, particularly for Gulf of Mexico discharge permits.
Industry Challenges
- HPHT formulation expertise scarcity:The industry lacks sufficient reservoir chemists capable of designing stable systems for combined high-pressure, high-temperature, and high-salinity environments, constraining innovation velocity.
- Legacy SCADA integration friction:Automated chemical injection systems require costly retrofitting to communicate with decades-old offshore platform control architectures, delaying smart field deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Oilfield Chemicals Market |
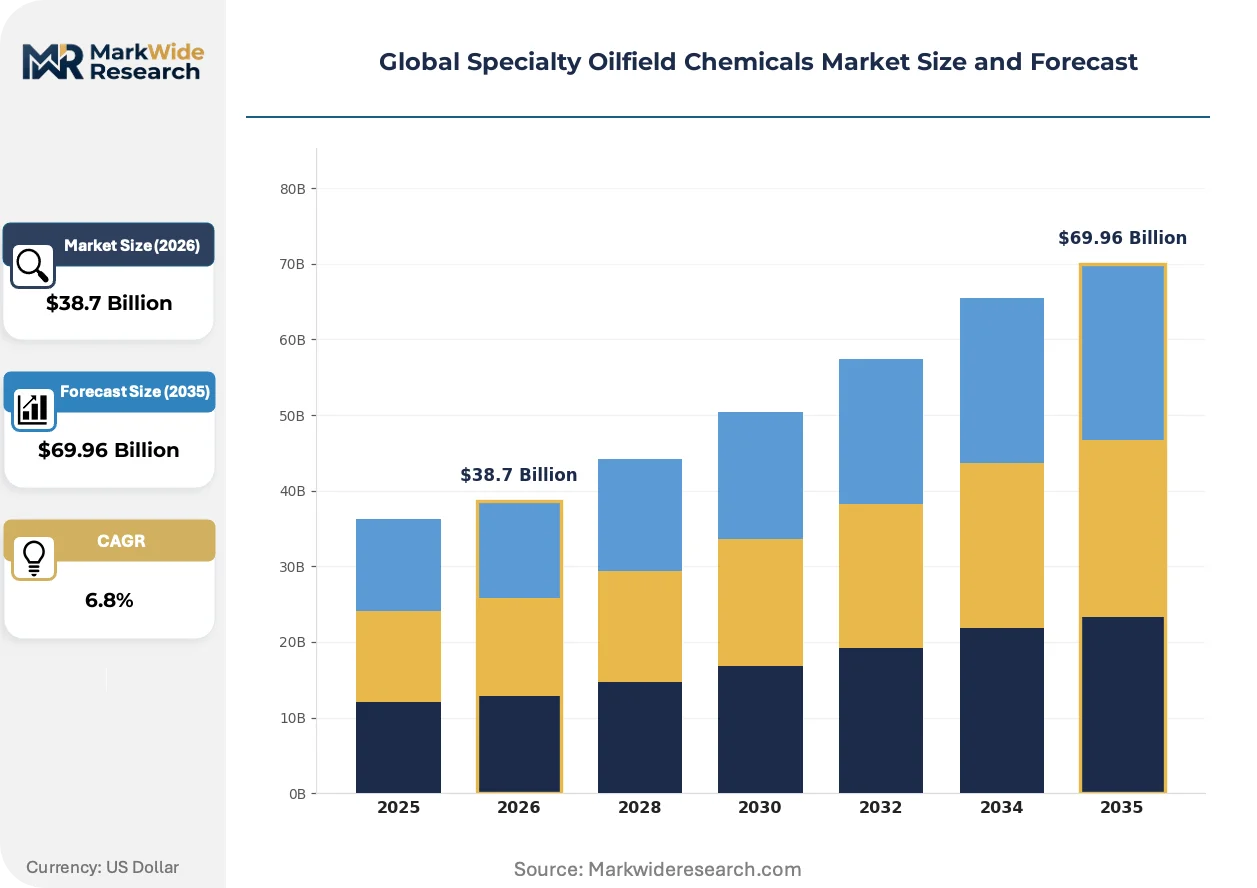
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrosion Inhibitors, Friction Reducers, Biocides, Demulsifiers Application: Drilling Fluids, Production Chemicals, Cementing, Enhanced Oil Recovery Technology: Innovative Formulations, Pseudoplastic Fluids, Microemulsions, Surfactants End User: Oil Companies, Service Providers, Independent Producers, Offshore Operators |
| Companies Covered | BASF SE, SMC Global, Baker Hughes, Halliburton, Nouryon, The Lubrizol Corporation, Clariant, Solvay S.A., Thermax Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Oilfield Chemicals Market Strategic Shifts
Formulation science is converging with digital field management, as real-time reservoir monitoring enables dynamic chemical dosing that was previously impossible with static batch treatments.
Bio-based demulsifier platforms derived from agricultural feedstocks are expanding into North Sea and Gulf of Mexico operations. Major integrated operators have adopted these systems for platforms within 50 kilometers of sensitive coastal zones. The technology is expanding into premium pricing tiers previously reserved for synthetic fluorochemicals, compressing the cost-performance gap between green and conventional chemistries.
REACH authorization requirements for persistent, bioaccumulative, and toxic substances are forcing reformulation of legacy corrosion inhibitors across European offshore assets. Operators in the Norwegian and UK sectors face 2026 sunset dates for several chrome-based chemistries. The North Sea drilling segment is responding fastest, with contractors pre-emptively substituting approved alternatives to avoid operational disruption during permit renewals.
Integrated service contracts now bundle chemical supply with performance guarantees tied to production uptime metrics. Deepwater operators in Brazil and West Africa have displaced traditional transactional purchasing with outcome-based arrangements where suppliers absorb injection system maintenance costs. This restructuring is most visible among independents lacking in-house chemical engineering capabilities, who now outsource formulation selection entirely to service company specialists.
Global Specialty Oilfield Chemicals Market Segmentation
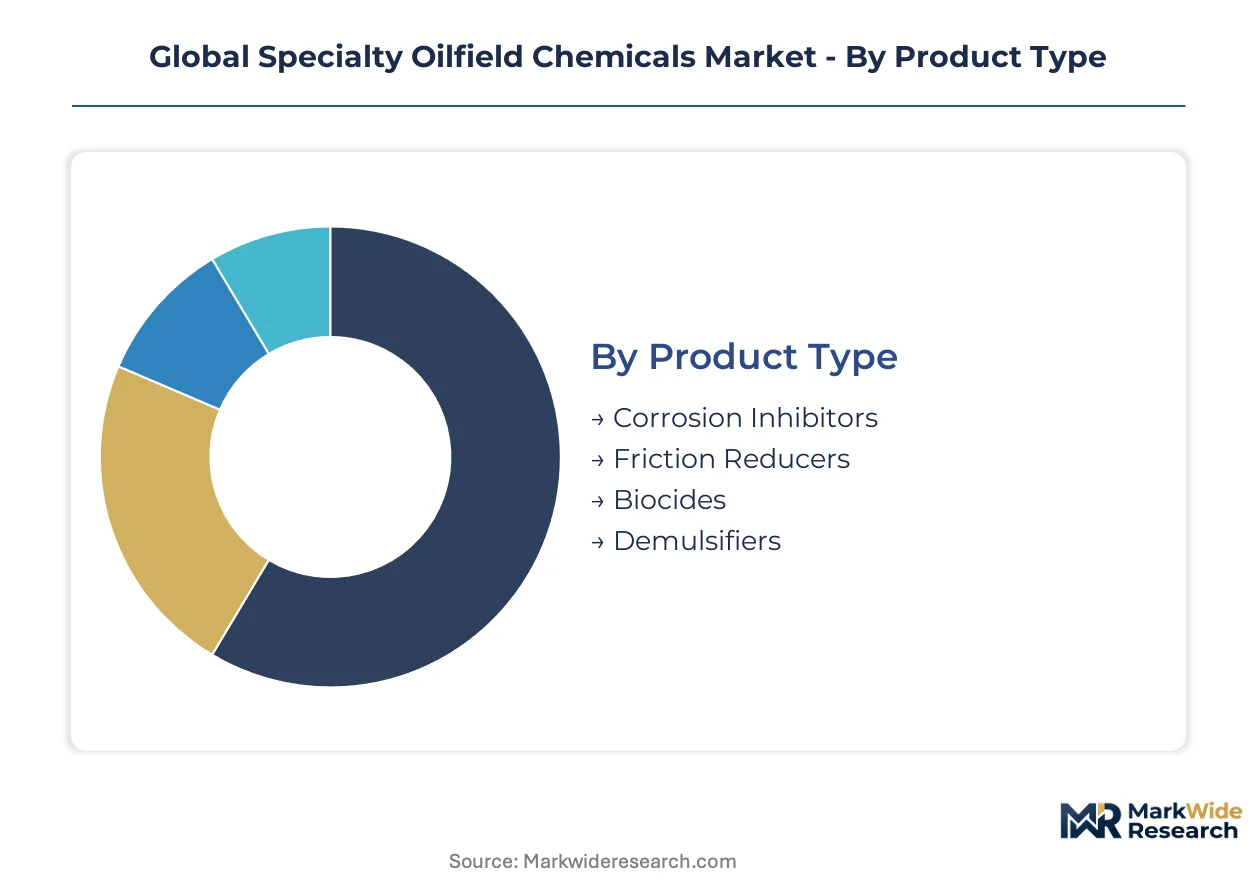
Specialty oilfield chemicals segment across four interlocking dimensions that determine procurement logic, technical specifications, and supplier relationships. Understanding these splits reveals where formulation investments concentrate and which customer types drive specification changes.
Product Type:
Operators prioritize product selection based on asset protection economics and regulatory discharge exposure, with non-discretionary spend dominating maintenance categories and environmental compliance reshaping specification requirements.
- Corrosion Inhibitors:These formulations protect downhole tubulars and surface equipment from CO₂ and H₂S attack through film-forming amines and quaternary ammonium compounds. Demand concentrates in the Permian Basin and offshore Brazil, where high-sour gas production and pre-salt CO₂ content accelerate metal degradation and mandate continuous injection.
- Friction Reducers:High-molecular-weight polyacrylamide polymers reduce pumping pressures during hydraulic fracturing and pipeline transport. North American unconventional operators in the Permian and Bakken formations consume the largest volumes, though Asian polyacrylamide supply concentration creates procurement vulnerability during shipping disruptions.
- Biocides:Glutaraldehyde and THPS-based formulations control sulfate-reducing bacteria in waterflooding systems and fracturing fluids. Offshore platforms in the Gulf of Mexico and North Sea deploy these chemicals most intensively due to closed-loop water reuse requirements.
- Demulsifiers:Ethoxylated phenol resins and polyamine derivatives separate oil-water emulsions at surface facilities. Brazil's pre-salt fields and mature North Sea assets generate sustained demand for thermally stable, biodegradable variants that satisfy ANP and REACH discharge protocols.
Corrosion inhibitors lead on scale; friction reducers lead on momentum.
Application:
Application selection follows reservoir lifecycle stage, with drilling and cementing dominating capital-intensive phases while production chemicals and EOR drive recurring operational expenditure.
- Drilling Fluids:Water-based and synthetic-based mud systems maintain wellbore stability and cuttings transport across vertical, directional, and horizontal well profiles. HPHT drilling in the Gulf of Mexico and pre-salt Brazil demands pseudoplastic rheology modifiers that maintain viscosity under combined thermal and pressure stress.
- Production Chemicals:Scale inhibitors, paraffin dispersants, and asphaltene controllers maintain flow assurance throughout field life. Offshore West Africa and the North Sea generate premium pricing for bundled chemical-plus-monitoring service contracts that guarantee production uptime.
- Cementing:Fluid loss additives, retarders, and gas-blocking polymers ensure zonal isolation during primary and remedial cement jobs. Geothermal and HPHT wells in Indonesia and Turkey drive demand for thermally stable latex and elastomer systems.
- Enhanced Oil Recovery:Surfactant-polymer flooding, alkaline-surfactant-polymer blends, and low-salinity waterflooding target stranded reserves in mature carbonate and sandstone reservoirs. Middle Eastern national oil companies in Saudi Arabia and the UAE are expanding pilot programs that represent the steepest expansion trajectory among application segments.
Production chemicals dominate current spend; EOR applications command the steepest expansion trajectory.
Technology:
Technology differentiation increasingly determines bid competitiveness, with environmental performance and digital integration capabilities displacing traditional cost-per-gallon metrics in operator evaluations.
- Innovative Formulations:Next-generation chemistries incorporate predictive degradation modeling and real-time response characteristics. Norwegian and UK North Sea operators favor these systems for their compatibility with automated injection platforms and carbon-intensity disclosure requirements.
- Pseudoplastic Fluids:Shear-thinning rheology modifiers reduce viscosity under high-shear pumping conditions then rebuild structure in static reservoir zones. These systems are displacing conventional polymers in high-salinity Permian and Bakken formations where divalent cation tolerance limits traditional chemistry performance.
- Microemulsions:Thermodynamically stable dispersions of oil, water, and surfactant enhance oil displacement efficiency at ultra-low interfacial tension. carbonate EOR pilots in Oman and Kuwait employ microemulsion formulations to unlock residual oil saturation in heterogeneous limestone reservoirs.
- Surfactants:Anionic, nonionic, and zwitterionic surface-active agents reduce interfacial tension and modify wettability across drilling, production, and EOR applications. Bio-based feedstock alternatives are gaining share in Gulf of Mexico coastal platforms subject to EPA NPDES discharge scrutiny.
Surfactants anchor current volume; pseudoplastic fluids are gaining share fastest.
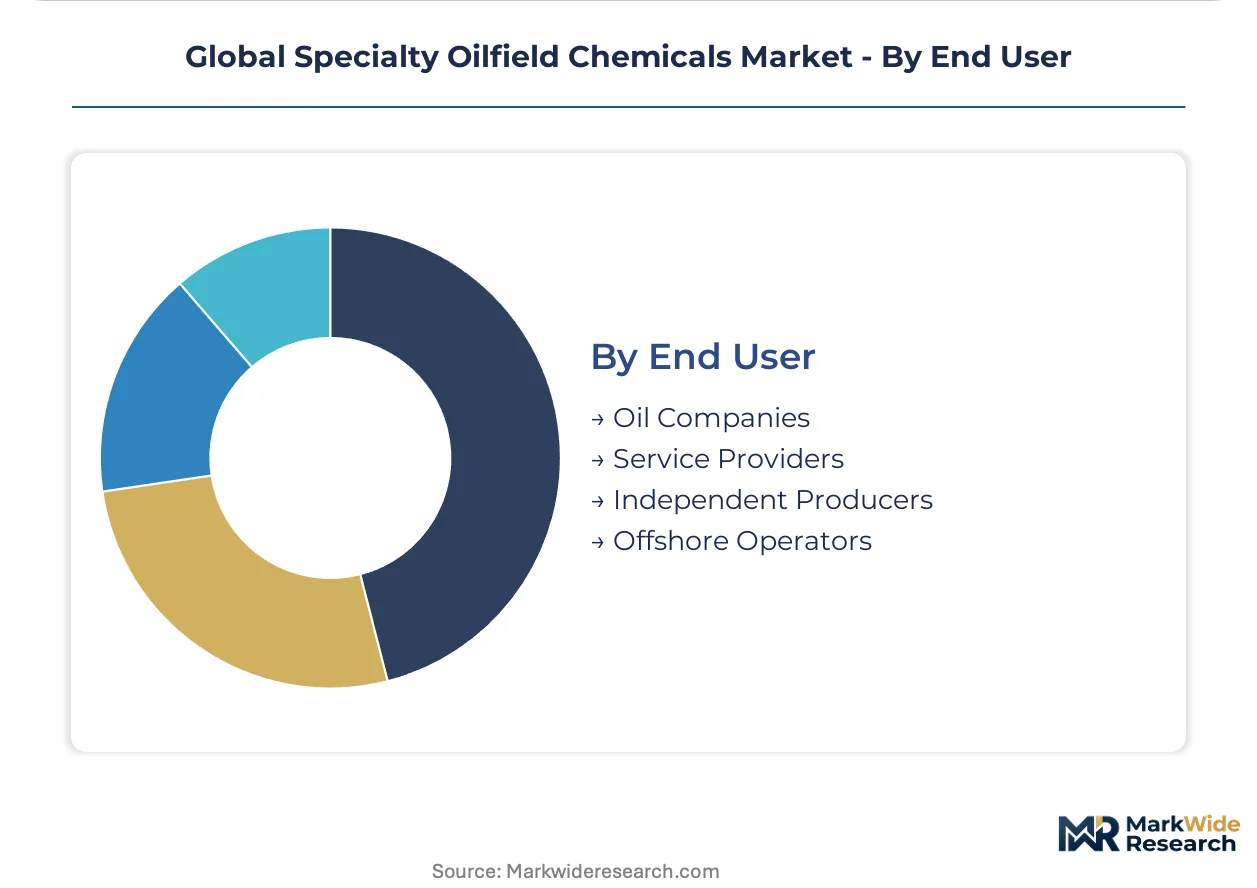
End User:
End-user procurement patterns split between integrated chemical-field management bundles for complex assets and transactional purchasing for standardized applications, with capability gaps driving outsourcing decisions.
- Oil Companies:Majors and national oil companies maintain in-house chemical engineering teams that specify formulations and audit supplier performance. Saudi Aramco, Petrobras, and Equinor drive industry standards through pre-qualification protocols that favor integrated service providers with multi-basin experience.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes bundle chemical supply with drilling, completion, and production services. These firms capture long-term contracts in deepwater Brazil and West Africa by absorbing injection system maintenance and performance risk.
- Independent Producers:Mid-size and small operators in the Permian and Bakken lack in-house chemical expertise and rely on distributor recommendations or service company outsourcing. Price sensitivity dominates procurement, though supply security concerns are shifting some volume toward regional blending facilities.
- Offshore Operators:Deepwater contractors in the Gulf of Mexico, North Sea, and offshore Brazil face the most stringent discharge regulations and highest cost of failure. These buyers consolidate procurement under integrated contracts that tie chemical performance to production uptime guarantees and environmental compliance metrics.
Oil companies lead on specification authority; offshore operators lead on contract innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum engineers and reservoir chemists concentrate in Houston, Aberdeen, and Rio de Janeiro, anchoring technical specification authority for the world's most demanding offshore developments. These talent clusters shape procurement standards that cascade through supply chains.
United States
Permian Basin operators consume the largest volumes of friction reducers and corrosion inhibitors for high-sour unconventional production. EPA NPDES discharge permits mandate aquatic toxicity testing for Gulf of Mexico offshore platforms. Houston hosts the headquarters of Halliburton and Baker Hughes, where integrated service contracts bundle chemical supply with real-time field monitoring.
Brazil
Pre-salt ultra-deepwater fields drive demand for thermally stable demulsifiers and biodegradable production chemicals. ANP environmental compliance plans require service providers to document carbon-intensity metrics for chemical selection. The Campos Basin and Santos Basin clusters near Rio de Janeiro concentrate procurement decision-making for Petrobras and international partners.
Norway
North Sea mature assets require reformulated corrosion inhibitors as ECHA REACH sunset dates approach for chrome-based chemistries. Equinor's pre-qualification protocols favor suppliers with automated injection platforms and carbon disclosure capabilities. Stavanger anchors the Norwegian continental shelf's technical specification authority.
Saudi Arabia
Carbonate reservoir EOR pilots are expanding surfactant-polymer flooding programs in mature Ghawar and Safaniya fields. Saudi Aramco's in-house chemical engineering teams set stringent performance benchmarks for enhanced oil recovery formulations. Dhahran's research centers drive pilot-to-field-scale transition timelines.
United Kingdom
North Sea decommissioning schedules and remaining field life extension projects sustain demand for production chemicals and flow assurance solutions. HSE offshore discharge regulations align with REACH substance restrictions for platform chemical inventories. Aberdeen maintains Europe's largest concentration of subsea chemical injection engineering expertise.
Global Specialty Oilfield Chemicals Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation development and field service delivery. The vendor base separates into three strategic archetypes: integrated oilfield service providers bundling chemicals with drilling and completion services; specialty chemical manufacturers supplying formulation ingredients and finished products; and regional blenders serving independent producers with rapid-response logistics. Dominant competitive moves include backward integration into bio-based feedstock supply and strategic partnerships with offshore contractors for multi-year integrated service contracts.
Among German-headquartered diversified chemical conglomerates, BASF SE exemplifies the specialty chemical manufacturer archetype with broad portfolio reach into oilfield applications. Halliburton and Baker Hughes represent the integrated service provider model, anchoring long-term supply positions through project delivery bundling. Nouryon occupies a position within the specialty chemical tier, differentiated by bio-based formulation capabilities serving European and North American offshore discharge compliance requirements.
| Leading Market Players |
|---|
| BASF SE |
| SMC Global |
| Baker Hughes |
| Halliburton |
| Nouryon |
| The Lubrizol Corporation |
| Clariant |
| Solvay S.A. |
| Thermax Global |
| Others |
Value Chain & Pricing Dynamics
Integrated service contract consolidation among deepwater operators in Brazil and West Africa is forcing formulation suppliers to absorb injection system maintenance costs, compressing margins and rewarding only those with captive bio-based feedstock supply or automated blending infrastructure.
Pricing Analysis
Capacity additions in the United States and Middle East are reshaping price floors for friction reducers and corrosion inhibitors. Three-tier pricing structure across premium HPHT-certified, standard offshore-grade, and economy onshore levels dominates procurement, with differentiation driven by thermal stability certification and volume commitment scale. Cost compression in standard-tier biocides is intensifying because Asian polyacrylamide supply volatility exposes margin predictability. Independent producers in the Permian Basin exhibit highest price sensitivity, while offshore operators in the North Sea prioritize performance guarantees over unit economics.
Supply Chain Analysis
Freight cost volatility from Asian polyacrylamide powder suppliers to North American friction reducer blenders is amplifying working capital requirements and forcing regional inventory builds. Supply concentrates in China for surfactant intermediates, the United States for specialty amines, and Germany for bio-based feedstock derivatives. Raw material dependencies include ethylene oxide for demulsifiers, acrylamide monomer for friction reducers, and agricultural lipids for biodegradable surfactants. Single-source vulnerability in Gulf Coast ethylene oxide supply creates disproportionate exposure during petrochemical outages. Distribution runs through integrated service company logistics networks for deepwater contracts and regional blending facilities for independent onshore producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialty oilfield chemicals market functions as a stable compounder anchored by non-discretionary asset protection spend and regulatory-mandated formulation turnover that sustains replacement demand regardless of commodity price cycles.
For Market Incumbents: Deepen backward integration into bio-based feedstock supply to defend margin position against REACH-driven reformulation costs and ethylene oxide price volatility. Anchor long-term integrated service contracts in pre-salt Brazil by absorbing real-time monitoring infrastructure investment. Prioritize HPHT formulation R&D to capture premium pricing from reservoir complexity escalation. For New Entrants and Emerging Players: Pseudoplastic rheology modifiers purpose-engineered for high-salinity Permian and Bakken formations offer the most penetrable white-space entry point. Target independent producers lacking in-house chemical engineering capabilities through distributor partnerships that bundle technical recommendation with rapid-response logistics. Pursue EPA Green Chemistry Challenge recognition as a qualification accelerator for Gulf of Mexico discharge permits. For Investors and Strategic Acquirers: Asymmetric upside sits with regional blenders possessing automated injection platform integration capabilities and established relationships with national oil company pre-qualification protocols. Long-term viability over a multi-year horizon favors suppliers with demonstrated carbon-intensity disclosure infrastructure and multi-basin regulatory compliance experience. Watch for ANP environmental compliance plan enforcement consistency as the signal indicating contract consolidation velocity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstock Supply | Captures margin from REACH-mandated reformulation cycles while securing supply continuity for biodegradable demulsifier production. |
| Automated Injection Platform Deployment | Equinor and Petrobras pre-qualification protocols increasingly require real-time chemical dosing verification for contract eligibility. |
| HPHT Formulation R&D Investment | Reservoir conditions exceeding 150°C and 10,000 psi are displacing conventional polymers with thermally stable alternatives. |
| Integrated Service Contract Expansion | Deepwater operators in Brazil and West Africa are consolidating procurement under multi-year performance-guarantee arrangements. |
| EPA Green Chemistry Challenge Pursuit | Federal environmental design awards accelerate pre-qualification for Gulf of Mexico platforms subject to NPDES discharge scrutiny. |
Study Parameters
Coverage spans North America, Europe, South America, and Middle East, with primary inputs from each region combined with secondary validation across trade databases and regulatory filings. Interviews with reservoir chemists at national oil companies, procurement leads at integrated service providers, plant managers at specialty chemical manufacturers, and technical directors at regional blending facilities informed demand-side assumptions. Secondary sources include EPA NPDES permit databases, ANP environmental compliance filings, ECHA REACH authorization lists, customs trade data, and SEC 10-K disclosures from publicly traded service companies. Bottom-up product-type volume estimates were triangulated against top-down application spend analysis.
Segmentation was modeled at product type, application, technology, and end-user dimensions, with additional granularity on HPHT certification tier and bio-based content percentage. CAGRs were derived from regression analysis of historical procurement patterns against drilling activity forecasts and regulatory implementation timelines. Forecast inputs included pre-salt development capex schedules, REACH sunset date enforcement probability, and ethylene oxide capacity expansion announcements across the analysis window.
The model holds under stable regulatory enforcement timelines and continued deepwater development commitment; deviation in commodity price collapse duration or trade policy disruption would shift volume trajectories. Stakeholders should weight assumptions against their own operating context and regional exposure concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
Resin Capsule Market
Specialty Compounds
Global Polymer Clay Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Global Stannic Chloride Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
Microcapsules Market
Specialty Compounds
Polyurea Market
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Metasulphite Market
Specialty Compounds
Tosyl Chloride Market