
 Global Molding Compounds Market | 2026-2036
Global Molding Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molding Compounds Market Analysis
The capital-intensity divergence between large resin producers and specialized compounders is unwinding as scale advantages erode. BASF SE leverages integrated petrochemical feedstocks to control raw material costs across thermoplastic formulations. Sumitomo Bakelite Co., Ltd. anchors its position in thermosetting compounds through proprietary phenolic resin chemistry developed for high-heat electrical applications. Toray Advanced Composites differentiates via carbon fiber-reinforced molding compounds serving aerospace qualification requirements.
Molding compounds are formulated resin systems—thermoplastic, thermosetting, or elastomer-based—often loaded with fillers or fibers, processed under heat and pressure to shape complex parts with tight dimensional tolerances. Thermoplastic compounds dominate volume due to recyclability and faster cycle times in injection molding, while reinforced compounds command premium positioning where strength-to-weight ratios determine specification. Among end users, automotive parts applications absorb the largest compound volumes as OEMs substitute metal with engineered plastics to meet emissions targets.
EPA regulations in the United States restrict volatile organic compound emissions from molding operations, pushing processors toward closed-loop systems. ECHA enforces REACH substance restrictions that ban or limit specific plasticizers and flame retardants in European-sold compounds. FDA biocompatibility requirements govern medical device applications, creating qualification barriers that favor established compounders with validated resin platforms. Stakeholders must monitor evolving chemical hazard classifications that could disqualify incumbent formulations without warning.
Market Dynamics
The automotive sector's metal-to-plastics substitution mandate is compressing qualification timelines while simultaneously fragmenting supplier tiers. Tier-1 molders now demand compound formulations validated for 150°C continuous-use environments within 18-month development windows.
Growth Catalysts
- EPA VOC emission caps:Closed-loop molding systems capture solvent vapors at 95%+ efficiency, qualifying processors for federal tax credits under the Inflation Reduction Act.
- Electric vehicle battery housings:Flame-retardant phenolic compounds replace aluminum in high-voltage enclosures, cutting pack weight by 40%.
- China's NEV production scaling:Domestic compound consumption concentrates in Jiangsu and Guangdong provinces where BYD and CATL operate gigafactories.
Market Restraints
- Benzene feedstock volatility:Phenolic resin producers face margin compression when crude spreads exceed $15 per barrel.
- German automotive supplier consolidation:Bosch, Continental, and ZF Group now specify single-source compound approvals, freezing out mid-tier compounders.
- Thermoplastic recycling contamination:Mixed-polymer feedstreams degrade mechanical properties below OEM specification thresholds.
Strategic Opportunities
- India's PLI scheme for auto components:Localized molding compound production qualifies for 18% subsidy on capital expenditure.
- 5G base station radomes:Low-dielectric thermoset formulations penetrate telecommunications infrastructure at 25% annual volume expansion.
- Japan's carbon neutrality roadmap:METI mandates bio-based content minimums in public procurement by fiscal 2030.
Industry Challenges
- REACH SVHC notification backlog:ECHA's 6-12 month substance evaluation delays new formulation launches.
- Multi-axis injection molding technician scarcity:European processors report 30% vacancy rates for skilled toolsetters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molding Compounds Market |
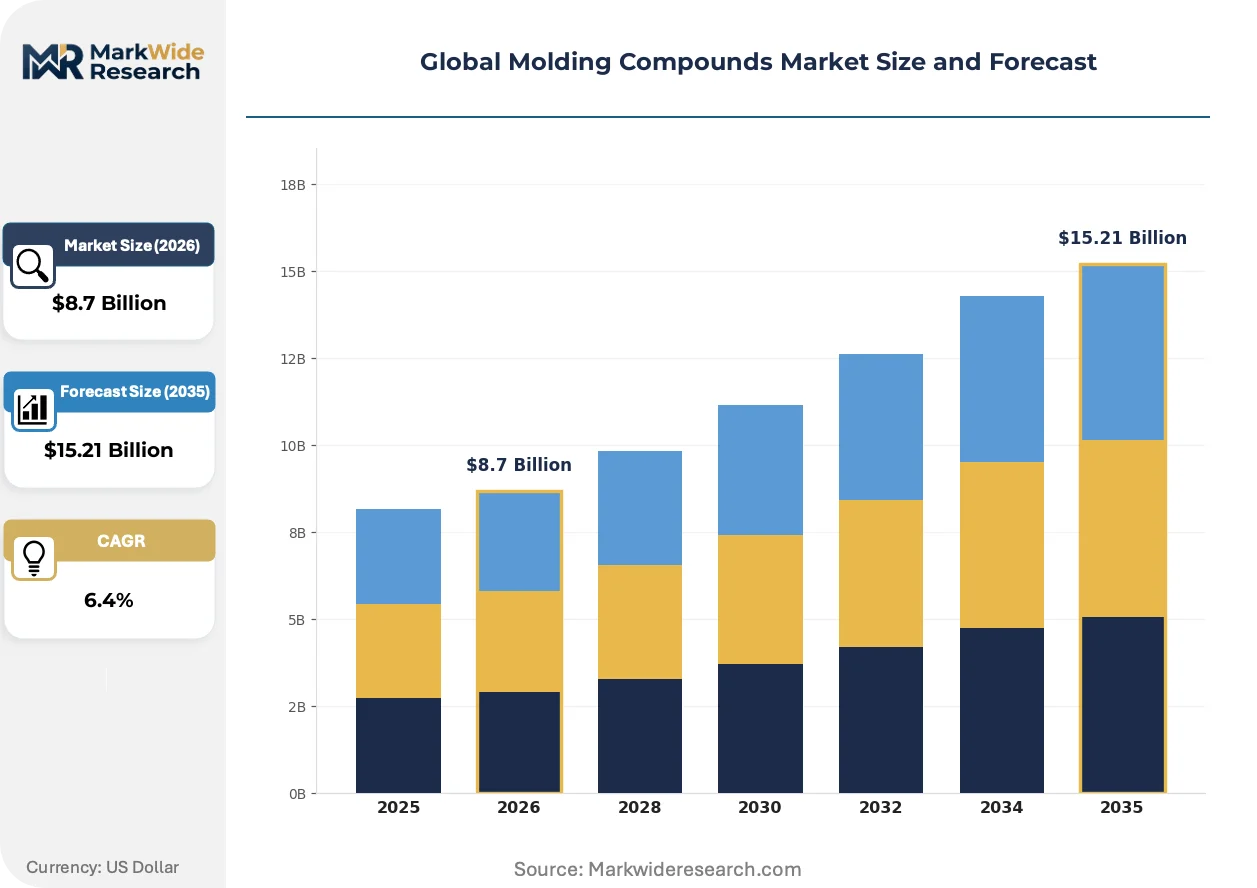
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Thermosetting, Elastomers, Reinforced End User: Automotive, Consumer Electronics, Aerospace, Medical Devices Form: Granules, Powder, Liquid, Sheet Application: Packaging, Electrical, Automotive Parts, Household Items |
| Companies Covered | IDI Composites International, KYOCERA Corporation, BASF SE, Showa Denko Materials Co. Ltd, Huntsman International LLC, Polynt Composites, Menzolit Kunststoffwerk GmbH, Toray Advanced Composites, Sumitomo Bakelite Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molding Compounds Market Emerging Trajectories
Material science breakthroughs are collapsing the traditional boundary between thermoplastic processability and thermoset performance. Formulators now engineer hybrid cure kinetics that accelerate cycle times without sacrificing heat resistance.
Long-fiber thermoplastic (LFT) technology is bifurcating the structural automotive market. Ford and Stellantis deploy glass-mat-reinforced polypropylene in underbody shields at 45-second cycle times. The technology is bifurcating metal-stamping supply chains as stampers retool for injection-compression hybrid cells.
ECHA's REACH restriction proposal on medium-chain chlorinated paraffins forces reformulation of wire-coating compounds. Electrical harness suppliers face 24-month requalification timelines. Asian exporters to the EU are accelerating phosphate-ester flame retardant substitution programs.
Automotive OEMs now specify compound grades against finished-part performance metrics rather than resin property datasheets. Tier-1 molders bear liability for shrinkage control and weld-line strength. Germany's KBA type-approval process rewards compounders with integrated simulation capabilities.
Global Molding Compounds Market Segmentation
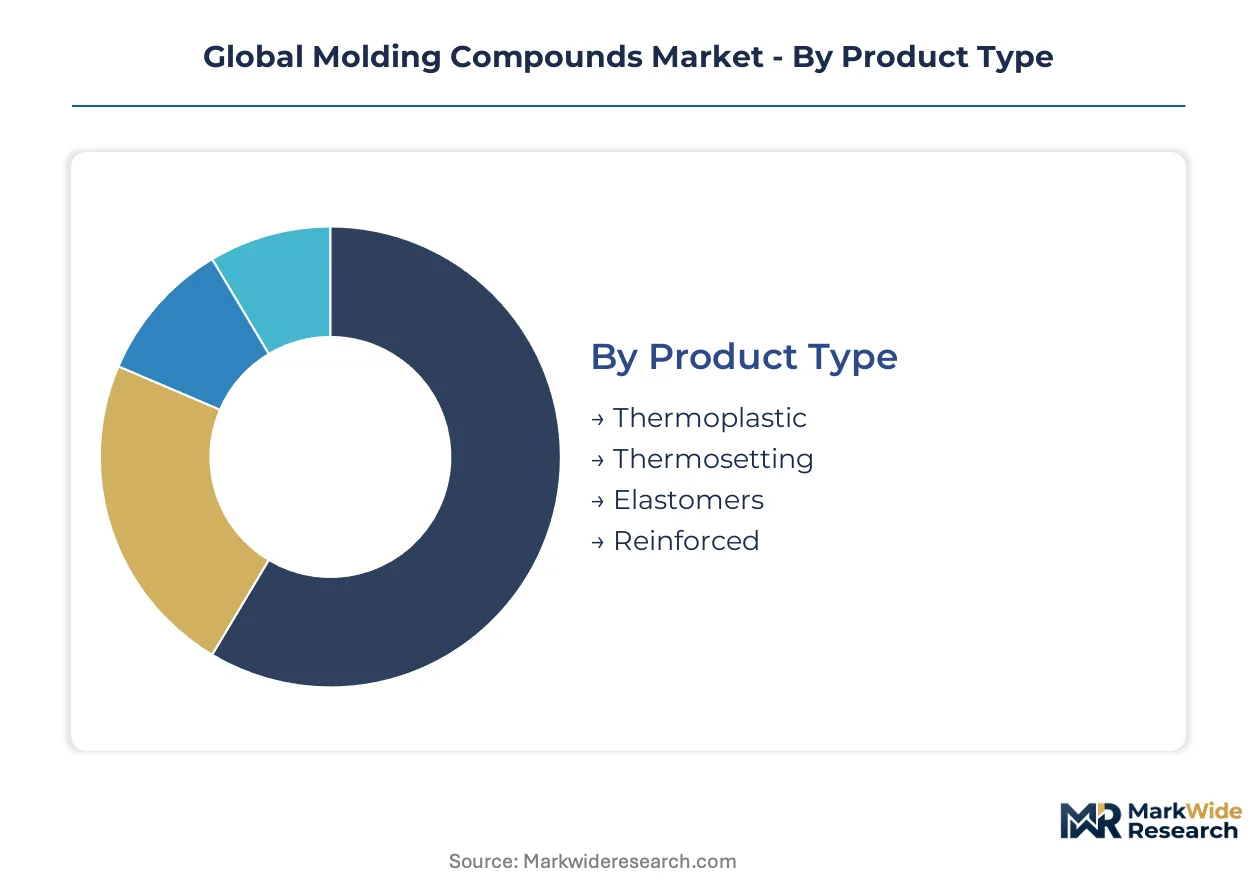
Molding compound specifications diverge sharply across thermal processing requirements and mechanical load conditions. Substitution dynamics between thermoplastic and thermosetting formulations reshape supplier positioning in high-temperature automotive applications.
Product Type:
Thermosetting compounds face intensifying substitution pressure from hybrid thermoplastic formulations that replicate heat resistance with superior recyclability credentials.
- Thermoplastic:Recyclable resin systems process through repeated heating cycles without chemical crosslinking. Automotive underbody shields in Germany absorb volume as Ford and Stellantis deploy glass-mat-reinforced polypropylene at 45-second cycle times.
- Thermosetting:Irreversibly cured networks deliver dimensional stability above 150°C continuous use. Phenolic formulations in China's Jiangsu province replace aluminum in electric vehicle battery housings, cutting pack weight by 40%.
- Elastomers:Cross-linked rubber compounds combine elasticity with compression set resistance for sealing applications.
- Reinforced:Fiber-loaded matrices spanning glass, carbon, and aramid fillers serve aerospace qualification requirements.
Thermoplastic anchors the volume base while reinforced compounds gain share at the steepest rate.
End User:
Cost tier stratification separates commodity automotive specifications from medical device grades requiring FDA biocompatibility validation.
- Automotive:Metal replacement mandates drive specification intensity. OEMs in Stuttgart and Detroit now demand compound grades validated against finished-part performance metrics rather than resin property datasheets.
- Medical Devices:ISO 10993 compliance creates qualification barriers favoring established compounders with validated resin platforms. Implantable device housings in Minnesota and Massachusetts specify implant-grade PEEK compounds.
- Consumer Electronics:Miniaturization pressures concentrate demand in Shenzhen and Seoul for flame-retardant laptop chassis compounds.
- Aerospace:Toray Advanced Composites supplies carbon fiber-reinforced molding compounds serving FAA qualification requirements for interior structural applications.
Automotive anchors the volume base while medical devices gain share at the steepest rate.
Form:
Supply concentration in granule production favors large resin producers with integrated compounding lines.
- Granules:Pelletized feedstock dominates injection molding throughput. BASF SE leverages integrated petrochemical feedstocks to control raw material costs across thermoplastic formulations in Ludwigshafen.
- Powder:Fine particle distributions serve compression molding and rotational casting applications. Phenolic molding powders in Japan target high-heat electrical insulation for METI-mandated carbon neutrality procurement.
- Liquid:Two-component systems enable reaction injection molding for large structural parts.
- Sheet:Pre-impregnated formats support thermoforming and matched-die molding in aerospace secondary structures.
Granules anchors the volume base while powder gains share at the steepest rate.
Application:
Application maturity varies sharply, with electrical insulation representing established demand and automotive parts undergoing rapid materials transition.
- Automotive Parts:Structural substitution of metal stamps accelerates. Long-fiber thermoplastic technology bifurcates supply chains as European stampers retool for injection-compression hybrid cells.
- Electrical:Wire coating compounds face ECHA REACH restriction proposals on medium-chain chlorinated paraffins. Asian exporters accelerate phosphate-ester flame retardant substitution programs.
- Packaging:Food-contact compliance under FDA and EFSA specifications governs migration limits for container applications.
- Household Items:Cost-driven specifications in appliance housings concentrate procurement with large-volume compounders.
Electrical anchors the volume base while automotive parts gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers exhibit the highest price elasticity as domestic EV production scales, while European medical device specifications show inelastic demand due to FDA and ECHA compliance barriers. German automotive OEMs compress supplier margins through single-source qualification mandates.
China
Electric vehicle battery housing demand from BYD and CATL concentrates compound procurement in Jiangsu and Guangdong provinces. MIIT mandates domestic content ratios under the NEV industrial policy. Shenzhen and Shanghai host the largest molding compound consumption clusters for consumer electronics chassis applications.
Germany
Stuttgart-based OEMs specify thermoplastic compounds for metal replacement in underbody shields at 45-second cycle times. KBA type-approval rewards integrated simulation capabilities. Ludwigshafen anchors BASF SE's integrated petrochemical feedstock control over thermoplastic formulations.
United States
EPA VOC emission caps push processors toward closed-loop systems qualifying for IRA federal tax credits. Minnesota and Massachusetts medical device clusters specify implant-grade PEEK compounds under FDA biocompatibility requirements. Detroit automotive suppliers demand 150°C continuous-use validation within 18-month windows.
Japan
METI mandates bio-based content minimums in public procurement by fiscal 2030. Phenolic molding powders target high-heat electrical insulation for carbon neutrality compliance. Nagoya and Osaka industrial corridors concentrate thermoset compound production for automotive electrical applications.
India
PLI scheme subsidies of 18% on capital expenditure attract localized molding compound production for auto components. BIS standards govern material specifications for domestic manufacturing. Maharashtra and Gujarat host emerging compound consumption clusters as domestic EV assembly scales.
Global Molding Compounds Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the molding compounds market. Large resin producers with captive petrochemical feedstocks control cost positions across thermoplastic formulations, while specialized compounders defend niches through proprietary cure chemistry and qualification barriers. Three archetypes dominate: integrated petrochemical players, thermoset chemistry specialists, and carbon fiber-reinforced compound innovators. Capacity expansion and backward integration into raw material production represent the two dominant competitive vectors as scale advantages erode.
Among integrated chemical conglomerates, BASF SE and Huntsman International LLC exemplify the scale-driven archetype with upstream control over resin feedstocks. Toray Advanced Composites and Sumitomo Bakelite Co., Ltd. occupy positions within the specialization tier, representing differentiated approaches to high-performance formulations. KYOCERA Corporation anchors the ceramics-to-polymers diversification vector among Japanese industrial groups.
| Leading Market Players |
|---|
| IDI Composites International |
| KYOCERA Corporation |
| BASF SE |
| Showa Denko Materials Co. Ltd |
| Huntsman International LLC |
| Polynt Composites |
| Menzolit Kunststoffwerk GmbH |
| Toray Advanced Composites |
| Sumitomo Bakelite Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between automotive OEMs and phenolic resin producers lock in supply access while providing price visibility across benzene feedstock cycles. These contracts insulate Tier 1 molders in Stuttgart and Detroit from spot market volatility while committing compounders to 18-month qualification windows under single-source mandates.
Pricing Analysis
After-sales service bundling with technical support contracts drives lifetime value for established compounders defending medical device accounts. Three-tier pricing structure across aerospace-qualified, automotive-validated, and commodity industrial grades separates implant-grade PEEK from glass-mat-reinforced polypropylene. Cost compression in thermosetting formulations is intensifying because phenolic resin producers face margin pressure when crude spreads widen. Automotive specifications show the highest price sensitivity as OEMs consolidate supplier tiers, while medical device grades exhibit inelastic demand under FDA biocompatibility barriers.
Supply Chain Analysis
Inventory buffers for phenolic molding powders stretch to 8-12 weeks in Japan as Nagoya producers manage METI-mandated bio-based transition timelines. Supply concentrates in China for EV battery housing compounds, Germany for automotive underbody shields, and the United States for medical-grade formulations. Raw material dependencies span benzene derivatives for phenolic chemistry, polypropylene feedstocks for thermoplastic compounds, and carbon fiber precursors for aerospace grades. Single-source vulnerability runs through Jiangsu province where BYD and CATL concentrate procurement. Distribution runs through integrated resin producers with captive compounding lines and specialized compounders with qualification-locked channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The molding compounds market fragments across thermal performance tiers as automotive OEMs abandon metal stamping for injection-molded structural parts. This substitution wave creates niches for hybrid cure-kinetic formulations that bridge thermoplastic processability with thermoset durability.
For Market Incumbents: Fortify qualification barriers by embedding simulation capabilities into customer development cycles before KBA type-approval deadlines. BASF SE's integrated Ludwigshafen feedstock control demonstrates how upstream resin production defends margin position against benzene volatility. Sumitomo Bakelite Co., Ltd. anchors defensibility through proprietary phenolic chemistry locked into 150°C continuous-use electrical applications. For New Entrants and Emerging Players: Lead with localized production in Maharashtra and Gujarat to capture India's PLI scheme subsidies before domestic EV assembly scales. India's auto component molding compound demand offers the most penetrable white space. Target 5G base station radome specifications with low-dielectric thermoset formulations as telecommunications infrastructure expands at 25% annual volume expansion. For Investors and Strategic Acquirers: Capital is best deployed toward specialized compounders with locked aerospace or medical device qualifications rather than commodity thermoplastic producers facing margin compression. The 5-10 year viability window favors firms with backward integration into phenolic resin chemistry or carbon fiber preform production. Watch ECHA REACH SVHC notification backlogs as the inflection signal—6-12 month evaluation delays create acquisition windows for formulation-ready assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenolic Resin Production | BASF SE's Ludwigshafen feedstock control demonstrates margin defense against benzene volatility. |
| Long-term Supply Agreement with EV Battery Producers | BYD and CATL procurement concentration in Jiangsu locks in volume through 2030. |
| Joint Venture for Localized India Production | Maharashtra and Gujarat facilities qualify for 18% PLI capital expenditure subsidies. |
| Green Manufacturing Transition to Bio-based Content | METI mandates minimum bio-based ratios for Japanese public procurement compliance. |
| Capacity Expansion in Carbon Fiber-Reinforced Compounds | Toray Advanced Composites supplies FAA-qualified materials for aerospace interior structures. |
Methodological Framework
Initial hypotheses were tested against primary input from plant managers at integrated resin producers, procurement leads at Tier 1 automotive suppliers, technical R&D directors at specialized compounders, and distribution channel partners in Asian export markets and refined through secondary validation. SEC 10-K filings, customs and trade data from ACC and Cefic, EPA emission compliance records, and ECHA REACH substance databases provided quantitative anchors. Bottom-up volume estimates from compounding line utilization rates were triangulated against top-down demand projections from automotive production and EV battery housing forecasts.
Variance decomposition across product type, end-use industry, thermal performance grade, and regional production hub shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by value per kilogram differentials between reinforced and unreinforced formulations. Key inputs included MIIT domestic content ratios for Chinese NEV policy, KBA type-approval timelines for German automotive specifications, and FDA biocompatibility validation durations for medical device grades.
The analysis sits within stated boundaries; outcomes outside sustained EV production scaling, stable benzene-crude spreads, and current REACH substance restrictions would require recalibration. Forecasts reflect documented assumptions about qualification timeline compression and single-source consolidation trends. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Toner Resins Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Solketal Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Hydroxypropyl Methylcellulose Market
Specialty Compounds
Global Customized Premixes Market
Specialty Compounds
N-Propyl Propionate Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
Flexible Foam Market
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Polypropylene Compounds Market
Specialty Compounds
Scratch-Resistant Compound Market
Specialty Compounds
Global Acetyls Market