
 Plasma Powder Market | 2026-2036
Plasma Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Powder Market Analysis
Plasma physicist and materials engineering talent scarcity is reorganizing competitive dynamics across the value chain. Darling Ingredients Inc. leverages its protein extraction infrastructure to secure feedstock streams for plasma-derived powders. Shenzhen Taier Biotechnology anchors Asia-Pacific supply through captive electrospray manufacturing lines. APC Inc. differentiates via ISO-certified plasma spray protocols for aerospace thermal barrier applications.
Plasma powder denotes finely divided material generated through high-energy plasma discharge, typically achieving particle sizes between 10 and 100 micrometers with spherical morphology and controlled porosity. The material serves primarily as feedstock for thermal spray deposition, additive manufacturing, and surface functionalization where melt flow and deposit efficiency govern performance. Cold plasma formulations command premium positioning in medical device sterilization and biocompatible coating segments where non-equilibrium chemistry preserves substrate integrity. Atmospheric plasma systems dominate volume throughput in automotive and electronics manufacturing due to inline integration without vacuum chamber constraints. Powder form factors retain the largest share of commercial transactions, though pelletized plasma feedstock is gaining traction in automated thermal spray operations seeking reduced dust exposure and improved flow consistency.
FDA 21 CFR Part 820 quality system requirements and EU MDR Class III implantable device standards constrain market access for non-compliant plasma coating suppliers. REACH chemical authorization protocols and RoHS substance restrictions further shape material selection in European electronics and automotive end uses. Stakeholders must monitor evolving ISO 13485 certification timelines and dual-use export control classifications for plasma spray equipment destined for defense-aerospace integrators.
Market Dynamics
Plasma powder production is consolidating around captive electrospray and plasma spray infrastructure as feedstock purity requirements tighten under medical device regulations, forcing mid-scale processors to exit or seek contract manufacturing partnerships.
Growth Catalysts
- EU MDR Class III implantable standards:Stricter biocompatibility mandates for cardiovascular and orthopedic coatings are pulling high-purity plasma powder through qualified supply chains into German and Swiss precision manufacturing clusters.
- Additive manufacturing feedstock qualification:Aerospace OEMs in France and Italy are certifying spherical plasma atomized powders for laser powder bed fusion, creating specification pull-through effects across Tier 2 suppliers.
- Cold plasma sterilization protocols:Non-equilibrium atmospheric plasma systems are displacing ethylene oxide in medical device finishing, expanding addressable powder applications beyond thermal spray into surface functionalization chemistry.
Market Restraints
- Argon and helium feedstock volatility:Inert gas supply concentration in Qatar and Algeria exposes European plasma atomization facilities to price spikes and allocation risk during energy market stress.
- REACH authorization timelines:ECHA substance evaluation delays for nickel-based and cobalt-chrome powder compositions are freezing material qualifications and extending new product introduction cycles by 18-24 months.
- High-velocity oxy-fuel substitution:HVOF spraying with liquid fuel alternatives retains cost advantage in non-critical automotive coating applications, capping plasma powder penetration in volume automotive.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting plasma spray coating investments for orthopedic and dental implant production in Gujarat and Karnataka special economic zones.
- Electronics miniaturization:Convergence of atmospheric plasma with roll-to-roll processing is enabling conformal dielectric coatings for flexible circuit substrates, opening semiconductor packaging applications.
- Direct-to-manufacturer powder sales:Bypassing distributor markups through qualified supplier programs is capturing margin in aerospace maintenance, repair, and overhaul channels where lot traceability commands premium positioning.
Industry Challenges
- Plasma physics and materials engineering talent scarcity:University programs in Germany and Japan produce insufficient graduates to staff process development and quality engineering roles at expanding atomization facilities.
- ISO 13485 certification timelines:Medical device quality system audits are backlogged at notified bodies, delaying market access for new plasma coating suppliers targeting implantable cardiovascular stent applications.
- Legacy thermal spray equipment integration:Retrofitting automated powder feed systems into existing robotic cells requires custom engineering that fragments implementation timelines and inflates project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Powder Market |
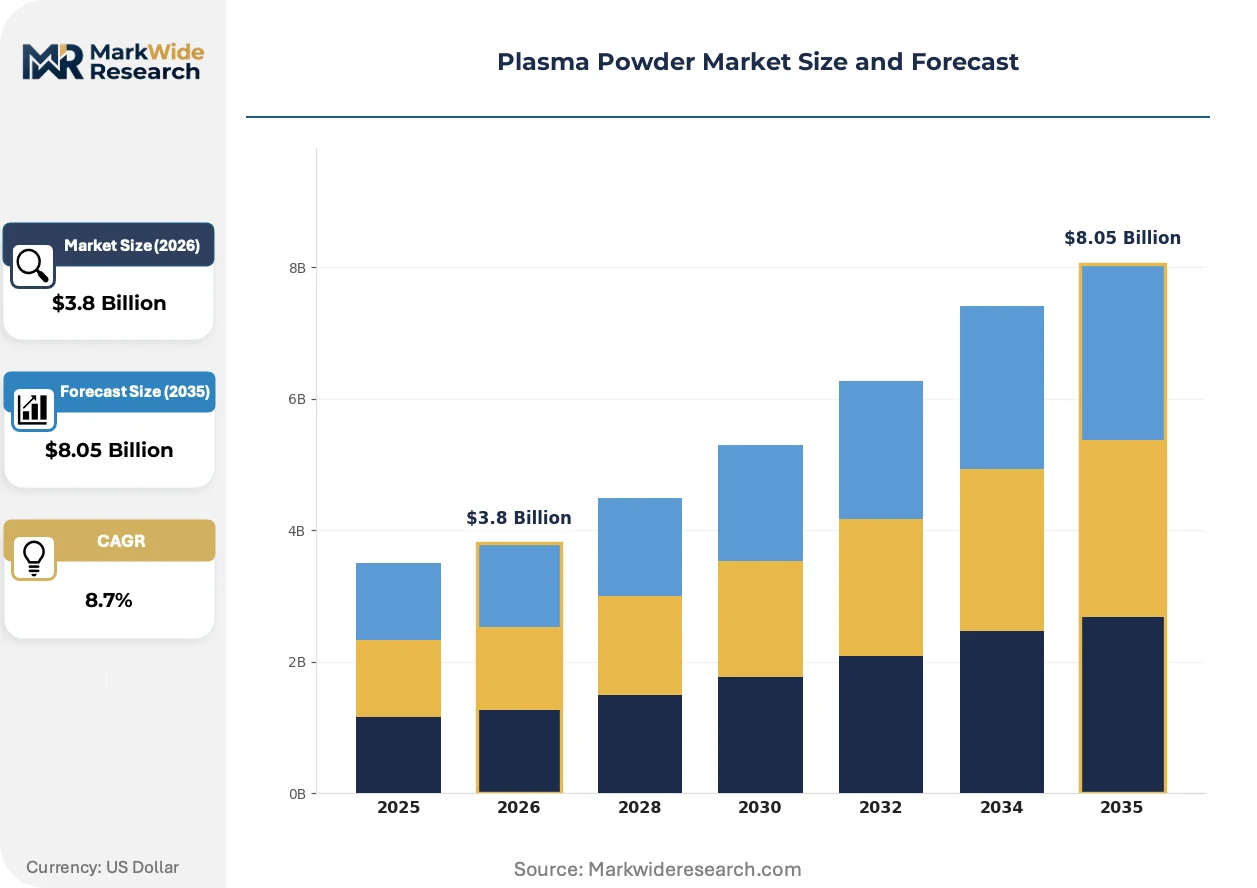
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Plasma, Atmospheric Plasma, Low Pressure Plasma, Plasma Coatings End Use Industry: Aerospace, Automotive, Electronics, Medical Devices Technology: Plasma Spraying, Thermal Plasma, Non-thermal Plasma, Electrospray Technology Form: Powder, Granules, Pellets, Coatings |
| Companies Covered | APC Inc., Lican Alimentos S.A., Darling Ingredients Inc., Acontex GmbH, British Aqua Feeds, Sonac, Shenzhen Taier Biotechnology, Otto Chemie Pvt. Ltd., ACTIPRO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Powder Market Emerging Trajectories
Plasma powder processing is bifurcating between high-purity medical-grade atomization and high-throughput atmospheric systems, with equipment architecture and quality protocols diverging to serve incompatible end-use specifications.
Electrospray atomization is fragmenting the traditional plasma rotating electrode process for sub-50 micrometer titanium and cobalt-chrome powders. Medical device coaters in Switzerland and the Netherlands are qualifying these finer distributions for porous implant surfaces. The technology is compressing incumbent gas atomization margins in orthopedic applications where spherical morphology governs deposit efficiency.
REACH chemical authorization protocols are forcing reformulation of nickel-bearing plasma powders in European electronics and automotive thermal barrier applications. ECHA substance restriction proposals for carcinogenic metal dusts are accelerating tungsten carbide-cobalt alternatives in cutting tool coatings. French and Italian thermal spray shops are front-loading compliance investments to secure qualified supplier status ahead of 2026 evaluation deadlines.
Specification-driven procurement is consolidating buyer power among aerospace primes and orthopedic OEMs with captive plasma spray operations. Tier 2 coating houses in the US Midwest and Germany's Baden-Württemberg region are losing volume to in-house production as lot traceability and IP protection concerns override outsourcing economics. Defense-aerospace integrators are mandating domestic atomization sources for critical engine component coatings under dual-use export control classifications.
Plasma Powder Market Segmentation
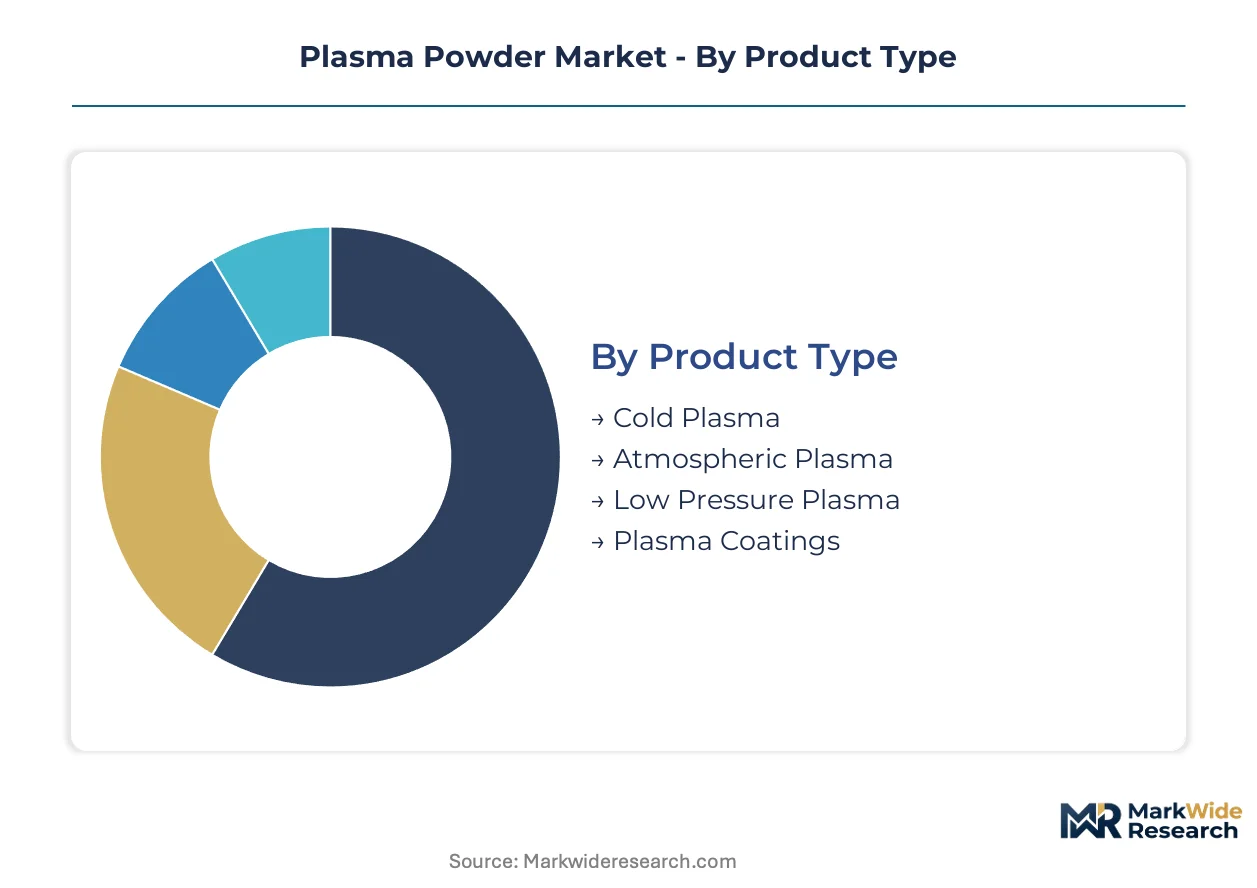
Plasma powder market segmentation reflects divergent purity requirements and equipment architectures across medical, aerospace, and electronics end uses. Channel economics favor direct supplier relationships in aerospace maintenance and contract manufacturing partnerships in medical device coatings.
Product Type:
Cold plasma formulations command premium positioning through qualified distributor networks serving Swiss and German implant manufacturers, while atmospheric plasma systems flow through equipment-integrated supply agreements with automotive and electronics OEMs.
- Cold Plasma:Non-equilibrium chemistry preserves substrate integrity in cardiovascular stent and orthopedic implant surface functionalization. Swiss coaters in the Lake Geneva corridor are qualifying these formulations under EU MDR Class III standards, with procurement consolidating around ISO 13485-certified atomization sources.
- Atmospheric Plasma:Inline integration without vacuum chamber constraints dominates volume throughput in automotive electronics and flexible circuit manufacturing. German automotive suppliers around Stuttgart are deploying these systems for conformal coating of power electronics modules, displacing traditional dip-coating lines.
- Low Pressure Plasma:Vacuum-dependent processing serves semiconductor packaging and precision optics where contamination control governs yield.
- Plasma Coatings:Pre-applied surface treatments bypass powder handling entirely in automated medical device assembly operations.
By volume, Atmospheric Plasma leads. By growth pace, Cold Plasma is ahead.
End Use Industry:
Cost tier stratification separates aerospace prime contractor specifications from automotive volume procurement, with medical devices occupying the premium certification tier and electronics spanning mid-range atmospheric applications.
- Medical Devices:EU MDR Class III implantable standards and FDA 21 CFR Part 820 quality systems constrain supplier qualification to captive electrospray atomization facilities in Germany and Switzerland. Orthopedic OEMs in Baden-Württemberg are consolidating coating supply through in-house plasma spray operations to protect lot traceability and IP.
- Aerospace:Thermal barrier coatings for turbine blades require spherical morphology powders qualified to aerospace OEM specifications. French and Italian engine manufacturers are certifying laser powder bed fusion feedstock, pulling qualified atomization capacity toward Mediterranean supply clusters.
- Automotive:High-velocity oxy-fuel substitution caps plasma penetration in non-critical coating volumes, though electric vehicle power electronics are opening new atmospheric plasma applications.
- Electronics:Roll-to-roll atmospheric processing enables conformal dielectric coatings for flexible circuit substrates in semiconductor packaging.
Medical Devices commands the highest margin tier. Electronics is expanding most quickly.
Technology:
Application maturity separates established plasma spraying infrastructure from emerging electrospray adoption, with thermal plasma occupying the volume base and non-thermal systems capturing sterilization and surface functionalization growth.
- Plasma Spraying:Robotic thermal spray cells deposit wear-resistant and thermal barrier coatings across aerospace and industrial gas turbine applications. US Midwest coating houses are retrofitting automated powder feed systems to extend equipment life, though custom engineering fragments implementation timelines.
- Electrospray Technology:Sub-50 micrometer titanium and cobalt-chrome powder production serves porous orthopedic implant surfaces. Dutch and Swiss medical device coaters are qualifying these finer distributions, compressing incumbent gas atomization margins in biocompatible applications.
- Thermal Plasma:High-energy discharge systems dominate industrial volume throughput where deposit efficiency governs cost economics.
- Non-thermal Plasma:Atmospheric pressure operation enables inline sterilization protocols displacing ethylene oxide in medical device finishing.
Thermal Plasma retains the largest installed base. Electrospray Technology is gaining share fastest.
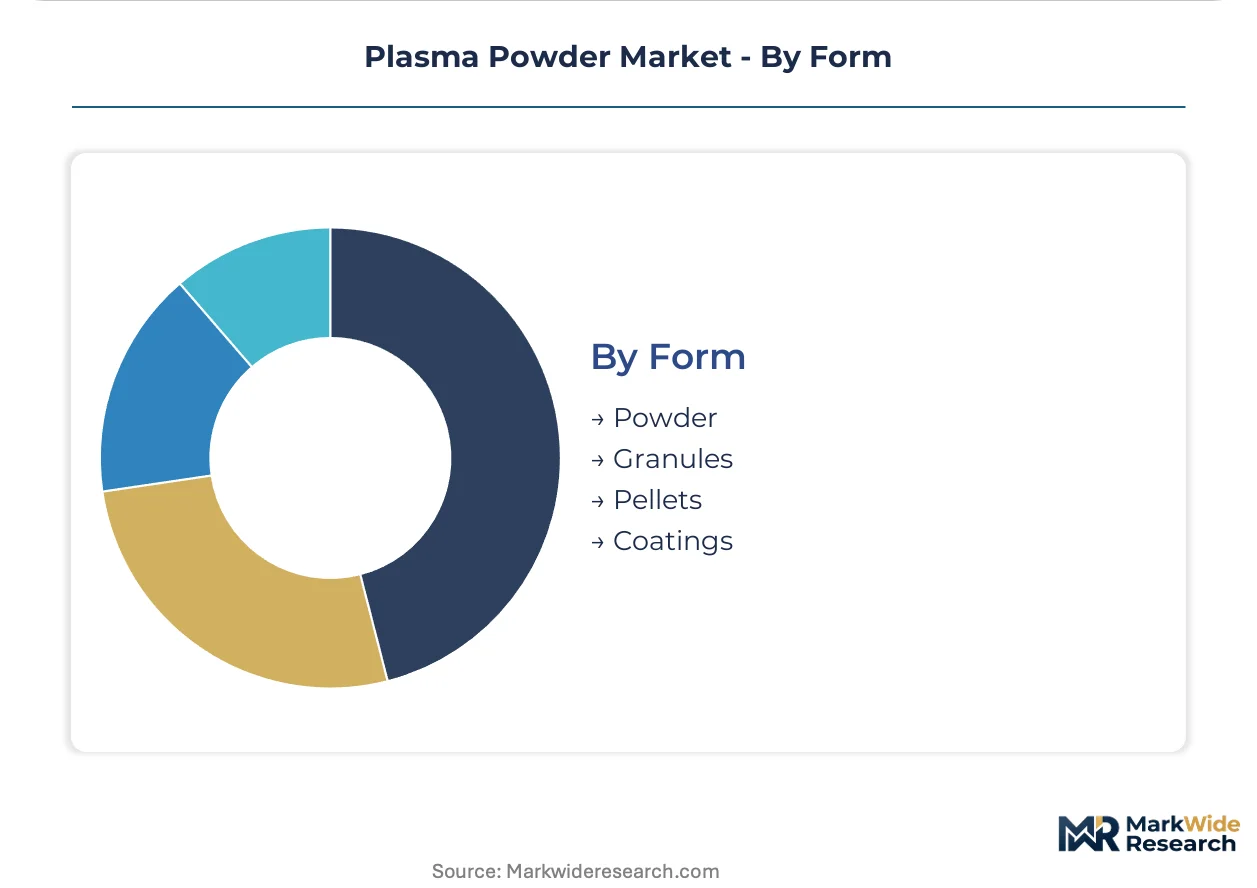
Form:
Supply concentration in powder atomization contrasts with emerging pelletization investments targeting automated thermal spray dust reduction and flow consistency improvement.
- Powder:Spherical morphology feedstock between 10 and 100 micrometers serves thermal spray deposition and additive manufacturing where melt flow governs deposit efficiency. REACH authorization protocols for nickel-bearing compositions are forcing reformulation in European electronics applications.
- Pellets:Densified feedstock reduces dust exposure and improves flow consistency in automated robotic spray operations. German precision manufacturing clusters are piloting pellet feed systems to streamline handling in high-volume automotive coating lines.
- Granules:Intermediate sizing serves specialty thermal spray applications requiring controlled feed rates.
- Coatings:Pre-applied plasma-deposited layers eliminate powder handling for medical device assemblers.
Powder dominates commercial transactions. Pellets are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH authorization protocols and EU MDR Class III implantable standards anchor European demand for high-purity plasma powder. Regulatory stringency in Switzerland and Germany is pulling qualified atomization capacity toward Central European precision manufacturing clusters.
Germany
Baden-Württemberg's orthopedic OEMs are consolidating coating supply through in-house plasma spray operations. The EU MDR tightens biocompatibility mandates for cardiovascular and orthopedic applications. Stuttgart and Munich precision manufacturing clusters concentrate captive electrospray atomization facilities serving implantable device manufacturers.
Switzerland
Swissmedic certification requirements and EU MDR alignment drive premium positioning for cold plasma formulations. The Lake Geneva corridor hosts medical device coaters qualifying sub-50 micrometer titanium powders. Geneva and Basel clusters specialize in porous implant surface functionalization for orthopedic and dental applications.
United States
FDA 21 CFR Part 820 quality system requirements constrain market access for non-compliant plasma coating suppliers. Aerospace primes mandate domestic atomization sources for critical engine component coatings under dual-use export controls. The US Midwest retains robotic thermal spray cells retrofitting automated powder feed systems for industrial gas turbine applications.
China
MIIT industrial policy and GB standards govern plasma spray equipment manufacturing and powder feedstock specifications. Shenzhen Taier Biotechnology anchors Asia-Pacific supply through captive electrospray manufacturing lines. The Pearl River Delta concentrates atmospheric plasma system production for electronics and automotive conformal coating applications.
India
India's PLI scheme for medical devices attracts plasma spray coating investments for orthopedic and dental implant production. CDSCO quality system requirements align with international standards for implantable device coatings. Gujarat and Karnataka special economic zones concentrate new atomization facility investments targeting domestic manufacturing incentives.
Plasma Powder Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in plasma powder production. Captive electrospray and plasma spray infrastructure consolidation is forcing mid-scale processors toward contract manufacturing partnerships or exit. Three archetypes dominate: protein extraction infrastructure owners leveraging feedstock streams, electrospray manufacturing specialists serving medical-grade specifications, and ISO-certified thermal barrier coating protocol providers. Competitive moves center on backward integration into feedstock supply and strategic partnerships with aerospace OEMs for additive manufacturing feedstock qualification.
Among protein extraction infrastructure owners, Darling Ingredients Inc. exemplifies backward integration into plasma-derived powder feedstock streams. Shenzhen Taier Biotechnology occupies a position within the electrospray manufacturing specialist tier, anchoring Asia-Pacific supply capacity. APC Inc. represents the ISO-certified protocol provider archetype, sitting within the aerospace thermal barrier application segment where qualified supplier status commands premium positioning.
| Leading Market Players |
|---|
| APC Inc. |
| Lican Alimentos S.A. |
| Darling Ingredients Inc. |
| Acontex GmbH |
| British Aqua Feeds |
| Sonac |
| Shenzhen Taier Biotechnology |
| Otto Chemie Pvt. Ltd. |
| ACTIPRO |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German orthopedic OEMs and Swiss atomization facilities lock in argon feedstock access while anchoring price visibility across EU MDR qualification cycles. These arrangements insulate premium-tier suppliers from spot market volatility in inert gases while forcing mid-scale processors toward contract manufacturing partnerships.
Pricing Analysis
Price spreads between German precision manufacturing clusters and Asia-Pacific contract manufacturers compress as REACH authorization timelines extend qualification costs. Three-tier pricing structure across medical-grade, aerospace-certified, and industrial-standard levels reflects certification investment differentials. Cost compression in atmospheric plasma systems intensifies because automotive electronics buyers consolidate volume procurement. Medical device OEMs exhibit lowest price sensitivity due to lot traceability mandates, while automotive Tier 2 suppliers face acute margin pressure from HVOF substitution.
Supply Chain Analysis
Germany and Switzerland anchor high-purity atomization capacity for implantable coatings, while China concentrates atmospheric plasma system manufacturing for electronics applications. European facilities draw from Qatar and Algeria for argon and helium feedstock, creating single-source vulnerability during energy market stress. Distribution runs through qualified supplier programs in aerospace maintenance channels and ISO 13485-certified distributor networks in medical devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among aerospace primes and orthopedic OEMs with captive plasma spray operations, fragmenting Tier 2 coating house economics across Germany's Baden-Württemberg region and the US Midwest.
For Market Incumbents: Consolidate backward integration into inert gas supply through long-term offtake agreements with Qatari producers. Expand captive electrospray capacity in Stuttgart and Munich clusters to defend against emerging electrospray specialists threatening orthopedic margins. Prioritize ISO 13485 certification maintenance as notified body audit backlogs delay competitor market access. For New Entrants and Emerging Players: CDSCO fast-track certification for implantable coatings offers entry into India's PLI scheme medical device zones. Target Gujarat and Karnataka special economic zones where domestic manufacturing incentives attract plasma spray investments. Pursue direct-to-manufacturer powder sales in aerospace MRO channels where lot traceability commands premium positioning absent distributor markups. For Investors and Strategic Acquirers: Capital is best deployed toward protein extraction infrastructure owners with latent feedstock stream leverage into plasma-derived powders. Five-to-ten year viability hinges on EU MDR enforcement intensity and additive manufacturing feedstock qualification velocity. Monitor ECHA substance evaluation timelines for nickel-based powder restrictions as inflection signals for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Inert Gas Supply | Long-term argon offtake agreements with Qatari producers reduce allocation risk exposure. |
| ISO 13485 Certification Fast-Track | Expedited notified body audits accelerate market access for cardiovascular stent coating suppliers. |
| Captive Electrospray Capacity Expansion | In-house atomization facilities in Stuttgart clusters protect lot traceability and IP for orthopedic OEMs. |
| Direct-to-Manufacturer Powder Sales | Bypassing distributor markups captures margin in aerospace MRO channels requiring qualified supplier status. |
| REACH Compliance Reformulation Investment | Tungsten carbide-cobalt alternatives secure qualified supplier status ahead of ECHA evaluation deadlines. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across plasma atomization facilities, thermal spray coating houses, and medical device OEM procurement teams. Primary interviews with biomedical engineers, GPO contracts managers, and aerospace quality assurance directors combined with secondary validation from FDA 510(k) filings, ECHA substance evaluation databases, and SEC 10-K disclosures from integrated feedstock suppliers. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Across the analysis window, the analytical framework segments by product type, end-use industry, technology, and form factor while modeling regional production hub dynamics. CAGRs derive from fitted growth curves against qualification timeline constraints and additive manufacturing adoption trajectories. Forecast inputs incorporate EU MDR implementation pace, REACH authorization delays, and inert gas supply concentration risk.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR enforcement intensity or accelerated ECHA substance restrictions would require recalibration. Forecasts reflect assumptions regarding aerospace OEM captive production trends and medical device outsourcing economics. Recalibration cycles align with material shifts in regulatory authorization timelines and dual-use export control classifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Gulf Collagen Market
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Small Molecules Innovator Contract Development and Manufacturing Organization Market
Specialty Compounds
GCC Specialty Chemicals Market
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
Polyoxin Market
Specialty Compounds
Global Black Masterbatch Market
Specialty Compounds
Gypsum-Free Plaster Market
Specialty Compounds
Tosyl Chloride Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Global Zinc Acetylacetonate Market
Specialty Compounds
Compounding Systems Market
Specialty Compounds
Chromium Phosphate Market
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
Low Density Sheet Moulding Compound (SMC) Market