
 Gypsum-Free Plaster Market | 2026-2036
Gypsum-Free Plaster Market Size, Share, and Industry Trends Forecast 2026-2036
Gypsum-Free Plaster Market Foresight
ISO 14001 environmental management certification is collapsing as a baseline market-access filter rather than a differentiator for gypsum-free plaster suppliers. Knauf AG leverages its captive lime supply network across Central Europe to sustain cost parity with conventional plaster. Saint Gobain competes through dedicated R&D centers in France that specialize in polymer-modified binder systems. Tarmac anchors its position in the United Kingdom by controlling regional aggregates-to-plaster logistics channels.
Gypsum-free plaster comprises mineral binders such as hydrated lime, dolomite, or magnesium oxide combined with siliceous fillers and cellulose ethers, formulated to achieve comparable workability and surface finish without calcium sulfate hemihydrate. The material serves commercial and residential construction where moisture resistance, breathability, or sulfate-source restrictions govern specification. Cement-based formulations dominate volume in repair work and exterior cladding segments where structural rigidity and weathering resistance command premium placement. Polymer-modified products represent the fastest-growing category in decorative finishing as architects specify enhanced adhesion and crack resistance for bespoke interior surfaces.
REACH chemical registration requirements in Europe, EPA emissions thresholds for mineral processing in the United States, and BIS construction-grade standards in India collectively shape formulation chemistry, labeling obligations, and cross-border shipment eligibility. The EU F-Gas Regulation indirectly amplifies gypsum-free alternatives by pressuring energy-intensive gypsum calcination processes that rely on fluorinated refrigerants in kiln operations. Stakeholders must monitor evolving embodied-carbon disclosure rules under the EU CSRD to anticipate which binder chemistries will retain specification access in public procurement.
Market Dynamics
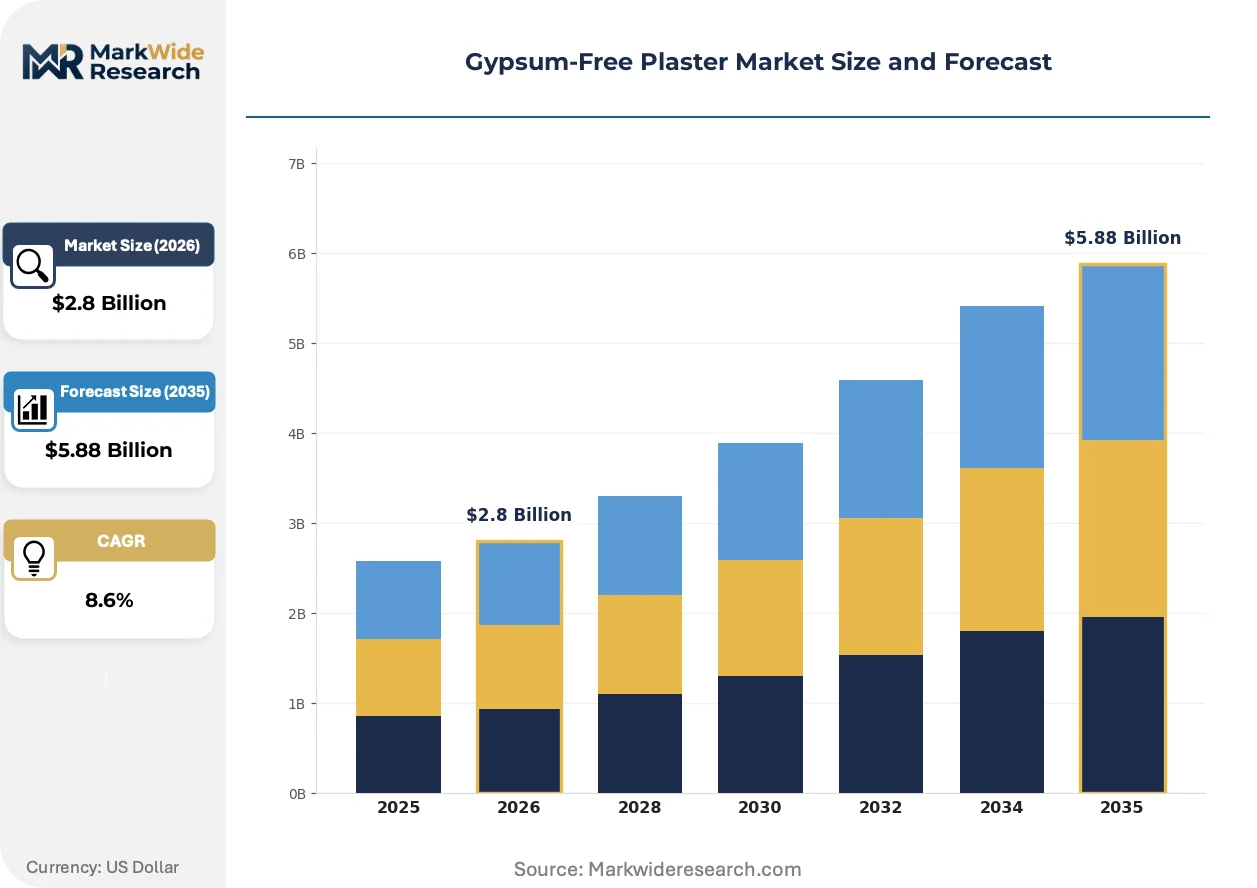
The EU Green Deal's embodied-carbon disclosure mandates are compressing specification windows for conventional gypsum plaster, forcing reformulation investments across the supply base as public procurement rules harden.
Growth Catalysts
- EU F-Gas Regulation:Kiln operators face refrigerant-phaseout deadlines that elevate energy-intensive gypsum calcination costs, tilting project economics toward lime-based and magnesium oxide alternatives in Western European retrofit pipelines.
- Moisture-resistant exterior cladding:Cement-based gypsum-free formulations capture repair-work specifications where breathability and freeze-thaw durability outweigh first-cost sensitivity in Nordic residential markets.
- Polymer-modified decorative finishing:Architects in France and Germany specify enhanced adhesion chemistries for bespoke interior surfaces, pulling volume from conventional ready-mix plaster through performance-based selection criteria.
Market Restraints
- Captive lime supply concentration:Central European suppliers with backward-integrated quarry networks control cost-parity thresholds, raising entry barriers for independent blenders lacking in-house mineral extraction.
- Cellulose ether input volatility:Price swings in etherified cellulose derivatives—critical for workability retention—compress margin predictability for mid-scale formulators without long-term chemical supply contracts.
- REACH registration burden:Novel binder chemistries face multi-year toxicity dossier requirements that delay market entry against incumbent gypsum-plaster formulations with grandfathered substance registrations.
Strategic Opportunities
- India BIS construction-grade standardization:Emerging formaldehyde-emission and compressive-strength benchmarks create first-mover positioning for exporters with pre-certified magnesium oxide plaster portfolios.
- CSRD-aligned embodied-carbon accounting:Public-sector tender rules in Germany and the Netherlands now reward products with verified Environmental Product Declarations, opening specification access for low-carbon binder systems.
- Digital specification platforms:Building-information-modeling libraries that embed material-carbon data are displacing traditional merchant-distributor influence, enabling direct architect-to-manufacturer engagement for specialty plaster lines.
Industry Challenges
- Skilled applicator scarcity:Gypsum-free plaster demands modified trowel techniques and extended curing protocols that outpace vocational training throughput in Poland and Romania's construction labor pools.
- Multi-certification timeline compression:Simultaneous pursuit of CE marking, ISO 14001, and national fire-reaction classifications stretches quality-assurance bandwidth for mid-cap suppliers targeting cross-border public contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gypsum-Free Plaster Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resin-Based, Cement-Based, Polymer-Modified, Air-Dried Application: Indoor Use, Exterior Cladding, Decorative Finishing, Repair Work Customer Type: Construction Companies, DIY Enthusiasts, Architects, Contractors Distribution Channel: Online Retail, Building Supply Stores, Direct Sales, Distributors |
| Companies Covered | Tarmac, Knauf AG, Global Mining company, Yoshino Gypsum Co. Ltd., Jonoub Gypsum, Saint Gobain, Georgia Pacific, American Gypsum, Zawami Minerals Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gypsum-Free Plaster Market Shifts & Advancements
Formulation chemistry and specification workflows are diverging simultaneously as regulatory pressure and digital procurement tools reshape how plaster products reach end-use applications.
Alkali-activated binder systems incorporating ground granulated blast-furnace slag are fragmenting the traditional lime-cement dichotomy in gypsum-free plaster. Infrastructure contractors in the Netherlands and Belgium are piloting these formulations for tunnel-lining repairs where sulfate attack resistance governs material selection. The technology is fragmenting established supply relationships by enabling steel-industry byproduct streams to bypass conventional mineral-supplier channels entirely.
REACH chemical registration requirements are tightening substance-volume thresholds for cellulose ether additives used in polymer-modified plaster. ECHA's 2023 update to guidance on nanomaterial classification has forced reformulators to resubmit dossiers for modified cellulose grades, delaying product launches by 12-18 months. Decorative-finishing specialists in France are responding by consolidating formulation platforms around fewer, higher-volume ether chemistries to amortize compliance costs.
Building-product procurement through centralized framework agreements is displacing spot purchasing by regional merchant distributors. Facility-management consortia in Germany now aggregate plaster demand across multi-site hospital and university portfolios, compressing supplier bases to three certified vendors per technical category. This concentration is most visible in North Rhine-Westphalia, where public-sector construction frameworks have halved active plaster-supplier counts since 2022.
Gypsum-Free Plaster Market Segmentation
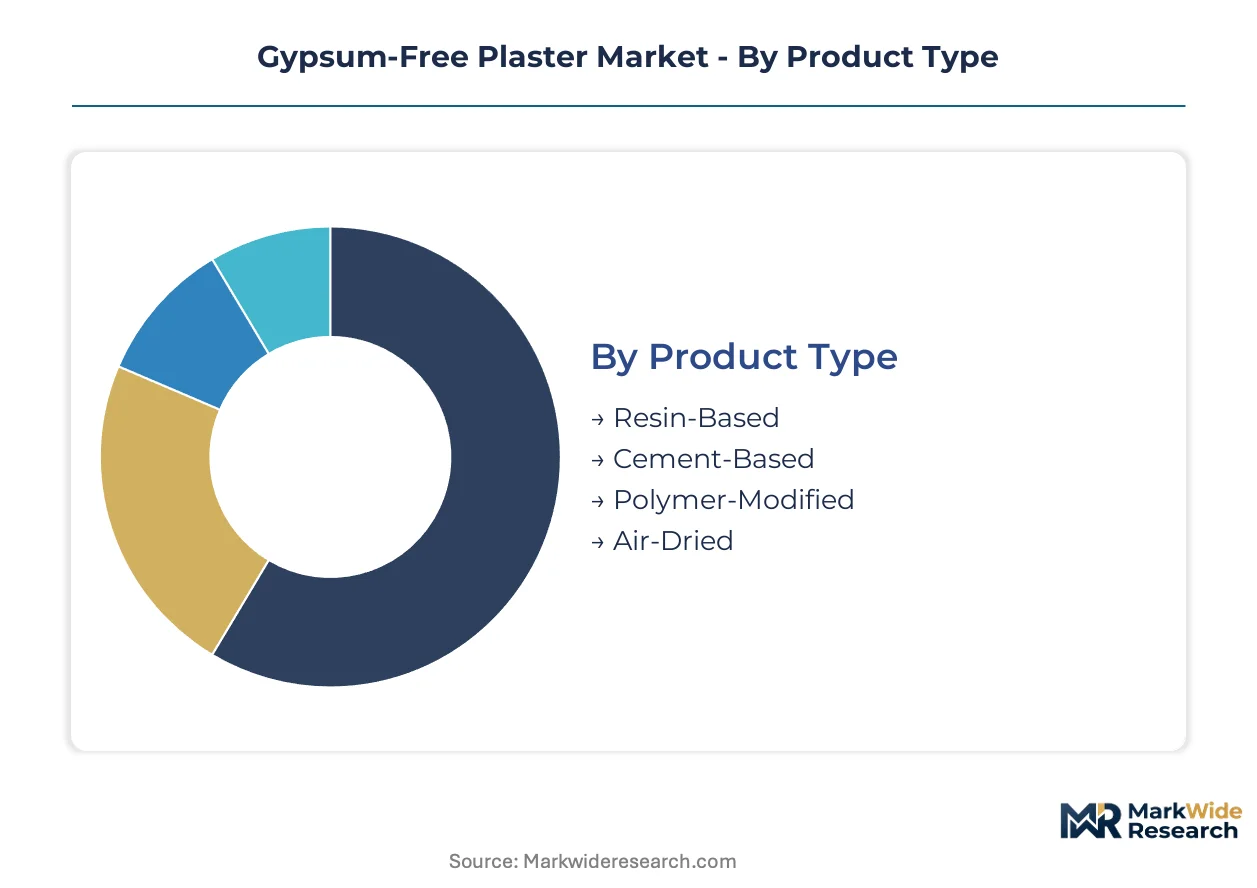
Gypsum-free plaster segments fragment across formulation chemistry, end-use application, and procurement channel, each carrying distinct margin profiles and certification burdens. Specification workflows in Western Europe now favor products with pre-verified Environmental Product Declarations, compressing supplier bases in high-volume categories while opening niches for specialty formulations.
Product Type:
Merchant distributors in Germany and France push cement-based and polymer-modified lines through building supply stores, while resin-based specialty formulations reach architects via direct technical sales teams.
- Resin-Based:Synthetic binder systems incorporating acrylic or epoxy resins deliver chemical resistance and substrate adhesion for industrial refurbishment. Demand clusters in pharmaceutical cleanroom retrofits across Belgium and the Netherlands where surface hygiene protocols override material cost.
- Cement-Based:Portland cement and hydrated lime blends dominate volume through standardized bags at building supply retailers. German residential contractors specify these formulations for exterior cladding repairs where freeze-thaw durability and breathability satisfy the EU Green Deal's embodied-carbon thresholds.
- Polymer-Modified:Cellulose ether-enhanced systems with improved workability retention and crack resistance. Decorative finishing specialists in France specify these for bespoke interior surfaces requiring enhanced adhesion.
- Air-Dried:Magnesium oxide and dolomite formulations curing through atmospheric carbonation rather than hydraulic set. Niche positioning in heritage restoration projects where moisture management and reversibility govern material selection.
By volume, cement-based leads. By growth pace, polymer-modified is ahead.
Application:
Cost tier stratification separates commodity repair work from premium decorative specifications, with exterior cladding occupying a mid-tier position defined by weathering performance requirements.
- Indoor Use:Standard wall and ceiling finishing in residential and commercial construction. German housing associations specify low-carbon lime-based systems for multi-family retrofit programs under public procurement frameworks.
- Exterior Cladding:Cement-based formulations with enhanced water repellency and vapor permeability. Nordic residential markets in Sweden and Denmark favor these for rain-screen constructions where breathability prevents interstitial condensation.
- Decorative Finishing:Thin-coat systems with pigmented or textured surface effects. Architects in Paris and Munich specify polymer-modified variants for high-visibility interior spaces where surface uniformity commands premium positioning.
- Repair Work:Patch and restoration compounds for damaged substrates. Volume concentrates in Poland and Romania's aging housing stock where structural maintenance outpaces new construction.
Repair work generates the highest shipment volumes. Decorative finishing claims the steepest expansion trajectory.
Customer Type:
Procurement authority is shifting from general contractors toward architects and facility managers as digital specification platforms embed carbon-accounting data directly into design workflows.
- Construction Companies:Large-scale developers and general contractors purchasing through framework agreements. German hospital and university consortia now aggregate demand across multi-site portfolios, compressing supplier counts.
- DIY Enthusiasts:Retail consumers purchasing pre-mixed bags through building supply stores and online channels. Price sensitivity dominates, with limited specification influence.
- Architects:Design professionals specifying products with verified Environmental Product Declarations. Netherlands-based practitioners increasingly embed material-carbon data in BIM libraries, enabling direct manufacturer engagement.
- Contractors:Specialized applicators with modified trowel techniques for gypsum-free systems. Skilled labor scarcity in Poland and Romania limits category expansion despite regulatory tailwinds.
Construction companies drive absolute volume. Architects are gaining the fastest specification influence.
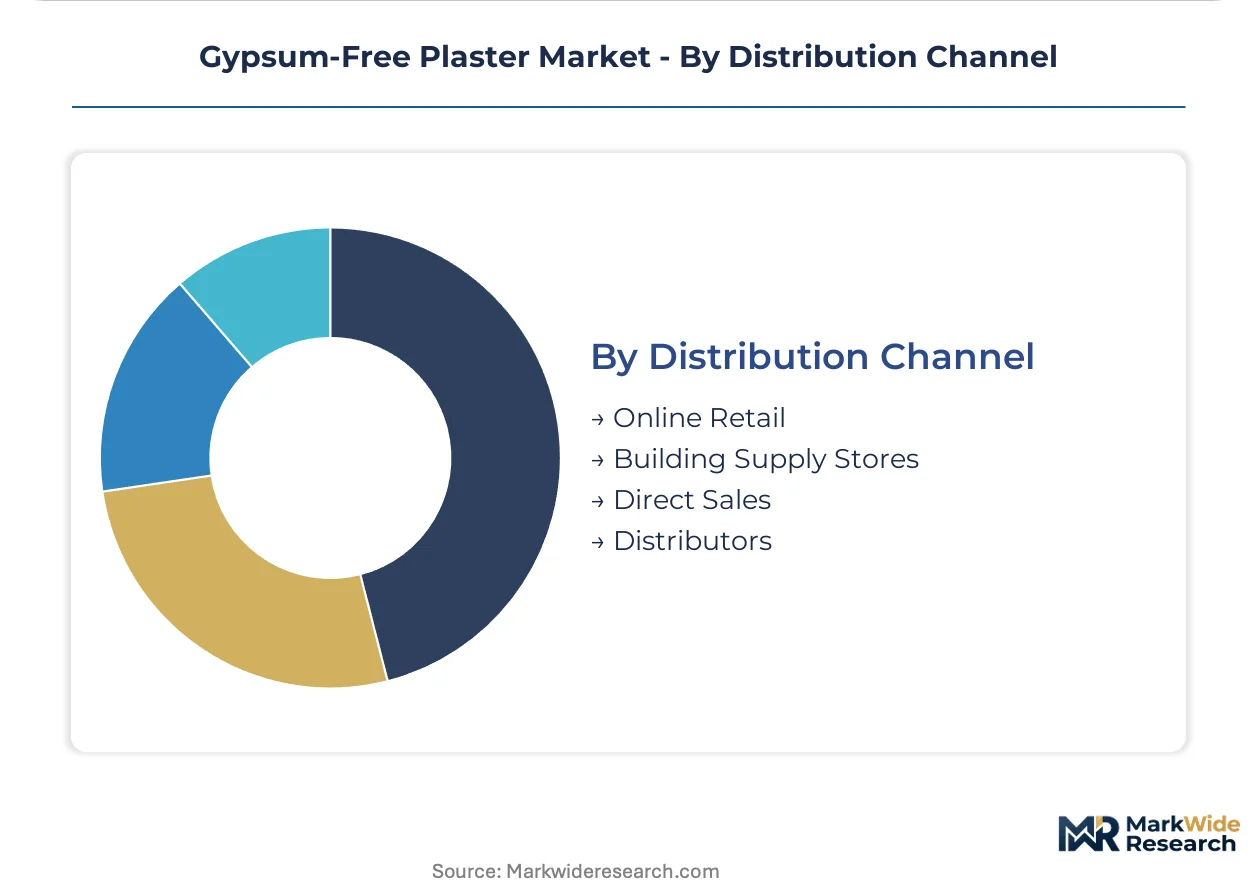
Distribution Channel:
Supply concentration varies by channel, with direct sales capturing the highest-margin specialty formulations while distributors handle commodity cement-based volumes.
- Online Retail:E-commerce platforms serving DIY segments and small contractors. Limited penetration for technical specialty products requiring application guidance.
- Building Supply Stores:Regional merchant networks stocking standardized cement-based and air-dried formulations. North Rhine-Westphalia's public-sector frameworks have halved active supplier counts since 2022.
- Direct Sales:Manufacturer technical representatives engaging architects and large contractors. Polymer-modified and resin-based lines flow through this channel to capture specification premiums.
- Distributors:Wholesale intermediaries with logistics control over regional aggregates-to-plaster supply chains. Tarmac's UK network exemplifies this model for cement-based volume.
Building supply stores handle the greatest shipment volume. Direct sales channels are expanding most quickly for high-margin specialty lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine freight corridor links German industrial zones to Mediterranean ports, cementing Central Europe's centrality in gypsum-free plaster supply chains. Port of Rotterdam bulk mineral terminals handle dolomite and magnesium oxide imports for Benelux formulators. This infrastructure underwrites Western Europe's dominance in low-carbon binder distribution.
Germany
Residential retrofit programs in North Rhine-Westphalia drive cement-based formulation demand. The EU Green Deal's embodied-carbon disclosure rules now govern public procurement for multi-family housing associations. Stuttgart's construction material clusters host captive lime supply networks that sustain cost parity with conventional plaster.
France
Architects in Paris specify polymer-modified systems for decorative interior finishes requiring enhanced adhesion. REACH chemical registration requirements force reformulators to consolidate around fewer cellulose ether chemistries. Lyon-based R&D centers specialize in bespoke binder systems for heritage restoration projects.
United Kingdom
Tunnel-lining repair specifications in London favor alkali-activated slag formulations with sulfate attack resistance. The country's building safety regulations post-Grenfell emphasize fire-reaction classifications for exterior cladding materials. Manchester's aggregates-to-plaster logistics channels anchor regional cement-based volume.
Netherlands
Infrastructure contractors pilot ground granulated blast-furnace slag binders for moisture-critical applications. CSRD-aligned embodied-carbon accounting now rewards products with verified Environmental Product Declarations in public tenders. Rotterdam's mineral import terminals enable direct steel-industry byproduct sourcing that bypasses traditional supplier channels.
India
Maharashtra's urban housing stock generates repair-work demand for cement-based gypsum-free compounds. BIS construction-grade standardization on formaldehyde-emission and compressive-strength benchmarks shapes import eligibility. Mumbai's merchant distributors stock pre-certified magnesium oxide portfolios for first-mover exporters.
Gypsum-Free Plaster Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry and supply chain control. The vendor base splits between backward-integrated quarry operators and independent blenders dependent on merchant mineral supply. Three archetypes dominate: captive lime networks, polymer-modification specialists, and regional logistics controllers. Competitive moves concentrate on framework agreement capture and certification bandwidth expansion.
Among European-based suppliers, Knauf AG exemplifies the captive-mineral archetype through its Central European quarry network. Saint Gobain occupies a position within the polymer-modification tier, anchoring French R&D specialization in cellulose ether-enhanced systems. Tarmac represents the logistics-control archetype, with its UK aggregates-to-plaster distribution infrastructure.
| Leading Market Players |
|---|
| Tarmac |
| Knauf AG |
| Global Mining company |
| Yoshino Gypsum Co. Ltd. |
| Jonoub Gypsum |
| Saint Gobain |
| Georgia Pacific |
| American Gypsum |
| Zawami Minerals Co. |
| Others |
Supply & Pricing Matrix
Ground granulated blast-furnace slag substitution for conventional lime binders is redrawing procurement geography across the Rhine-Alpine corridor while compressing margin structures for captive-quarry incumbents. This input shift simultaneously opens Rotterdam's mineral terminals to steel-industry byproduct streams and erodes the pricing power of Central European backward-integrated suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction dynamics, with polymer-modified decorative lines commanding certification-grade premiums while commodity cement-based bags compete on volume scale. Price differentiation hinges on Environmental Product Declaration verification and regional logistics reach, with German hospital consortia extracting steepest discounts through multi-site framework aggregation. Cost compression in standard-grade cement formulations is intensifying because REACH registration amortization burdens fall heaviest on mid-scale blenders. DIY enthusiasts at building supply stores exhibit highest price sensitivity; architects specifying bespoke interior finishes show least.
Supply Chain Analysis
Strait of Hormuz transit exposure for magnesium oxide feedstocks creates vulnerability for Benelux formulators dependent on Asian dolomite shipments. Geographic supply concentration centers on Germany, France, and the Netherlands, with captive lime networks in Stuttgart and Lyon anchoring regional cost parity. Raw material dependencies encompass etherified cellulose derivatives, ground granulated blast-furnace slag, and hydrated lime. Single-source vulnerability pervades the cellulose ether tier where ECHA nanomaterial reclassifications have thinned qualified suppliers. Distribution runs through building supply stores for commodity volumes and direct technical sales for specialty lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around German facility-management consortia and Netherlands-based architect networks, fragmenting traditional merchant-distributor intermediation as digital specification platforms embed carbon-accounting data directly into procurement workflows.
For Market Incumbents: Consolidate framework agreement capture through CSRD-aligned Environmental Product Declaration pre-certification, defending against alkali-activated slag entrants by deepening captive lime supply control across Central European quarry networks. Channel control investments in Rotterdam bulk mineral terminals offset steel-industry byproduct bypass threats. For New Entrants and Emerging Players: Differentiate on BIS construction-grade pre-certification for magnesium oxide portfolios targeting Maharashtra's urban repair-work demand, the most penetrable geography given India's emerging formaldehyde-emission benchmarks. Direct architect engagement through BIM-embedded material-carbon data offers viable go-to-market positioning against established distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed polymer-modification specialists holding concentrated French R&D capabilities and REACH-compliant cellulose ether supply contracts. Long-term viability over a multi-year horizon favors targets with certification bandwidth for simultaneous CE marking, ISO 14001, and national fire-reaction classifications. Watch ECHA substance-volume threshold tightening for cellulose ethers as inflection indicator for formulation platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Lime Supply | Knauf AG's Central European quarry network sustains cost parity against conventional plaster incumbents. |
| REACH-Compliant Cellulose Ether Consolidation | Saint Gobain's Lyon R&D centers amortize registration costs across fewer, higher-volume ether chemistries. |
| CSRD-Aligned EPD Pre-Certification | German hospital consortia now mandate verified Environmental Product Declarations for framework eligibility. |
| Rotterdam Bulk Mineral Terminal Control | Tarmac's aggregates-to-plaster logistics channels anchor UK cement-based volume against slag-bypass threats. |
| BIS Construction-Grade Standardization | Mumbai merchant distributors stock pre-certified magnesium oxide portfolios for first-mover export positioning. |
Research Methodology
A standing panel of plant managers at Benelux formulators, procurement leads at German hospital consortia, technical R&D directors at polymer-modification specialists, and distributor channel partners provided ongoing calibration across the study period. Primary interview findings triangulated against customs and trade data from Eurostat, construction-material filings from BSI and DIN standardization bodies, SEC 10-K disclosures from listed building-products suppliers, and ECHA REACH registration databases. Bottom-up shipment volume estimates from formulation-grade tiering converged with top-down demand-side modeling across retrofit and new-build application segments.
Consistency checks validated volume and value outputs against external benchmarks including embodied-carbon disclosure filings under the EU Green Deal, national construction statistics from Destatis and INSEE, and mineral extraction licensing records from regional geological surveys. The analytical framework modeled formulation chemistry, end-use application, procurement channel, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating EU F-Gas Regulation compliance cost pass-through, REACH registration timeline compression, and CSRD procurement rule adoption curves.
Forecasts assume regulatory continuity in EU REACH, EPA emissions thresholds, and India BIS construction-grade regimes; material policy shifts would require re-modeling. Specific risk factors encompass ECHA nanomaterial classification updates, EU Green Deal embodied-carbon disclosure threshold adjustments, and skilled applicator training throughput constraints in Eastern European labor markets. Practitioners should keep alternative scenarios live as F-Gas Regulation refrigerant phaseout deadlines and steel-industry byproduct supply availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Thioglycolate Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
Acetyl Tyrosine Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Methyl Anthranilate Market
Specialty Compounds
Additive Masterbatch Market
Specialty Compounds
Metasulphite Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Acrylic Pad Market
Specialty Compounds
GCC Hydroxypropyl Methylcellulose Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Chromatography Silica Resins Market
Specialty Compounds
Global Zinc Phosphate Market
Specialty Compounds
White Carbon Black Market