
 Quinidine Sulfate Market | 2026-2036
Quinidine Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Quinidine Sulfate Market Analysis
Maintenance and compliance service contracts around cardiac rhythm management is repositioning how quinidine sulfate reaches end users, bundling drug supply with patient monitoring protocols. Cipla Inc. leverages its generic cardiovascular portfolio to sustain hospital formulary placement across North America. Merck and Co. Inc. anchors its position through backward integration into alkaloid sourcing. Teva Pharmaceutical Industries Ltd. competes on manufacturing scale, operating high-volume tablet lines that serve retail pharmacy networks.
Quinidine sulfate is a dextrorotatory stereoisomer of quinine, typically formulated as the dihydrate salt with a molecular weight of 782.94 g/mol, functioning as a class Ia antiarrhythmic agent that blocks sodium channels and prolongs cardiac action potentials. Tablet formulations dominate current revenue due to established bioequivalence profiles and long-standing USP monograph compliance, while oral solutions represent the fastest-expanding category as pediatric and geriatric dosing requirements reshape prescription patterns. Hospital pharmacy procurement of injection-grade quinidine sulfate commands premium positioning during acute arrhythmia interventions, concentrating margin pools in institutional settings.
FDA enforces current Good Manufacturing Practice standards through facility inspections and drug master file reviews, while USP Chapter 621 chromatographic methods define identity and assay thresholds that manufacturers must meet for commercial release. The European Medicines Agency applies ICH Q3D elemental impurity guidelines that constrain heavy-metal limits in quinidine sulfate APIs, shaping supplier qualification processes for EU market access. Stakeholders must monitor evolving pharmacovigilance requirements for QT-prolonging agents across multiple jurisdictions, as regulatory scrutiny of proarrhythmic risk intensifies labeling and post-market study obligations.
Market Dynamics
Hospital formulary consolidation and Medicare reimbursement tightening are compressing quinidine sulfate distribution into fewer procurement channels, forcing manufacturers to bundle patient monitoring services with drug supply contracts.
Growth Catalysts
- Cardiovascular disease prevalence:Aging populations across developed economies are expanding the addressable patient pool for antiarrhythmic therapy. Hospital emergency departments are stocking injection-grade quinidine sulfate for acute intervention protocols.
- USP monograph updates:Revised chromatographic purity standards are disqualifying marginal API suppliers and concentrating volume among certified manufacturers. This regulatory filtering is stabilizing quality-assured supply channels.
- Pediatric formulation demand:Oral solution formats are capturing prescriber preference for geriatric and pediatric dosing flexibility. Compounding pharmacies are expanding sterile preparation capacity for liquid quinidine sulfate.
Market Restraints
- Cinchona bark supply concentration:Raw alkaloid sourcing remains concentrated in Southeast Asian cultivation regions, exposing API manufacturers to climate-driven crop volatility and export restriction risk.
- QT-prolonging safety labeling:FDA-mandated black-box warnings for proarrhythmic potential are constraining prescriber willingness to initiate quinidine sulfate therapy. Pharmacovigilance reporting requirements are elevating litigation exposure.
- Generic substitution pressure:Broad patent expiration and bioequivalence-established tablet formulations are compressing branded pricing power. Retail pharmacy benefit managers are mandating automatic generic substitution at point of dispensing.
Strategic Opportunities
- Home-based cardiac monitoring integration:Wearable ECG device convergence with telehealth platforms is creating remote patient monitoring bundles that incorporate antiarrhythmic therapy management. Cardiology practices are piloting subscription-based drug-plus-device service models.
- EMA orphan drug pathway:Residual quinidine sulfate indications for rare arrhythmia subtypes may qualify for protocol assistance and fee reductions. European market access teams are evaluating centralized procedure eligibility.
- Specialty pharmacy distribution:Limited distribution networks for high-risk antiarrhythmics are displacing traditional wholesale channels. Hub-and-spoke models with REMS compliance infrastructure are capturing margin from institutional procurement.
Industry Challenges
- API synthesis expertise scarcity:Stereoselective quinidine isolation from natural sources requires specialized alkaloid chemistry capabilities that are retiring from the workforce without adequate replacement pipelines.
- ICH Q3D elemental impurity compliance:Heavy-metal testing protocol validation is extending batch release timelines and elevating analytical chemistry overhead for EU market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quinidine Sulfate Market |
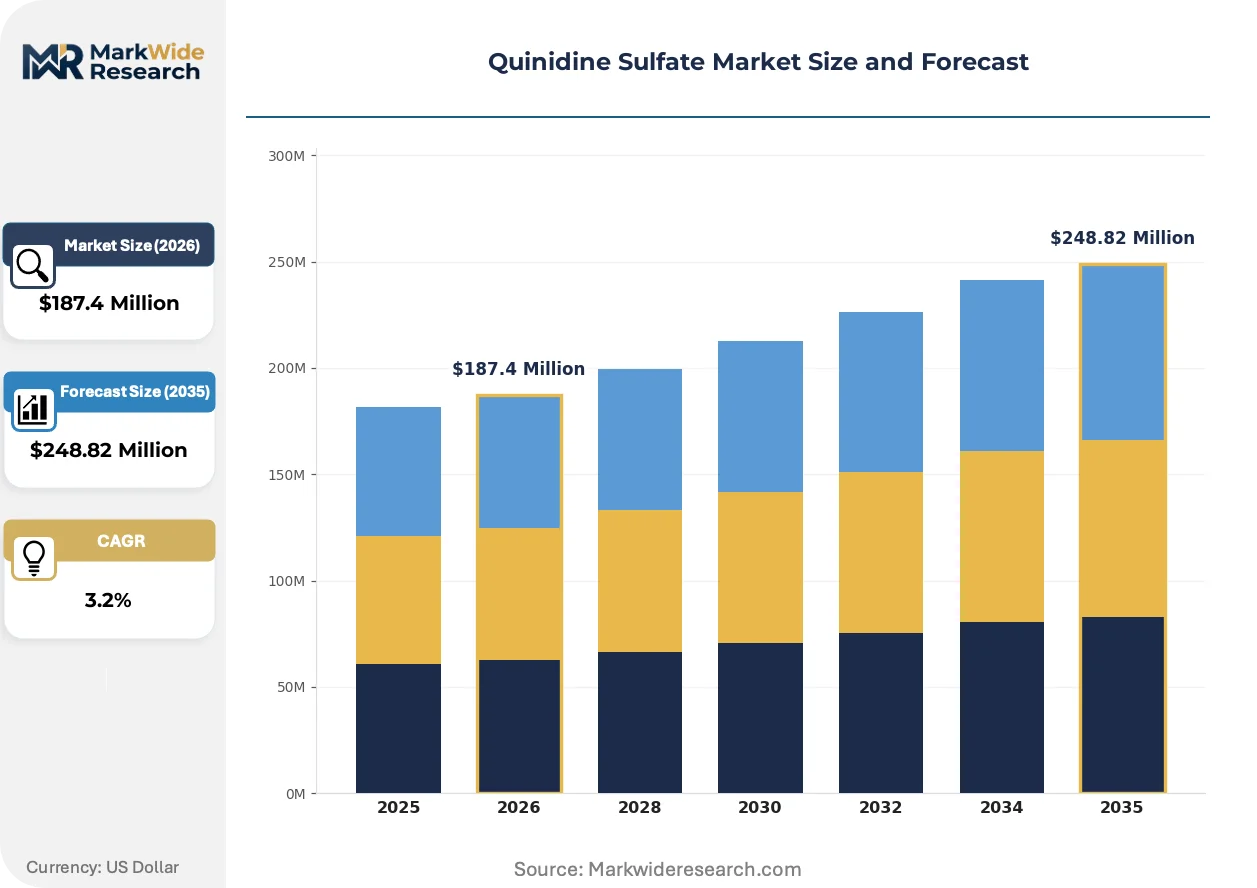
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $248.82 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Injection, Oral Solution, Capsule End User: Hospitals, Clinics, Homecare, Specialty Pharmacies Distribution Channel: Retail Pharmacy, Online Pharmacy, Hospital Pharmacy, Wholesalers Application: Cardiac Arrhythmia, Atrial Fibrillation, Ventricular Tachycardia, Others |
| Companies Covered | Bennet Pharmaceuticals Ltd., Biophore India Pharmaceuticals Pvt. Ltd., Buchler GmbH, Cipla Inc., Ipca Laboratories, Merck and Co. Inc., Teva Pharmaceutical Industries Ltd., PMC Group Inc., Lark Laboratories India Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quinidine Sulfate Market Emerging Trajectories
Continuous manufacturing and real-time release testing are displacing batch-oriented quinidine sulfate production, compressing quality control cycles while FDA process analytical technology guidance accelerates regulatory acceptance.
Hot-melt extrusion for amorphous solid dispersion is overtaking conventional wet granulation in quinidine sulfate tablet processing. Contract development and manufacturing organizations are installing twin-screw extrusion lines to serve generic sponsors seeking bioequivalence differentiation. This platform is enabling fixed-dose combination formulations with companion cardiovascular agents.
EMA's intensified pharmacovigilance requirements for QT-prolonging agents are mandating periodic safety update reports with cardiovascular mortality signal detection. Marketing authorization holders are investing in registry-based outcome studies to satisfy post-authorization measure obligations. The injectable segment is absorbing disproportionate compliance cost due to acute care liability exposure.
Hospital procurement committees are consolidating antiarrhythmic purchasing into cardiovascular service line bundles that incorporate device implantation and drug therapy. Integrated delivery networks in the United States are negotiating multi-year sole-source agreements that displace fragmented pharmacy buying. This concentration is visible in Medicare Advantage plan formulary design, where preferred drug lists are narrowing to two suppliers maximum.
Quinidine Sulfate Market Segmentation
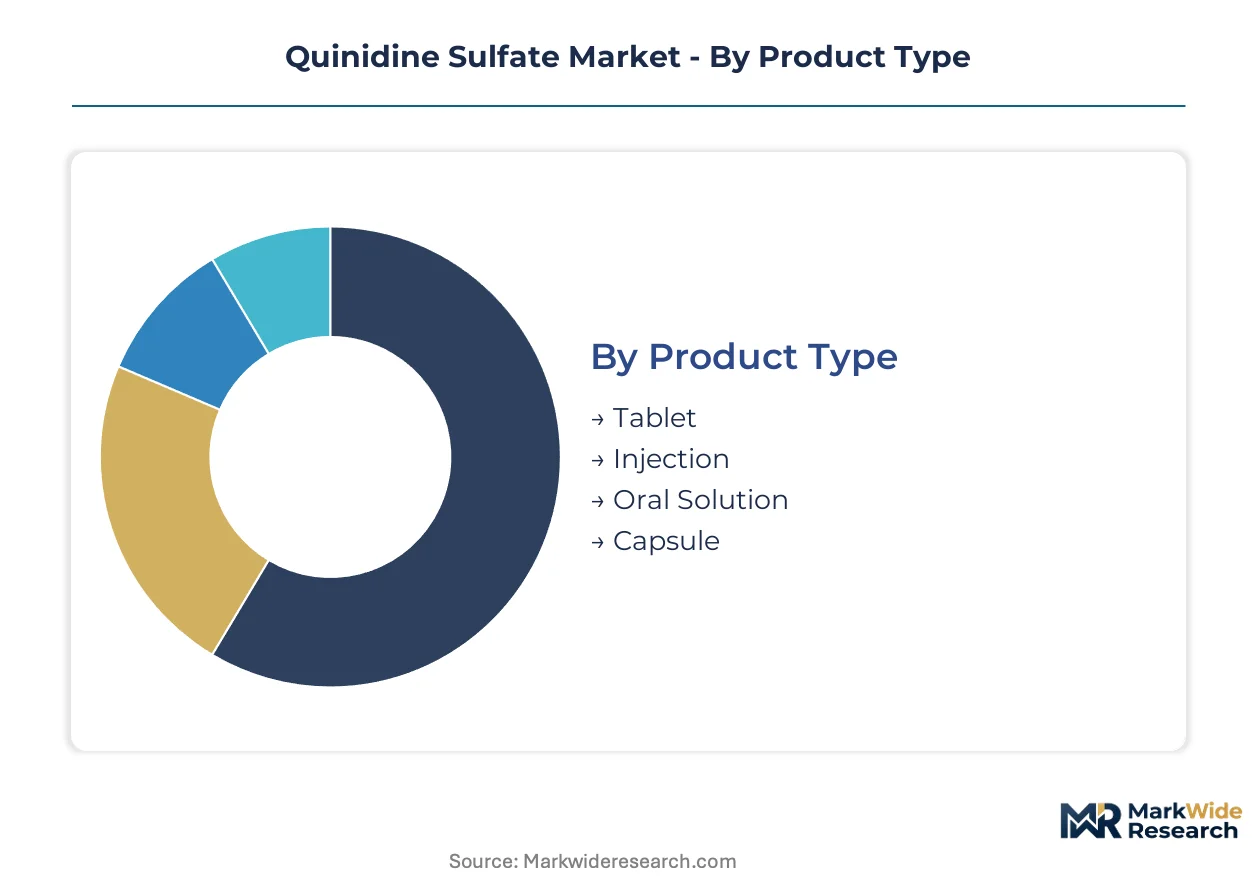
Segmentation in the quinidine sulfate market reveals how formulation choices, care settings, and procurement channels determine competitive positioning. Manufacturers must align production capabilities with the specific compliance and logistics requirements of each segment cluster.
Product Type:
Customization versus standardization splits sharply across this category, with legacy formats competing against emerging delivery innovations for formulary placement.
- Tablet:Compressed quinidine sulfate dihydrate formulations dominate hospital and retail dispensing due to established USP dissolution profiles and bioequivalence documentation. Medicare Part D reimbursement sustains volume leadership in United States outpatient settings despite generic substitution pressures.
- Injection:Sterile quinidine sulfate for intravenous administration commands premium positioning in emergency department protocols for acute arrhythmia conversion. Hospital pharmacy procurement concentrates this segment within institutional buying committees that negotiate sole-source contracts.
- Oral Solution:Liquid formulations enable weight-based dosing flexibility for pediatric and geriatric populations. Compounding pharmacies are expanding sterile preparation capacity to serve this niche.
- Capsule:Gelatin-encapsulated alternatives offer taste masking and modified release options. Limited manufacturers maintain dedicated capsule lines given tablet format economies of scale.
Leading the category by volume: Tablet. Expanding most quickly: Oral Solution.
End User:
Cost tier stratification separates acute intervention sites from chronic management settings, with reimbursement intensity declining across the care continuum.
- Hospitals:Acute care institutions stock injection-grade quinidine sulfate for rapid arrhythmia termination under continuous cardiac monitoring. FDA-mandated REMS compliance infrastructure elevates procurement qualification thresholds.
- Clinics:Outpatient cardiology practices initiate oral quinidine sulfate therapy with telemetry supervision. United States-based electrophysiology clinics are piloting remote monitoring bundles that integrate drug dispensing with wearable ECG surveillance.
- Homecare:Home health agencies manage stable patients on maintenance oral regimens. Nursing oversight requirements limit penetration in this channel.
- Specialty Pharmacies:Limited distribution networks handle high-risk antiarrhythmics with patient counseling protocols. Hub-and-spoke models are displacing traditional wholesale channels for REMS-covered therapies.
Dominating procurement value: Hospitals. Gaining share fastest: Specialty Pharmacies.
Distribution Channel:
Volume concentration versus margin capture defines competitive positioning, with institutional buyers leveraging scale against fragmented retail networks.
- Retail Pharmacy:Chain and independent pharmacies dispense maintenance oral quinidine sulfate against generic substitution mandates from United States pharmacy benefit managers. Automated dispensing systems enforce formulary compliance at point of sale.
- Online Pharmacy:Mail-order and digital platforms serve chronic patients with 90-day supply fulfillment. Verification of REMS enrollment creates operational friction in this channel.
- Hospital Pharmacy:Centralized purchasing within integrated delivery networks consolidates antiarrhythmic procurement into cardiovascular service line bundles. Group purchasing organizations negotiate multi-year agreements that displace fragmented buying.
- Wholesalers:Traditional distributors face margin compression as direct manufacturer-to-hospital contracts proliferate. Remaining relevance centers on generic tablet stocking for retail pharmacy replenishment.
Capturing highest throughput: Hospital Pharmacy. Facing steepest erosion: Wholesalers.
Application:
Maturity gradients separate well-established indications from emerging therapeutic niches, with regulatory scrutiny intensifying for high-risk patient populations.
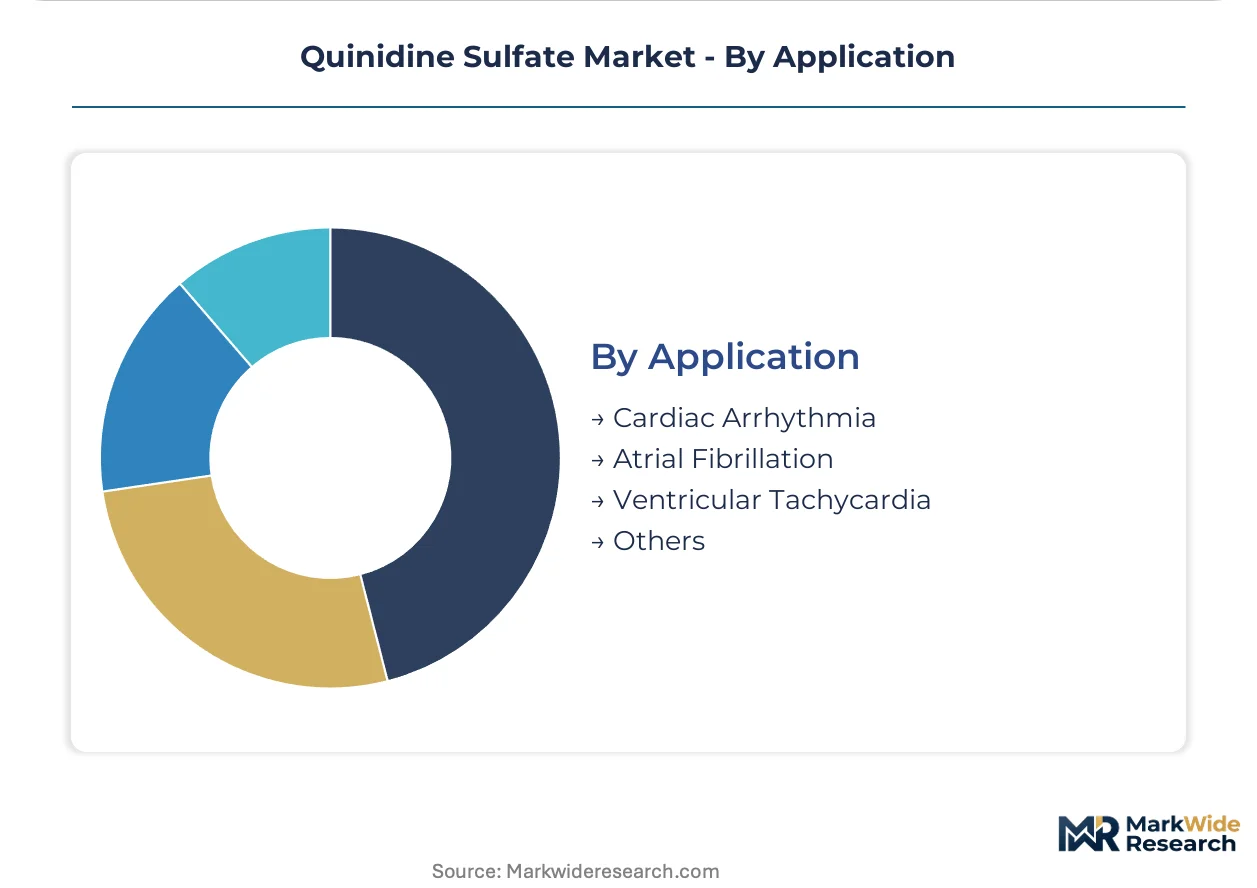
- Cardiac Arrhythmia:Broad indication category encompassing multiple rhythm disturbances where quinidine sulfate serves as second-line therapy after failure of first-line agents. FDA pharmacovigilance requirements for QT-prolonging agents elevate post-market study obligations across this application cluster.
- Atrial Fibrillation:Rate and rhythm control in AF patients represents the largest addressable population for oral quinidine sulfate. United States cardiology guidelines have downgraded quinidine preference due to proarrhythmic risk, shifting volume toward catheter ablation candidates.
- Ventricular Tachycardia:Intravenous quinidine sulfate retains niche utility for polymorphic VT storm unresponsive to standard agents. Emergency department stocking protocols sustain limited demand.
- Others:Residual indications include malaria treatment and rare arrhythmia subtypes where EMA orphan drug pathways may apply. European market access teams are evaluating centralized procedure eligibility for these niche applications.
Highest patient volume: Atrial Fibrillation. Steepest clinical guideline downgrade: Atrial Fibrillation. Narrowest but most defensible niche: Ventricular Tachycardia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing concentrates in South Asian cultivation zones while consumption tilts toward North American and European hospital systems. Cinchona bark sourcing from Indonesia and India feeds alkaloid extraction facilities serving formulation sites in Germany, Switzerland, and the United States. This geographic split shapes regulatory compliance costs and supply security calculations across the value chain.
United States
Medicare Part D reimbursement sustains outpatient dispensing of oral quinidine sulfate despite generic substitution pressure. FDA enforces current Good Manufacturing Practice standards through facility inspections and drug master file reviews that disqualify non-compliant API suppliers. Hospital procurement committees in the Northeast Corridor and California are consolidating antiarrhythmic purchasing into cardiovascular service line bundles.
Germany
EMA centralized procedure applications for quinidine sulfate products flow through German marketing authorization holders seeking EU-wide approval. ICH Q3D elemental impurity guidelines constrain heavy-metal limits in APIs, extending batch release timelines for manufacturers. The Rhine-Main industrial cluster hosts analytical chemistry service providers specializing in alkaloid purity testing for EU market access.
India
CDSCO manufacturing license requirements and state-level pharmaceutical inspectorates govern domestic quinidine sulfate tablet production. Telangana and Gujarat house API extraction facilities sourcing cinchona bark through import channels from Southeast Asia. Hyderabad-based contract manufacturers are expanding sterile preparation capacity for oral solution formats targeting pediatric export markets.
Switzerland
Swissmedic's pharmacovigilance requirements for QT-prolonging agents mandate periodic safety update reports with cardiovascular mortality signal detection. Basel anchors European regulatory strategy functions for alkaloid-based cardiovascular therapies. The country's precision chemistry heritage supports specialized stereoselective isolation capabilities for natural-source quinidine production.
Indonesia
Cinchona bark cultivation in West Java and Sumatra supplies raw alkaloid feedstock to global API manufacturers. The country's national pharmaceutical regulator oversees export certification for botanical raw materials. Climate-driven crop volatility in these cultivation regions exposes downstream manufacturers to supply interruption risk during monsoon disruption cycles.
Quinidine Sulfate Market Vendor Landscape
Capital-heavy producers with captive alkaloid sourcing compete with asset-light formulation specialists dependent on merchant API supply. The market structure shows moderate consolidation among tablet manufacturers serving retail pharmacy networks, while injection-grade production concentrates among hospital-contracted suppliers with REMS compliance infrastructure. Three archetypes dominate: vertically integrated alkaloid extractors, high-volume generic tablet manufacturers, and specialty sterile compounders. Competitive moves center on backward integration into cinchona cultivation partnerships and bundling patient monitoring services with drug supply contracts.
Among Indian pharmaceutical conglomerates, Cipla Inc. and Ipca Laboratories occupy positions as scale-driven generic manufacturers with established USP monograph compliance. Teva Pharmaceutical Industries Ltd. anchors the high-volume tablet production tier serving retail pharmacy networks across North America. Merck and Co. Inc. exemplifies the backward-integrated archetype through upstream control over natural alkaloid sourcing channels. These three companies represent distinct strategic postures within a market where manufacturing scale, regulatory certification depth, and supply chain security separate sustainable competitors from marginal participants.
| Leading Market Players |
|---|
| Bennet Pharmaceuticals Ltd. |
| Biophore India Pharmaceuticals Pvt. Ltd. |
| Buchler GmbH |
| Cipla Inc. |
| Ipca Laboratories |
| Merck and Co. Inc. |
| Teva Pharmaceutical Industries Ltd. |
| PMC Group Inc. |
| Lark Laboratories India Ltd. |
| Others |
Supply Flow & Price Mechanics
Cinchona bark alkaloid costs cascade through three pricing tiers downstream, from plantation-gate volatility in Indonesia to injection-grade premiums commanded by hospital pharmacy procurement committees in the United States.
Pricing Analysis
Cost-down pressure on oral tablet formats accelerates because Medicare Part D reimbursement tightening and pharmacy benefit manager generic substitution mandates compress retail pharmacy margins. Three-tier pricing structure across premium injection-grade, standard tablet, and economy oral solution levels separates acute care institutional buyers from maintenance therapy patients. FDA batch certification and USP monograph compliance investment drive price differentiation between certified API suppliers and marginal producers. Retail pharmacy networks exhibit highest price sensitivity, while emergency department procurement committees prioritize supply security over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian and Indian cinchona bark cultivation regions feeding alkaloid extraction facilities. API manufacturing draws from natural botanical feedstock, specialized stereoselective isolation chemistry, and chromatographic purification equipment. Climate-driven crop volatility and export restriction risk expose downstream formulation sites to supply interruption. Distribution runs through hospital pharmacy direct contracts, specialty pharmacy limited networks, and retail pharmacy wholesale replenishment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FDA current Good Manufacturing Practice enforcement and USP Chapter 621 purity standards create regulatory moats that marginal producers cannot cross.
For Market Incumbents: Deploy backward integration into cinchona cultivation partnerships to secure alkaloid feedstock against climate volatility. Expand sterile preparation capacity for oral solution formats capturing pediatric and geriatric prescribing. Consolidate hospital formulary placement through cardiovascular service line bundling that incorporates patient monitoring protocols. For New Entrants and Emerging Players: Begin with compounding pharmacy partnerships for liquid quinidine sulfate preparation serving niche dosing requirements. Target specialty pharmacy limited distribution networks with REMS compliance infrastructure as the most penetrable channel. Pursue EMA centralized procedure applications for rare arrhythmia orphan indications with protocol assistance eligibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor API extraction specialists with captive Indonesian cinchona sourcing in South Asian supply corridors. Long-term viability hinges on regulatory certification depth rather than manufacturing scale alone. Watch for FDA warning letter issuance against incumbent suppliers as inflection signal for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Cinchona plantation partnerships in Indonesia insulate alkaloid supply from monsoon disruption cycles. |
| Sterile Preparation Capacity Expansion | Oral solution manufacturing lines capture pediatric and geriatric prescribing shifting away from tablets. |
| REMS Compliance Infrastructure | FDA-mandated risk evaluation and mitigation systems qualify suppliers for high-risk antiarrhythmic distribution. |
| Cardiovascular Service Line Bundling | Integrated delivery network contracts combine drug supply with device implantation and remote monitoring. |
| EMA Centralized Procedure Application | European orphan drug pathways for rare arrhythmia subtypes reduce regulatory fees and accelerate market access. |
Methodological Framework
Document review covered FDA drug master files, USP monograph revisions, and EMA centralized procedure applications, complemented by interviews with formulary directors at integrated delivery networks, hospital pharmacy procurement managers, and regulatory affairs leads at generic manufacturers. Secondary validation drew from ClinicalTrials.gov cardiovascular outcome studies, Medicare Part D utilization databases, and customs records tracking cinchona bark trade flows. Bottom-up volume estimates from dosage form production data were cross-referenced against top-down expenditure analysis from payer reimbursement filings.
Historical volume trends were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the projection horizon. The analytical framework modeled segmentation across formulation type, care setting, and distribution channel, with regional regulatory clusters as an additional dimension. CAGRs were derived from trend extrapolation adjusted for patent expiration impacts and guideline preference shifts. Forecast inputs incorporated USP monograph update implementation timelines and FDA facility inspection scheduling patterns.
Underlying measurement precision varies by segment; oral tablet formats carry tighter precision than injection-grade and compounding pharmacy volumes. Forecasts reflect assumptions about Medicare reimbursement stability, cinchona crop yields, and pharmacovigilance enforcement intensity that could shift materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Polyurea Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Flexible Foam Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Kokum Butter Market
Specialty Compounds
Acetyl Tyrosine Market
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Small Molecules Innovator Contract Development and Manufacturing Organization Market
Specialty Compounds
Global Zinc Acetylacetonate Market
Specialty Compounds
China Collagen Market
Specialty Compounds
Lithium Compound Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Silicone Potting Compounds Market