
 Organoclay Market | 2026-2036
Organoclay Market Size, Share, and Industry Trends Forecast 2026-2036
Organoclay Market Analytics
The capability gap between integrated bentonite processors and specialty additive formulators is collapsing as raw material costs equalize. Minerals Technologies Inc. leverages captive montmorillonite deposits across the southeastern United States to sustain cost-advantaged feedstock security. BYK Additives & Instruments differentiates through proprietary surface modification chemistry that dominates high-performance coatings formulations in Germany and adjacent markets.
Organoclays are layered silicate minerals, typically bentonite or hectorite, intercalated with quaternary ammonium surfactants to render hydrophilic clay surfaces organophilic and compatible with polymer or solvent systems. These modified clays function primarily as rheology modifiers, thixotropic agents, and barrier enhancers in formulations requiring viscosity control or gas-impermeable films. Surface Modified Organoclays command the largest revenue share due to their versatility across paints and adhesives, while Polymer Clay Composites represent the fastest-expanding category as automotive lightweighting intensifies demand for nylon nanocomposites. Oil-Modified Clay variants occupy a mature niche in drilling fluids where established supply relationships and API certification requirements protect incumbent positions.
The EPA regulates organoclay disposal under hazardous waste classifications when quaternary ammonium compounds exceed threshold concentrations, compelling reformulation toward biodegradable surfactant alternatives. REACH registration requirements in Europe mandate full toxicological dossiers for organomodifier substances, elevating compliance costs for importers while favoring Clariant and Evonik Industries with established registration portfolios. Stakeholders must monitor the trajectory of bio-based surfactant substitution and its implications for processing economics and product certification timelines.
Market Dynamics
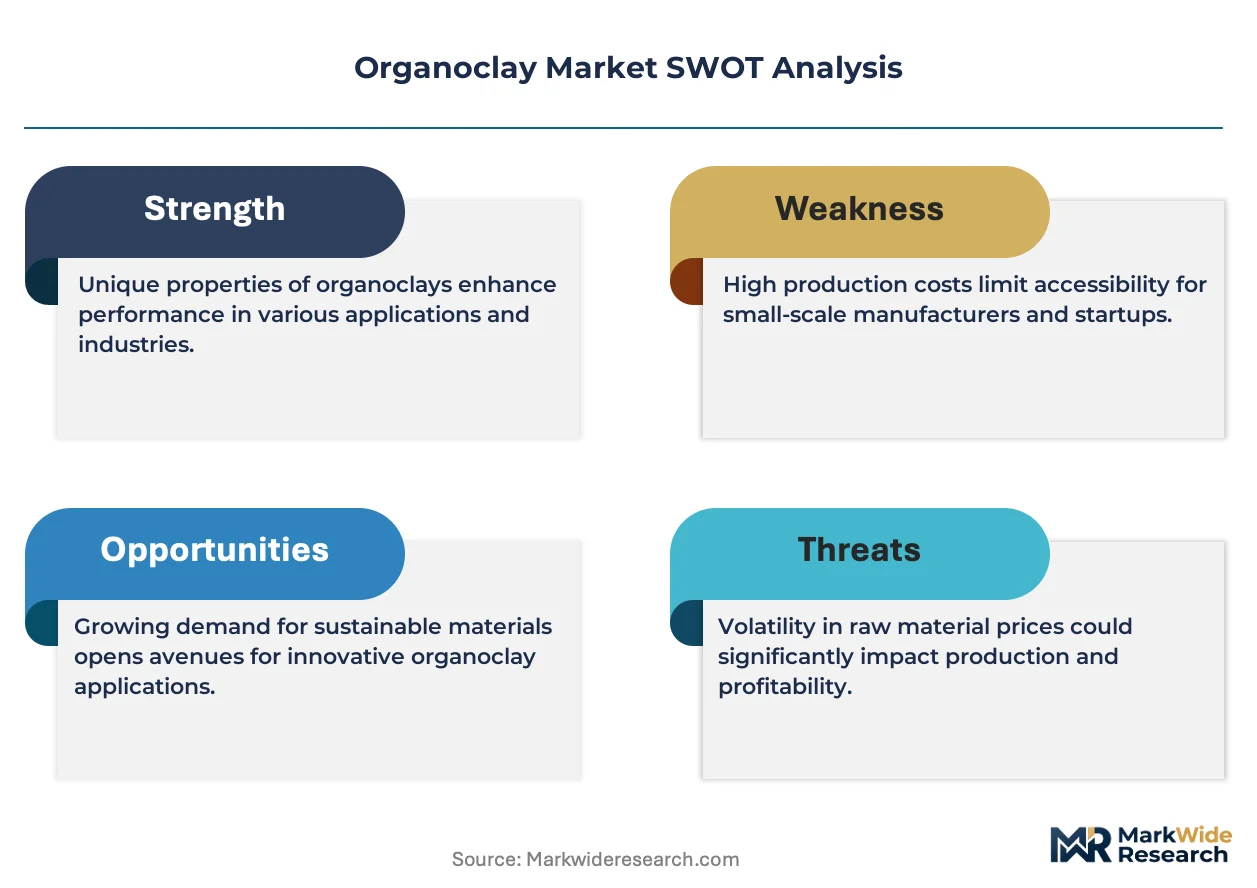
The collapse of capability gaps between integrated bentonite processors and specialty additive formulators is compressing margin structures across the value chain. Raw material cost equalization is eliminating historical feedstock advantages and forcing differentiation through surface chemistry innovation rather than mineral access.
Growth Catalysts
- High-temperature drilling expansion:Oil and gas operators in the Permian Basin and North Dakota are specifying organoclay rheology modifiers for wells exceeding 150°C bottom-hole temperatures, creating specification pull for thermally stable quaternary ammonium modifications.
- REACH registration maturation:Completed toxicological dossiers for organomodifier substances in the European Union are reducing import friction and accelerating formulation approvals for compliant suppliers.
- Automotive lightweighting mandates:Nylon nanocomposite consumption for under-hood components is accelerating as OEMs pursue gram-level mass reduction targets in Germany, Japan, and the United States.
Market Restraints
- Bentonite deposit concentration:Premium montmorillonite reserves cluster in Wyoming's Bighorn Basin and select Mediterranean deposits, creating geographic supply vulnerability for non-integrated processors.
- Quaternary ammonium cost volatility:Fatty amine feedstocks track palm oil and tallow commodity swings, compressing formulation margins during agricultural price spikes.
- EPA hazardous waste thresholds:Disposal classifications trigger when surfactant loadings exceed regulatory limits, constraining end-of-life options for drilling fluid waste in Texas and Gulf Coast states.
Strategic Opportunities
- Bio-based surfactant substitution:Choline chloride and betaine-derived modifiers are penetrating coatings formulations in the Netherlands and Belgium as ECHA evaluates reduced-toxicity alternatives.
- India automotive manufacturing:Domestic polymer clay composite capacity is underdeveloped relative to Maruti Suzuki and Tata Motors' localization requirements for engineered plastics.
- Direct-to-compounder distribution:Bypassing traditional distributor networks for tier-one adhesives manufacturers in Guangdong and Jiangsu provinces is compressing channel costs by 8-12 percentage points.
Industry Challenges
- Surface chemistry talent scarcity:Formulators with expertise in ion-exchange kinetics and exfoliation control for polymer intercalation are concentrated among retiring specialists at German and American research institutes.
- API certification timelines:Drilling fluid qualification protocols require 18-24 month validation cycles, freezing product specifications and delaying reformulation responses to regulatory changes.
- Legacy solvent system integration:Waterborne coating conversions in architectural and industrial segments demand re-engineered organoclay dispersions incompatible with established high-shear mixing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organoclay Market |
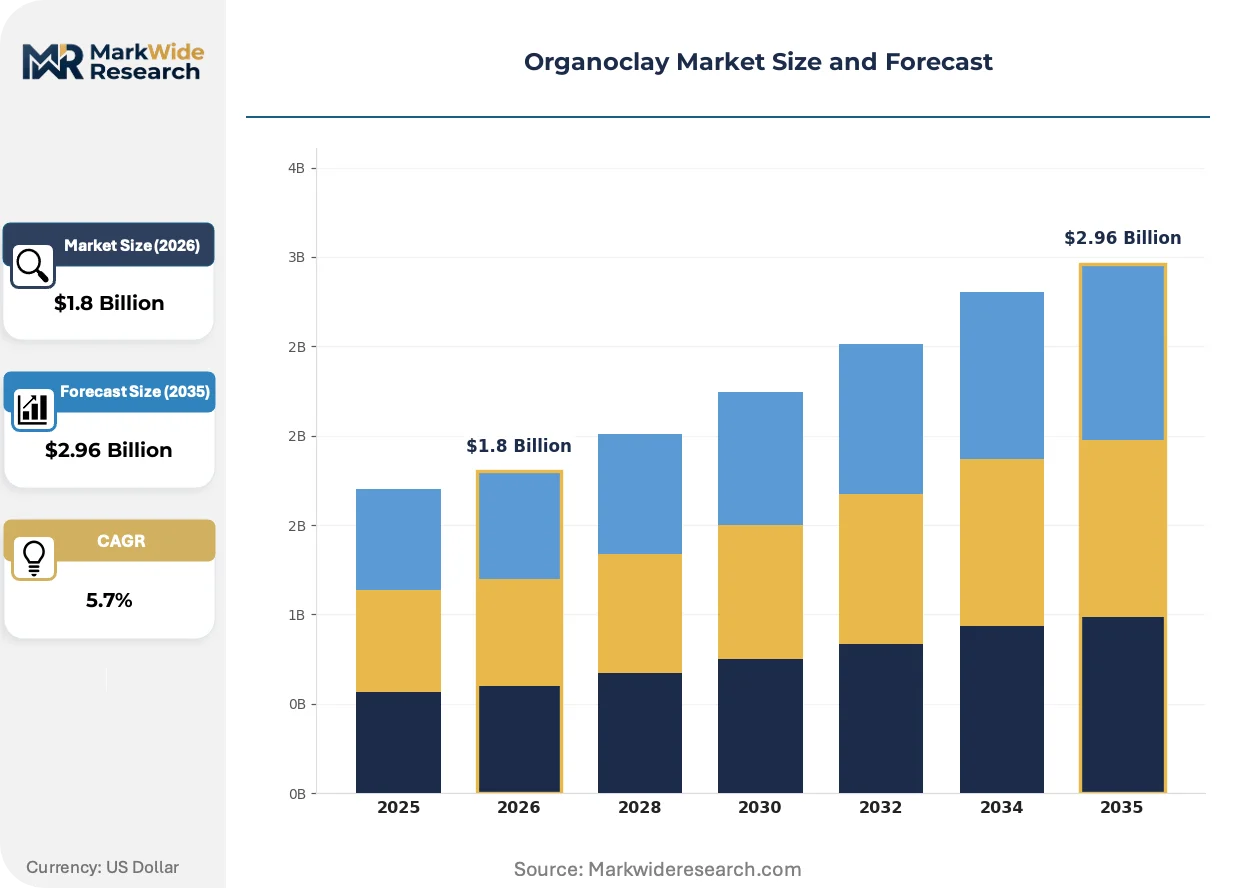
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Modified Organoclays, Polymer Clay Composites, Oil-Modified Clay, Others Application: Paints & Coatings, Packaging Materials, Rubber Production, Adhesives End User: Construction, Automotive, Electronics, Agriculture Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | Minerals Technologies Inc., BYK Additives & Instruments, Sinochem Holdings Corporation, Elementis Specialties Inc., Ashapura Minechem, Clariant, Evonik Industries, Southern Clay Products, Imerys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organoclay Market Evolving Landscape
Surface modification chemistry is advancing faster than mineral processing economics, shifting competitive advantage toward molecular design capabilities and away from captive deposit control. This reorientation favors specialists with proprietary intercalation protocols over traditional mining-integrated suppliers.
Hybrid organic-inorganic surface architectures are miniaturizing the effective particle dimensions required for transparent film applications. Optical coatings manufacturers in Japan and South Korea are adopting these nanoscale dispersions for display polarizers and anti-reflective layers. The technology is miniaturizing the addressable market from commodity drilling fluids toward high-value electronics barrier films where particle size specifications tighten below 100 nanometers.
EPA's evolving standards for quaternary ammonium compound disposal are compelling reformulation investments across the American manufacturing base. The agency's hazardous waste classification thresholds for spent drilling fluids are forcing operators toward biodegradable surfactant alternatives or on-site treatment systems. Gulf Coast service companies are responding by pre-qualifying organoclay suppliers with validated waste-stream compliance documentation.
Automotive procurement departments are consolidating approved vendor lists for polymer nanocomposite feedstocks, compressing qualification cycles from multi-year to 12-month windows. Tier-one compounders in Germany and Michigan are displacing spot-market purchasing with framework agreements specifying volume commitments and technical service integration. This concentration is most visible in nylon 6 and nylon 66 formulations where single-source qualification now dominates transmission component specifications.
Organoclay Market Segmentation
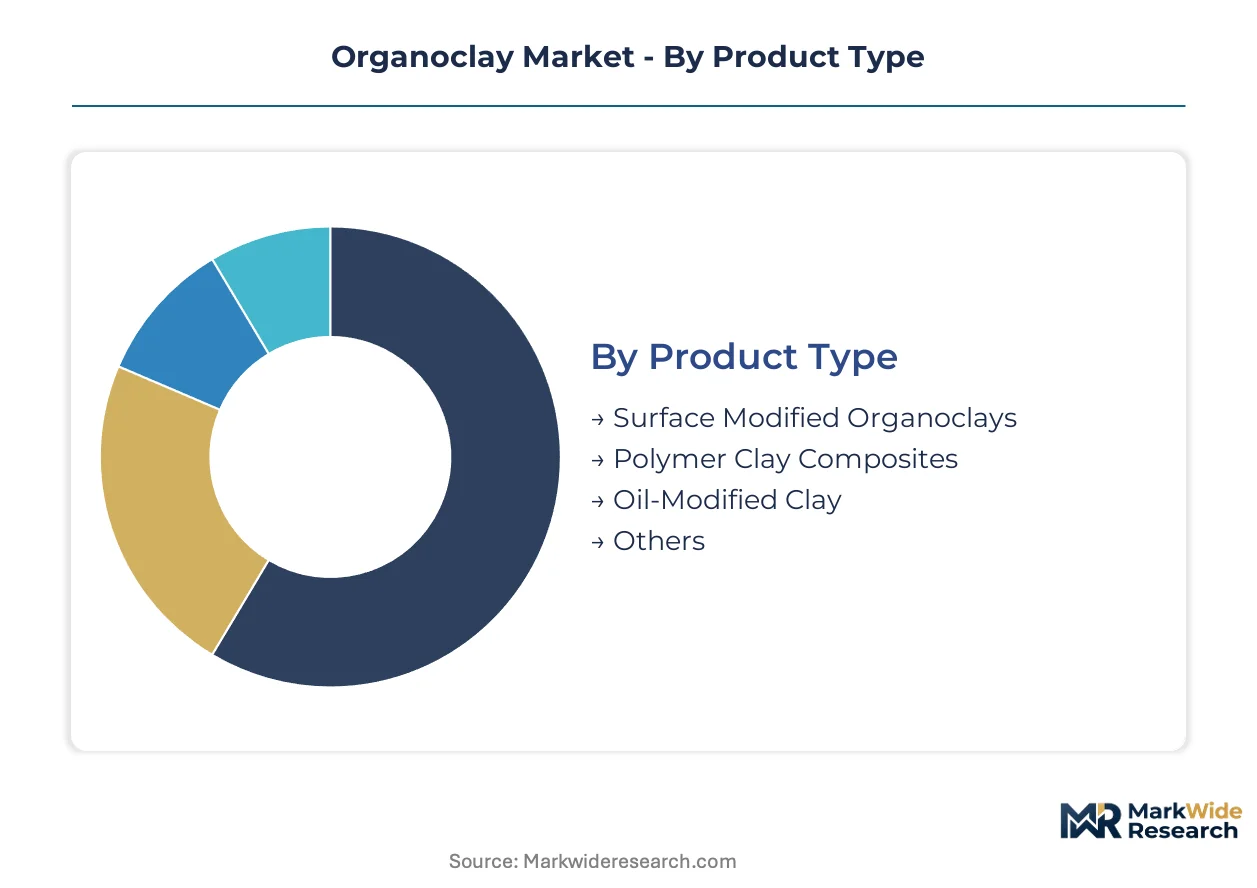
Organoclay segmentation reveals divergent vulnerability profiles across product architectures. Substitute technologies threaten mature formulations while emerging categories command premium positioning through performance differentiation.
Product Type:
Surface modification chemistry faces the most acute substitution pressure from synthetic rheology modifiers in waterborne coatings, while mineral-based alternatives compete aggressively in drilling fluids.
- Surface Modified Organoclays:Layered silicates intercalated with quaternary ammonium surfactants deliver organophilic compatibility for solvent and polymer systems. Paints and adhesives manufacturers in Germany specify these for thixotropic control in high-solids formulations where sag resistance is critical.
- Polymer Clay Composites:Exfoliated nanoclays dispersed within nylon matrices create gas barrier enhancement and dimensional stability for under-hood automotive components. OEMs in Michigan and Stuttgart are qualifying these for transmission covers and engine beauty shields as gram-level mass reduction targets tighten.
- Oil-Modified Clay:Conventional organophilic bentonites formulated for diesel and synthetic-based drilling fluids face displacement from polymeric viscosifiers in deepwater Gulf of Mexico operations.
- Others:Specialty hectorite derivatives and synthetic layered double hydroxides serve niche personal care and catalyst support applications with limited volume scale.
Surface Modified Organoclays anchors the volume base while Polymer Clay Composites gains share at the steepest rate.
Application:
Formulation cost tiers stratify sharply between commodity architectural coatings and specification-driven industrial segments.
- Paints & Coatings:Architectural, industrial, and automotive refinish formulations employ organoclays for sag control and pigment suspension. ECHA evaluations of quaternary ammonium toxicity are accelerating reformulation toward bio-based surfactant alternatives in Dutch and Belgian manufacturing.
- Adhesives:Structural and pressure-sensitive adhesive systems require precise thixotropic profiles for automated dispensing equipment. Tier-one manufacturers in Guangdong province are consolidating supplier lists to compress qualification cycles.
- Packaging Materials:Oxygen barrier films for food and pharmaceutical packaging utilize polymer nanocomposites to extend shelf life, though metallized films compete on cost in high-volume flexible packaging.
- Rubber Production:Tire and industrial rubber compounding employs organoclays as processing aids and reinforcement fillers, facing displacement from precipitated silica in rolling resistance-optimized tire treads.
Paints & Coatings generates the largest revenue pool while Adhesives demonstrates the most rapid specification migration toward nanocomposite architectures.
End User:
Customer procurement sophistication varies dramatically between project-based construction purchasing and integrated automotive supply chains.
- Automotive:OEMs and tier-one compounders specify polymer clay composites for engineered plastics qualification programs. Framework agreements with volume commitments are displacing spot-market purchasing for nylon nanocomposite feedstocks in Germany and Michigan.
- Construction:Waterproofing membranes and sealant formulations consume organoclays for rheology control, though price-sensitive project procurement limits premium product penetration.
- Electronics:Display polarizers and anti-reflective coatings in Japan and South Korea require sub-100 nanometer particle specifications for optical transparency, commanding substantial premiums over commodity grades.
- Agriculture:Controlled-release fertilizer coatings and pesticide formulations represent a developing application with limited current scale.
Automotive dominates value capture while Electronics delivers the highest margin per kilogram through specification intensity.
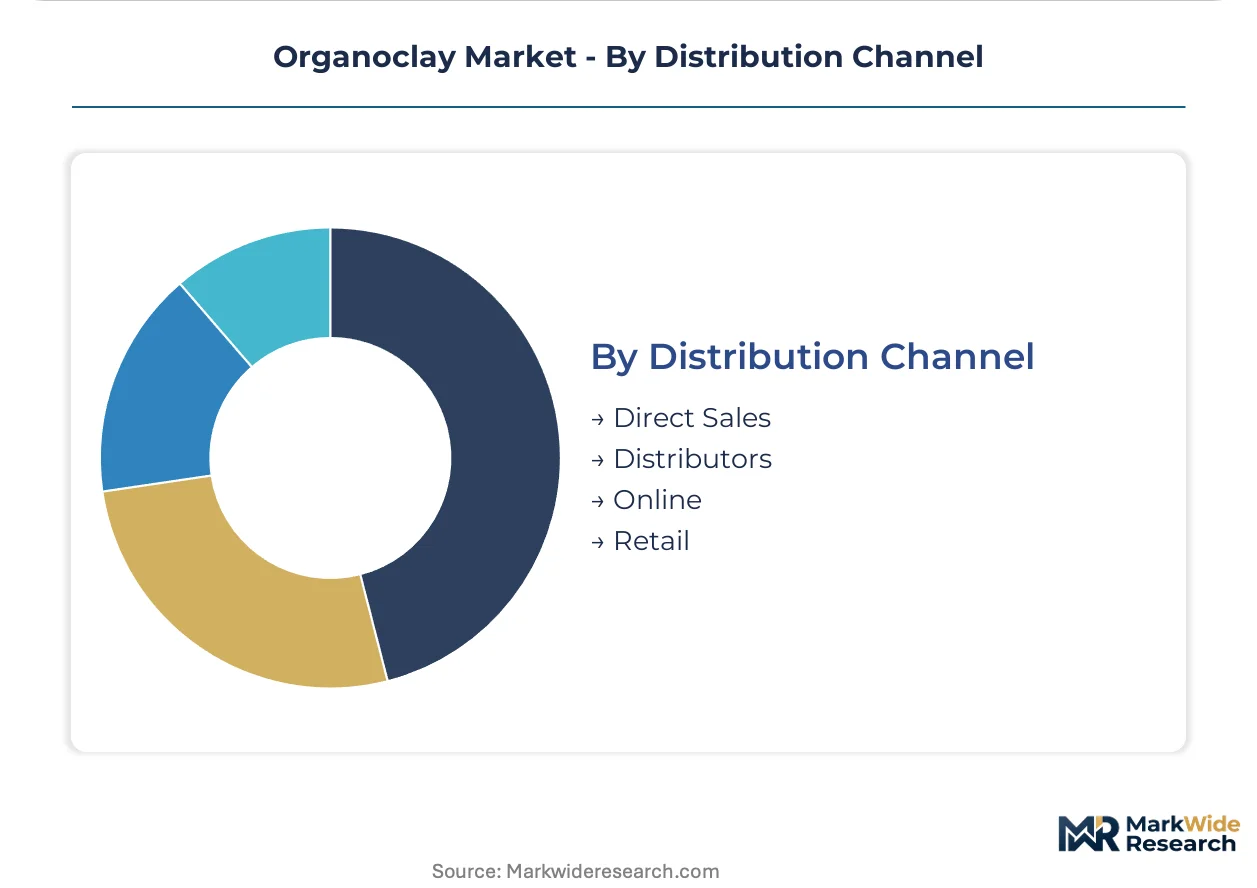
Distribution Channel:
Channel economics compress margins most severely in fragmented retail segments while direct relationships preserve technical service value.
- Direct Sales:Technical service integration and formulation co-development support specification lock-in with tier-one adhesives and coatings manufacturers. Bypassing distributor networks in Jiangsu province reduces channel costs by 8-12 percentage points.
- Distributors:Regional chemical distributors serve mid-tier formulators with inventory consolidation and credit terms, though technical support capabilities vary widely.
- Online:E-procurement platforms penetrate standard-grade drilling fluid additives where API certification reduces qualification friction.
- Retail:Limited to small-scale construction and DIY applications with minimal organoclay content per transaction.
Direct Sales commands the specification-intensive premium tier while Distributors retains the broadest geographic coverage footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate low price elasticity for specification-grade polymer nanocomposites, while construction formulators in India and China remain highly sensitive to raw material fluctuations. This divergence shapes regional competitive strategies.
United States
Permian Basin drilling operators specify thermally stable organoclay rheology modifiers for high-temperature wells exceeding 150°C. EPA hazardous waste classifications for spent drilling fluids constrain disposal options in Texas and Gulf Coast states. Houston-based service companies pre-qualify suppliers with validated waste-stream compliance documentation.
China
Automotive OEMs in Guangdong and Jiangsu provinces accelerate polymer clay composite consumption for under-hood engineered plastics. MIIT industrial standards for nanomaterial safety influence qualification protocols for domestic compounders. The Yangtze River Delta hosts expanding bentonite processing capacity serving regional coatings manufacturers.
Germany
REACH registration maturation for organomodifier substances reduces import friction for compliant suppliers. ECHA evaluations of quaternary ammonium toxicity accelerate reformulation toward bio-based surfactant alternatives in Dutch and Belgian adjacent markets. Stuttgart's automotive cluster consolidates approved vendor lists for nylon nanocomposite feedstocks.
India
Maruti Suzuki and Tata Motors drive localization requirements for engineered plastics where domestic polymer clay composite capacity remains underdeveloped. BIS standards for industrial chemical imports create compliance hurdles for non-registered suppliers. Maharashtra's automotive belt exhibits concentrated demand for transmission component specifications.
Japan
Display polarizer and anti-reflective coating manufacturers require sub-100 nanometer particle specifications for optical transparency. METI technology roadmaps for advanced materials support R&D investment in hybrid organic-inorganic surface architectures. Osaka and Nagoya electronics clusters command substantial premiums over commodity grades.
Organoclay Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Integrated bentonite processors leverage captive montmorillonite deposits for feedstock security, while specialty additive formulators differentiate through proprietary surface modification chemistry. Three archetypes dominate: mining-integrated suppliers with upstream mineral control, specialty chemical houses with molecular design capabilities, and regional compounders serving localized formulation needs. M&A activity concentrates on surface chemistry talent acquisition, and strategic partnerships between mineral processors and polymer compounders reshape distribution economics.
Within the integrated processor tier, Minerals Technologies Inc. exemplifies captive deposit control, while BYK Additives & Instruments represents specialty surface chemistry differentiation. Clariant occupies a position bridging both archetypes with established REACH registration portfolios. These three anchors illustrate how competitive advantage shifts from mineral access toward molecular design capabilities as raw material costs equalize across the value chain.
| Leading Market Players |
|---|
| Minerals Technologies Inc. |
| BYK Additives & Instruments |
| Sinochem Holdings Corporation |
| Elementis Specialties Inc. |
| Ashapura Minechem |
| Clariant |
| Evonik Industries |
| Southern Clay Products |
| Imerys |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Wyoming bentonite processors and Permian Basin drilling operators lock in both supply access and price visibility, insulating integrated suppliers from fatty amine commodity swings while constraining margin recovery during agricultural price spikes.
Pricing Analysis
After-sales technical service contracts drive lifetime value for specialty additive formulators, with annual formulation support agreements generating recurring revenue streams that exceed initial product margins. Three-tier pricing structure across REACH-registered premium grades, API-certified standard tiers, and unregistered economy imports stratifies the market. Cost compression in economy-grade drilling fluid additives is intensifying because polymeric viscosifiers capture share in deepwater applications. Construction formulators in India exhibit the highest price sensitivity, while automotive OEMs in Germany demonstrate minimal elasticity for specification-grade polymer nanocomposites.
Supply Chain Analysis
Strategic stockpiling of quaternary ammonium surfactants prevails among European coatings manufacturers anticipating ECHA regulatory actions, whereas just-in-time mineral sourcing dominates Asian automotive compounders with localized bentonite processing. Supply concentrates in Wyoming, China, and select Mediterranean deposits, with fatty amine feedstocks drawing from palm oil and tallow commodity markets. Single-source vulnerability clusters around Wyoming's Bighorn Basin premium montmorillonite reserves. Distribution runs through direct technical sales for tier-one adhesives manufacturers and regional chemical distributors for mid-tier formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collapsing capability gap between mineral processors and surface chemistry specialists has concentrated scarce talent among retiring German and American research institute formulators, creating acquisition premiums for teams with ion-exchange kinetics expertise.
For Market Incumbents: Consolidate surface chemistry talent through targeted acquisition of research institute spinouts and specialty additive laboratories in Germany and the United States. Secure captive bentonite reserves through lease extensions in Wyoming's Bighorn Basin before non-integrated processors develop alternative feedstock relationships. Synthetic rheology modifiers in waterborne coatings represent the most acute substitution threat requiring defensive patent filing. For New Entrants and Emerging Players: Lead with bio-based surfactant formulations targeting Dutch and Belgian coatings manufacturers ahead of ECHA's finalized quaternary ammonium toxicity evaluations. India automotive manufacturing presents the most penetrable white-space opportunity, where domestic polymer clay composite capacity lags Maruti Suzuki and Tata Motors localization requirements. Direct-to-compounder distribution in Guangdong province offers channel cost compression without legacy distributor relationship burdens. For Investors and Strategic Acquirers: Specialty additive laboratories with proprietary intercalation protocols and completed REACH registration dossiers represent the highest-value acquisition archetype in this market. Long-term viability hinges on molecular design capabilities displacing mineral access as the primary competitive moat. Watch for EPA hazardous waste threshold enforcement actions in Texas and Gulf Coast states as the inflection indicator for biodegradable surfactant substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Montmorillonite Reserves | Minerals Technologies secures Wyoming feedstock security against fatty amine cost volatility. |
| Bio-based Surfactant R&D Partnership | Clariant accelerates choline chloride modifier development ahead of ECHA regulatory finalization. |
| Direct Distribution Expansion in Jiangsu Province | BYK Additives compresses channel costs 8-12 percentage points for tier-one adhesives manufacturers. |
| Automotive OEM Framework Agreement Consolidation | Evonik Industries locks in nylon nanocomposite volume commitments from Stuttgart's transmission component suppliers. |
| Surface Chemistry Talent Acquisition | Elementis Specialties acquires German research institute spinout with exfoliation control expertise. |
Research Methodology
Desk research of SEC 10-K filings, customs and trade databases, and ECHA registration dossiers preceded structured interviews with plant managers at bentonite processing facilities, procurement leads at downstream coatings manufacturers, technical R&D directors at specialty additive formulators, and distribution channel partners in Guangdong and Jiangsu provinces. Primary intelligence was triangulated against secondary validation from API certification records, EPA hazardous waste documentation, and MIIT industrial standards filings. Bottom-up volume estimates from application-level consumption patterns were reconciled with top-down market sizing derived from mineral processing capacity and trade flow analysis.
Variance decomposition across product type, application, end user, and regional production hub dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate assumptions applied to baseline consumption estimates, with cross-segment elasticities calibrated against historical substitution patterns between organoclays and synthetic rheology modifiers. Forecast inputs incorporated automotive lightweighting mandate trajectories in Germany, Japan, and the United States, alongside drilling activity projections for Permian Basin high-temperature well completions.
Forecasts assume regulatory continuity in EPA hazardous waste classifications and REACH registration requirements; material policy shifts would require re-modeling surfactant substitution timelines and import friction coefficients. Revision becomes warranted when bio-based surfactant penetration in European coatings formulations crosses validated commercial scale thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
China Collagen Market
Specialty Compounds
Carbon Black for Packaging Market
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
Superacids Market
Specialty Compounds
Neohespiridine Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Silicone Masterbatches Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Lithium Compound Market
Specialty Compounds
White Carbon Black Market
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
Acetyl Serine Market