
 Global Stannic Chloride Market | 2026-2036
Global Stannic Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stannic Chloride Market Foresight
The capital-intensity divergence between integrated tin smelters and specialty chemical distributors is unwinding competitive stability in stannic chloride supply. Yunnan Tin Group leverages captive tin ore access to control feedstock costs across anhydrous grades. Merck KGaA sustains pharmaceutical and electronic-grade certification depth that smaller competitors cannot replicate. Gulbrandsen anchors North American supply through chlor-alkali integration and regional logistics infrastructure.
Stannic chloride is tin tetrachloride, a colorless fuming liquid with formula SnCl4 that hydrolyzes to hydrated oxides and serves primarily as a tin source for electroplating baths, chemical vapor deposition precursors, and polymerization catalysts. Liquid formulations dominate volume throughput in catalyst and electroplating applications where precise dosing and rapid dissolution matter. Semiconductor fabrication within the end user industry segment commands premium pricing for ultra-high-purity anhydrous material, while coatings production absorbs larger tonnages of standard-grade hydrated variants. Powder grades occupy a narrower niche in solid catalyst formulations where transport stability outweighs solubility speed.
EPA hazardous waste rules and OSHA permissible exposure limits govern American production and handling protocols, while REACH registration and the EU F-Gas Regulation indirectly shape competitive dynamics by elevating environmental compliance costs for tin chemical processors. China's MEE enforces wastewater discharge standards that affect chlorination byproduct management at domestic facilities. Stakeholders must monitor evolving semiconductor material purity specifications from customer fabs and assess backward integration into tin concentrate sourcing as a structural hedge against feedstock volatility.
Market Dynamics
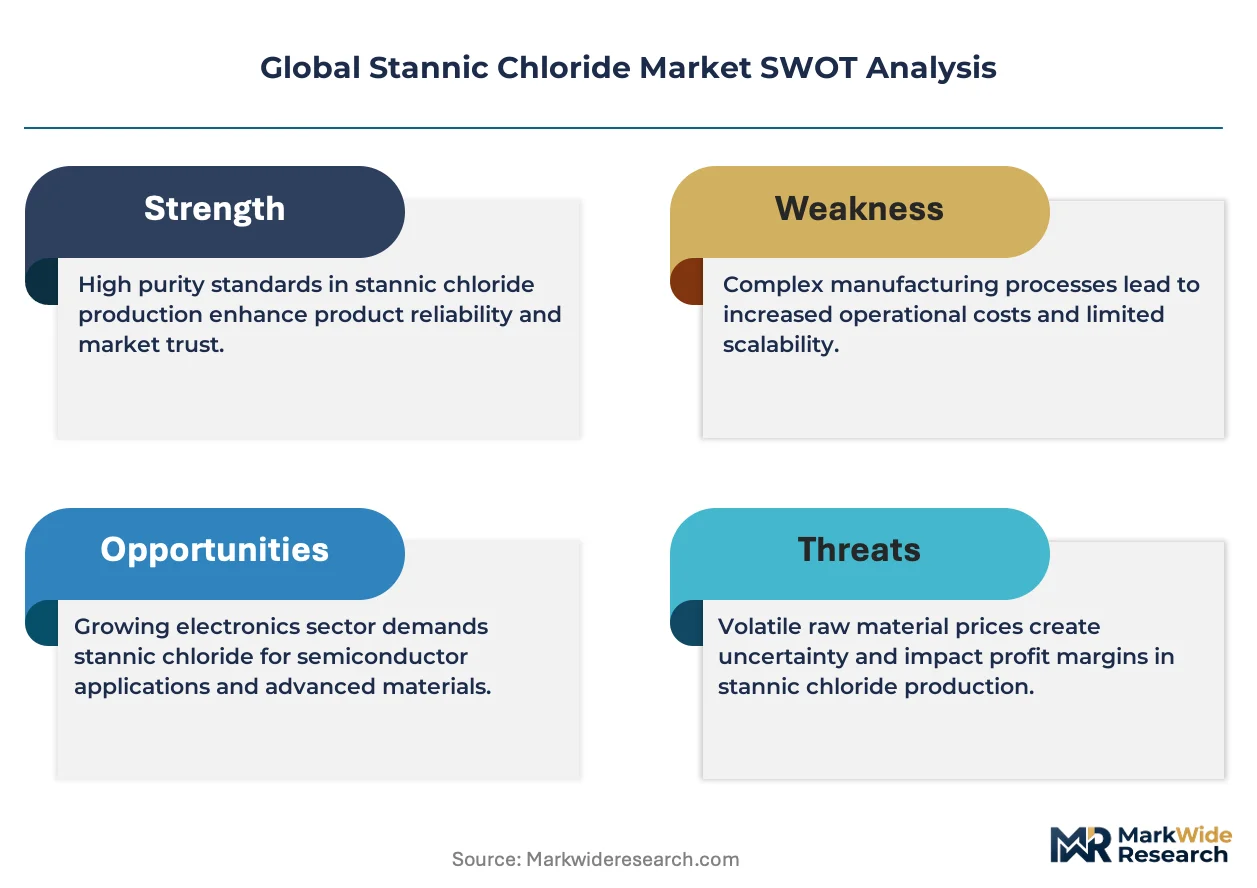
Semiconductor node shrinkage below 5nm is decomposing legacy tin precursor specifications, forcing electroplating chemical suppliers to recalibrate purity thresholds and certification protocols for atomic layer deposition compatibility.
Growth Catalysts
- Advanced node semiconductor fabrication:Tin-based precursors enable conformal barrier layers in 3nm logic chips. South Korean foundry clusters in Hwaseong and Pyeongtaek are expanding electroplating capacity for EUV lithography mask blanks.
- REACH Substance Evaluation:ECHA's 2024-2026 work program prioritizes tin compound hazard assessment, accelerating substitution toward higher-purity electronic grades that command process efficiency advantages in wet chemistry lines.
- Chlor-alkali integration:Captive chlorine supply at integrated tin smelters reduces logistics exposure and stabilizes anhydrous grade availability for chemical vapor deposition tool operators.
Market Restraints
- Tin concentrate supply concentration:Indonesian export quota volatility and Myanmar ore disruption concentrate feedstock risk with Chinese and Indonesian smelters controlling 70% of mined tin conversion.
- EPA RCRA hazardous waste classification:Spent stannic chloride solutions trigger costly disposal protocols at US electroplating facilities, elevating total cost of ownership versus alternative metal precursors.
- Technical limitation in aqueous stability:Hydrated grade hydrolysis sensitivity restricts shelf life and complicates just-in-time inventory management for coatings manufacturers.
Strategic Opportunities
- Indian semiconductor mission:Ministry of Electronics and Information Technology production-linked incentives for display and logic fab construction in Gujarat and Tamil Nadu will localize tin chemical demand by 2027.
- Solid oxide fuel cell catalysts:Tin oxide derived from stannic chloride is displacing rare earth alternatives in intermediate-temperature fuel cell anode formulations for stationary power applications.
- EU F-Gas Regulation phase-down:Fluorinated precursor restrictions in semiconductor etching processes are redirecting tool chemistry investment toward tin-based alternatives with lower global warming potential.
Industry Challenges
- Electronic-grade certification timelines:Fab qualification cycles for new precursor batches extend 18-24 months, freezing supplier switching and compressing margin recovery windows.
- Analytical chemistry skill scarcity:ICP-MS trace metal analysis expertise required for sub-ppb purity verification is concentrating at contract laboratories, creating bottlenecks for smaller compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stannic Chloride Market |
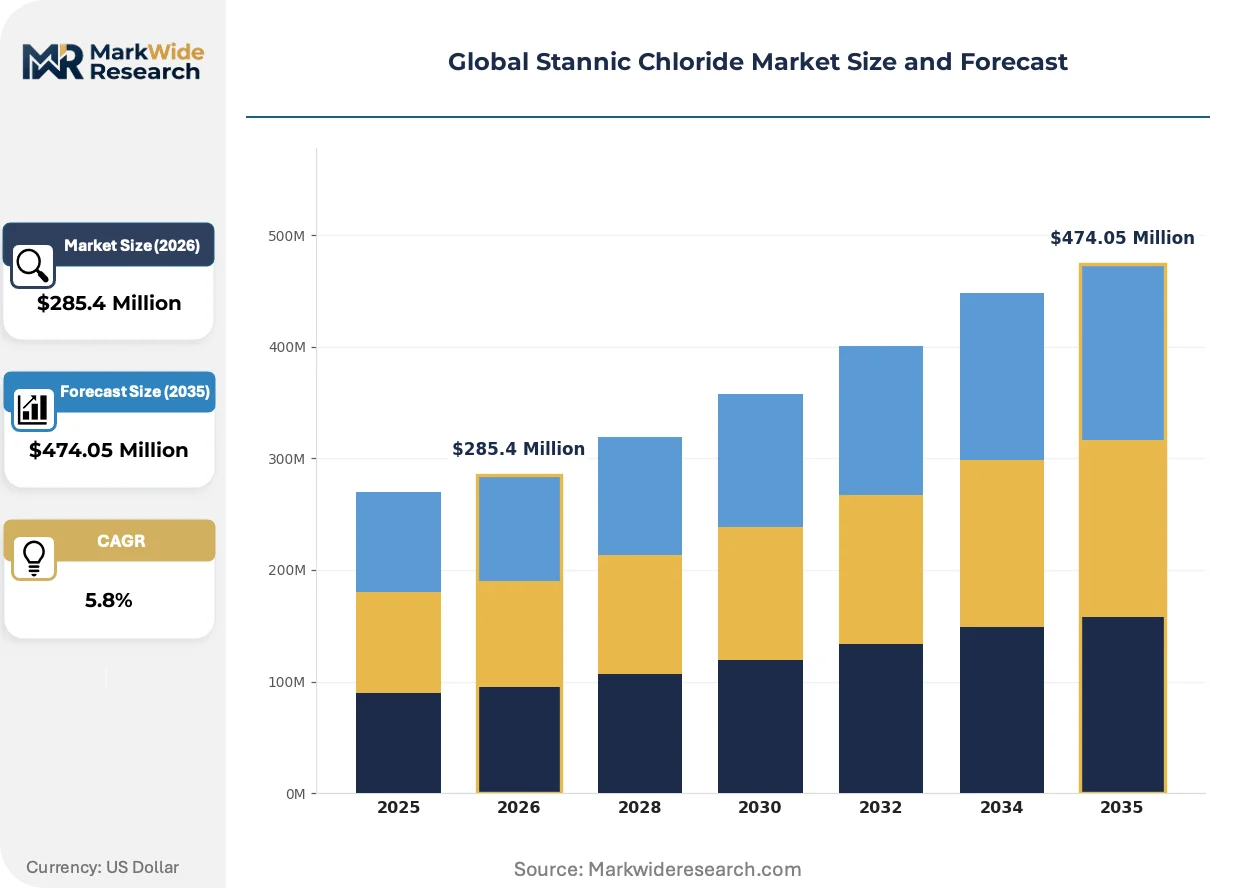
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Anhydrous, Hydrated Application: Electroplating, Catalysts, Textile Treatment, Chemical Synthesis, Pigment Manufacturing End User Industry: Semiconductor Fabrication, Coatings Production, Paper Processing, Metal Refining Packaging Type: Drums, Bags, Bottles, Bulk Containers |
| Companies Covered | Alfa Aesar, BOC Sciences, Merck KGaA, Gulbrandsen, Mason Corporation, Thermo Fisher Scientific Inc., American Elements, Yunnan Tin Group, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stannic Chloride Market Shifts & Advancements
Process chemistry convergence with atomic layer deposition is restructuring how tin precursors are specified, qualified, and priced across semiconductor and energy material supply chains.
Vapor-phase tin alkylamide precursors are decomposing traditional stannic chloride dominance in high-k dielectric deposition. Memory manufacturers in Yokkaichi and Pyeongtaek are qualifying these alternatives for 3D NAND stack uniformity. The shift is compressing volume forecasts for standard anhydrous grades while expanding ultra-high-purity sublimed solid precursor categories.
REACH authorization list expansion is accelerating substitution pathways for tin compounds with reproductive toxicity classifications. Chemical distributors are restructuring inventory toward pre-registered grades with complete safety data sheet portfolios. Electronics compounders serving German automotive sensor fabs face the most compressed compliance timelines.
Direct procurement from chlor-alkali integrated smelters is displacing distributor intermediation for large electroplating houses. Tier-one semiconductor chemical managers in Hsinchu and Shanghai are negotiating multi-year offtake agreements indexed to tin concentrate rather than spot metal prices. This concentrates volume with backward-integrated suppliers and fragments distributor relevance in premium grades.
Global Stannic Chloride Market Segmentation
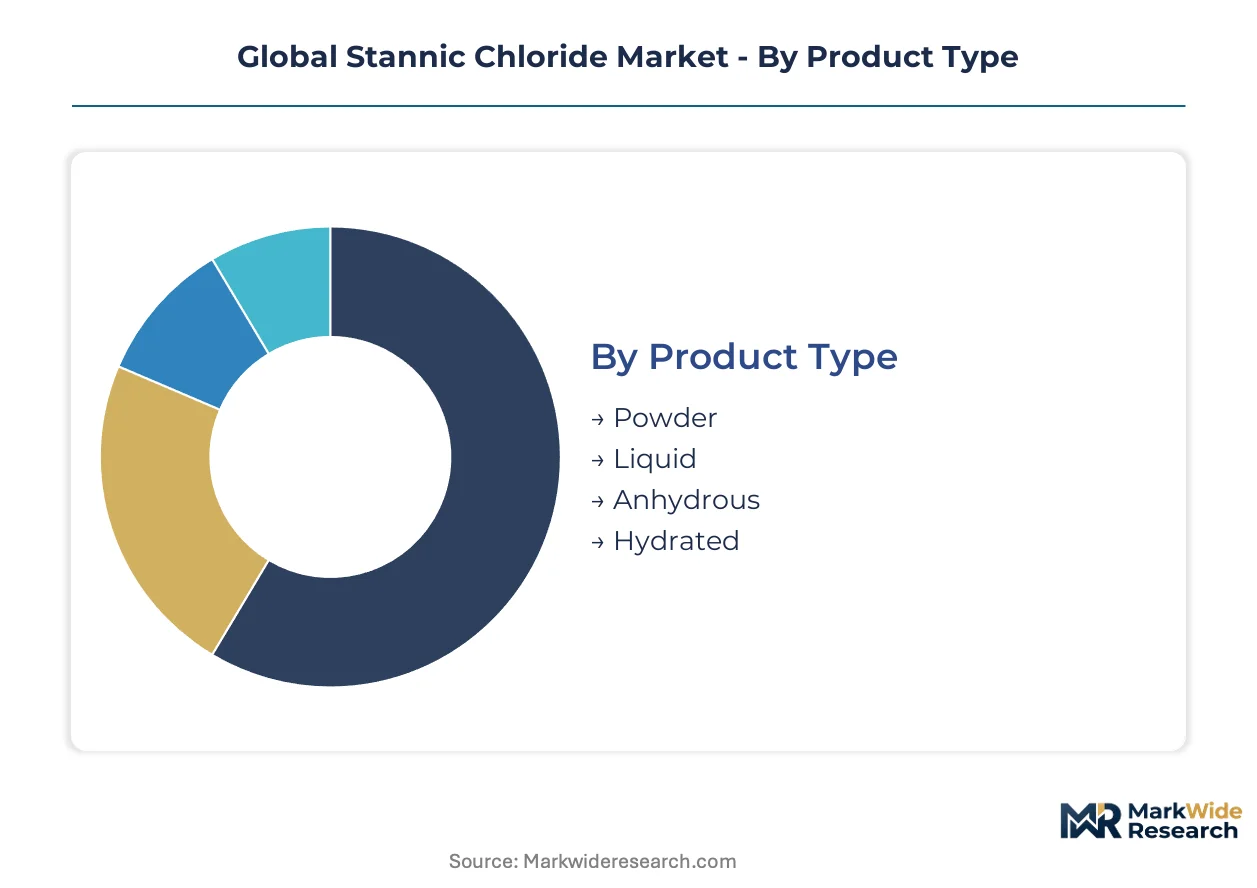
Stannic chloride demand fragments across purity grades, physical states, and end-use specifications that command divergent pricing power. Semiconductor fabs, electroplating houses, and catalyst manufacturers each impose distinct certification and logistics requirements that reshape supplier economics.
Product Type:
Tin alkylamide alternatives are displacing traditional chloride precursors in atomic layer deposition, compressing volume outlook for standard grades while elevating ultra-purity anhydrous specifications.
- Anhydrous:Ultra-high-purity material with moisture content below 10 ppm serves chemical vapor deposition and EUV lithography mask blank fabrication. South Korean foundry clusters in Hwaseong absorb the majority of semiconductor-grade offtake as 3nm node production scales. REACH authorization pressures on tin compounds are accelerating fab qualification of this grade for process efficiency advantages.
- Liquid:Standard aqueous and solvent-based formulations dominate electroplating bath preparation and polymerization catalyst applications where precise dosing equipment integrates directly into production lines. Chinese chlor-alkali integrated smelters in Yunnan province anchor supply for Asian electroplating houses serving automotive connector manufacturers.
- Hydrated:Crystalline pentahydrate and similar forms hydrolyze upon atmospheric exposure, limiting shelf life for coatings producers and textile treatment compounders.
- Powder:Sublimed solid precursors occupy emerging niches in solid oxide fuel cell anode formulations and specialized catalyst supports.
Anhydrous retains volume leadership; powder holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity chemical synthesis from premium semiconductor precursor segments, with margin compression accelerating in mid-tier electroplating applications.
- Electroplating:Tin deposition for printed circuit board finishes, semiconductor packaging, and connector plating consumes the largest tonnage of standard-grade liquid material. Hwaseong and Pyeongtaek foundry expansions are redirecting specification requirements toward sub-ppb purity thresholds compatible with advanced packaging.
- Catalysts:Polymerization initiators for polyester resins and esterification reactions represent stable demand from specialty chemical manufacturers in Germany and Japan. Solid oxide fuel cell research programs are qualifying tin oxide derived from chloride precursors as rare earth alternatives.
- Chemical Synthesis:Intermediate production for organotin compounds and other tin derivatives serves agrochemical and pharmaceutical routes.
- Textile Treatment:Flame retardant and antistatic finishing applications face substitution pressure from phosphorus-based alternatives under evolving EU hazard classifications.
- Pigment Manufacturing:Ceramic colorant and glass coating applications absorb standard hydrated grades with limited purity requirements.
Electroplating dominates absolute volume; catalysts are climbing the fastest on energy transition demand.
End User Industry:
Customer type concentration creates procurement power asymmetry, with semiconductor material managers extracting multi-year offtake commitments indexed to concentrate rather than spot metal prices.
- Semiconductor Fabrication:Logic and memory fabs command the most stringent purity protocols, with qualification cycles extending 18-24 months for new precursor batches. Hsinchu and Shanghai chemical managers are consolidating supplier panels to chlor-alkari integrated producers capable of tin concentrate backward integration.
- Coatings Production:Industrial and automotive coating manufacturers absorb larger hydrated grade tonnages with price-sensitive procurement patterns and limited certification requirements.
- Metal Refining:Electrolytic tin production and secondary recovery operations utilize chloride chemistry in limited specialty applications.
- Paper Processing:Sizing and coating applications represent declining demand as digital substitution compresses publication paper volumes.
Coatings production retains volume leadership; semiconductor fabrication commands the steepest margin expansion trajectory.
Packaging Type:
Supply chain configuration varies with hazard classification and customer scale, with bulk formats concentrating among integrated electroplating houses and small containers serving laboratory and pilot-scale users.
- Bulk Containers:ISO tanks and dedicated tanker deliveries serve high-volume electroplating and catalyst manufacturing facilities with dedicated unloading infrastructure.
- Drums:Standard 200-liter steel and composite drums dominate intermediate-volume shipments to chemical distributors and compounders.
- Bottles:Glass and fluoropolymer bottles protect anhydrous grades from atmospheric moisture for semiconductor chemical suppliers and research institutions.
- Bags:Moisture-barrier flexible packaging serves hydrated powder grades in coatings and pigment applications.
Drums retain volume leadership; bulk containers are gaining share fastest on direct procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese electroplating houses absorb standard-grade liquid stannic chloride with acute price sensitivity, while South Korean semiconductor fabs pay premiums for sub-ppb anhydrous material. German automotive sensor manufacturers occupy a mid-tier position where REACH compliance costs compress margins. Indian display fab construction is redirecting procurement patterns toward chlor-alkali integrated suppliers.
China
Yunnan province chlor-alkali integrated smelters dominate standard-grade liquid supply for Asian electroplating houses serving automotive connector manufacturers. MEE wastewater discharge standards force chlorination byproduct management investments at domestic facilities. The Yangtze River Delta concentration of PCB fabricators in Suzhou and Kunshan absorbs the majority of hydrated grade tonnage for tin plating baths.
South Korea
Hwaseong and Pyeongtaek foundry clusters drive premium anhydrous demand for EUV lithography mask blank fabrication and 3nm logic chip barrier layers. MFDS chemical substance registration requirements align with ECHA hazard assessment timelines for tin compound imports. Seoul Capital Area chemical managers consolidate supplier panels toward backward-integrated producers capable of tin concentrate sourcing.
Germany
Automotive sensor fabs in Baden-Württemberg face compressed REACH authorization compliance timelines for tin compounds with reproductive toxicity classifications. ECHA's 2024-2026 substance evaluation work program accelerates substitution toward pre-registered electronic grades. Bavarian specialty chemical manufacturers absorb stable catalyst demand for polyester resin polymerization initiators.
United States
EPA RCRA hazardous waste classification for spent stannic chloride solutions elevates total cost of ownership at domestic electroplating facilities. OSHA permissible exposure limits govern production and handling protocols across chlor-alkali integrated operations. Gulf Coast chemical distributors anchor North American supply through regional logistics infrastructure serving coatings manufacturers.
India
Ministry of Electronics and Information Technology production-linked incentives for display and logic fab construction in Gujarat and Tamil Nadu will localize tin chemical demand by 2027. BIS certification requirements for electronic-grade material imports create qualification barriers for non-integrated suppliers. Maharashtra chemical compounders serving pharmaceutical intermediates represent stable hydrated grade offtake.
Global Stannic Chloride Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Captive tin ore access at integrated smelters enables feedstock cost control across anhydrous grades, while pharmaceutical and electronic-grade certification depth concentrates with specialty chemical distributors. The market fragments across three strategic archetypes: backward-integrated mining-chemical conglomerates, chlor-alkali integrated regional suppliers, and global distributors with certification infrastructure. Dominant competitive moves include direct procurement consolidation by large electroplating houses and multi-year offtake agreements indexed to concentrate rather than spot metal prices.
Among Germany-based diversified chemical groups, Merck KGaA occupies a position exemplifying certification depth that smaller competitors cannot replicate. Gulbrandsen anchors North American supply archetype through chlor-alkali integration and regional logistics infrastructure. Yunnan Tin Group represents the backward-integrated mining-chemical conglomerate model, leveraging captive tin ore access to control feedstock costs.
| Leading Market Players |
|---|
| Alfa Aesar |
| BOC Sciences |
| Merck KGaA |
| Gulbrandsen |
| Mason Corporation |
| Thermo Fisher Scientific Inc. |
| American Elements |
| Yunnan Tin Group |
| Honeywell International Inc. |
| Others |
Supply & Pricing Matrix
Tin alkylamide substitution in atomic layer deposition is simultaneously redrawing supply geography toward South Korean vapor-phase precursor specialists and compressing pricing power for standard anhydrous grades. This displacement dynamic concentrates premium value capture with chlor-alkari integrated smelters capable of sublimed solid production while liquid formulations face margin erosion.
Pricing Analysis
After-sales certification support and multi-year fab qualification assistance drive lifetime value for electronic-grade suppliers. Three-tier pricing structure across electronic, pharmaceutical, and industrial grades separates sub-ppb purity material commanding process efficiency premiums from standard hydrated variants sold on volume metrics. Cost compression in mid-tier electroplating applications is intensifying because Chinese chlor-alkali integrated producers leverage captive tin ore access. Coatings manufacturers exhibit acute price sensitivity versus semiconductor material managers who prioritize qualification stability over unit cost.
Supply Chain Analysis
Inbound logistics costs for anhydrous grades hinge on Shanghai-to-Busan container availability and specialized fluoropolymer-lined tank integrity across the East Asian trade lane. Supply concentrates with Chinese smelters in Yunnan province and Indonesian concentrate processors, with South Korean foundry clusters drawing from both feedstock bases. The network rests on captive chlorine supply, high-purity tin sponge, and sublimed precursor packaging as critical inputs. Single-source vulnerability around Myanmar ore disruption concentrates risk with Chinese and Indonesian smelters. Distribution runs through direct procurement consolidation at tier-one semiconductor chemical managers and regional distributor networks serving smaller electroplating houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a semiconductor capital expenditure recovery cycle. Foundry buildout timelines in Hwaseong and Pyeongtaek provide the cyclical anchor.
For Market Incumbents: Fortify backward integration into tin concentrate sourcing to hedge against Indonesian export quota volatility and Myanmar supply disruption. Deepen ICP-MS trace metal analysis capabilities in-house to reduce contract laboratory bottlenecks that freeze qualification timelines. Chlor-alkari integration in Yunnan province exemplifies the structural lever that smaller compounders cannot replicate. For New Entrants and Emerging Players: Anchor in Indian display fab construction under Ministry of Electronics and Information Technology production-linked incentives as the most penetrable demand node. Solid oxide fuel cell catalyst qualification programs represent adjacent white space with lower certification barriers than semiconductor precursor markets. A joint development agreement with stationary power OEMs offers the cleanest go-to-market angle versus competing directly for fab qualification slots. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty chemical distributors holding REACH-registered tin compound portfolios but lacking chlor-alkali integration. Long-term viability favors producers with captive ore access and vapor-phase precursor capabilities across a five-to-ten year window. Watch South Korean foundry cluster expansion announcements as the signal for inflection in ultra-high-purity grade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tin Concentrate | Yunnan Tin Group's captive ore access stabilizes feedstock costs against Indonesian quota volatility. |
| Long-term Supply Agreement | Hsinchu chemical managers index multi-year offtake to concentrate prices rather than spot metal benchmarks. |
| Capacity Expansion | Hwaseong foundry cluster growth absorbs additional anhydrous grade volume for EUV mask blank fabrication. |
| Joint Venture | Indian display fab partnerships localize supply chains under BIS certification requirements by 2027. |
| Green Manufacturing Transition | REACH authorization pressures accelerate substitution toward pre-registered electronic grades with complete safety data. |
Research Methodology
Cross-validation between primary interviews with plant managers at chlor-alkali integrated smelters and secondary validation through customs trade data anchors the qualitative findings. Procurement leads at South Korean foundry clusters, technical R&D directors at German specialty chemical manufacturers, distribution channel partners serving coatings producers, and semiconductor material qualification managers provided stakeholder perspectives. Bottom-up volume modeling triangulates against top-down value estimates derived from SEC filings, Cefic chemical industry reports, and trade flow databases.
Sensitivity analysis around tin concentrate price volatility and foundry capacity expansion timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include purity grade tier, end-use industry, packaging format, and regional production hub. CAGRs derive from regression against semiconductor capital expenditure cycles and electroplating bath replacement rates. Key inputs model EUV lithography mask blank demand and solid oxide fuel cell catalyst qualification velocity.
Underlying assumptions cover stable Indonesian export quota administration and South Korean foundry cluster expansion execution, with deviation risk concentrated in Myanmar ore supply disruption and REACH authorization timeline acceleration. Forecasts reflect these documented conditions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
Superacids Market
Specialty Compounds
GCC Hydroxypropyl Methylcellulose Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Dammar Gum Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Compounds Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
Galactoarabinan Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Global Color Masterbatch Market