
 Propylene Trimer Market | 2026-2036
Propylene Trimer Market Size, Share, and Industry Trends Forecast 2026-2036
Propylene Trimer Market Analytics
Merchant supply contracts between polyolefin producers and specialty chemical distributors is rewriting regional availability patterns. LyondellBasell leverages its integrated propylene pipeline to secure captive feedstock for trimer output. INEOS sustains European supply through its Rotterdam aromatics complex. Braskem anchors South American distribution via its Triunfo petrochemical hub.
Propylene trimer, a C9 olefin oligomer produced through acid-catalyzed propylene polymerization, typically contains 95% minimum nonene content with branched and linear isomer distributions tailored for downstream reactivity. The material serves primarily as a chemical intermediate for plasticizer alcohols, surfactant feedstocks, and synthetic lubricant base stocks. Trimers and copolymers within the product type segmentation command the deepest margin pools due to specification-sensitive offtake from coatings and adhesives formulators. Application demand concentrates in plasticizers and surfactants where performance requirements resist substitution by lower-purity alternatives.
EPA fuel and chemical registration requirements in the United States, REACH substance authorization in Europe, and China's GB standards for chemical intermediates collectively elevate purity thresholds and documentation burdens for market entry. These frameworks push non-compliant merchant producers toward technical upgrading or regional exit. Stakeholders must track evolving bio-based propylene feedstock certifications and their compatibility with existing oligomerization catalyst systems.
Market Dynamics
REACH substance authorization in Europe is forcing coatings formulators to source higher-purity oligomer grades, compressing margins for merchant producers while rewarding integrated petrochemical complexes with captive feedstock control.
Growth Catalysts
- Plasticizer alcohol demand:Construction and automotive sectors in China absorb expanding volumes of nonene-derived plasticizers for flexible PVC applications.
- REACH compliance premiums:European coatings manufacturers pay specification premiums for 95%+ purity material that satisfies ECHA authorization requirements.
- Acid-catalyzed process optimization:Refinery-integrated producers achieve yield improvements through zeolite catalyst upgrades that reduce byproduct formation.
Market Restraints
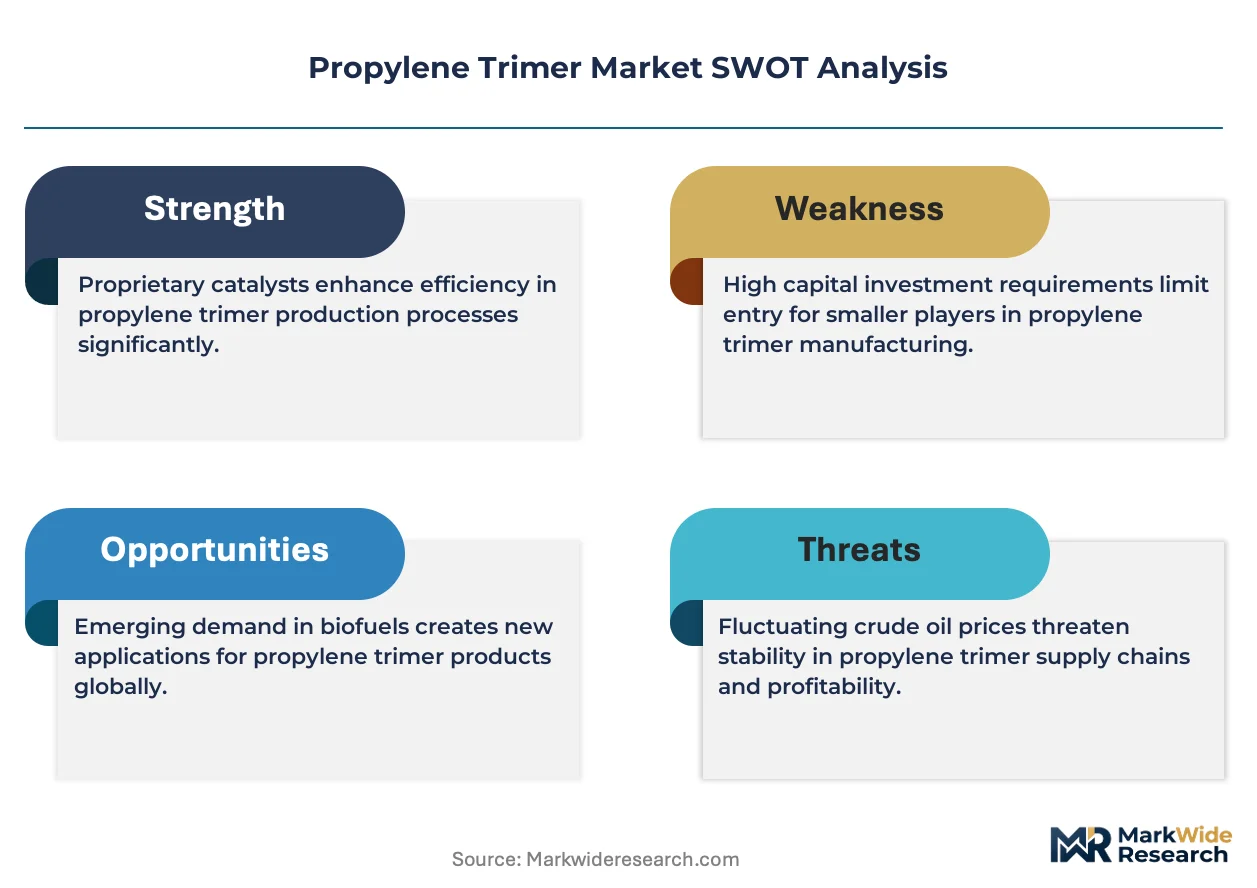
- Propylene feedstock volatility:Merchant trimer producers face margin compression when naphtha-cracker propylene spot prices spike against contract differentials.
- Merchant supply concentration:Rotterdam and Houston hubs control over half of seaborne export volumes, creating single-point vulnerability for Asian buyers.
- Linear alpha-olefin substitution:Metallocene-produced LAO C9 fractions compete in synthetic lubricant base stock applications with superior viscosity indices.
Strategic Opportunities
- India surfactant expansion:Local alcohol ethoxylate producers seek nonene feedstock as BIS standards tighten on imported intermediate purity.
- Bio-based propylene integration:Renewable propylene from glycerol dehydration routes offers pathway to mass-balance certified oligomers for EU Green Deal compliance.
- Direct-to-formulator distribution:Specialty chemical distributors bypass traditional merchant traders to capture margin from coatings SMEs in Southeast Asia.
Industry Challenges
- Catalyst regeneration expertise:Solid phosphoric acid catalyst management requires specialized technical talent scarce outside major petrochemical clusters.
- GB standard documentation:China's MEE enforcement of chemical intermediate registration creates six-to-twelve month approval timelines for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propylene Trimer Market |
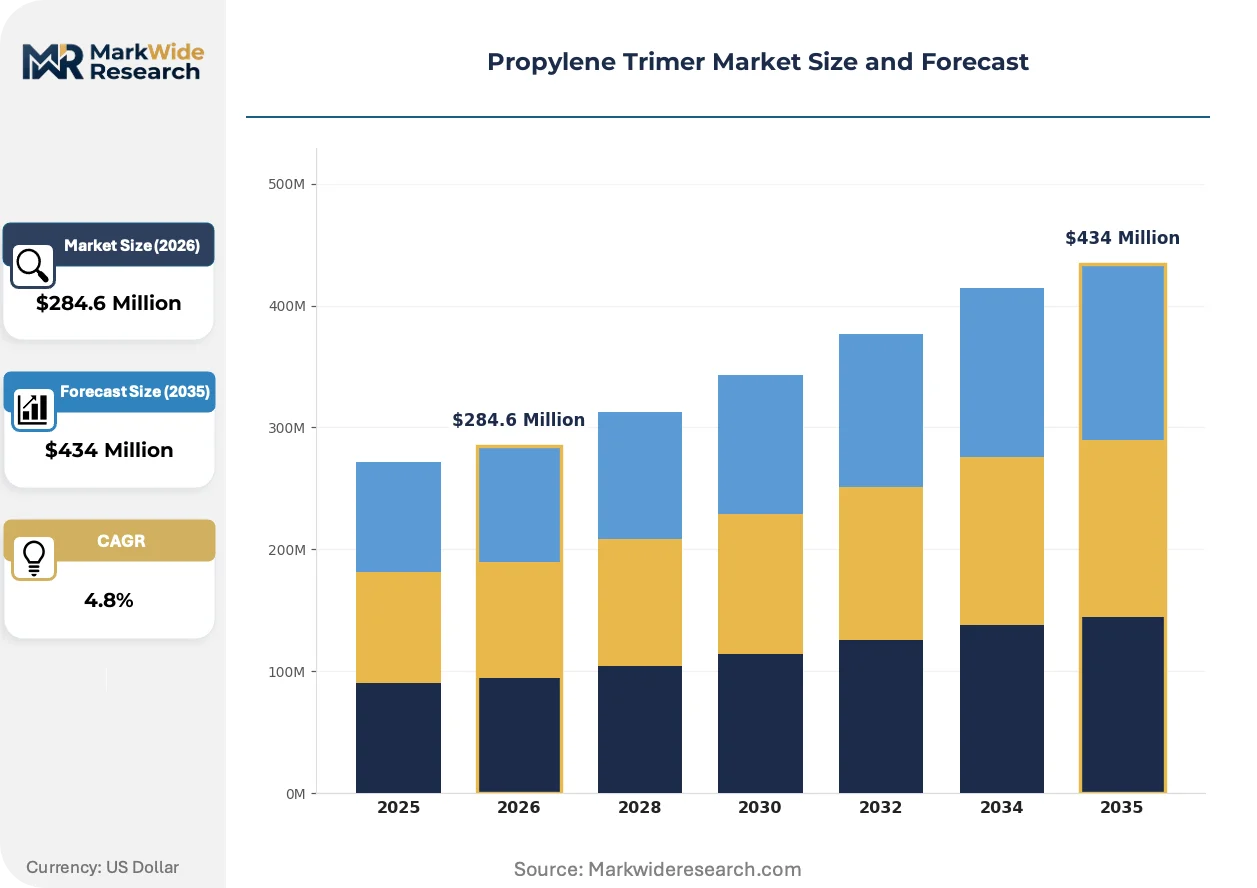
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $434 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene Glycol, Trimers, Copolymers, Polymer Blends Application: Adhesives, Coatings, Plasticizers, Surfactants End User: Construction, Automotive, Consumer Goods, Industrial Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | LyondellBasell, TPC Group, Exxon Mobil Corporation, INEOS, SABIC, Shell, Braskem, Suncor Energy Inc, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propylene Trimer Market Evolving Landscape
Oligomerization technology and regulatory chemistry specifications are diverging across major demand centers, creating parallel development tracks for catalyst systems and purification methods.
Zeolite-based oligomerization is migrating from pilot refinery installations to full-scale commercial units at integrated complexes in South Korea and Saudi Arabia. Coatings formulators in these supply zones now specify narrow isomer distributions that legacy SPA catalysts cannot achieve. The technology is migrating from high-volume lubricant applications into specification-sensitive adhesive and sealant segments where branching control determines reactivity with maleic anhydride derivatization.
REACH authorization for C9 oligomers as intermediates now requires full substance identity dossiers including isomer-specific toxicological data. ECHA's 2023 update to guidance on UVCB substances extends registration burdens to imported trimers previously classified as generic intermediates. German coatings manufacturers have responded by consolidating supplier bases to three or four REACH-registered producers with complete analytical documentation.
Buyers in Asia-Pacific now require certificate-of-analysis authentication for every lot rather than quarterly quality assurance reports. Specialty distributors have displaced merchant traders in Japan and South Korea by offering lot-level documentation and just-in-time drum delivery. This pattern is most visible in surfactant feedstock procurement where ethoxylate producers face downstream customer audits demanding full supply chain substance identity.
Propylene Trimer Market Segmentation
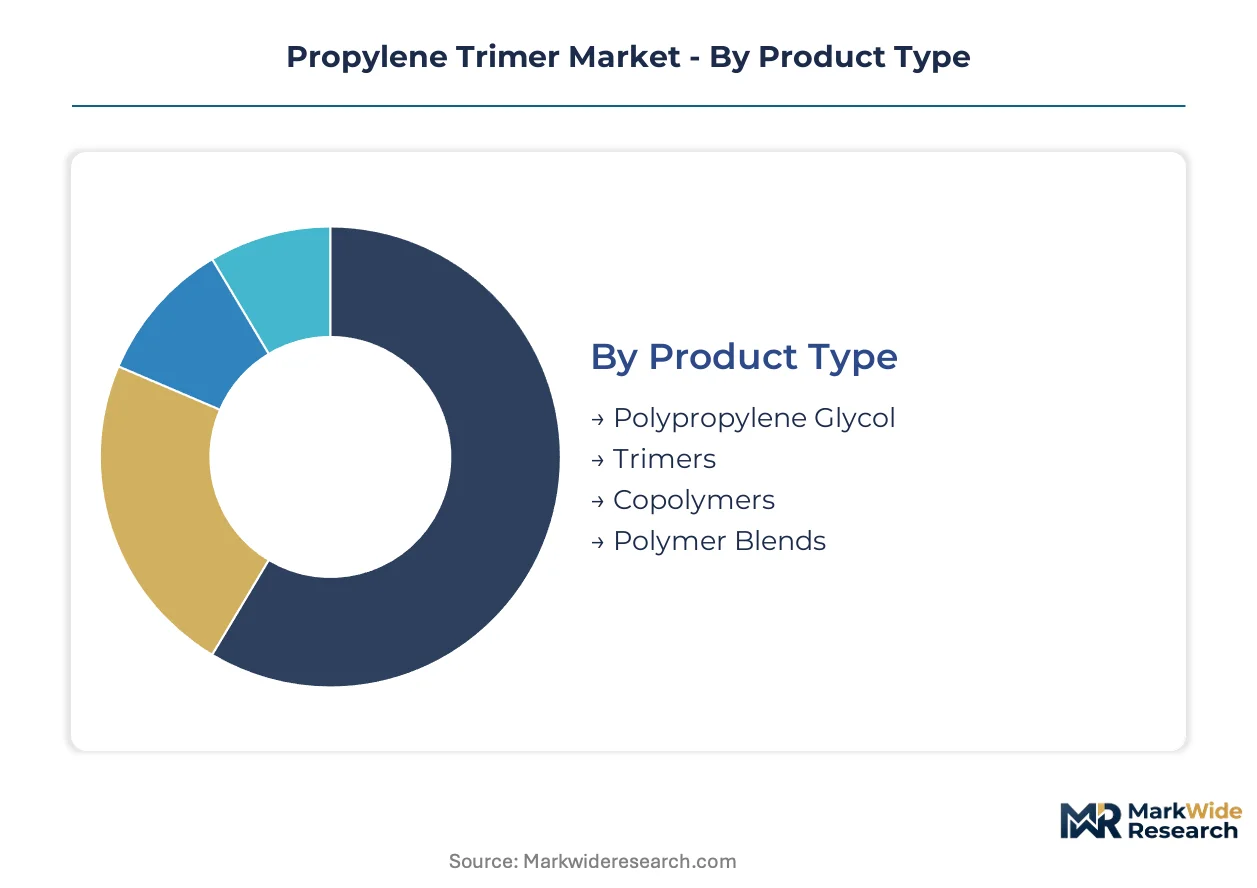
Propylene trimer segmentation reveals divergent margin profiles across product chemistry and customer procurement patterns. Specification-sensitive coatings formulators drive premium tier economics while commodity plasticizer applications absorb volume at thinner spreads.
Product Type:
Cycle times vary sharply across oligomer categories, with trimers turning inventory fastest due to coatings sector just-in-time requirements while polymer blends move on quarterly contracting rhythms.
- Trimers:C9 olefin oligomers with 95% minimum nonene content serve as the foundational intermediate for plasticizer alcohols and surfactant feedstocks. Chinese construction and automotive sectors absorb expanding merchant volumes as domestic crackers expand propylene output. REACH compliance premiums in Germany and France compress margins for non-integrated producers while rewarding complexes with captive feedstock control.
- Copolymers:Branched-chain distributions tailored for maleic anhydride derivatization command specification premiums from adhesive and sealant formulators. South Korean and Saudi Arabian refineries now deploy zeolite catalyst systems that achieve narrow isomer distributions legacy solid phosphoric acid units cannot replicate. These materials gain share in pressure-sensitive adhesive applications where reactivity control determines crosslink density.
- Polypropylene Glycol:Polyether polyols derived from propylene oxide polymerization serve polyurethane foam and coating applications.
- Polymer Blends:Custom-formulated oligomer mixtures address niche lubricant and process oil specifications.
Trimers anchors the volume base while copolymers gains share at the steepest rate.
Application:
Cost tier stratification separates specification-sensitive coatings from commodity plasticizer procurement, with surfactant feedstocks occupying an intermediate position on purity documentation requirements.
- Plasticizers:Nonene-derived alcohols phthalate and non-phthalate types dominate flexible PVC consumption in construction and automotive end-uses. China's GB standard enforcement on chemical intermediate registration creates six-to-twelve month approval timelines that favor incumbent producers with established MEE documentation. Merchant producers face margin compression when naphtha-cracker propylene spot prices spike against contract differentials.
- Coatings:High-purity oligomer grades satisfy ECHA authorization requirements for UVCB substance identity dossiers including isomer-specific toxicological data. German coatings manufacturers have consolidated supplier bases to REACH-registered producers with complete analytical documentation. Lot-level certificate-of-analysis authentication now replaces quarterly quality assurance reports in Japan and South Korea procurement.
- Surfactants:Alcohol ethoxylate producers in India seek nonene feedstock as BIS standards tighten on imported intermediate purity.
- Adhesives:Pressure-sensitive and structural adhesive formulators specify narrow isomer distributions for controlled reactivity.
Plasticizers retains the largest volume position while coatings expands most quickly on REACH compliance premiums.
End User:
Customer type maturity separates long-term contracting industrial buyers from spot-market construction procurement with divergent inventory and specification requirements.
- Construction:Flexible PVC applications in flooring, wallcovering, and cable insulation absorb merchant-grade trimer volumes on quarterly price formulas. Chinese infrastructure investment cycles drive regional demand volatility with inventory accumulation ahead of policy stimulus announcements.
- Automotive:Interior trim and underhood applications specify low-volatility plasticizer grades with enhanced thermal stability profiles. OEM qualification timelines extending 18-24 months lock in supplier relationships and resist merchant trader displacement.
- Consumer Goods:Personal care and household product formulations utilize surfactant derivatives with mass-balance certification requirements.
- Industrial:Synthetic lubricant base stocks and process oils compete with metallocene-produced linear alpha-olefin C9 fractions on viscosity index performance.
Construction provides the volume foundation while automotive offers the most stable contract tenors.
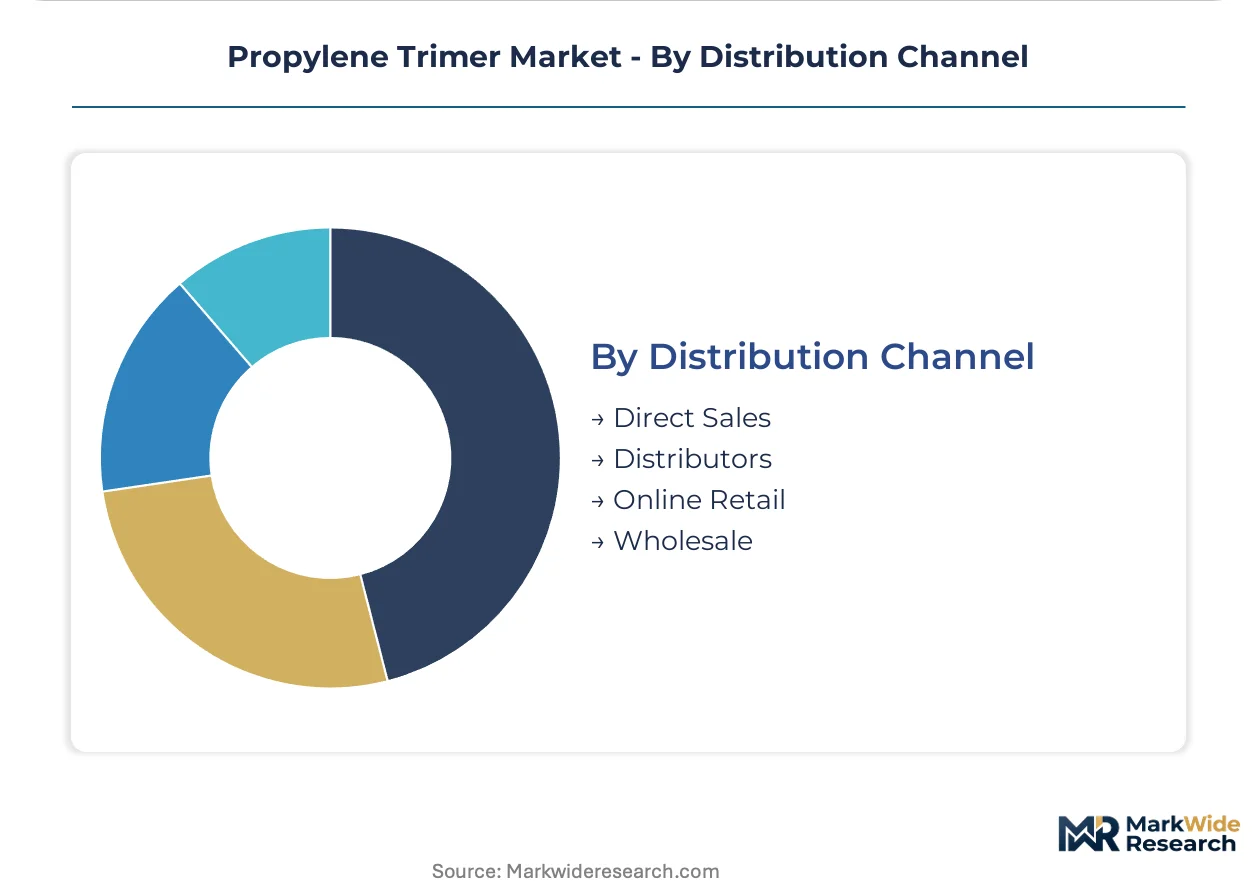
Distribution Channel:
Supply concentration in Rotterdam and Houston hubs shapes channel economics, with direct sales rewarding scale and distributors capturing SME margin in documentation-intensive markets.
- Distributors:Specialty chemical distributors bypass traditional merchant traders to capture margin from coatings SMEs in Southeast Asia. Just-in-time drum delivery and lot-level documentation displace quarterly quality assurance report models in Japan and South Korea. These intermediaries invest in REACH and GB standard technical expertise scarce outside major petrochemical clusters.
- Direct Sales:Integrated producers with captive feedstock leverage pipeline economics to supply large-volume plasticizer and surfactant manufacturers on formula pricing. LyondellBasell and INEOS sustain European supply through dedicated logistics infrastructure with minimal intermediary markup.
- Wholesale:Bulk tank and drum resellers serve mid-tier formulators without dedicated supply chain infrastructure.
- Online Retail:Digital procurement platforms emerge for standardized drum quantities in laboratory and pilot-scale applications.
Distributors gains share fastest in documentation-intensive Asian markets while direct sales defends position in high-volume European contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH authorization framework anchors European demand patterns while Chinese GB standards and MEE enforcement reshape Asian procurement. Merchant supply contracts concentrate in Rotterdam and Houston hubs, with regulatory divergence creating parallel certification tracks across major demand centers.
China
Construction and automotive sectors absorb expanding volumes of nonene-derived plasticizers for flexible PVC applications. MEE enforcement of chemical intermediate registration under GB standards creates six-to-twelve month approval timelines that favor incumbent producers. Yangtze River Delta petrochemical complexes now absorb the largest volume of merchant-grade material, with domestic crackers expanding propylene output.
Germany
Coatings manufacturers have consolidated supplier bases to REACH-registered producers with complete analytical documentation for UVCB substance identity dossiers. ECHA's 2023 guidance update on isomer-specific toxicological data extends registration burdens to imported trimers. Industrial clusters along the Rhine corridor drive specification premiums for 95%+ purity material.
United States
EPA fuel and chemical registration requirements elevate purity thresholds for market entry alongside state-level environmental regulations. Merchant trimer producers face margin compression when naphtha-cracker propylene spot prices spike against contract differentials. Gulf Coast petrochemical infrastructure around Houston controls a significant share of seaborne export volumes.
South Korea
Zeolite-based oligomerization technology migrates from pilot refinery installations to full-scale commercial units at integrated complexes. Lot-level certificate-of-analysis authentication now replaces quarterly quality assurance reports in procurement contracts. Ulsan petrochemical hubs deploy catalyst systems achieving narrow isomer distributions that legacy solid phosphoric acid units cannot replicate.
India
Local alcohol ethoxylate producers seek nonene feedstock as BIS standards tighten on imported intermediate purity. Construction sector demand for flexible PVC applications in flooring and cable insulation follows quarterly price formulas. Gujarat and Maharashtra industrial corridors attract specialty chemical distributors offering just-in-time drum delivery and technical documentation support.
Propylene Trimer Market Competitive Landscape
Integrated petrochemical complexes and merchant specialty chemical distributors split the market along feedstock control and documentation capability lines. The vendor base concentrates around refinery-integrated producers with captive propylene supply and regional distributors with regulatory expertise. Two archetypes dominate: pipeline-integrated complexes leveraging backward integration into feedstock, and specialty distributors capturing SME margin through REACH and GB standard technical services. Capacity expansion and strategic partnerships represent the dominant competitive moves, with technology licensing emerging in zeolite catalyst upgrades.
Within the integrated-producer tier, LyondellBasell and INEOS exemplify archetypes anchored by dedicated logistics infrastructure. LyondellBasell leverages its integrated propylene pipeline to secure captive feedstock for trimer output, representing the backward-integration model. INEOS sustains European supply through its Rotterdam aromatics complex, occupying a position within the hub-and-spoke distribution architecture. Among diversified energy majors, Shell and SABIC sit within portfolios where oligomerization represents one node in broader olefin derivative strategies.
| Leading Market Players |
|---|
| LyondellBasell |
| TPC Group |
| Exxon Mobil Corporation |
| INEOS |
| SABIC |
| Shell |
| Braskem |
| Suncor Energy Inc |
| BASF |
| Others |
Value Network & Pricing Analysis
Rotterdam and Houston petrochemical hubs command pricing power through seaborne export concentration, anchoring margin pools with coatings formulators in Asia-Pacific who absorb specification premiums for REACH-compliant oligomer grades. Merchant producers outside these hubs face cost compression when propylene feedstock volatility erodes contract differentials against spot naphtha-cracker pricing.
Pricing Analysis
Geographic price spreads between European REACH-registered material and merchant-grade Asian supply run 12-18 percent on certificate-of-analysis documentation alone. Contract-based long-term offtake dominates high-volume plasticizer procurement, while spot-market drum sales serve coatings SMEs in Southeast Asia. Price differentiation hinges on purity certification tier and captive feedstock integration, with integrated complexes capturing margin from non-integrated traders. Cost compression in standard-grade material is intensifying as Chinese domestic crackers expand propylene output and compress import premiums. Construction sector buyers exhibit highest price sensitivity on quarterly formulas, while automotive OEMs with 18-24 month qualification timelines show lowest sensitivity due to supplier lock-in.
Supply Chain Analysis
Toll oligomerization capacity concentrates with LyondellBasell's Channelview complex, INEOS Rotterdam aromatics hub, and South Korean zeolite-equipped refineries at Ulsan. Merchant supply draws from propylene feedstock anchored in US Gulf Coast steam crackers, Middle East gas-based complexes, and Chinese naphtha crackers. Single-source vulnerability runs through Rotterdam-Houston export concentration controlling over half of seaborne volumes. Distribution runs through specialty chemical distributors displacing traditional merchant traders in documentation-intensive Asian markets, with direct pipeline sales defending position in high-volume European contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Propylene trimer demand sits in early-cycle expansion as REACH authorization tightens specification requirements and coatings formulators consolidate supplier bases to registered producers with complete UVCB dossiers.
For Market Incumbents: Insulate margin position through captive feedstock integration and zeolite catalyst upgrades that achieve narrow isomer distributions legacy solid phosphoric acid units cannot replicate. Defend against linear alpha-olefin substitution in synthetic lubricant applications by deepening technical service relationships with automotive OEMs on 18-24 month qualification timelines. Prioritize certification investment for ECHA substance authorization and China's MEE registration to maintain access to consolidating buyer bases in Germany and the Yangtze River Delta. For New Entrants and Emerging Players: India's alcohol ethoxylate producers seeking nonene feedstock as BIS standards tighten represent the most penetrable entry point for merchant-grade material. Direct-to-formulator distribution bypassing traditional traders captures margin from coatings SMEs in Gujarat and Maharashtra industrial corridors. A technical documentation service bundling REACH and GB standard expertise with just-in-time drum delivery offers the strongest go-to-market angle against established merchant traders. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty chemical distributors in Asia-Pacific who have built regulatory documentation capabilities but lack captive feedstock integration. Long-term viability over a 5-10 year window favors targets with zeolite catalyst technology licenses and established MEE registration dossiers. Watch for inflection in bio-based propylene feedstock certification compatibility with existing oligomerization systems as the EU Green Deal compliance pathway matures.| Strategic Initiative | Industry Significance |
|---|---|
| Zeolite Catalyst Upgrade | South Korean and Saudi Arabian refineries achieve narrow isomer distributions for specification-sensitive adhesive applications. |
| Backward Integration into Propylene | LyondellBasell's Channelview pipeline secures captive feedstock margin against naphtha-cracker spot volatility. |
| REACH Registration Investment | German coatings manufacturers consolidate supplier bases to ECHA-registered producers with complete UVCB dossiers. |
| Direct-to-Formulator Distribution | Specialty distributors capture SME margin in Southeast Asia through lot-level documentation and just-in-time delivery. |
| Bio-Based Feedstock Certification | Renewable propylene from glycerol dehydration offers mass-balance certified pathway for EU Green Deal compliance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, ACC and Cefic industry reports, and ECHA registration dossiers. Primary interviews engaged plant managers at integrated petrochemical complexes, procurement leads at downstream plasticizer and surfactant manufacturers, distribution channel partners in Rotterdam and Singapore hubs, and technical R&D directors overseeing catalyst system upgrades. Bottom-up volume estimates from oligomerization unit capacities triangulate against top-down demand segmentation from end-use industry consumption patterns.
Forecast inputs include propylene feedstock cost trajectories, REACH authorization timelines for UVCB substances, and coatings sector procurement consolidation patterns across the projection horizon. Segmentation dimensions modeled span product chemistry grade tier, end-use application intensity, captive versus merchant supply structure, and regional regulatory framework clusters. CAGRs derive from elasticity-adjusted demand projections against capacity expansion announcements, with zeolite catalyst diffusion curves and bio-based propylene certification penetration serving as industry-specific scenario variables.
Macroeconomic conditions sit as an overlay; deviation in naphtha pricing spreads, Chinese infrastructure investment cycles, or European coatings production indices would shift the trajectory. Forecasts embed assumptions on ECHA enforcement continuity and MEE registration processing timelines. Quarterly review of propylene contract-spot differentials, REACH substance authorization updates, and BIS standard implementation progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Methyl Anthranilate Market
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
Low Density Sheet Moulding Compound (SMC) Market
Specialty Compounds
Solketal Market
Specialty Compounds
Propoxylates Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
EPDM Sealing Strip Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Hydroxypropyl Methylcellulose Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
United States Caustic Potash Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Small Molecules Innovator Contract Development and Manufacturing Organization Market
Specialty Compounds
Dextran Sulfate Sodium Market