
 Silicone Coating Market | 2026-2036
Silicone Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Coating Market Intelligence
China's massive expansion of silicone production capacity is reconfiguring the supply landscape for key intermediates and finished coatings. Major producers like Wacker Chemie AG are responding by focusing on specialty, high-performance formulations for niche applications. Dow leverages its extensive global manufacturing footprint to serve multinational clients in automotive and construction sectors. Shin-Etsu Chemical Co., Ltd. dominates specific high-purity segments required by the advanced electronics industry.
Silicone coatings are thin, protective films derived from siloxane polymers, which are cross-linked to form a durable matrix. These materials are prized for their thermal stability and hydrophobicity, providing a barrier against moisture, heat, and corrosion. Water repellent and anti-corrosion product types command a significant share due to use in construction and automotive components. The electronics protection application represents the fastest-growing segment, driven by device miniaturization.
Regulatory frameworks like the EU’s REACH and EPA volatile organic compound (VOC) limits in the United States are pushing manufacturers toward water-based and solvent-free formulations. In China, compliance with national GB standards for industrial coatings governs market access for both domestic and imported products. Navigating the divergent regional compliance requirements for specific end-uses remains a critical strategic challenge for suppliers.
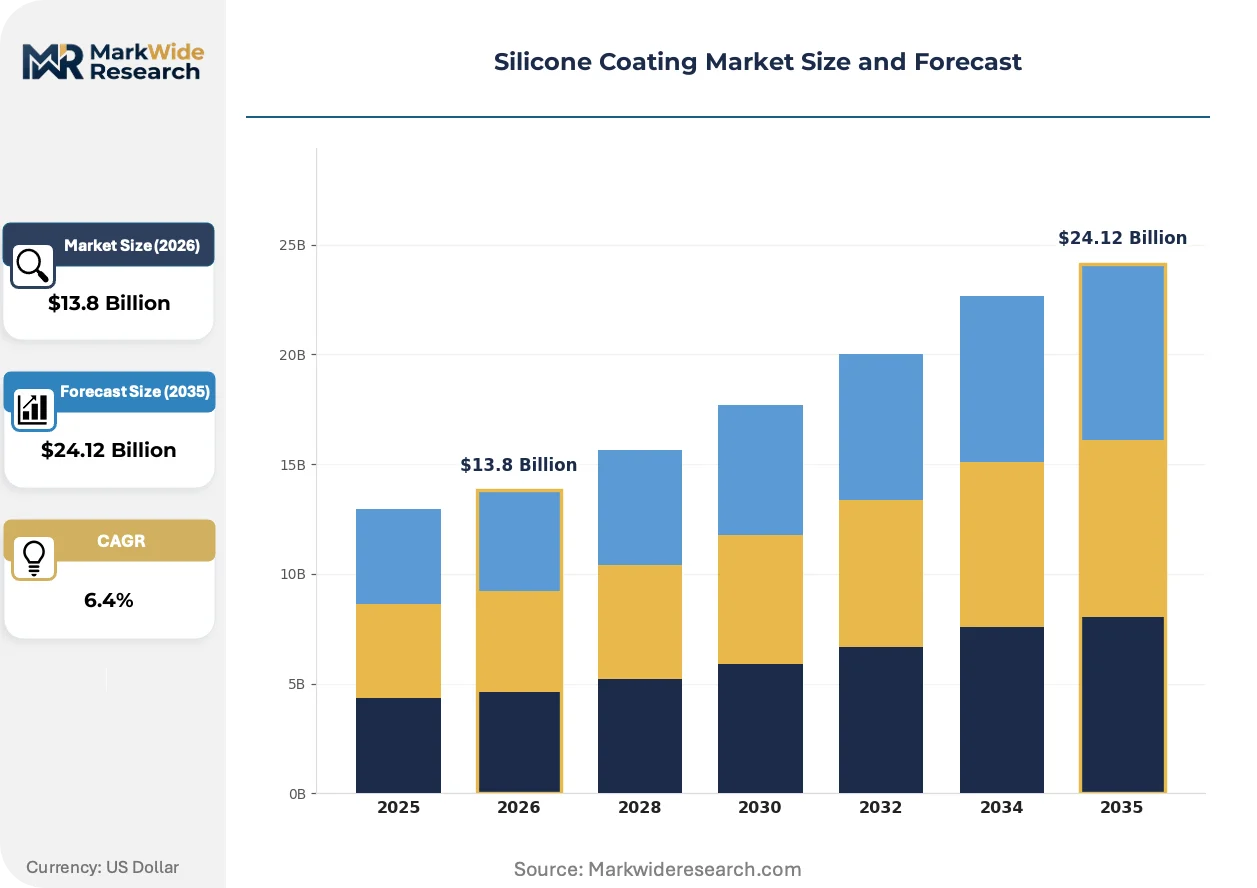
Market Dynamics
The central force shaping the silicone coating market is the global push for sustainable formulations, driven by regulations like the EU's REACH. This trend intersects with China's expanding production of silicone intermediates, fundamentally altering supply chain economics and competitive strategies.
Growth Catalysts
- Consumer Electronics Miniaturization:The trend towards smaller, more powerful devices in the consumer electronics sector necessitates advanced, thin-film silicone coatings for effective thermal management and moisture protection.
- EU Green Deal Initiatives:Policies promoting energy efficiency and sustainable building materials are driving adoption of silicone coatings for architectural envelopes and cool roof applications, particularly in Germany and France.
- Automotive Electrification:The expansion of electric vehicle manufacturing in South Korea and China creates demand for high-performance silicone coatings for battery packs, power electronics, and sensors.
Market Restraints
- Siloxane Price Volatility:Fluctuations in the price of raw materials like silicon metal and methanol, often linked to energy costs and production quotas in China, create significant margin pressure for coating formulators.
- Adhesion on Low-Energy Surfaces:Achieving durable adhesion on certain polymer substrates, such as polypropylene, without extensive and costly surface pre-treatment remains a key technical barrier for some industrial applications.
- Competition from Alternative Chemistries:In less demanding construction and industrial maintenance applications, lower-cost acrylic and polyurethane coatings present a persistent substitution threat, limiting market penetration.
Strategic Opportunities
- Biocompatible Medical Coatings:The development of medical-grade silicone coatings for implantable devices, catheters, and surgical instruments represents a high-value niche, driven by advancements in global healthcare technology.
- Smart and Functional Coatings:Integrating functionalities like self-healing properties or embedded sensors into silicone matrices opens new possibilities in aerospace, defense, and smart textile applications.
- Infrastructure Development in India:Large-scale public and private infrastructure projects in India offer significant growth potential for corrosion-resistant and waterproofing silicone coatings, supported by government investment initiatives.
Industry Challenges
- Divergent Regional Standards:Navigating the complex and differing chemical registration and VOC content requirements between the EU's REACH, US EPA rules, and China's GB standards complicates global product launches.
- Solvent-Free Production Transition:Shifting manufacturing lines from traditional solvent-based systems to 100% solids or water-based formulations requires significant capital investment in new mixing and application equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Coating Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Resistant, Water Repellent, Anti-Corrosion, UV Resistant, Anti-Friction Application: Electronics Protection, Textile Finishing, Medical Devices, Automotive Components, Construction Materials End User: Consumer Electronics Manufacturers, Garment Producers, Medical Equipment Suppliers, OEMs, Building Contractors Form: Liquid, Powder, Foam, Spray, Emulsion |
| Companies Covered | Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Dow, Momentive, Evonik Industries AG, Elkem ASA, BASF SE, Carboline Company, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Coating Market Strategic Shifts & Innovations
This market's evolution is defined by the dual pressures of sustainability mandates and the performance demands of advanced manufacturing sectors. These forces compel innovation in both formulation chemistry and application processes, prioritizing functional and environmentally compliant materials.
UV-curable silicone coatings provide instant, low-temperature curing upon exposure to ultraviolet light. Electronics and medical device manufacturers are rapidly adopting this technology for high-throughput production lines. This shift away from thermal or moisture-cure systems is digitizing the application process, enabling precise, automated, and faster coating deposition on sensitive components.
The European Union's REACH regulation continues to restrict specific siloxanes and organotin catalysts used in older silicone formulations. This regulatory action compels manufacturers to invest in R&D for compliant, safer alternatives without compromising performance. The construction and consumer goods segments are most impacted, advancing the transition toward tin-free and low-VOC product lines in Europe.
End-users in high-tech sectors are increasingly specifying coatings based on performance certifications rather than just material composition. This trend disrupts traditional supplier relationships, favoring formulators who provide extensive testing data and compliance with standards like ISO 10993 or UL 94. The shift is most visible within the medical device and aerospace industries, where validation is paramount.
Silicone Coating Market Segmentation
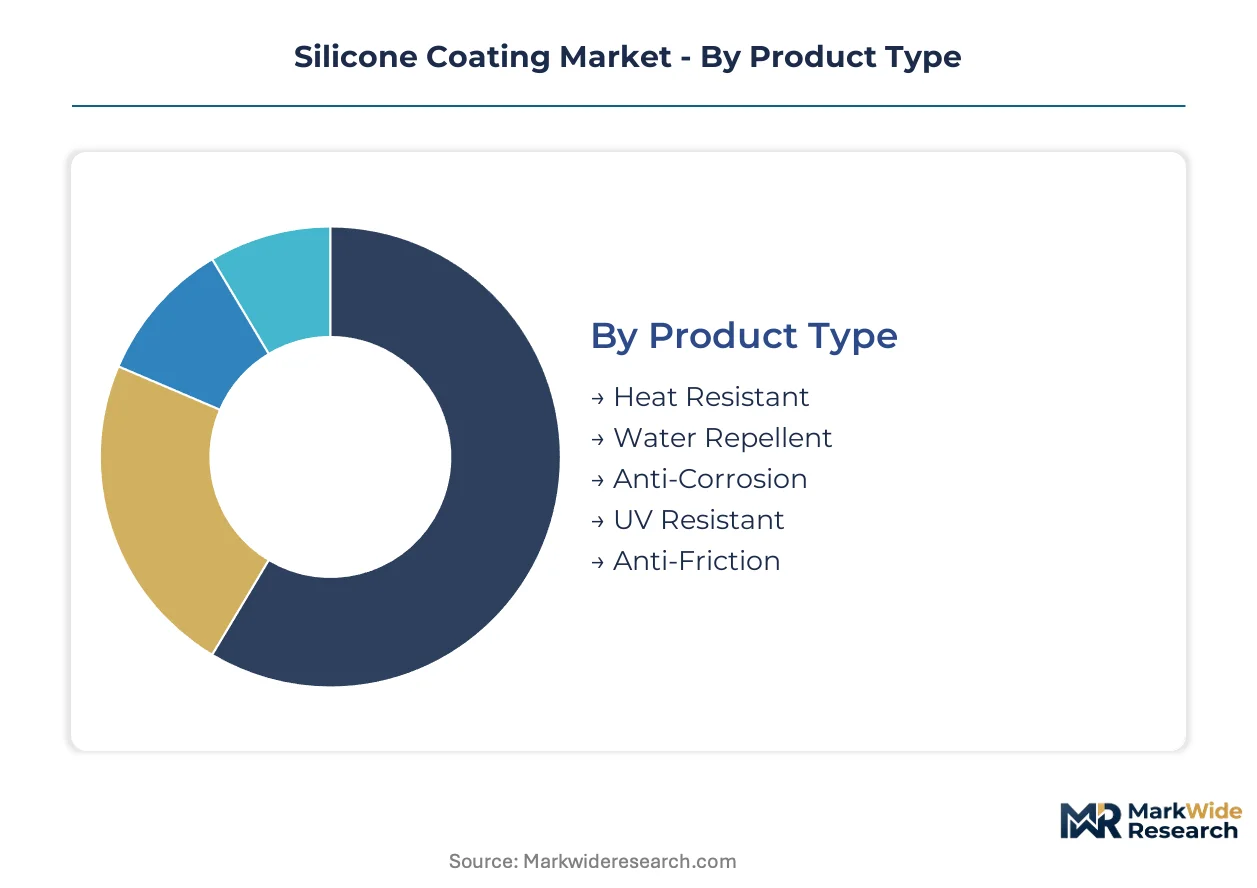
The silicone coating market segmentation reveals diverse product functionalities and application methods addressing specific industry requirements. Understanding these distinct categories provides clarity on demand drivers and technological advancements. This detailed breakdown highlights areas of concentrated value and emerging opportunities across various end-use sectors.
Product Type:
The product type segment spans mature formulations alongside emerging high-performance variants.
- Water Repellent:Water repellent coatings leverage siloxane polymers to create hydrophobic surfaces, effectively shedding moisture. Demand concentrates in construction materials and automotive components, driven by the need for weatherproofing and extended product lifespan.
- Anti-Corrosion:Anti-corrosion silicone coatings form a robust barrier against chemical degradation and oxidation, protecting metal substrates. The automotive and infrastructure sectors in India show strong demand for these durable protective layers.
- Heat Resistant:Heat resistant formulations maintain integrity under extreme temperatures, crucial for industrial equipment.
- UV Resistant:UV resistant coatings prevent degradation from solar radiation, extending the lifespan of outdoor assets.
- Anti-Friction:Anti-friction silicones reduce surface drag, improving efficiency in mechanical systems.
Water Repellent coatings retain volume leadership; Anti-Corrosion formulations hold the steepest expansion curve.
Application:
This application segment delineates where silicone coatings provide their most critical functional benefits.
- Electronics Protection:Electronics protection coatings safeguard sensitive components from moisture, heat, and physical damage, essential for device reliability. This segment is expanding most quickly, driven by miniaturization trends in consumer electronics in China and South Korea.
- Automotive Components:Automotive components utilize silicone coatings for thermal management, corrosion resistance, and electrical insulation in harsh environments. Electric vehicle manufacturing in South Korea creates significant demand for these high-performance materials.
- Textile Finishing:Textile finishing uses silicone for water repellency and soft-touch properties in performance apparel.
- Medical Devices:Medical devices require biocompatible silicone coatings for implants and surgical instruments, meeting ISO 10993 standards.
- Construction Materials:Construction materials benefit from silicone coatings for weatherproofing and improved durability of building envelopes.
Demand across these applications reflects varied performance needs, from high-tech protection to long-term infrastructure durability.
End User:
The end-user segment highlights the distinct customer bases driving demand for silicone coating solutions.
- Consumer Electronics Manufacturers:Consumer electronics manufacturers integrate silicone coatings for protecting circuit boards and enhancing device durability. This sector's demand is concentrated in advanced electronics hubs like China, necessitating high-purity, thin-film applications.
- Medical Equipment Suppliers:Medical equipment suppliers require specialized, biocompatible silicone coatings for implantable devices and catheters. Adherence to stringent certifications like ISO 10993 is paramount for these high-value applications.
- Garment Producers:Garment producers apply silicone coatings for water-resistant and breathable performance textiles.
- OEMs:OEMs across various industries use silicone coatings for component protection and functional enhancement.
- Building Contractors:Building contractors utilize silicone coatings for waterproofing, sealing, and protecting architectural structures.
Each end-user segment presents unique procurement requirements, from regulatory compliance to high-volume manufacturing efficiency.
Form:
This form segment differentiates silicone coatings based on their physical state and application methodology.
- Liquid:Liquid silicone coatings are versatile, allowing for various application techniques like dipping, brushing, or roll coating. They are widely used across industrial and consumer product manufacturing due to their adaptability and cure versatility.
- Spray:Spray silicone coatings enable efficient, uniform deposition over complex geometries, ideal for high-volume production lines. Automotive assembly and large-scale construction projects often favor sprayable formulations for ease of application.
- Powder:Powder coatings offer solvent-free application and excellent durability, often used for metal parts.
- Foam:Foam silicones provide lightweight cushioning and sealing properties, common in automotive and electronics.
- Emulsion:Emulsion coatings are water-based systems, aligning with environmental regulations and low VOC requirements.
The choice of form directly influences application efficiency and final coating properties, impacting overall project economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards for industrial coatings govern market access and product compliance, influencing the supply chain for silicone intermediates. This comprehensive regulatory framework shapes competitive dynamics for both domestic and imported products. Manufacturers must navigate these requirements for successful market penetration across various end-use sectors.
China
Consumer electronics miniaturization and electric vehicle manufacturing drive significant demand for advanced silicone coatings in China. The national GB standards for industrial coatings dictate product specifications and market entry for formulators. Electronics manufacturing hubs within the Yangtze River Delta region concentrate this specialized demand.
South Korea
Automotive electrification, particularly in battery packs and power electronics, fuels high-performance silicone coating demand in South Korea. The country's environmental regulations push manufacturers toward compliant, sustainable formulations. The Seoul Capital Area and Gyeonggi Province house major automotive and electronics production facilities.
Germany
The EU Green Deal initiatives and stringent environmental policies promote the adoption of sustainable silicone coatings for architectural envelopes in Germany. REACH regulations compel continuous innovation towards tin-free and low-VOC alternatives. Bavaria and North Rhine-Westphalia are key regions for chemical production and automotive applications.
India
Infrastructure development projects, requiring corrosion-resistant and waterproofing solutions, create substantial opportunities for silicone coatings in India. The Bureau of Indian Standards (BIS) guides product quality and application in construction materials. Maharashtra and Gujarat lead industrial and construction activity, necessitating durable protective layers.
United States
Industrial maintenance, construction materials, and aerospace applications sustain demand for silicone coatings in the United States. EPA volatile organic compound (VOC) limits increasingly influence formulation chemistry and product development. The Gulf Coast region, with its extensive chemical and industrial infrastructure, represents a major consumption area.
Silicone Coating Market Key Industry Players
Global chemical conglomerates and specialty formulators split the silicone coating market, each pursuing distinct strategic vectors. This structure features a tiered competitive landscape, with established players leveraging extensive R&D capabilities. Companies primarily focus on portfolio diversification and capacity expansion to secure market share.
Within the global chemical conglomerates, Dow leverages its extensive global manufacturing footprint to serve multinational clients across automotive and construction sectors. Wacker Chemie AG, a German-based entity, represents a specialty formulator archetype, focusing on high-performance formulations for niche applications. Shin-Etsu Chemical Co., Ltd., a Japanese firm, occupies a position in specific high-purity segments required by the advanced electronics industry.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Dow |
| Momentive |
| Evonik Industries AG |
| Elkem ASA |
| BASF SE |
| Carboline Company |
| Sika AG |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region's expanding silicone production capacity directly influences downstream pricing power for finished coatings across global markets. This concentration of manufacturing capability in China creates both competitive pricing and potential supply chain vulnerabilities for international buyers.
Pricing Analysis
Geographic price spreads reflect regional manufacturing costs and regulatory compliance burdens. Pricing operates predominantly on a contract-based long-term offtake model for large-volume customers, complemented by commodity spot pricing for certain intermediates. Price differentiation stems from quality grade, particularly for high-purity electronics applications, and specific certifications like ISO 10993 for medical devices. Pricing softness runs through the construction and industrial maintenance segments due to competition from alternative chemistries. Advanced electronics and medical device manufacturers exhibit lower price sensitivity, prioritizing performance and regulatory adherence.
Supply Chain Analysis
Siloxane price volatility, often linked to energy costs and production quotas in China, represents a significant supply chain risk. The global supply of silicone intermediates concentrates in China, Germany, and Japan. Raw material dependencies include silicon metal and methanol, which are subject to global commodity market fluctuations. Regulatory divergence between the EU's REACH, US EPA VOC limits, and China's GB standards complicates global sourcing. Distribution primarily occurs through direct sales channels to large automotive and electronics OEMs, with specialized distributors serving niche applications requiring technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents high-growth disruption, driven by the shift towards sustainable formulations mandated by regulations like the EU's REACH.
For Market Incumbents: Harden core market positions by investing heavily in R&D for compliant, solvent-free and UV-curable formulations. Expand specialty, high-performance product lines targeting advanced electronics and medical applications to counter competition from alternative chemistries. Invest in certification processes like ISO 10993 and UL 94 to maintain market access and premium pricing. Secure long-term supply agreements for key raw materials to mitigate siloxane price volatility.
For New Entrants and Emerging Players: Build out capabilities in high-value niche segments such as biocompatible medical coatings or smart, functionalized materials for aerospace. Target underpenetrated applications requiring specific performance certifications rather than broad commodity volumes. Focus on developing partnerships with specialized application equipment providers for automated, precise deposition of thin-film coatings. Leverage agility to bring innovative, compliant solutions to market faster than established players.
For Investors and Strategic Acquirers: Carve-out targets emerge from chemical conglomerates seeking to divest non-core or less profitable silicone coating divisions. The market offers sustained growth potential over the next decade, particularly in specialized, high-performance segments. Identify acquisition targets with proprietary intellectual property in UV-curable, solvent-free, or functional silicone chemistries. Increased M&A activity focused on intellectual property in compliant and functionalized coatings signals market maturation and consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asian Hubs | Addresses growing demand from consumer electronics and EV manufacturing in China and South Korea. |
| R&D for Solvent-Free Formulations | Ensures compliance with stringent environmental regulations like the EU's REACH and EPA VOC limits. |
| Certification for Medical-Grade Coatings | Unlocks access to high-value implantable device markets requiring ISO 10993 standards. |
| Partnerships for UV-Cure Technology | Accelerates adoption of high-throughput, automated application processes for sensitive components. |
| Investment in Smart Coating R&D | Creates new revenue streams in aerospace, defense, and smart textile applications with embedded functionalities. |
Research Approach
A standing panel of R&D directors, procurement leads from consumer electronics manufacturers, automotive engineers, and regulatory affairs specialists provided ongoing calibration. This involved combining primary interviews with industry stakeholders and secondary validation from sources like EU REACH documentation, EPA VOC regulations, and China GB standards. Bottom-up analysis of production capacities and top-down assessment of end-user demand were triangulated for robustness.
Scenario-bracketing framed the quantitative modeling across the analysis window, incorporating various economic and regulatory environments. Segmentation dimensions modeled included product type, application, end user, form, and regional regulatory compliance. Compound annual growth rates were derived from historical growth trends and projected technological adoption rates. Key forecast inputs included raw material price forecasts and new environmental regulation implementation schedules.
Stress conditions across raw material price volatility and regulatory shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding market dynamics and technological advancements. Geopolitical shifts affecting trade, unforeseen technological breakthroughs, or sudden changes in key raw material supply represent specific risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Germany Industrial Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
Global Hydrophobic Coating Market
Coatings
Polyvinylidene Fluoride (PVDF) Coatings Market
Coatings
Epoxy Coating Market
Coatings
Italy Protective Coatings Market
Coatings
UV Coatings Market
Coatings
Epoxy Surface Coatings Market
Coatings
Coating Agents for Synthetic Leather Market
Coatings
Fire Retardant Coatings Market
Coatings
Radiation Curable Coatings Market
Coatings
Global Anti-Corrosion Coating Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
North America Epoxy Powder Coatings Market
Coatings
Biopolymer Coatings Market
Coatings
Tablet Coatings Market