
 Biopolymer Coatings Market | 2026-2036
Biopolymer Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Biopolymer Coatings Market Analysis
REACH restrictions on volatile organic compounds in the European Union is shifting the cost-of-entry calculus toward bio-based formulation platforms. BASF SE leverages its Ludwigshafen integrated production complex to captive-supply polysaccharide precursors for barrier coatings. Novamont S.p.A. anchors its position through proprietary starch-ester chemistry optimized for flexible packaging substrates. NatureWorks LLC specializes in polylactic acid-derived coatings for food-contact applications across North American converting operations.
Biopolymer coatings are thin-film barriers derived from renewable polysaccharides, proteins, or microbial polyesters, typically applied at thicknesses of 5-50 micrometers through aqueous dispersion or melt-processing routes, designed to confer oxygen barrier, moisture resistance, or controlled-release functionality to paper, plastic, or metal substrates. Starch-based coatings dominate current volume due to feedstock abundance and mature extrusion coating infrastructure, while chitosan coatings command premium positioning in antimicrobial food preservation and medical device applications where biocompatibility requirements are stringent. Cellulose coatings compete most directly with synthetic oxygen barriers in high-performance packaging, though alginates represent the fastest-growing chemistry for agricultural film coatings requiring soil-degradability certification.
The EPA regulates volatile organic compound emissions from coating operations under 40 CFR Part 59, while the EU Green Deal mandates 55% packaging recyclability targets that biopolymer solutions can satisfy through compostable design. FDA food-contact substance notifications and EFSA safety assessments govern migration limits for edible and near-food applications, creating dual-jurisdiction compliance burdens for multinational suppliers. Stakeholders must monitor evolving compostability certification standards across Germany, Italy, and France, where national packaging waste ordinances are diverging on home versus industrial composting acceptance criteria.
Market Dynamics
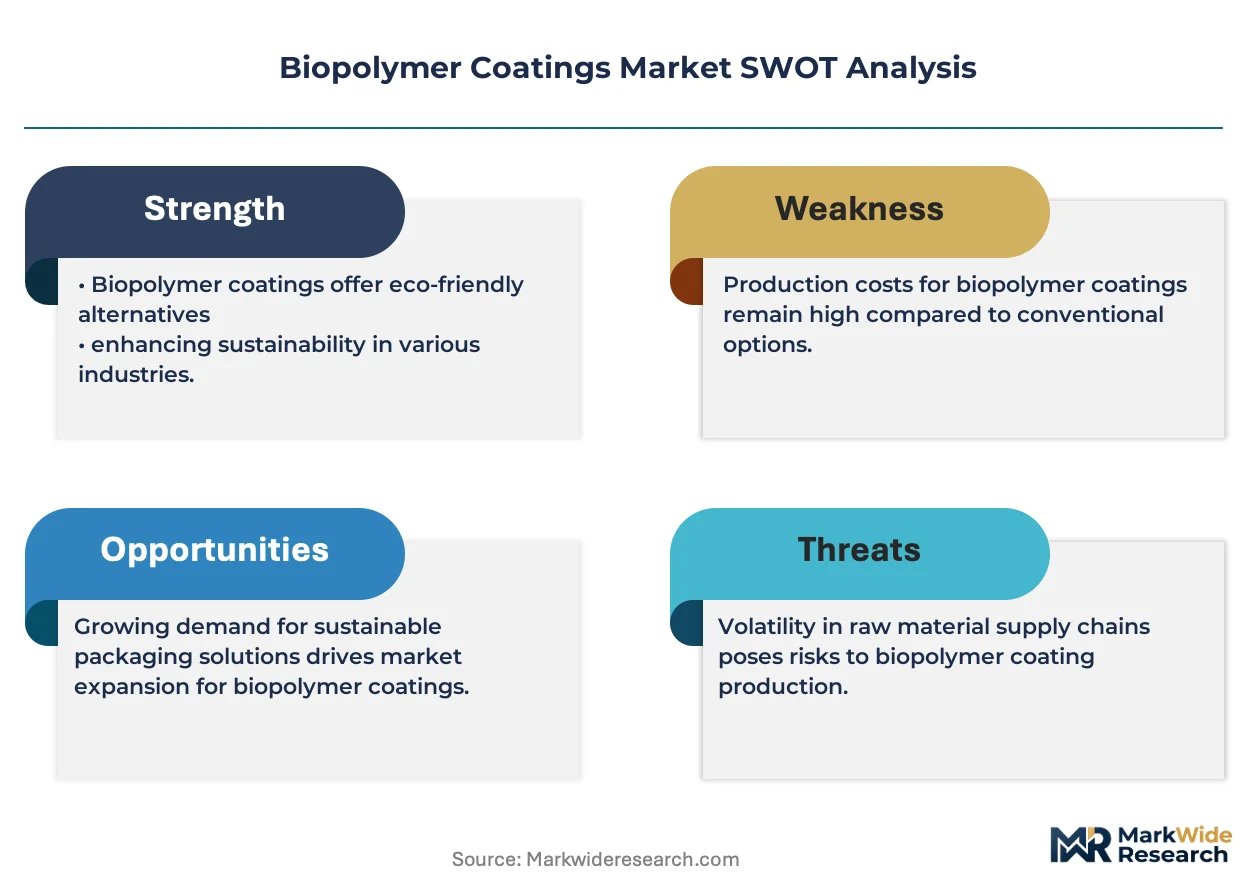
REACH restrictions on volatile organic compounds in the European Union are compressing synthetic coating margins while elevating bio-based alternatives. This regulatory pressure is accelerating capital reallocation toward polysaccharide deposition infrastructure and integrated precursor supply chains.
Growth Catalysts
- EU Green Deal packaging recyclability mandates:The 55% recyclability target creates direct substitution incentives for compostable barrier films in food-contact applications.
- Starch-ester chemistry maturation:Optimized extrusion coating protocols now achieve oxygen transmission rates competitive with synthetic ethylene-vinyl alcohol barriers.
- Germany:National packaging waste ordinances diverging on composting certification standards are concentrating pilot-scale production investment in Ludwigshafen and Terni industrial clusters.
Market Restraints
- Feedstock cost volatility:Corn and potato starch prices fluctuate with agricultural commodity cycles, compressing margin stability for coating formulators.
- Industrial composting infrastructure gaps:Home composting rejection in France and Italy limits addressable market for certified-degradable films.
- Moisture sensitivity:Unmodified polysaccharide barriers exhibit hydrophilic swelling that degrades high-humidity performance versus synthetic alternatives.
Strategic Opportunities
- Chitosan antimicrobial coatings:Medical device sterilization packaging represents underpenetrated premium positioning where biocompatibility requirements exclude petroleum-derived options.
- Alginate agricultural films:Soil-degradability certification requirements in precision farming applications drive fastest-growing chemistry segment.
- Dual-jurisdiction compliance services:FDA food-contact substance notifications and EFSA safety assessments create bundled consulting demand for multinational suppliers.
Industry Challenges
- Compostability certification timeline fragmentation:Divergent national standards across Germany, Italy, and France delay product launch cycles.
- Aqueous dispersion equipment retrofit costs:Legacy solvent-based coating lines require capital-intensive conversion to handle high-viscosity biopolymer slurries.
- Migration limit testing capacity:FDA and EFSA analytical backlog extends food-contact approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopolymer Coatings Market |
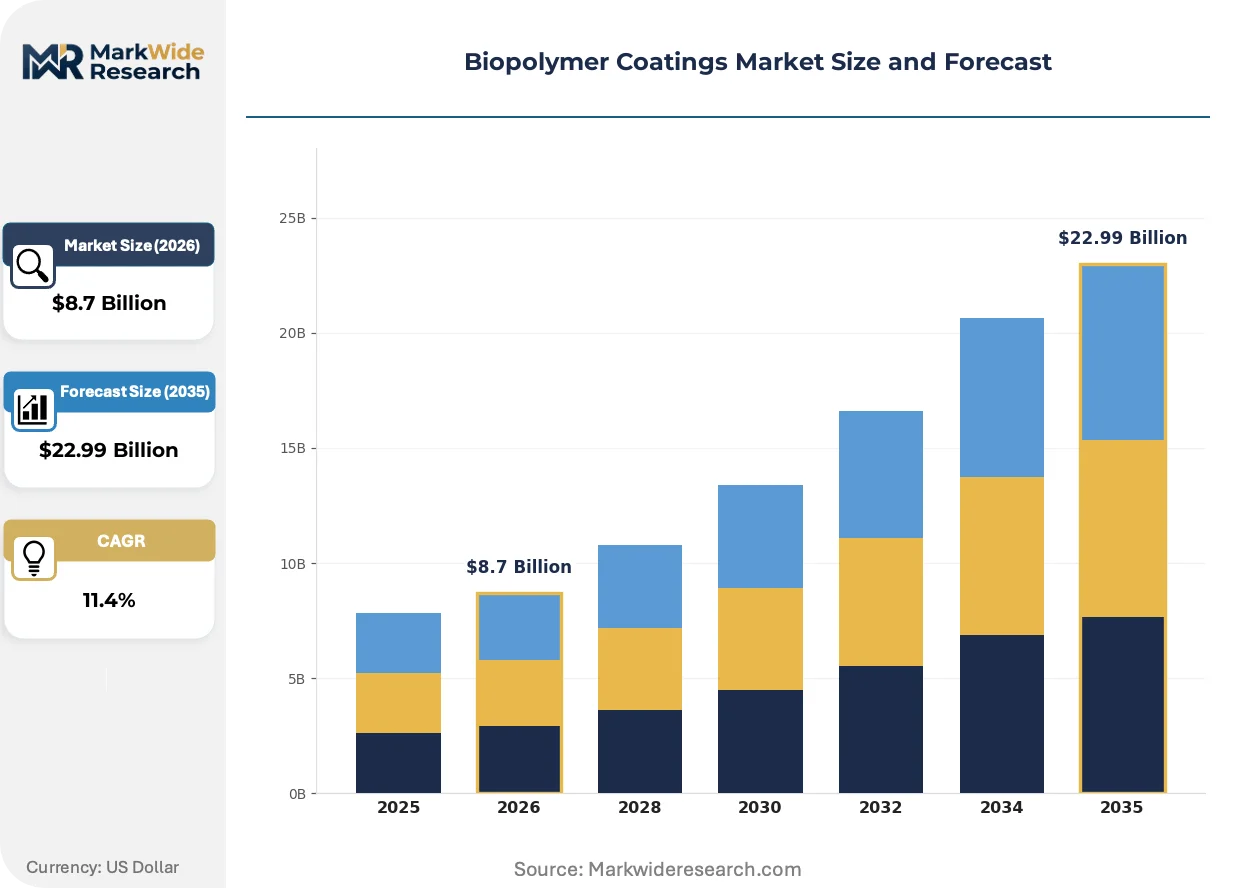
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch-Based Coatings, Cellulose Coatings, Chitosan Coatings, Alginates Application: Packaging, Agricultural Films, Food Preservation, Coatings for Medical Devices End User: Food Industry, Healthcare, Agriculture, Textile Industry Technology: Spray Coating, Dip Coating, Extrusion Coating, Electrospinning |
| Companies Covered | BASF SE, Arkema S.A., AkzoNobel N.V., NatureWorks LLC, Novamont S.p.A., DuPont de Nemours Inc, Cargill, Incorporated, Evonik Industries AG, Mitsubishi Chemical Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopolymer Coatings Market Emerging Trajectories
Coating deposition technology is fragmenting into substrate-specific process modules. Equipment suppliers and formulators are co-developing integrated systems that match polysaccharide rheology to paper, plastic, and metal surface energy profiles.
Multilayer coextrusion is modularizing barrier architecture design. Food packaging converters in North America are adopting plug-and-play die configurations that alternate starch-based oxygen barriers with cellulose moisture layers. This equipment flexibility is compressing formulation-to-production cycles from months to weeks for customized substrate specifications.
EPA enforcement of 40 CFR Part 59 is tightening volatile organic compound emission thresholds for coating operations. The industrial consequence is accelerated aqueous dispersion adoption in US converting facilities. Flexible packaging substrates face the steepest compliance cost escalation, driving solvent-to-water technology switching in Midwestern paper coating clusters.
Buyer specifications now mandate compostability certification as a gatekeeping criterion. Brand-owner procurement teams are disqualifying uncertified suppliers from shortlists regardless of price positioning. This preference shift is most visible in German retail private-label packaging, where industrial composting acceptance has become a mandatory tender requirement.
Biopolymer Coatings Market Segmentation
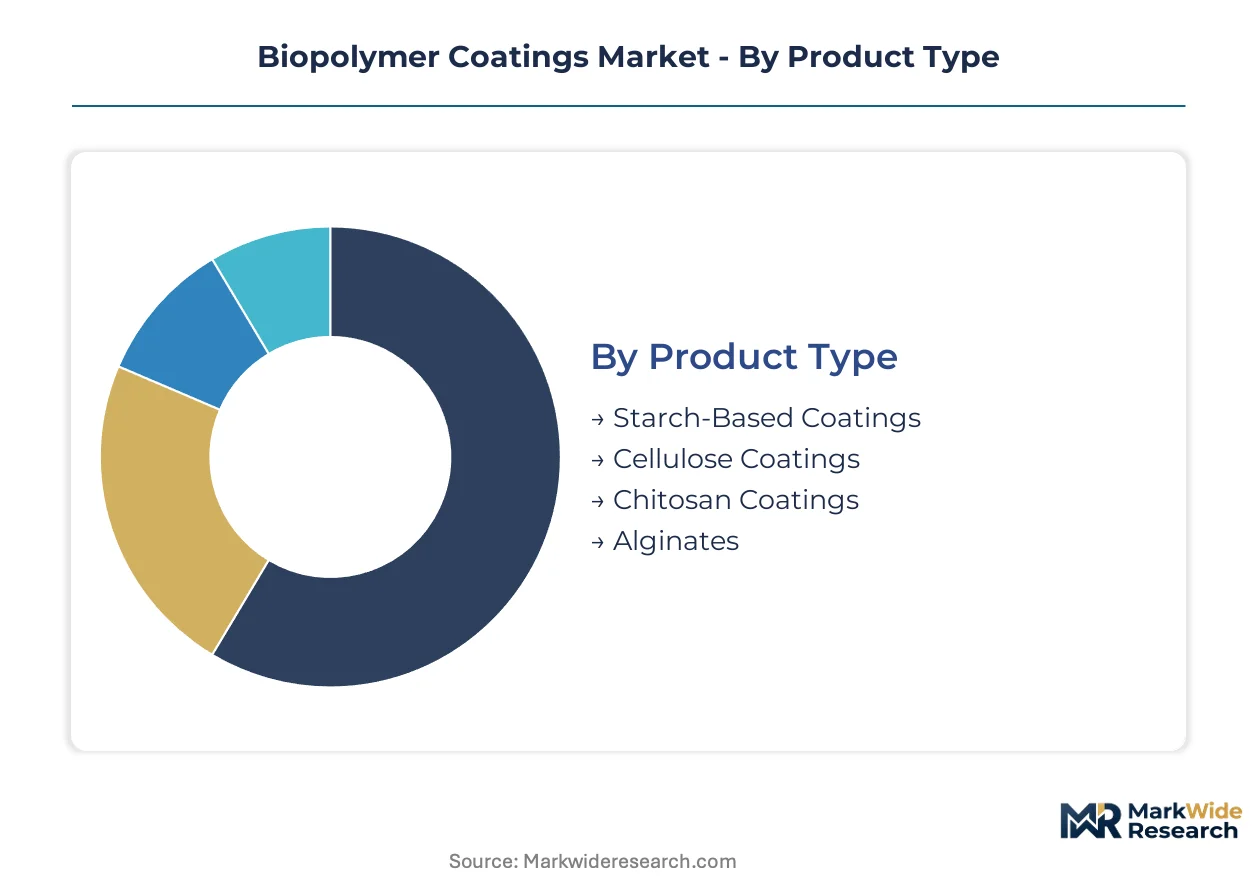
Biopolymer coatings serve divergent performance requirements across packaging, medical, and agricultural substrates. Segmentation reveals which chemistries and deposition methods align with specific barrier specifications and regulatory compliance tiers.
Product Type:
Starch-based formulations function as standalone barrier layers, while cellulose and chitosan variants embed into multilayer substrate architectures demanding higher oxygen impermeability.
- Starch-Based Coatings:Derived from corn, potato, or tapioca polysaccharides through esterification or grafting protocols. Demand concentrates in German flexible packaging converters supplying retail private-label food brands, where REACH volatile organic compound restrictions have accelerated solvent-to-aqueous line conversions.
- Cellulose Coatings:Regenerated cellulose or cellulose derivative films applied through solvent casting or aqueous dispersion. High-performance oxygen barrier specifications in Italian pasta and bakery packaging drive adoption where extended shelf life requirements exclude unmodified starch alternatives.
- Chitosan Coatings:Deacetylated chitin polysaccharides with inherent antimicrobial activity.
- Alginates:Seaweed-derived gelling polysaccharides for soil-degradable agricultural films.
Volume placements concentrate in starch-based formulations; the faster expansion belongs to alginates.
Application:
Cost tier stratification separates commodity packaging volumes from premium medical and precision agriculture positioning.
- Packaging:Barrier coatings for paperboard, flexible films, and rigid containers. German retail procurement mandates now require industrial composting certification as a tender gatekeeper, disqualifying uncertified suppliers regardless of price positioning.
- Agricultural Films:Mulch and greenhouse films requiring soil biodegradability certification.
- Food Preservation:Edible or near-food coatings extending produce shelf life through moisture regulation or antimicrobial release. French and Italian home composting rejection limits addressable market for certified-degradable edible films.
- Coatings for Medical Devices:Sterilization barrier and biocompatible surface treatments. FDA food-contact substance notification requirements and EFSA safety assessments create dual-jurisdiction compliance burdens for multinational suppliers targeting both North American and European device manufacturers.
Packaging absorbs the largest volume commitments; medical device coatings command the steepest pricing premiums.
End User:
Customer type determines specification stringency, with healthcare and food industries imposing migration limit testing that agricultural and textile buyers rarely require.
- Food Industry:Converters and brand owners demanding oxygen and moisture barriers for shelf-stable and fresh products. EPA enforcement of 40 CFR Part 59 volatile organic compound thresholds accelerates aqueous dispersion adoption in Midwestern US paper coating clusters.
- Healthcare:Medical device manufacturers and sterilization packaging suppliers. Chitosan antimicrobial coatings penetrate this segment fastest where biocompatibility requirements exclude petroleum-derived alternatives.
- Agriculture:Precision farming operations and controlled-environment growers.
- Textile Industry:Functional fabric treatments and technical textile finishing.
Food industry procurement dominates current placements; healthcare represents the most defensible margin tier.
Technology:
Maturity gradients separate established extrusion coating infrastructure from emerging electrospinning precision deposition.
- Spray Coating:Pneumatic or airless atomization of aqueous biopolymer dispersions. Legacy solvent-based coating lines in US flexible packaging substrates face capital-intensive retrofit to handle high-viscosity starch-ester slurries under tightening EPA emission thresholds.
- Dip Coating:Submersion and withdrawal processes for complex geometries.
- Extrusion Coating:Melt-processing of thermoplastic biopolymers onto moving substrates. BASF SE and Novamont S.p.A. operate integrated pilot lines in Ludwigshafen and Terni industrial clusters optimized for high-throughput polysaccharide deposition.
- Electrospinning:Electric field-driven fiber formation for nanostructured barrier layers.
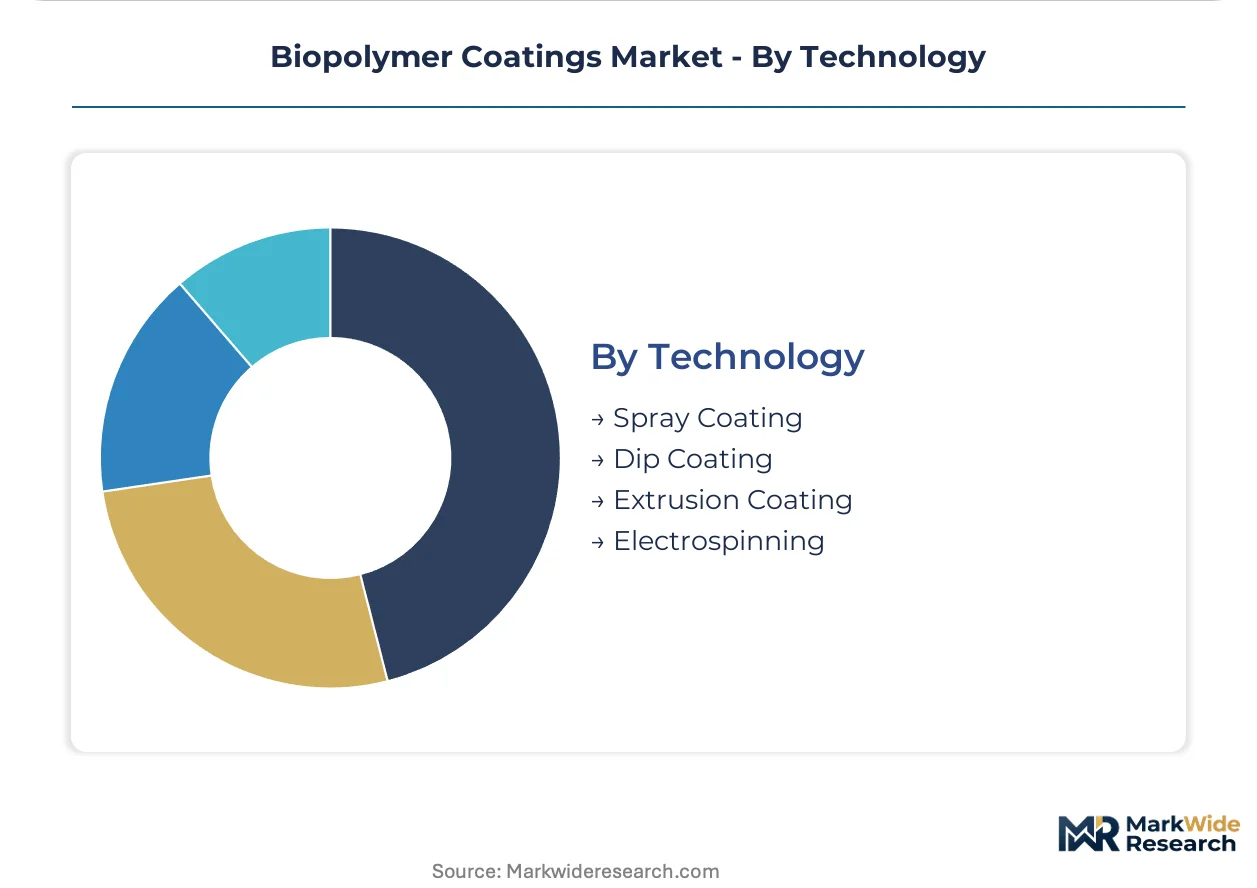
Extrusion coating anchors the installed base; electrospinning gains share fastest in medical and high-barrier packaging niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for biopolymer coatings clusters in Germany, the United States, and Japan, where food packaging converters and medical device manufacturers drive specification intensity. Regulatory pressure on petroleum-derived alternatives accelerates capital deployment toward polysaccharide deposition infrastructure in these markets.
Germany
Flexible packaging converters supplying retail private-label brands dominate starch-based coating procurement. REACH restrictions on volatile organic compounds elevate compliance costs for synthetic alternatives. BASF SE operates integrated pilot lines at its Ludwigshafen complex for high-throughput polysaccharide deposition.
United States
EPA enforcement of 40 CFR Part 59 emission thresholds accelerates aqueous dispersion adoption in Midwestern paper coating clusters. FDA food-contact substance notifications govern migration limits for edible and near-food applications. NatureWorks LLC specializes in polylactic acid-derived coatings for North American converting operations.
Japan
Medical device sterilization packaging generates premium demand for chitosan antimicrobial barriers where biocompatibility requirements exclude petroleum-derived options. METI industrial standards support bio-based material certification programs. Mitsubishi Chemical Group Corporation anchors domestic supply chain development for high-performance oxygen barriers.
Italy
Pasta and bakery packaging converters specify cellulose coatings for extended shelf life requirements that exclude unmodified starch alternatives. National packaging waste ordinances diverge from France on home versus industrial composting acceptance criteria. Novamont S.p.A. maintains integrated production at its Terni industrial cluster.
France
Retail procurement mandates now require industrial composting certification as a tender gatekeeper, disqualifying uncertified suppliers. ANSM biocompatibility assessments govern medical device coating approvals. Arkema S.A. positions within specialty polymer portfolios serving barrier film applications.
Biopolymer Coatings Market Vendor Landscape
German producers anchor one tier; United States specialists hold differentiated positions in polylactic acid chemistry. The vendor base organizes around three strategic archetypes: integrated chemical conglomerates with captive precursor supply, dedicated biopolymer specialists with proprietary starch-ester platforms, and diversified material science portfolios spanning synthetic and bio-based barriers. Competitive moves concentrate on backward integration into agricultural feedstock sourcing and technology licensing partnerships with food packaging converters.
Among Germany-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated archetype through Ludwigshafen production complex operations and specialty additive positioning. Novamont S.p.A. represents the dedicated biopolymer specialist model with Italian integrated pilot line infrastructure. NatureWorks LLC occupies a position within United States polylactic acid chemistry for food-contact applications.
| Leading Market Players |
|---|
| BASF SE |
| Arkema S.A. |
| AkzoNobel N.V. |
| NatureWorks LLC |
| Novamont S.p.A. |
| DuPont de Nemours Inc |
| Cargill, Incorporated |
| Evonik Industries AG |
| Mitsubishi Chemical Group Corporation |
| Others |
Supply Flow & Price Mechanics
Corn starch futures and agricultural commodity benchmarks cascade through biopolymer coating supply chains into three distinct pricing tiers. Feedstock volatility at the farm gate compresses margin stability for formulators while concentrating pricing power among integrated producers with captive precursor supply.
Pricing Analysis
Volume placements cluster in standard-grade starch-ester coatings where price competition is most intense, while premium tiers capture medical and antimicrobial applications with biocompatibility certification requirements. Price differentiation hinges on compostability certification grade and REACH compliance tier, with German industrial composting certification commanding substantial premiums. Cost compression in commodity packaging tiers is intensifying due to agricultural feedstock volatility, though food industry buyers exhibit highest price sensitivity while healthcare procurement tolerates steeper premiums for regulatory assurance.
Supply Chain Analysis
Polysaccharide precursor supply rests on German, Italian, and United States agricultural processing infrastructure and specialty chemical manufacturing clusters. Corn starch, potato starch, and chitosan feedstock dependencies create exposure to commodity crop cycles and seasonal harvest variability. Single-source vulnerability concentrates in seaweed-derived alginate supply chains anchored to specific coastal harvesting regions. Distribution runs through integrated chemical conglomerates with captive logistics networks and specialized biopolymer distributors serving regional converting clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH volatile organic compound restrictions have erected a formidable cost-of-compliance barrier that rewards integrated players with existing aqueous dispersion infrastructure while screening out undercapitalized entrants lacking regulatory affairs capabilities.
For Market Incumbents: Anticipate margin compression in commodity starch-based tiers from emerging Asian producers with lower feedstock costs. BASF SE and Novamont S.p.A. should deepen backward integration into agricultural sourcing and accelerate technology licensing partnerships with North American converters to lock in long-term offtake before capacity expansion saturates standard-grade segments. For New Entrants and Emerging Players: EU Green Deal packaging recyclability mandates in Germany open a window for alginate agricultural film specialists with soil-degradability certification capabilities. The most penetrable white-space sits in French and Italian home composting-certified edible coatings, where national regulatory divergence has stalled incumbent product launch cycles. A targeted go-to-market angle leverages bundled FDA-EFSA dual-jurisdiction compliance services for multinational food brands. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap biopolymer specialists with proprietary starch-ester platforms and established industrial composting certification in the Terni and Ludwigshafen clusters. Long-term viability over the next decade hinges on successful navigation of aqueous dispersion equipment retrofit demand and migration limit testing capacity expansion. The critical signal to watch is EPA enforcement intensity under 40 CFR Part 59, which would accelerate solvent-to-water technology switching and concentrate demand among compliant coating formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Sourcing | Captive corn and potato starch supply secures margin stability against agricultural commodity cycles. |
| Dual-Jurisdiction Compliance Service Bundling | Combined FDA and EFSA navigation capability captures multinational food packaging procurement demand. |
| Industrial Composting Certification Acceleration | German retail tender gatekeeping requirements disqualify uncertified competitors regardless of price positioning. |
| Aqueous Dispersion Equipment Retrofit Partnerships | Legacy solvent-based line conversion demand in US Midwestern paper coating clusters creates captive equipment-supplier relationships. |
| Alginate Agricultural Film Capacity Expansion | Soil-degradability certification requirements in precision farming drive fastest-growing chemistry segment adoption. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with coating formulator R&D directors, food packaging converter procurement leads, agricultural film distributors, and FDA regulatory affairs consultants combined with ECHA restriction dossiers, EPA enforcement records, and EU Green Deal implementation reports. Bottom-up volume modeling across deposition technology types triangulated against top-down chemical industry capacity assessments.
Segmentation granularity extended to chemistry type, substrate application, and end-use industry across the projection horizon. Starch-based, cellulose, chitosan, and alginate chemistries were modeled separately with distinct feedstock cost structures and certification requirement tiers. CAGRs derived from installed base growth, regulatory substitution elasticities, and brand-owner procurement specification shifts. Forecast inputs incorporated REACH volatile organic compound restriction phase-in schedules and divergent national composting certification timelines.
The model assumes a particular technology adoption path; alternative pathways for electrospinning nanostructured barrier deposition would alter the outlook if equipment cost curves steepen faster than projected. Forecasts reflect assumptions regarding EPA enforcement continuity, EU packaging waste ordinance harmonization, and agricultural commodity price normalization. Regulatory backlog at FDA and EFSA, feedstock crop failure frequency, and home composting infrastructure buildout rates constitute the small set of triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Metal Coatings Market
Coatings
Global Sputter Coater Market
Coatings
Polyvinylidene Chloride (PVDC) Coated Films Market
Coatings
Russia Protective Coatings Market
Coatings
Glass Coatings Market
Coatings
Marine Nanocoating Market
Coatings
North America Polyimide Coating Market
Coatings
Insulation Coating Market
Coatings
Plastic-Coated Wires Market
Coatings
Canada Automotive OEM Coatings Market
Coatings
Camouflage Coatings Market
Coatings
Polyurethane Powder Coatings Market
Coatings
Marine Anti Fouling Coatings Market
Coatings
South America Thermal Spray Market
Coatings
Stain Resistance Coatings Market
Coatings
Anti Fog Coatings Market