
 Asia-Pacific Automotive Refinish Coatings Market | 2026-2036
Asia-Pacific Automotive Refinish Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Refinish Coatings Market Outlook
Water-borne polyurethane dispersion technology is rewriting the formulation architecture for automotive refinish coatings across the Asia-Pacific. Axalta Coating Systems leverages its Thailand manufacturing base to supply collision centers throughout ASEAN with low-VOC compliant systems. Kansai Paint Co., Ltd. anchors its regional position through deep distribution ties with Japanese OEM-certified bodyshops. PPG Industries, Inc. competes on color-matching digital infrastructure that reduces rework rates in high-throughput repair environments.
Asia-Pacific automotive refinish coatings constitute pigmented and clear film-forming systems designed for substrate adhesion, corrosion protection, and aesthetic restoration on damaged vehicle surfaces, typically applied in 2-3 coat build sequences with bake schedules between 60-80°C. Their primary commercial purpose is to return collision-damaged or weathered vehicles to OEM color specifications while meeting durability benchmarks of 5-10 years under regional climate stress. Clear coat formulations command premium positioning due to gloss retention and UV resistance requirements in tropical markets, while water-based base coat systems represent the fastest-growing technology segment as environmental compliance tightens across multiple jurisdictions. Primer-surfacer demand remains volume-heavy in India and Indonesia where substrate preparation standards lag premium markets.
China's MEE enforces GB 24409 limits on VOC content in automotive coatings, directly constraining solvent-based formulation sales while accelerating water-borne line conversions. Japan's METI promotes JIS K 5658 compliance for refinish durability, creating specification barriers for imported products lacking local weathering validation. India's BIS certification requirements for automotive coatings are expanding from decorative to functional performance standards, raising market access costs for unqualified suppliers. Stakeholders must monitor regulatory divergence between harmonized ASEAN frameworks and country-specific emission rules when allocating R&D and production assets across the region.
Market Dynamics
Water-borne polyurethane dispersion technology is forcing solvent-based formulation obsolescence across collision repair networks, while China's GB 24409 VOC limits and India's BIS certification expansion reshape competitive entry barriers.
Growth Catalysts
- GB 24409 Enforcement:China's MEE mandates on automotive coating VOC content are accelerating water-borne line conversions among domestic manufacturers and imported brands alike.
- Tier-2 Workshop Density:India's independent bodyshops in secondary cities now outnumber organized collision centers, creating volume demand for primer-surfacer systems.
- ASEAN Network Expansion:Thailand-based manufacturing hubs supply low-VOC compliant systems to collision centers throughout Southeast Asia as vehicle parc density rises.
Market Restraints
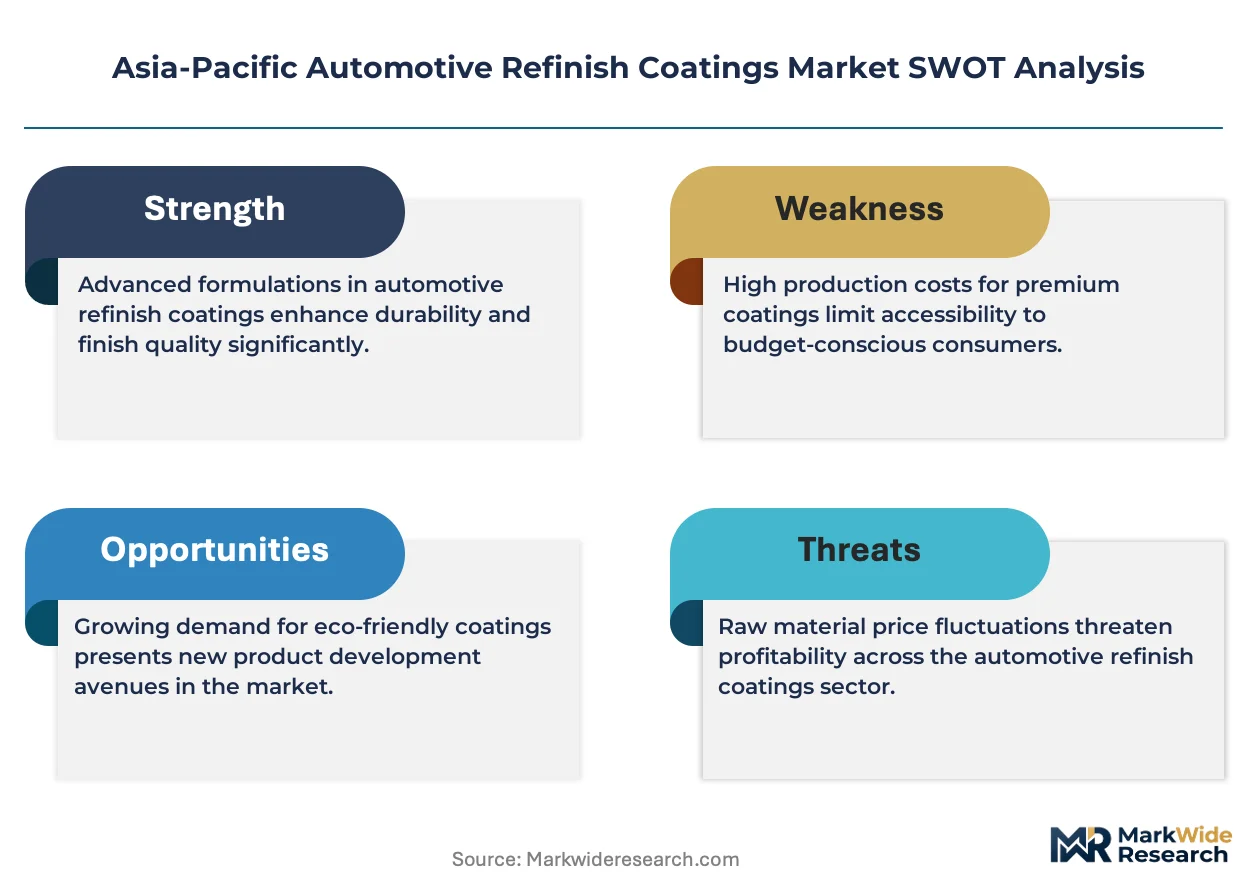
- Isocyanate Input Volatility:Polyurethane hardener raw material costs fluctuate with petrochemical feedstock availability, compressing margin predictability for refinish coating producers.
- Weathering Validation Gaps:Japan's METI JIS K 5658 durability standards create specification barriers for imported products lacking localized tropical climate testing protocols.
- Substrate Preparation Lag:Primer-surfacer demand concentration in Indonesia and India reflects persistent gaps in surface preparation standards versus premium markets.
Strategic Opportunities
- Digital Color-Matching Infrastructure:High-throughput repair environments in metropolitan Australia and South Korea are adopting spectrophotometer-linked formulation systems to reduce rework rates.
- Dual Carbon Alignment:China's dual carbon goals are creating procurement preference for coatings suppliers with verified carbon footprint reduction across their manufacturing footprint.
- Tier-3 City Penetration:India's BIS certification expansion into functional performance standards is raising access costs for unqualified suppliers, favoring organized distributors with compliance capabilities.
Industry Challenges
- Application Technician Certification:Water-borne system conversions require spray booth reconfiguration and painter retraining, extending deployment timelines in independent workshop segments.
- Harmonization Friction:Regulatory divergence between ASEAN framework harmonization efforts and country-specific emission rules complicates R&D asset allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Refinish Coatings Market |
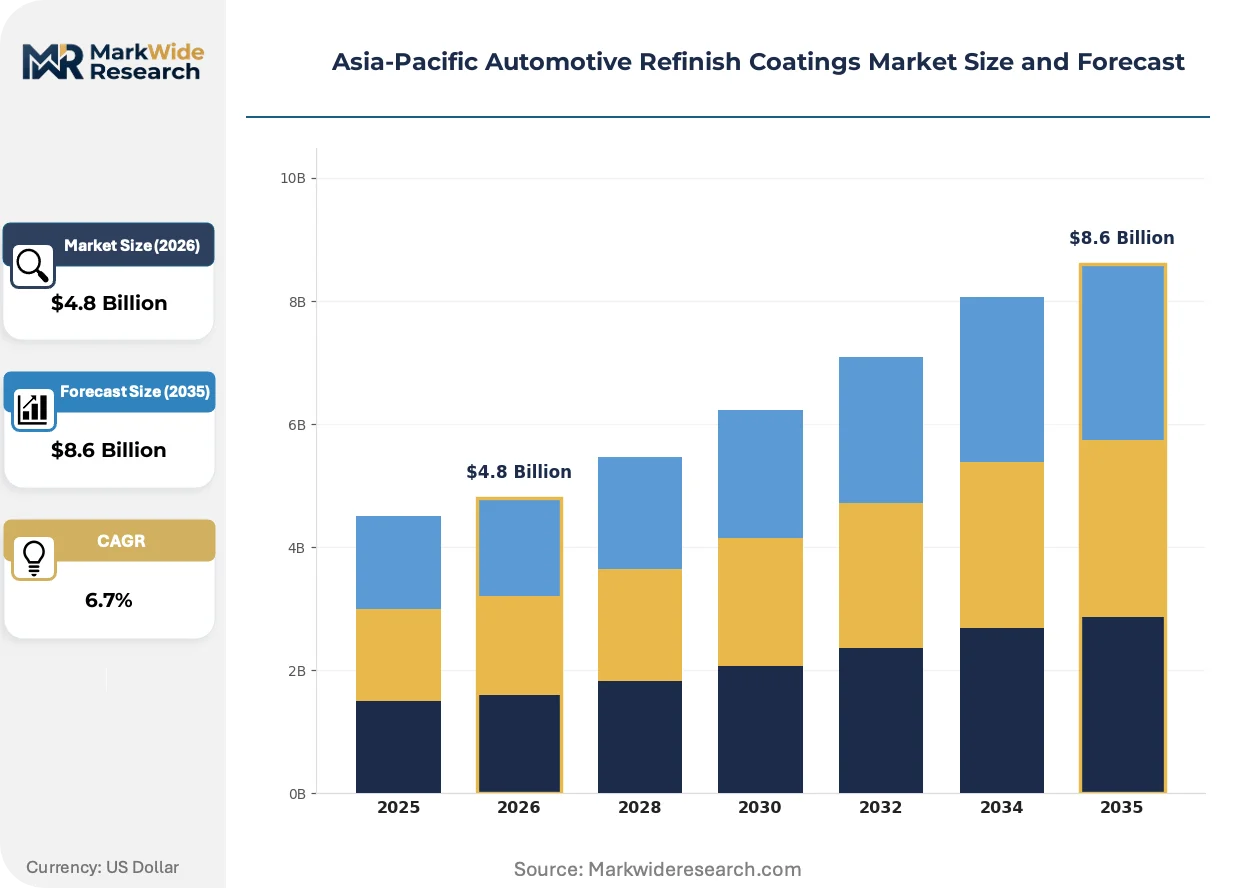
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Coat, Clear Coat, Primer, Surfacer Technology: Solvent-Based, Water-Based, Powder Coating, UV-Cured End User: OEMs, Bodyshops, Independent Workshops, Fleet Operators Application: Repair, Restoration, Customization, Touch-Up |
| Companies Covered | Axalta Coating Systems, AkzoNobel N.V., Nippon Paint Holdings Co., Ltd., 3M, The Sherwin-Williams Company, Kansai Paint Co., Ltd., BASF SE, Asian Paints Limited, PPG Industries, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Refinish Coatings Market Strategic Shifts
Formulation chemistry, compliance architecture, and repair workflow digitization are converging to redefine competitive advantage in automotive refinish coatings across the Asia-Pacific.
Water-borne base coat systems are migrating from solvent-dominated architectures to polyurethane dispersion platforms engineered for tropical UV resistance and humidity tolerance. Collision centers in Thailand, Malaysia, and Vietnam are adopting these systems at accelerated pace to meet tightening environmental enforcement. This technology transition is compressing the viable product portfolio for suppliers lacking water-borne R&D capabilities.
China's GB standards on volatile organic compound emissions are constraining solvent-based formulation sales while accelerating line conversions among domestic and multinational producers. The industrial consequence is a bifurcation between compliant water-borne suppliers and legacy solvent-dependent operations facing market access restrictions. Base coat and clear coat segments in coastal Chinese provinces are responding fastest, driven by MEE inspection intensity in manufacturing clusters.
Independent workshop procurement patterns are consolidating around distributor-led technical service models that bundle product supply with color-matching support and inventory management. Organized multi-shop operators in Australia's metropolitan corridors are displacing fragmented single-location buying through volume-negotiated supply agreements. This channel evolution is most visible in South Korea and Japan, where OEM-certified bodyshop networks concentrate purchasing leverage.
Asia-Pacific Automotive Refinish Coatings Market Segmentation
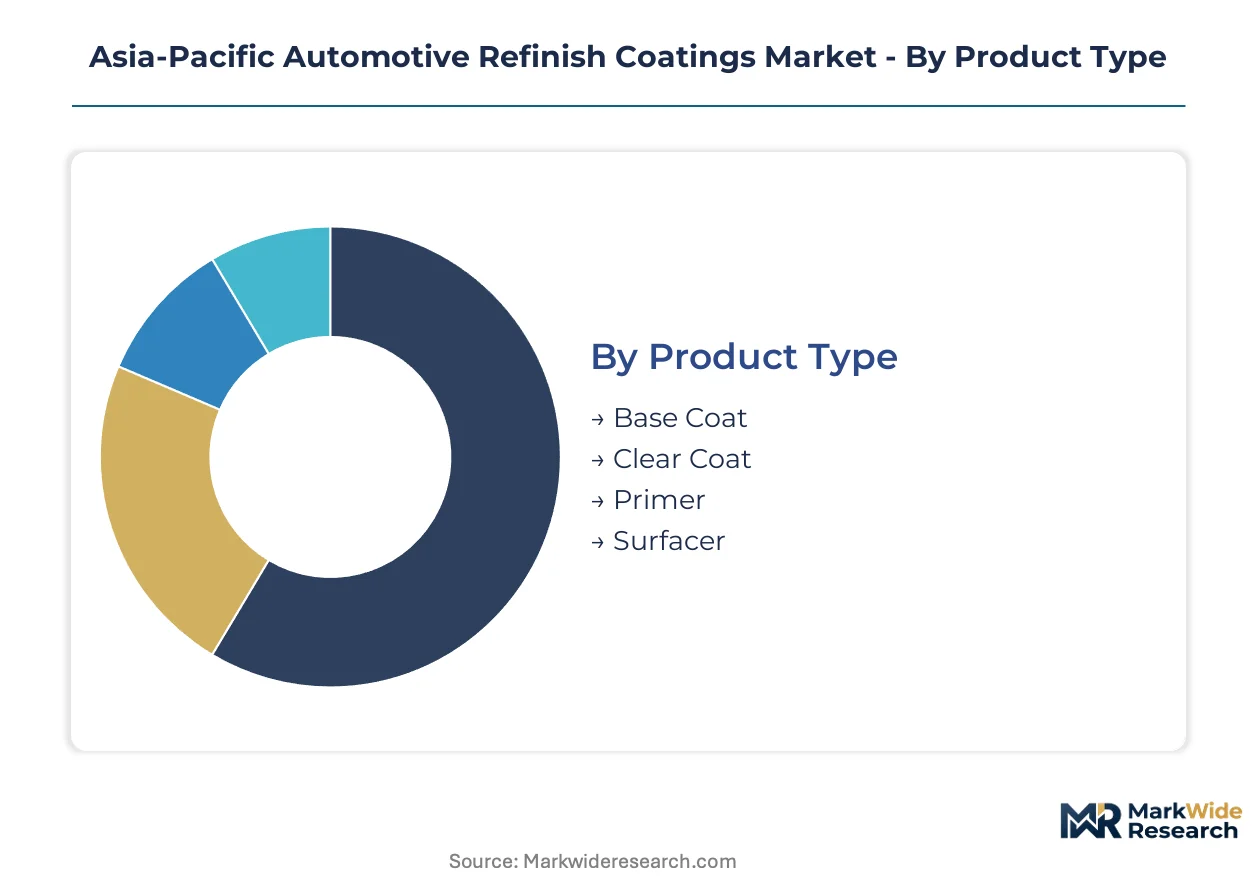
Segmentation in Asia-Pacific automotive refinish coatings reveals divergent profit pools across technology generations and service channel tiers. Understanding where volume concentrates versus where margins expand allows suppliers to align R&D and distribution investments with structural market shifts.
Product Type:
Base coat systems turn over fastest in high-throughput collision networks, while primer-surfacer demand cycles align with substrate preparation standards in emerging markets.
- Base Coat:Pigmented film-forming systems engineered for OEM color fidelity and substrate adhesion. Demand concentrates in China's coastal provinces where MEE enforcement on VOC content accelerates water-borne conversions among domestic manufacturers.
- Clear Coat:Transparent polyurethane formulations providing gloss retention and UV resistance against tropical climate stress. Expansion concentrates in Thailand and Malaysia where collision centers prioritize durability benchmarks for premium vehicle segments.
- Primer:Corrosion-inhibiting undercoats applied for substrate sealing and adhesion promotion. Volume demand persists in India's tier-2 cities where independent workshops outnumber organized bodyshops.
- Surfacer:High-build formulations filling substrate imperfections prior to base coat application. Procurement concentrates in Indonesia where surface preparation standards lag premium markets.
Primer-surfacer dominates installed base across India and Indonesia. Clear coat is where expansion concentrates as tropical UV resistance specifications tighten.
Technology:
Cost tier stratification separates legacy solvent systems from premium water-borne platforms, with powder and UV technologies occupying narrow specialty niches.
- Solvent-Based:Conventional polyurethane and acrylic formulations with established application protocols. Demand is contracting in China's manufacturing clusters under GB 24409 VOC limits enforced by MEE inspectors.
- Water-Based:Polyurethane dispersion platforms engineered for humidity tolerance and low-emission compliance. This segment is gaining share fastest in Thailand, Vietnam, and coastal China where environmental enforcement intensifies.
- Powder Coating:Thermoset polymer systems requiring electrostatic application and high-temperature cure. Adoption remains limited to specialized restoration workshops in Japan and South Korea with captive bake infrastructure.
- UV-Cured:Photoinitiator-activated formulations polymerizing under ultraviolet exposure. Niche deployment concentrates in Australia's metropolitan collision centers seeking minimized cycle times for fleet repair contracts.
Solvent-based technology dominates installed base. Water-based platforms are where expansion concentrates.
End User:
Customer type determines procurement leverage, with OEM-certified networks extracting volume discounts versus fragmented independent channels.
- OEMs:Original equipment manufacturer captive repair facilities maintaining brand-standard color matching and warranty protocols. Concentrated in Japan and South Korea where JIS K 5658 durability certification creates specification barriers.
- Bodyshops:Organized multi-bay collision centers with spray booth infrastructure and certified technician staffing. Australia's metropolitan corridors show consolidation toward volume-negotiated supply agreements displacing fragmented purchasing.
- Independent Workshops:Single-location or small-chain repair operators dominating India's tier-2 and tier-3 cities. Procurement patterns consolidate around distributor-led technical service models bundling product with color-matching support.
- Fleet Operators:Commercial vehicle and rental fleet maintenance departments with standardized color requirements and throughput priorities. Expanding across Southeast Asia as logistics vehicle parc density rises.
Independent workshops dominate installed base across India and Indonesia. Organized bodyshops are where expansion concentrates.
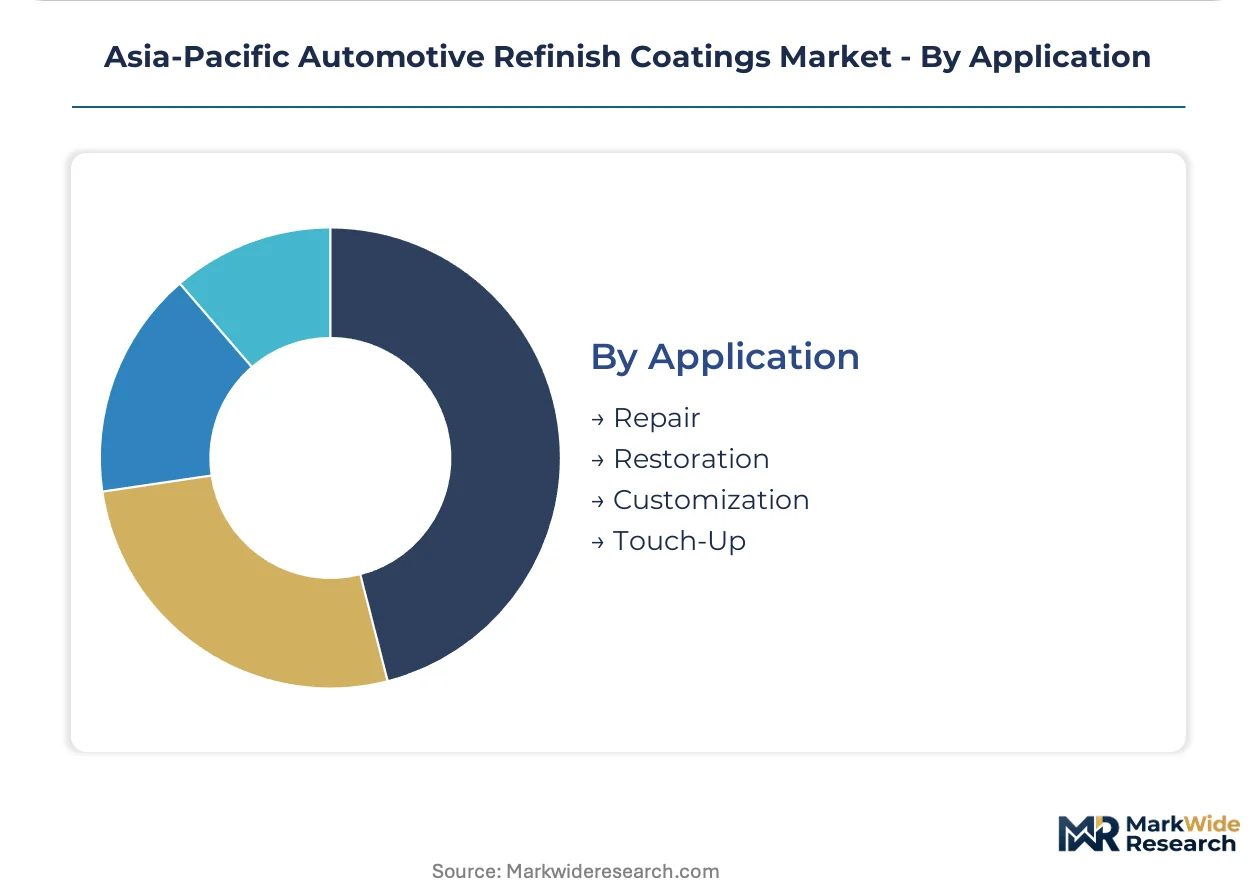
Application:
Volume scale differentiates high-frequency collision repair from episodic restoration and customization work.
- Repair:Standard collision damage remediation returning vehicles to OEM specifications. This segment commands highest throughput in China's dense urban corridors and Australia's metropolitan networks.
- Restoration:Comprehensive refinishing of aged or collectible vehicles requiring period-correct color matching. Niche demand concentrates in Japan's specialist workshops serving classic vehicle collectors.
- Customization:Aesthetic modification including color changes, graphics, and specialty finishes. Growing in South Korea's aftermarket scene and Thailand's tuning culture.
- Touch-Up:Localized spot repair for minor damage and stone chip remediation. Volume-heavy in India's independent workshop segment where full panel resprays are cost-prohibitive for many vehicle owners.
Repair dominates installed base. Customization is where expansion concentrates as discretionary spending on vehicle personalization rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Collision repair procurement concentrates in organized bodyshop networks across China's coastal manufacturing clusters and India's expanding tier-2 cities. Water-borne technology migrations and VOC enforcement are reshaping supplier access across jurisdictions.
China
Guangdong and Jiangsu provinces drive base coat demand as MEE enforces GB 24409 VOC limits in manufacturing clusters. Shanghai's collision centers accelerate water-borne line conversions to maintain market access. The Yangtze River Delta houses the densest concentration of compliant coating distribution infrastructure.
India
Maharashtra and Gujarat host expanding vehicle parc density fueling primer-surfacer procurement in independent workshops. BIS certification expansion into functional performance standards raises compliance costs for imported suppliers. Delhi-NCR's organized bodyshops consolidate purchasing through distributor-led technical service bundles.
Japan
Kanto region collision networks concentrate OEM-certified repair demand under METI's JIS K 5658 durability protocols. Osaka-Kansai workshops enforce specification barriers lacking localized tropical weathering validation. Nagoya's automotive manufacturing corridor anchors captive refinish supply relationships with domestic coating suppliers.
Thailand
Bangkok metropolitan collision centers absorb low-VOC compliant systems from regional manufacturing hubs. Rayong's industrial estates support ASEAN distribution networks serving Vietnam and Malaysia. Environmental enforcement in coastal provinces accelerates water-borne polyurethane dispersion adoption.
Australia
New South Wales and Victoria metropolitan corridors deploy spectrophotometer-linked color-matching systems to reduce rework rates. Sydney's multi-shop operators displace fragmented purchasing through volume-negotiated supply agreements. Melbourne's fleet repair contracts prioritize minimized cycle times for commercial vehicle throughput.
Asia-Pacific Automotive Refinish Coatings Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent service tiers. The market structure consolidates around multinational coating manufacturers with captive distribution networks, while regional specialists occupy technology-transition niches. Two archetypes dominate: integrated coating-distribution platforms serving OEM-certified networks, and independent formulators targeting price-sensitive independent workshops. Competitive moves center on water-borne R&D licensing agreements and distributor acquisition to secure tier-2 city penetration.
Within the integrated platform tier, Axalta Coating Systems and PPG Industries, Inc. exemplify multinational manufacturers with established ASEAN supply infrastructure. Kansai Paint Co., Ltd. represents Japanese-origin specialists with deep OEM bodyshop certification relationships. These three entities occupy positions defined by regulatory compliance capabilities and color-matching digital infrastructure rather than commodity formulation supply.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| AkzoNobel N.V. |
| Nippon Paint Holdings Co., Ltd. |
| 3M |
| The Sherwin-Williams Company |
| Kansai Paint Co., Ltd. |
| BASF SE |
| Asian Paints Limited |
| PPG Industries, Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's solvent-based coating manufacturing clusters is compressing margins and accelerating supplier exits as MEE enforcement on GB 24409 VOC limits intensifies. This utilization imbalance concentrates pricing power among water-borne compliant producers while forcing distressed asset sales among legacy operators unable to fund line conversions.
Pricing Analysis
Cost-plus contracts indexed to isocyanate and petrochemical feedstock benchmarks dominate procurement between multinational suppliers and organized bodyshop networks across Australia and South Korea. Price differentiation rests on JIS K 5658 certification tier and volume scale, with OEM-certified channels commanding premium positioning while India's independent workshops drive cost compression through distributor-led technical service bundles. Pricing pressure stems from raw material volatility in polyurethane hardener inputs. Fleet operators exhibit lowest price sensitivity due to throughput guarantees, whereas tier-3 independent workshops in Indonesia remain most price-sensitive.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard between Thailand-based manufacturers and ASEAN distributors managing inventory for Vietnamese and Malaysian collision centers. Raw material dependencies center on isocyanate hardeners from South Korea and Japan, titanium dioxide feedstock from China, and specialty additives from Germany. Tariff exposure on Chinese-origin raw materials creates margin vulnerability for water-borne line producers. Distribution runs through distributor-led technical service models bundling color-matching support with inventory management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-borne formulation R&D capabilities and localized weathering validation protocols represent scarce assets that determine competitive survival as environmental enforcement tightens across the Asia-Pacific. Suppliers lacking these competencies face structural exclusion from premium procurement channels.
For Market Incumbents: Pre-empt further consolidation by acquiring distressed solvent-dependent operations in China's coastal provinces for water-borne conversion rather than greenfield capacity. Secure backward integration into isocyanate supply through captive agreements with South Korean petrochemical producers to harden margin predictability against feedstock volatility. For New Entrants and Emerging Players: India's tier-3 cities with BIS certification gaps represent the most penetrable entry point for organized distributors bundling compliance capabilities with technical service. Indonesia's surfacer-heavy independent workshop segment offers secondary white-space where substrate preparation standards lag. Enter through exclusive distribution partnerships with established color-matching infrastructure rather than direct sales investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across water-borne R&D and tropical weathering validation facilities as regulatory barriers compound. Acquisition targets should emphasize Japanese-origin specialists with METI-validated durability protocols and deep OEM bodyshop certification relationships. Monitor MEE inspection intensity in China's Yangtze River Delta as an inflection signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Borne Line Conversion | GB 24409 compliance secures market access in China's coastal manufacturing clusters. |
| Tropical Weathering Validation | JIS K 5658 certification creates specification barriers against unqualified imports. |
| Distributor Acquisition | Channel control in India's tier-2 cities captures independent workshop procurement consolidation. |
| Digital Color-Matching Deployment | Spectrophotometer-linked systems reduce rework rates in Australian high-throughput networks. |
| Isocyanate Supply Agreement | Captive feedstock agreements with South Korean producers compress raw material volatility exposure. |
Study Parameters
A spread of perspectives from collision center operators, automotive coating procurement leads, distributor technical service heads, and regulatory compliance officers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs trade data, GB standard enforcement disclosures, SEC filings of listed coating manufacturers, and ASEAN automotive production databases. Bottom-up volume estimates from individual country clusters were triangulated against top-down regional demand projections.
Demand-supply balance modeling across product type, technology generation, end-user channel tier, and application frequency anchored the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic vehicle parc expansion assumptions. Modeled inputs included collision frequency rates by vehicle age cohort, environmental enforcement intensity indices, and water-borne technology penetration curves by jurisdiction.
Practitioners should monitor MEE inspection schedules, BIS certification expansion timelines, and isocyanate feedstock price movements for early signals of forecast deviation. Macroeconomic vehicle sales contraction, regulatory harmonization acceleration, or breakthrough UV-cured technology adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Asia-Pacific Coil Coatings Market
Coatings
Global Polytetrafluoroethylene (PTFE) Coatings Market
Coatings
Yacht Coatings Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Protective Coatings Market
Coatings
Global Performance Coating Market
Coatings
Anti-Corrosion Nanocoatings Market
Coatings
Stealth Coating Material Market
Coatings
United States Industrial Wood Coatings Market
Coatings
United States Floor Coatings Market
Coatings
North America Thermal Spray Market
Coatings
Global Polyurea Coating Market
Coatings
Global Diamond Coatings Market
Coatings
Shipping Container Coatings Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
Silicate Coatings Market