
 Coating Agents for Synthetic Leather Market | 2026-2036
Coating Agents for Synthetic Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Coating Agents for Synthetic Leather Market Analysis
Multi-source procurement among tier-one synthetic leather producers is hardening as coating agent buyers diversify away from single-supplier dependence. Covestro AG anchors its position through captive isocyanate production and direct mill relationships across Asia. Stahl Holdings B.V. differentiates via water-based polyurethane leadership and specialized finishing systems for automotive seating. Huntsman Corporation sustains geographic reach through integrated polyol supply chains serving footwear clusters in Vietnam and Indonesia.
Coating agents for synthetic leather comprise formulated polymer systems—typically polyurethane dispersions, PVC plastisols, or silicone emulsions—applied to woven or non-woven substrates to impart abrasion resistance, color fastness, and tactile properties mimicking natural leather. Polyurethane coatings dominate current volumes due to superior hand-feel and breathability in footwear and upholstery applications, while water-based technology segments expand fastest as manufacturers phase out solvent-borne systems under tightening volatile organic compound limits. Solvent-based formulations retain share in automotive interiors where extreme durability and chemical resistance specifications persist.
REACH restrictions on N-methyl-2-pyrrolidone and evolving EPA maximum achievable control technology standards are redirecting formulation investments toward low-VOC alternatives. China's GB standards on hazardous substance limits in synthetic leather products are reshaping export compliance requirements for coating agent suppliers serving Dongguan and Wenzhou manufacturing belts. Stakeholders must monitor regulatory divergence between European hazard-based frameworks and China's standards-driven approach when allocating R&D budgets and certifying product platforms.
Market Dynamics
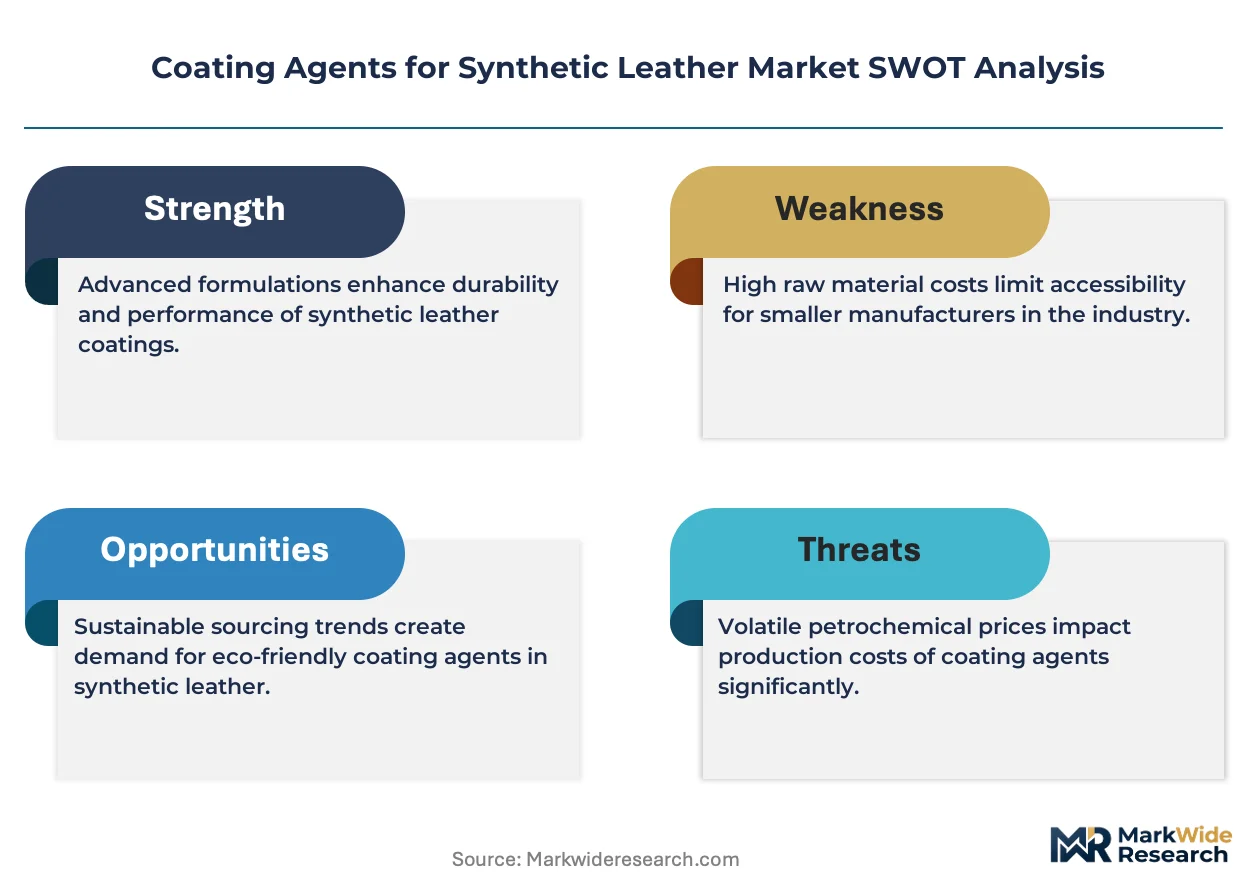
Water-based polyurethane formulations are overtaking solvent-borne systems as REACH N-methyl-2-pyrrolidone restrictions and EPA maximum achievable control technology standards harden compliance thresholds across automotive and footwear supply chains.
Growth Catalysts
- REACH Phase-Out Mandates:European ECHA restrictions on N-methyl-2-pyrrolidone are compelling coating agent suppliers to accelerate low-VOC polyurethane dispersion development for synthetic leather substrates.
- Automotive Interior Specification Shifts:OEM seating programs in Germany, the United States, and Japan are substituting animal hides with performance-engineered synthetics requiring advanced abrasion-resistant coating systems.
- China Domestic Manufacturing Scale:Dongguan and Wenzhou synthetic leather production clusters are absorbing rising volumes of water-based polyurethane coatings for export-compliant footwear and upholstery.
Market Restraints
- Isocyanate Feedstock Concentration:Captive production of aliphatic isocyanates concentrates among three Asian chemical groups, creating supply vulnerability for European and North American formulators.
- Durability Specification Gaps:Water-based polyurethane coatings still fail to match solvent-borne systems on chemical resistance and heat-aging performance in premium automotive interior applications.
- Capital Intensity of Emission Controls:Retrofitting solvent-based coating lines with thermal oxidizers and carbon recovery systems demands substantial fixed investment from mid-scale synthetic leather producers.
Strategic Opportunities
- Silicone Emulsion Convergence:Hybrid silicone-polyurethane coating systems are opening premium upholstery segments where breathability and ultra-soft hand-feel command specification premiums.
- Indonesia Footwear Cluster Expansion:Relocating athletic shoe manufacturing from China to Java and Sumatra is creating demand for localized coating agent technical service and just-in-time supply.
- EPA Green Chemistry Incentives:Safer Choice program recognition and state-level VOC credit trading systems are rewarding early movers in water-based formulation commercialization.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in water-based polyurethane dispersion stability and substrate adhesion is concentrated among retiring specialists in European coating agent houses.
- Multi-Jurisdiction Certification Burden:Simultaneous compliance with REACH, EPA 40 CFR Part 63, and China's GB standards requires parallel testing protocols that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coating Agents for Synthetic Leather Market |
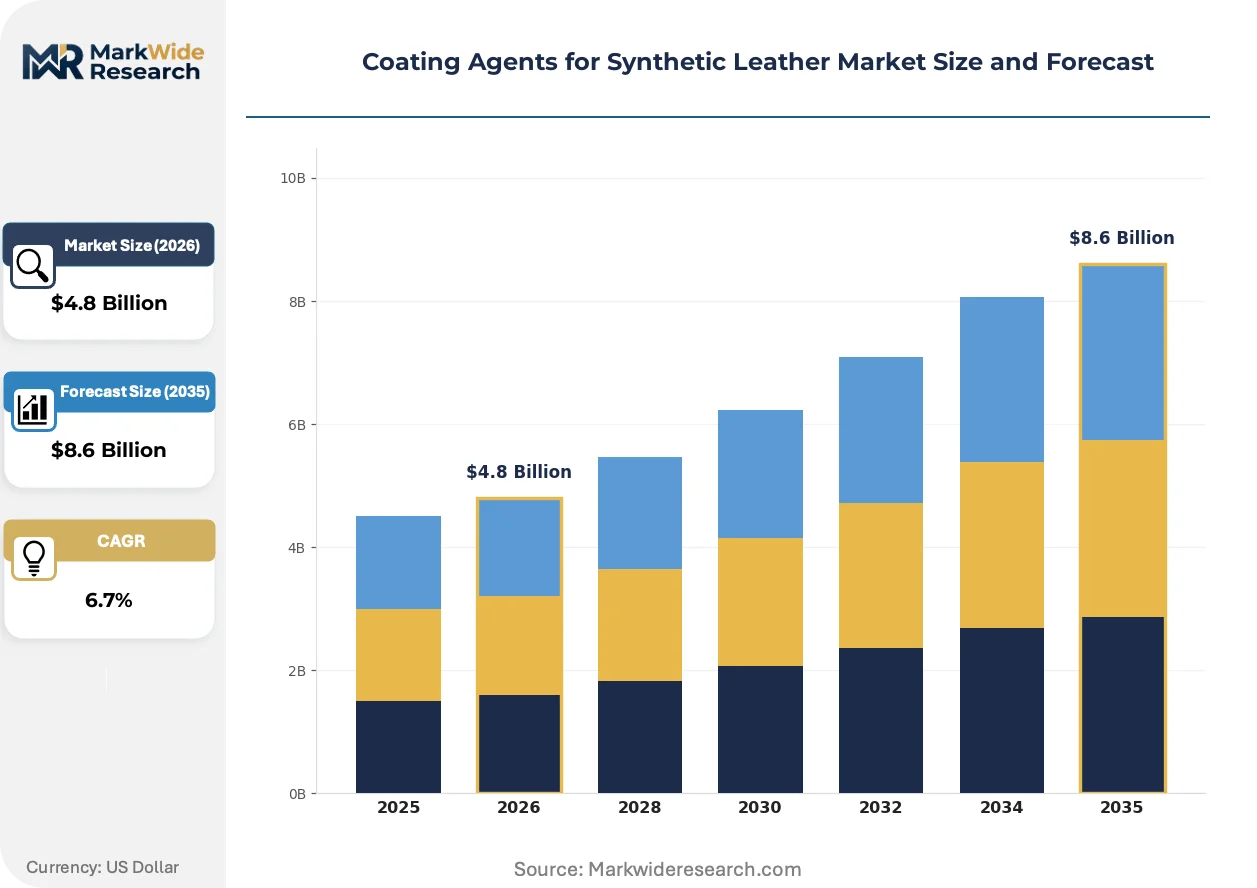
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
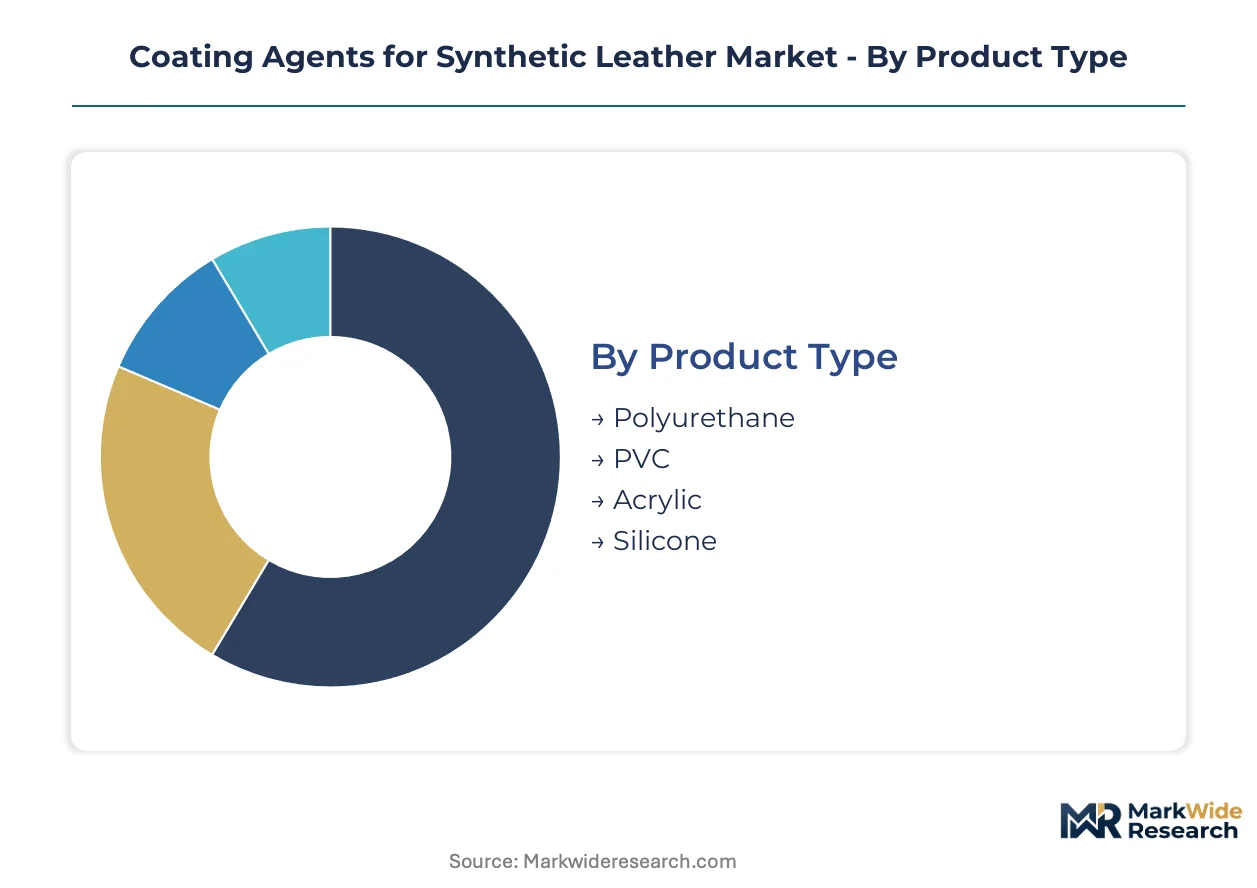
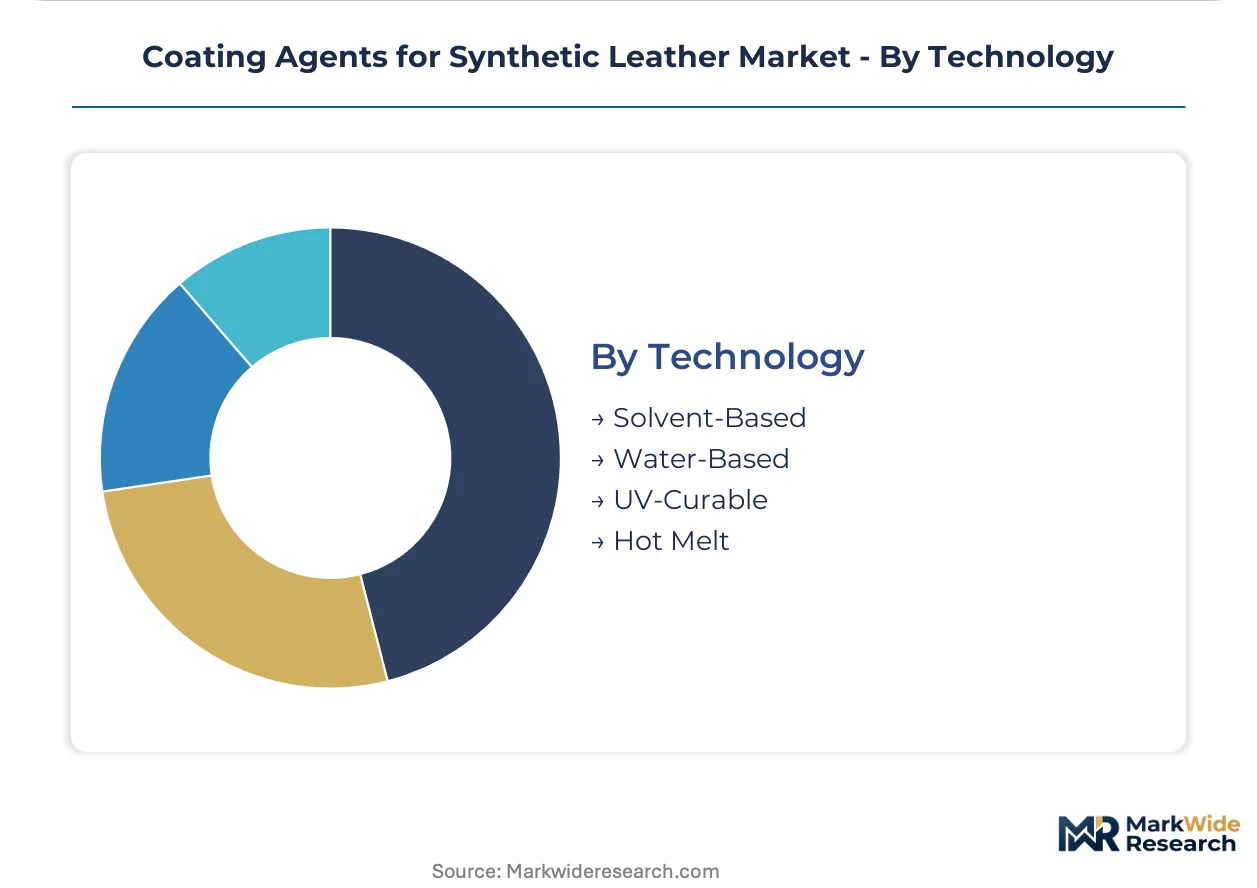
| Segmentation | Product Type: Polyurethane, PVC, Acrylic, Silicone Application: Footwear, Upholstery, Automotive Interiors, Fashion Accessories End User: Manufacturers, Distributors, Retailers, Wholesalers Technology: Solvent-Based, Water-Based, UV-Curable, Hot Melt |
| Companies Covered | LANXESS AG, Huntsman Corporation, Covestro AG, Arkema S.A., Wacker Chemie AG, BASF SE, Stahl Holdings B.V., Dow Inc., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coating Agents for Synthetic Leather Market Emerging Trajectories
Formulation chemistry, regulatory compliance architecture, and procurement operating models are undergoing simultaneous recalibration as the industry transitions from solvent-dominant to water-based systems.
Water-based polyurethane dispersions are overtaking solvent-borne coatings in footwear and upholstery applications. German and Italian synthetic leather mills are adopting these systems at pace to maintain OEM supply qualifications. This shift is compressing demand for aromatic solvent carriers while expanding technical service requirements around substrate wetting and drying optimization.
EPA maximum achievable control technology standards for synthetic leather coating operations are tightening volatile organic compound emission limits in the United States. Coating agent suppliers are reformulating product platforms to maintain surface-active performance at reduced solvent loadings. Automotive seating specifications in Michigan and Ohio manufacturing corridors are driving accelerated validation of compliant systems.
Multi-source procurement contracts are displacing single-supplier agreements among tier-one synthetic leather producers. Footwear brand technical teams in Vietnam and Indonesia are qualifying secondary coating agent vendors to reduce concentration risk. This pattern is most visible in athletic shoe supply chains where order volatility and qualification speed determine contract awards.
Coating Agents for Synthetic Leather Market Segmentation
Segmentation in coating agents for synthetic leather reveals how formulation chemistry, application requirements, and regulatory compliance intersect to shape procurement decisions. Each dimension carries distinct certification burdens that determine supplier qualification timelines and technical service intensity.
Product Type:
REACH registration requirements, EPA 40 CFR compliance, and China's GB standards each map differently onto polymer chemistries, creating segmented approval pathways for formulators.
- Polyurethane:Aliphatic and aromatic isocyanate-based dispersions dominate current volumes through superior abrasion resistance and breathability in footwear substrates. Water-based polyurethane variants are capturing specification share fastest as ECHA N-methyl-2-pyrrolidone restrictions and EPA maximum achievable control technology standards harden across German and US automotive supply chains.
- PVC:Plastisol formulations retain cost advantage in mass-market upholstery through phthalate plasticizer flexibility, though REACH Substances of Very High Concern listings and state-level US restrictions on plasticizer migration are compressing addressable market scope.
- Acrylic:Emulsion systems serve price-sensitive fashion accessories where UV stability and color fastness specifications are moderate.
- Silicone:Hybrid silicone-polyurethane coatings command premium positioning in luxury upholstery segments where ultra-soft hand-feel and thermal aging performance justify formulation cost premiums.
Leading the category by volume: Polyurethane. Growing fastest: Silicone.
Application:
End-use specifications diverge sharply on durability testing protocols, with automotive OEMs imposing the most stringent multi-jurisdiction certification requirements.
- Footwear:Dongguan and Wenzhou manufacturing clusters absorb the largest coating agent volumes for athletic and casual shoe uppers. Water-based polyurethane systems are displacing solvent-borne alternatives as export compliance to REACH and EPA standards becomes mandatory for tier-one brand supply qualifications.
- Automotive Interiors:Seating programs at German, US, and Japanese OEMs specify aromatic polyurethane coatings for extreme abrasion and chemical resistance, though water-based validation programs are accelerating under corporate sustainability mandates.
- Upholstery:Residential and contract furniture applications balance cost against flame retardancy and stain resistance specifications.
- Fashion Accessories:Handbags, belts, and small leather goods prioritize aesthetic surface finish and color matching precision over mechanical durability.
Highest certification burden: Automotive Interiors. Fastest technology transition: Footwear.
End User:
Procurement sophistication varies with scale, determining whether buyers qualify formulations directly or delegate technical validation to coating line operators.
- Manufacturers:Synthetic leather mills in China, Vietnam, and Indonesia conduct direct formulation qualification with coating agent suppliers, maintaining in-house laboratories for substrate adhesion and aging performance validation.
- Distributors:Regional chemical distributors in Southeast Asia provide localized inventory and technical service for mid-scale producers lacking direct supplier relationships.
- Retailers:Vertical footwear brands with captive manufacturing qualify coating agents through central technical teams.
- Wholesalers:Trading companies serving fragmented upholstery fabricators aggregate demand but exert limited formulation influence.
Dominant procurement channel: Manufacturers. Fastest-growing intermediary role: Distributors.
Technology:
Capital investment requirements and emission control infrastructure divide the technology landscape between incumbent solvent systems and emerging low-VOC alternatives.
- Solvent-Based:Aromatic solvent carriers retain automotive interior share where chemical resistance and heat-aging specifications exceed current water-based performance, though thermal oxidizer retrofit costs are accelerating line conversions.
- Water-Based:Polyurethane dispersions are overtaking solvent systems in footwear and upholstery as REACH N-methyl-2-pyrrolidone phase-outs and EPA standards redirect formulation investments.
- UV-Curable:Acrylate oligomer systems serve niche applications requiring instant cure and low heat exposure for temperature-sensitive substrates.
- Hot Melt:Reactive polyurethane hot melts address specific automotive lamination applications where solvent elimination and processing speed converge.
Volume leader: Solvent-Based. Steepest expansion trajectory: Water-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aliphatic isocyanate production concentrates in China, Germany, and the United States, anchoring regional formulation capabilities around these feedstock nodes. Each geography shapes coating agent specifications through distinct regulatory architectures and end-use manufacturing clusters.
China
Dongguan and Wenzhou synthetic leather manufacturing belts absorb the largest water-based polyurethane coating volumes for export-compliant footwear. GB standards on hazardous substance limits in synthetic leather products are reshaping formulation requirements for suppliers serving domestic mills. Domestic isocyanate producers in Ningbo and Shanghai are expanding captive supply to reduce import dependence for polyurethane dispersion manufacturers.
Germany
Automotive seating programs at OEMs in Bavaria and Baden-Württemberg specify high-durability aromatic polyurethane coatings for synthetic leather interiors. ECHA restrictions on N-methyl-2-pyrrolidone are accelerating low-VOC polyurethane dispersion adoption among coating agent formulators. The Cologne-Düsseldorf chemical corridor hosts specialized technical service laboratories supporting mill qualification programs.
United States
EPA maximum achievable control technology standards are tightening VOC emission limits for coating operations in Michigan and Ohio automotive manufacturing corridors. Water-based polyurethane validation programs are accelerating under corporate sustainability mandates from Detroit-area OEMs. State-level VOC credit trading systems in California are rewarding early movers in low-emission formulation commercialization.
Vietnam
Relocating athletic shoe manufacturing from China to Ho Chi Minh City and Binh Duong provinces is creating demand for localized coating agent technical service. Regional chemical distributors are expanding inventory positions to serve mid-scale synthetic leather producers lacking direct supplier relationships. Footwear brand technical teams are qualifying secondary coating agent vendors to reduce supply concentration risk.
Japan
OEM seating specifications from Tokyo and Nagoya manufacturers emphasize extreme abrasion resistance for premium synthetic leather applications. METI industrial standards on chemical substance management are influencing formulation choices for suppliers serving domestic automotive supply chains. Osaka-based synthetic leather mills maintain in-house laboratories for substrate adhesion and aging performance validation.
Coating Agents for Synthetic Leather Market Vendor Landscape
Global majors compete with regional champions across formulation chemistry and technical service intensity. The vendor base separates into three tiers: integrated chemical conglomerates with captive isocyanate supply, specialized coating agent houses with water-based polyurethane leadership, and regional distributors providing localized inventory and mill support. Dominant competitive moves include strategic partnerships with synthetic leather mills for co-development programs and geographic expansion through technical service center establishment.
Among European integrated chemical producers, LANXESS AG and Covestro AG exemplify the conglomerate archetype with upstream control over critical feedstocks. Covestro occupies a position anchored by captive isocyanate production and direct mill relationships across Asia. Stahl Holdings B.V. represents the specialized coating agent house model, sitting within a tier defined by water-based polyurethane leadership and automotive finishing system expertise. These three companies illustrate how competitive positioning separates around supply chain integration depth versus formulation specialization intensity.
| Leading Market Players |
|---|
| LANXESS AG |
| Huntsman Corporation |
| Covestro AG |
| Arkema S.A. |
| Wacker Chemie AG |
| BASF SE |
| Stahl Holdings B.V. |
| Dow Inc. |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
Multi-source procurement mandates from tier-one synthetic leather producers are forcing coating agent suppliers to unbundle technical service from base chemical pricing, compressing margins on commodity polyurethane dispersions while creating premium capture opportunities for formulation houses with mill-embedded support capabilities.
Pricing Analysis
Technical service bundling separates premium coating agent vendors from commodity suppliers in this market. Three-tier pricing structure across certified-automotive, export-compliant footwear, and domestic upholstery tiers reflects REACH and EPA compliance investment differentials. Price differentiation hinges on formulation certification level and volume scale, with automotive-qualified aromatic polyurethanes commanding substantial premiums over standard footwear grades. Cost compression in mid-tier water-based systems is intensifying as Chinese domestic producers expand capacity. Export-facing footwear manufacturers in Vietnam demonstrate highest price sensitivity, while German automotive OEM seating programs show lowest sensitivity due to specification rigidity.
Supply Chain Analysis
Dual-sourcing requirements from synthetic leather mills in Vietnam and Indonesia are fragmenting procurement contracts across multiple coating agent suppliers to reduce concentration risk. Aliphatic isocyanate production concentrates in China, Germany, and the United States, anchoring regional formulation capabilities around these feedstock nodes. Supply chains draw from aromatic isocyanates, polyester polyols, and silicone intermediates as critical inputs. Single-source vulnerability in specialty aliphatic isocyanates creates structural exposure for European formulators dependent on Asian chemical groups. Distribution runs through direct mill relationships for tier-one producers and regional chemical distributors for mid-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH N-methyl-2-pyrrolidone phase-out mandates have erected a cost-of-compliance barrier that favors incumbent formulators with validated low-VOC platforms, entrenching market position for European coating agent houses with ECHA-registered polyurethane dispersions.
For Market Incumbents: Anticipate margin compression in standard water-based footwear grades as Chinese domestic suppliers achieve export certification parity. Prioritize backward integration into captive aliphatic isocyanate supply to defend feedstock security against Asian chemical group consolidation. Accelerate automotive validation programs for next-generation hybrid silicone-polyurethane systems before durability specification gaps close. For New Entrants and Emerging Players: EPA maximum achievable control technology standards in the United States open a window for specialized water-based formulation houses with Michigan and Ohio technical service presence. Target mid-scale synthetic leather producers in Indonesia's expanding footwear clusters where incumbent technical service density remains thin. Lead with just-in-time inventory partnerships and substrate-specific drying optimization support rather than commodity chemical supply. For Investors and Strategic Acquirers: The window for entry favors specialized coating agent houses with water-based polyurethane leadership and automotive OEM qualification track records. Long-term viability rests on formulation chemistry expertise concentration among retiring European specialists, creating acquisition value for technical talent retention. Watch for inflection in water-based polyurethane heat-aging performance validation at premium German automotive seating programs as the signal for technology substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Feedstock | Captive aliphatic isocyanate production at Covestro and LANXESS eliminates supply vulnerability for European formulators serving REACH-compliant markets. |
| Water-Based Formulation Platform Expansion | Stahl Holdings' polyurethane dispersion leadership captures specification share as ECHA restrictions harden compliance thresholds across automotive supply chains. |
| Technical Service Center Establishment | Localized mill support in Vietnam's Binh Duong province addresses footwear brand multi-sourcing requirements with just-in-time supply capability. |
| Hybrid Silicone-Polyurethane Development | Silicone emulsion convergence opens premium upholstery segments where breathability specifications justify formulation cost premiums over standard polyurethanes. |
| Automotive OEM Co-Development Programs | Direct seating program partnerships with Bavarian and Baden-Württemberg manufacturers lock in multi-year supply contracts through embedded formulation validation. |
Methodological Framework
Document review covered customs trade databases, ECHA registration filings, and SEC chemical segment disclosures, complemented by interviews with synthetic leather mill technical directors, coating agent formulation chemists, automotive OEM seating procurement managers, and Southeast Asian chemical distributors. Primary fieldwork engaged plant managers at Dongguan and Wenzhou manufacturing clusters alongside regulatory affairs leads at European coating agent houses. Secondary validation drew from EPA maximum achievable control technology standards documentation, China's GB hazardous substance limit protocols, and industry association reports. Bottom-up volume estimates from individual mill consumption patterns were triangulated against top-down chemical feedstock demand allocations.
Segment-level value outputs were constructed across formulation chemistry, end-use application, and technology type dimensions throughout the forecast period. The analytical framework modeled polyurethane, PVC, acrylic, and silicone product categories against footwear, automotive interior, upholstery, and fashion accessory applications. CAGRs were derived from regression analysis of historical coating agent consumption against synthetic leather production volumes, adjusted for regulatory-driven technology substitution rates. Water-based penetration assumptions and automotive specification shift timelines served as primary forecast sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for water-based polyurethane heat-aging performance breakthrough would accelerate solvent-borne displacement beyond baseline projections. Forecasts reflect assumptions about REACH enforcement consistency, EPA standard implementation timelines, and Chinese domestic isocyanate capacity expansion. Deviation in automotive OEM sustainability mandate acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Passive Fire Protection Coatings Market
Coatings
FBE Coatings Market
Coatings
Dispersion Coating Market
Coatings
Bio-Fouling Prevention Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Electron Beam Curable Coating Market
Coatings
Global Wood Protection Coating Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Vinyl Surface Coatings Market
Coatings
Hydrophilic Interior Glass Defogging Coatings Market
Coatings
Brazil Automotive OEM Coatings Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
Emulsion Coatings Market
Coatings
Coating Market
Coatings
Anti Fog Coatings Market
Coatings
Global Anti Slip Coatings Market