
 Italy Protective Coatings Market | 2026-2036
Italy Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Protective Coatings Market Foresight
The EU Green Deal is decoupling solvent-based formulations from premium project specifications across Italian public procurement. AkzoNobel NV leverages its marine R&D center in Ravenna to anchor high-performance epoxy supply for Adriatic shipyards. PPG Industries Inc competes through specialized automotive refinish channels that dominate Turin's OEM supplier ecosystem.
Italy protective coatings comprise resin-bound films engineered to resist corrosion, chemical attack, and mechanical wear on substrates such as steel, concrete, and aluminum, with typical dry-film thickness ranging from 100 to 500 micrometers depending on exposure severity. Epoxy formulations lead industrial maintenance cycles due to their adhesion strength and chemical resistance, while water-based systems represent the fastest-growing formulation category as VOC thresholds tighten across EU member enforcement. Marine applications concentrate margin pools around Genoa, La Spezia, and Venice-Porto Marghera, where salt-laden environments demand cyclic re-coating protocols.
REACH, the EU F-Gas Regulation, and Italy's transposed Legislative Decree on industrial emissions collectively mandate hazardous substance phase-outs and volatile organic compound ceilings that reshape product registration costs. ECHA's substance evaluation pace determines reformulation timelines for suppliers serving ENI refineries and Trenitalia infrastructure networks. Stakeholders must monitor how the EU AI Act's quality infrastructure requirements will alter coating inspection and certification workflows across Italian fabrication yards.
Market Dynamics
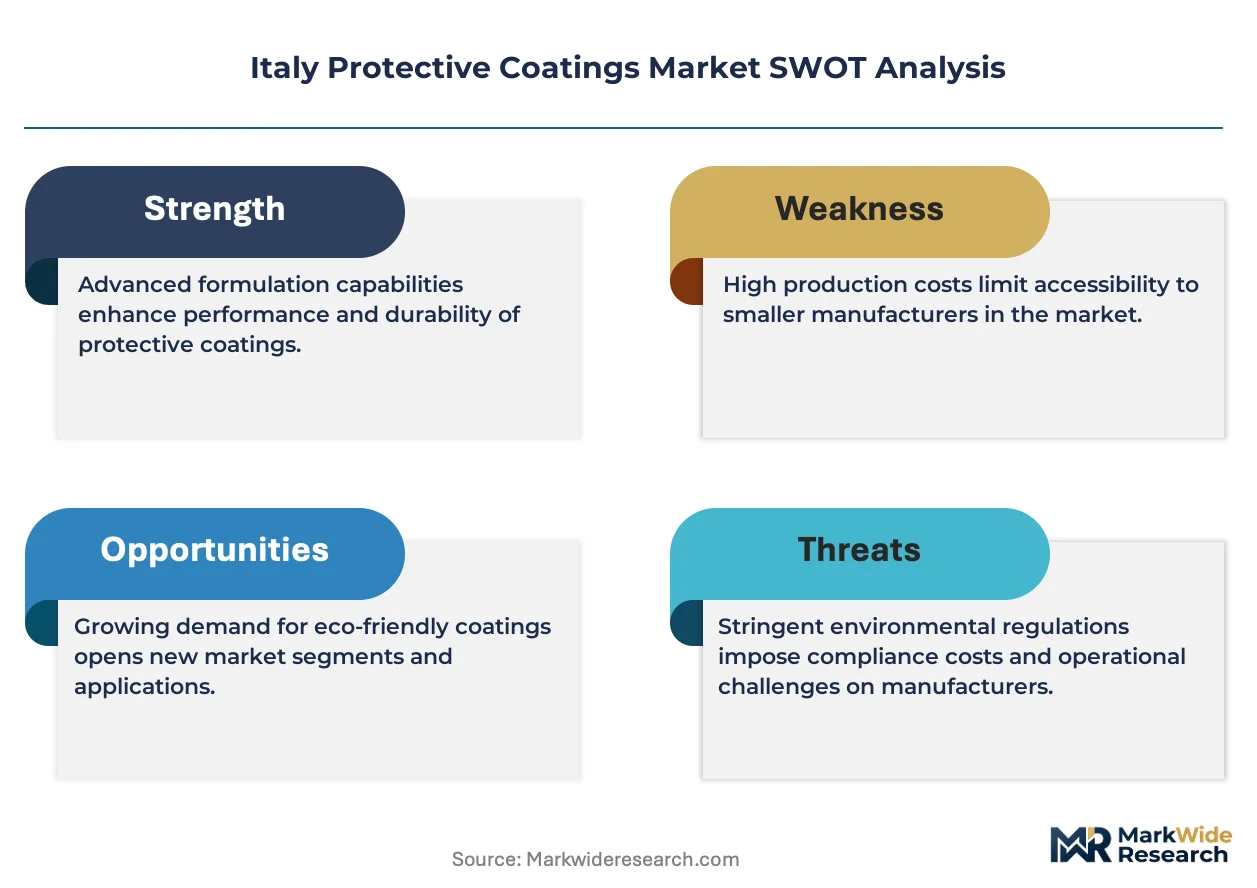
REACH substance evaluation timelines and the EU Green Deal's decarbonization mandates are forcing simultaneous reformulation of solvent-based product lines and accelerated water-based system registration across Italian coating manufacturers.
Growth Catalysts
- Epoxy demand surge:Infrastructure rehabilitation across Northern Italy's industrial corridors is expanding high-performance coating uptake for steel protection in heavy manufacturing facilities.
- Water-based transition:EU VOC ceilings are pulling investment into low-emission formulation capacity at production sites serving Lombardy's manufacturing belt.
- Marine maintenance cycles:Salt-laden Adriatic and Ligurian environments demand cyclic re-coating protocols at Genoa, La Spezia, and Venice-Porto Marghera.
Market Restraints
- Raw material volatility:Epoxy resin and isocyanate feedstock costs fluctuate with petrochemical pricing, compressing margin stability for domestic formulators.
- Registration cost inflation:ECHA substance evaluation fees and extended toxicity testing timelines extend product launch cycles for mid-tier suppliers.
- Technical performance gaps:Water-based systems still lag solvent-based alternatives in humidity-cure speed and film-build capacity for severe marine exposures.
Strategic Opportunities
- Southern industrial expansion:Underpenetrated maintenance markets in Sicily and Calabria's process industries offer first-mover positioning for corrosion protection specialists.
- EU AI Act integration:Automated coating inspection and certification workflows create demand for digital-physical system bundling in Italian fabrication yards.
- Green public procurement:Environmental product declaration mandates in state infrastructure tenders favor suppliers with verified lifecycle data.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in hybrid water-epoxy systems remains concentrated among aging technical workforces at established suppliers.
- Certification timeline compression:EN 1504 concrete protection and NORSOK marine standard approvals require 18-24 month validation cycles that outpace project bidding windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Protective Coatings Market |
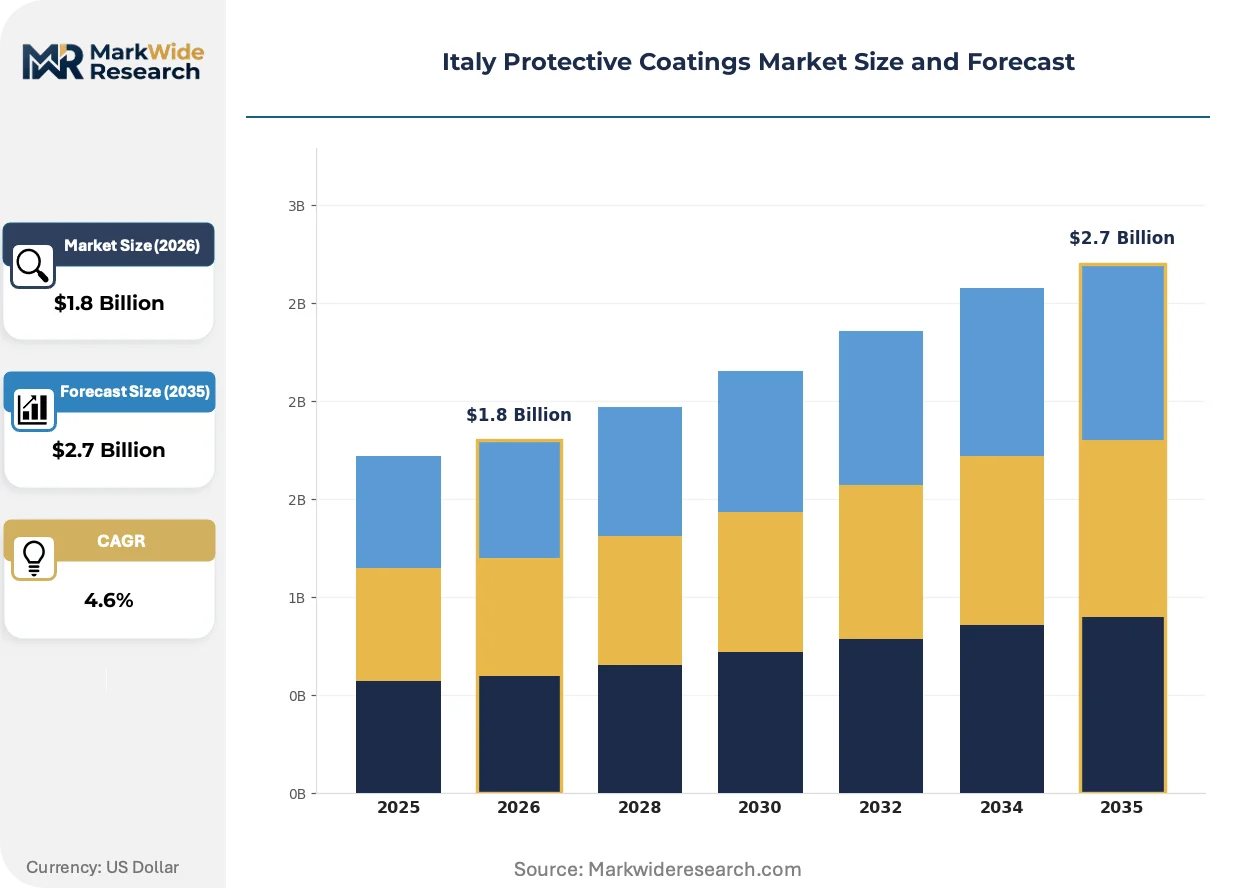
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Alkyd End User: Construction, Automotive, Aerospace, Marine Application: Industrial Coatings, Decorative Coatings, Marine Coatings, Protective Coatings Formulation Type: Water-Based, Solvent-Based, Powder Coatings, UV-Cured |
| Companies Covered | The Sherwin-Williams Company, Axalta Coating Systems, RPM International Inc, Beckers Group, Hempel A/S, AkzoNobel NV, Jotun, Aemme Colors, PPG Industries Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Protective Coatings Market Shifts & Advancements
Formulation chemistry, compliance automation, and procurement digitization are converging to reshape how protective coating specifications are written, validated, and fulfilled across Italian industrial end-uses.
Hybrid water-epoxy systems with improved low-temperature cure performance are rewriting project feasibility for winter maintenance windows at ENI refineries and Trenitalia infrastructure networks. These formulations now achieve 150-micron dry film builds at 5°C ambient conditions. Contractors in the Po Valley industrial corridor are adopting them for compressed outage schedules previously requiring solvent-based alternatives.
The EU F-Gas Regulation and transposed Italian Legislative Decree on industrial emissions are tightening volatile organic compound ceilings for coating application in enclosed fabrication environments. Shipyards at Trieste and Monfalcone must now deploy vapor recovery systems or switch to compliant formulations. This is accelerating capital allocation toward water-based and high-solids product development among suppliers serving Adriatic marine clusters.
Asset owners at ANAS road infrastructure and RFI rail networks are unbundling coating specification from application contractor selection, creating direct procurement relationships with certified material suppliers. Digital tender platforms now require pre-loaded technical data sheets and third-party test reports before bid submission. This pattern concentrates specification influence among formulators with established laboratory partnerships in Milan and Bologna testing facilities.
Italy Protective Coatings Market Segmentation
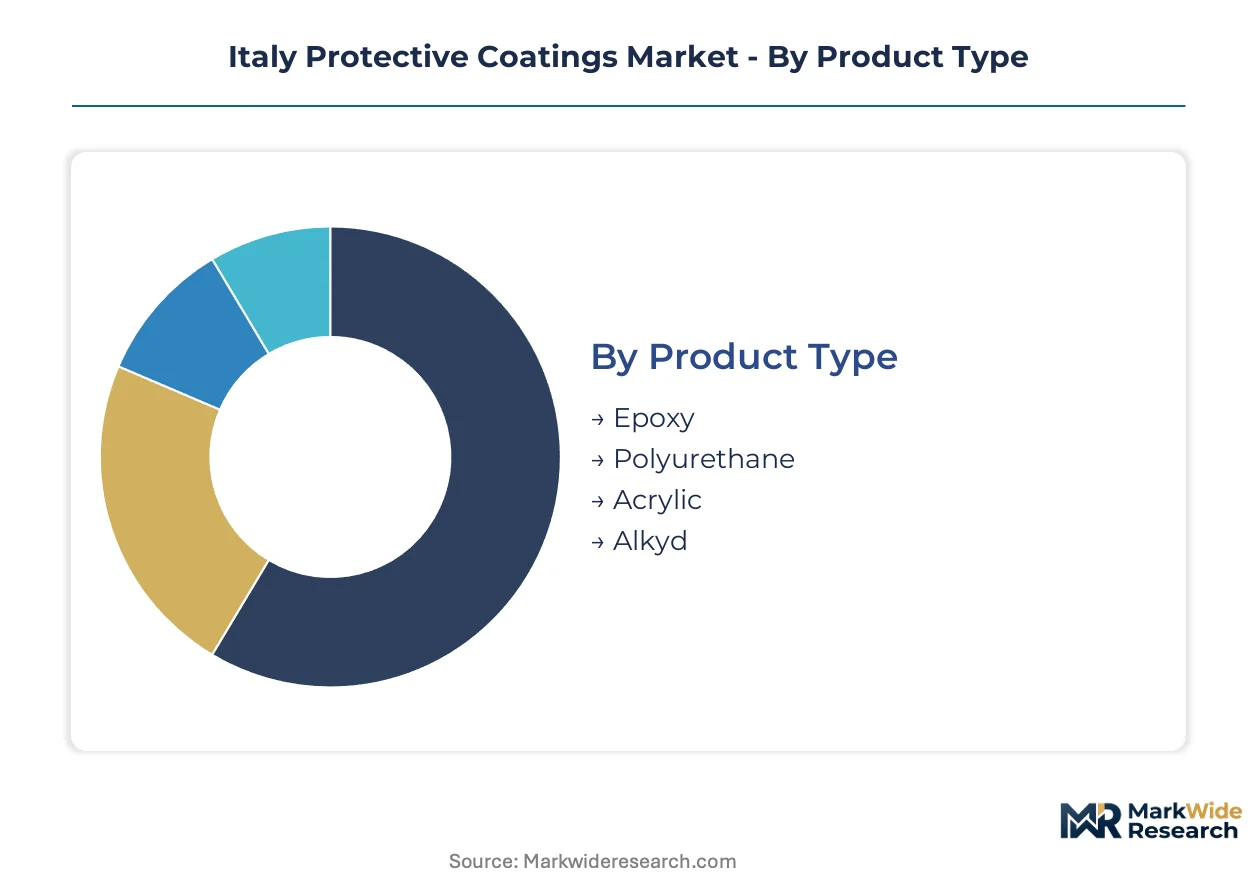
Protective coating specifications in Italy diverge sharply across substrate requirements, environmental exposure severity, and regulatory compliance tiers. Understanding these segment boundaries clarifies where formulation investments concentrate and where margin pools shift under tightening EU VOC mandates.
Product Type:
Buyers differentiate primarily by chemical resistance needs and cure conditions rather than price sensitivity alone.
- Epoxy:Two-part thermosetting systems deliver superior adhesion to steel and concrete substrates with excellent chemical resistance. Demand concentrates at ENI refineries in Ravenna and Taranto, where maintenance cycles require 250-500 micron film builds for immersion service. REACH substance evaluation timelines are forcing bisphenol-A-based variants toward alternative curing agents.
- Polyurethane:Aliphatic and aromatic formulations provide UV stability and abrasion resistance for exterior exposure. Lombardy's manufacturing belt drives specification for machinery and structural steel, though humidity-cure sensitivity limits winter application windows in the Po Valley.
- Acrylic:Thermoplastic resins offer rapid dry-to-touch properties for decorative-protective hybrid applications. Water-borne acrylics gain traction in ANAS infrastructure tenders requiring low-VOC compliance.
- Alkyd:Oil-modified polyester systems retain cost advantage for light-duty atmospheric protection. Traditional solvent-borne alkyds face phasedown pressure under EU F-Gas Regulation transposition into Italian industrial emissions law.
Volume sits with epoxy formulations; growth tilts toward polyurethane systems as infrastructure asset life extension demands intensify.
End User:
Procurement scale and specification authority separate large asset owners from fragmented contractor channels.
- Construction:Concrete protection dominates specification for bridges, tunnels, and water treatment infrastructure. EN 1504 compliance mandates drive coating selection for RFI rail network rehabilitation projects across the Apennine corridor.
- Automotive:OEM refinish and component finishing require color-matched durability under cyclic corrosion testing. Turin's supplier ecosystem maintains specialized demand for high-solids polyurethane clearcoats.
- Aerospace:Chromate-free pretreatment and topcoat systems serve Leonardo's helicopter and aerostructures facilities. NADCAP certification barriers concentrate supply among qualified formulators with Milan-area laboratory partnerships.
- Marine:Cyclic re-coating protocols at Genoa, La Spezia, and Venice-Porto Marghera anchor demand for anti-corrosive and antifouling systems. Salt-laden Adriatic environments accelerate coating degradation versus Mediterranean averages.
Construction commands procurement volume; marine applications deliver the steepest expansion trajectory as Adriatic shipyard activity intensifies.
Application:
Performance certification requirements and application environment constraints segment buyer priorities.
- Industrial Coatings:Heavy-duty protection for manufacturing equipment, storage tanks, and processing vessels. Northern Italy's chemical and steel production clusters specify epoxy-polyurethane systems for combined chemical and mechanical resistance.
- Decorative Coatings:Architectural finishes balancing aesthetic durability with environmental compliance. Public procurement mandates increasingly require Environmental Product Declarations for state-funded restoration projects.
- Marine Coatings:Immersion and atmospheric zone protection for hulls, decks, and superstructures. Shipyards at Trieste and Monfalcone face compressed application windows due to EU F-Gas Regulation vapor recovery requirements.
- Protective Coatings:Specialized formulations for extreme exposure including fire protection and chemical containment. ENI's petrochemical assets and Trenitalia's coastal infrastructure drive specification complexity.
Industrial applications absorb the largest coating volumes; marine coatings are climbing fastest as fleet renewal and environmental regulations tighten maintenance cycles.
Formulation Type:
Regulatory compliance trajectory and application equipment compatibility guide buyer migration paths.
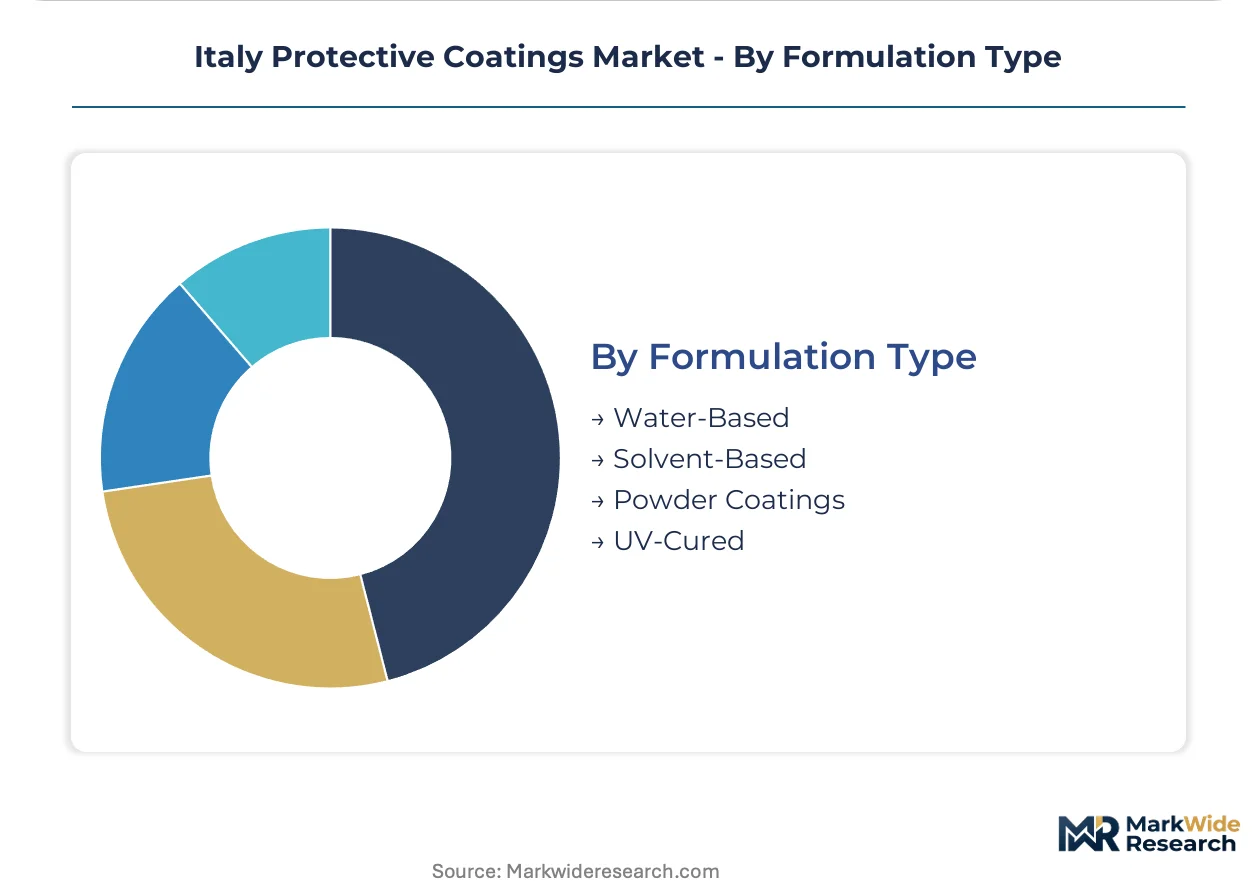
- Water-Based:Acrylic and epoxy dispersions with VOC content below EU solvent emission thresholds. Reformulation investment concentrates at production sites serving Lombardy's manufacturing belt, though humidity-cure speed gaps persist versus solvent alternatives.
- Solvent-Based:Traditional high-solids and conventional systems facing phasedown under REACH and EU Green Deal procurement mandates. Remaining demand concentrates in marine maintenance where film-build requirements exceed current water-based capabilities.
- Powder Coatings:Thermosetting epoxy and polyester powders for factory-applied metal finishing. Automotive component suppliers in Piedmont adopt powder for zero-VOC compliance with oven-cure compatibility.
- UV-Cured:Rapid-cure acrylic and epoxy systems for specialized industrial applications. Limited penetration in protective coatings due to substrate geometry constraints and capital equipment requirements.
Solvent-based formulations retain volume leadership; water-based systems gain share fastest as ECHA enforcement tightens and public procurement pivots toward verified lifecycle performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lombardy's fiscal incentive zones for industrial rehabilitation concentrate protective coating demand in Northern Italy's manufacturing belt. Special economic provisions for infrastructure renewal pull specification authority toward Milan-area formulators serving ENI and Trenitalia networks.
Lombardy
Steel protection cycles at Brescia's metalworking clusters and Bergamo's chemical processing facilities drive epoxy consumption for immersion service. REACH substance evaluation timelines force reformulation of bisphenol-A-based systems toward alternative curing agents. Milan's testing laboratories anchor certification workflows for EN 1504 concrete protection standards.
Piedmont
Automotive refinish demand from Turin's OEM supplier ecosystem sustains specialized polyurethane clearcoat specifications. EU F-Gas Regulation transposition pressures solvent-based lines toward high-solids alternatives. Alessandria's coating application shops face compressed vapor recovery compliance deadlines.
Veneto
Port of Venice-Porto Marghera's marine maintenance cluster generates cyclic anti-corrosive demand for salt-laden Adriatic exposure. EU Green Deal procurement mandates decouple solvent-based formulations from premium project specifications. Padua's industrial corridor adopts water-based acrylics for ANAS infrastructure tenders.
Liguria
Genoa's shipyard concentration anchors high-performance marine coating specification for hull and superstructure protection. Legislative Decree on industrial emissions mandates vapor recovery systems in enclosed fabrication environments. La Spezia's naval maintenance facilities accelerate re-coating protocols for fleet renewal cycles.
Emilia-Romagna
Food processing equipment protection at Parma's machinery manufacturers drives hygienic coating specifications for stainless steel substrates. ECHA enforcement tightens VOC thresholds across EU member state compliance. Bologna's research partnerships concentrate hybrid water-epoxy development for low-temperature cure performance.
Italy Protective Coatings Market Competitive Landscape
Benelux producers anchor one tier; Scandinavian specialists hold premium marine positions. Italian domestic formulators occupy mid-market corrosion protection. The vendor base splits between consolidated multinationals with Ravenna and Milan laboratory infrastructure and regional coating houses serving ANAS and RFI procurement channels. Three archetypes dominate: marine-certified specialists, automotive refinish integrators, and infrastructure maintenance generalists. Competitive moves concentrate on ECHA registration portfolio expansion and water-based formulation capacity allocation.
Among Netherlands-based multinationals, AkzoNobel NV occupies a position exemplifying marine R&D anchoring for Adriatic shipyard supply. PPG Industries Inc represents the automotive refinish archetype within Turin's OEM supplier ecosystem. Hempel A/S exemplifies Scandinavian marine specialization with proximity to Italian port maintenance clusters.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Axalta Coating Systems |
| RPM International Inc |
| Beckers Group |
| Hempel A/S |
| AkzoNobel NV |
| Jotun |
| Aemme Colors |
| PPG Industries Inc |
| Others |
Supply & Pricing Matrix
Captive resin production at integrated Benelux suppliers anchors both supply security and premium pricing power for marine-grade epoxy systems serving Adriatic shipyards. This backward integration shields formulators from petrochemical volatility while compressing margin room for mid-tier Italian competitors dependent on spot epoxy resin markets.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations at ENI refineries and Trenitalia maintenance networks, where compressed outage windows command surcharge pricing over standard inventory positions. Three-tier pricing structure across certified-premium, standard-industrial, and economy-alkyd levels separates specification authority by project criticality. Cost compression in economy alkyds is intensifying because REACH registration fees disproportionately burden low-margin product lines. Small contractor channels show highest price sensitivity, while ANAS infrastructure tenders prioritize lifecycle performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Dutch epoxy resin suppliers serving Northern Italy's manufacturing belt, where bisphenol-A alternative curing agents face extended ECHA evaluation timelines. Formulation chemistry draws from Belgian specialty additives, German isocyanate feedstocks, and domestic titanium dioxide from Veneto processing facilities. Tariff exposure on Chinese titanium dioxide pigment imports threatens margin stability for decorative coating producers. Distribution runs through Milan-area chemical distributors with direct-to-yard delivery contracts for marine maintenance clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized water-epoxy formulation capacity operates as the binding constraint propping pricing power for certified suppliers, with ECHA registration backlogs preventing rapid competitor entry.
For Market Incumbents: To counter technical workforce attrition in hybrid water-epoxy systems, anchor retention programs at Bologna and Milan laboratory partnerships while securing captive supply of low-temperature cure additives from German specialty chemical suppliers. Certification investment in EN 1504 concrete protection standards reinforces specification control at RFI and ANAS procurement channels. For New Entrants and Emerging Players: Regional coating applicators in Sicily and Calabria's process industries represent the most penetrable white-space target, where corrosion protection demand outpaces established supplier presence. Direct procurement relationships with mid-sized chemical processors bypass incumbent distributor control. A technical-service-led go-to-market angle emphasizing rapid humidity-cure validation addresses the performance gap slowing water-based adoption. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap formulators with established ECHA registration portfolios and Ravenna-area marine certification infrastructure. Long-term viability across the analysis window hinges on water-based capacity allocation outpacing solvent-based stranded asset risk. Monitor ECHA substance evaluation pace as the critical inflection signal for reformulation cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Supply | Captive resin production at integrated suppliers shields margin from petrochemical volatility at ENI refinery service accounts. |
| Water-Based Formulation Capacity Expansion | Low-VOC capacity allocation at Lombardy production sites captures EU Green Deal procurement preference at ANAS tenders. |
| EN 1504 Certification Investment | Concrete protection standard validation opens direct specification relationships with RFI rail network rehabilitation projects. |
| Marine Laboratory Partnership in Ravenna | Adriatic shipyard proximity accelerates anti-corrosive system validation cycles for Genoa and La Spezia maintenance clusters. |
| Hybrid Water-Epoxy R&D Collaboration | Bologna university partnerships advance low-temperature cure performance for compressed Trenitalia outage schedules. |
Research Methodology
Independent corroboration across formulation chemists at Italian coating manufacturers, procurement managers at ENI and Trenitalia, and technical directors at Milan-area testing laboratories underwrites the qualitative findings. Secondary validation drew from ECHA substance registration databases, EU F-Gas Regulation implementation reports, and ANAS tender documentation. Bottom-up demand modeling triangulated against top-down petrochemical feedstock consumption patterns.
Rate-of-change decomposition across resin type, end-use industry, formulation technology, and regional production hub segmentation dimensions structured the analytical framework. CAGRs derived from installed base corrosion protection cycle analysis and infrastructure rehabilitation pipeline assessment. Forecast inputs incorporated REACH substance evaluation timeline probabilities and EU Green Deal procurement mandate adoption curves.
Caveats apply where ECHA enforcement acceleration or raw material supply disruption could materially shift the outlook. Forecasts reflect assumptions about regulatory compliance cost trajectories and water-based performance gap closure rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Anti Slip Coatings Market
Coatings
Asia-Pacific Thermal Spray Market
Coatings
Anti Fog Coatings Market
Coatings
Wood Preservative Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Coating Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Electrical Insulation Coatings Market
Coatings
Dispersion Coating Market
Coatings
Coating Auxiliaries Market
Coatings
2K Coatings Market
Coatings
Protective Coatings Market
Coatings
Ultraviolet (UV) Coatings Market
Coatings
US Concrete Floor Coatings Market
Coatings
Brazil Automotive OEM Coatings Market
Coatings
Stealth Coating Material Market