
 Europe Silicone Rubber Market | 2026-2036
Europe Silicone Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Silicone Rubber Market Foresight
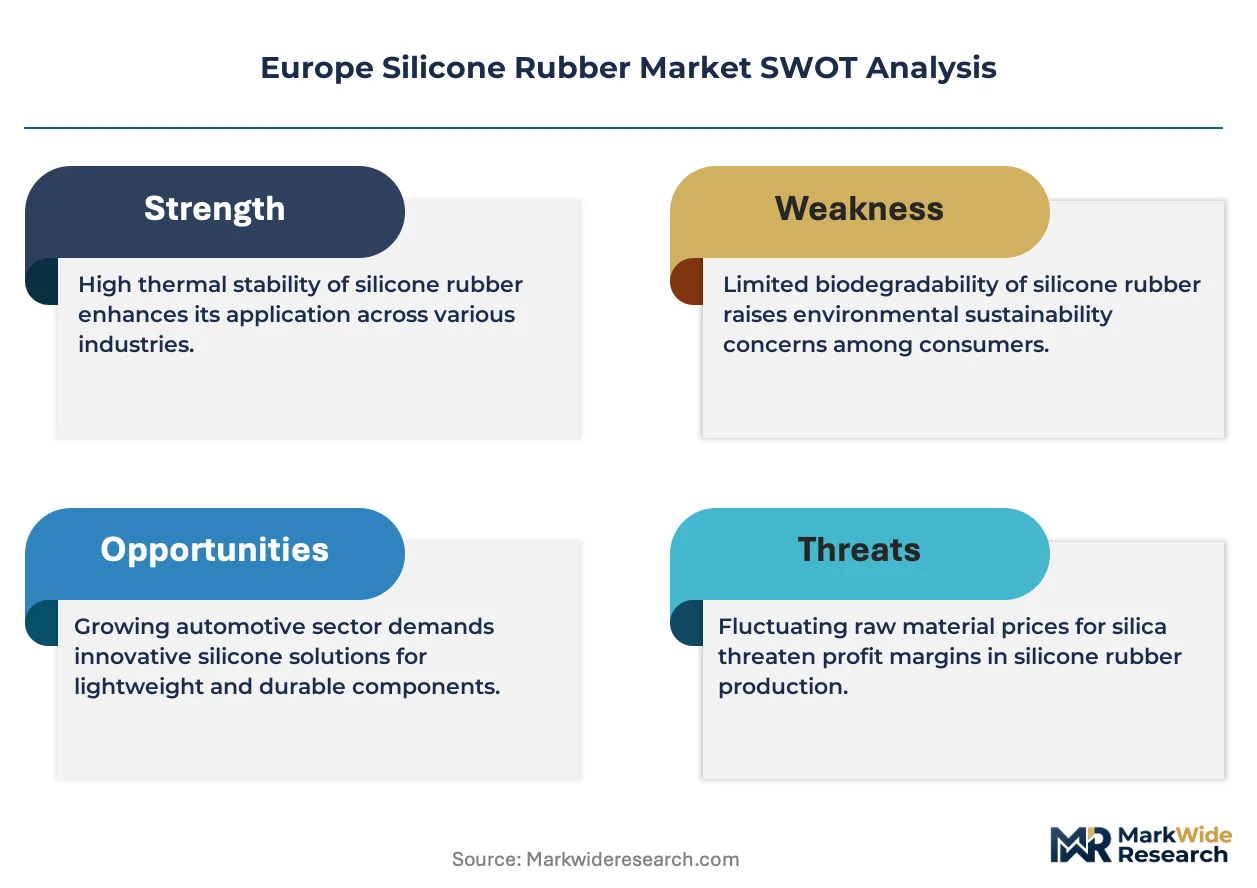
REACH compliance is realigning the cost-of-entry calculus for silicone rubber compounders serving European industrial buyers. Wacker Chemie AG leverages its Bavarian manufacturing complex to sustain captive siloxane supply chains that insulate formulation costs from import volatility. Elkem Silicones anchors its competitive position through integrated quartz-to-silicone operations in France, while Momentive Performance Materials differentiates via high-consistency rubber grades certified for medical device applications under MDR.
Silicone rubber comprises polydimethylsiloxane polymers cross-linked through platinum-catalyzed addition or peroxide-initiated radical curing, yielding elastomers that maintain elasticity from minus sixty degrees Celsius to over two hundred degrees Celsius. Liquid silicone dominates medical and automotive injection molding due to its low viscosity and rapid cure cycles, while solid silicone retains leadership in extruded profiles and compression-molded seals where green strength matters. Gel silicone captures expanding share in wearable electronics and wound-care interfaces where Shore A hardness below ten is required, whereas foam silicone occupies niche thermal and acoustic insulation roles in EV battery pack architectures.
EMA medical device regulations and ECHA substance restrictions under REACH jointly determine which silicone formulations achieve market access across EU member states, with biocompatibility testing protocols adding twelve to eighteen months to qualification timelines for healthcare suppliers. The EU F-Gas Regulation indirectly shapes demand by accelerating fluorocarbon displacement in sealing applications, pushing equipment OEMs toward silicone alternatives. Stakeholders must monitor the interplay between delegated acts under the EU AI Act and automated manufacturing investments, as machine-vision inspection requirements for medical-grade silicone parts will soon reshape capital allocation decisions.
Market Dynamics
EU Green Deal industrial decarbonization mandates are compressing supplier qualification timelines while simultaneously elevating carbon-footprint thresholds, forcing compounders to reconfigure formulation chemistry and energy sourcing at unprecedented speed.
Growth Catalysts
- EV battery sealing demand:Electric vehicle manufacturers across Germany, France, and the Netherlands are specifying platinum-cured liquid silicone for thermal management gaskets, creating procurement pull through 2035.
- REACH substance authorization:ECHA restrictions on legacy plasticizers and phthalates are redirecting medical device OEMs toward biocompatible silicone alternatives certified under MDR.
- F-Gas displacement:The EU F-Gas Regulation's phasedown of hydrofluorocarbons in HVAC and refrigeration seals is accelerating silicone rubber substitution in compressor gaskets and valve seats.
Market Restraints
- Siloxane feedstock concentration:European siloxane production clusters in Bavaria and the Rhône Valley, exposing compounders to localized energy cost spikes and logistics bottlenecks.
- Platinum catalyst volatility:Hydrosilylation chemistry depends on platinum group metal pricing that fluctuates with South African mining output and automotive catalytic converter demand.
- Biocompatibility testing duration:EMA cytotoxicity and sensitization protocols add twelve to eighteen months to medical-grade silicone qualification, freezing supplier switching.
Strategic Opportunities
- Poland and Czech Republic manufacturing:Automotive Tier 1 suppliers are relocating injection molding capacity to Central Europe to serve Volkswagen Group and Stellantis assembly plants with reduced logistics radius.
- Silicone gel wearable interfaces:Ultra-soft gel formulations below Shore A 10 are penetrating continuous glucose monitor patches and sleep-tracking earbuds in Scandinavia and the Netherlands.
- CSRD supply chain disclosure:Corporate Sustainability Reporting Directive mandates are creating premium pricing tiers for silicone compounders with verified Scope 3 carbon accounting and renewable energy certificates.
Industry Challenges
- Platinum-cure process engineering talent:Compounders face acute shortages of technicians trained in hydrosilylation kinetics and cleanroom liquid injection molding operation.
- Legacy compression molding asset stranding:Solid silicone extrusion and compression equipment requires seven-figure replacement cycles to accommodate high-cavitation liquid silicone tooling.
- MDR technical documentation burden:Medical device regulation Annex I general safety and performance requirements demand extensive clinical evaluation reports that drain regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Silicone Rubber Market |
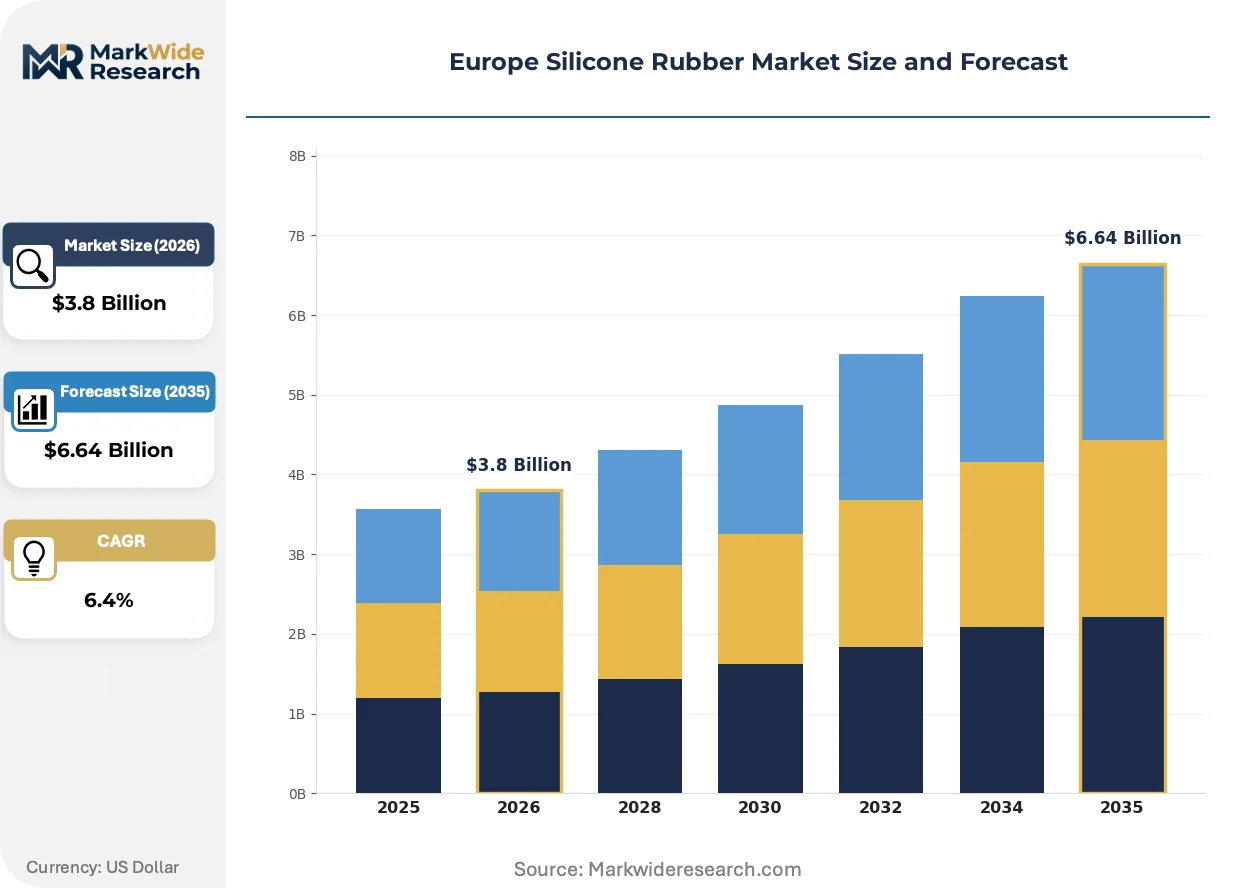
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Silicone, Solid Silicone, Gel Silicone, Foam Silicone End User: Automotive, Electronics, Healthcare, Construction Application: Seals, Gaskets, Adhesives, Coatings Form: Sheet, Tube, Block, Granule |
| Companies Covered | Wacker Chemie AG, Dow Inc., Elkem Silicones, Momentive Performance Materials, Evonik Industries AG, Shin-Etsu Chemical Co Ltd, KCC Corporation, MESGO S.p.A., Simtec Silicone Parts, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Silicone Rubber Market Shifts & Advancements
Material science convergence with digital manufacturing is collapsing traditional lead times while regulatory disclosure requirements are embedding carbon traceability into procurement specifications.
Self-healing silicone formulations incorporating dynamic covalent bond chemistry are entering prototype validation with automotive OEMs in Stuttgart and Munich. BMW Group and Mercedes-Benz AG are testing these materials for underhood gaskets subject to thermal cycling stress. This capability is integrating predictive maintenance data streams with material failure modes, enabling warranty cost reduction and service interval extension.
REACH Annex XIV authorization list expansions are systematically removing organotin catalysts from silicone curing processes, compelling reformulation toward platinum or peroxide systems. German compounders in the Munich-Stuttgart corridor are absorbing retooling costs fastest. Medical device extruders serving EMA-regulated markets are responding with dedicated production lines segregated from legacy tin-catalyzed operations.
Automotive OEMs are consolidating silicone rubber suppliers to single-source relationships for platform-level sealing systems, compressing vendor panels from six to two qualified compounders per vehicle program. Tier 1 integrators including Continental and Bosch are enforcing this consolidation. France and Germany exhibit the most aggressive supplier rationalization, with Spanish and Italian OEMs following eighteen to twenty-four months behind.
Europe Silicone Rubber Market Segmentation
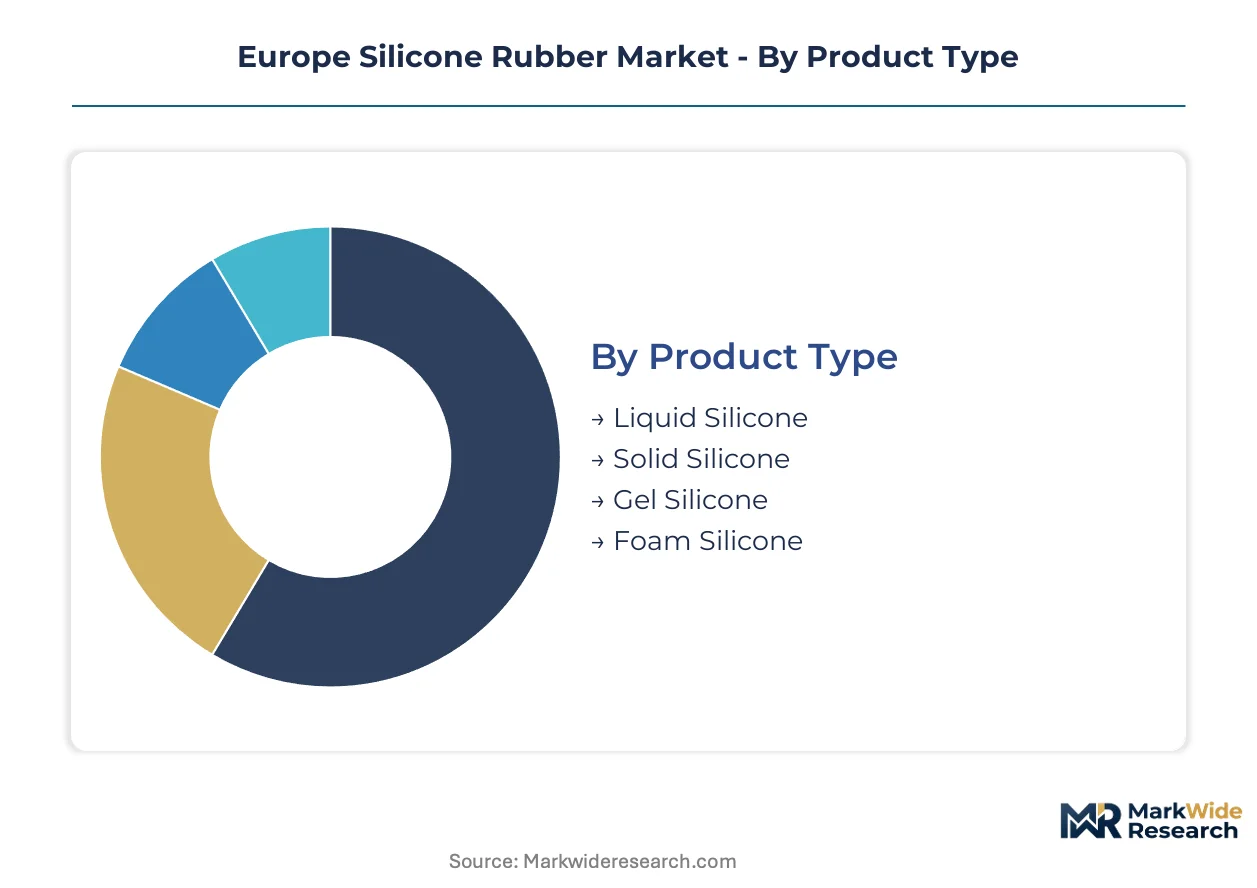
Segmentation in the Europe silicone rubber market reveals how material form and curing chemistry determine integration depth across automotive battery systems, medical devices, and industrial sealing applications. Procurement patterns diverge sharply between standalone commodity grades and formulation-critical compounds embedded in regulated end-products.
Product Type:
Integration depth varies from fully formulated liquid systems ready for automated injection molding to solid compounds requiring downstream compounding and vulcanization steps.
- Liquid Silicone:Low-viscosity polydimethylsiloxane polymers cured via platinum-catalyzed hydrosilylation enable high-cavitation injection molding with cycle times under sixty seconds. German automotive OEMs specify liquid silicone for EV battery thermal management gaskets, where part-to-part consistency and flash-free molding justify premium positioning over compression-molded alternatives.
- Solid Silicone:High-consistency rubber compounds delivered in slab or strip form require mill mixing and compression or transfer molding. French construction seal manufacturers favor solid grades for extruded window gaskets, leveraging the material's green strength and dimensional stability during cure.
- Gel Silicone:Ultra-soft formulations below Shore A 10 penetrate wearable medical interfaces and continuous glucose monitor adhesives in the Netherlands and Scandinavia.
- Foam Silicone:Cellular structures provide thermal and acoustic insulation in EV battery pack architectures, with Dutch and Belgian OEMs testing grades for cell-to-cell compression pads.
Solid silicone leads volumes today; liquid silicone is gaining share fastest.
End User:
Customer sophistication tiers separate specification-driven regulated industries from price-sensitive construction applications.
- Automotive:OEMs and Tier 1 suppliers specify platinum-cured grades with full lot traceability for powertrain and battery sealing. The Munich-Stuttgart corridor concentrates procurement volumes for Volkswagen Group and Mercedes-Benz AG platform programs.
- Electronics:Consumer device manufacturers in Germany and France demand ultra-pure liquid silicone for keypads, connector seals, and thermal interface materials.
- Healthcare:EMA MDR compliance requirements extend qualification timelines to eighteen months for implantable and long-term contact applications.
- Construction:Building envelope sealant compounders prioritize cost efficiency and weathering resistance over biocompatibility certification.
Automotive commands the largest revenue pool; healthcare expands most quickly.
Application:
Functional performance requirements dictate formulation complexity and regulatory burden across sealing and bonding use cases.
- Seals:Dynamic and static sealing applications in HVAC, automotive, and industrial equipment represent the foundational demand segment. ECHA F-Gas Regulation acceleration drives silicone substitution for fluorocarbon seals in compressor applications.
- Gaskets:Compression-set resistance and thermal stability specifications dominate EV battery and exhaust system procurement. German OEMs enforce single-source relationships for platform-level gasket programs.
- Adhesives:Room-temperature-vulcanizing formulations serve assembly bonding in electronics and medical device manufacturing.
- Coatings:Thin-film silicone protection layers extend to textile and paper substrates for specialized industrial applications.
Seals generate the highest absolute tonnage; gaskets show the steepest expansion trajectory.
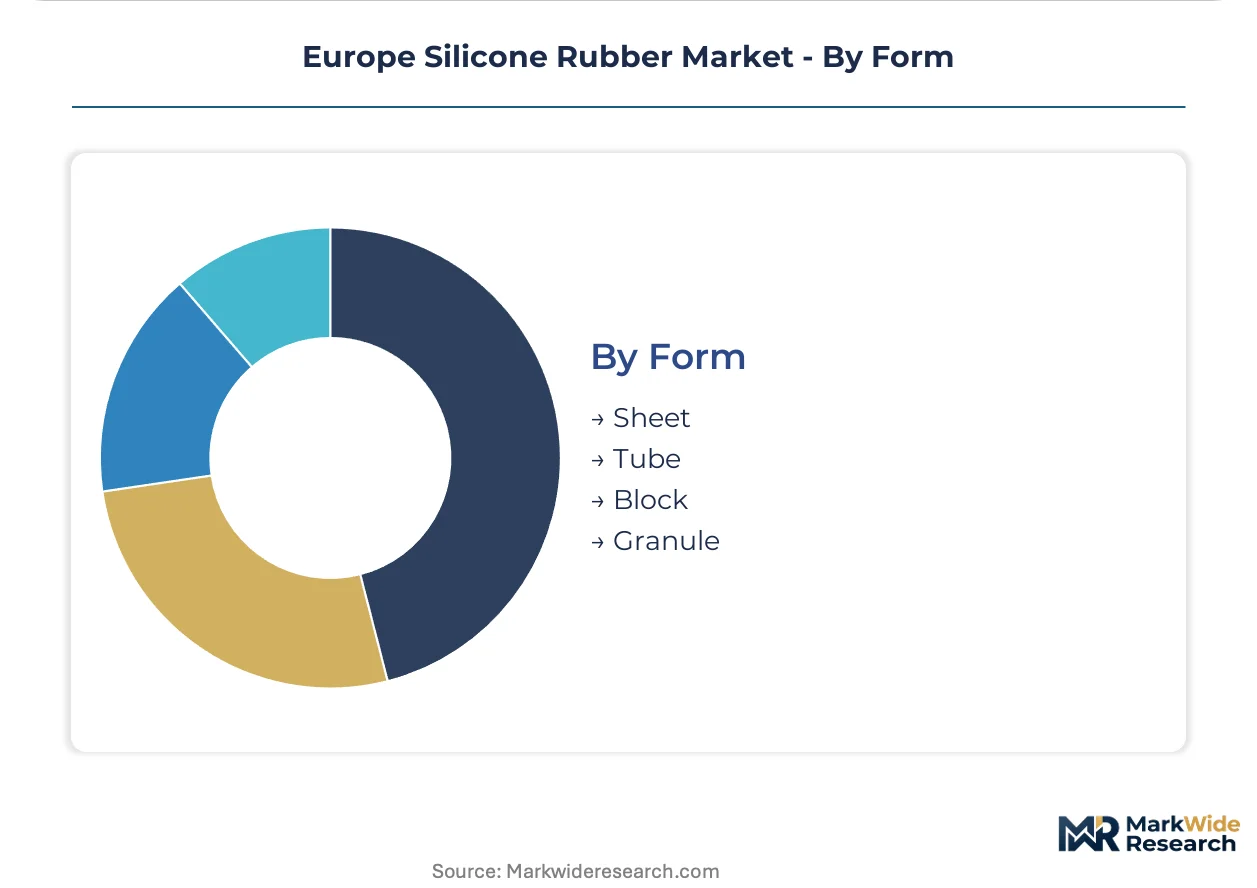
Form:
Physical delivery format determines downstream processing economics and supply chain configuration for compounders and converters.
- Sheet:Calendered silicone sheets serve gasket punching, diaphragm fabrication, and industrial belting across French and Italian manufacturing bases.
- Tube:Extruded tubular profiles dominate medical device and beverage tubing applications requiring peroxide or platinum cure.
- Block:Uncured rubber blocks enable custom compounding by specialized processors serving niche industrial segments.
- Granule:Free-flowing pellet forms support automated dosing in liquid injection molding and specialized extrusion operations.
Sheet and tube forms dominate current procurement; granule formats climb fastest on automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized technicians trained in platinum-cure hydrosilylation kinetics and cleanroom liquid injection molding cluster along the Munich-Stuttgart corridor, anchoring Europe's densest concentration of silicone rubber formulation expertise.
Germany
Volkswagen Group and Mercedes-Benz AG platform programs specify platinum-cured liquid silicone for EV battery thermal management gaskets. The EU Green Deal's industrial decarbonization mandates compress supplier qualification timelines while elevating carbon-footprint thresholds for Bavarian compounders. Wacker Chemie AG leverages its Burghausen manufacturing complex to sustain captive siloxane supply chains insulating formulation costs from import volatility.
France
Construction sealant manufacturers favor solid silicone grades for extruded window gaskets requiring green strength and dimensional stability during cure. ECHA REACH Annex XIV authorization list expansions systematically remove organotin catalysts from silicone curing processes, compelling reformulation toward platinum or peroxide systems. Elkem Silicones anchors its competitive position through integrated quartz-to-silicone operations in the Rhône Valley.
Netherlands
Continuous glucose monitor patch manufacturers and sleep-tracking earbud producers specify ultra-soft gel formulations below Shore A 10 for wearable medical interfaces. The EU F-Gas Regulation accelerates fluorocarbon displacement in HVAC and refrigeration seals, pushing equipment OEMs toward silicone alternatives. Dutch and Belgian OEMs test foam silicone grades for cell-to-cell compression pads in EV battery pack architectures.
Poland
Automotive Tier 1 suppliers relocate injection molding capacity to serve Volkswagen Group and Stellantis assembly plants with reduced logistics radius. Corporate Sustainability Reporting Directive mandates create premium pricing tiers for compounders with verified Scope 3 carbon accounting. Manufacturing investments concentrate around Kraków and Wrocław to access technical workforce pipelines from regional polytechnic institutes.
Sweden
Medical device extruders serving EMA-regulated markets establish dedicated production lines segregated from legacy tin-catalyzed operations. EMA cytotoxicity and sensitization protocols extend qualification timelines to eighteen months for implantable silicone applications. Stockholm and Gothenburg host specialist compounders focused on biocompatible grades certified under MDR for long-term patient contact devices.
Europe Silicone Rubber Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive siloxane feedstock positions. German and French compounders dominate formulation-critical supply relationships with automotive OEMs, while Asian specialists penetrate price-sensitive industrial segments. Three archetypes prevail: upstream-integrated siloxane producers, medical-grade certification specialists, and regional conversion-focused compounders. Capacity expansion and M&A consolidation represent the dominant competitive moves as OEMs rationalize vendor panels from six to two qualified suppliers per vehicle program.
Among Germany-based chemical conglomerates, Wacker Chemie AG exemplifies the upstream-integrated archetype through its Bavarian siloxane manufacturing complex. Dow Inc. and Momentive Performance Materials occupy positions within the premium-tier formulation segment, with the latter representing medical-grade certification specialists serving EMA-regulated healthcare markets. Elkem Silicones anchors the quartz-to-silicone integrated model through its French operations.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Dow Inc. |
| Elkem Silicones |
| Momentive Performance Materials |
| Evonik Industries AG |
| Shin-Etsu Chemical Co Ltd |
| KCC Corporation |
| MESGO S.p.A. |
| Simtec Silicone Parts |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon-footprint thresholds for industrial suppliers are compressing procurement timelines and forcing compounders toward renewable energy certificates and verified Scope 3 accounting, which stratifies pricing across sustainability-verified and conventional supply tiers.
Pricing Analysis
Formulated compound pricing separates captive siloxane-integrated producers from merchant compounders sourcing feedstock externally. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with medical-grade MDR-certified formulations commanding substantial premiums over construction-grade alternatives. Cost compression in standard-tier automotive sealing runs through platinum catalyst volatility and energy cost spikes in Bavarian production clusters. Construction sealant buyers exhibit highest price sensitivity, while automotive OEMs and medical device manufacturers prioritize lot traceability and biocompatibility certification over unit cost.
Supply Chain Analysis
EU F-Gas Regulation domestic-content mandates for fluorocarbon displacement are reshaping sourcing toward regional silicone alternatives. Siloxane feedstock concentrates in Germany, France, and Belgium, with Wacker Chemie AG and Elkem Silicones anchoring captive supply chains. European compounding draws from quartz mining operations in the Rhône Valley and chlorosilane production at Burghausen. Single-source vulnerability persists in platinum group metal sourcing from South African mining output. Distribution runs through automotive Tier 1 integrators and medical device contract manufacturers with direct formulation relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Central European manufacturing cost structures and Western European regulatory compliance premiums, with Poland and Czech Republic offering technical workforce access at lower operational cost bases.
For Market Incumbents: Cement platform-level supplier status with Volkswagen Group and Mercedes-Benz AG through dedicated liquid silicone injection molding capacity in the Munich-Stuttgart corridor. Prioritize backward integration into siloxane feedstock to insulate margins from platinum catalyst volatility and energy cost spikes threatening merchant compounders. Lock in long-term offtake agreements with renewable energy certificate holders to meet EU Green Deal carbon-footprint thresholds. For New Entrants and Emerging Players: CSRD in Europe opens a window for verified Scope 3 carbon accounting services and sustainability-certified compound offerings that incumbent siloxane producers have not fully commercialized. Target wearable medical interface segments in the Netherlands and Scandinavia where ultra-soft gel formulations below Shore A 10 face limited qualified supply. Lead with EMA MDR compliance documentation capabilities to compress eighteen-month qualification timelines for healthcare OEMs. For Investors and Strategic Acquirers: Asymmetric upside sits with medical-grade certification specialists possessing dedicated cleanroom liquid injection molding lines segregated from tin-catalyzed operations. Five-to-ten-year viability hinges on MDR technical documentation bandwidth and EMA regulatory affairs expertise rather than commodity scale. Watch for delegated acts under the EU AI Act reshaping machine-vision inspection requirements for medical-grade silicone parts as the inflection signal for capital allocation toward automated manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstock | Wacker Chemie AG's Bavarian complex demonstrates captive supply insulation from import volatility. |
| Medical-Grade Cleanroom Capacity Expansion | Segregated platinum-cure lines capture MDR-certified demand from long-term patient contact devices. |
| Central European Manufacturing Relocation | Polish and Czech facilities reduce logistics radius to Volkswagen Group and Stellantis assembly plants. |
| Renewable Energy Certificate Procurement | Verified Scope 3 accounting unlocks premium pricing tiers under CSRD supply chain disclosure mandates. |
| Platinum-Cure Process Engineering Talent Acquisition | Hydrosilylation kinetics expertise scarcity constrains liquid silicone injection molding capacity expansion. |
Research Methodology
Bottom-up automotive and medical device modeling reconciled against top-down siloxane production tracking forms the analytical core of this study. Primary interviews with plant managers at compounding facilities, procurement leads at Tier 1 automotive suppliers, regulatory affairs directors at medical device OEMs, and technical R&D directors at silicone formulation houses combined with secondary validation. Secondary sources include ECHA REACH substance restriction databases, EMA MDR technical documentation filings, EU F-Gas Regulation implementation reports, and customs trade data for siloxane and silicone rubber imports. Triangulation across these sources ensures volume and value estimates align with observed procurement patterns.
Historical trendline analysis of platinum-cured liquid silicone adoption in EV battery sealing and solid silicone displacement in construction applications informed projection frameworks. Segmentation dimensions modeled include product form (liquid, solid, gel, foam), curing chemistry (platinum, peroxide, tin), end-use industry (automotive, healthcare, electronics, construction), and regional production hub (Germany, France, Netherlands, Poland, Sweden). CAGRs derive from fitted growth curves applied to technology substitution rates and regulatory-driven material displacement timelines. Forecast inputs incorporate EU Green Deal industrial decarbonization mandate compliance costs and EMA biocompatibility testing protocol durations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under platinum group metal supply disruptions or accelerated REACH Annex XIV authorization list expansions. Forecasts reflect assumptions regarding EV battery platform standardization timelines and MDR technical documentation burden evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Foam Materials Market
Rubber
Plastomers Market
Rubber
Performance Elastomers Market
Rubber
EPDM Rubber Market
Rubber
Styrene Butadiene (SB) Latex Market
Rubber
Global Cast Elastomers Market
Rubber
Cellular Rubber Market
Rubber
Rubber Block Market
Rubber
Tire Softener Market
Rubber
Recycled Elastomers Market
Rubber
Rubber Valve Stem Market
Rubber
Snap on Rubber Stopper Market
Rubber
Rubber Sand Market
Rubber
Sterile Rubber Stopper Market
Rubber
Silica for S-SBR Market
Rubber
Rubber Foam Market