
 Global Anti-Corrosion Coating Market | 2026-2036
Global Anti-Corrosion Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Corrosion Coating Market Foresight
Specialty chemical distribution networks serving marine yards and energy producers is reshaping how formulations reach end users in the Global Anti-Corrosion Coating Market. Akzo Nobel N.V. leverages its marine coatings heritage across European and Asian shipyards. PPG Industries, Inc. anchors its position through electrodeposition technology leadership in automotive-adjacent industrial segments. The Sherwin-Williams Company dominates North American infrastructure maintenance channels with extensive distributor relationships.
Anti-corrosion coatings are barrier-formulating systems, typically comprising epoxy resins, zinc particulates, or polyurethane binders applied at dry-film thicknesses of 75–500 microns, designed to inhibit electrochemical degradation of steel and aluminum substrates in aggressive environments. Epoxy formulations occupy the largest volume share due to their adhesion strength and chemical resistance in offshore oilfield equipment. Powder coating technology leads growth among application methods as manufacturers eliminate solvent handling and reduce hazardous air pollutant emissions. Maritime operators represent the most concentrated end user industry, with dry-dock maintenance cycles driving predictable re-coating demand across global fleets.
REACH in Europe, China's GB standards under SAMR oversight, and the EPA's National Emission Standards for Hazardous Air Pollutants in the United States each constrain solvent-borne formulation availability while accelerating water-borne and high-solids alternatives. ECHA's candidate list of substances of very high concern continues to disqualify legacy chromate-based inhibitors from EU supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure cross-border formulation approvals.
Market Dynamics
Water-borne formulation chemistry is compressing solvent-borne capacity across marine and industrial coating supply chains as ECHA's SVHC list and China's GB standards simultaneously disqualify legacy systems. This dual regulatory pressure is forcing reformulation investments that favor integrated resin producers with captive R&D infrastructure.
Growth Catalysts
- Fleet renewal cycles:Maritime operators in Hamburg, Singapore, and Busan are accelerating dry-dock schedules for CII-compliant hull coatings. Re-coating demand from existing vessels now outpaces newbuild volumes in several anchor ports.
- REACH substance restrictions:ECHA's ongoing chromate and isocyanate classifications are redirecting specification authority toward coating formulators with pre-approved water-borne alternatives. Early registrants capture specification lock-in at European yards.
- Electrodeposition expansion:Automotive-adjacent industrial segments in Michigan and Stuttgart are adopting cathodic epoxy e-coat systems for precision components. This application method delivers edge coverage that spray alternatives cannot replicate.
Market Restraints
- Zinc raw material concentration:Zinc dust supply for sacrificial primers concentrates with smelter networks in Australia and Peru. Price volatility in LME zinc contracts directly compresses margin on marine epoxy formulations.
- High-solids technical ceiling:Solvent-borne systems above 80% volume solids exhibit application viscosity limits that spray equipment cannot handle. This creates a performance gap water-borne chemistry has not closed in heavy industrial environments.
- Cross-border formulation divergence:ECHA's SVHC list, EPA NESHAP, and China's GB standards maintain non-overlapping restricted substance schedules. Multi-site manufacturers face stranded inventory risk and duplicate certification costs.
Strategic Opportunities
- Offshore wind installation growth:Monopile and jacket foundation fabricators in Denmark and Taiwan require specialized splash-zone coatings with 25-year service life. This application sits outside traditional marine specification channels.
- Powder coating line conversions:Industrial manufacturers in Ontario and Bavaria are retrofitting liquid spray booths for powder application. Zero-VOC compliance eliminates solvent handling infrastructure and hazardous waste streams.
- Digital specification platforms:Engineering procurement teams at energy majors are adopting cloud-based coating selector tools. Distributors with integrated technical data capture specification influence earlier in project timelines.
Industry Challenges
- Formulation chemist scarcity:Expertise in hybrid water-borne epoxy-polyurethane systems resides with a narrow cohort of specialists. Shipyards in Gdansk and Nagasaki report extended qualification timelines due to technical resource constraints.
- Surface preparation standards:ISO 8501-1 Sa 2.5 blast cleanliness requirements demand capital-intensive automated blasting infrastructure. Subcontractor capacity bottlenecks in Rotterdam and Houston delay coating application windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Corrosion Coating Market |
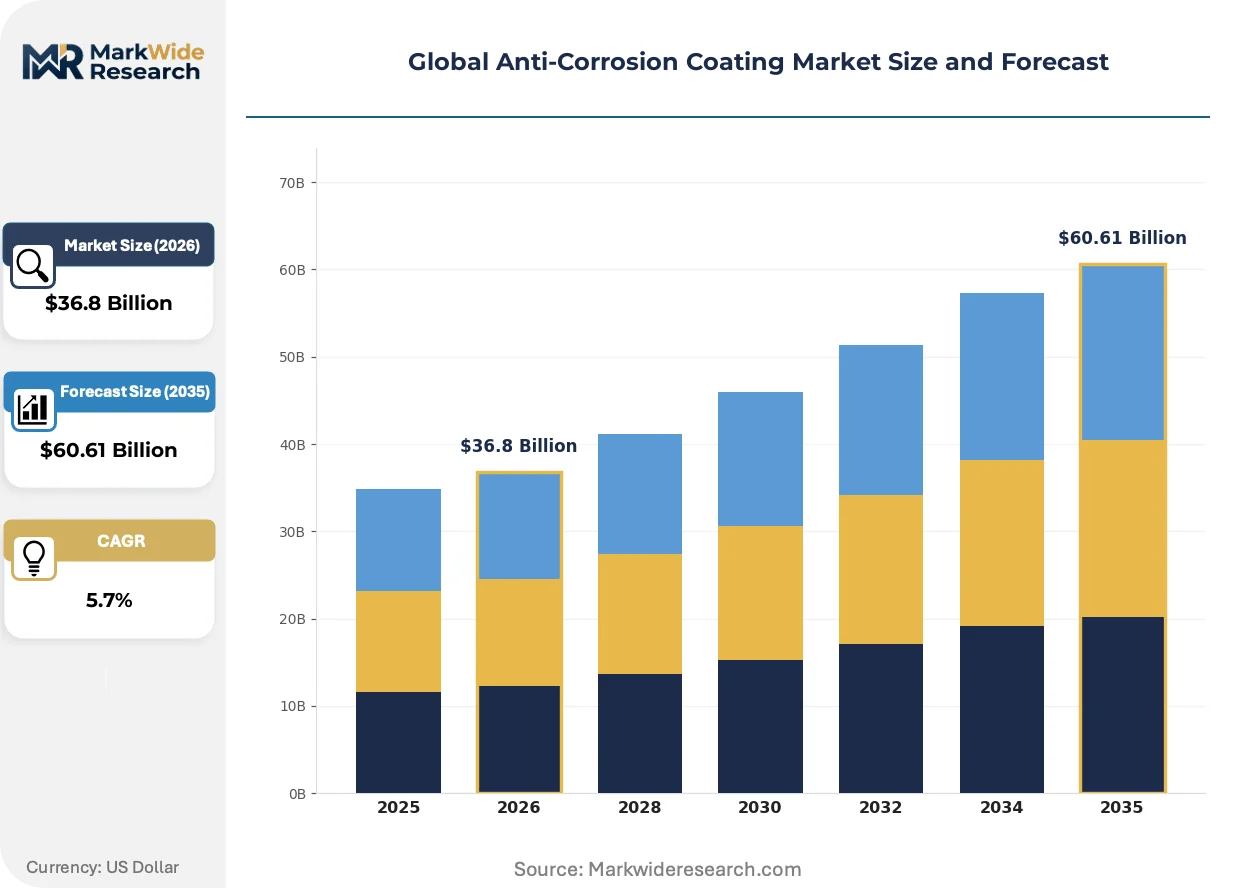
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $60.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Zinc-Rich, Alkyd Application: Marine, Infrastructure, Oilfield Equipment, Power Generation, Aerospace End User Industry: Construction Operators, Maritime Operators, Energy Producers, Aircraft Manufacturers, Heavy Industry Coating Technology: Thermal Spray, Electrodeposition, Powder Coating, Chemical Vapor Deposition, Sol-Gel |
| Companies Covered | Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Jotun, Hempel A/S, Axalta Coating Systems, LLC, BASF SE, RPM International Inc., Kansai Paint Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Corrosion Coating Market Shifts & Advancements
Digital coating specification tools and predictive corrosion monitoring are compressing traditional distributor influence while elevating technical data transparency as a competitive weapon. Formulators now compete on algorithm-accessible performance databases rather than relationship-based specification alone.
Self-healing microcapsule technology is virtualizing maintenance scheduling for subsea pipelines and offshore platforms. Operators in the North Sea and Gulf of Mexico are piloting autonomous repair systems that release corrosion inhibitors upon coating breach detection. This capability compresses inspection frequency requirements and shifts value capture toward coating suppliers with embedded sensor partnerships.
EPA NESHAP Subpart HHHHHH is tightening HAP emission limits for shipbuilding and ship repair facilities in US coastal states. Yard operators in Virginia and Mississippi face capital decisions between add-on control devices and full process conversion to compliant chemistries. The regulation is accelerating water-borne primer adoption in military and commercial newbuild programs previously resistant to reformulation.
Integrated coating-plus-inspection service bundles are displacing discrete material procurement at major energy producers. National oil companies in Saudi Arabia and Brazil now contract corrosion protection on availability-guaranteed terms rather than per-liter pricing. This shift transfers performance risk to applicators with NACE-certified inspection capabilities and captive access to approved product systems.
Global Anti-Corrosion Coating Market Segmentation
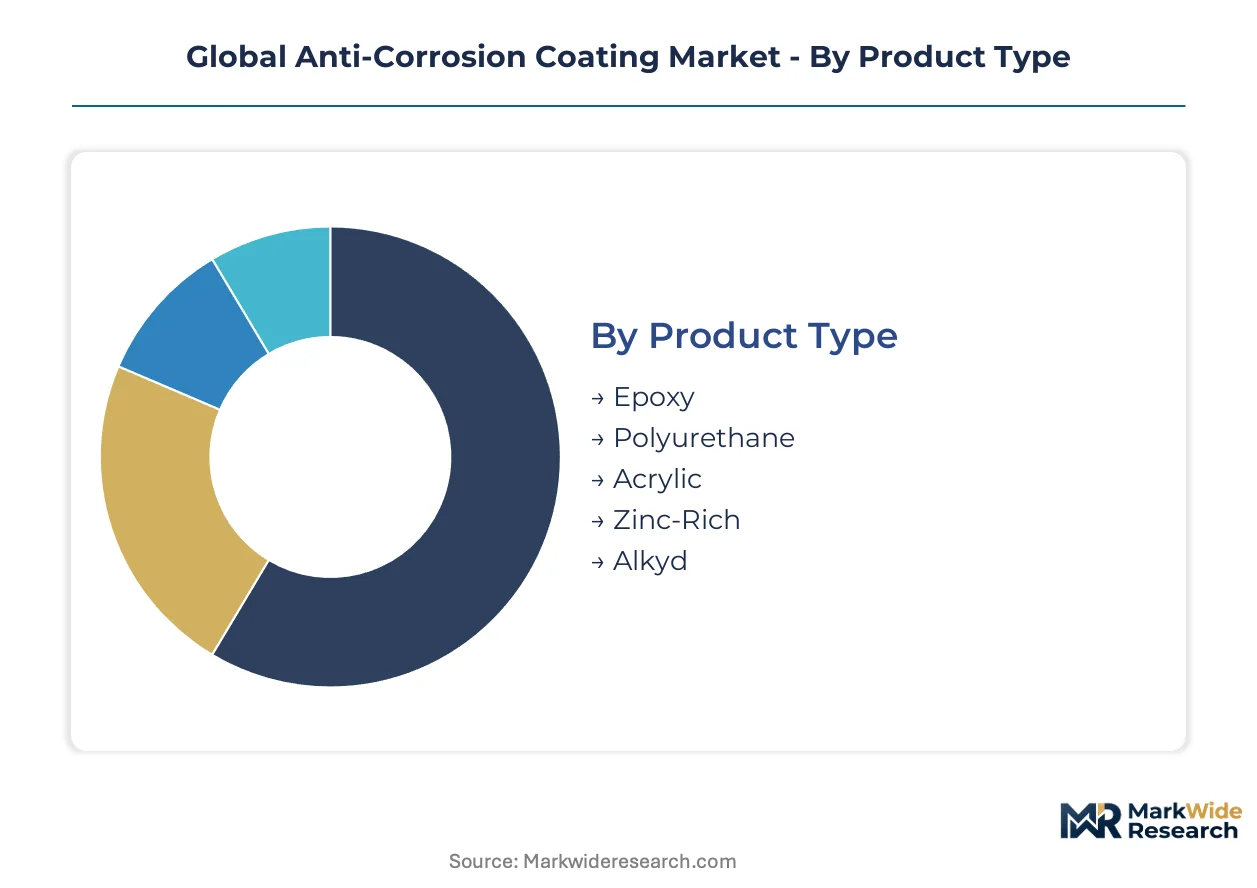
Anti-corrosion coating procurement varies sharply by maintenance cycle intensity. Fleet operators in Hamburg and Singapore demand predictable re-coating schedules, while infrastructure owners prioritize extended service intervals. This divergence shapes formulation specifications across every segment.
Product Type:
After-sales service intensity runs highest where coating failure carries catastrophic replacement cost.
- Epoxy:Two-part thermoset systems combining bisphenol-A resins with polyamine hardeners deliver adhesion strength exceeding 15 MPa on blast-cleaned steel. Offshore platform fabricators in the Gulf of Mexico specify these formulations for splash-zone protection where delamination risks platform structural integrity. REACH substance restrictions on chromate accelerators are forcing reformulation toward silane-modified alternatives.
- Polyurethane:Aliphatic isocyanate-cured topcoats provide UV resistance and color retention for architectural steel exposed to coastal atmospheres. Bridge maintenance contractors in Florida and New South Wales favor these systems for aesthetic durability in high-salinity environments. Isocyanate exposure regulations are tightening applicator certification requirements.
- Acrylic:Water-borne emulsions serve light industrial and OEM applications with moderate corrosion exposure. Metal roofing manufacturers in Ontario specify these for factory-applied protection.
- Zinc-Rich:Inorganic ethyl silicate binders suspending 85%+ zinc dust provide sacrificial protection to structural steel. Demand concentrates in petrochemical construction around Houston and Rotterdam.
- Alkyd:Oxidative-cure oil-modified polyesters retain position in maintenance painting of existing industrial equipment. Railcar refurbishment shops in Pennsylvania represent steady volume.
By volume, Epoxy leads. By growth pace, Polyurethane is ahead.
Application:
Cost tier stratification separates specification-grade systems from commodity maintenance coatings.
- Marine:Hull, ballast tank, and cargo hold coatings must withstand cyclic immersion and cathodic protection compatibility demands. Dry-dock operators in Busan and Nagasaki drive re-coating volume through mandatory CII compliance schedules. Fleet renewal programs are extending specification authority to coating suppliers with integrated inspection capabilities.
- Infrastructure:Bridge, pipeline, and water treatment coatings prioritize extended service life over initial application speed. State transportation departments in Germany and Japan specify high-performance systems with 25-year warranties.
- Oilfield Equipment:Downhole tubing and subsea pipeline coatings resist sour gas and high-pressure seawater exposure. Fabricators in Aberdeen and Stavanger require NORSOK-qualified formulations.
- Power Generation:Boiler, turbine, and cooling system coatings balance thermal cycling resistance with fouling prevention. Combined cycle plant operators in Texas and Gujarat specify specialized high-temperature epoxies.
- Aerospace:Chromate-free pretreatments and primer systems protect airframe aluminum from galvanic corrosion. OEM qualification timelines in Toulouse and Seattle extend 18-24 months.
Marine dominates absolute volume. Infrastructure is expanding most quickly as bridge replacement cycles accelerate.
End User Industry:
Customer type determines whether procurement favors distributor relationships or direct formulation partnerships.
- Construction Operators:General contractors and steel fabricators specify coatings through project engineering consultants. Demand concentrates in commercial high-rise and industrial warehouse construction.
- Maritime Operators:Container lines, tanker owners, and cruise operators contract coating application through shipyard networks. Fleet managers in Copenhagen and Singapore are consolidating supplier relationships to secure dry-dock slot priority.
- Energy Producers:National oil companies and independent operators are shifting to availability-based corrosion protection contracts. Saudi Aramco and Petrobras now require integrated coating-plus-inspection service bundles.
- Aircraft Manufacturers:OEMs and tier-one aerostructures suppliers mandate qualified product lists with extensive testing documentation. Airbus and Boeing qualification status gates commercial access.
- Heavy Industry:Mining equipment, agricultural machinery, and rail rolling stock manufacturers balance corrosion protection with abrasion resistance. Caterpillar and Komatsu specify coating systems through component supplier manuals.
Maritime Operators lead by re-coating frequency. Energy Producers are gaining share fastest through contract structure transformation.
Coating Technology:
Technology maturity separates established application methods from emerging deposition processes.
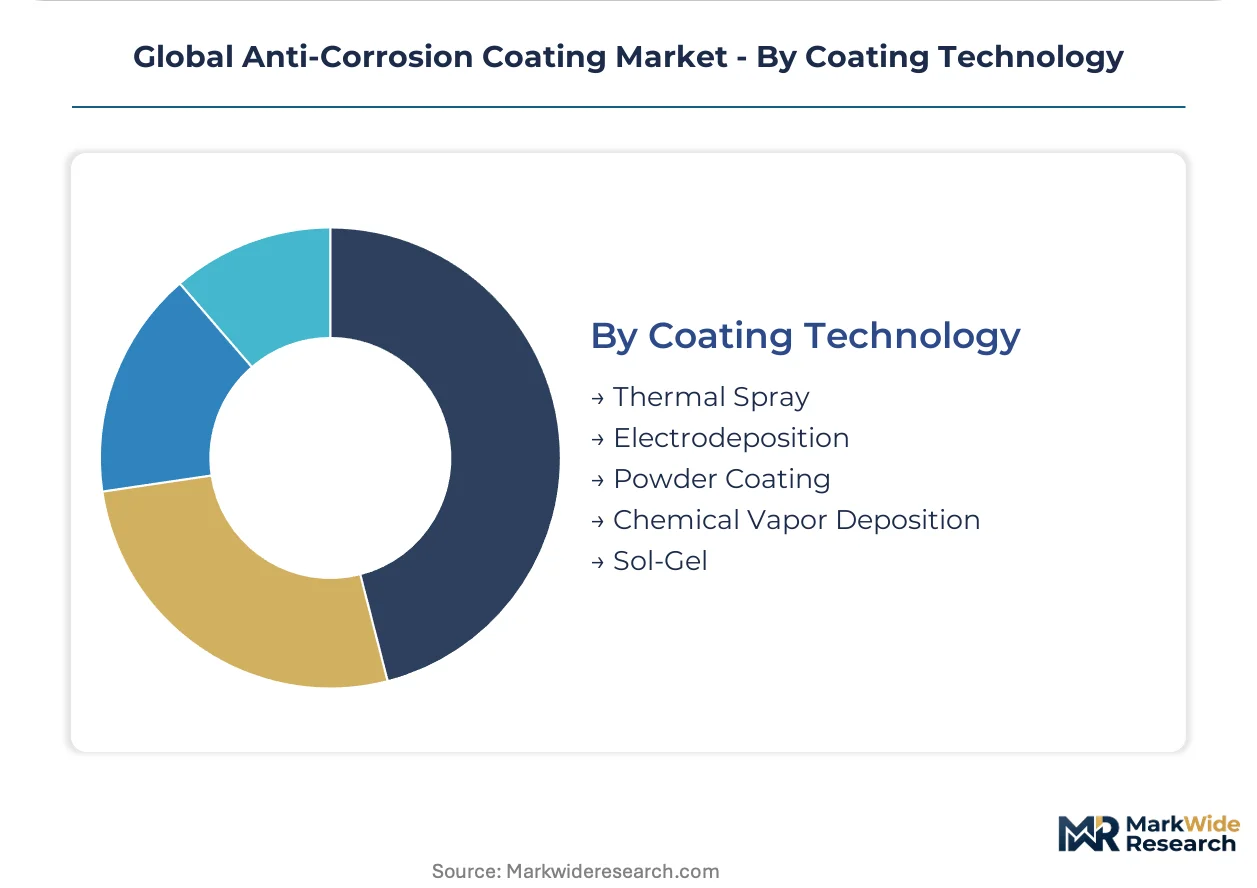
- Thermal Spray:Arc wire and plasma spray systems deposit metallic aluminum or zinc coatings onto large structural surfaces. Offshore wind foundation fabricators in Denmark specify these for 25-year splash-zone protection.
- Electrodeposition:Cathodic epoxy e-coat systems deliver uniform edge coverage on complex automotive and precision components. Adopters in Stuttgart and Michigan value film thickness consistency.
- Powder Coating:Electrostatic application of thermoset powders eliminates solvent handling and hazardous waste streams. Industrial manufacturers in Bavaria and Ontario are retrofitting liquid lines for zero-VOC compliance.
- Chemical Vapor Deposition:Thin-film ceramic coatings protect turbine blades and precision instruments from high-temperature oxidation. Aerospace and power generation applications require specialized vacuum chambers.
- Sol-Gel:Hybrid organic-inorganic nanocomposite films provide barrier protection with minimal film thickness. Electronics and medical device manufacturers in Switzerland and Massachusetts pilot these for component-level corrosion prevention.
Powder Coating leads by volume conversion rate. Thermal Spray is climbing the fastest as offshore wind installation scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with European formulators commanding specification premiums, while Chinese producers compete on volume through coastal manufacturing clusters. German and Dutch coating specialists leverage REACH-compliant water-borne portfolios to secure long-term contracts at North Sea yards. Asian manufacturers respond with high-solids solvent systems optimized for tropical application conditions and cost-sensitive procurement.
China
Shipbuilding clusters around Shanghai and Ningbo drive concentrated demand for marine-grade epoxy systems. SAMR's GB standards under tightening VOC limits accelerate water-borne primer adoption at state-owned yards. Dalian and Guangzhou facilities are retrofitting spray booths to meet dual carbon goals while maintaining throughput.
United States
Gulf Coast offshore platform fabricators and Virginia shipyards sustain demand for high-performance barrier coatings. EPA NESHAP Subpart HHHHHH tightens HAP emission limits, forcing capital decisions between add-on controls and chemistry conversion. Houston petrochemical construction and Mississippi military newbuild programs anchor regional volume.
Germany
Automotive-adjacent industrial segments in Stuttgart and Bavaria adopt cathodic electrodeposition for precision components. REACH substance restrictions on chromate accelerators redirect specification authority toward early registrants with pre-approved alternatives. Hamburg maritime operators accelerate dry-dock schedules for CII-compliant hull coatings.
Japan
Nagasaki and Kure shipyards face extended qualification timelines due to formulation chemist scarcity in hybrid water-borne systems. METI oversight aligns domestic standards with IMO environmental regulations. Osaka-based industrial manufacturers balance corrosion protection with abrasion resistance for export machinery.
South Korea
Busan dry-dock operators drive re-coating volume through mandatory compliance schedules for container fleets. Ulsan shipbuilders consolidate supplier relationships to secure slot priority amid fleet renewal programs. Domestic formulators compete with European specialists for specification influence at major yards.
Global Anti-Corrosion Coating Market Competitive Landscape
Integrated resin producers and specialty distributors split the market along the formulation-versus-delivery axis. The vendor base concentrates among three tiers: multinational chemical conglomerates with captive R&D infrastructure, regional coating specialists with shipyard relationships, and industrial distributors with technical service capabilities. Competitive moves center on reformulation investments for regulatory compliance and strategic partnerships for inspection-integrated service bundles.
Within the multinational tier, Akzo Nobel N.V. and PPG Industries, Inc. exemplify divergent strategic positioning. The former leverages marine coatings heritage across European and Asian shipyards, while the latter anchors position through electrodeposition technology leadership in automotive-adjacent segments. Among North American infrastructure channels, The Sherwin-Williams Company occupies a distributor-relationship position that captures maintenance procurement volume.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Jotun |
| Hempel A/S |
| Axalta Coating Systems, LLC |
| BASF SE |
| RPM International Inc. |
| Kansai Paint Co., Ltd. |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors transmit zinc dust cost volatility directly into marine epoxy formulation pricing, compressing margins for distributors serving North Sea yards while amplifying premium capture for integrated resin producers with captive smelter relationships.
Pricing Analysis
The customization-premium spread separates specification-grade marine systems from commodity maintenance coatings by a factor of three to five, driven by NORSOK certification requirements and dry-dock slot priority guarantees. Zinc-rich primers carrying 85%+ metallic content command premium positioning against standard epoxies due to sacrificial protection performance in splash-zone applications. Pricing pressure stems from LME zinc contract volatility transmitted through Australian and Peruvian smelter networks. Maritime operators in Hamburg and Singapore exhibit lowest price sensitivity due to CII compliance mandates, while industrial maintenance contractors in Pennsylvania and Ontario face acute cost compression.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk for water-borne resin intermediates, forcing dual-sourcing strategies among formulators with trans-Pacific manufacturing footprints. Raw material concentration centers on bisphenol-A epichlorohydrin production in China, Germany, and the United States, with zinc dust supply anchored in Australian and Peruvian mining operations. The supply chain draws from chromate accelerator stockpiles facing ECHA SVHC disqualification, creating stranded inventory exposure for distributors with legacy formulations. Distribution runs through specialty chemical networks serving shipyard clusters in Busan, Nagasaki, and Hamburg, with technical service capabilities determining specification influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
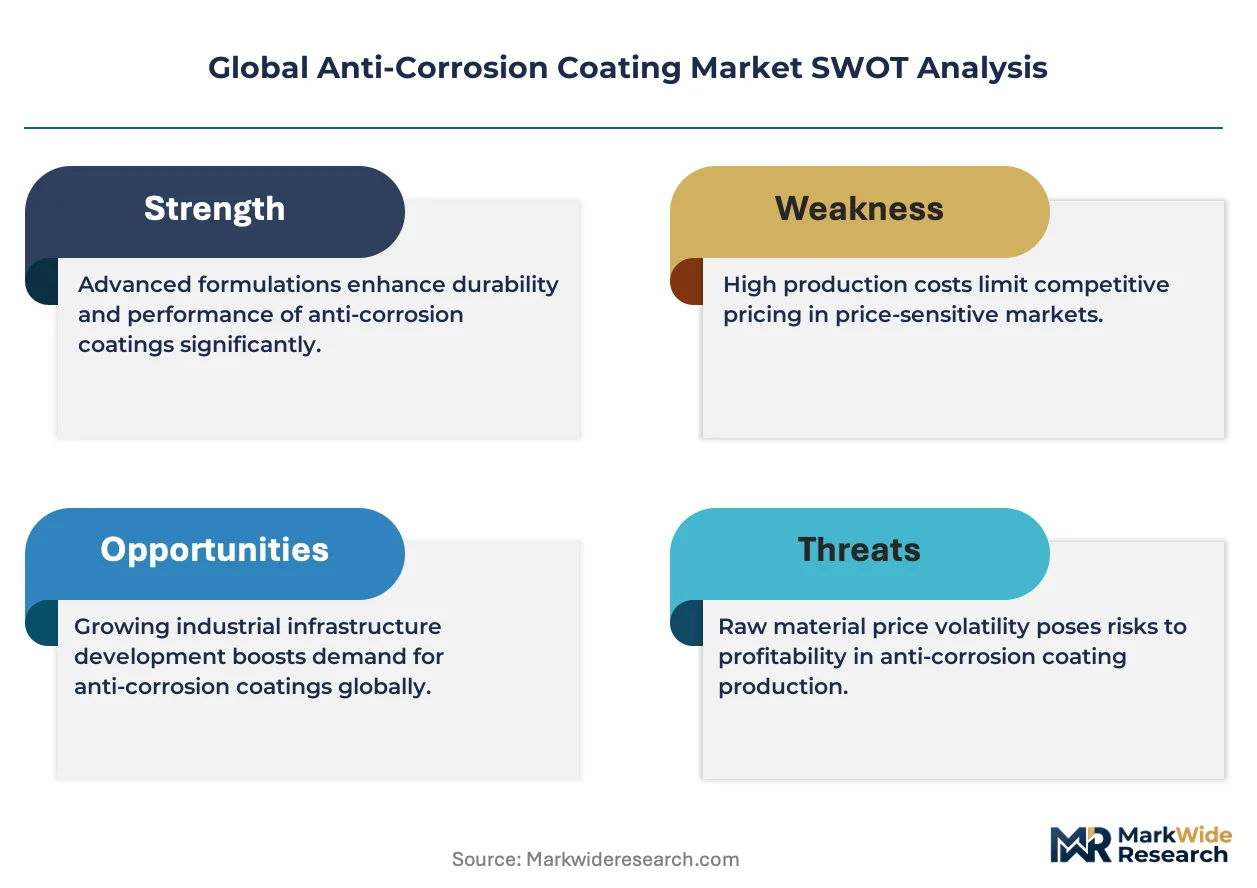
Water-borne formulation chemistry represents a high-growth disruption as dual regulatory pressure from ECHA and SAMR compresses solvent-borne capacity, creating specification lock-in opportunities for early registrants with pre-approved alternatives.
For Market Incumbents: Pre-empt specification authority erosion by accelerating silane-modified accelerator R&D ahead of REACH chromate restrictions, while securing backward integration into zinc dust supply through offtake agreements with Australian smelter networks. Defend distributor relationships at Hamburg and Singapore yards through integrated inspection service bundles that transfer performance risk from operators. For New Entrants and Emerging Players: Pursue offshore wind foundation coating specifications in Denmark and Taiwan, where monopile fabricators sit outside traditional marine channels and demand 25-year splash-zone protection without incumbent lock-in. Target powder coating line conversion projects in Bavaria and Ontario industrial manufacturing, offering zero-VOC compliance without solvent handling infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid water-borne epoxy-polyurethane specialists with narrow formulation chemist cohorts and shipyard qualification timelines. Long-term viability hinges on regulatory divergence navigation capabilities across ECHA, EPA, and SAMR jurisdictions. The signal to watch is qualification timeline compression at Nagasaki and Gdansk yards as technical resource constraints ease.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Supply | Captive smelter relationships insulate margin from LME volatility transmitted through Rotterdam-Antwerp corridors. |
| Water-Borne Formulation Registration | Early ECHA registrants capture specification lock-in at Hamburg yards before chromate restrictions tighten. |
| Offshore Wind Certification Investment | NORSOK-qualification for monopile coatings opens 25-year service contracts outside traditional marine channels. |
| Integrated Inspection Service Bundles | NACE-certified capabilities transfer performance risk from Saudi Aramco and Petrobras toward coating suppliers. |
| Powder Coating Line Conversion | Zero-VOC compliance eliminates solvent handling infrastructure for Bavaria and Ontario industrial manufacturers. |
Research Methodology
Two parallel data streams informed the analysis: direct engagement with coating formulators, shipyard procurement directors, and specialty chemical distributors, combined with secondary validation through customs trade records, SEC filings of multinational coating suppliers, ECHA substance restriction announcements, and SAMR GB standard updates. Bottom-up volume estimates from shipyard dry-dock schedules and offshore wind installation pipelines were triangulated against top-down resin production data from Cefic and ACC reports.
Forecast inputs span product type segmentation across epoxy, polyurethane, and zinc-rich systems; application dimensions including marine, infrastructure, and oilfield equipment; and coating technology categories from solvent-borne to water-borne and powder. CAGRs were derived through regression analysis of historical formulation adoption curves against regulatory phase-in schedules. Zinc price volatility transmission and fleet renewal cycle intensity served as primary demand-side inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-owned resin producers or accelerated ECHA substance restrictions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Metallic Powder Coating Market
Coatings
Ethylene Tetrafluoroethylene (ETFE) Coatings Market
Coatings
Global Diamond Coatings Market
Coatings
Functional Coil Coating Market
Coatings
ASEAN Automotive OEM Coatings Market
Coatings
Emulsion Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Global Pipe Coatings Market
Coatings
Silicone Coating Market
Coatings
US Protective Coatings Market
Coatings
UV Coatings Market
Coatings
Coating Resins Market
Coatings
Global Mirror Coatings Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
Coating Binders Market
Coatings
Coating Thickness Gauge Market