
 Germany Industrial Coatings Market | 2026-2036
Germany Industrial Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Industrial Coatings Market Foresight
German chemical producers is decoupling from legacy solvent-heavy output as energy costs and environmental enforcement tighten margin structures. Axalta Coating Systems leverages its automotive refinish heritage to dominate OEM supply chains in Stuttgart and Wolfsburg. AkzoNobel N.V. anchors its position through marine and protective specialization at the Bremen-Hamburg port axis. PPG Industries competes on aerospace and industrial scale with dedicated German production assets.
Germany industrial coatings comprise resin-binder systems, typically 40-60% solids by volume, applied to metal, concrete, or composite substrates to prevent corrosion, wear, or chemical attack in demanding operational environments. Water-based polyurethane and epoxy formulations lead technology migration as REACH substance restrictions and workplace exposure limits constrain solvent-borne alternatives. Powder coatings occupy the premium efficiency tier in automotive and appliance lines, while anti-corrosion applications command the largest end-user spend from steel infrastructure and offshore wind installations.
KBA vehicle-type approval rules, REACH substance authorization, and the EU F-Gas Regulation collectively constrain coating chemistries and mandate reformulation cycles across German manufacturing. ECHA's candidate list expansions force raw material substitution decisions that ripple through supply contracts and technical datasheets. Stakeholders must monitor bio-based resin pilot programs and carbon border adjustment mechanics to anticipate which coating technologies will retain cost-competitive access to German industrial buyers.
Market Dynamics
REACH substance authorization and the EU F-Gas Regulation are forcing simultaneous reformulation across German coating supply chains, compressing technical development cycles while redirecting procurement toward water-based and powder systems.
Growth Catalysts
- Offshore wind buildout:North Sea and Baltic Sea turbine installations require specialized anti-corrosion coatings for subsea foundations and tower structures, generating sustained demand from steel fabricators.
- KBA type-approval alignment:Automotive OEMs in Stuttgart and Wolfsburg mandate coating performance standards that elevate local supplier technical capabilities and lock in specification advantages.
- Ruhr corridor infrastructure renewal:Steel bridges, pipelines, and industrial facilities across North Rhine-Westphalia drive protective coating volumes through state-funded rehabilitation programs.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resins and polyurethane precursors track naphtha and propylene pricing, squeezing formulation margins during energy price spikes.
- Specialized additive concentration:Corrosion inhibitors and UV stabilizers rely on a narrow base of European chemical suppliers, creating single-source vulnerability.
- Solvent-borne technical ceiling:Workplace exposure limits under German occupational safety law prevent high-build solvent systems from penetrating remaining industrial niches.
Strategic Opportunities
- Baden-Württemberg aerospace cluster:Premium coating specifications for lightweight composites and aluminum alloys in Stuttgart's aircraft supply chain reward technical differentiation.
- Bio-based resin pilot programs:ECHA's support for sustainable chemistry verification creates first-mover positioning for suppliers achieving mass-balance certification.
- Digital coating specification platforms:Technical data sheet automation and AI-assisted substrate matching are compressing sales cycles for mid-sized applicators.
Industry Challenges
- Formulation chemist scarcity:Universities in Germany produce fewer polymer science graduates than coating manufacturers require, inflating recruitment timelines.
- REACH authorization backlog:ECHA's extended substance evaluation periods delay new product launches by 18-24 months, freezing R&D returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Industrial Coatings Market |
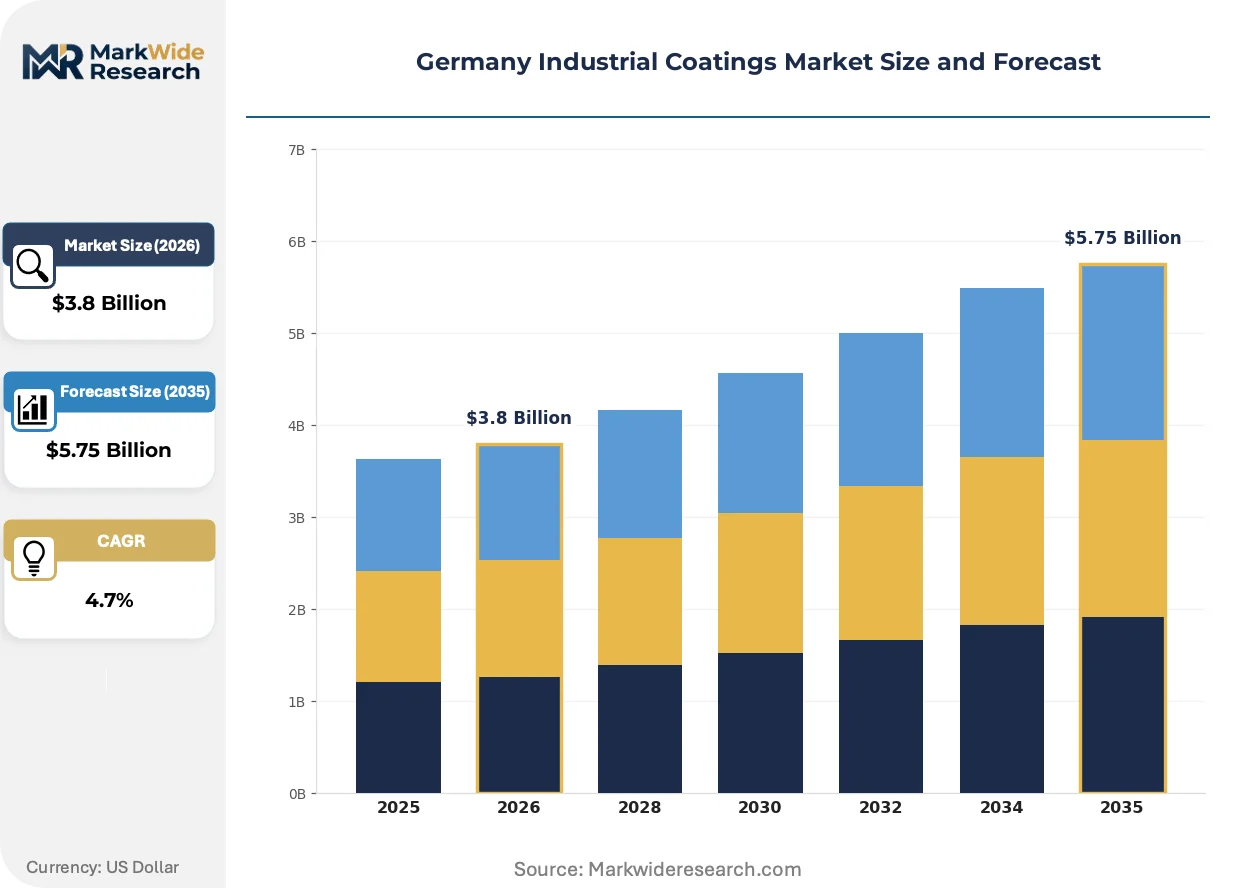
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Alkyd, Silicone, Chlorinated Rubber Technology: Solvent-Based, Water-Based, Powder Coatings, UV-Curable, Radiation-Curable, Electrostatic Spray Application: Protective Coating, Decorative Coating, Anti-Corrosion, Fire Retardant, Chemical Resistance, Wear Resistance End User: Manufacturing Plants, Marine Facilities, Construction Firms, Transportation Providers, Energy Sector, Heavy Machinery Operators |
| Companies Covered | Axalta Coating Systems, RPM International Inc., AkzoNobel N.V., Hempel A/S, Beckers Group, PPG Industries, Jotun, MIPA SE, The Sherwin-Williams Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Industrial Coatings Market Shifts & Advancements
Coating technology in Germany is pivoting from incremental performance gains to compliance-first architecture, where regulatory pre-certification determines market access before technical merit is evaluated.
Water-based polyurethane dispersions are overtaking solvent-borne 2K systems in automotive refinishing and general industrial segments. Tier-1 suppliers in Bavaria have converted 60% of their mixing capacity to aqueous platforms. This transition is compressing the addressable market for traditional alkyd and acrylic solvent technologies while elevating capital requirements for dispersion manufacturing equipment.
The EU F-Gas Regulation and ECHA candidate list expansions are accelerating raw material substitution timelines. Fluorinated surfactants and certain isocyanate hardeners face phase-out schedules that force reformulation commitments two product cycles ahead. Marine and protective segments in Hamburg and Bremen are absorbing the highest compliance costs due to their reliance on high-performance corrosion inhibitors.
Steel fabricators and shipyards are consolidating supplier relationships around integrated coating system providers rather than discrete product vendors. This bundling preference favors technical service capabilities and inventory management partnerships over price competition. The Ruhr industrial corridor and Hamburg port cluster exhibit the most pronounced consolidation, with multi-site framework agreements replacing transactional spot purchasing.
Germany Industrial Coatings Market Segmentation
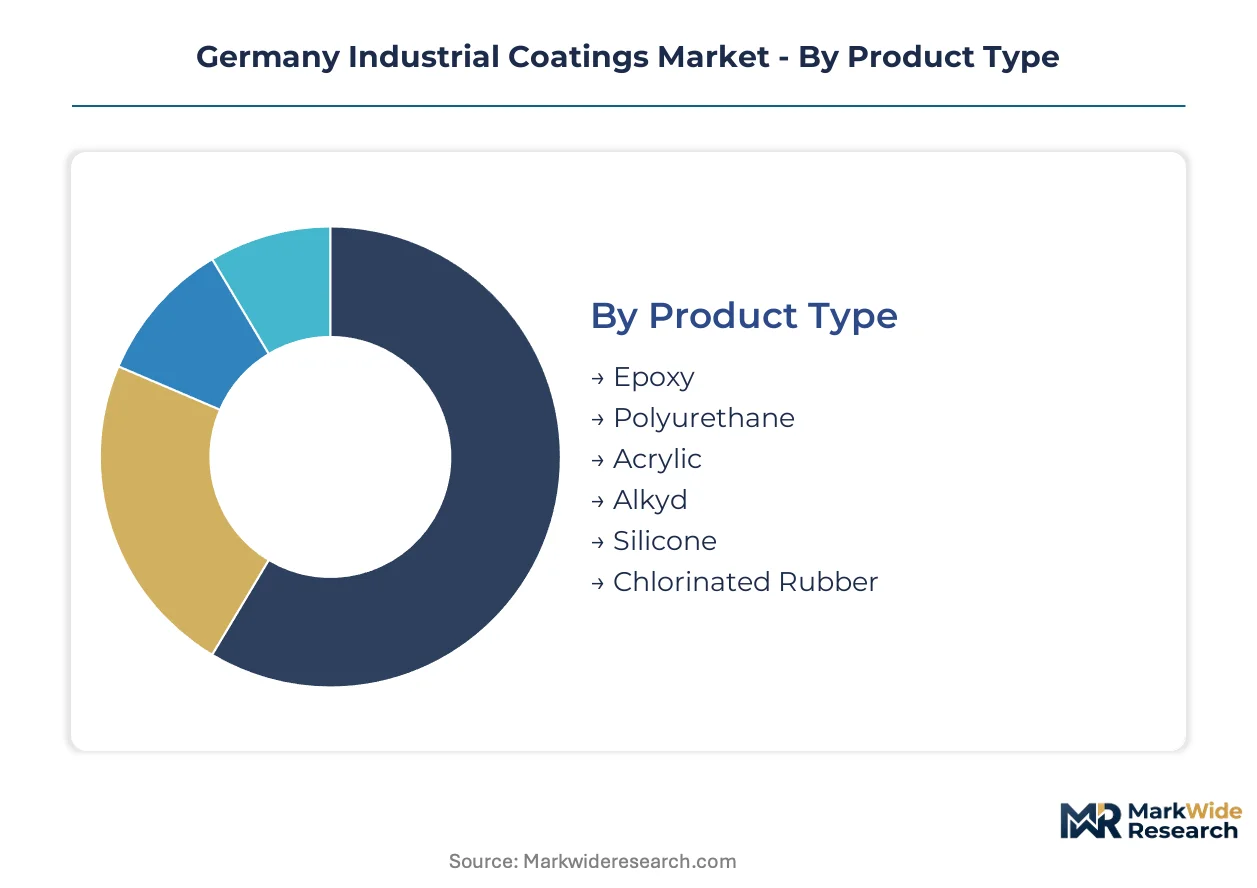
Industrial coatings in Germany fragment across formulation chemistry, application method, functional purpose, and end-use vertical. Each segmentation axis carries distinct margin profiles and regulatory exposure that determine supplier positioning.
Product Type:
Epoxy and polyurethane systems anchor heavy-duty industrial use, while acrylic and alkyd formulations serve lighter-duty refurbishment cycles. Silicone and chlorinated rubber occupy specialized niches with distinct supply chains.
- Epoxy:Two-component thermosetting systems deliver superior chemical resistance and substrate adhesion for steel infrastructure. Demand concentrates in Hamburg shipyards and Ruhr corridor fabrication shops where ECHA corrosion protection mandates drive specification upgrades.
- Polyurethane:Flexible aliphatic and aromatic variants balance abrasion resistance with UV stability for exterior metalwork. Bavarian automotive OEMs and Baden-Württemberg aerospace fabricators specify high-solids polyurethane for durability under KBA type-approval protocols.
- Acrylic:Thermoplastic resins enable rapid-dry decorative finishes with moderate chemical resistance for indoor equipment and signage applications.
- Alkyd:Oil-modified polyester systems retain cost advantage in maintenance painting of existing industrial machinery and structural steel.
- Silicone:Inorganic-organic hybrid chemistry withstands extreme thermal cycling for exhaust stacks, furnaces, and high-temperature process equipment.
- Chlorinated Rubber:Solvent-borne single-pack systems persist in marine immersion zones where rapid recoat windows outweigh VOC compliance penalties.
Volume placements concentrate in epoxy; the faster expansion belongs to polyurethane.
Technology:
Application technology determines capital intensity, regulatory compliance burden, and finish quality consistency across German manufacturing.
- Solvent-Based:Conventional high-solids and medium-solids systems deliver film build and flow characteristics for complex geometries. REACH substance restrictions and workplace exposure limits under German occupational safety law are compressing permissible application zones to specialty marine and chemical-resistant segments.
- Water-Based:Acrylic and polyurethane dispersions eliminate VOC emissions at point of application while matching solvent-borne durability in controlled environments. Tier-1 suppliers in Bavaria have converted the majority of mixing capacity to aqueous platforms to secure automotive OEM contracts.
- Powder Coatings:Thermoset epoxy-polyester hybrid powders achieve near-zero VOC output with exceptional transfer efficiency for metal furniture, appliances, and automotive components.
- UV-Curable:Rapid polymerization under ultraviolet radiation enables high-speed line coating of flat stock and assembled components with minimal thermal exposure.
- Radiation-Curable:Electron beam curing systems penetrate opaque films for thick-section industrial parts where UV light cannot reach.
- Electrostatic Spray:Charged particle deposition maximizes coating transfer efficiency and reduces overspray waste in high-volume metal finishing operations.
Water-based systems claim the steepest expansion trajectory as regulatory pressure intensifies.
Application:
Functional coating purposes align with asset protection priorities and operational duty cycles across German industry.
- Protective Coating:Barrier systems prevent moisture and oxygen ingress to extend steel asset service life in atmospheric and immersion exposures. North Sea offshore wind foundations and Ruhr corridor bridges absorb the largest procurement volumes through state-funded rehabilitation frameworks.
- Anti-Corrosion:Active pigment technologies including zinc-rich primers and micaceous iron oxide intermediate coats provide sacrificial or inhibitive protection for structural steel in aggressive environments.
- Decorative Coating:Color and gloss control for architectural metalwork, consumer appliances, and visible machinery surfaces where aesthetic standards accompany functional requirements.
- Fire Retardant:Intumescent formulations expand under heat exposure to insulate steel structural members and delay collapse during fire events in commercial and industrial buildings.
- Chemical Resistance:Specialized epoxy and vinyl ester systems withstand acid, alkali, and solvent splash in chemical processing, pharmaceutical manufacturing, and wastewater treatment facilities.
- Wear Resistance:Ceramic-filled and fluoropolymer-modified coatings reduce friction and abrasion in material handling equipment, pump components, and processing machinery.
Anti-corrosion applications dominate current spend; fire retardant specifications are climbing fastest on building code tightening.
End User:
Customer verticals concentrate demand in geographic clusters tied to Germany's industrial geography.
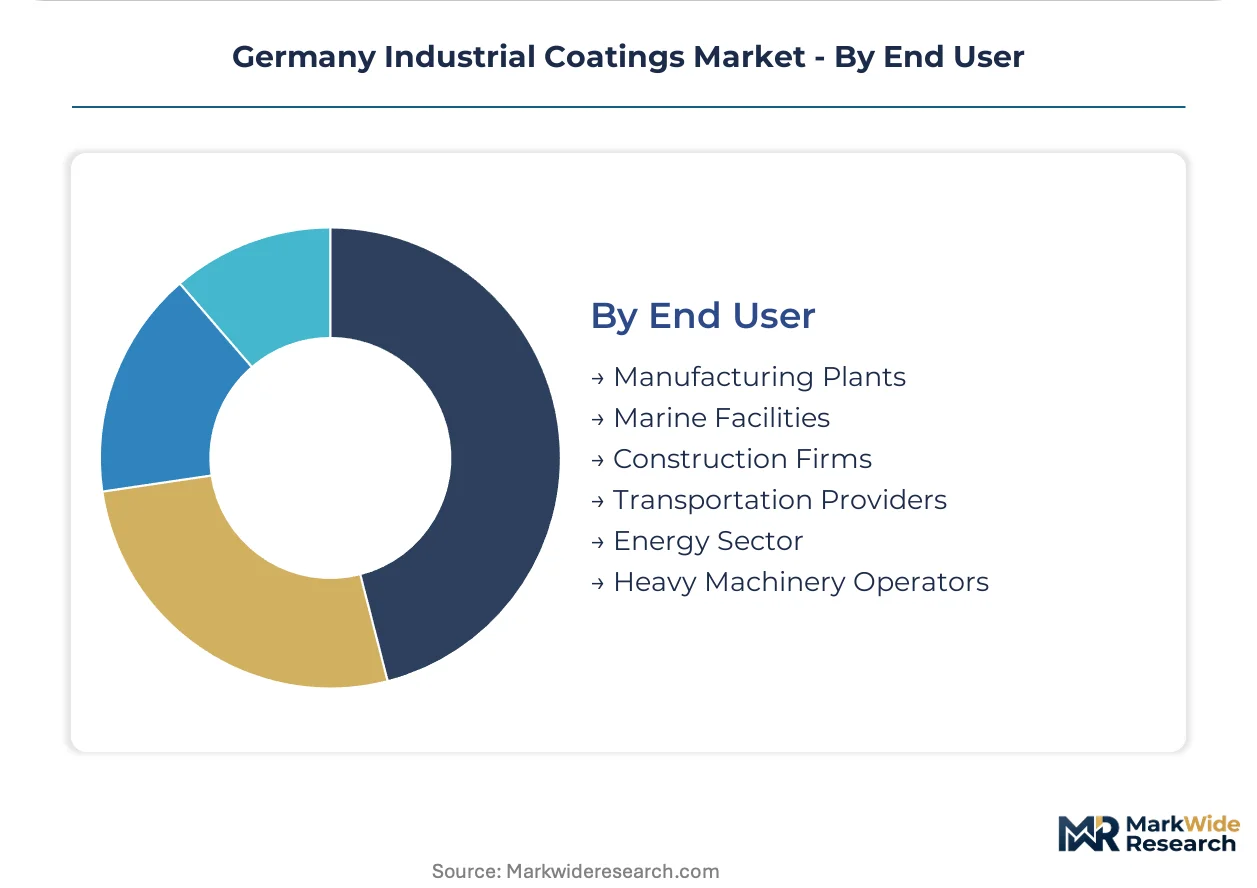
- Manufacturing Plants:Machinery OEMs and process equipment fabricators in Baden-Württemberg and Bavaria specify coating systems for new build and refurbishment cycles.
- Marine Facilities:Hamburg and Bremen shipyards, repair docks, and offshore service bases drive specialized anti-corrosion and antifouling procurement.
- Construction Firms:Steel structure erectors and infrastructure contractors across North Rhine-Westphalia source protective coatings for bridges, stadiums, and commercial developments.
- Transportation Providers:Deutsche Bahn infrastructure, municipal transit authorities, and logistics fleet operators require durable coatings for rolling stock and fixed installations.
- Energy Sector:Offshore wind developers, conventional power generators, and grid operators specify coating systems for generation and transmission assets.
- Heavy Machinery Operators:Mining, quarrying, and material processing equipment owners in eastern industrial zones demand abrasion-resistant finishes for extreme service conditions.
Manufacturing plants anchor volume demand; energy sector procurement is gaining share fastest on offshore wind buildout acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability from the Rotterdam-Antwerp refining cluster anchors coating formulation capacity across northwestern Europe. German industrial demand concentrates in automotive, marine, and steel fabrication corridors where REACH compliance reshapes procurement geography.
Bavaria
Automotive OEM coating specifications from Munich and Ingolstadt plants drive demand for high-solids polyurethane systems. KBA type-approval protocols mandate performance standards that elevate local supplier technical capabilities. Tier-1 mixing facilities around Munich have converted the majority of capacity to water-based platforms.
Baden-Württemberg
Aerospace fabricators in Stuttgart specify premium coatings for aluminum alloys and composite substrates under strict durability protocols. ECHA substance restrictions accelerate raw material substitution timelines for corrosion inhibitors. The region's aircraft supply chain rewards technical differentiation over price competition.
North Rhine-Westphalia
Ruhr corridor steel fabricators absorb the largest protective coating volumes through state-funded bridge and pipeline rehabilitation programs. EU Green Deal chemical restrictions redirect procurement toward low-VOC water-based systems. Düsseldorf and Dortmund host integrated coating system providers serving multi-site framework agreements.
Hamburg
Shipyards and offshore service bases drive specialized anti-corrosion and antifouling procurement for marine immersion environments. EU F-Gas Regulation phase-out schedules force reformulation commitments two product cycles ahead. The port cluster exhibits pronounced supplier consolidation around technical service partnerships.
Lower Saxony
Offshore wind turbine manufacturers in Cuxhaven and Wilhelmshaven generate sustained demand for subsea foundation coatings. ECHA corrosion protection mandates drive specification upgrades for North Sea and Baltic Sea installations. Steel fabricators here source through integrated system providers rather than discrete product vendors.
Germany Industrial Coatings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based resin certification and digital specification platforms. The vendor base organizes around three archetypes: integrated multinationals with captive raw material streams, regional specialists with technical service depth, and niche innovators with sustainability credentials. Competitive dynamics center on REACH pre-certification speed and multi-site framework agreement capture.
Within the integrated multinational tier, Axalta Coating Systems and AkzoNobel N.V. exemplify archetypes anchored in automotive OEM and marine specialization respectively. PPG Industries occupies a position emphasizing aerospace and industrial scale. Hempel A/S and Jotun represent specialists with technical service capabilities concentrated in northern European port clusters. MIPA SE exemplifies the mid-sized regional fabricator archetype with proximity advantages in southern German automotive corridors.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| RPM International Inc. |
| AkzoNobel N.V. |
| Hempel A/S |
| Beckers Group |
| PPG Industries |
| Jotun |
| MIPA SE |
| The Sherwin-Williams Company |
| Others |
Supply & Pricing Matrix
EU Green Deal chemical restrictions gate qualified supply and premium-tier pricing access for coating formulators serving German industrial buyers. REACH substance authorization timelines compress procurement windows for compliant raw materials, elevating certified suppliers into preferential pricing tiers while excluding uncertified competitors from specification lists.
Pricing Analysis
Warranty and technical service bundling separates premium coating suppliers from commodity competitors in German procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with KBA type-approved systems commanding substantial premiums over uncertified alternatives. Price erosion runs through solvent-borne tiers as REACH restrictions narrow their addressable applications. Construction firms and smaller steel fabricators exhibit highest price sensitivity; automotive OEMs and aerospace fabricators prioritize performance over unit cost.
Supply Chain Analysis
Reverse logistics for unused coating returns and expired inventory flows through specialized chemical waste handlers certified under German occupational safety law. Raw material supply concentrates in Belgium, the Netherlands, and Germany's own chemical corridor around Ludwigshafen and Leverkusen. Epoxy resins, polyurethane precursors, and specialized corrosion inhibitors draw from petrochemical feedstocks anchored in the Rotterdam-Antwerp refining cluster. Single-source vulnerability for fluorinated surfactants and certain isocyanate hardeners creates supply interruption risk. Distribution runs through integrated system providers serving multi-site framework agreements rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German industrial coatings sit in a technology-transition phase where water-based polyurethane dispacements displace legacy solvent-borne 2K systems. This substitution reshapes competitive positioning toward aqueous formulation expertise and capital-intensive dispersion manufacturing.
For Market Incumbents: Anchor market position through backward integration into certified raw material streams and captive aqueous dispersion capacity in Bavaria or Baden-Württemberg. ECHA authorization backlogs threaten 18-24 month product launch delays; incumbents should pre-validate alternative resin systems before candidate list expansions force emergency reformulation. Multi-site framework agreement capture with Ruhr corridor steel fabricators locks out emerging competitors.
For New Entrants and Emerging Players: Launch via digital coating specification platforms targeting mid-sized applicators in Hamburg ship repair and Lower Saxony offshore wind supply chains. Bio-based resin pilot programs offer white-space positioning before mass-balance certification becomes table stakes. Technical service partnerships with regional distributors bypass direct competition with integrated multinationals for automotive OEM accounts.
For Investors and Strategic Acquirers: ECHA candidate list expansions accelerating raw material substitution timelines is the leading indicator that formulation chemistry capabilities will concentrate among fewer suppliers. Five-to-ten year viability favors acquirers of regional specialists with REACH pre-certification depth and technical service infrastructure. Monitor ECHA substance authorization grant rates for early signals of which resin technologies will retain market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive supply of REACH-compliant epoxy and polyurethane precursors insulates margin structures from petrochemical volatility. |
| Aqueous Dispersion Capacity Expansion | Dedicated water-based mixing lines in Bavaria secure automotive OEM contracts under KBA type-approval protocols. |
| Multi-Site Framework Agreement Capture | Ruhr corridor steel fabricators and Hamburg shipyards consolidate procurement around integrated system providers. |
| Bio-Based Resin Certification Program | ECHA mass-balance verification creates first-mover positioning ahead of mandatory sustainable chemistry mandates. |
| Digital Specification Platform Launch | AI-assisted substrate matching compresses sales cycles for mid-sized applicators in marine and protective segments. |
Research Methodology
Trade association filings, customs and import-export records, and SEC 10-K disclosures formed the secondary backbone for market sizing and competitive positioning. Plant managers at coating formulation facilities, procurement leads at automotive OEMs and steel fabricators, distribution channel partners, and technical R&D directors contributed primary perspective. Bottom-up volume modeling across resin chemistry, application technology, and end-use vertical triangulated against top-down macroeconomic indicators.
Bottom-up segmentation analysis tracked formulation chemistry, technology platform, functional application, and regional industrial cluster across the analysis window. CAGRs derived from regression analysis against industrial production indices, construction spending, and automotive output. Forecast inputs included offshore wind installation pipelines, bridge rehabilitation program allocations, and REACH authorization timelines.
The model assumes a particular technology adoption path; alternative pathways for solvent-borne system retention would alter the outlook if regulatory enforcement delays materialize. Forecasts reflect assumptions about ECHA candidate list expansion rates and EU F-Gas Regulation phase-out adherence. Practitioners should monitor ECHA authorization grant rates and bio-based resin pilot program scale-up for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Pipe Coatings Market
Coatings
Hard Coating Market
Coatings
South Korea Marine Coatings Market
Coatings
Global UV-Cured Coatings Market
Coatings
North America Hydrocarbon Fire Intumescent Coating Services Market
Coatings
Fire Retardant Coatings Market
Coatings
Powder Coating Booth Market
Coatings
Coating Auxiliaries Market
Coatings
Emulsion Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
Flexible Waterproof Coating Market
Coatings
Coating Thickness Gauge Market
Coatings
High Performance Epoxy Coating Market
Coatings
Vietnam Architectural Coatings Market
Coatings
Ethylene Tetrafluoroethylene (ETFE) Coatings Market