
 Epoxy Coating Market | 2026-2036
Epoxy Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Coating Market Intelligence
The European Union's Green Deal, with its focus on sustainable materials, is hardening specifications for epoxy coatings. AkzoNobel N.V. leverages its R&D in waterborne formulations to meet these new standards. BASF SE differentiates through integrated chemical production, ensuring stable supply of key resins and curing agents. The Sherwin-Williams Company sustains its position via a vast distribution network targeting industrial end-users.
Epoxy coatings are thermosetting polymer systems derived from the chemical reaction between an epoxy resin and a polyamine hardener. These coatings cure to form a hard, durable, and chemically resistant film, making them ideal for protective surface applications. Water-based epoxy formulations are gaining share over traditional solvent-based types due to stricter environmental regulations. Within applications, flooring remains a high-volume segment, while marine protection offers higher margins due to specialized performance requirements.
Regulatory frameworks such as the US EPA's rules on Volatile Organic Compounds (VOCs) and China's GB standards for chemical safety directly influence product formulation. Compliance with standards like ISO 9001 is also a critical market access requirement for industrial suppliers. The key decision for manufacturers now involves balancing investments in sustainable, low-VOC technologies against the cost pressures in high-volume construction applications.
Market Dynamics
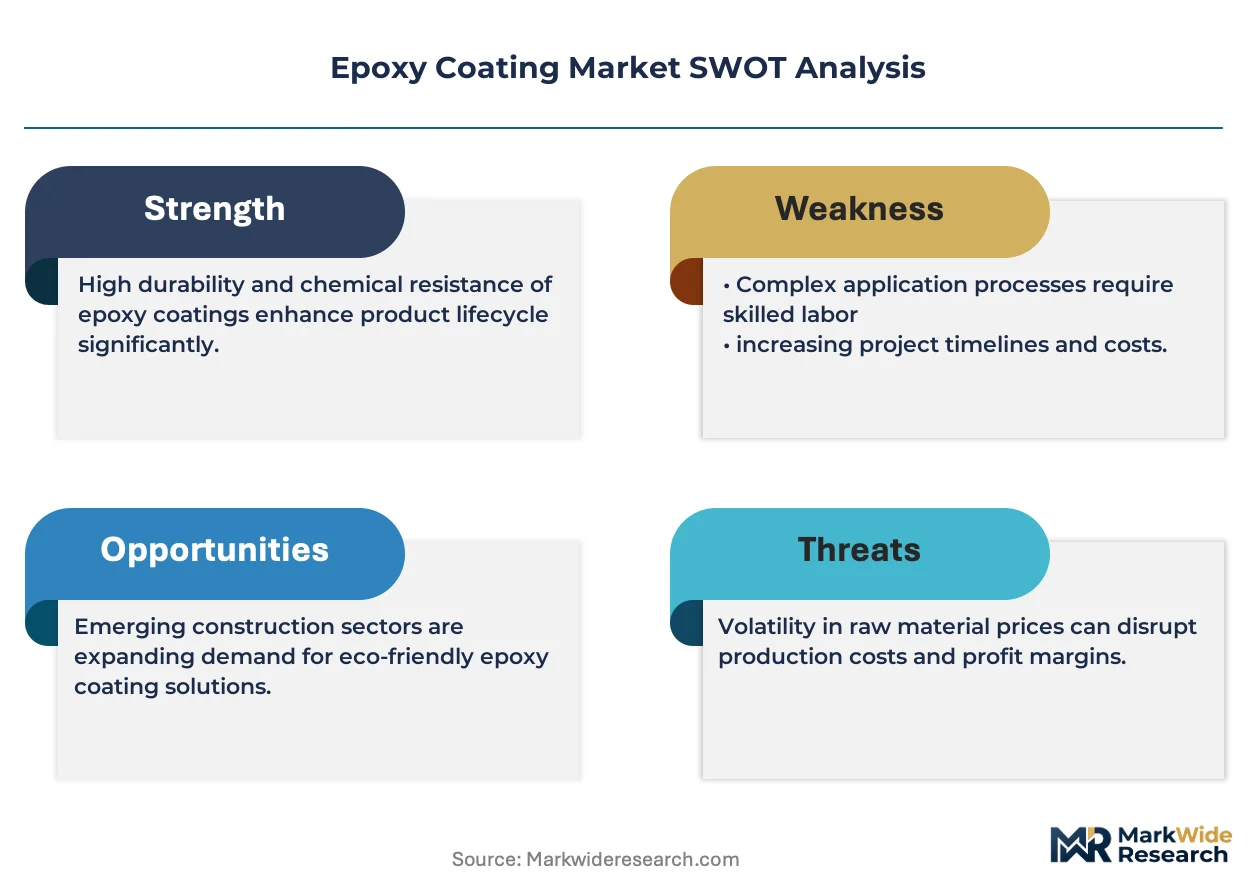
The central dynamic shaping the epoxy coating market is the structural tension between stringent environmental regulations demanding low-VOC formulations and intense cost-down pressure from high-volume end-uses like commercial construction and industrial maintenance.
Growth Catalysts
- Wind Energy Expansion:Investment in renewable energy creates demand for specialized epoxy composites and coatings for manufacturing durable, weather-resistant wind turbine blades.
- Regulatory Mandates:The EU's REACH regulation pushes the adoption of waterborne and high-solids epoxy systems, particularly within the automotive and construction sectors.
- Asian Urbanization:Rapid urban development in Southeast Asia fuels the need for protective coatings in new commercial buildings and industrial facilities.
Market Restraints
- Raw Material Volatility:Pricing for key inputs like bisphenol-A (BPA) and epichlorohydrin tracks volatile petrochemical markets, compressing manufacturer margins.
- Substitution by Polyurethanes:In flooring topcoats, polyurethane and polyaspartic coatings offer superior UV stability, presenting a significant substitution threat.
- Fragmented VOC Rules:Divergent regulations from the US EPA and state bodies like California's CARB create compliance complexity and raise formulation costs.
Strategic Opportunities
- Bio-Based Formulations:Epoxies from renewable sources like plant oils meet sustainability goals, appealing to specifiers in green building and consumer goods.
- EV Battery Encapsulation:Electric vehicle growth creates demand for epoxy encapsulants providing thermal management and insulation for battery packs.
- African Water Infrastructure:Underdeveloped water systems in Africa present an opportunity for corrosion-resistant pipe linings and tank coatings.
Industry Challenges
- Applicator Skill Gaps:A shortage of technicians skilled in correct surface preparation and two-component mixing leads to coating failures and warranty claims.
- Lengthy Certification Cycles:Obtaining approvals for specialized uses, such as food-contact compliance from the FDA or fire-retardant ratings, is a slow and costly barrier.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Coating Market |
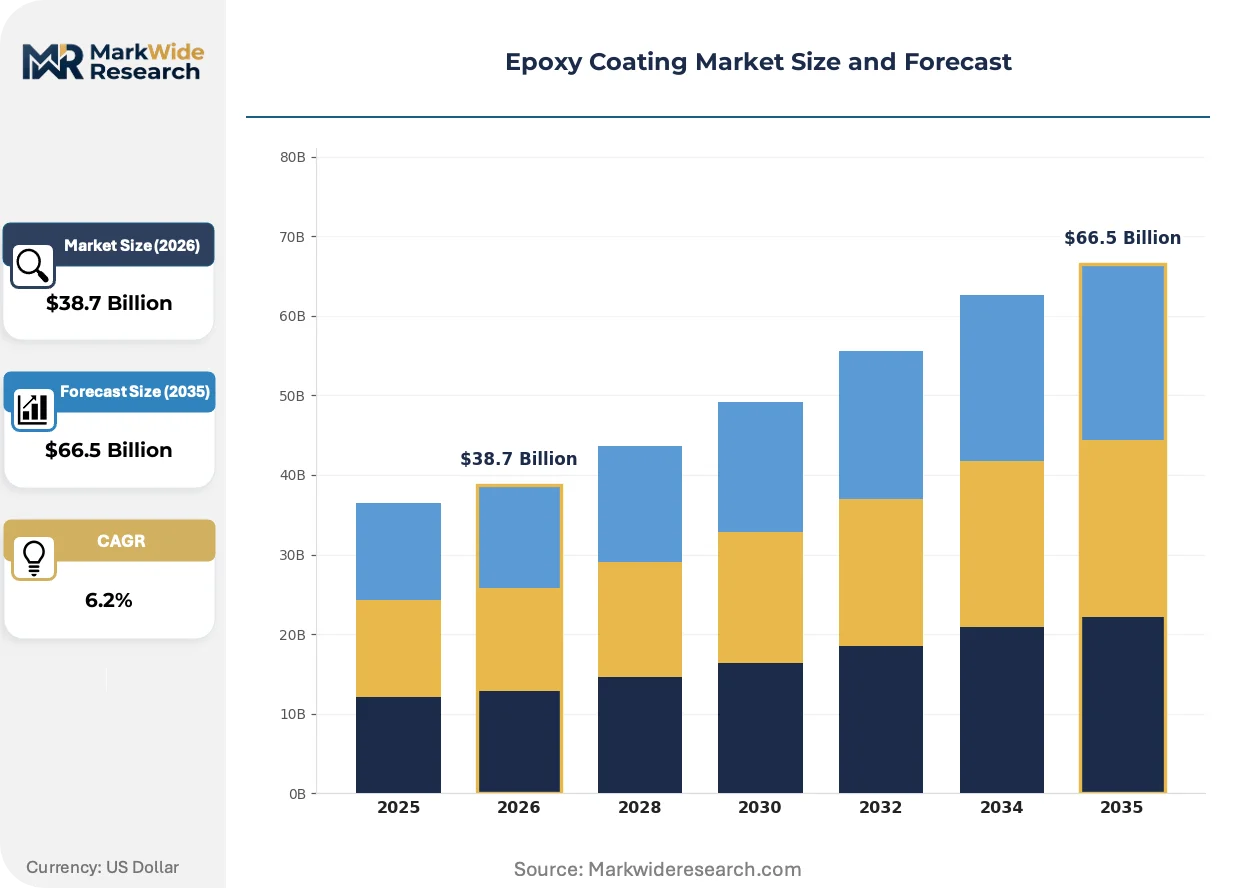
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $66.5 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based Epoxy, Water-Based Epoxy, 100% Solid Epoxy, Novolac Epoxy Application: Flooring, Marine Protection, Automotive Components, Electrical Insulation, Protective Coating End Use Industry: Construction, Aerospace, Electronics Manufacturing, Oil & Gas, Infrastructure Projects Technology: Curing Agents, Powder Coating, UV-Curable Epoxy, Epoxy Primers |
| Companies Covered | Axalta Coating Systems, Jotun A/S, PPG Industries, Inc., Nippon Paint Holdings Co., Ltd., Hempel A/S, AkzoNobel N.V., BASF SE, Kansai Paint Co. Ltd., The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Coating Market Strategic Shifts & Innovations
Product development is shifting from basic corrosion resistance toward multifunctional coatings. This evolution balances demands for advanced performance, such as thermal management, with strict environmental compliance driven by global regulations on chemical safety and sustainability.
Waterborne epoxy technology uses water as a primary solvent to reduce VOC emissions. Industrial and commercial flooring contractors are adopting these systems to meet indoor air quality standards. This technology is expanding into more demanding applications like automotive primers and protective metal coatings, areas previously held by solvent-based products.
China's GB standards for chemical safety and its national 'dual carbon' goals impose stricter limits on VOC content in industrial coatings. This directive compels manufacturers to reformulate products sold within the Chinese market. The construction and electronics manufacturing sectors are most affected, speeding the transition to water-based and high-solids epoxy coatings.
A notable shift in specification criteria is the emphasis on Life Cycle Assessment (LCA) data by architects and engineers. This moves selection beyond initial cost to include long-term durability, maintenance, and end-of-life impact. This trend is most visible in green building projects seeking certifications like LEED or BREEAM in North America and Europe.
Epoxy Coating Market Segmentation
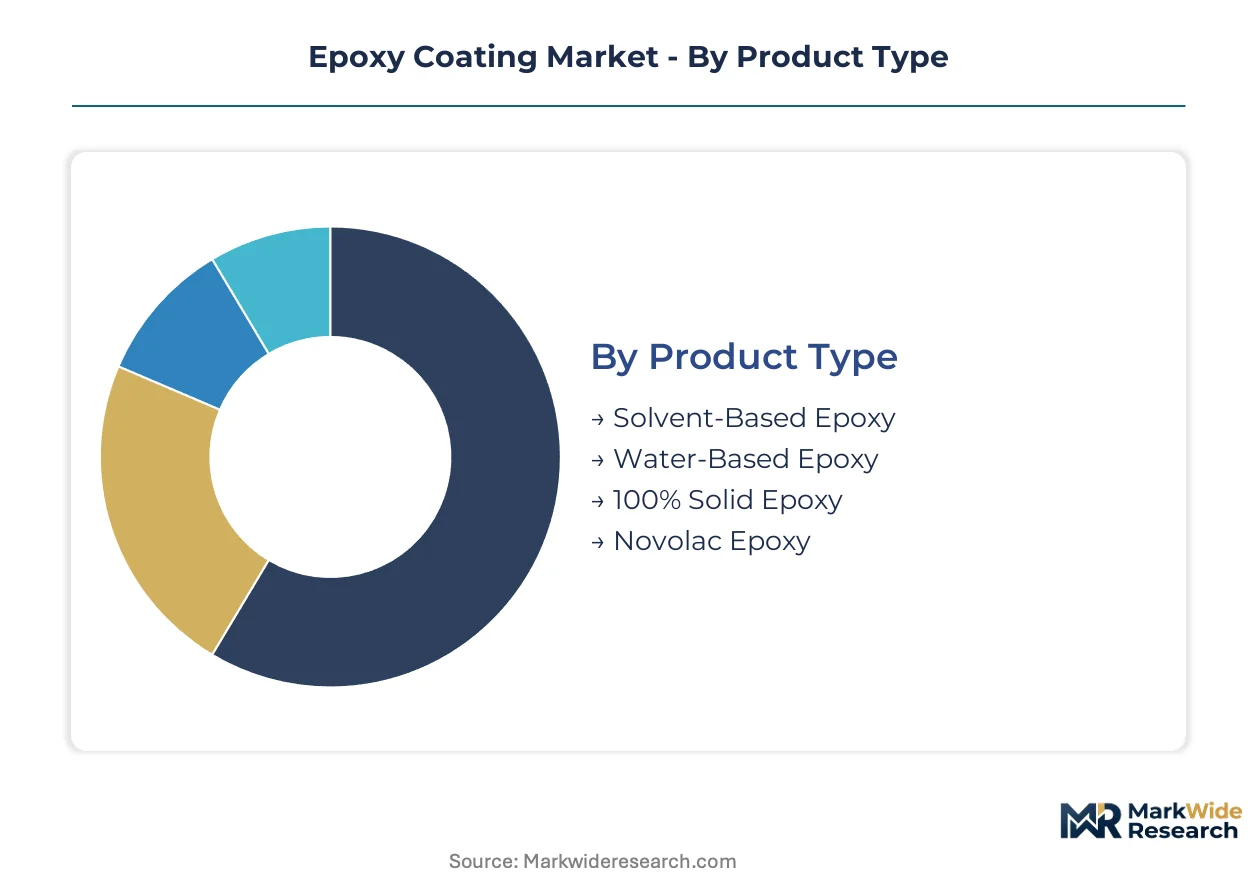
Understanding the epoxy coating market through its segmentation reveals the diverse factors influencing product development and adoption. Each category reflects distinct buyer priorities, technological advancements, and end-user requirements that shape competitive strategies.
Product Type:
Buyer decisions for epoxy coating product types hinge on balancing performance requirements with environmental compliance and application specifics.
- Water-Based Epoxy:These formulations utilize water as the primary solvent, significantly reducing Volatile Organic Compound (VOC) emissions during application. Demand concentrates in regions like the European Union and China, driven by stringent environmental regulations like REACH and GB standards, particularly for indoor applications and automotive primers.
- 100% Solid Epoxy:Formulations containing virtually no solvents or water, offering maximum film build per coat and superior durability. This product type sees high demand in industrial flooring and heavy-duty protective coatings in North America, where long-term performance and minimal VOCs are critical for facility owners.
- Solvent-Based Epoxy:Traditional epoxy systems employing organic solvents for viscosity control and application, providing excellent adhesion and chemical resistance. These products remain prevalent in cost-sensitive markets and specific industrial applications where regulatory pressure on VOCs is less intense.
- Novolac Epoxy:Specialized epoxy resins known for their enhanced chemical resistance, particularly to acids and solvents, and high-temperature performance. These are critical for linings in chemical processing plants and aggressive industrial environments in countries with heavy manufacturing bases.
Solvent-Based Epoxy leads on scale; Water-Based Epoxy leads on momentum.
Application:
Application-specific performance demands dictate the choice of epoxy coating formulations across diverse end-uses.
- Flooring:Epoxy coatings provide durable, chemical-resistant, and aesthetically pleasing surfaces for commercial, industrial, and residential floors. This high-volume segment is experiencing growth in Southeast Asian urbanization projects and new commercial construction in the United States, driven by the need for hard-wearing, easy-to-clean surfaces.
- Marine Protection:Specialized epoxy systems protect ships, offshore platforms, and port infrastructure from corrosion, abrasion, and biofouling in harsh saltwater environments. This high-margin application requires advanced formulations and rigorous certification, seeing demand from major shipbuilding nations like South Korea and maritime logistics hubs.
- Automotive Components:Epoxies are used for primers, underbody coatings, and specialized parts due to their corrosion protection and adhesion properties. OEMs in Germany and Japan specify these coatings for enhanced vehicle longevity and performance.
- Electrical Insulation:Epoxy resins encapsulate and insulate electronic components, transformers, and circuit boards, providing dielectric strength and thermal management. This application is critical for electronics manufacturing in China and for high-voltage equipment globally.
- Protective Coating:Broad category encompassing general corrosion protection for metal structures, pipelines, and industrial equipment. Demand is consistent across industrial maintenance sectors in mature economies and infrastructure development in emerging markets.
High-volume applications like Flooring define market size, while specialized uses such as Marine Protection drive innovation.
End Use Industry:
Industrial sector requirements shape demand for epoxy coatings, reflecting distinct operational environments and regulatory landscapes.
- Construction:Epoxy coatings protect and enhance concrete, steel, and other building materials in commercial, residential, and infrastructure projects. Extensive infrastructure development in China and India fuels demand for protective flooring and structural coatings.
- Electronics Manufacturing:Epoxies serve as encapsulants, adhesives, and conformal coatings for printed circuit boards, semiconductors, and battery packs. Growth in electric vehicle battery encapsulation and consumer electronics production in East Asia drives this segment.
- Aerospace:High-performance epoxy composites and coatings are used in aircraft structures, interior components, and specialized protective layers. Strict performance and safety standards from regulators like the FAA in the US and EASA in Europe govern material selection.
- Oil & Gas:Corrosion-resistant epoxy coatings protect pipelines, storage tanks, and offshore platforms from harsh chemicals and extreme environmental conditions. Demand is tied to new exploration projects and maintenance of existing infrastructure in the Middle East and North America.
- Infrastructure Projects:This segment includes bridges, roads, water treatment facilities, and utilities requiring durable, long-lasting protective coatings. Investments in water infrastructure in Africa and public works in Europe present significant opportunities.
Market expansion is significantly influenced by investments in Construction, with Electronics Manufacturing offering specialized growth niches.
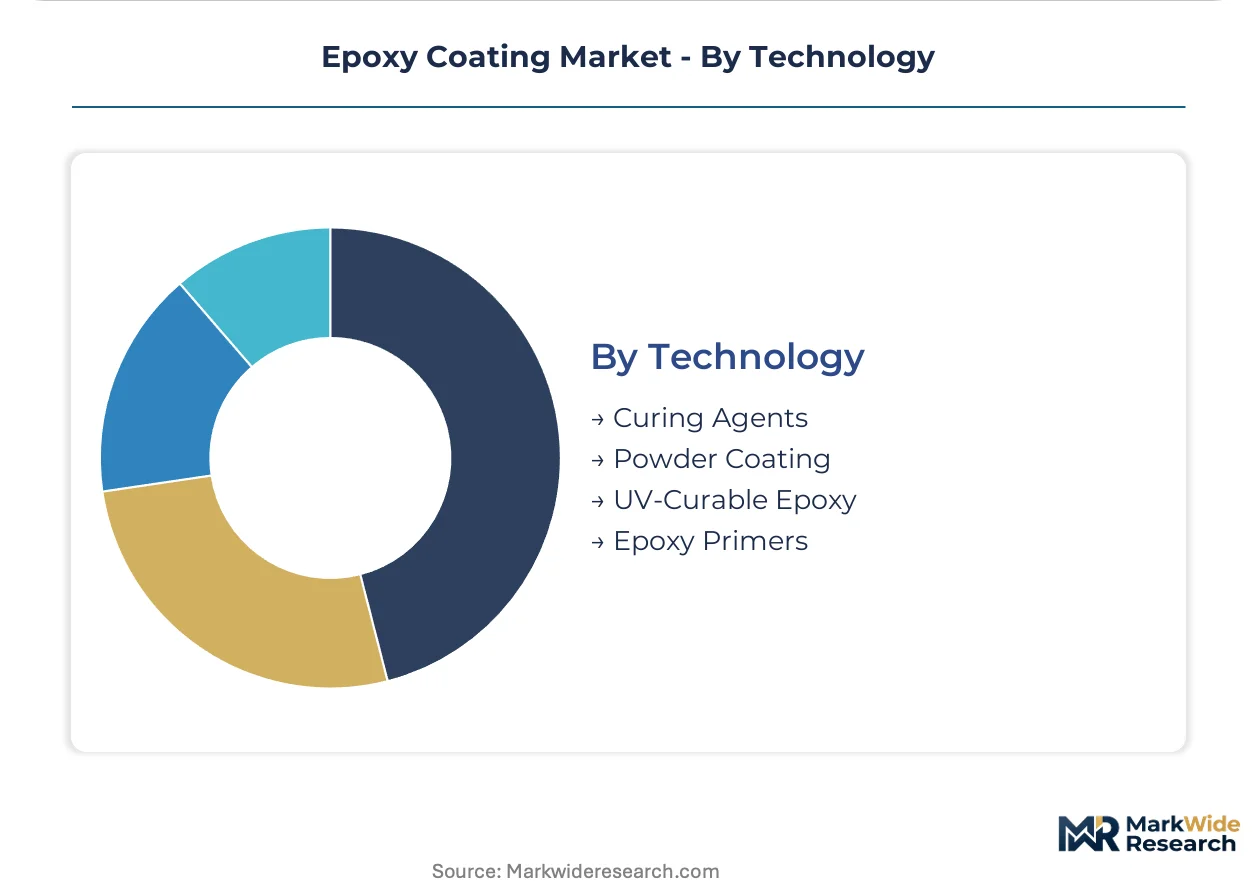
Technology:
Technological advancements and functional requirements influence the selection of epoxy coating systems.
- Curing Agents:These chemical compounds react with epoxy resins to form the final thermoset polymer, dictating cure speed, hardness, and chemical resistance. Innovation in low-temperature and fast-curing agents enhances application efficiency in manufacturing.
- UV-Curable Epoxy:Formulations that cure rapidly under ultraviolet light, offering fast processing times and reduced energy consumption without VOC emissions. This technology is gaining traction in electronics manufacturing and graphic arts due to its speed and environmental benefits.
- Powder Coating:Epoxy resins formulated as dry powders applied electrostatically and then cured with heat, producing a durable, uniform finish with zero VOCs. This technology is widely used for automotive parts and metal furniture in Europe and North America.
- Epoxy Primers:Base coats applied to substrates to improve adhesion, provide initial corrosion protection, and prepare the surface for subsequent topcoats. Primers are fundamental across all major end-use industries, ensuring system performance.
Underlying chemical components like Curing Agents enable performance, while advanced systems like UV-Curable Epoxy address evolving application needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The epoxy coating industry first scaled significantly with the post-war industrial boom in North America and Western Europe, where durable protective finishes became essential for manufacturing and infrastructure. Early formulations addressed corrosion and wear in heavy industries. This foundational demand established key production hubs and technological advancements globally.
China
Extensive infrastructure development and manufacturing output drive the demand for protective flooring and structural coatings in China. The country's GB standards for chemical safety and national 'dual carbon' goals impose strict limits on VOC content. Cities within the Yangtze River Delta, like Shanghai, anchor significant electronics manufacturing and construction activity, requiring high-performance epoxy systems.
United States
New commercial construction and industrial maintenance projects fuel the need for hard-wearing, easy-to-clean epoxy surfaces across the United States. The US EPA's rules on Volatile Organic Compounds (VOCs) influence product formulation towards lower-emission solutions. The Gulf Coast region, particularly around Houston, concentrates petrochemical production, impacting raw material supply for specialized industrial coatings.
Germany
Automotive OEMs in Germany specify advanced epoxy primers and protective coatings for enhanced vehicle longevity and performance. The European Union's REACH regulation pushes the adoption of waterborne and high-solids epoxy systems in various sectors. Bavaria's strong automotive industry and chemical production centers utilize sophisticated epoxy formulations for both components and manufacturing facilities.
India
Rapid urbanization and significant infrastructure investments generate substantial demand for protective coatings in India's construction sector. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for industrial materials, including epoxy coatings. Major metropolitan areas like Delhi-NCR experience high demand for commercial and residential epoxy flooring solutions due to ongoing development.
South Korea
Demand from major shipbuilding nations like South Korea requires specialized marine protection epoxy systems for vessels and offshore structures. The country's national environmental regulations impact industrial coating formulations, pushing for more sustainable options. Busan's maritime industry heavily utilizes advanced epoxy systems to combat corrosion and abrasion in harsh marine environments.
Epoxy Coating Market Key Industry Players
Premium-margin players sit above commodity-margin players across the performance and specialization dimensions within the epoxy coating market. The market exhibits a tiered structure, with global chemical conglomerates at the top and regional specialists below. Strategic archetypes include integrated chemical producers, specialized coating manufacturers, and broad-portfolio industrial suppliers. Dominant competitive moves involve portfolio diversification into sustainable formulations and strategic partnerships for market access.
Integrated chemical producers like BASF SE exemplify the advantage of stable supply chains for key resins and curing agents, ensuring consistent product quality and availability for complex industrial applications. European-based AkzoNobel N.V. represents companies leveraging extensive R&D in waterborne formulations to meet evolving environmental standards and capture demand in regulated markets. The Sherwin-Williams Company, a US-based entity, anchors the segment focused on vast distribution networks and direct sales to industrial end-users, maintaining market penetration across diverse industrial end-uses.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| Jotun A/S |
| PPG Industries, Inc. |
| Nippon Paint Holdings Co., Ltd. |
| Hempel A/S |
| AkzoNobel N.V. |
| BASF SE |
| Kansai Paint Co. Ltd. |
| The Sherwin-Williams Company |
Cost & Logistics Intelligence
Volatility in bisphenol-A pricing, a key raw material for epoxy resins, directly impacts manufacturer margins and subsequently influences pricing for finished epoxy coatings across industrial and construction sectors.
Pricing Analysis
Contract-based long-term agreements and project-specific quotes define the epoxy coating market's pricing structure. Price differentiation stems from performance specifications, such as marine protection versus general construction flooring, and established brand reputation. Cost compression in high-volume construction applications persists due to intense competition and buyer demand for economical solutions. Industrial maintenance buyers exhibit higher price sensitivity compared to specifiers for specialized marine or aerospace applications.
Supply Chain Analysis
Regulatory compliance, including ISO 9001 and specific environmental certifications, acts as a primary gating factor for suppliers entering the epoxy coating value chain. Global supply of key raw materials like bisphenol-A and epichlorohydrin concentrates in petrochemical hubs, particularly in the US Gulf Coast and China. This dependence on a few regions creates single-source vulnerability and exposes manufacturers to commodity price volatility. Distribution runs through a dual model, combining direct sales to large industrial end-users with specialized distributors serving niche high-performance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The epoxy coating market presents a geographic arbitrage opportunity, leveraging varying regulatory stringencies. Manufacturers can optimize production costs by balancing EU REACH compliance requirements against less stringent environmental regulations in other regions.
For Market Incumbents: Lock in long-term supply agreements for bisphenol-A and epichlorohydrin to mitigate raw material volatility, a significant margin threat. Incumbents must deepen R&D investments in waterborne and bio-based formulations to counter stricter VOC regulations and the substitution threat from polyurethanes. Expand specialized applicator training programs to address skill gaps, reducing warranty claims and reinforcing market leadership. Strategic partnerships with construction firms in rapidly urbanizing Asian markets secure high-volume demand.
For New Entrants and Emerging Players: Begin with specialized niches where performance requirements outweigh initial cost, such as EV battery encapsulation or corrosion-resistant pipe linings in African water infrastructure. Focus on developing bio-based formulations to appeal to green building projects and specifiers seeking LEED or BREEAM certifications. The electronics manufacturing sector, particularly in East Asia, offers a penetrable segment for UV-curable epoxy systems. Market entry should emphasize superior environmental profiles and rapid processing times.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized performance and regulatory compliance create barriers to entry. The epoxy coating market offers long-term viability, driven by continuous infrastructure development and the global push for sustainable materials. Target acquisition archetypes include mid-sized firms with proprietary waterborne or bio-based epoxy technologies and established market access in high-growth Asian markets. A critical signal to watch is the widespread mandate of Life Cycle Assessment data for major public and private construction projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Waterborne R&D | Meets EU REACH and China GB standards, capturing demand in regulated construction and automotive sectors. |
| Secure Raw Material Supply Agreements | Mitigates bisphenol-A and epichlorohydrin price volatility, stabilizing manufacturer margins against petrochemical market swings. |
| Expand Applicator Training Programs | Addresses applicator skill gaps, reducing coating failures and enhancing product performance for industrial end-users. |
| Develop Bio-Based Epoxy Formulations | Appeals to green building initiatives and specifiers seeking LEED or BREEAM certifications for sustainable projects. |
| Target EV Battery Encapsulation | Capitalizes on electric vehicle growth, providing thermal management and insulation for critical battery packs. |
Research Approach
Bottom-up construction and industrial end-use modeling reconciled against top-down epoxy resin and hardener supply-side tracking forms the analytical core. This approach integrates primary interviews with coating manufacturers' R&D directors, procurement leads at large construction firms, and regulatory compliance specialists. Secondary validation draws from SEC 10-K filings, Cefic reports, and government environmental agency publications like the US EPA and EU ECHA. This triangulation ensures robust data integrity.
An input-output matrix underpins the quantitative forecast, projecting market evolution across the analysis window. The framework models segmentation across product type, application, end-use industry, and technology. Compound Annual Growth Rates (CAGRs) are derived from historical growth rates, projected demand shifts, and anticipated technological adoption curves. Key industry-specific forecast inputs include global construction spending forecasts and renewable energy investment trends.
Caveats apply where sudden shifts in petrochemical raw material prices or disruptive environmental regulations could materially shift the outlook. Forecasts reflect current macroeconomic conditions and established regulatory pathways. A model refresh is warranted upon material change in global trade policies or bio-based epoxy development.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
UV Coatings Market
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
Middle-East and Africa Thermal Spray Market
Coatings
Marine Deck Coatings Market
Coatings
Global Graphite Coatings Market
Coatings
E-Coat Market
Coatings
Australia Industrial Coatings Market
Coatings
Global Industrial Floor Coatings Market
Coatings
Thermal Insulation Coating Market
Coatings
Epoxy Surface Coatings Market
Coatings
Technical Coil Coatings Market
Coatings
Tablet Coatings Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Global Fusion Bonded Epoxy Coatings Market